
 Professional Skin Care Market | 2026-2036
Professional Skin Care Market Size, Share, and Industry Trends Forecast 2026-2036
Professional Skin Care Market Insights
Clinical-grade formulation standards is reorganizing how manufacturers allocate R&D budgets and certify efficacy claims. L'Oréal leverages its dermatological science division to anchor professional credibility in European aesthetic clinics. Estée Lauder competes through prestige channel control, sustaining margin density in med-spa distribution. Amorepacific Group specializes in fermented ingredient platforms, differentiating its professional protocols across Asian dermatology offices.
Professional skin care encompasses biologically active topical preparations manufactured at higher concentrations than retail equivalents, typically requiring pH stabilization between 3.0 and 4.5 for acid-based resurfacing protocols and clinical substantiation under ISO 10993 for irritation potential. These formulations serve licensed practitioners performing controlled epidermal remodeling, collagen induction, and barrier repair in supervised settings. Moisturizers and serums command the deepest margin pools due to repeat purchase cycles and protocol bundling in aesthetic clinics, while cleansers represent the most mature category with compressed differentiation. Application through dermatology offices is expanding fastest as physicians integrate cosmeceutical dispensing with in-office procedures, though spas retain volume leadership through membership-based facial programs.
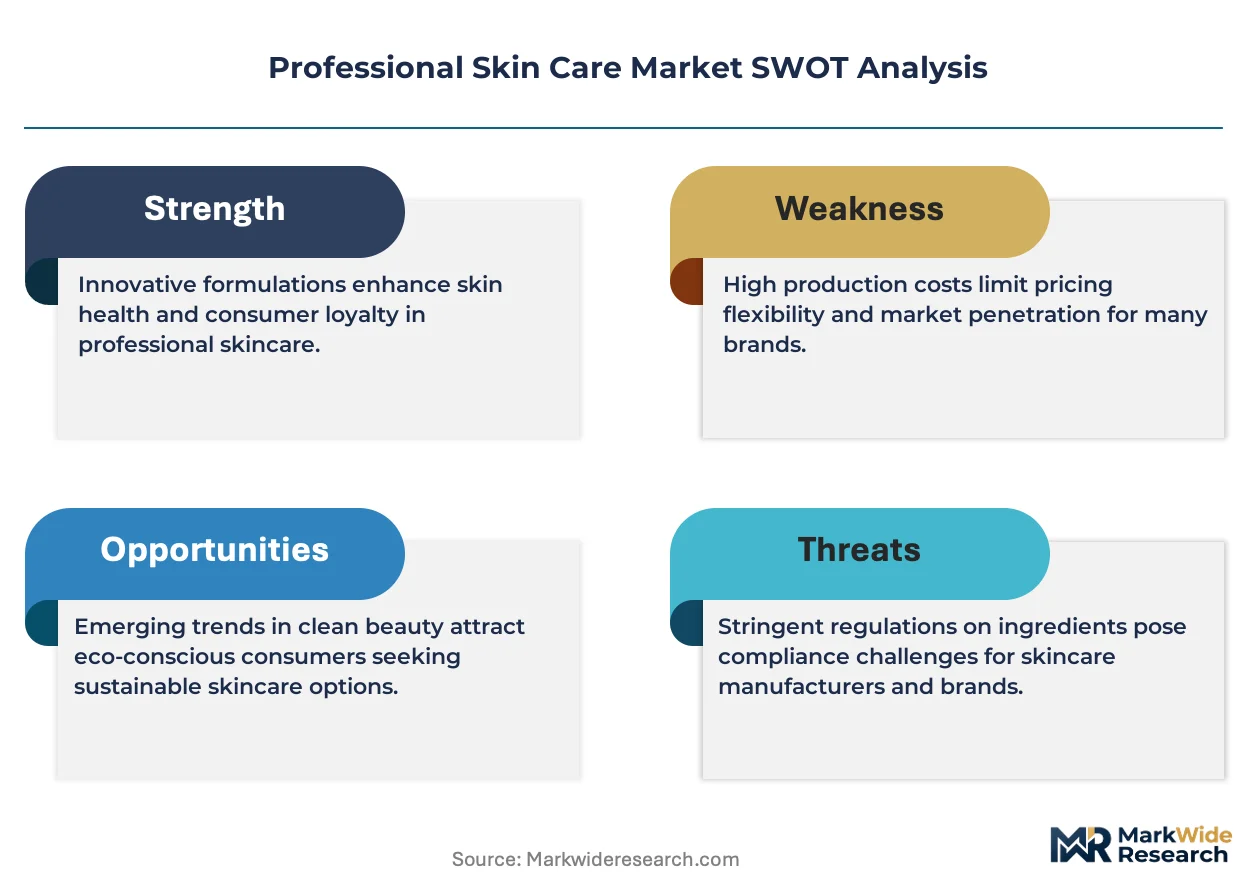
FDA oversight of device-cosmetic hybrids, the EU's MDR for clinic-dispensed products, and REACH chemical safety thresholds collectively elevate compliance costs while restricting unverified ingredient claims. These frameworks channel demand toward manufacturers with established regulatory dossiers and clinical trial infrastructures. Stakeholders must monitor how biologics-inspired peptides and exosome-derived actives trigger novel classification debates across jurisdictions.
Market Dynamics
Clinical substantiation requirements under the EU's MDR and REACH frameworks are forcing manufacturers to reallocate R&D budgets toward ISO 10993-compliant irritation testing and pH-stabilized acid formulation protocols. This regulatory compression favors incumbent players with established dossier infrastructures.
Growth Catalysts
- Protocol-driven clinic expansion:Medical aesthetic centers in Seoul's Gangnam district anchor premium service pricing through bundled treatment menus, creating pull-through demand for professional-grade resurfacing serums.
- MDR compliance infrastructure:The EU's tightened ingredient disclosure mandates channel procurement toward manufacturers with pre-existing clinical trial frameworks, consolidating vendor relationships.
- Fermented bioactive platforms:Biotechnology-derived peptide synthesis is enabling next-generation collagen induction therapies with enhanced epidermal penetration profiles.
Market Restraints
- High-purity acid feedstock volatility:Pharmaceutical-grade glycolic and lactic acid supplies concentrate among specialty chemical producers in Germany and China, exposing formulators to input cost swings.
- Device-cosmetic hybrid classification:FDA scrutiny of microneedling serums and LED-activated topicals creates regulatory uncertainty, delaying commercialization timelines.
- Clinical labor scarcity:Licensed aesthetic practitioners require specialized training in pH-controlled epidermal remodeling, constraining clinic expansion velocity.
Strategic Opportunities
- Dermatology office dispensing integration:Physician-dispensed cosmeceutical protocols in São Paulo and Dubai are displacing traditional spa channels, capturing higher-margin repeat purchase cycles.
- Exosome-derived active classification:Biologics-inspired signaling molecules occupy regulatory gray zones across jurisdictions, offering first-mover advantage for dossier-ready entrants.
- Membership-based facial programs:Subscription models in South Korean clinics bundle cleansers with in-office procedures, locking in predictable revenue streams.
Industry Challenges
- ISO 10993 certification timelines:Irritation potential testing for acid-based resurfacing protocols extends product development cycles by 18-24 months.
- Barrier repair formulation complexity:pH stabilization between 3.0 and 4.5 while maintaining biologically active concentrations demands specialized manufacturing equipment.
- Cross-jurisdiction dossier fragmentation:Divergent classification standards for peptide-based actives between the EU's ECHA and South Korea's MFDS multiply compliance costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Professional Skin Care Market |
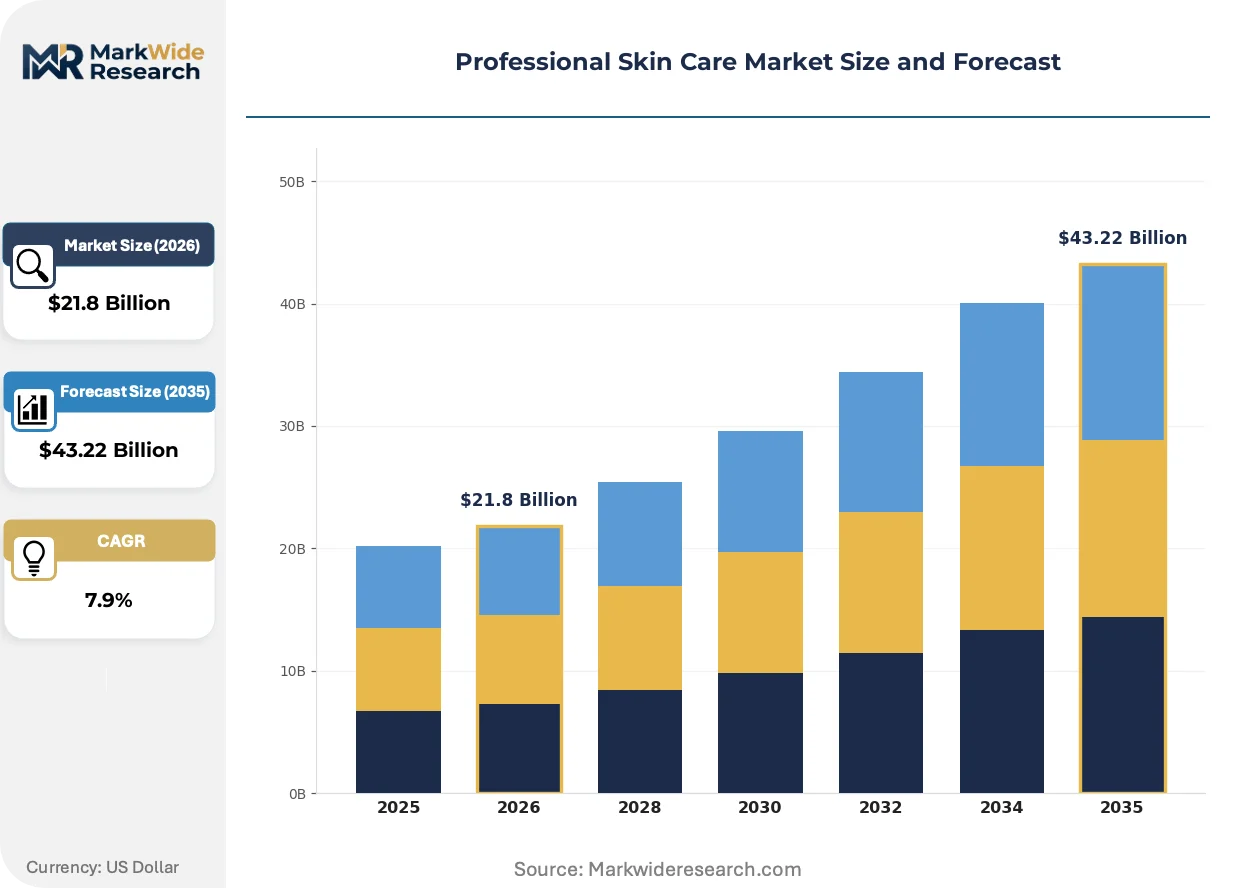
| Market Size in 2026 | $21.8 Billion |
| Market Size in 2035 | $43.22 Billion |
| CAGR (2026 – 2036) | 7.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cleansers, Exfoliators, Moisturizers, Serums Application: Aesthetic Clinics, Spas, Dermatology Offices, Home Use End User: Professionals, Consumers, Retailers, Distributors Ingredient Type: Natural Extracts, Retinoids, Peptides, Acids |
| Companies Covered | Estée Lauder, Beiersdorf, L'Oréal, Amorepacific Group, Unilever, Galderma, Procter & Gamble, Johnson & Johnson, Pierre Fabre Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Professional Skin Care Market Trends and Innovations
Biotechnology-derived actives and digital protocol standardization are compressing traditional formulation cycles while elevating clinical outcome documentation requirements. These shifts favor manufacturers with integrated dermatological science divisions.
Exosome-derived signaling molecules are supplanting traditional growth factor cocktails in collagen induction protocols. Seoul-based dermatology offices are adopting these biologics-inspired actives at accelerated pace for barrier repair treatments. The technology is supplanting commodity peptide suppliers and triggering novel classification debates across the EU's EMA and South Korea's MFDS.
REACH chemical safety thresholds are tightening disclosure requirements for professional channel ingredients. The framework elevates compliance costs while restricting unverified efficacy claims on acid-based resurfacing preparations. European aesthetic clinics are responding by consolidating procurement around manufacturers with established ECHA dossiers.
Clinic-dispensed protocol bundling is displacing standalone product sales in membership-based facial programs. São Paulo medical spas are integrating cosmeceutical dispensing with in-office microneedling procedures, compressing traditional distributor margins. This pattern concentrates in Brazil's clinic-dense urban centers where physician oversight anchors premium pricing.
Professional Skin Care Market Segmentation
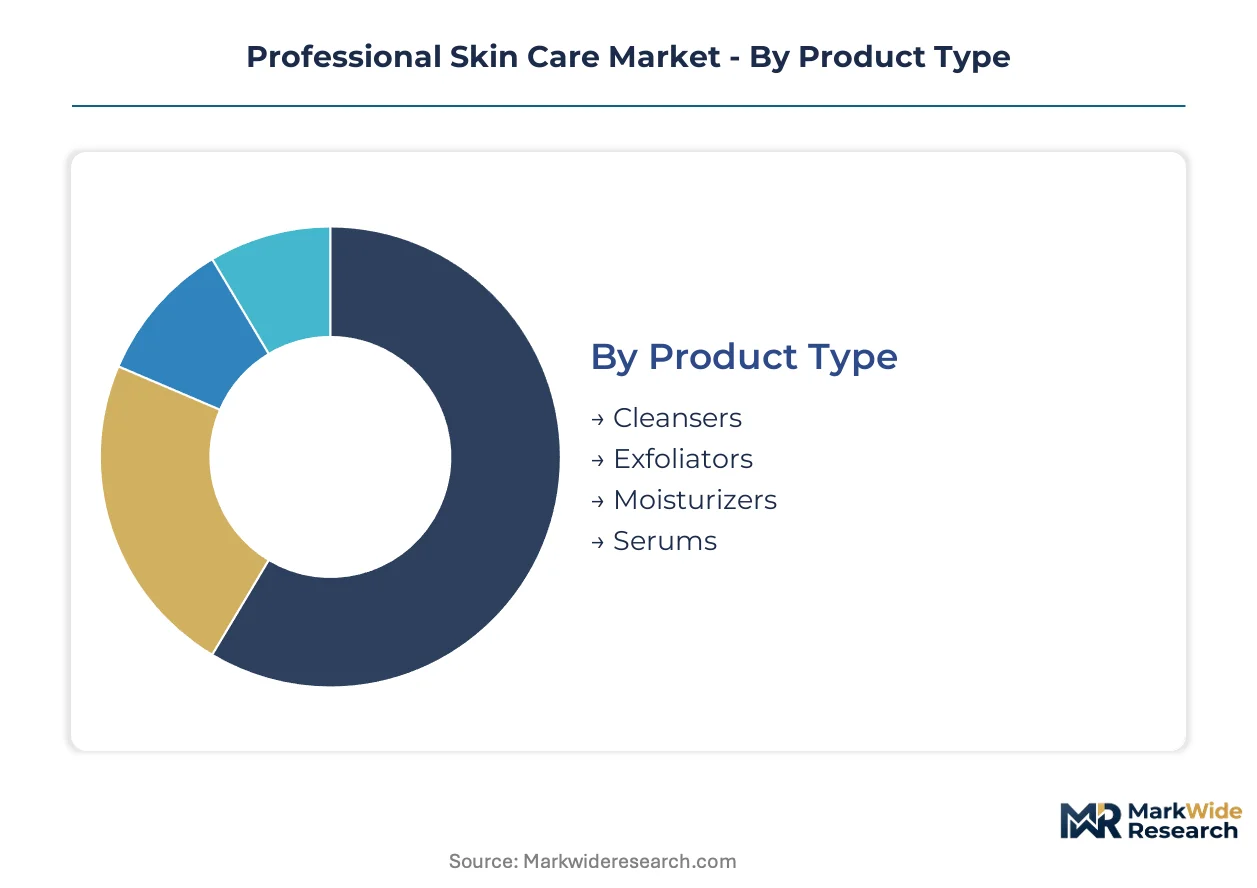
Professional skin care segmentation reveals how formulation specifications and channel access permissions determine pricing architecture. Product chemistry, application setting, and end-user credentialing together govern which formulations reach which patients under what supervision protocols.
Product Type:
Cleansers flow through spa membership programs while resurfacing acids concentrate in dermatology dispensing channels. Each product tier carries distinct pH stabilization requirements and clinical substantiation burdens.
- Moisturizers:Barrier repair formulations require ceramide-lipid matrices at concentrations exceeding retail equivalents. São Paulo aesthetic clinics bundle these with collagen induction procedures, locking in repeat purchase cycles through protocol integration.
- Serums:Biologically active preparations with acid concentrations between 3.0 and 4.5 pH anchor premium pricing in Gangnam district clinics. Seoul's medical aesthetic centers leverage these for controlled epidermal remodeling under physician supervision.
- Cleansers:The most mature category with compressed differentiation; membership-based facial programs in South Korean clinics bundle these with in-office procedures.
- Exfoliators:Pharmaceutical-grade glycolic and lactic acid formulations serve licensed practitioners performing supervised resurfacing treatments.
Cleansers dominate installed base through spa volume leadership. Serums are where expansion concentrates as dermatology offices displace traditional channels.
Application:
Channel access credentials determine which formulations reach patients. Physician oversight requirements fragment distribution between supervised clinical settings and membership-based retail environments.
- Dermatology Offices:Physician-dispensed protocols in Dubai and São Paulo integrate cosmeceutical dispensing with in-office microneedling. The EU's MDR compliance infrastructure channels procurement toward manufacturers with established clinical trial frameworks.
- Aesthetic Clinics:Medical aesthetic centers in Seoul's Gangnam district anchor premium service pricing through bundled treatment menus. These facilities pull through demand for professional-grade resurfacing serums via protocol-driven expansion.
- Spas:Retain volume leadership through membership-based facial programs, though margins compress as physician-supervised channels capture higher-value repeat purchases.
- Home Use:Limited to lower-concentration preparations lacking clinical substantiation requirements; growth constrained by regulatory barriers to professional-grade formulation access.
Spas dominate installed base through membership program scale. Dermatology offices are climbing the fastest as physician dispensing integration reshapes channel economics.
End User:
Credentialing requirements stratify procurement authority. Licensed practitioners command access to pH-controlled acid formulations unavailable to unlicensed purchasers.
- Professionals:Licensed aesthetic practitioners in Seoul, Dubai, and São Paulo require specialized training in pH-controlled epidermal remodeling. Clinical labor scarcity constrains clinic expansion velocity despite formulation availability.
- Consumers:Access restricted to lower-concentration retail equivalents; professional-grade formulations require intermediary dispensing through credentialed channels.
- Distributors:Facing margin compression as clinic-dispensed protocol bundling displaces standalone product sales in Brazil's urban centers.
- Retailers:Limited to cleansers and basic moisturizers; professional-grade acids and serums excluded from open-channel distribution under REACH and FDA frameworks.
Professionals dominate installed base through exclusive access to high-concentration protocols. Distributors are gaining share fastest as São Paulo and Dubai clinics consolidate vendor relationships around established regulatory dossiers.
Ingredient Type:
Biological activity levels and regulatory classification status determine which chemistries reach professional channels. Exosome-derived actives occupy evolving classification frameworks across jurisdictions.
- Peptides:Biotechnology-derived synthesis enables next-generation collagen induction therapies with enhanced epidermal penetration profiles. Divergent classification standards between the EU's ECHA and South Korea's MFDS multiply compliance costs for cross-border suppliers.
- Acids:Pharmaceutical-grade glycolic and lactic acid supplies concentrate among specialty chemical producers in Germany and China. REACH chemical safety thresholds tighten disclosure requirements while restricting unverified efficacy claims on resurfacing preparations.
- Retinoids:Concentration limits vary by jurisdiction; physician dispensing required for professional-grade protocols in most regulated markets.
- Natural Extracts:Fermented bioactive platforms differentiate Amorepacific Group protocols across Asian dermatology offices, though clinical substantiation requirements under ISO 10993 extend development timelines.
Acids dominate installed base through established resurfacing protocol penetration. Peptides represent the steepest expansion trajectory as biologics-inspired signaling molecules trigger novel classification debates across the EU's EMA and South Korea's MFDS.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty chemical feedstock for pharmaceutical-grade acids concentrates among producers in Germany and China, while clinical demand clusters in high-density metropolitan clinic networks across three continents. Regulatory frameworks in the EU, South Korea, and Brazil are diverging on classification standards for biologics-inspired actives.
South Korea
Gangnam district medical aesthetic centers anchor premium service pricing through bundled treatment menus incorporating protocol-driven resurfacing serums. MFDS oversight of peptide-based actives tightens clinical substantiation requirements for professional channel distribution. Seoul Capital Area clinics pull through demand for fermented bioactive platforms as membership-based facial programs displace standalone product sales.
United States
FDA scrutiny of device-cosmetic hybrids including microneedling serums and LED-activated topicals creates regulatory uncertainty delaying commercialization timelines. Physician-dispensed cosmeceutical protocols integrate with in-office procedures in metropolitan dermatology networks. California and New York aesthetic clinics consolidate procurement around manufacturers with established ISO 10993 dossiers for irritation potential testing.
Brazil
São Paulo medical spas displace traditional distributor channels through clinic-dispensed protocol bundling with in-office microneedling procedures. ANVISA classification standards for professional-grade acid concentrations govern physician oversight requirements. Urban clinic-dense centers in Rio de Janeiro and Minas Gerais capture higher-margin repeat purchase cycles through membership-based facial programs.
Germany
REACH chemical safety thresholds and EU MDR frameworks elevate compliance costs while restricting unverified efficacy claims on acid-based resurfacing preparations. Specialty chemical producers in Baden-Württemberg and North Rhine-Westphalia concentrate pharmaceutical-grade glycolic and lactic acid feedstock supply. Bavarian aesthetic clinics channel procurement toward manufacturers with pre-existing ECHA dossier infrastructures.
United Arab Emirates
Dubai medical aesthetic centers expand professional-grade treatment menus leveraging physician-dispensed protocol integration. MOHAP oversight aligns with tightening Gulf Cooperation Council disclosure mandates for clinic-distributed cosmeceuticals. Abu Dhabi dermatology offices capture premium positioning through bundled collagen induction therapies with enhanced epidermal penetration profiles.
Professional Skin Care Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with dermatological science divisions anchoring premium credibility while mass-market portfolios compete on volume scale. The vendor base stratifies across three tiers: multinational conglomerates with integrated regulatory infrastructures, regional specialists in fermented bioactive platforms, and private-label manufacturers serving membership-based clinic programs. Consolidation pressures favor incumbents with established ISO 10993 certification timelines and cross-jurisdiction dossier capabilities. Dominant competitive moves include backward integration into pharmaceutical-grade acid feedstock and strategic partnerships with high-density clinic networks in Seoul and São Paulo.
Within the conglomerate tier, L'Oréal and Estée Lauder occupy positions defined by channel control architectures. L'Oréal leverages its dermatological science division to anchor professional credibility in European aesthetic clinics, while Estée Lauder competes through prestige channel control sustaining margin density in med-spa distribution. Amorepacific Group exemplifies the regional specialist archetype, differentiating through fermented ingredient platforms across Asian dermatology offices.
| Leading Market Players |
|---|
| Estée Lauder |
| Beiersdorf |
| L'Oréal |
| Amorepacific Group |
| Unilever |
| Galderma |
| Procter & Gamble |
| Johnson & Johnson |
| Pierre Fabre Group |
| Others |
Pricing and Supply Chain Analysis
Pharmaceutical-grade acid feedstock substitution—shifting from commodity chemical suppliers to specialty producers in Germany and China—simultaneously concentrates supply geography around Baden-Württemberg and North Rhine-Westphalia production clusters and elevates pricing power for manufacturers with captive sourcing arrangements. This input restructuring compresses margins for formulators lacking backward integration while rewarding incumbents with established ECHA dossier infrastructures.
Pricing Analysis
The EU's MDR dictates the pricing tier structure across professional skin care channels, separating ISO 10993-certified formulations from uncertified alternatives. Price differentiation hinges on clinical substantiation grade and channel access permissions, with dermatology-dispensed protocols commanding substantial premiums over spa-distributed equivalents. Cost compression in the cleanser category is intensifying because membership-based bundling locks in volume commitments at negotiated rates. Distributors exhibit the highest price sensitivity due to margin compression from clinic-direct procurement, while physician-supervised channels prioritize efficacy documentation over unit cost.
Supply Chain Analysis
Inventory lead times for pharmaceutical-grade glycolic and lactic acid extend substantially when sourcing from specialty chemical producers rather than commodity distributors. Supply concentrates in Germany, China, and South Korea for acid feedstocks, with fermentation-derived bioactives drawing from Seoul Capital Area biotechnology clusters. Single-source vulnerability pervades the high-purity acid segment, where REACH disclosure requirements restrict supplier qualification pools. Distribution runs through clinic-direct relationships in São Paulo and Dubai, displacing traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Professional skin care operates as a regulatory-moat market where EU MDR and REACH entrenchment creates substantial switching costs for clinic procurement officers. This structural advantage favors incumbents with pre-existing clinical trial frameworks and cross-jurisdiction dossier capabilities.
For Market Incumbents: Shield market position by deepening backward integration into pharmaceutical-grade acid feedstock production in Germany, eliminating exposure to specialty chemical price volatility. Accelerate ISO 10993 certification timelines for next-generation peptide formulations to preempt emerging biotechnology entrants. Channel control through exclusive dermatology office partnerships in Seoul's Gangnam district anchors premium pricing against spa-channel erosion. For New Entrants and Emerging Players: Membership-based protocol bundling in Brazil's clinic-dense urban centers represents a service-layer gap where incumbents under-serve independent aesthetic practitioners. Target São Paulo medical spas with white-label fermented bioactive platforms, leveraging ANVISA regulatory pathways that remain less congested than EU MDR channels. A go-to-market angle emphasizing pH-stabilized acid formulations with abbreviated irritation testing protocols penetrates cost-conscious clinic segments. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors manufacturers with established ECHA dossiers and cross-border regulatory capabilities. Long-term viability centers on acquiring regional specialists in exosome-derived active platforms before classification standards solidify across the EU's EMA and South Korea's MFDS. The signal to watch is FDA guidance on device-cosmetic hybrid classification, which would trigger repricing of microneedling serum portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 10993 Certification Acceleration | Shortens product development cycles for acid-based resurfacing protocols entering EU MDR channels. |
| Backward Integration into Acid Feedstock | Captures pharmaceutical-grade glycolic supply from Baden-Württemberg specialty chemical producers. |
| Clinic-Direct Distribution Partnerships | Displaces traditional distributor margins in São Paulo and Dubai medical aesthetic centers. |
| Exosome-Derived Active Platform Development | Occupies regulatory gray zones before EMA and MFDS classification standards converge. |
| Membership-Based Facial Program Integration | Locks in predictable revenue streams through protocol bundling in South Korean clinics. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EMA marketing authorization applications, REACH registration databases, and South Korean MFDS peptide classification rulings. Interviews with dermatology clinic procurement managers, aesthetic practitioner training directors, specialty chemical procurement leads, and regulatory affairs consultants at multinational manufacturers informed demand-side validation. Customs trade data for pharmaceutical-grade acid imports and hospital procurement database extracts provided supply-side triangulation. Bottom-up clinic census modeling and top-down market sizing converged on segment-level estimates.
Segmentation dimensions modeled include product chemistry tier, application channel credentialing requirements, end-user licensing status, and ingredient biological activity classification across the projection horizon. CAGRs derive from protocol adoption curves in high-density clinic networks, regulatory approval velocity assumptions, and substitution elasticities between fermented bioactives and synthetic peptides. Forecast inputs incorporate REACH chemical safety threshold evolution, MFDS oversight tightening timelines, and clinic expansion velocity constraints from licensed practitioner scarcity.
Forecasts assume regulatory continuity in EU MDR, REACH, and South Korean MFDS frameworks; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Skincare
Asia Pacific Traditional Chinese Herbal Medicine for Face-Care Market
Skincare
Mineral Sunscreen Market
Skincare
Global Anti-Aging Products and Services Market
Skincare
Skin Care Emulsion Market
Skincare
Anti-Acne Dermal Patch Market
Skincare
South Korea Anti-Acne Dermal Patch Market
Skincare
Skincare Serums Market
Skincare
Asia-Pacific Skincare Market
Skincare
Tinted Sunscreen Market
Skincare
Cosmeceutical Ingredients Market
Skincare
United Kingdom Skincare Market
Skincare
Global Physician Dispensed Cosmeceuticals Market
Skincare
Hyaluronic Acid Personal Care Products Market
Skincare
Facial Cleansing Balm Market
Skincare
Global Healthcare Wipes Market
Skincare
Hidradenitis Suppurativa Market