
 Dermocosmetics Market | 2026-2036
Dermocosmetics Market Size, Share, and Industry Trends Forecast 2026-2036
Dermocosmetics Market Analysis
Pharmacy retail is rewriting how dermocosmetics reach consumers, blending clinical authority with accessible purchasing. L'Oréal Group leverages its dermatological portfolio to anchor shelf presence across European pharmacy chains. Beiersdorf competes through sustained R&D investment in sensitive-skin formulations. Pierre Fabre Group specializes in prescription-adjacent distribution, occupying a distinct position between medical and beauty channels.
Dermocosmetics comprise topical preparations formulated with active ingredients at concentrations that deliver measurable dermatological outcomes beyond basic cosmetic function, typically manufactured under pharmaceutical-grade quality systems and validated for tolerability on compromised skin barriers. The segment serves consumers seeking evidence-based solutions for conditions ranging from rosacea to photoaging, bridging the gap between over-the-counter skincare and prescription therapeutics. Moisturizers and serums command the deepest margin pools due to repeat purchase frequency and premium positioning around patented active complexes. The sensitive-skin target customer category leads volume adoption as barrier-repair claims gain traction across pharmacy and online channels.
EMA guidelines on cosmetic-drug borderline products, FDA oversight of over-the-counter sunscreen monographs, and REACH chemical safety requirements collectively elevate compliance costs while filtering out subscale competitors. These frameworks shape demand by mandating clinical substantiation for claims and restricting certain preservative systems, effectively favoring established players with dedicated regulatory affairs infrastructure. Stakeholders must monitor evolving biotech ingredient classifications as synthetic biology-derived actives challenge traditional regulatory categories and consumer perception boundaries.
Market Dynamics
Pharmacy retail expansion is restructuring dermocosmetics distribution, with clinical credibility becoming the primary currency for consumer trust and shelf access across European and Asian markets.
Growth Catalysts
- EU Green Deal chemical phase-outs:REACH restrictions on traditional preservatives are accelerating reformulation cycles, creating first-mover advantages for brands with biotech-derived alternatives already in pipeline.
- Dermatologist office retailing:Clinical channel expansion in France and Germany is capturing high-intent consumers at point of diagnosis, converting prescription conversations into over-the-counter purchases.
- Sensitive-skin demographic expansion:Barrier-compromised patient populations are multiplying due to environmental stressors and over-exfoliation trends, expanding the addressable base beyond traditional rosacea and eczema segments.
Market Restraints
- Pharmaceutical-grade manufacturing costs:GMP-compliant production facilities require capital intensity three to five times standard cosmetic manufacturing, elevating break-even thresholds for new entrants.
- Active ingredient supply concentration:Peptide and ceramide precursor synthesis concentrates among Swiss and German specialty chemical suppliers, creating vulnerability to single-source disruptions.
- EMA borderline classification uncertainty:Ambiguity around cosmetic-drug thresholds delays product launches and forces redundant clinical testing for claims substantiation.
Strategic Opportunities
- India pharmacy channel formalization:Organized retail pharmacy chains in Mumbai and Delhi are adopting European-style dermocosmetic merchandising, opening access to 1.4 billion consumers with rising dermatological awareness.
- Synthetic biology actives:Fermentation-derived retinoids and growth factors are converging with clean beauty positioning, enabling brands to bypass traditional petrochemical supply chains entirely.
- Telemedicine integration:Virtual dermatology platforms in South Korea and Brazil are creating direct-to-patient subscription models that bypass traditional wholesale pharmacy margins.
Industry Challenges
- Regulatory affairs talent scarcity:Specialists capable of navigating EMA-FDA dual filings command premium compensation, constraining mid-tier brand expansion timelines.
- Clinical substantiation documentation:Peer-reviewed trial requirements for barrier-repair claims extend development cycles by 18-24 months versus standard cosmetic marketing.
- Legacy ERP integration:Pharmaceutical lot-traceability systems collide with beauty-industry demand-forecasting platforms, forcing expensive middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dermocosmetics Market |
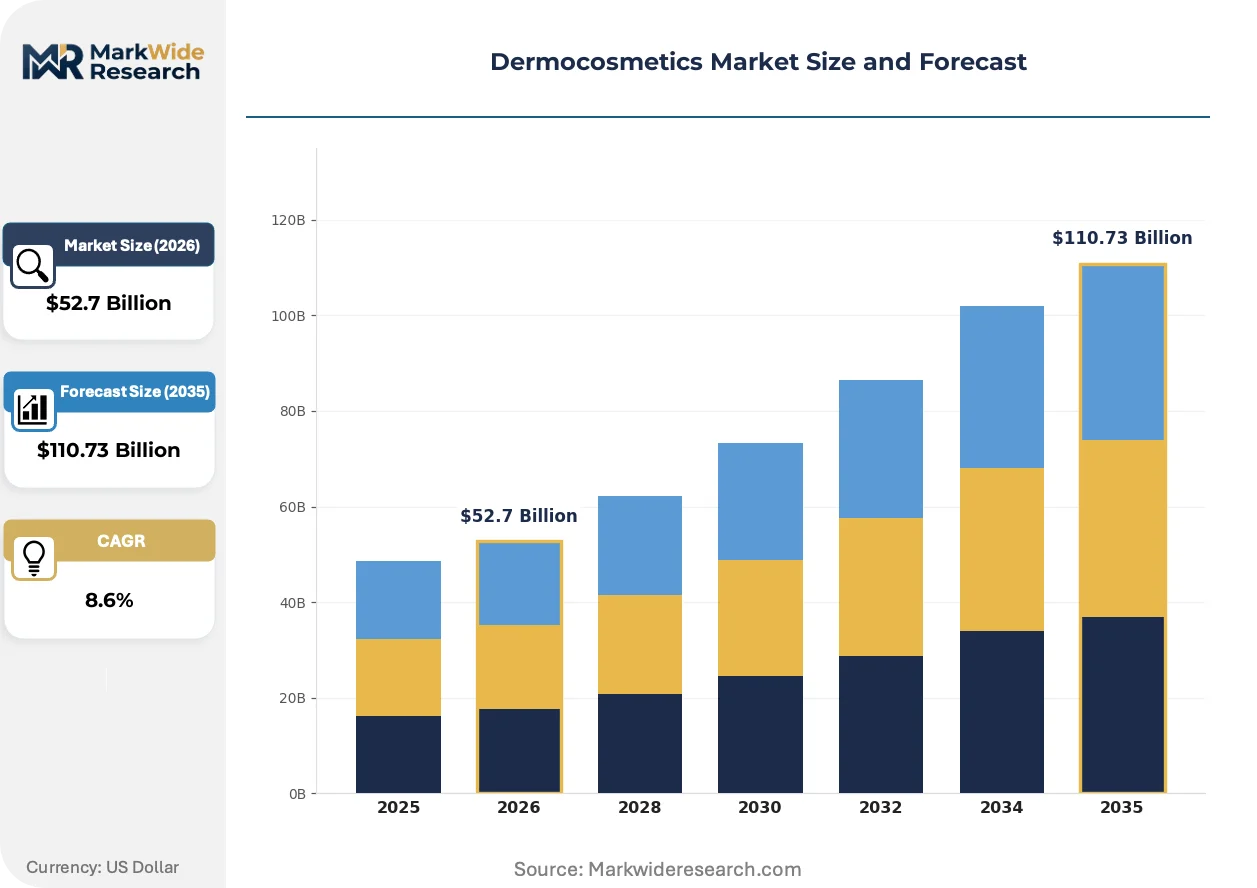
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $110.73 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Moisturizers, Serums, Sunscreens, Cleansers Target Customer: Sensitive Skin, Acne-Prone, Aging, Hyperpigmented Distribution Channel: Pharmacies, Online, Specialty Stores, Dermatologist Offices Ingredient Source: Natural, Synthetic, Botanical, Biotech |
| Companies Covered | Estée Lauder Companies, Beiersdorf, L’Oréal Group, LVMH, Coty Inc., Pierre Fabre Group, Shiseido Company, Kao Corporation, Unilever, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dermocosmetics Market Emerging Trajectories
Biotechnology is displacing conventional chemistry as the primary innovation engine, with fermentation and cell-culture methods rewriting cost structures and sustainability credentials simultaneously.
Microbiome-targeted formulations are hybridizing traditional moisturizer categories with live-culture therapeutics. Korean and French laboratories are embedding postbiotic lysates and prebiotic fibers into daily-use serums at scale. This convergence is collapsing the boundary between cosmetic maintenance and dermatological intervention, forcing regulators to draft new assessment frameworks.
REACH chemical safety revisions are mandating full supply-chain transparency for endocrine-disrupting suspects. ECHA's expanded candidate list now captures UV filters and preservatives previously grandfathered into cosmetic use. Formulators serving the European market are pivoting toward mineral-only sunscreens and phenoxyethanol-free preservation systems ahead of 2026 enforcement windows.
Subscription-based replenishment is capturing repeat-purchase behavior previously managed through pharmacy loyalty programs. Direct-to-consumer platforms in Germany and Japan are bundling diagnostic apps with personalized regimen deliveries. This channel shift concentrates customer data ownership with brands, reducing pharmacy intermediaries to fulfillment nodes rather than relationship owners.
Dermocosmetics Market Segmentation
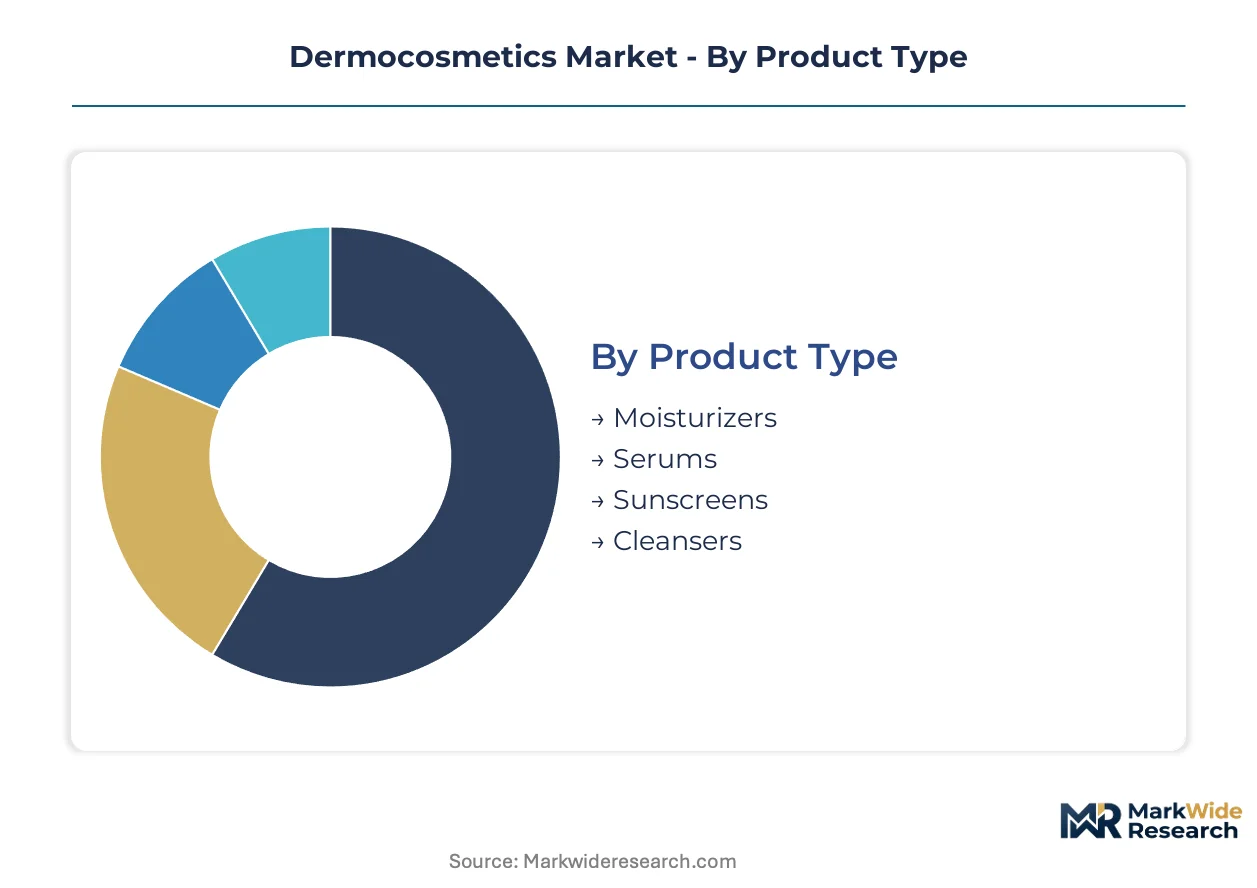
Dermocosmetics segmentation reflects divergent purchase rhythms across patient populations and retail environments. Product lifecycles compress where clinical validation meets subscription replenishment, while channel friction elongates cycles in prescription-adjacent settings.
Product Type:
Moisturizers and serums turn inventory fastest through pharmacy repeat purchases, whereas sunscreens spike seasonally and cleansers lag on slower replenishment cycles.
- Moisturizers:Barrier-repair formulations with ceramide and niacinamide complexes dominate pharmacy shelves in France and Germany. Eczema and rosacea patients in Paris and Berlin drive consistent restocking through pharmacy loyalty programs, though REACH preservative restrictions are forcing reformulation delays.
- Serums:Concentrated active delivery systems featuring peptides and growth factors command premium positioning. Korean manufacturing clusters supply fermentation-derived actives to German direct-to-consumer platforms, where diagnostic-app bundling accelerates purchase velocity.
- Sunscreens:Mineral-filter formulations are displacing chemical UV absorbers under ECHA endocrine-disruptor screening.
- Cleansers:pH-balanced syndet bars and micellar waters serve as entry-point products for sensitive-skin trial.
Moisturizers anchor the volume base while serums gain share at the steepest rate.
Target Customer:
Cost-tier stratification separates clinical-grade prescriptions from accessible pharmacy solutions, with reimbursement pathways determining price elasticity across patient segments.
- Sensitive Skin:Barrier-compromised consumers require fragrance-free, preservative-minimized formulations validated for atopic dermatitis. French pharmacy chains in Lyon and Marseille stock dedicated sensitive-skin zones, where ANSM labeling requirements elevate trust premiums.
- Acne-Prone:Retinoid and benzoyl peroxide combinations bridge cosmetic and prescription categories under EMA borderline scrutiny. Brazilian telemedicine platforms in São Paulo are converting virtual consultations into subscription regimens, bypassing traditional wholesale margins.
- Aging:Photoaging interventions concentrate in Japanese department store dermatology counters and German medical spa channels.
- Hyperpigmented:Melasma-focused formulations with tranexamic acid and azelaic acid serve South Asian and Latin American populations.
Sensitive-skin formulations represent the largest addressable base, though acne-prone segments are expanding most quickly through digital channel migration.
Distribution Channel:
Geographic concentration of pharmacy infrastructure creates divergent access economics, with European density contrasting Asian fragmentation and American retail healthcare integration.
- Pharmacies:European pharmacy networks in France, Germany, and Italy maintain category exclusivity through pharmacist consultation requirements. L'Oréal and Pierre Fabre leverage this channel to capture diagnosis-adjacent purchases when dermatologists recommend specific regimens.
- Online:Direct-to-consumer platforms in Japan and Germany bundle AI skin diagnostics with personalized subscription deliveries. Customer data ownership shifts from pharmacy intermediaries to brand operators, enabling predictive replenishment algorithms.
- Specialty Stores:Sephora and Douglas in Paris and Berlin curate dermocosmetic assortments with certified dermatologist partnerships.
- Dermatologist Offices:Clinical retailing in French and German private practices converts prescription conversations into over-the-counter add-on sales.
Pharmacies retain volume dominance while online channels climb the fastest through telemedicine integration.
Ingredient Source:
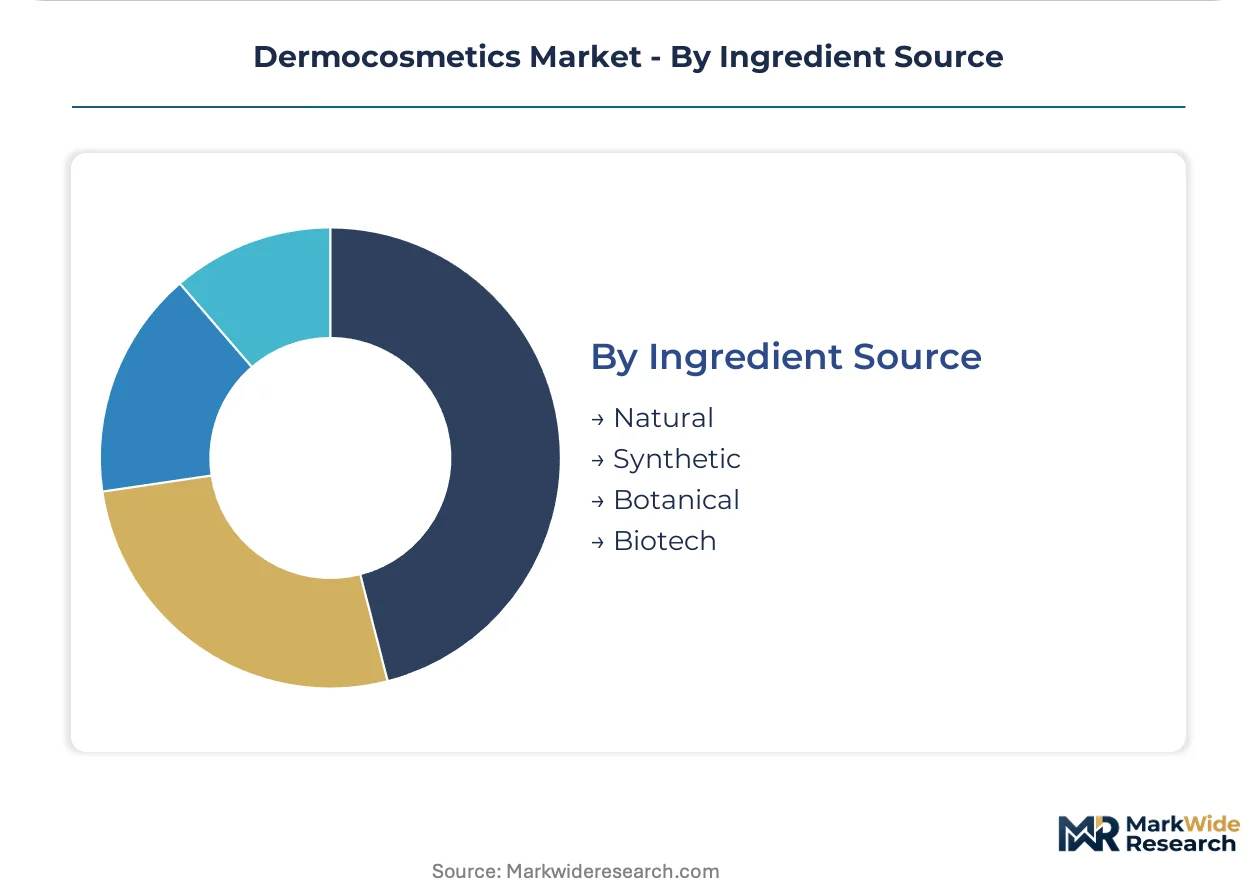
Supply concentration among Swiss and German specialty chemical houses shapes sourcing economics, with biotechnology disruptors rewriting cost curves through fermentation scale-up.
- Natural:Mineral-derived zinc oxide and titanium dioxide sunscreens are gaining share under REACH chemical phase-out mandates. Formulators pivot toward natural alternatives ahead of ECHA enforcement windows.
- Synthetic:Petrochemical-derived retinoids and peptides face sustainability scrutiny despite cost advantages. Traditional suppliers in Basel and Ludwigshafen maintain capacity leadership while biotech competitors erode market position.
- Botanical:Plant-derived centella asiatica and green tea extracts serve K-beauty positioning in Seoul and Tokyo.
- Biotech:Fermentation-derived ceramides and growth factors enable clean-beauty claims while bypassing agricultural supply chains.
Synthetic ingredients anchor current production volumes while biotech alternatives are gaining share at the steepest rate through sustainability differentiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's pharmaceutical cold-chain infrastructure anchors European dermocosmetic distribution, while Incheon International Airport's biotech cargo terminals underwrite Korean active ingredient exports to global formulators.
France
Pharmacy-based dermocosmetic retail originated here and remains structurally dominant. ANSM labeling requirements elevate trust premiums for sensitive-skin formulations. Lyon and Marseille host dedicated pharmacy chain distribution centers where dermatologist recommendations convert directly to over-the-counter purchases.
Germany
GMP-compliant manufacturing clusters concentrate in Ludwigshafen and Basel-adjacent Baden-Württemberg. REACH chemical phase-outs are accelerating reformulation cycles for preservative systems. Direct-to-consumer platforms in Berlin bundle AI skin diagnostics with personalized subscription deliveries.
United States
FDA oversight of over-the-counter sunscreen monographs shapes product development timelines. Clinical channel expansion captures high-intent consumers at point of diagnosis. Greater Boston's dermatology research corridor feeds formulation pipelines for barrier-repair technologies.
South Korea
Fermentation-derived active manufacturing clusters in Seoul and Busan supply global peptide and ceramide precursor demand. MFDS cosmetic regulations mandate rigorous safety documentation. Virtual dermatology platforms enable direct-to-patient subscription models that bypass traditional wholesale margins.
Brazil
ANVISA regulatory frameworks govern cosmetic-drug borderline classifications for acne treatments. São Paulo's telemedicine platforms convert virtual consultations into subscription regimens. Rising dermatological awareness in Rio de Janeiro and Brasília expands the addressable consumer base.
Dermocosmetics Market Vendor Landscape
On the supply side, the industry is consolidating around pharmaceutical-grade manufacturing capabilities and clinical credibility assets. Three strategic archetypes dominate: diversified beauty conglomerates with dermatological portfolios, mid-sized specialists in sensitive-skin formulations, and prescription-adjacent players occupying the medical-beauty channel boundary. Competitive moves concentrate on pharmacy shelf access negotiations and biotechnology licensing for next-generation actives.
Within the diversified conglomerate tier, L'Oréal Group and Estée Lauder Companies exemplify scale-driven positioning through European pharmacy chain penetration. Beiersdorf anchors the mid-sized specialist archetype with sustained R&D positioning in barrier-repair technologies. Pierre Fabre Group occupies a distinct prescription-adjacent position between medical and beauty channels, representing the hybrid clinical-retail model that captures diagnosis-adjacent purchases.
| Leading Market Players |
|---|
| Estée Lauder Companies |
| Beiersdorf |
| L'Oréal Group |
| LVMH |
| Coty Inc. |
| Pierre Fabre Group |
| Shiseido Company |
| Kao Corporation |
| Unilever |
| Others |
Supply Flow & Price Mechanics
Swiss and German specialty chemical suppliers of peptide and ceramide precursors anchor upstream concentration, directing margin capture toward fermentation-derived biotech alternatives that bypass traditional petrochemical intermediaries. Pharmaceutical-grade GMP manufacturing costs three to five times standard cosmetic production, elevating break-even thresholds and compressing accessible price tiers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies dermocosmetics by clinical validation depth and distribution channel. Premium tiers command pharmacy and dermatologist office placement backed by peer-reviewed trial data, while standard tiers serve mass-market pharmacy chains and economy tiers address price-sensitive entry-point consumers. Pricing pressure stems from REACH-mandated reformulation cycles as preservative system substitutions inflate R&D amortization. Subscription-based direct-to-consumer models in Germany and Japan exhibit lowest price sensitivity due to diagnostic-app bundling, whereas Indian pharmacy formalization drives acute price competition.
Supply Chain Analysis
Upstream feedstock for active ingredients concentrates in South Korea, Germany, and Switzerland, where fermentation facilities and peptide synthesis operations cluster. Biotech-derived ceramides and growth factors draw from agricultural feedstocks and cell-culture media, while mineral sunscreen filters source from Chinese and Australian titanium dioxide and zinc oxide refiners. Single-source vulnerability concentrates in Swiss peptide precursor suppliers, exposing formulators to disruption risk. Distribution runs through European pharmacy networks, Korean direct-to-consumer platforms, and Brazilian telemedicine channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The dermocosmetics market is recovering from regulatory-driven reformulation cycles as ECHA enforcement windows and EMA borderline clarifications reset competitive positions. Recovery timing hinges on biotech active ingredient scale-up economics crossing cost parity with synthetic alternatives.
For Market Incumbents: Harden pharmacy shelf access through exclusive pharmacist consultation partnerships in France and Germany, where ANSM and BfArM labeling requirements create switching costs. Deepen backward integration into fermentation capacity in Baden-Württemberg and Seoul to secure ceramide and growth factor supply against Swiss specialty chemical concentration. Accelerate clinical substantiation documentation for barrier-repair claims to extend prescription-adjacent positioning before EMA classification uncertainty resolves. For New Entrants and Emerging Players: Indian organized retail pharmacy chains in Mumbai and Delhi represent underpenetrated white space, where European-style dermocosmetic merchandising is formalizing without entrenched incumbent shelf control. Brazilian telemedicine platforms in São Paulo offer second-mover subscription model opportunities as ANVISA frameworks clarify cosmetic-drug boundaries. Target sensitive-skin formulations with phenoxyethanol-free preservation systems ahead of 2026 REACH enforcement, leveraging clean-beauty positioning against legacy reformulation delays. For Investors and Strategic Acquirers: Capital is best deployed toward mid-sized specialists with dedicated regulatory affairs infrastructure and existing EMA-FDA dual filing capabilities, where talent scarcity constrains competitor expansion. Long-term viability favors acquisition targets with captive biotech active ingredient pipelines and pharmacy channel relationships in Lyon or Berlin. Watch synthetic biology cost curves as the inflection signal: fermentation-derived retinoid production costs falling below petrochemical equivalents will accelerate incumbent displacement and reward early positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Biotech Active Ingredient Scale-Up | Fermentation-derived ceramides bypass REACH-restricted petrochemical supply chains entirely. |
| Pharmacy Channel Exclusivity Agreements | ANSM-compliant labeling in Lyon and Marseille pharmacies converts dermatologist recommendations directly. |
| Telemedicine Platform Integration | São Paulo virtual consultations in Brazil bypass traditional wholesale pharmacy margin extraction. |
| Regulatory Affairs Infrastructure Investment | EMA-FDA dual filing capabilities command premium compensation and constrain mid-tier expansion. |
| Direct-to-Consumer Diagnostic Bundling | Berlin AI skin diagnostics with subscription deliveries shift customer data ownership from intermediaries. |
Methodological Framework
Cross-validation between primary interviews with dermatology R&D directors, pharmacy chain category managers, regulatory affairs specialists, and biotech fermentation engineers and secondary sources including ECHA substance databases, ANSM labeling registries, FDA sunscreen monograph filings, and MFDS cosmetic safety documentation anchors the qualitative findings. Bottom-up triangulation from individual product pipelines and top-down validation against pharmacy retail audit data ensures coverage completeness.
Calibration against historical CAGRs from pharmaceutical-grade manufacturing expansions and biotech active ingredient commercialization curves shapes the projection framework. Segmentation dimensions span product type, target customer condition, distribution channel, and ingredient source across the analysis window. Modeled outputs incorporate REACH chemical phase-out timelines, EMA borderline classification probabilities, and synthetic biology cost curve trajectories as industry-specific inputs.
Practitioners should monitor ECHA candidate list expansions, EMA cosmetic-drug guidance revisions, and fermentation scale-up economics for early signals that assumptions require reassessment. Cross-checking against pharmacy inventory turnover data from Lyon and Berlin distribution centers is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Skincare
Allantoin Extract for Skincare Products Market
Skincare
Sun-Care Wipes Market
Skincare
Incontinence Skin Care Products Market
Skincare
After Sun Care Products Market
Skincare
Ultrasound Skin Cleaners Market
Skincare
Cystic Acne Market
Skincare
Facial Cleansing Balm Market
Skincare
Global Anti-Aging Market
Skincare
Rice Water Skincare Market
Skincare
Skin Care Supplements Market
Skincare
Global Eczema Skin-Care Products Market
Skincare
Skin Replacement Market
Skincare
Body Scrub Market
Skincare
Facial Erythema Treatment Market
Skincare
Global Physician Dispensed Cosmeceuticals Market
Skincare
Skincare Serums Market