
 Skin Barrier Market | 2026-2036
Skin Barrier Market Size, Share, and Industry Trends Forecast 2026-2036
Skin Barrier Market Analysis
Silicone-based adhesives is broadening the formulation palette for advanced skin barrier systems, replacing traditional hydrocolloid compositions in high-moisture wound environments. Coloplast Corp leverages its Nordic manufacturing footprint to sustain premium positioning in ostomy-adjacent skin protection. 3M Company anchors its competitive stance through proprietary acrylic polymer platforms that dominate hospital procurement channels. Medline Industries LP competes aggressively on private-label volume across US long-term care facilities.
Skin barrier denotes a protective interface—typically comprising petrolatum, dimethicone, zinc oxide, or polymer films—engineered to shield compromised epidermis from moisture, friction, and exogenous irritants while permitting selective vapor transmission. The primary commercial purpose centers on preventing moisture-associated skin damage in patients with incontinence, ostomies, or chronic wounds. Wound Care applications command the deepest clinical validation and reimbursement access, while Pediatric Care segments generate the fastest volume growth due to neonatal intensive care protocols. Cream formulations occupy the broadest retail shelf presence, though gel formats are capturing margin pools in post-procedure cosmetic recovery channels.
FDA 510(k) clearance pathways and EMA Medical Device Regulation (MDR) classifications shape product development timelines and clinical evidence requirements for barrier claims. Health Canada and TGA standards further fragment market access for multi-territory launches. Stakeholders must monitor evolving biocompatibility ISO 10993 testing expansions and reimbursement code consolidation that will determine which formulation investments achieve commercial viability.
Market Dynamics
Silicone-based formulations are systematically displacing hydrocolloid compositions in high-moisture clinical environments, forcing manufacturers to reconfigure polymer supply chains and reformulation pipelines around vapor-permeable elastomer platforms.
Growth Catalysts
- Ceramide science maturation:Dermatology clinics in Germany and South Korea are expanding protocols for lipid-replacement barrier therapies. EMA biocompatibility standards under MDR Annex I are accelerating clinical evidence generation for epidermal repair claims.
- Neonatal intensive care protocols:Pediatric Care segments are generating volume pull through standardized skin integrity protocols in US and German NICU networks. FDA 510(k) clearance pathways for pediatric indications are streamlining commercial timelines.
- Post-procedure cosmetic recovery:Gel format adoption is concentrating in aesthetic dermatology channels across South Korea and the United States. ISO 10993 testing expansions are validating biocompatibility for polymer film interfaces.
Market Restraints
- Petrochemical input volatility:Dimethicone and petrolatum feedstock costs fluctuate with refinery output scheduling. Formulation houses face margin compression when silicone precursor supply tightens.
- East Asian polymer concentration:Acrylic polymer platform supply clusters in South Korean and Chinese chemical parks. Western converters face extended lead times and tariff exposure.
- ISO 10993 testing burden:Expanded biocompatibility protocols for cytotoxicity and sensitization are lengthening development cycles. Small manufacturers lack in-house toxicology capacity.
Strategic Opportunities
- German outpatient dermatology:Reimbursement code consolidation for barrier products is creating access windows for ceramide-dominant formulations. EMA MDR classification clarity is reducing market entry uncertainty.
- Telemedicine-integrated dispensing:Direct-to-patient subscription models for chronic wound care are emerging in US long-term care networks. Pharmacy benefit managers are piloting outcome-linked coverage.
- Zinc oxide-polymer hybrid convergence:Mineral-active barriers with film-forming elastomers are capturing margin pools in pediatric and geriatric segments. Formulation patents in this space remain sparse.
Industry Challenges
- Formulation chemistry specialization:Scarce talent pools for silicone-polymer interface engineering are constraining R&D throughput. Universities in the United States and Germany are only now adding dedicated programs.
- Legacy ERP integration:Batch record systems for pharmaceutical-grade barrier production resist connectivity with modern quality management platforms. Validation timelines for software updates extend 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Skin Barrier Market |
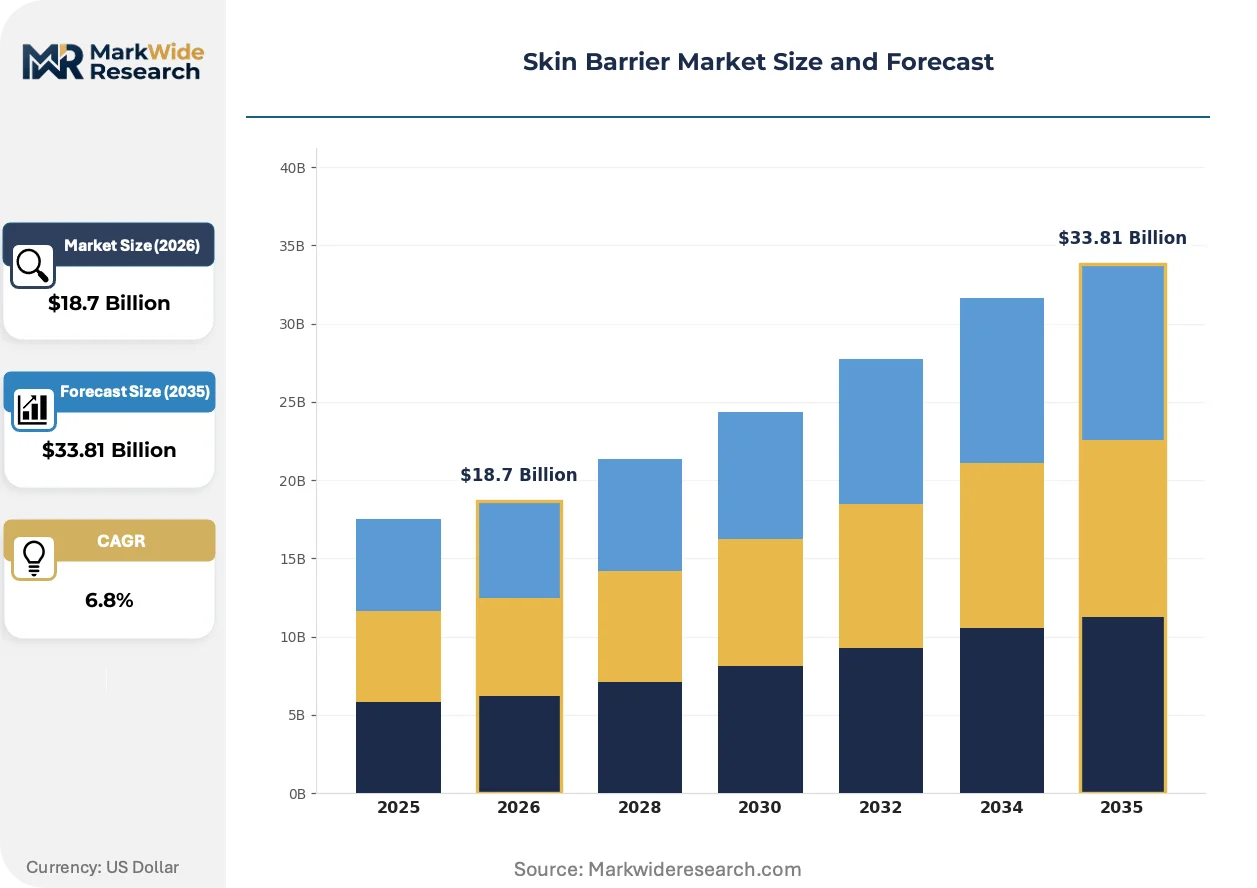
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Creams, Ointments, Gels, Lotions Application: Dermatology, Cosmetic, Wound Care, Pediatric Care End User: Hospitals, Clinics, Home Care, Dermatologists Distribution Channel: Online Retail, Pharmacies, Supermarkets, Specialty Stores |
| Companies Covered | Hollister Inc., Stryker Inc., ConvaTec Inc., Medline Industries LP, DermaRite Industries LLC, 3M Company, B. Braun Melsungen AG, Integra Lifesciences Corporation, Coloplast Corp, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Skin Barrier Market Emerging Trajectories
Reformulation momentum around vapor-permeable elastomers is compressing traditional hydrocolloid market share while regulatory biocompatibility expansions are reshaping clinical evidence requirements.
Silicone adhesive platforms are overtaking hydrocolloid matrices in ostomy and wound care applications where moisture management determines patient adherence. German hospital procurement networks are adopting these formulations at accelerating pace. The technology is overtaking legacy compositions by enabling extended wear times and reducing maceration incidents.
EMA Medical Device Regulation Annex I biocompatibility expansions are mandating comprehensive ISO 10993 testing for all barrier claims involving compromised epidermis. German notified bodies are interpreting these requirements most stringently. Wound Care applications face the heaviest documentation burden, with manufacturers in the United States and South Korea accelerating toxicology investments to maintain EU market access.
Hospital procurement committees are consolidating supplier rosters around outcome-validated barrier portfolios. Group purchasing organizations in the United States are displacing fragmented vendor relationships with single-source contracts tied to skin integrity metrics. This concentration is most visible in long-term care networks across the Midwest and Southeast states.
Skin Barrier Market Segmentation
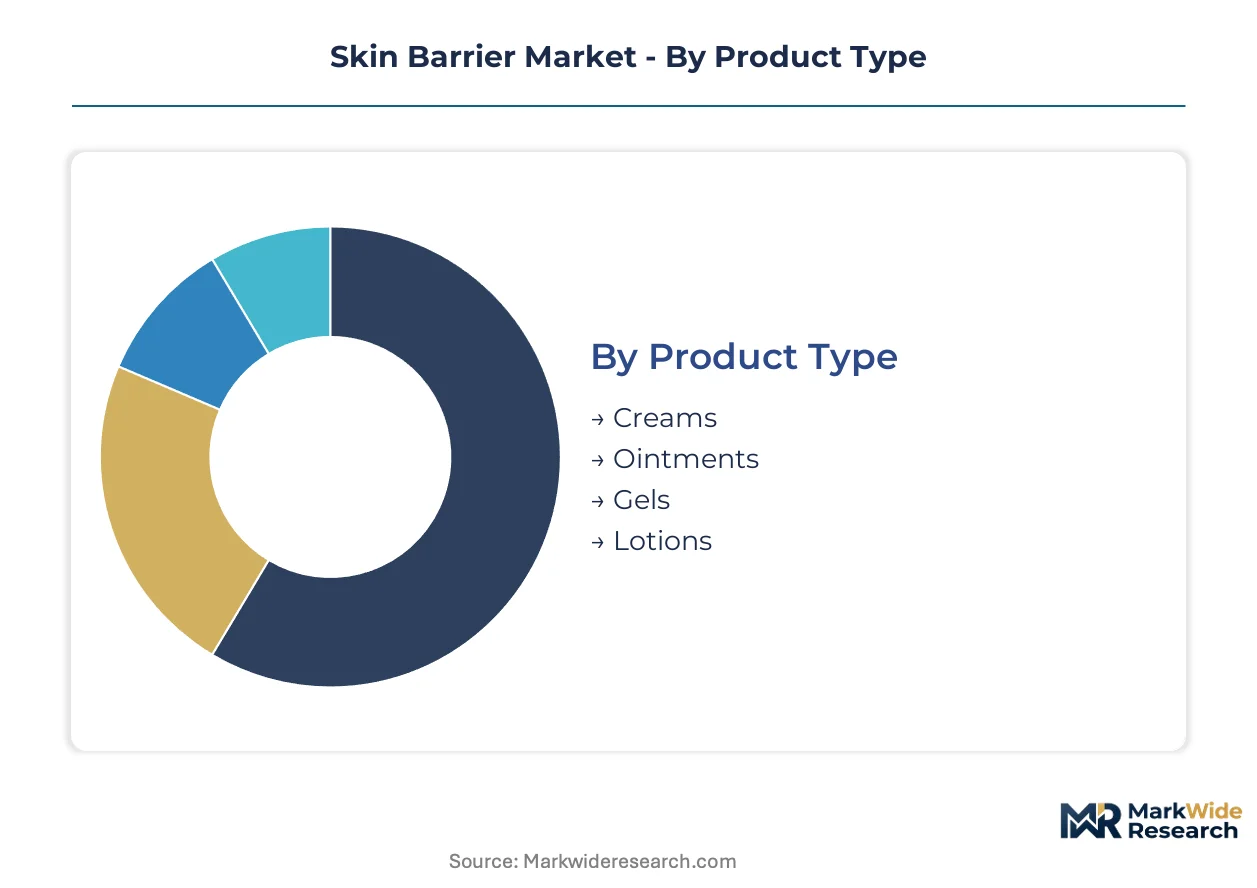
Segmentation in the skin barrier market reveals distinct formulation-performance tradeoffs and channel-specific purchasing behaviors. Manufacturers configure polymer supply chains and clinical evidence packages differently for each tier, creating divergent margin structures across the value chain.
Product Type:
Reformulation cycles are shortening as silicone elastomers displace legacy compositions in high-moisture environments, forcing R&D investment toward vapor-permeable platforms.
- Creams:Petrolatum-ceramide emulsions dominate retail pharmacy shelves and hospital formulary listings. Demand concentrates in US long-term care networks where standardized protocols favor pump-dispensed formats for incontinence-associated dermatitis prevention.
- Ointments:Zinc oxide-petrolatum matrices provide occlusive protection for neonatal skin integrity protocols. German NICU networks are expanding procurement of these formulations as EMA MDR biocompatibility requirements harden evidence standards for pediatric claims.
- Gels:Silicone-polymer hybrids capture margin pools in South Korean aesthetic dermatology channels where post-procedure recovery drives premium positioning.
- Lotions:Lower-viscosity formats serve high-volume institutional contracts with cost-sensitive procurement committees.
Creams sit at the top of the volume ranking, with gels climbing the fastest.
Application:
Clinical validation depth varies sharply across use cases, determining reimbursement access and development timeline economics.
- Dermatology:Lipid-replacement ceramide therapies are expanding in German outpatient clinics. EMA MDR Annex I classifications are accelerating toxicology investments for epidermal repair claims involving compromised barrier function.
- Wound Care:Hydrocolloid and silicone adhesive platforms command the deepest evidence requirements. FDA 510(k) clearance pathways and ISO 10993 testing expansions are lengthening commercial timelines for polymer film interfaces.
- Cosmetic:Post-procedure recovery segments in South Korea and the United States favor gel formats with biocompatibility validation for aesthetic dermatology channels.
- Pediatric Care:Neonatal intensive care protocols in US and German hospital networks are standardizing skin integrity prevention bundles, generating volume pull for zinc oxide-based barriers.
Wound Care anchors revenue concentration due to reimbursement density, while Pediatric Care is expanding most quickly through protocol standardization.
End User:
Procurement authority fragmentation creates distinct pricing architectures and evidence requirements across institutional and clinical settings.
- Hospitals:Group purchasing organizations in the United States are consolidating supplier rosters around outcome-validated portfolios tied to skin integrity metrics. Silicone-based formulations are capturing share in high-acuity wound care units.
- Clinics:German outpatient dermatology networks are driving demand for ceramide-dominant formulations as reimbursement code consolidation creates access windows.
- Home Care:Direct-to-patient subscription models are emerging in US long-term care networks, with pharmacy benefit managers piloting outcome-linked coverage for chronic wound management.
- Dermatologists:Aesthetic channels in South Korea concentrate demand for gel-format barriers with post-procedure biocompatibility credentials.
Hospitals command the largest procurement volumes, with home care channels gaining share fastest through telemedicine-integrated dispensing models.
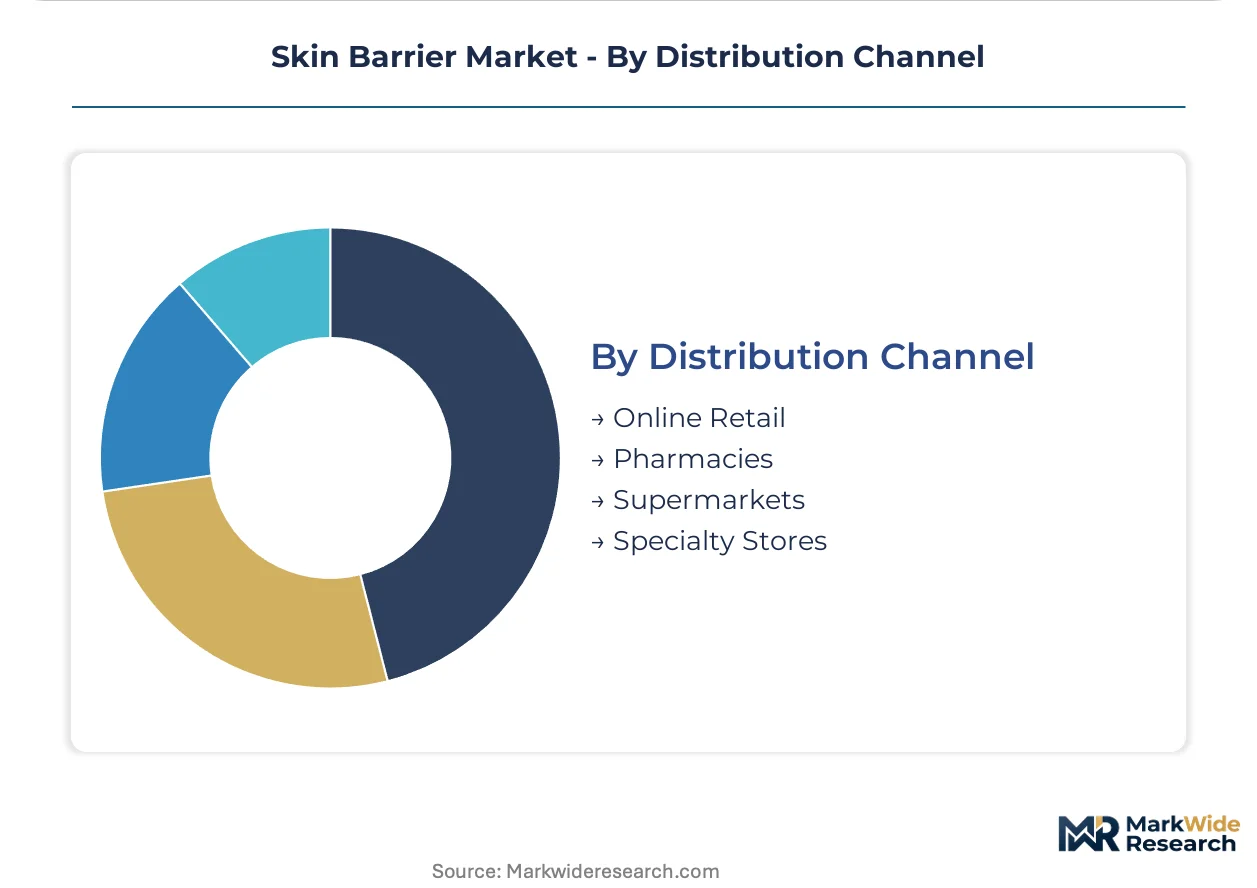
Distribution Channel:
Channel mix determines packaging specifications, margin retention, and patient education burden for manufacturers.
- Pharmacies:Retail pharmacy networks in Germany and the United States dominate cream and ointment volumes, with pump-dispensed formats preferred for institutional compliance.
- Online Retail:Direct-to-consumer platforms are capturing pediatric and cosmetic segments where patient education content substitutes for clinical counseling.
- Specialty Stores:Medical supply distributors serve ostomy and wound care segments with clinician-trained sales support.
- Supermarkets:Mass retail channels concentrate economy-tier petrolatum formulations with minimal clinical positioning.
Pharmacies retain the highest volume share, with online retail showing the steepest expansion trajectory through subscription model adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicone-polymer manufacturing clusters in South Korea anchor formulation supply for advanced skin barrier systems across Asia-Pacific and European export markets.
United States
Hospital procurement consolidation and NICU protocol standardization drive volume concentration. FDA 510(k) clearance pathways streamline pediatric indication timelines. Group purchasing organizations in the Midwest and Southeast states are displacing fragmented vendor relationships with single-source contracts tied to skin integrity metrics.
Germany
Outpatient dermatology networks and notified body stringency create dual demand for ceramide therapies and biocompatibility documentation. EMA MDR Annex I classifications are accelerating toxicology investments for epidermal repair claims. The Ruhr chemical corridor houses acrylic polymer converters serving Western European barrier film production.
South Korea
Aesthetic dermatology channels and telemedicine-integrated dispensing generate premium gel format demand. MFDS biocompatibility standards align with expanded ISO 10993 testing protocols. The Gyeonggi-do polymer cluster supplies silicone adhesive precursors to domestic and export formulation houses.
Japan
Aging demographics and chronic wound prevalence expand home care subscription models. PMDA medical device classifications require clinical evidence packages for barrier claims involving compromised epidermis. The Kansai region maintains specialty chemical production for petrolatum-ceramide emulsion components.
United Kingdom
Long-term care network procurement and NHS formulary consolidation shape cream and ointment volumes. MHRA post-Brexit regulatory alignment with MDR standards extends development timelines for polymer film interfaces. The Southeast England logistics corridor distributes pump-dispensed formats to institutional buyers.
Skin Barrier Market Vendor Landscape
Global majors compete with regional champions across formulation technology and procurement channel access. Market structure tilts toward consolidation among hospital-supply incumbents with established GPO relationships, while specialty dermatology channels sustain mid-tier fragmentation. Three archetypes dominate: diversified medical device conglomerates with wound care divisions, pure-play ostomy and continence specialists, and private-label converters serving long-term care networks. Competitive moves center on silicone-polymer supply chain security and EMA MDR toxicology capacity expansion.
Among diversified medical device conglomerates, 3M Company and Stryker Inc. occupy positions anchored by proprietary polymer platforms and hospital procurement channel dominance. Coloplast Corp exemplifies the ostomy-specialist archetype through Nordic manufacturing footprint and premium positioning in adjacent skin protection. Medline Industries LP sits within the private-label tier, competing on volume across US long-term care facilities. Hollister Inc. and ConvaTec Inc. represent mid-scale specialists with concentrated wound care and ostomy portfolios. B. Braun Melsungen AG anchors the German-speaking clinical channel with integrated hospital supply relationships.
| Leading Market Players |
|---|
| Hollister Inc. |
| Stryker Inc. |
| ConvaTec Inc. |
| Medline Industries LP |
| DermaRite Industries LLC |
| 3M Company |
| B. Braun Melsungen AG |
| Integra Lifesciences Corporation |
| Coloplast Corp |
| Others |
Supply Flow & Price Mechanics
Hospital procurement consolidation in the United States is forcing formulation houses to reconfigure polymer supply chains around outcome-validated portfolios, compressing margins for converters lacking GPO contracts while elevating pricing power among silicone-elastomer incumbents with NICU protocol approvals.
Pricing Analysis
Petrochemical feedstock volatility in dimethicone and petrolatum markets passes through to finished barrier pricing with 60-90 day lags, compressing converter margins when refinery output tightens. Three-tier pricing structure across premium, standard, and economy levels separates silicone-polymer hybrids with ISO 10993 validation from zinc oxide-petrolatum matrices and commodity petrolatum creams. Pricing pressure stems from group purchasing organization concentration in Midwest and Southeast long-term care networks. Home care subscription buyers exhibit highest price sensitivity; aesthetic dermatology channels in South Korea show least.
Supply Chain Analysis
EMA MDR Annex I biocompatibility expansions are reshaping local-content calculations for EU market access, accelerating toxicology capacity investments in Germany and displacing imports lacking notified body relationships. Acrylic polymer platform supply clusters in South Korea and China; silicone adhesive precursor production concentrates in Gyeonggi-do and the Ruhr corridor. Raw material dependencies span dimethicone, ceramide lipids, and zinc oxide feedstocks. Single-source vulnerability runs through East Asian polymer concentration. Distribution runs through hospital procurement committees, specialty medical distributors, and direct-to-patient subscription platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
German outpatient dermatology reimbursement consolidation against US GPO pricing pressure creates geographic-arbitrage opportunities for ceramide-dominant formulations with EMA MDR clearance.
For Market Incumbents: Acquire toxicology testing capacity and notified body relationships to defend against ISO 10993 documentation burdens that favor diversified medical device conglomerates. Secure backward integration into silicone-polymer precursor supply through South Korean chemical park partnerships. Channel control through hospital system exclusive contracts represents the critical defensive lever against private-label volume erosion. For New Entrants and Emerging Players: Telemedicine-integrated dispensing models for chronic wound home care represent the most penetrable white-space target, bypassing GPO procurement consolidation through direct-to-patient subscription economics. German outpatient dermatology networks offer secondary entry through reimbursement code consolidation for ceramide therapies. A go-to-market angle anchored on outcome-linked pharmacy benefit manager coverage pilots accelerates access. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale specialists possessing EMA MDR toxicology infrastructure and Nordic manufacturing footprints serving ostomy-adjacent skin protection. Long-term viability over a 5-10 year horizon hinges on silicone-elastomer formulation patents and pediatric indication portfolios. Watch FDA 510(k) clearance velocity for pediatric NICU indications as the inflection signal for premium valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| Ceramide Science Investment | German outpatient dermatology networks are expanding lipid-replacement protocols with EMA MDR validation requirements. |
| Silicone-Polymer Supply Security | South Korean Gyeonggi-do chemical park partnerships anchor vapor-permeable elastomer access for advanced wound care. |
| Pediatric Indication Expansion | FDA 510(k) clearance pathways for NICU protocols generate fastest volume growth through standardized skin integrity bundles. |
| Telemedicine-Integrated Dispensing | Direct-to-patient subscription models in US long-term care networks bypass GPO procurement consolidation. |
| Biocompatibility Testing Capacity | ISO 10993 cytotoxicity and sensitization documentation determines EU market access under EMA MDR Annex I. |
Methodological Framework
Multiple input streams — primary interviews with hospital procurement managers, biomedical engineers, and GPO contracts specialists; secondary validation through FDA 510(k) filings, EMA MDR submission databases, and hospital procurement records; and customs data on polymer precursor trade flows — were reconciled through bottom-up and top-down triangulation to construct segment-level demand estimates.
Historical volume trajectories were cross-referenced against expert panel inputs across formulation technology, application, and end-user dimensions to anchor CAGR derivation over the projection horizon. Modeled segmentation spans product type, clinical application, procurement channel, and geographic regulatory cluster. Forecast inputs incorporated ISO 10993 testing burden timelines, NICU protocol standardization rates, and reimbursement code consolidation patterns.
Underlying measurement precision varies by segment; wound care and pediatric care applications carry tighter precision than cosmetic recovery channels due to deeper procurement data availability. Forecasts reflect assumptions around regulatory clearance velocity and polymer feedstock cost stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Skincare
Germany Skincare Product Market
Skincare
Facial Mask Market
Skincare
ASEAN Sensitive Skin Care Market
Skincare
Global Healthcare Wipes Market
Skincare
Facial Massage Cream Market
Skincare
Global Physician Dispensed Cosmeceuticals Market
Skincare
Africa Cosmeceutical Market
Skincare
Skin Resurfacing Market
Skincare
Skin Toner Market
Skincare
Hidradenitis Suppurativa Market
Skincare
Skin Replacement Market
Skincare
United Kingdom Skincare Market
Skincare
Skincare Ingredients Market
Skincare
Cosmeceutical Ingredients Market
Skincare
Skin Care Body Products Market
Skincare
Herbal Skincare Products Market