
 United Kingdom Skincare Market | 2026-2036
United Kingdom Skincare Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Skincare Market Outlook
Multi-step regimen bundling is hardening as the dominant product-configuration pattern across prestige and masstige tiers. L'Oréal leverages its dermatological science heritage to anchor clinical credibility in bundled routines. Beiersdorf competes through Nivea's accessible tiering, while Estée Lauder Companies differentiates via prestige capsule collections.
United Kingdom skincare encompasses topical formulations designed for epidermal maintenance, typically specifying pH-balanced compositions between 4.5 and 5.5 and incorporating active concentrations regulated under safety thresholds. These products serve consumer-driven prevention, treatment, and aesthetic enhancement objectives across daily and periodic use cycles. Moisturizers and serums capture the deepest margin pools as consumers prioritize barrier repair and targeted actives over basic cleansing. The ingredient dimension shows botanical extracts gaining traction against synthetic benchmarks as clean-label expectations intensify.
The UK's Office for Product Safety and Standards enforces post-Brexit cosmetics compliance, while Trading Standards monitors claims accuracy, and EU REACH residual obligations continue influencing ingredient permissibility. These frameworks elevate formulation costs but simultaneously create defensible moats for laboratories with established safety dossiers. Stakeholders must track divergence between UK and EU ingredient lists to preempt supply chain disruption and reformulation cycles.
Market Dynamics
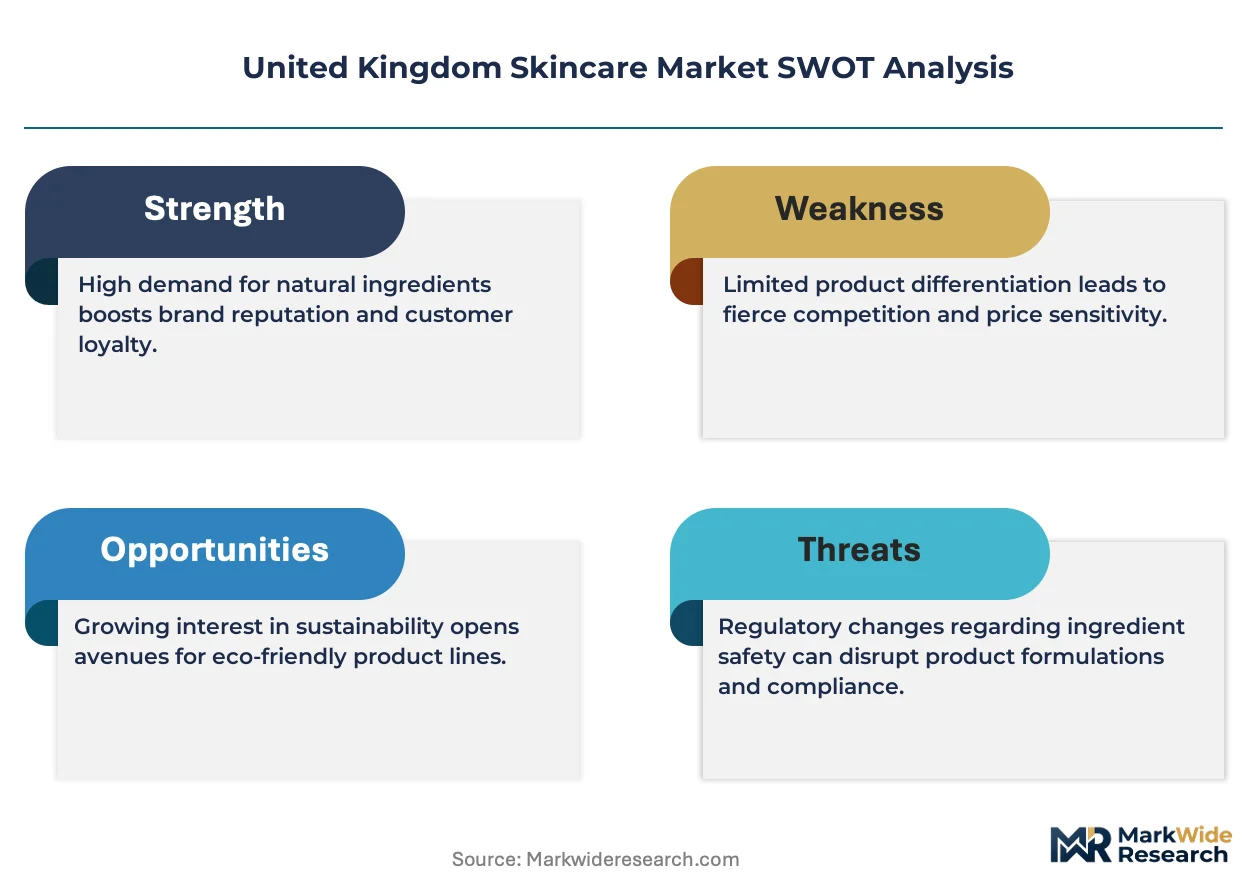
Post-Brexit regulatory divergence between the UK and EU is forcing dual-track compliance investments, reshaping formulation pipelines and supplier qualification protocols across domestic laboratories and international brands operating in British retail channels.
Growth Catalysts
- Men's grooming normalization:Dissolving gendered consumption barriers unlocks incremental household spend as male consumers adopt multi-step routines previously coded feminine.
- Clean-label ingredient premiums:Consumer preference for botanical extracts over synthetic benchmarks drives reformulation cycles and justifies price architecture elevation.
- Greater London retail corridor density:Flagship presence in premium department stores and specialty boutiques concentrates brand visibility and trial conversion.
Market Restraints
- Dual compliance cost burden:The Office for Product Safety and Standards and residual EU REACH obligations require parallel safety dossier maintenance, elevating fixed costs for mid-tier laboratories.
- Active ingredient supply concentration:Niacinamide, retinol, and peptide precursors flow through limited German and Swiss chemical suppliers, creating vulnerability to input disruption.
- Barrier function claim substantiation:Trading Standards scrutiny of dermatological assertions demands clinical trial investment that smaller indie brands cannot fund.
Strategic Opportunities
- Manchester indie brand ecosystem:Lower commercial rent and proximity to Northern England manufacturing clusters enables challenger brand incubation outside London cost structures.
- Subscription-based replenishment models:Direct-to-consumer platforms bypass retailer margin extraction while capturing recurring revenue and consumption data.
- Post-Brexit UKCA marking divergence:Simplified conformity assessment procedures relative to EU CE marking reduce time-to-market for domestically focused product lines.
Industry Challenges
- Formulation chemist scarcity:Brexit-related immigration friction constrains access to EU-trained cosmetic scientists, compressing R&D bandwidth.
- Ingredient list synchronization:Divergent UK-EU prohibited substance schedules force warehouse segmentation and increase working capital requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Skincare Market |
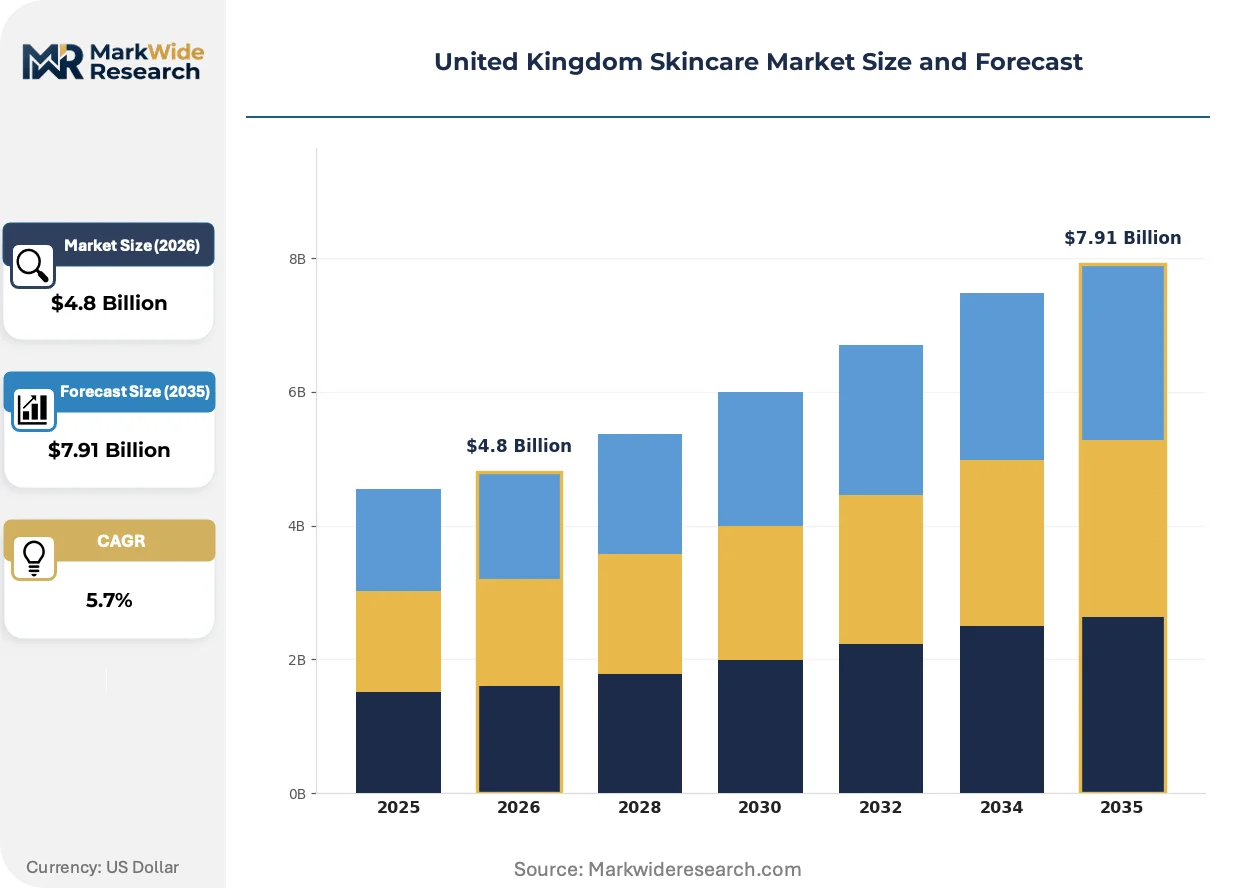
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Moisturizers, Cleansers, Serums, Masks End User: Men, Women, Teenagers, Seniors Ingredient: Natural, Organic, Synthetic, Botanical Distribution Channel: Online, Retail Stores, Pharmacies, Specialty Shops |
| Companies Covered | L'Oréal, Unilever, Procter & Gamble, Estée Lauder Companies, Clarins, Beiersdorf, Shiseido, Allergan, Coty, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Skincare Market Strategic Shifts
Biotechnology-derived actives and microbiome-targeted formulations are displacing conventional chemistry, while regulatory transparency mandates and channel fragmentation reshape how brands build consumer trust and capture margin.
Biotechnology fermentation platforms for producing ceramides and hyaluronic acid is expanding into prestige and masstige tiers simultaneously. Independent British brands and multinational dermatological lines are adopting these bio-identical actives at comparable velocity. The shift is compressing cost differentials between synthetic and bio-engineered ingredients while enabling clean-label claims without performance sacrifice.
The UK's Office for Product Safety and Standards now mandates expanded digital product information files accessible via on-pack QR codes. This transparency obligation elevates documentation costs but simultaneously deflates counterfeit penetration by enabling consumer verification. Prestige brands with established safety dossiers are weaponizing this as a trust-building mechanism against gray-market competitors.
Pharmacy and clinic channels are capturing consultation-driven skincare purchases that department stores once dominated. Boots and independent pharmacy chains are deploying skin diagnostic tools that match consumers to regimen bundles, displacing self-selection in beauty halls. Manchester and Birmingham show the steepest channel-share rotation as regional pharmacy networks invest in trained skincare advisors.
United Kingdom Skincare Market Segmentation
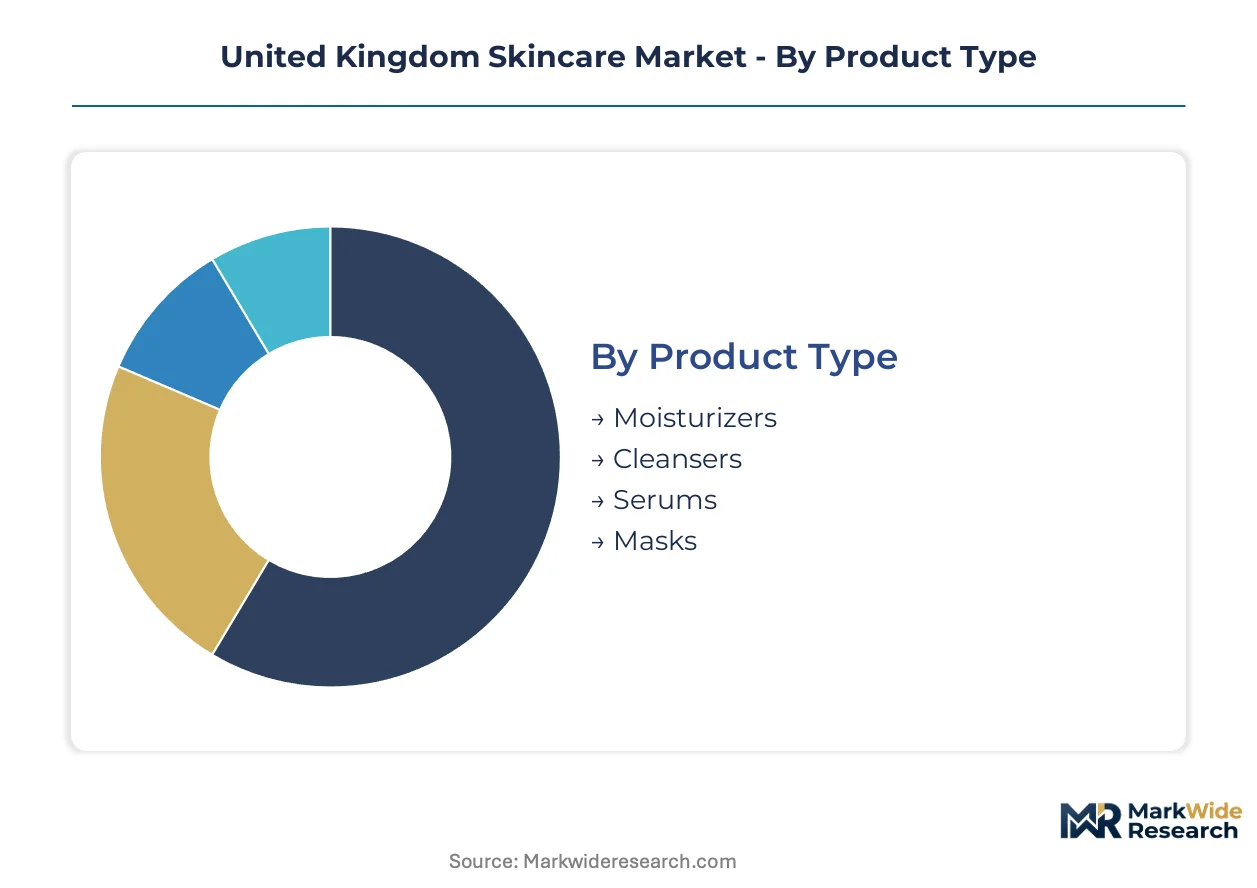
Segmentation in the United Kingdom skincare market reveals how formulation priorities, channel access, and demographic targeting fragment revenue pools. Understanding these divisions exposes where margin concentrates and where challenger positioning remains viable.
Product Type:
Supply concentration in active ingredient sourcing shapes competitive dynamics across product formats, with laboratories prioritizing categories that justify premium positioning through technical differentiation.
- Moisturizers:Barrier-repair formulations incorporating ceramides and hyaluronic acid dominate household penetration. Greater London department stores and Manchester pharmacy networks drive replenishment velocity as consumers prioritize daily epidermal maintenance over episodic treatment.
- Serums:Concentrated active delivery systems specify pH-stabilized compositions between 4.5 and 5.5 for optimal penetration. Northern England manufacturing clusters are expanding fermentation-platform capacity to serve indie brand demand for biotechnology-derived actives.
- Cleansers:pH-balanced surfactant systems compete on gentleness credentials without residue.
- Masks:Periodic treatment formats concentrate trial-driven purchases in specialty retail.
Today's leader: Moisturizers. Tomorrow's challenger: Serums.
End User:
Customer type fragmentation reflects shifting grooming norms, with previously excluded demographics now representing incremental spend capture opportunities for repositioned brands.
- Men:Dissolving gendered consumption barriers unlocks multi-step regimen adoption previously coded feminine. Boots pharmacy networks and direct-to-consumer platforms are capturing this expansion through diagnostic-guided bundle matching.
- Women:Established core demand concentrates in prestige capsule collections and masstige tiered routines. Greater London retail corridor density sustains brand visibility and replenishment loyalty.
- Teenagers:Entry-point price sensitivity drives pharmacy channel preference over department store positioning.
- Seniors:Barrier function and age-specific actives concentrate consultation-driven purchases in clinic-adjacent retail.
Women anchor current volume. Men are climbing the fastest.
Ingredient:
Cost tier stratification separates premium-positioned formulations from accessible alternatives, with clean-label premiums justifying price architecture elevation across positioning tiers.
- Botanical:Plant-derived extracts gain traction against synthetic benchmarks as clean-label expectations intensify. Manchester's emerging indie brand ecosystem leverages proximity to Northern England manufacturing for localized sourcing narratives.
- Natural:Unprocessed ingredient claims require Trading Standards scrutiny compliance that elevates documentation investment.
- Organic:Certification-dependent positioning concentrates in specialty shops and premium online channels.
- Synthetic:Cost-optimized benchmarks retain masstige tier dominance despite clean-label headwinds.
Botanical claims command current premium. Organic certification faces tomorrow's regulatory tightening.
Distribution Channel:
Channel fragmentation is reshaping how brands capture margin, with consultation-driven formats displacing self-selection in regional markets outside London.
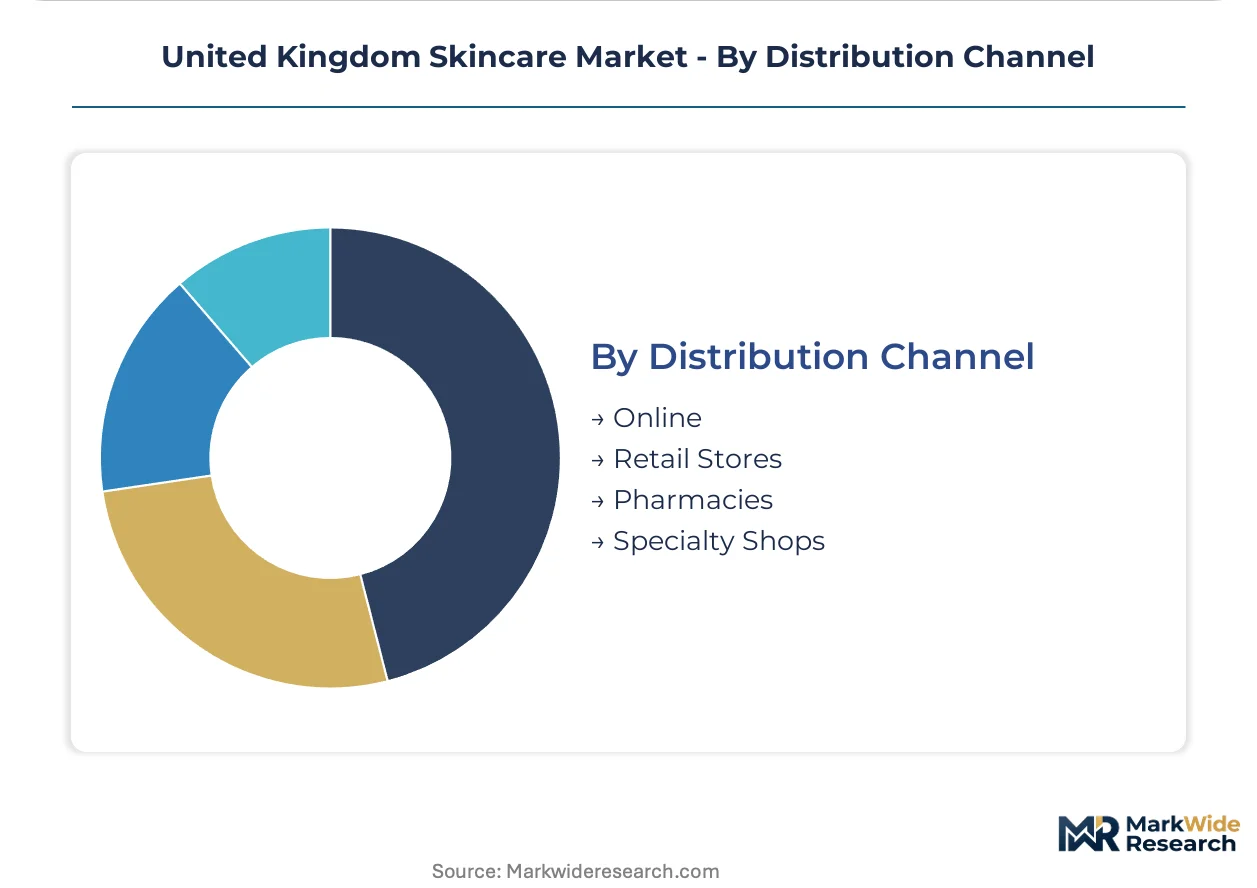
- Pharmacies:Skin diagnostic tools and trained advisor deployment match consumers to regimen bundles. Manchester and Birmingham networks show steepest share rotation as regional pharmacy chains invest in consultation infrastructure.
- Online:Direct-to-consumer platforms bypass retailer margin extraction while capturing recurring revenue through subscription-based replenishment models.
- Retail Stores:Flagship presence in Greater London's premium department stores sustains brand visibility for prestige positioning.
- Specialty Shops:Curated indie brand discovery concentrates in Manchester's lower commercial rent environment.
Pharmacies lead consultation conversion. Online subscription models are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United Kingdom's skincare industry traces its commercial lineage to Victorian-era apothecaries and the post-war expansion of cosmetic science at Port Sunlight and Slough manufacturing clusters.
London and the Southeast
Flagship department stores on Oxford Street and Knightsbridge concentrate prestige brand visibility and trial conversion. The Office for Product Safety and Standards enforces post-Brexit compliance from its London base, elevating documentation requirements for formulations. Greater London's premium retail corridor sustains the deepest margin pools through consultation-driven bundling.
Midlands
Manufacturing heritage in Birmingham and Nottingham supports contract laboratories serving masstige tier production. Trading Standards regional offices monitor claims accuracy across pharmacy and retail channels. The East Midlands pharmaceutical corridor is expanding fermentation-platform capacity for biotechnology-derived actives.
North England
Manchester's emerging indie brand ecosystem leverages lower commercial rent and proximity to Northern England manufacturing clusters. The UKCA marking divergence from EU CE procedures reduces time-to-market for domestically focused product lines. Leeds and Sheffield are incubating challenger brands outside London cost structures.
Scotland
Edinburgh and Glasgow pharmacy networks are deploying skin diagnostic tools that match consumers to regimen bundles. Scotland's devolved health policy creates variation in NHS aesthetic clinic referrals. The Central Belt is capturing consultation-driven purchases previously concentrated in English department stores.
Wales
Cardiff and Newport serve as distribution nodes for Irish Sea retail channels with lower regulatory friction than cross-Channel routes. Welsh manufacturing clusters specialize in botanical extract processing for clean-label formulations. The South Wales corridor is consolidating as a secondary packaging and logistics hub.
United Kingdom Skincare Market Competitive Environment
The competitive structure tilts toward multinational dermatological heritage brands with established safety dossiers. L'Oréal, Unilever, and Procter & Gamble anchor tiered portfolios spanning prestige to mass market positioning. Beiersdorf and Estée Lauder Companies exemplify the dual-track strategy of clinical credibility and accessible tiering. Strategic moves concentrate on multi-step regimen bundling and pharmacy channel consultation infrastructure.
Among French-origin multinationals, L'Oréal and Clarins represent the dermatological science and botanical heritage archetypes respectively. Japanese-listed Shiseido occupies a position bridging Eastern formulation traditions with Western retail penetration. German-based Beiersdorf exemplifies accessible tiering through heritage brand architecture. These anchors demonstrate how regulatory compliance scale and R&D bandwidth determine competitive viability under post-Brexit divergence.
| Leading Market Players |
|---|
| L'Oréal |
| Unilever |
| Procter & Gamble |
| Estée Lauder Companies |
| Clarins |
| Beiersdorf |
| Shiseido |
| Allergan |
| Coty |
| Others |
Value Chain & Pricing Dynamics
Pharmacy chain procurement managers in Greater London and Manchester negotiate multi-year supply agreements that lock in volume discounts, anchoring a three-tier pricing structure across premium, standard, and economy levels. Their consolidated purchasing power compresses margins for mid-tier laboratories while rewarding scale players with predictable offtake.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates prestige capsule collections from masstige tiered routines and accessible pharmacy lines. Price differentiation hinges on certification grade under UKCA marking and brand heritage credibility. Cost compression in the masstige tier is intensifying because dual compliance requirements elevate fixed safety dossier costs. Teenage entry-point buyers exhibit highest price sensitivity; prestige serum purchasers show least.
Supply Chain Analysis
Chemist workforce availability constraints in Northern England manufacturing clusters are compressing R&D bandwidth as Brexit-related immigration friction limits EU-trained cosmetic scientist access. Active ingredient sourcing draws from German and Swiss chemical suppliers for niacinamide and peptide precursors, with botanical extract processing concentrated in Welsh manufacturing corridors. Single-source vulnerability in fermentation-platform capacity creates exposure to input disruption. Distribution runs through pharmacy networks and direct-to-consumer subscription platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United Kingdom skincare market functions as a geographic-arbitrage play where Manchester's lower commercial rent and proximity to Northern England manufacturing clusters offers 30-40% cost savings versus Greater London operations, while UKCA marking divergence from EU CE procedures accelerates time-to-market for domestically focused lines.
For Market Incumbents: Anticipate regulatory divergence between UK and EU ingredient safety standards by maintaining parallel safety dossiers and preemptively warehouse-segregating formulations. Prioritize backward integration into biotechnology fermentation platforms for ceramide and hyaluronic acid production to secure supply against German and Swiss chemical supplier concentration. Channel control through pharmacy diagnostic tool deployment defends margin position against direct-to-consumer subscription encroachment. For New Entrants and Emerging Players: UKCA marking divergence from EU CE procedures in the United Kingdom opens a window for challenger brand incubation targeting Manchester's emerging indie brand ecosystem with lower commercial rent structures. White-space targets include men's grooming normalization through diagnostic-guided bundle matching at Boots pharmacy networks, and subscription-based replenishment models bypassing retailer margin extraction. Go-to-market through skin diagnostic tool partnerships with regional pharmacy chains in Birmingham and Leeds accelerates trial conversion. For Investors and Strategic Acquirers: French-origin multinational dermatological heritage brands are the most active acquirer in this space, seeking biotechnology fermentation platform capabilities and established UK safety dossiers. Long-term viability centers on laboratories with defensible moats from post-Brexit compliance scale and clean-label botanical sourcing narratives. Monitor Office for Product Safety and Standards ingredient list divergence announcements as early signals for supply chain disruption and reformulation cycle triggers.| Strategic Initiative | Industry Significance |
|---|---|
| Biotechnology Fermentation Platform Investment | Secures captive supply of bio-identical ceramides and hyaluronic acid against German supplier concentration. |
| UKCA Marking Fast-Track Certification | Accelerates time-to-market for domestically focused product lines versus EU CE marking complexity. |
| Pharmacy Diagnostic Tool Deployment | Captures consultation-driven purchases from department store self-selection in Manchester and Birmingham. |
| Subscription-Based Replenishment Model | Bypasses retailer margin extraction while capturing recurring revenue and consumption data. |
| Botanical Extract Localized Sourcing | Leverages Welsh manufacturing corridors for clean-label claims and regulatory transparency compliance. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with formulation chemists, pharmacy category buyers, regulatory affairs specialists at the Office for Product Safety and Standards, and indie brand founders with secondary validation. Secondary sources encompassed UK customs records, Trading Standards enforcement disclosures, EU REACH substance restriction updates, and Boots and Superdrug retail audit data. Bottom-up demand modeling and top-down market sizing triangulated volume estimates.
Historical reference periods anchored the projection horizon across the analysis window, with segmentation dimensions spanning product type, end user demographic, ingredient classification, and distribution channel. CAGRs derived from regression analysis against macroeconomic indicators and category penetration rates. Industry-specific forecast inputs included men's grooming adoption velocity and biotechnology fermentation platform capacity expansion timelines.
Revisions become necessary when regulatory divergence accelerates, active ingredient supply disruptions materialize, or pharmacy channel share rotation exceeds modeled thresholds. Practitioners should monitor Office for Product Safety and Standards substance schedule updates and Northern England manufacturing cluster workforce migration patterns for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Skincare
Ampoule Cream Market
Skincare
Vitamin C Serum Market
Skincare
Anti-Aging Services Market
Skincare
Rice Water Skincare Market
Skincare
Professional Skin Care Market
Skincare
Personalized Skin Care Products Market
Skincare
India Skin Care Products Market
Skincare
Facial Erythema Treatment Market
Skincare
Exfoliators and Scrubs Market
Skincare
Anti-Acne Dermal Patch Market
Skincare
Medicine Skin Care Market
Skincare
Retinol Skincare Product Market
Skincare
Retinoids Market
Skincare
Skincare Cdmo and Cmo Market
Skincare
Skin Grafting System Market
Skincare
Africa Cosmeceutical Market