
 Skin Boosters Market | 2026-2036
Skin Boosters Market Size, Share, and Industry Trends Forecast 2026-2036
Skin Boosters Market Intelligence
Buyer concentration among dermatology clinics is recalibrating as medical spas and certified beauty salons fragment the professional channel. Teoxane leverages its Swiss manufacturing base to sustain premium positioning in hyaluronic acid injectables. Galderma anchors European distribution through physician-only networks, while Merz Aesthetics competes on R&D intensity in polylactic acid formulations.
Skin boosters comprise biocompatible injectable or topical formulations, typically hyaluronic acid suspensions at 12-20 mg/mL concentration, designed to restore dermal hydration and stimulate collagen neogenesis without volumizing effect. Hyaluronic acid products dominate current revenue pools due to established safety profiles and reversible action, while poly-L-lactic acid segments capture faster growth among patients seeking gradual, long-duration collagen remodeling. Delivery mode insights reveal injectable routes command premium pricing, though electroporation devices are gaining traction in beauty salon channels seeking non-needle alternatives.
The EU MDR and FDA biologics licensing frameworks impose escalating clinical evidence requirements on novel skin booster formulations, directly shaping R&D budgets and time-to-market curves. South Korea's MFDS maintains distinct approval pathways that accelerate domestic innovation while creating parallel standards for export markets. Stakeholders must monitor regulatory divergence between aesthetic-device and pharmaceutical classifications, as this boundary determines market access costs and competitive moat depth.
Market Dynamics
Regulatory divergence between aesthetic-device and pharmaceutical classifications is forcing manufacturers to maintain parallel compliance infrastructures, with the EU MDR's biocompatibility tightening and South Korea's MFDS acceleration creating divergent time-to-market curves that reshape competitive positioning.
Growth Catalysts
- EU MDR biocompatibility mandates:Stricter hyaluronic acid filler standards in Europe are compressing substandard supplier bases, elevating incumbent manufacturers with established clinical dossiers.
- Electroporation device adoption:Non-needle delivery systems are expanding into beauty salon channels seeking needle-free alternatives to physician-administered microinjections.
- Seoul dermatology clinic density:South Korea's aesthetic medicine cluster concentration generates protocol innovation spillovers that export to Southeast Asian markets.
Market Restraints
- Hyaluronic acid raw material concentration:Fermentation-derived sodium hyaluronate supply concentrates among Chinese and Japanese biotech suppliers, creating input cost volatility.
- FDA biologics licensing timelines:Novel polylactic acid formulations face extended clinical evidence requirements that stretch R&D amortization periods.
- Reversible action limitation:Hyaluronic acid's enzymatic reversability constrains duration-based pricing premiums against permanent collagen stimulators.
Strategic Opportunities
- Brazil ANVISA pathway acceleration:Latin America's largest aesthetic medicine market maintains faster approval timelines for established hyaluronic acid formulations than FDA or EMA processes.
- Poly-L-lactic acid segment expansion:Gradual collagen remodeling protocols capture patients seeking natural-appearing outcomes without immediate volumizing effects.
- At-home microneedling convergence:Consumer-grade electroporation devices paired with topical booster serums create channel bypass opportunities around professional-only injectable networks.
Industry Challenges
- Physician injector certification scarcity:Microinjection technique mastery requires supervised training hours that lag clinic expansion plans in secondary cities.
- Cross-border regulatory dossier fragmentation:Parallel MFDS, FDA, and EMA submission requirements multiply clinical trial costs for novel formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Skin Boosters Market |
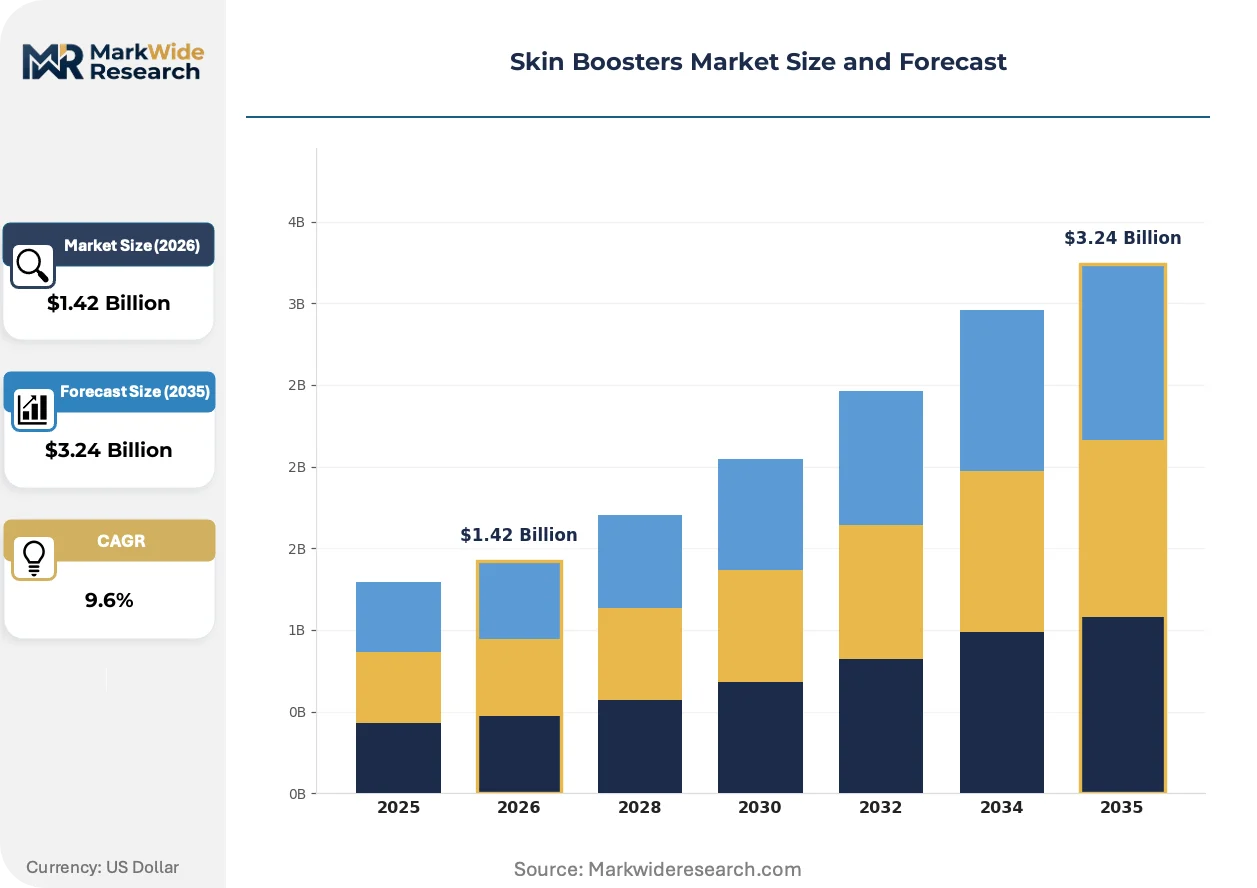
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $3.24 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hyaluronic Acid, Calcium Hydroxylapatite, Poly-L-lactic Acid, Microneedling Delivery Mode: Injectable, Topical, Microdermabrasion, Electroporation End User: Dermatology Clinics, Beauty Salons, Medical Spas, Home Users Application: Skin Hydration, Anti-Aging, Acne Scarring, Skin Rejuvenation |
| Companies Covered | Teoxane, HUGEL, Galderma, IBSA Farmaceutici, Croma-Pharma, Allergan Aesthetics, Sinclair Pharma, Bloomage Biotechnology Corporation Limited, Merz Aesthetics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Skin Boosters Market Strategic Shifts & Innovations
Needle-free delivery modalities are compressing the traditional physician-clinic monopoly over skin booster administration, while regulatory frameworks in major markets diverge on classification boundaries between cosmetics, devices, and pharmaceuticals.
Multi-molecular-weight hyaluronic acid complexes are expanding into premium service tiers through sustained-release formulations that extend hydration duration beyond standard 12-20 mg/mL suspensions. Seoul dermatology clinics pioneered these protocols, with adoption now visible in Bangkok and Singapore aesthetic medicine practices. The technology is expanding into maintenance-interval compression, enabling clinics to capture recurring revenue at shortened treatment cycles.
The EU MDR's 2021 implementation tightened biocompatibility testing requirements for hyaluronic acid fillers previously grandfathered under the Medical Device Directive. Manufacturers must now submit extended cytotoxicity and sensitization data for renewal approvals. European physician-only networks are consolidating around suppliers with dossier-ready portfolios, compressing distributor margins.
Patient preference is rotating toward gradual, imperceptible aesthetic improvement over immediate volumizing outcomes. Poly-L-lactic acid protocols displace hyaluronic acid in Seoul's premium anti-aging segments, with treatment plans spanning 3-6 month collagen neogenesis windows. This behavioral shift is most visible among 35-50 year-old demographics in South Korea and Japan, where natural-appearing results command price premiums.
Skin Boosters Market Segmentation
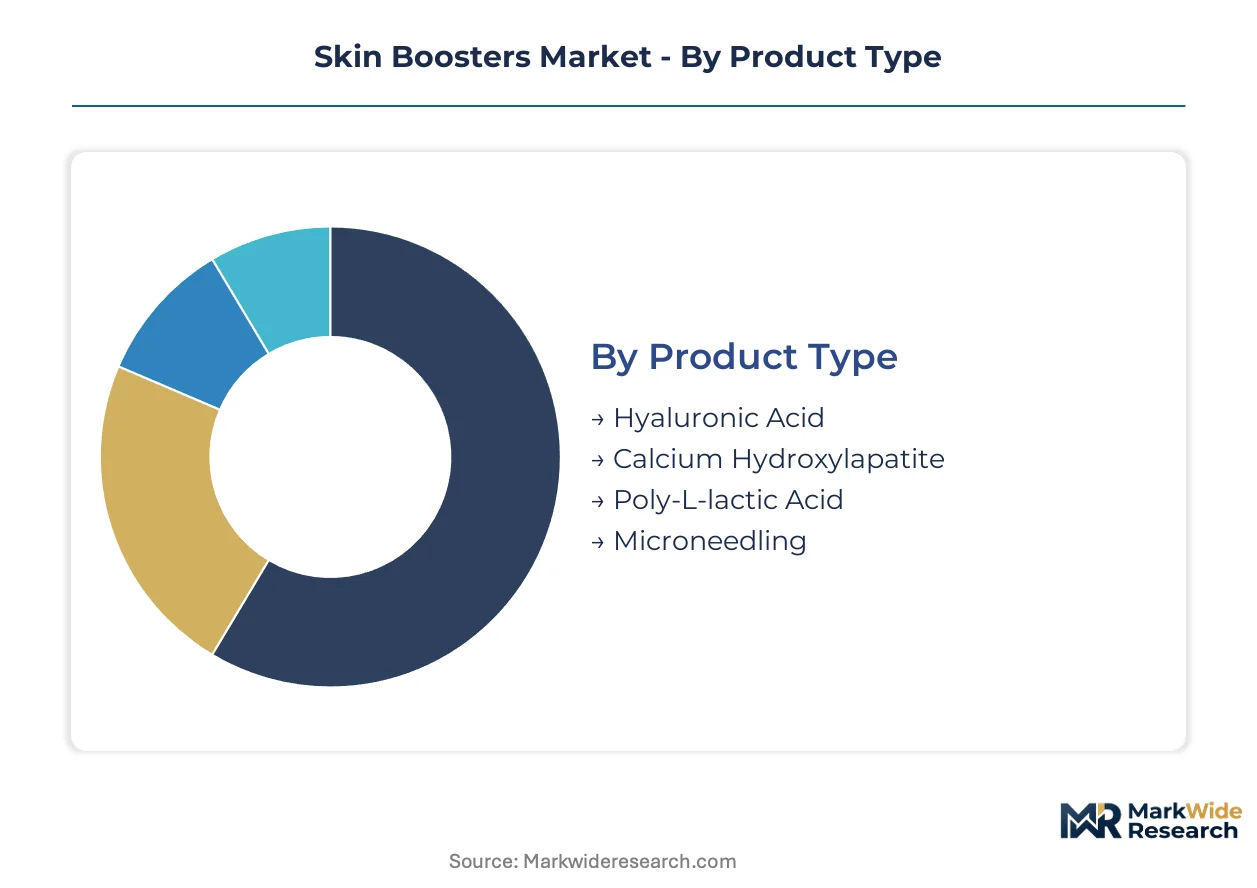
Skin booster segmentation reveals how formulation chemistry, delivery technology, and treatment setting interact to determine pricing power and regulatory pathway. Each dimension carries distinct margin profiles and compliance burdens that reshape competitive positioning.
Product Type:
Supply concentration in fermentation-derived raw materials concentrates manufacturing advantage among established hyaluronic acid producers, while novel biostimulators face extended qualification timelines.
- Hyaluronic Acid:Cross-linked sodium hyaluronate suspensions at 12-20 mg/mL concentration dominate current revenue pools due to established safety profiles and enzymatic reversibility. Seoul dermatology clinics and Bangkok aesthetic medicine practices anchor demand for sustained-release multi-molecular-weight complexes.
- Poly-L-lactic Acid:Biodegradable polymer microparticles stimulate gradual collagen neogenesis over 3-6 month windows without immediate volumizing effect. Premium anti-aging segments in South Korea and Japan favor this modality for natural-appearing outcomes, displacing hyaluronic acid among 35-50 year-old demographics.
- Calcium Hydroxylapatite:Mineral-based biostimulator with longer duration than hyaluronic acid formulations. Demand concentrates in physician-administered protocols requiring advanced injection technique certification.
- Microneedling:Mechanical collagen induction paired with topical booster serums. Beauty salon channels in Southeast Asia adopt this as a needle-free alternative to injectable protocols.
Hyaluronic acid absorbs the bulk of installed capacity; poly-L-lactic acid is expanding most quickly.
Delivery Mode:
Cost tier stratification separates physician-administered premium services from device-mediated salon offerings, with at-home alternatives compressing margins at the economy level.
- Injectable:Microinjection protocols command premium pricing through physician certification requirements and immediate dermal placement precision. EU MDR biocompatibility tightening and FDA biologics licensing frameworks elevate compliance costs for novel formulations.
- Electroporation:Non-needle delivery systems using electrical pulses to enhance topical penetration. Beauty salon channels in Singapore and Bangkok adopt these devices to bypass physician-only network constraints.
- Topical:Booster serums paired with consumer-grade application devices. Home user segments drive volume at compressed price points relative to professional administration.
- Microdermabrasion:Mechanical exfoliation combined with infusion protocols. Medical spa channels favor this hybrid approach for patient comfort and reduced downtime positioning.
Injectable routes capture the highest margin per treatment; electroporation is climbing the fastest as salon channels seek regulatory arbitrage opportunities.
End User:
Customer type fragmentation is redistributing volume across professional tiers, with certification scarcity creating bottlenecks in clinic expansion while salons capture maintenance-protocol patients.
- Dermatology Clinics:Physician-supervised settings with full injectable licensing and advanced technique training. Seoul's cluster density generates protocol innovation that exports to Southeast Asian markets.
- Medical Spas:Hybrid facilities operating under physician oversight with expanded service menus. These venues capture patients seeking convenience without hospital-grade overhead.
- Beauty Salons:Non-physician settings limited to needle-free delivery modalities. Electroporation device adoption concentrates here as regulatory frameworks permit broader operator scopes.
- Home Users:Consumer-grade microneedling rollers and topical serums. At-home convergence creates channel bypass around professional-only injectable networks.
Dermatology clinics retain the premium tier; beauty salons are gaining share fastest through device-based service expansion.
Application:
Maturity gradients separate established hydration protocols from emerging indication expansions, with anti-aging commanding price premiums against commoditized rejuvenation services.
- Anti-Aging:Collagen neogenesis and dermal remodeling protocols targeting fine lines and laxity. Poly-L-lactic acid formulations displace hyaluronic acid in premium segments where gradual, imperceptible improvement commands price premiums.
- Skin Hydration:Baseline moisture restoration using hyaluronic acid suspensions. This indication anchors volume across all professional tiers but faces margin compression from at-home topical alternatives.
- Acne Scarring:Biostimulator protocols targeting atrophic scar remodeling. Physician injector certification requirements concentrate delivery in dermatology clinic settings.
- Skin Rejuvenation:General maintenance protocols with shortest treatment intervals. Medical spas and beauty salons capture recurring revenue through compressed maintenance cycles.
Skin hydration absorbs the bulk of treatment volume; anti-aging applications are expanding most quickly as patient preferences rotate toward gradual collagen remodeling outcomes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fermentation-derived sodium hyaluronate supply concentrates among Chinese and Japanese biotech suppliers, anchoring raw material flows into finished formulation networks across East Asia and export markets.
South Korea
Seoul's Gangnam district hosts the densest cluster of dermatology clinics administering microinjection protocols worldwide. MFDS maintains distinct approval pathways that accelerate domestic innovation while creating parallel standards for export markets. The Seoul Capital Area generates protocol innovations that migrate to Bangkok and Singapore aesthetic medicine practices.
United States
FDA biologics licensing frameworks impose escalating clinical evidence requirements on novel polylactic acid formulations, stretching R&D amortization periods for manufacturers. Physician-only distribution networks consolidate around suppliers with dossier-ready portfolios. The Greater Los Angeles and Miami metropolitan areas concentrate demand for premium anti-aging injectable services.
Germany
EU MDR biocompatibility mandates compress substandard supplier bases, elevating incumbent manufacturers with established clinical dossiers. EMA oversight of hyaluronic acid fillers tightens cytotoxicity and sensitization data requirements for renewal approvals. The Munich-Stuttgart corridor anchors specialized manufacturing of sustained-release multi-molecular-weight complexes.
Brazil
ANVISA maintains faster approval timelines for established hyaluronic acid formulations than FDA or EMA processes, attracting portfolio prioritization from multinational suppliers. São Paulo's aesthetic medicine market absorbs premium-tier volume across injectable and device-mediated delivery modes. The Southeast region concentrates physician injector training programs serving Latin American markets.
Japan
PMDA oversight aligns with international standards while maintaining distinct documentation requirements for collagen-stimulating biostimulators. Tokyo and Osaka metropolitan areas drive demand for gradual, imperceptible aesthetic improvement protocols among 35-50 year-old demographics. The Kanto region imports Seoul-developed treatment plans adapted for domestic patient preferences.
Skin Boosters Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue electroporation device and at-home delivery alternatives to bypass physician-only network constraints. Market structure consolidates around Swiss and European manufacturers with dossier-ready portfolios under EU MDR frameworks, while Asian suppliers compete on fermentation scale and cost position. Strategic archetypes include premium-positioned hyaluronic acid specialists, diversified biostimulator portfolio holders, and device-mediated delivery innovators. Competitive moves concentrate on geographic expansion into Brazil and Southeast Asia, plus portfolio diversification into poly-L-lactic acid formulations.
Within the premium-tier vector, Teoxane leverages its Swiss manufacturing base to sustain positioning in hyaluronic acid injectables. Galderma anchors European distribution through physician-only networks, while Merz Aesthetics occupies a position in biostimulator research intensity. Bloomage Biotechnology Corporation Limited represents Chinese fermentation scale advantage in raw material supply. These three exemplify how geographic origin and corporate structure map onto divergent strategic pathways.
| Leading Market Players |
|---|
| Teoxane |
| HUGEL |
| Galderma |
| IBSA Farmaceutici |
| Croma-Pharma |
| Allergan Aesthetics |
| Sinclair Pharma |
| Bloomage Biotechnology Corporation Limited |
| Merz Aesthetics |
| Others |
Cost & Logistics Intelligence
Physician-certification tiering bifurcates the skin booster market into premium injectable protocols and device-mediated salon services, with this divergence manifesting in bundled warranty structures for clinical outcomes versus unbundled equipment leases for electroporation operators. Pricing power concentrates with Swiss and European manufacturers holding EU MDR dossiers, while supply chain configurations anchor on fermentation scale in Chinese and Japanese biotech suppliers serving both finished formulation networks and raw material spot markets.
Pricing Analysis
Service-bundling separates physician-administered protocols with clinical outcome warranties from unbundled electroporation device leases in salon channels. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and brand heritage, with Teoxane and Galderma commanding premiums against Asian fermentation-scale suppliers. Cost compression in the salon tier is intensifying because beauty operators bypass physician-only network constraints. Dermatology clinics exhibit lowest price sensitivity due to patient willingness to pay for reversible, physician-supervised outcomes.
Supply Chain Analysis
Direct-to-clinic channels handle physician-network demand while distributor-mediated flows serve medical spa and salon tiers. Manufacturing concentrates in Switzerland, Germany, and South Korea for finished formulations, with raw material fermentation anchored in China and Japan. Sodium hyaluronate supply draws from Shandong and Hyogo biotech clusters, with polylactic acid polymerization resting on European specialty chemical producers. Single-source vulnerability concentrates in fermentation-derived hyaluronic acid inputs, where Chinese environmental regulations threaten capacity utilization.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The skin booster market is becoming a vertical-integration race as manufacturers pursue captive supply of fermentation-derived sodium hyaluronate to secure margin control against raw material volatility.
For Market Incumbents: Hedge against electroporation device disruption by acquiring needle-free delivery technology licenses or developing hybrid service protocols that preserve physician involvement. Consolidate position in poly-L-lactic acid R&D to capture the 35-50 demographic rotation toward gradual collagen remodeling. Defend EU MDR-compliant manufacturing advantage as Brazilian and Southeast Asian regulators tighten biocompatibility standards. For New Entrants and Emerging Players: Launch via at-home microneedling convergence, pairing consumer-grade electroporation devices with topical booster serums to bypass professional-only injectable networks. Target beauty salon channels in Bangkok and Singapore where regulatory arbitrage permits non-physician operation. Exploit white space in acne scarring protocols, where physician injector certification requirements have limited supply expansion. For Investors and Strategic Acquirers: Re-rating potential sits with device-mediated delivery innovators given accelerating salon channel adoption and compressed regulatory approval timelines. Long-term viability favors manufacturers with backward integration into fermentation capacity or exclusive polymer sourcing agreements. Watch MFDS export pathway acceleration as the signal for which Seoul-developed protocols will capture Southeast Asian premium segments.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Capacity | Captive sodium hyaluronate supply insulates margin structures against Chinese environmental regulatory volatility. |
| Poly-L-lactic Acid Portfolio Expansion | Biostimulator diversification captures patient preference rotation toward gradual, imperceptible aesthetic outcomes in Seoul and Tokyo. |
| Electroporation Device Partnership | Needle-free delivery licensing preserves clinic channel access as beauty salons fragment professional service tiers. |
| ANVISA Priority Filing | Brazilian regulatory acceleration attracts multinational portfolio prioritization ahead of FDA or EMA timelines. |
| Physician Injector Training Program | Certification scarcity in secondary cities creates bottlenecked expansion opportunity for clinic network operators. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across dermatology clinic directors, medical spa operators, device distribution channel managers, and pharmaceutical regulatory affairs specialists. MFDS submission databases, EU MDR notified body registers, FDA biologics master files, and Korean pharmaceutical export customs declarations provided validation layers. Bottom-up treatment volume modeling triangulated against top-down manufacturer revenue estimates.
Granularity-level framing applied country-specific regulatory pathway assumptions, with formulation chemistry, delivery mode, and treatment setting as core segmentation dimensions across the projection horizon. CAGRs derived from installed capacity expansion curves, patent expiry timelines, and clinician adoption rate surveys. Electroporation device penetration curves and polylactic acid protocol substitution rates served as industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for at-home microneedling convergence would alter the outlook if consumer-grade devices achieve efficacy parity with professional protocols. Forecasts reflect assumptions about physician certification scarcity, raw material fermentation capacity, and regulatory divergence between aesthetic-device and pharmaceutical classifications. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Skincare
Ultrasound Skin Cleaners Market
Skincare
Global Skin Tears Treatment Market
Skincare
Global Scar Removal Treatment Market
Skincare
Skincare Serums Market
Skincare
Skincare Ingredients Market
Skincare
Europe Functional Cosmetics Market
Skincare
Global Anti-Aging Products and Services Market
Skincare
Skin Barrier Market
Skincare
Sun-Care Wipes Market
Skincare
Bangladesh Skin Care Products Market
Skincare
Dermal Regeneration Market
Skincare
Algae Skincare Products Market
Skincare
Global Physician Dispensed Cosmeceuticals Market
Skincare
Cosmeceuticals Market
Skincare
Global Hand Lotion and Hand Cream Market
Skincare
Skin Care Emulsion Market