
 Mineral Sunscreen Market | 2026-2036
Mineral Sunscreen Market Size, Share, and Industry Trends Forecast 2026-2036
Mineral Sunscreen Market Outlook
Reef-safe certification services are decoupling product value from base formulation chemistry, creating recurring revenue streams that manufacturers now bundle with bulk orders. Neutrogena leverages its mass-market distribution network to sustain volume leadership in zinc oxide lotions across North American drugstore channels. La Roche-Posay differentiates through dermatologist endorsement programs that anchor premium positioning in European pharmacy retail. EltaMD specializes in professional-channel formulations that command higher unit economics through clinic and med-spa dispensing.
Mineral sunscreen employs inorganic ultraviolet filters—principally zinc oxide and titanium dioxide in particle sizes ranging from microfine to nanoparticulate grades—to reflect or scatter UVA and UVB radiation before skin penetration occurs. The formulation category serves photoprotection needs for populations with photosensitivity, pediatric safety concerns, or marine ecosystem exposure where organic filters face usage restrictions. Cream formats dominate current revenue pools due to consumer familiarity and spreadability performance, while stick formats represent the fastest-growing configuration as on-the-go reapplication habits reshape portable usage occasions. Zinc oxide ingredient demand outpaces titanium dioxide growth as single-filter formulations gain preference among clean-label consumers seeking simplified ingredient lists.
FDA sunscreen monograph enforcement shapes permissible active ingredient concentrations and labeling claims across the United States, while Australia's Therapeutic Goods Administration imposes parallel efficacy testing protocols that manufacturers must duplicate for market access. The EU's REACH framework and evolving nanomaterial classification requirements from ECHA are tightening particle-size disclosure obligations for titanium dioxide formulations sold in European member states. Stakeholders must monitor regulatory divergence between reef-safe certification standards in Hawaii and Key West versus emerging marine toxicity protocols in Mediterranean jurisdictions, as compliance fragmentation threatens to partition formulation strategies by coastal market.
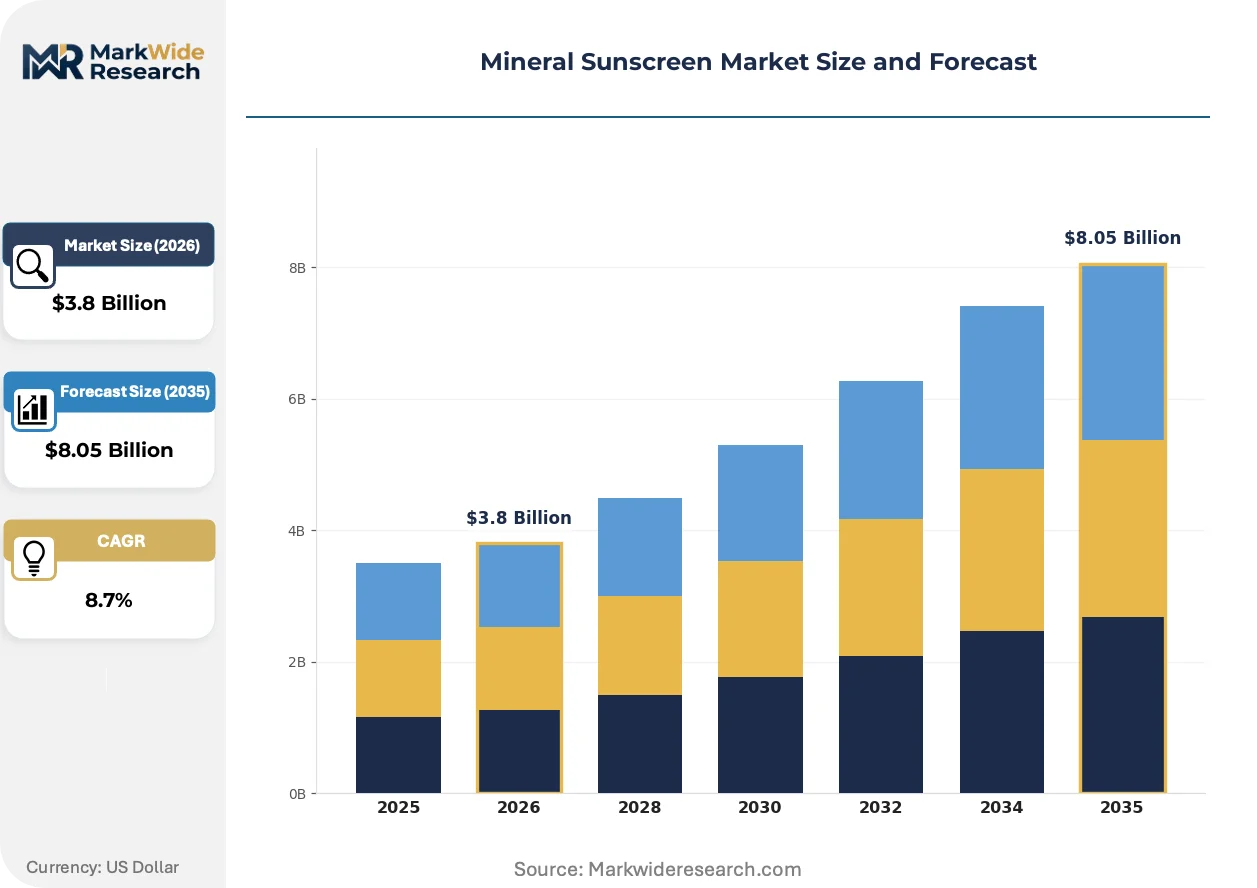
Market Dynamics
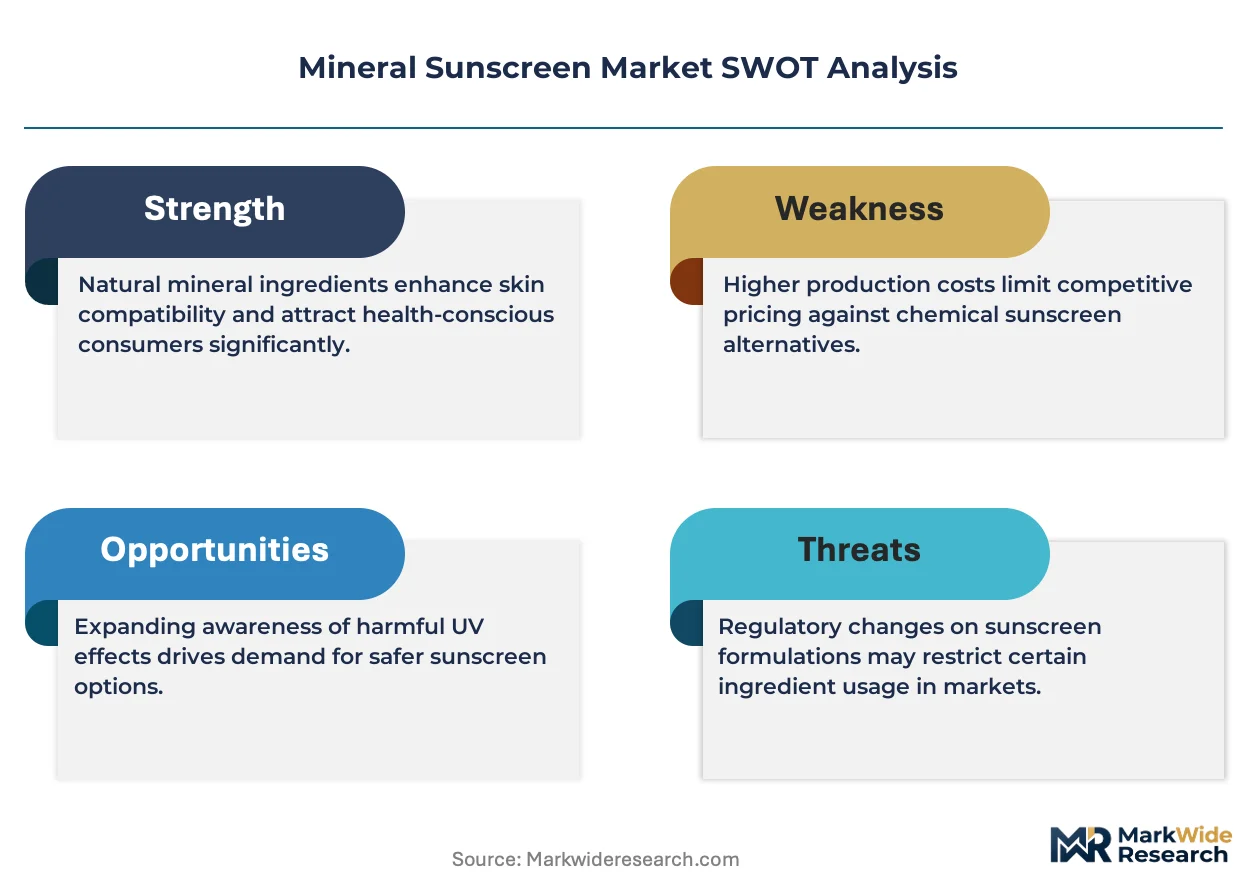
Reef-safe certification mandates in coastal jurisdictions are forcing simultaneous reformulation across multiple filter chemistries, compressing product development cycles while elevating compliance costs as a permanent cost-of-entry barrier.
Growth Catalysts
- Hawaii's reef-safe ban on oxybenzone and octinoxate:This 2021 state law eliminated organic filter alternatives in one of the world's highest per-capita sunscreen consumption markets, redirecting demand toward zinc oxide formulations.
- Pediatric dermatology protocols:Clinic networks in Australia and the United States now specify mineral filters for infant photoprotection, creating institutional prescribing pathways that bypass retail price sensitivity.
- Non-nano zinc oxide particle engineering:Advanced milling technologies are eliminating the white-cast cosmetic barrier that previously limited adult facial category penetration.
Market Restraints
- Zinc oxide supply concentration:Active pharmaceutical-grade production clusters in China and Peru create single-source vulnerability for North American and European formulators.
- Titanium dioxide nanomaterial reclassification:ECHA's 2022 Category 2 carcinogen classification for inhalable powder forms has triggered reformulation costs and labeling obligations across EU member states.
- Cosmetic elegance gap:Mineral formulations still require heavier emollient loads to achieve equivalent spreadability versus organic filter competitors, constraining texture innovation.
Strategic Opportunities
- Stick format portable occasions:On-the-go reapplication behaviors among outdoor recreation participants in Australia and California are creating new SKU economics with higher per-unit margins than traditional lotions.
- Med-spa professional dispensing channels:Post-procedure photoprotection protocols in dermatology and aesthetic medicine practices command premium pricing with limited price transparency.
- Mediterranean marine toxicity protocols:Emerging regulatory frameworks in France and Spain are poised to replicate Pacific reef-safe mandates, opening first-mover positioning for pre-certified formulations.
Industry Challenges
- Formulation chemist specialization shortage:The intersection of colloidal particle science, photostability engineering, and cosmetic elegance requires hybrid expertise that outpaces current graduate pipeline output.
- Dual jurisdiction testing duplication:FDA and TGA efficacy protocols lack mutual recognition, forcing identical clinical studies to be repeated for US and Australian market access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mineral Sunscreen Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gel, Cream, Lotion, Stick Ingredient: Zinc Oxide, Titanium Dioxide, Natural Oils, Extracts Packaging Type: Tubes, Pumps, Jars, Sachets Customer Type: Adults, Children, Athletes, Outdoor Enthusiasts |
| Companies Covered | Neutrogena, La Roche-Posay, EltaMD, Sun Bum, Avalon Natural Products, Crown Laboratories (Blue Lizard), Australian Gold, Coola, W. S. Badger Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mineral Sunscreen Market Strategic Shifts
Particle surface modification chemistry is dissolving the historical trade-off between photoprotection efficacy and cosmetic elegance, enabling mineral filters to compete directly with organic alternatives in facial skincare categories previously closed to inorganic formulations.
Encapsulated zinc oxide is integrating silicone-based shell technologies that maintain UV scattering efficiency while eliminating particle aggregation on skin surfaces. Premium facial skincare brands in South Korea and Japan are adopting these materials at accelerated procurement cycles, compressing the traditional 18-month formulation timeline to under 10 months for competitive launch windows. This integration is enabling mineral-only portfolios to capture market share in tone-adapting and tinted categories where organic filters previously dominated.
REACH nanomaterial disclosure requirements are forcing granular particle-size distribution reporting for all titanium dioxide imports into EU member states. Manufacturers must now submit full analytical datasets to ECHA prior to product registration, adding 4-6 months to European market entry timelines. Small and mid-sized formulators without in-house particle characterization capabilities are outsourcing compliance documentation to specialized testing laboratories in Germany and Switzerland.
Subscription-based replenishment models are displacing traditional retail repurchase cycles among millennial and Gen-Z consumers in urban coastal markets. Direct-to-consumer brands in California and Florida are capturing recurring revenue through algorithmic delivery scheduling tied to UV index forecasting and usage-pattern data. This channel shift is most visible in the facial sunscreen segment, where convenience positioning outweighs price sensitivity for daily-wear products.
Mineral Sunscreen Market Segmentation
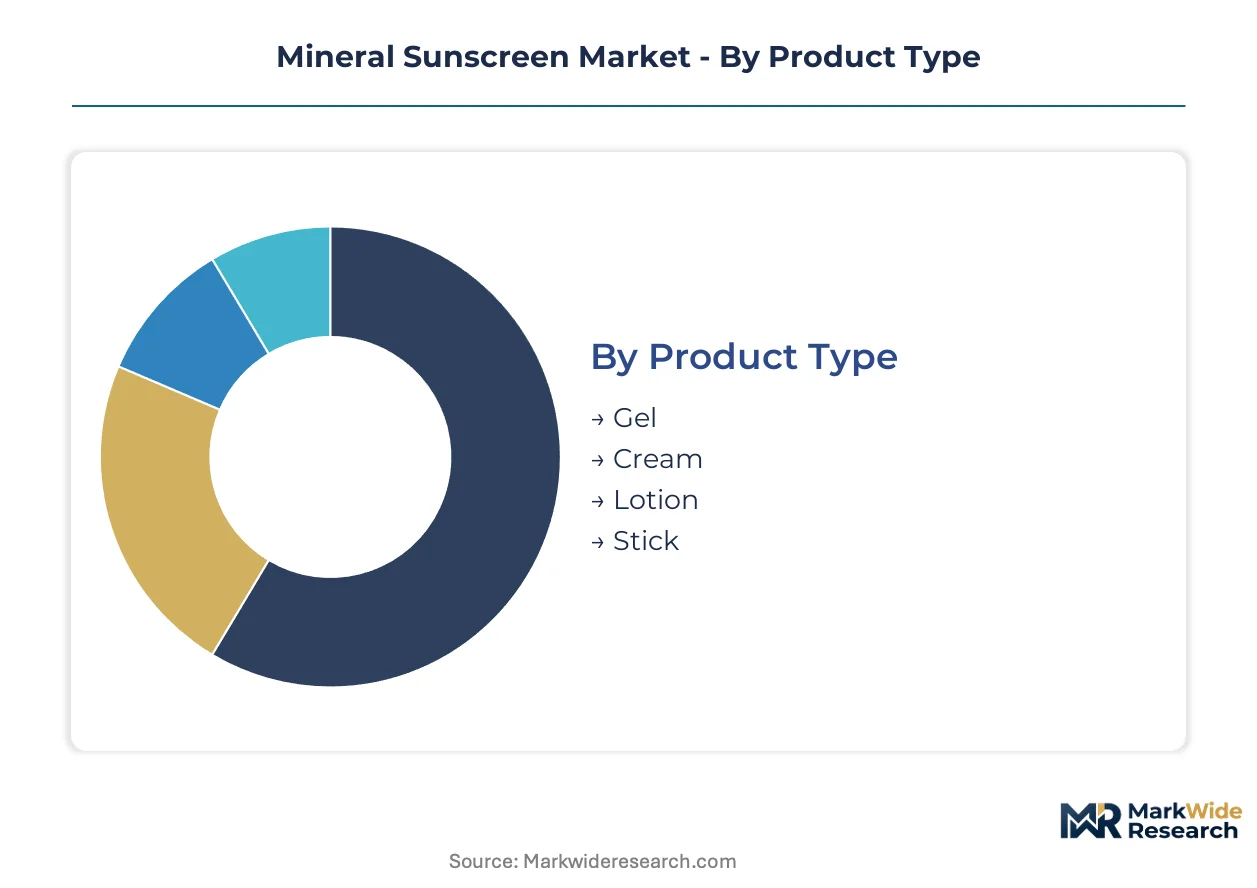
Mineral sunscreen manufacturers must align formulation chemistry, delivery format, and packaging portability with distinct usage occasions and buyer risk profiles. Pediatric safety protocols, marine ecosystem exposure, and on-the-go reapplication behaviors each demand specialized product architectures that command differentiated unit economics.
Product Type:
Cream formats anchor household purchasing decisions through familiarity and perceived value, while stick configurations capture premium portable occasions where convenience overrides price sensitivity.
- Cream:Dense emulsion structures with elevated zinc oxide loads serve facial skincare routines and infant photoprotection protocols. Demand clusters in Australian pharmacy retail where TGA-mandated efficacy testing elevates consumer trust in registered therapeutic goods.
- Stick:Solid balm formats with silicone-enhanced glide properties enable single-hand reapplication during outdoor recreation. California and Florida direct-to-consumer brands are capturing recurring subscription revenue through algorithmic replenishment tied to UV index forecasting.
- Lotion:Pump-dispersed fluid emulsions dominate family-size beach purchasing in coastal urban corridors with reef-safe labeling mandates.
- Gel:Water-based transparent matrices with microfine zinc oxide suspensions target adult male facial categories previously resistant to white-cast formulations.
Volume sits with Cream; growth tilts toward Stick.
Ingredient:
Active filter selection determines regulatory compliance pathways across reef-protected marine jurisdictions and pediatric prescribing protocols.
- Zinc Oxide:Broad-spectrum UV scattering across UVA and UVB wavelengths enables single-filter simplicity prized by clean-label consumers. Non-nano particle engineering from South Korean and Japanese suppliers is dissolving cosmetic elegance barriers in facial skincare categories.
- Titanium Dioxide:Secondary UVB-optimized filter requires combination with zinc oxide for full-spectrum protection. ECHA's 2022 inhalable powder carcinogen classification has triggered reformulation costs and REACH disclosure obligations across EU member states.
- Natural Oils:Carrot seed and raspberry seed oil derivatives provide supplementary antioxidant photoprotection in premium organic-positioned lines.
- Extracts:Botanical soothing agents including aloe and green tea polyphenols address post-sun exposure inflammation in sensitive-skin protocols.
Formulation gravity centers on Zinc Oxide; Titanium Dioxide faces compressive regulatory headwinds.
Packaging Type:
Dispensing mechanism selection reflects usage occasion portability requirements and contamination risk tolerance across institutional versus consumer channels.
- Tubes:Collapsible aluminum-laminate structures dominate pharmacy and mass retail distribution with calibrated squeeze control for portion consistency.
- Pumps:Airless dispenser systems preserve emulsion stability for premium facial formulations in dermatology clinic dispensing channels.
- Jars:Wide-mouth containers support stick format solid balms and whipped cream textures in aesthetic medicine post-procedure protocols.
- Sachets:Single-serve foil pouches enable trial-size sampling and travel compliance in airline carry-on restricted contexts.
Revenue concentrates in Tubes; premium positioning expands through Pumps.
Customer Type:
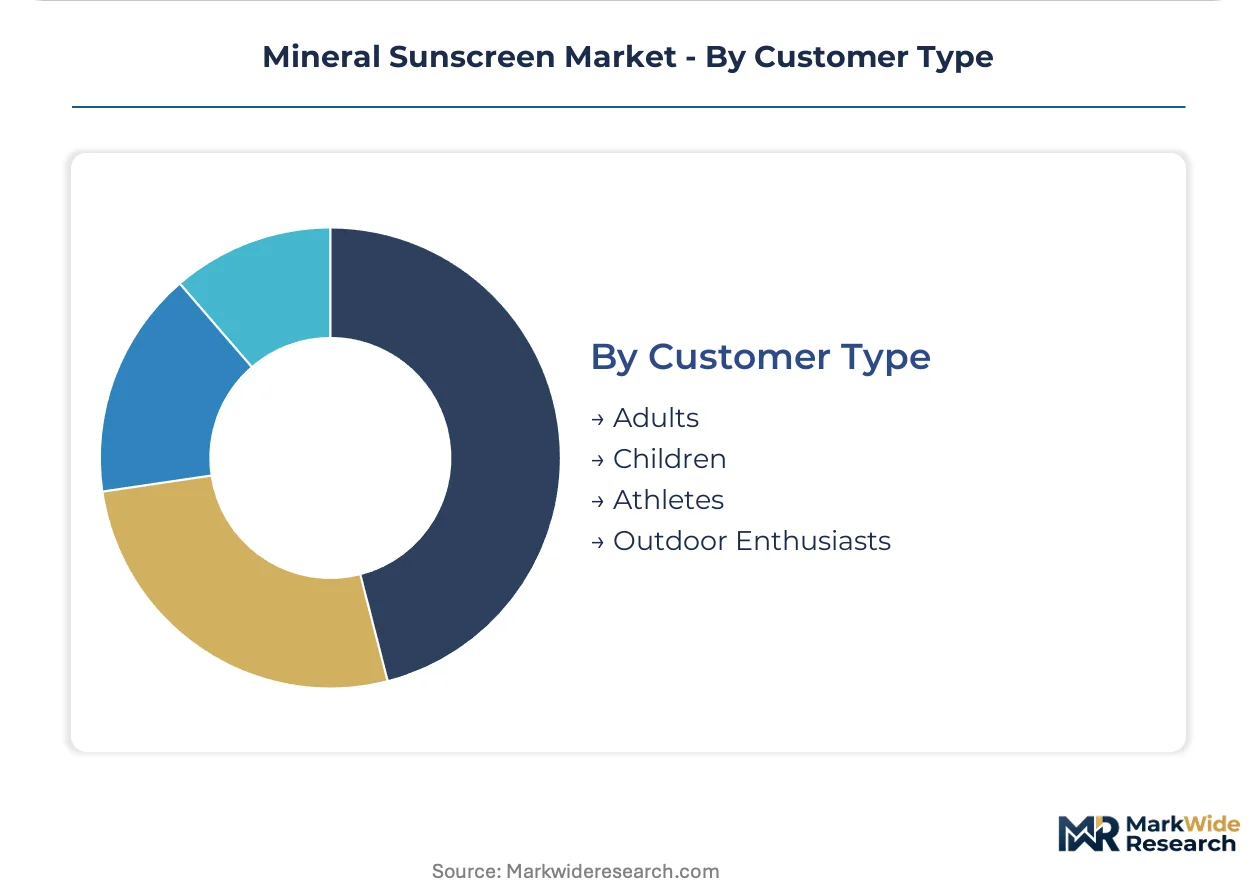
Risk tolerance and purchasing authority diverge sharply between institutional pediatric prescribing and self-directed adult recreational buying.
- Children:Institutional protocols from Australian and United States pediatric dermatology networks specify mineral-only filters, bypassing retail price sensitivity through clinic dispensing pathways. Caregiver purchasing decisions prioritize photostability and skin sensitivity over cosmetic elegance.
- Adults:Self-directed facial skincare integration demands tone-adapting and tinted formats where organic filters previously dominated. South Korean and Japanese procurement cycles for encapsulated zinc oxide are compressing formulation timelines below 10 months.
- Athletes:Sweat-resistant and water-resistant endurance formulations serve marathon and triathlon participants with reapplication intervals tied to training load.
- Outdoor Enthusiasts:Hiking and climbing demographics prioritize stick format portability and reef-safe certification for backcountry water source protection.
Institutional volume flows through Children; Adult facial categories are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sydney and Melbourne anchor mineral sunscreen demand through Australia's reef-safe mandate enforcement and elevated UV exposure indices. Coastal urban corridors in Queensland and New South Wales concentrate retail shelf composition shifts toward zinc oxide formulations.
United States
Pediatric dermatology protocols in Boston and New York Metro specify mineral-only filters for infant photoprotection, creating institutional prescribing pathways. FDA sunscreen monograph requirements accelerate reformulation timelines across domestic manufacturers. California direct-to-consumer brands in Los Angeles and San Francisco capture recurring subscription revenue through algorithmic replenishment models.
Australia
TGA-mandated efficacy testing elevates consumer trust in registered therapeutic goods across pharmacy retail. Therapeutic Goods Administration protocols require parallel clinical studies that duplicate FDA testing for market access. Demand concentrates in coastal urban corridors of Queensland and New South Wales where reef-safe labeling mandates reshape retail shelf composition.
France
ANSM oversight of cosmetic safety intersects with ECHA nanomaterial classification requirements for titanium dioxide formulations. REACH framework obligations force granular particle-size distribution reporting prior to product registration. Marseille and Nice emerge as testing laboratory clusters serving Mediterranean marine toxicity protocol preparation.
South Korea
MFDS cosmetic registration requirements govern encapsulated zinc oxide integration into facial skincare categories. Advanced milling technologies from Seoul and Busan suppliers compress formulation timelines below ten months. Premium beauty brands in Gangnam and Hongdae districts accelerate procurement cycles for tone-adapting mineral-only portfolios.
Japan
METI industrial standards support silicone-based shell technologies for particle surface modification chemistry. PMDA consultation pathways enable rapid market entry for photostability-engineered formulations. Osaka and Tokyo cosmetic innovation clusters drive adoption of non-nano zinc oxide in adult male facial categories.
Mineral Sunscreen Market Competitive Environment
Capital-heavy producers with captive zinc oxide milling capabilities compete with asset-light formulators outsourcing particle engineering to specialized suppliers. The market structure tilts toward tiered positioning where mass-market drugstore channels, professional dermatology dispensing, and direct-to-consumer subscription models operate with limited overlap. Three archetypes dominate: mass-market volume leaders leveraging distribution density, premium dermatology-endorsed specialists commanding clinic channel premiums, and agile direct-to-consumer brands capturing algorithmic replenishment revenue. Competitive moves concentrate on reef-safe certification bundling and stick format SKU expansion for portable occasion capture.
Within the mass-market volume tier, Neutrogena anchors North American drugstore channel positioning through zinc oxide lotion breadth. La Roche-Posay and EltaMD occupy the professional-endorsed specialist tier, with the former exemplifying European pharmacy retail premium positioning and the latter representing clinic and med-spa dispensing channel focus. These three companies illustrate the geographic and channel specialization that fragments competitive encounters across distinct buyer segments.
| Leading Market Players |
|---|
| Neutrogena |
| La Roche-Posay |
| EltaMD |
| Sun Bum |
| Avalon Natural Products |
| Crown Laboratories (Blue Lizard) |
| Australian Gold |
| Coola |
| W. S. Badger Company |
| Others |
Value Chain & Pricing Dynamics
Pharmaceutical-grade zinc oxide spot pricing in Asian bulk chemical markets cascades through three distinct formulation cost tiers, with active filter purity grades determining margin capture across mass-market drugstore, professional dermatology, and direct-to-consumer subscription channels.
Pricing Analysis
Reef-safe certification outcomes anchor value-based pricing premiums that separate clinic-dispensed pediatric formulations from commodity beach lotions. Three-tier pricing structure across premium, standard, and economy levels reflects filter particle engineering sophistication, with non-nano zinc oxide commanding substantial markups over conventional grades. Cost compression in mass-market tiers is intensifying because of Chinese supply concentration and competing organic filter alternatives. Pediatric institutional buyers show least price sensitivity due to prescribing protocol compliance requirements, while family-size beach purchasers exhibit highest elasticity.
Supply Chain Analysis
Direct-to-consumer subscription channels handle algorithmic replenishment demand from California and Florida coastal demographics, bypassing traditional retail distribution markups. Active pharmaceutical-grade zinc oxide production clusters in China and Peru, with secondary milling capabilities concentrated in South Korea and Japan. Raw material inputs draw from zinc ore smelters, specialized particle engineering facilities, and silicone-based encapsulation chemical suppliers. Single-source vulnerability in Peruvian zinc oxide feedstock creates tariff exposure and geopolitical risk concentration. Distribution runs through pharmacy wholesale networks, dermatology clinic dispensing systems, and e-commerce fulfillment centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Active filter supply constraints in pharmaceutical-grade zinc oxide prop pricing power for integrated manufacturers, with captive milling capabilities determining competitive viability across reef-safe certification tiers.
For Market Incumbents: Anchor market position through backward integration into zinc oxide particle engineering capabilities in South Korea or Japan, eliminating third-party supply dependency. Defend against direct-to-consumer algorithmic replenishment models by locking clinic dispensing channel exclusivity through pediatric dermatology protocol sponsorship. Certification investment in emerging Mediterranean marine toxicity standards creates first-mover barrier against reformulation laggards.
For New Entrants and Emerging Players: Subscription-based direct-to-consumer platforms offer the most penetrable route for millennial and Gen-Z facial skincare segments in California and Florida coastal corridors. Target adult male gel format categories in Japan and South Korea where cosmetic elegance barriers have dissolved through encapsulated zinc oxide adoption. Go-to-market execution should emphasize UV index-integrated replenishment algorithms and reef-safe certification bundling.
For Investors and Strategic Acquirers: Distressed-cycle entries favor asset-light formulators with established clinic channel relationships in Australia and the United States, where TGA and FDA testing duplication costs burden smaller competitors. Long-term viability hinges on five-to-ten year regulatory divergence between Pacific reef-safe mandates and emerging Mediterranean protocols. Watch ECHA nanomaterial classification expansion beyond titanium dioxide as the critical signal for European market entry cost inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Zinc Oxide Milling | Captive supply from South Korean particle engineering facilities eliminates single-source vulnerability to Chinese and Peruvian concentrate markets. |
| Reef-Safe Certification Pre-Positioning | Early compliance with emerging French and Spanish marine toxicity protocols opens Mediterranean coastal retail shelf access before mandate enforcement. |
| Stick Format SKU Expansion | Portable occasion capture in Australian and California outdoor recreation markets commands per-unit margins exceeding traditional lotion configurations. |
| Encapsulated Filter Technology Licensing | Silicone-shell zinc oxide integration from Japanese suppliers compresses facial skincare formulation timelines below competitive benchmarks. |
| Clinic Channel Exclusive Dispensing Agreements | Post-procedure photoprotection protocols in Boston and New York Metro dermatology practices secure premium pricing with limited price transparency. |
Study Parameters
Independent corroboration across formulation chemists at North American and European manufacturers, procurement leads at zinc oxide suppliers, and pharmacy retail category buyers underwrites the qualitative findings in this study. Primary interviews with pediatric dermatology network directors, reef-safe certification laboratory technicians, and direct-to-consumer brand operations executives combined with secondary validation from FDA sunscreen monograph filings, TGA therapeutic goods registrations, ECHA nanomaterial disclosure databases, and customs trade data. Bottom-up demand modeling across product format, filter type, and customer segment triangulates against top-down market sizing from regional consumption patterns.
Rate-of-change decomposition separates volume expansion from price realization effects across the projection horizon, with analytical framework approach modeling cream, stick, lotion, and gel formats alongside zinc oxide and titanium dioxide filter chemistries. Pediatric, adult, athlete, and outdoor enthusiast customer types intersect with geographic regulatory clusters to generate segment-level CAGRs. Forecast inputs incorporate reef-safe mandate enforcement timelines, particle engineering technology adoption curves, and clinic dispensing channel penetration rates without specifying implementation dates.
The model holds under stable zinc oxide supply concentration and incremental regulatory expansion; deviation in ECHA carcinogen classification scope or Pacific trade route disruption would shift volume and value outputs. Forecasts reflect documented assumptions regarding filter substitution elasticity and certification cost pass-through. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Skincare
Dermocosmetics Skin Care Products Market
Skincare
United Kingdom Skincare Market
Skincare
South Korea Anti-Acne Dermal Patch Market
Skincare
Asia Pacific Traditional Chinese Herbal Medicine for Face-Care Market
Skincare
Skin Care Supplements Market
Skincare
Skin Boosters Market
Skincare
Global Skin Tears Treatment Market
Skincare
Facial Skincare Market
Skincare
Hyaluronic Acid Personal Care Products Market
Skincare
Organic Skincare Products Market
Skincare
Skincare Ingredients Market
Skincare
Skin Antiseptic Market
Skincare
Sun-Care Wipes Market
Skincare
Fragrance-Free Skin Care Products Market
Skincare
Biological Skin Substitutes Market
Skincare
Global Eczema Skin-Care Products Market