
 Pseudo Collagen Market | 2026-2036
Pseudo Collagen Market Size, Share, and Industry Trends Forecast 2026-2036
Pseudo Collagen Market Analytics
Asset-light contract manufacturing and white-label financing is fragmenting competitive barriers in pseudo collagen production. Lonza Group leverages its biotech fermentation infrastructure to sustain high-purity peptide output for cosmetic grade supply. Celsie Limited anchors European demand through specialized native pseudo collagen extraction. Vital Proteins competes in the ingestible segment with differentiated marine-origin positioning.
Pseudo collagen denotes recombinant or plant-derived protein structures that mimic mammalian collagen triple-helix architecture, typically engineered through microbial fermentation or enzymatic hydrolysis to achieve 50-300 kDa molecular weight ranges for dermal penetration or nutritional bioavailability. Its primary commercial purpose centers on replacing animal-derived collagen in topical anti-aging formulations, nutraceutical powders, and regenerative wound dressings where immunogenicity and sourcing ethics constrain conventional options. Hydrolyzed pseudo collagen dominates current volume given its superior solubility profile for serum and cream matrices, while peptide fragment grades command premium positioning in medical aesthetics where precise chain-length targeting enhances fibroblast signaling. Native pseudo collagen retains niche occupancy in luxury beauty channels where intact triple-helix claims support clean-label marketing.
REACH compliance in Europe and FDA cosmetic ingredient oversight in the United States both tighten purity and traceability requirements, pushing manufacturers toward documented fermentation-source certification. EMA and ISO 10993 biocompatibility standards further govern medical-grade pseudo collagen destined for wound healing and aesthetic injection applications. Stakeholders must monitor evolving cross-border ingredient disclosure rules and decide between dedicated regional compliance investments versus centralized global certification strategies.
Market Dynamics
Fermentation-based peptide engineering now dominates pseudo collagen supply architecture, compressing extraction-dependent production timelines and forcing legacy hydrolysis operations toward hybrid bioreactor investments. REACH disclosure mandates and South Korean beauty export requirements are accelerating documented chain-of-custody systems across ingredient certification workflows.
Growth Catalysts
- REACH ingredient transparency mandates:European cosmetic formulators now require fermentation-source documentation, pushing contract manufacturers toward GMP-certified bioreactor infrastructure. This compliance pressure filters downstream to raw material procurement specifications.
- Marine-origin peptide bioavailability:Nutraceutical brands in Japan and Australia prioritize algal and microbial collagen mimics for ingestible powders, creating parallel demand streams beyond topical applications.
- Seoul beauty cluster export volume:South Korean skincare houses drive hydrolyzed pseudo collagen consumption through multi-step routine formulations distributed across Southeast Asian duty-free channels.
Market Restraints
- Fermentation feedstock cost volatility:Glucose and yeast extract prices fluctuate with agricultural commodity cycles, squeezing margin structures for mid-scale peptide producers without long-term supply contracts.
- Triple-helix structural fidelity limits:Microbial expression systems struggle to replicate native collagen thermal stability above 37°C, restricting medical-grade applications requiring intact helical architecture.
- Animal-derived collagen price competition:Bovine and porcine hydrolysate from established abattoir supply chains undercuts recombinant alternatives in mass-market cosmetic segments where immunogenicity concerns remain secondary.
Strategic Opportunities
- Indian pharmaceutical contract manufacturing:CDSCO-regulated facilities in Hyderabad and Bangalore seek biocompatibility-certified peptide inputs for wound healing exports to Middle Eastern healthcare systems.
- Precision fermentation scale-up:Integration of AI-driven bioprocess optimization with continuous manufacturing platforms promises tenfold titer improvements for cosmetic-grade output.
- Direct-to-consumer ingestible channels:Subscription powder brands bypass traditional nutraceutical distribution, capturing full margin stack through vertically controlled e-commerce fulfillment.
Industry Challenges
- ISO 10993 biocompatibility certification timelines:Medical-grade pseudo collagen requires eighteen-to-twenty-four month toxicology dossier preparation, delaying market entry for aesthetic injection applications.
- Cross-functional talent scarcity:Fermentation engineering expertise must interface with cosmetic formulation chemistry and regulatory affairs, creating recruitment bottlenecks for integrated product development teams.
- Legacy ERP integration with batch genealogy systems:Mid-tier manufacturers struggle to retrofit traceability software for REACH-compliant ingredient disclosure without disrupting existing production scheduling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pseudo Collagen Market |
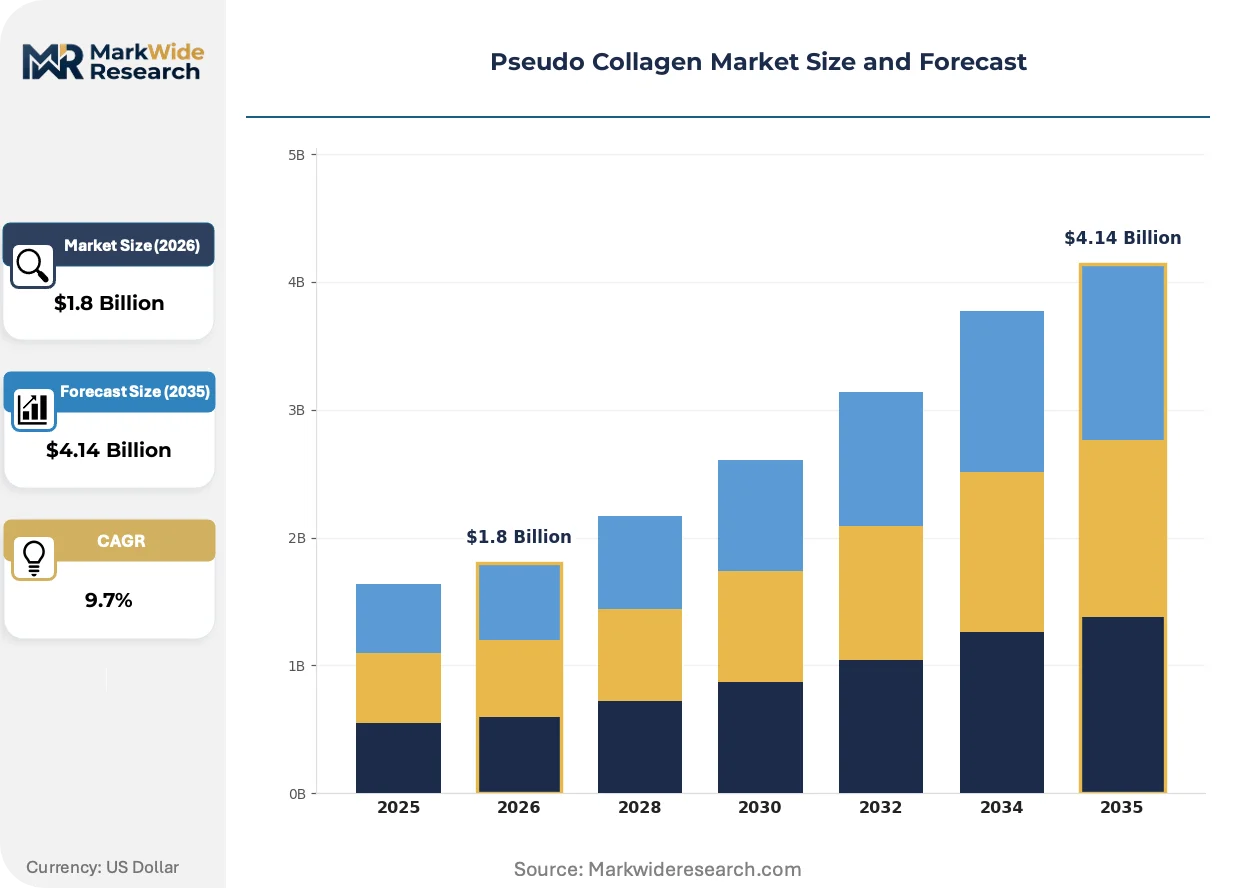
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.14 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrolyzed Pseudo Collagen, Native Pseudo Collagen, Peptide Fragment, Gel Formulation Application: Cosmetics, Dietary Supplements, Medical Aesthetics, Wound Healing End User: Pharmaceutical Companies, Beauty Brands, Nutraceutical Firms, Hospitals Distribution Channel: Online Retail, Pharmacies, Specialty Stores, Direct Sales |
| Companies Covered | Celsie Limited, Lonza Group, Aromantic Ltd., Vanatari International GmbH, Nestle, Vital Proteins, Arbré, Arch Personal Care Natures L.P, Ancient Brands, LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pseudo Collagen Market Evolving Landscape
Bioreactor-derived peptide production is compressing traditional extraction economics while regulatory disclosure requirements reshape competitive differentiation around documented supply chain provenance rather than performance claims alone.
Precision fermentation platforms utilizing CRISPR-optimized yeast strains now achieve 90% purity in single-pass outputs, eliminating downstream chromatography steps that previously constrained hydrolyzed pseudo collagen economics. Medical aesthetics manufacturers in Switzerland and Germany adopt these inputs for fibroblast-signaling peptide fragments. The technology is migrating from cosmetic-grade commodity supply toward pharmaceutical-contract applications where batch consistency documentation commands premium positioning.
EMA's 2024 update to cosmetic ingredient safety assessment guidelines now requires chronic dermal exposure data for novel peptide structures, extending pre-market notification timelines. Formulators serving EU distribution channels must maintain toxicology dossiers exceeding prior substance-volume thresholds. Small-scale Korean and Chinese exporters face compliance cost barriers, consolidating procurement relationships toward established fermentation houses with dedicated regulatory affairs capacity.
Ingredient buyers now mandate third-party carbon footprint certification alongside purity specifications, reflecting Scope 3 emissions accounting pressures from parent cosmetics conglomerates. This procurement evolution displaces spot-market purchasing for long-term offtake agreements with documented renewable energy inputs. German and French formulators lead this transition, embedding lifecycle assessment requirements into supplier scorecards ahead of anticipated CSRD supply chain disclosure mandates.
Pseudo Collagen Market Segmentation
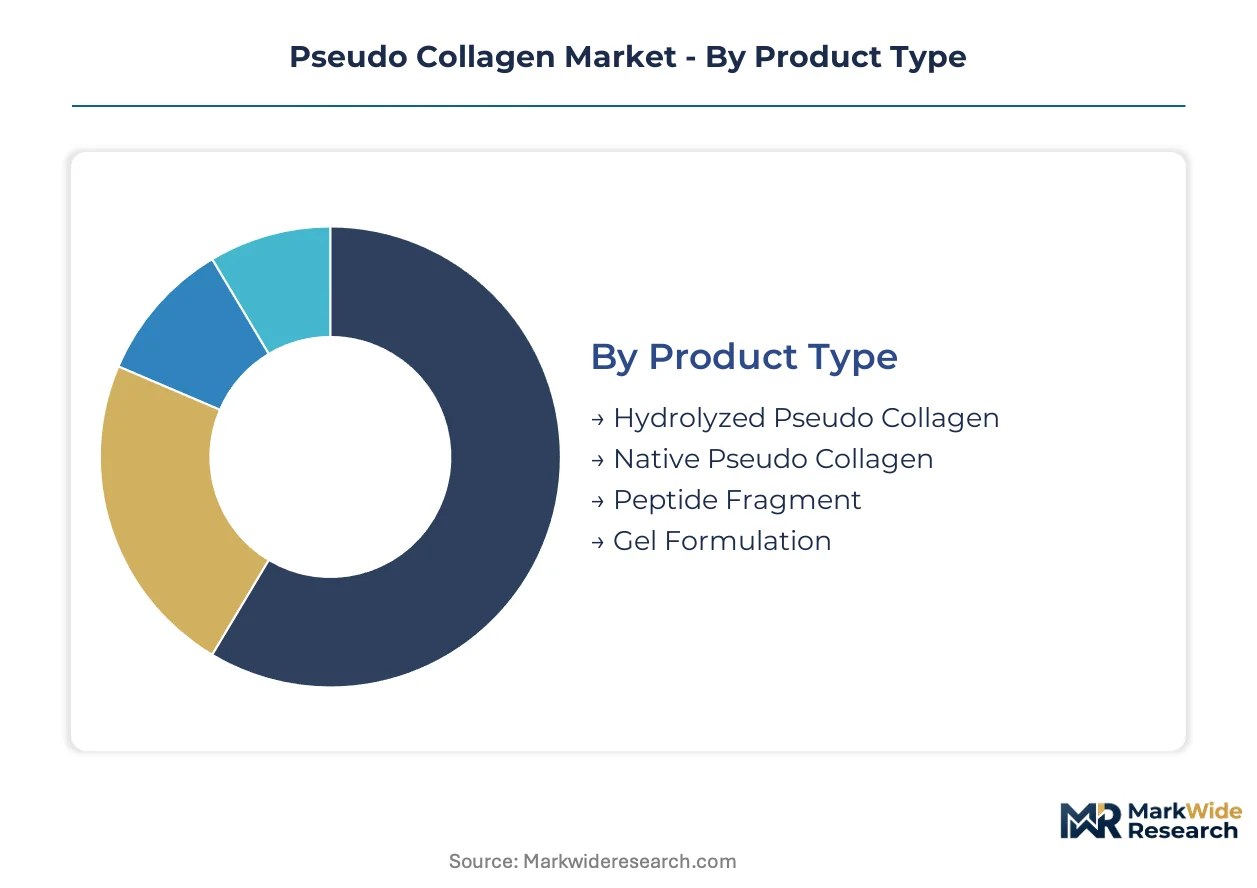
Segmentation in the pseudo collagen market separates commodity-grade hydrolyzed outputs from premium medical-grade architectures, with each tier commanding distinct certification requirements and margin structures. Manufacturers optimize fermentation parameters and downstream processing differently depending on whether the target application demands dermal penetration, nutritional bioavailability, or intact triple-helix stability.
Product Type:
Cost tier stratification across molecular weight and structural fidelity determines procurement specifications for cosmetic versus medical applications.
- Hydrolyzed Pseudo Collagen:Enzymatically cleaved peptide chains ranging 50-300 kDa achieve superior aqueous solubility for serum and cream matrices. South Korean beauty brands concentrate procurement for multi-step skincare routines distributed through Southeast Asian duty-free channels, with REACH-compliant fermentation documentation now mandatory for EU-bound exports.
- Native Pseudo Collagen:Intact triple-helix structures retain thermal stability claims valued in luxury clean-label marketing. Swiss and German medical aesthetics manufacturers source these grades for fibroblast-signaling applications where helical architecture governs receptor binding efficacy.
- Peptide Fragment:Short-chain sequences below 50 kDa target specific collagen receptor pathways in precision dermatology.
- Gel Formulation:Pre-hydrated matrices simplify compounding workflows for wound dressing manufacturers.
Hydrolyzed variants command the established base. The steepest expansion runs through peptide fragment grades for medical aesthetics.
Application:
End-use maturity separates volume-driven cosmetic consumption from regulated medical segments with extended certification timelines.
- Cosmetics:Topical anti-aging formulations absorb the majority of fermentation output, with Japanese and Australian brands prioritizing marine-origin mimics for clean-label positioning. EMA's updated chronic dermal exposure requirements now extend pre-market notification timelines for novel peptide structures entering EU distribution.
- Medical Aesthetics:Injectable fibroblast stimulants require ISO 10993 biocompatibility certification and eighteen-to-twenty-four month toxicology dossier preparation. Swissmedic-regulated facilities in Switzerland anchor European demand for precision-grade peptide fragments with documented batch consistency.
- Dietary Supplements:Ingestible powders compete on bioavailability claims in Japan and Australian nutraceutical channels.
- Wound Healing:Regenerative dressings leverage pseudo collagen's low immunogenicity profile for chronic ulcer management.
Cosmetics retains volume leadership. Medical aesthetics climbs fastest as certification-capable suppliers consolidate procurement relationships.
End User:
Customer type dictates contract structure, with pharmaceutical buyers requiring GMP-certified batch genealogy versus spot-market purchasing by mid-tier beauty formulators.
- Beauty Brands:Seoul-based skincare houses drive hydrolyzed grade consumption through vertically integrated product development, specifying fermentation-source documentation to satisfy tightening EU cosmetic ingredient standards under REACH.
- Pharmaceutical Companies:CDSCO-regulated facilities in Hyderabad and Bangalore seek biocompatibility-certified inputs for wound healing exports to Middle Eastern healthcare systems, with long-term offtake agreements replacing spot-market purchasing.
- Nutraceutical Firms:Subscription powder brands capture full margin stack through direct-to-consumer e-commerce fulfillment.
- Hospitals:Central procurement offices specify carbon footprint certification alongside purity metrics.
Beauty brands anchor current demand. Pharmaceutical contract manufacturing shows the steepest order book expansion.
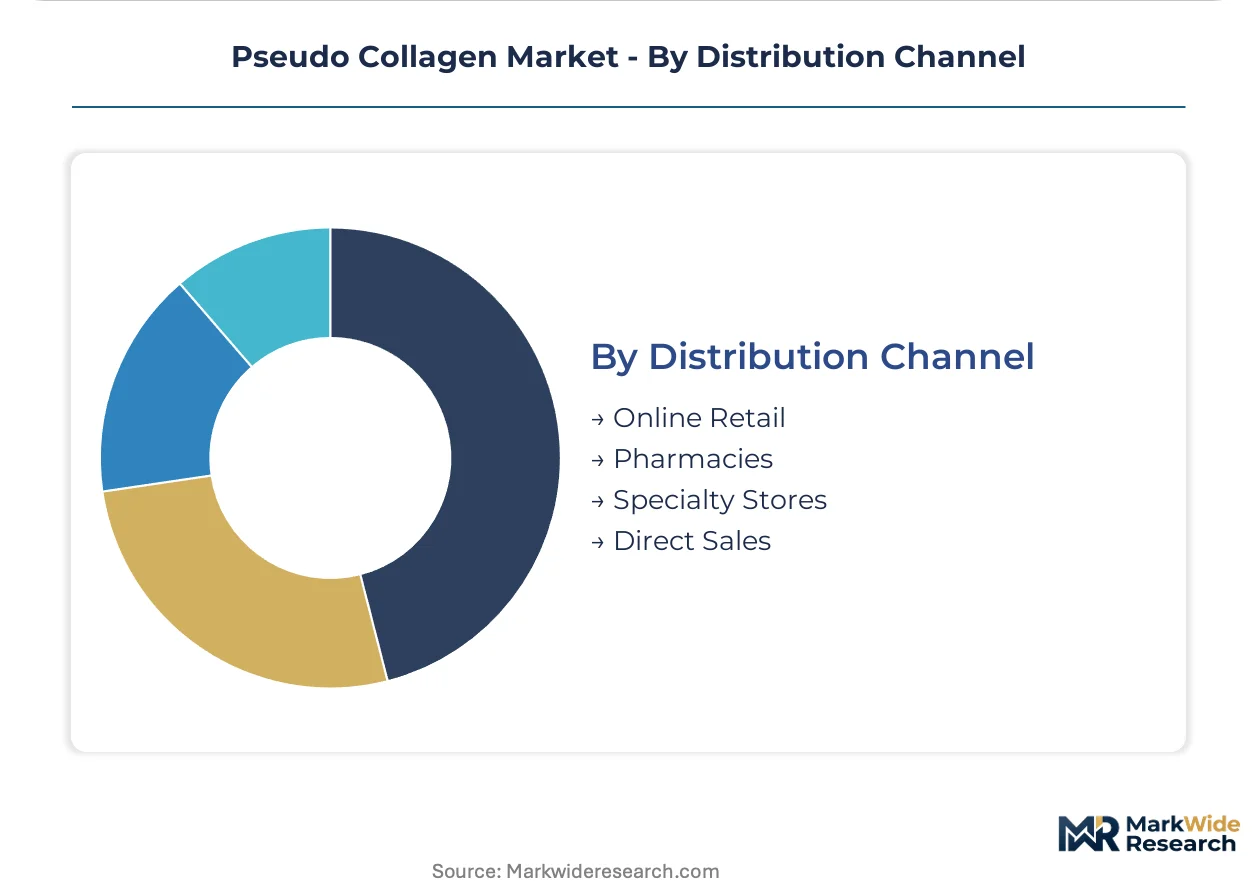
Distribution Channel:
Channel configuration reflects margin capture strategy, with vertically controlled e-commerce displacing traditional wholesale for ingestible segments.
- Online Retail:Direct-to-consumer subscription models bypass nutraceutical distribution markups, with Australian and Japanese brands leading marine-origin peptide positioning in ingestible powders. German and French formulators embed lifecycle assessment requirements into supplier scorecards ahead of anticipated CSRD supply chain disclosure mandates.
- Direct Sales:Medical-grade peptide fragments move through dedicated pharmaceutical representative networks serving Swiss and German aesthetic clinics, with batch consistency documentation commanding premium positioning over commodity alternatives.
- Pharmacies:Retail chains stock mid-tier cosmetic grades with established brand recognition.
- Specialty Stores:Premium beauty retailers curate native pseudo collagen for clean-label positioning.
Direct sales maintains the highest value per kilogram. Online retail gains share fastest as subscription models consolidate consumer loyalty.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics reshape pseudo collagen procurement geography. South Korean beauty houses source fermentation-derived grades for Southeast Asian duty-free distribution. European formulators import documented-chain-of-custody inputs to satisfy tightening REACH disclosure mandates.
South Korea
Seoul-based skincare brands concentrate hydrolyzed pseudo collagen demand through multi-step routine formulations. MFDS cosmetic ingredient oversight requires fermentation-source documentation for export-bound products. The Seoul Capital Area anchors contract manufacturing clusters serving Southeast Asian duty-free channels.
Germany
German formulators prioritize carbon footprint certification alongside purity metrics for cosmetic-grade inputs. ECHA REACH mandates now extend to chronic dermal exposure data for novel peptide structures. The Rhine-Ruhr industrial corridor hosts bioreactor infrastructure serving pharmaceutical-contract applications.
Switzerland
Swiss medical aesthetics manufacturers drive premium-grade peptide fragment procurement for fibroblast-signaling applications. Swissmedic regulates batch consistency documentation for aesthetic injection inputs. Basel-Zurich biotech clusters specialize in ISO 10993-certified outputs for wound healing exports.
United States
American nutraceutical brands scale direct-to-consumer subscription models for ingestible marine-origin powders. FDA cosmetic ingredient oversight tightens purity and traceability requirements for topical formulations. The Greater Boston biotech corridor advances precision fermentation platforms for pharmaceutical-grade supply.
India
Indian pharmaceutical contract manufacturers seek biocompatibility-certified peptide inputs for wound healing exports to Middle Eastern healthcare systems. CDSCO-regulated facilities in Hyderabad and Bangalore require GMP-certified batch genealogy documentation. The Hyderabad-Bangalore corridor consolidates long-term offtake agreements replacing spot-market purchasing.
Pseudo Collagen Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in fermentation infrastructure and extraction technology. The vendor base stratifies across three tiers: multinational biotech houses with dedicated regulatory affairs capacity, regional fermentation specialists serving cosmetic-grade commodity supply, and niche native extraction operators for luxury positioning. Two strategic archetypes dominate: precision fermentation scale-up players and hybrid bioreactor-legacy hydrolysis operators. Competitive moves concentrate on GMP-certified capacity expansion and documented chain-of-custody certification investments.
Among European extraction specialists, Celsie Limited occupies a position within the native pseudo collagen tier for luxury clean-label channels. Lonza Group exemplifies the multinational fermentation infrastructure archetype, anchoring high-purity peptide output for cosmetic and pharmaceutical-grade supply. Vital Proteins represents the marine-origin ingestible positioning vector in direct-to-consumer nutraceutical distribution.
| Leading Market Players |
|---|
| Celsie Limited |
| Lonza Group |
| Aromantic Ltd. |
| Vanatari International GmbH |
| Nestle |
| Vital Proteins |
| Arbré |
| Arch Personal Care Natures L.P |
| Ancient Brands, LLC |
| Others |
Value Network & Pricing Analysis
Swiss and German bioreactor infrastructure concentrates high-purity peptide output, capturing margin pools in medical-grade certification tiers where ISO 10993 documentation commands substantial premiums over commodity cosmetic supply.
Pricing Analysis
Beauty brand procurement teams anchor contract-based long-term offtake structures, with pricing stratifying across medical-grade, cosmetic-grade, and commodity hydrolyzed tiers. Price differentiation rests on fermentation-source documentation and EMA biocompatibility certification, with REACH compliance costs intensifying pressure on mid-scale producers lacking dedicated regulatory affairs capacity. Pharmaceutical buyers show lowest price sensitivity given eighteen-to-twenty-four month toxicology dossier requirements, while mass-market cosmetic formulators face margin compression from bovine hydrolysate competition.
Supply Chain Analysis
Export-control scrutiny on precision fermentation technology limits bioreactor equipment flows to certain jurisdictions, concentrating supply architecture in Switzerland, Germany, and South Korea where established GMP infrastructure already exists. Raw material dependencies center on glucose feedstocks, yeast extract nutrients, and chromatography resins for downstream purification. Single-source vulnerability runs through agricultural commodity cycles affecting fermentation input costs. Distribution feeds from contract manufacturing clusters toward beauty brand compounders and pharmaceutical CDMOs with documented batch genealogy requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Integrated product development teams capable of bridging fermentation engineering with cosmetic formulation chemistry remain scarce, constraining speed-to-market for novel peptide architectures and consolidating advantage toward incumbents with captive technical talent.
For Market Incumbents: Harden GMP-certified capacity in Basel-Zurich and Rhine-Ruhr corridors against emerging precision fermentation scale-ups. Deepen backward integration into glucose feedstock supply through long-term agricultural offtake agreements. Prioritize ISO 10993 certification investments to defend medical-grade positioning against peptide fragment competitors.
For New Entrants and Emerging Players: Indian pharmaceutical contract manufacturing represents the most penetrable white-space target, with CDSCO-regulated facilities in Hyderabad seeking biocompatibility-certified inputs for Middle Eastern wound healing exports. Marine-origin ingestible positioning in Australian and Japanese direct-to-consumer channels offers parallel entry. Lead with carbon footprint certification to differentiate against established fermentation houses.
For Investors and Strategic Acquirers: Capital is best deployed toward precision fermentation platforms with demonstrated CRISPR-optimized yeast strain performance and existing regulatory affairs capacity. Long-term viability hinges on tenfold titer improvement potential and continuous manufacturing integration. Watch for EMA chronic dermal exposure guideline expansions as inflection signals for compliance-capable supplier consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | CRISPR-optimized yeast strains achieving single-pass purity eliminate downstream chromatography bottlenecks. |
| GMP Certification Investment | ISO 10993-compliant batch genealogy documentation commands premium positioning in Swiss medical aesthetics. |
| Backward Integration into Feedstocks | Long-term glucose supply contracts insulate margin structures from agricultural commodity volatility. |
| Direct-to-Consumer Channel Launch | Subscription powder models capture full margin stack in Australian and Japanese nutraceutical markets. |
| Carbon Footprint Certification Program | Documented renewable energy inputs satisfy German and French CSRD supply chain disclosure requirements. |
Research Methodology
Initial hypotheses were tested against primary input from fermentation engineering directors, cosmetic formulation chemists, regulatory affairs leads, and pharmaceutical procurement managers, then refined through secondary validation across EMA cosmetic ingredient safety assessments, REACH disclosure databases, MFDS export documentation requirements, and customs trade flow records. Bottom-up capacity modeling triangulated against top-down beauty brand procurement spend analysis.
Demand-supply balance dynamics across peptide fragment, hydrolyzed, and native structural grades anchored the analytical framework throughout the projection horizon. Segmentation dimensions spanned molecular weight tier, application endpoint, and regional regulatory cluster. CAGRs derived from capacity expansion pipelines, import-export flow trajectories, and substitution elasticity estimates for animal-derived collagen alternatives.
Macroeconomic conditions sit as an overlay; deviation in agricultural commodity indices, bioreactor equipment lead times, or cross-border ingredient disclosure rule expansions would shift the trajectory. Forecasts reflect documented assumptions on fermentation titer improvement curves and certification timeline standardization. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Skincare
Global Hand Lotion and Hand Cream Market
Skincare
Self-Tanning Care Market
Skincare
Global Cosmetic Skin Care Market
Skincare
Hand Eczema (HE) Treatment Market
Skincare
Dermocosmetics Market
Skincare
Skin Grafting System Market
Skincare
Algae Skincare Products Market
Skincare
Non-Surgical Skin Tightening Market
Skincare
Skin Barrier Market
Skincare
Facial Skincare Market
Skincare
CBD Skin Care Market
Skincare
CBD Skincare Products Market
Skincare
Moisturizing Cream Market
Skincare
Skincare Cdmo and Cmo Market
Skincare
Europe Functional Cosmetics Market
Skincare
Africa Cosmeceutical Market