
 Europe Personal Care Packaging Market | 2026-2036
Europe Personal Care Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Personal Care Packaging Market Foresight
Post-consumer recycled polyethylene terephthalate is expanding its share in bottle applications as virgin resin costs and ESG procurement criteria tighten. Albéa Group leverages European compounding partnerships to secure consistent PCR supply chains. Gerresheimer AG anchors its position through specialized glass molding for fragrance and premium skincare flacons. Mondi Group differentiates via paper-based barrier solutions that target replacement of multi-layer plastic laminates in pouches.
Europe personal care packaging encompasses primary and secondary containment systems engineered from plastics, glass, metals, and paper substrates, with specifications including oxygen transmission rates below 0.1 cc per square meter per day for sensitive formulations and compatibility with ISO 8317 child-resistant closure standards. Its commercial purpose centers on preserving product integrity, enabling precise dosing, and transmitting brand positioning through tactile and visual design cues. Tubes retain dominant volume share in haircare due to squeeze-controlled dispensing and shelf efficiency, while pouches represent the fastest-expanding format as refill economics gain traction among sustainability-focused skincare marketers. Glass commands the premium margin pool in fragrance, where weight, clarity, and decoration convey luxury positioning.
REACH restrictions on substance migration and the EU Packaging and Packaging Waste Regulation's recycled content targets are reshaping material selection and supplier qualification timelines across the value chain. EMA and national competent authorities in France and Germany enforce cosmetic safety assessments that extend to packaging-contact compliance, creating layered certification burdens. Stakeholders must monitor how the EU Green Deal's packaging reuse mandates will reconfigure format economics and capital allocation for filling line retrofits.
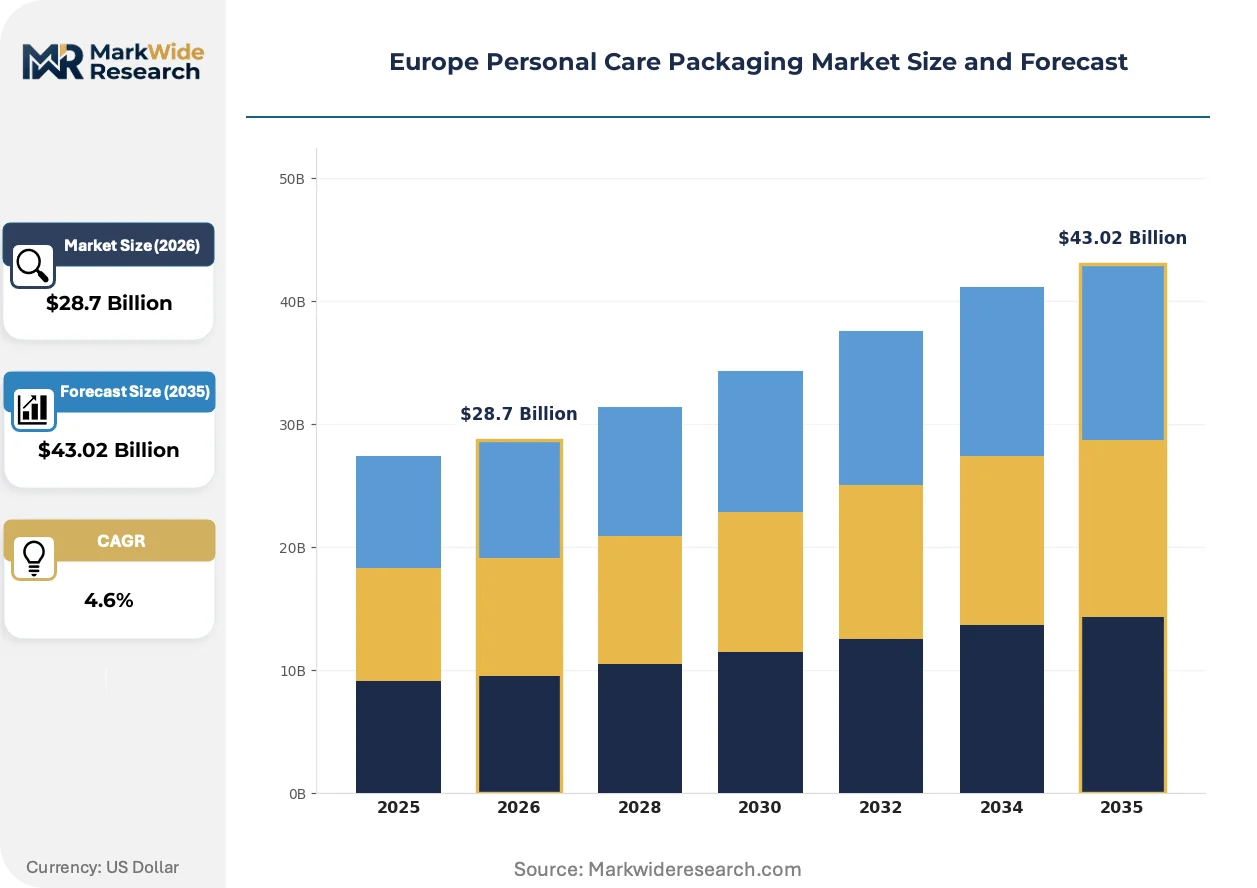
Market Dynamics
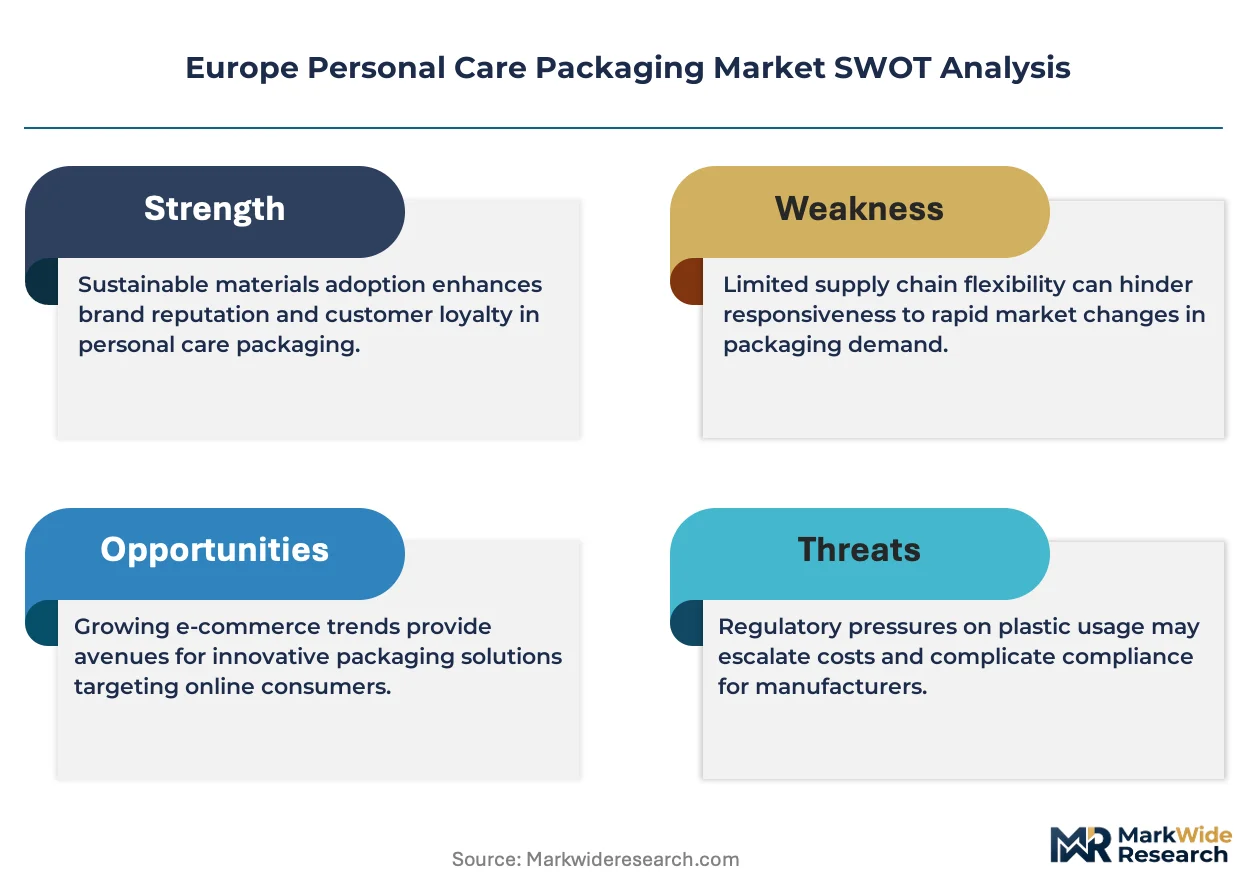
The EU Packaging and Packaging Waste Regulation is compressing supplier qualification timelines while mandating minimum recycled content thresholds, forcing converters to requalify material streams and accelerate capital deployment into compounding partnerships.
Growth Catalysts
- REACH migration limits:Tighter substance restrictions on packaging-contact materials are filtering out non-compliant Asian imports and expanding addressable market for certified European converters.
- Airless pump adoption:Premium skincare formulators in France and Germany are specifying precision dosing systems that extend shelf stability and justify unit price premiums.
- Rhine-Ruhr cluster density:Germany's packaging corridor concentrates blow-molding, injection, and decoration capabilities within 150 kilometers, reducing logistics drag for just-in-time cosmetics supply chains.
Market Restraints
- PCR resin volatility:Post-consumer recycled polyethylene terephthalate availability fluctuates with collection infrastructure gaps in Southern and Eastern Europe, creating input cost instability.
- Glass energy intensity:Natural gas-dependent melting furnaces in Czech and Italian glassworks face margin compression from carbon pricing under EU ETS phase-in schedules.
- Multi-layer laminate lock-in:Existing pouch filling lines across Spanish and Portuguese converters cannot accommodate paper-based barrier substrates without seven-figure retrofit investments.
Strategic Opportunities
- Poland and Romania expansion:Underpenetrated skincare contract manufacturing in Warsaw and Bucharest corridors offers first-mover positioning before local converter capacity catches demand.
- EU Green Deal reuse mandates:Draft refill-station requirements for personal care retail create equipment and format specification opportunities for pump and dosing system specialists.
- Paper-polymer hybrid convergence:Combining Mondi's barrier paper expertise with injection-molded fitments opens pouch segments previously reserved for pure plastic laminates.
Industry Challenges
- Migration testing bottlenecks:EMA and ANSM cosmetic safety assessments now require 18-24 month packaging-contact validation cycles, delaying new product launches.
- Legacy filling line incompatibility:German and French cosmetics houses operate 1990s-era tube and bottle lines that cannot handle lightweighted or bio-based substrate dimensional tolerances.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Personal Care Packaging Market |
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $43.02 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Tubes, Jars, Bottles, Pouches Material Type: Plastic, Glass, Metal, Paper End User: Cosmetics, Skincare, Haircare, Fragrance Closure Type: Screw Cap, Pump, Spray, Flip Top |
| Companies Covered | AptarGroup Inc., Silgan Holdings Inc., Gerresheimer AG, Albéa Group, Libo Cosmetics Company Ltd, Amcor Plc, Berry Global Inc., Mondi Group, Quadpack Industries SA, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Personal Care Packaging Market Shifts & Advancements
Material science advances and regulatory compliance automation are converging to redefine format economics, with sustainability credentials becoming a technical specification rather than a marketing overlay.
Digital printing with UV-curable inks is automating short-run decoration workflows for niche fragrance launches. Independent perfume houses in Milan and Paris are adopting this technology to compress minimum order quantities from fifty thousand to five thousand units. The structural consequence is automating the collapse of traditional screen-printing moats that protected large-format converters.
REACH substance restrictions on intentionally added microplastics are forcing reformulation of glitter, exfoliant beads, and texture modifiers. This regulatory pressure cascades into packaging design, as incompatible actives require oxygen transmission barriers below 0.05 cc per square meter per day. Premium skincare marketers in Germany are responding by specifying glass or high-barrier co-injection molded bottles with desiccant closures.
Refill economics are restructuring procurement relationships between brand owners and retailers. Bulk concentrate pouches paired with durable primary vessels are displacing single-use bottles in Scandinavian and Benelux markets. This behavioral shift concentrates most visibly in Stockholm and Copenhagen, where municipal waste-sorting infrastructure and consumer willingness-to-participate exceed Southern European baselines.
Europe Personal Care Packaging Market Segmentation
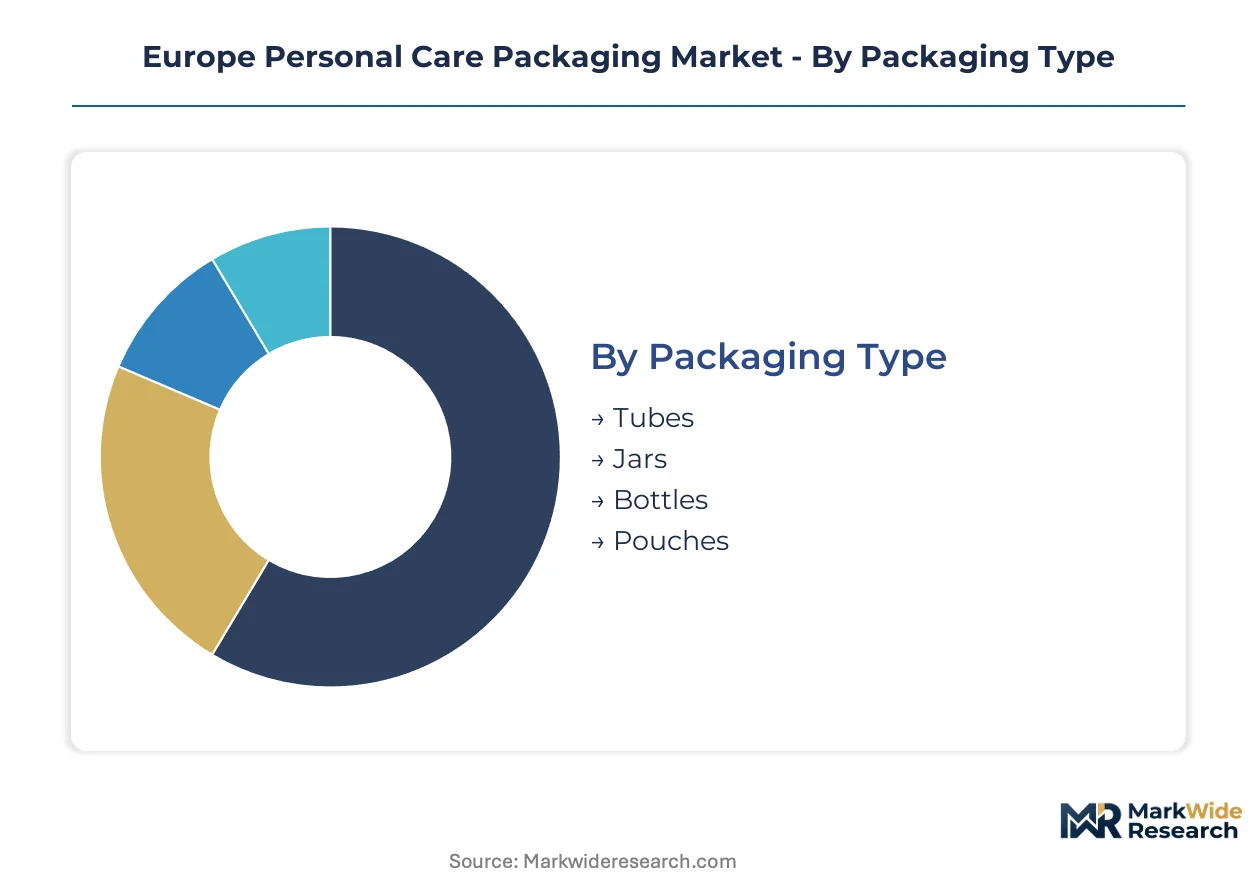
Packaging specification in Europe's personal care sector carries layered certification burdens that vary sharply by segment. REACH migration limits, EMA cosmetic safety assessments, and ISO 8317 child-resistance standards create divergent compliance timelines across formats and materials.
Packaging Type:
Certification intensity clusters around oxygen transmission specifications and child-resistance mandates, with airless systems demanding the longest validation cycles under EMA and ANSM protocols.
- Tubes:Multi-layer extruded or mono-material structures with diameter ranges from 19mm to 50mm dominate haircare dispensing. Demand concentrates in Germany's Rhine-Ruhr corridor where converters supply squeeze-controlled formats to domestic cosmetics houses facing refill economics pressure.
- Jars:Wide-mouth containers in 15ml to 250ml capacities serve thick emulsions and masks. French premium skincare marketers in the Île-de-France region specify double-wall constructions with desiccant closures to meet REACH substance migration thresholds for sensitive formulations.
- Bottles:Blow-molded or injection-stretch formats with neck finishes from 18mm to 28mm accommodate liquid and semi-viscous products. PCR-PET sourcing volatility from uneven Southern European collection infrastructure constrains converter margins.
- Pouches:Flat, stand-up, or spouted configurations enable refill economics and travel-size distribution. Scandinavian retail refill-station pilots under EU Green Deal drafts are accelerating format specification requests for bulk concentrate applications.
Leading the category by volume: Tubes. Growing fastest: Pouches.
Material Type:
Cost tier stratification separates commodity substrates from certified sustainable alternatives, with premium positioning commanding threefold unit economics over standard grades.
- Plastic:PE, PP, PET, and bio-based polymers constitute the volume base. German converters leverage compounding partnerships with Albéa Group to secure consistent PCR supply chains amid virgin resin price volatility.
- Glass:Soda-lime and borosilicate molded flacons command fragrance and ultra-premium skincare positioning. Czech and Italian glassworks face carbon pricing compression under EU ETS phase-in schedules for natural gas-dependent melting furnaces.
- Metal:Aluminum tubes and tinplate containers serve niche pharmaceutical-cosmetic crossover applications. REACH restrictions on substance migration require extended validation timelines for lacquered interior coatings.
- Paper:Barrier-coated boards and molded fiber formats target plastic displacement in secondary and emerging primary applications. Mondi Group's paper-polymer hybrid expertise opens pouch segments previously reserved for multi-layer laminates.
Plastic dominates unit shipments. Paper gains share fastest amid EU Packaging and Packaging Waste Regulation recycled content mandates.
End User:
Application-specific barrier requirements segment procurement relationships, with fragrance and premium skincare demanding oxygen transmission rates below 0.05 cc per square meter per day.
- Cosmetics:Color cosmetics and daily-use toiletries drive high-volume tube and bottle demand. Mass-market procurement in Spain and Portugal favors lightweighted plastic formats compatible with legacy filling lines from the 1990s.
- Skincare:Serums, essences, and active formulations require precision dosing and extended shelf stability. Airless pump adoption accelerates in France and Germany where premium marketers justify unit price premiums through technical performance.
- Haircare:Shampoo, conditioner, and styling products retain tube dominance for squeeze-controlled dispensing and shelf efficiency. Polish and Romanian contract manufacturing corridors offer underpenetrated expansion opportunities before local converter capacity matures.
- Fragrance:Parfum, eau de toilette, and cologne applications command the premium margin pool through glass weight, clarity, and decoration. Milan and Paris independent perfume houses compress minimum order quantities via digital UV-curable printing adoption.
Skincare leads value concentration. Fragrance maintains the steepest margin trajectory.
Closure Type:
Customer type stratification separates mass-market commodity closures from precision-engineered dispensing systems with 18-24 month EMA validation cycles.
- Screw Cap:Standard 18mm to 28mm threaded closures serve cost-optimized bottle applications. Multi-layer laminate pouch converters in Iberia face seven-figure retrofit investments to accommodate fitment compatibility.
- Pump:Airless and standard lotion pumps deliver measured dosing for skincare and haircare. German precision molding specialists anchor supply for French premium formulators specifying oxygen barrier performance.
- Spray:Fine mist and continuous spray actuators serve fragrance and body care distribution. REACH intentionally added microplastic restrictions are forcing reformulation cascades into compatible barrier packaging designs.
- Flip Top:Hinged closures for tubes and bottles enable single-hand dispensing in shower and travel contexts. PCR resin availability gaps in Eastern Europe create input cost instability for molded polypropylene variants.
Screw caps dominate shipment volume. Pumps expand most quickly as airless technology penetrates mid-tier skincare positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Germany's Rhine-Ruhr corridor, where converters serve both domestic cosmetics houses and export markets across the continent. France and Germany together anchor premium skincare specification, while Poland and Romania emerge as underpenetrated contract manufacturing frontiers. Southern European collection infrastructure gaps constrain PCR resin availability.
Germany
Precision molding specialists in the Rhine-Ruhr cluster supply airless pump systems to premium skincare formulators seeking oxygen barrier performance. REACH substance migration limits filter out non-compliant imports, expanding addressable market for certified domestic converters. Berlin-Brandenburg houses EMA headquarters, driving 18-24 month packaging-contact validation cycles that delay new product launches.
France
Île-de-France premium marketers specify double-wall jar constructions with desiccant closures for sensitive formulations. ANSM cosmetic safety assessments enforce layered certification burdens extending to packaging-contact compliance. Paris independent perfume houses compress minimum order quantities via digital UV-curable printing adoption.
Italy
Natural gas-dependent glassworks in Veneto and Emilia-Romagna face margin compression from EU ETS carbon pricing phase-in schedules. Milan anchors fragrance flacon decoration demand where weight and clarity convey luxury positioning. REACH intentionally added microplastic restrictions force reformulation cascades into compatible barrier packaging designs.
Poland
Warsaw corridor contract manufacturing offers first-mover positioning before local converter capacity catches skincare demand. EU Packaging and Packaging Waste Regulation recycled content mandates reshape material selection timelines. Polish converters leverage proximity to German cosmetics houses while operating below Rhine-Ruhr cost baselines.
Spain
Iberian multi-layer laminate pouch converters face seven-figure retrofit investments to accommodate paper-based barrier substrates. Barcelona and Madrid mass-market procurement favors lightweighted plastic formats compatible with legacy filling lines. Southern European PCR collection infrastructure gaps create input cost instability for molded polypropylene variants.
Europe Personal Care Packaging Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with premium skincare favoring integrated solution providers while mass-market haircare tolerates fragmented supply. The vendor base organizes around three strategic archetypes: precision dispensing system specialists, substrate-agnostic barrier material innovators, and vertically integrated glass molders. M&A activity concentrates on compounding partnerships for PCR supply security, while capacity expansion targets underpenetrated Eastern European corridors.
Among diversified packaging conglomerates, AptarGroup Inc. and Silgan Holdings Inc. exemplify the precision dispensing archetype, with Gerresheimer AG occupying a position within premium glass molding. Albéa Group and Mondi Group represent substrate innovation vectors—plastic compounding partnerships and paper-polymer hybrid convergence respectively. These five anchors illustrate how competitive positioning stratifies across technical specification depth, geographic proximity to demand clusters, and regulatory certification velocity rather than scale alone.
| Leading Market Players |
|---|
| AptarGroup Inc. |
| Silgan Holdings Inc. |
| Gerresheimer AG |
| Albéa Group |
| Libo Cosmetics Company Ltd |
| Amcor Plc |
| Berry Global Inc. |
| Mondi Group |
| Quadpack Industries SA |
| Others |
Supply & Pricing Matrix
Precision molding specialists concentrated in Germany's Rhine-Ruhr corridor anchor the skilled workforce pool, with labor-cost differentials between this cluster and emerging Warsaw-Bucharest corridors widening the spread between premium technical specifications and economy-grade commodity formats.
Pricing Analysis
Volume concentrates in mass-market haircare tubes where per-unit economics compress margins, while fragrance glass and airless skincare pumps capture the premium margin pool. Three-tier pricing structure across premium, standard, and economy levels separates certified REACH-compliant formats from import alternatives. Cost compression in PCR-dependent segments is intensifying because Southern European collection infrastructure gaps create input volatility. Mass-market procurement in Iberia shows highest price sensitivity; premium skincare marketers in France exhibit lowest sensitivity due to technical performance requirements.
Supply Chain Analysis
Regional distribution centers in the Rhine-Ruhr cluster operate on hub-and-spoke patterns feeding cosmetics houses across Western Europe. Manufacturing concentrates in Germany, France, and Italy, with compounding partnerships for PCR supply drawing from Albéa Group's network. Raw material dependencies include virgin and post-consumer recycled polyethylene terephthalate, borosilicate glass batches, and barrier-coated paper substrates. Single-source vulnerability in PCR resin streams from uneven collection infrastructure poses structural risk. Distribution runs through converter-direct relationships with cosmetics houses and contract manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where upstream control over PCR compounding partnerships and downstream filling-line retrofit capabilities determine who captures margin from regulatory compliance mandates.
For Market Incumbents: Hedge against PCR resin volatility by securing long-term compounding partnerships in Germany and Poland before Eastern European collection infrastructure matures. Anchor airless pump technical specifications through EMA validation cycle investments that delay competitive replication. Defend against paper-polymer hybrid entrants by accelerating Mondi-style barrier paper R&D partnerships.
For New Entrants and Emerging Players: EU Packaging and Packaging Waste Regulation recycled content mandates in Europe open a window for Polish and Romanian converters offering REACH-compliant formats below Rhine-Ruhr cost baselines. Target underpenetrated skincare contract manufacturing corridors in Warsaw and Bucharest where local capacity lags demand. Enter through digital UV-curable printing services for Milan and Paris independent perfume houses seeking compressed minimum order quantities.
For Investors and Strategic Acquirers: The window for entry favors precision dispensing specialists with EMA certification velocity and substrate-agnostic barrier material innovators. Long-term viability hinges on capturing compounding partnerships before PCR supply chains consolidate. Watch refill-station pilot scale-up in Scandinavian markets as the inflection signal for format economics reconfiguration.
| Strategic Initiative | Industry Significance |
|---|---|
| PCR Compounding Partnership | Secures resin supply chains amid EU Packaging and Packaging Waste Regulation mandates. |
| Airless Pump Certification Investment | Accelerates EMA validation cycles that protect premium skincare specification relationships. |
| Paper-Polymer Hybrid R&D | Opens pouch segments previously locked by multi-layer laminate incumbent equipment. |
| Digital Printing Capability Buildout | Captures Milan and Paris independent fragrance houses with compressed minimum order economics. |
| Eastern European Capacity Expansion | Positions ahead of Warsaw-Bucharest skincare contract manufacturing demand maturation. |
Research Methodology
Trade association filings, EU regulatory databases, and customs records formed the secondary backbone, supplemented by primary interviews with packaging converters, cosmetics procurement directors, and EMA regulatory affairs specialists. Bottom-up and top-down triangulation validated volume estimates across material formats and end-use segments. Stakeholder conversations with Rhine-Ruhr cluster plant managers and French ANSM compliance officers grounded certification timeline assumptions.
Bottom-up modeling built from individual converter capacity and utilization rates, while top-down analysis cross-checked against EU packaging waste generation statistics and cosmetics industry production data. Segmentation dimensions included packaging type, material substrate, end-use application, closure mechanism, and geographic demand cluster. CAGRs derived from trend extrapolation of regulatory compliance investment cycles and format substitution elasticities observed in refill economics pilots.
The model assumes a particular technology adoption path; alternative pathways for paper-polymer hybrid barrier performance would alter the outlook for plastic displacement rates. Forecasts reflect documented assumptions around REACH migration limit enforcement timing and PCR collection infrastructure buildout. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Packaging
Lip Gloss Tube Market
Cosmetic Packaging
Cream Jars Market
Cosmetic Packaging
Global Eye Cosmetic Packaging Market
Cosmetic Packaging
Latin America Personal Care Packaging Market
Cosmetic Packaging
Crimp Neck Serum Bottles Market
Cosmetic Packaging
Global Cosmetic Packaging Market
Cosmetic Packaging
US Personal Care Packaging Market
Cosmetic Packaging
Asia Pacific Cosmetic Packaging Market
Cosmetic Packaging
Skin Glossing Pencil Packaging Market
Cosmetic Packaging
Hair Care Packaging Market
Cosmetic Packaging
Asia Pacific Personal Care Packaging Market
Cosmetic Packaging
North America Cosmetic Packaging Market
Cosmetic Packaging
Plastic Cosmetic Packaging Market
Cosmetic Packaging
Fragrance Packaging Market
Cosmetic Packaging
Global Perfume Packaging Market
Cosmetic Packaging
Cosmetic Bottles Packaging Market