
 Speed Chute Market | 2026-2036
Speed Chute Market Size, Share, and Industry Trends Forecast 2026-2036
Speed Chute Market Analytics
The gap between premium adjustable chutes and commodity standard chutes is repositioning procurement patterns across athletic programs. SKLZ leverages direct-to-consumer channels and digital training content to sustain brand recognition among fitness enthusiasts. Performance Designs anchors its position through specialized military-grade parachute expertise applied to sports resistance equipment. Strong Enterprises competes on manufacturing scale, supplying bulk orders to collegiate athletic departments nationwide.
A speed chute is a resistance training device consisting of a fabric canopy attached to a harness worn by an athlete, generating drag force proportional to running velocity through air displacement, typically constructed from ripstop nylon with mesh ventilation panels and adjustable release clips for variable resistance calibration. The product type dimension shows adjustable chutes capturing margin pools through customization premiums while standard chutes occupy volume positions in institutional bulk purchasing. Within end users, sports teams dominate current revenue while fitness enthusiasts represent the fastest-growing segment as home gym investment persists post-pandemic.
The Consumer Product Safety Commission oversees sports equipment safety standards in the United States, while ISO 20957 establishes international fitness equipment testing protocols that manufacturers must satisfy for export access. ASTM International publishes voluntary consensus standards for athletic training equipment that influence insurance liability coverage and institutional procurement eligibility. Stakeholders must monitor evolving state-level concussion prevention mandates that increasingly prescribe certified resistance training protocols for youth athletics.
Market Dynamics
Adjustable resistance calibration technology is compressing replacement cycles and forcing manufacturers to integrate digital feedback systems or cede margin to specialized sensor providers. The shift from fixed-resistance to variable-drag systems reconfigures procurement criteria across collegiate athletic departments and military training facilities.
Growth Catalysts
- ISO 20957 certification mandates:Export eligibility for European fitness equipment distributors now requires documented compliance with international testing protocols, accelerating facility-level equipment refresh timelines.
- Home gym infrastructure investment:Post-pandemic residential fitness space construction in suburban United States markets sustains direct-to-consumer channel velocity for portable resistance systems.
- Concussion prevention protocols:State-level youth athletics mandates in Texas, California, and Florida increasingly prescribe certified resistance training regimens, embedding speed chutes into formal conditioning curricula.
Market Restraints
- Ripstop nylon supply concentration:Technical fabric production clusters in Zhejiang Province create input cost volatility and extended lead times for North American manufacturers.
- Substitution by sled-based resistance:Weighted sled systems offer comparable drag profiles without wind dependency, capturing budget-conscious institutional procurement in northern climates.
- ASTM liability coverage thresholds:Voluntary consensus standards for athletic training equipment elevate insurance premiums for uncertified product lines, compressing margins for commodity manufacturers.
Strategic Opportunities
- Underpenetrated Canadian collegiate athletics:U Sports programs maintain lower resistance training equipment density than NCAA counterparts, presenting first-mover positioning for adjustable chute suppliers.
- Military special operations procurement:Load-bearing parachute expertise from defense contractors converges with sports resistance applications, opening dual-use contract pathways.
- Direct-to-consumer subscription bundling:Digital training content integration with hardware sales creates recurring revenue streams and reduces customer acquisition costs through fitness influencer partnerships.
Industry Challenges
- Biomechanics specialist scarcity:Product development teams lack sufficient expertise in drag coefficient optimization for variable velocity profiles, delaying next-generation release schedules.
- Consumer Product Safety Commission compliance timelines:Equipment safety standard updates require extensive third-party testing, extending time-to-market for redesigned harness systems by 8-14 months.
- Mesh ventilation panel supplier consolidation:Limited qualified vendors for high-tear-strength breathable fabrics create single-source dependencies and quality assurance bottlenecks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Speed Chute Market |
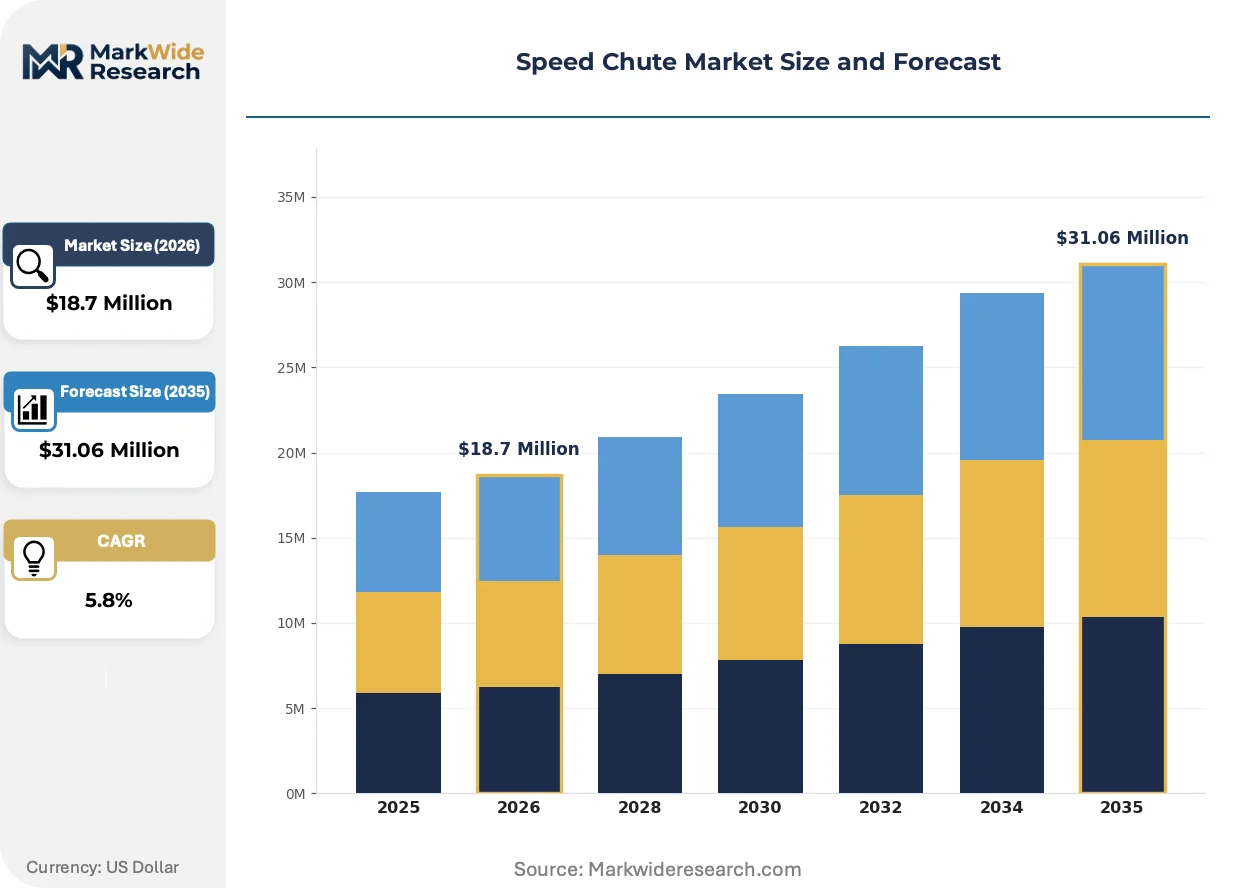
| Market Size in 2026 | $18.7 Million |
| Market Size in 2035 | $31.06 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Chutes, Adjustable Chutes, Parachute Chutes, Resistance Bands End User: Athletes, Coaches, Fitness Enthusiasts, Sports Teams Material: Nylon, Polyester, Lycra, Mesh Application: Speed Training, Agility Training, Strength Conditioning, Physiotherapy |
| Companies Covered | SKLZ, Strong Enterprises, Performance Designs, Precision Aerodynamics, Airborne Systems, Mills Manufacturing, FXC Corporation, Aerodyne Research, Parachute Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Speed Chute Market Evolving Landscape
Sensor-integrated resistance systems are compressing the feedback loop between training stimulus and performance analytics. Manufacturers now face pressure to embed telemetry or partner with wearable platforms.
Magnetic quick-release clip mechanisms are automating resistance level transitions during interval training protocols. Collegiate strength and conditioning coaches in the Southeastern Conference have adopted these systems at accelerated rates. The technology is automating manual adjustment labor and enabling more complex periodization schemes without coaching staff expansion.
ASTM International's updated athletic equipment liability guidelines are reshaping insurance underwriting for resistance training devices. Manufacturers must now document material fatigue testing under cyclic loading conditions to maintain coverage eligibility. Institutional buyers in Texas and California are prioritizing certified suppliers, compressing vendor pools for uncertified imports.
Fitness enthusiasts are unbundling equipment purchases from facility memberships, building permanent home training infrastructure. Specialty e-commerce platforms and direct-to-consumer brands capture this demand shift from traditional sporting goods retail. This behavioral pivot concentrates most visibly in suburban United States markets with dedicated garage gym construction.
Speed Chute Market Segmentation
Equipment refresh cycles across collegiate athletic departments and military training facilities create divergent replacement timelines by product tier. Procurement committees now weight calibration precision and telemetry compatibility alongside base durability metrics.
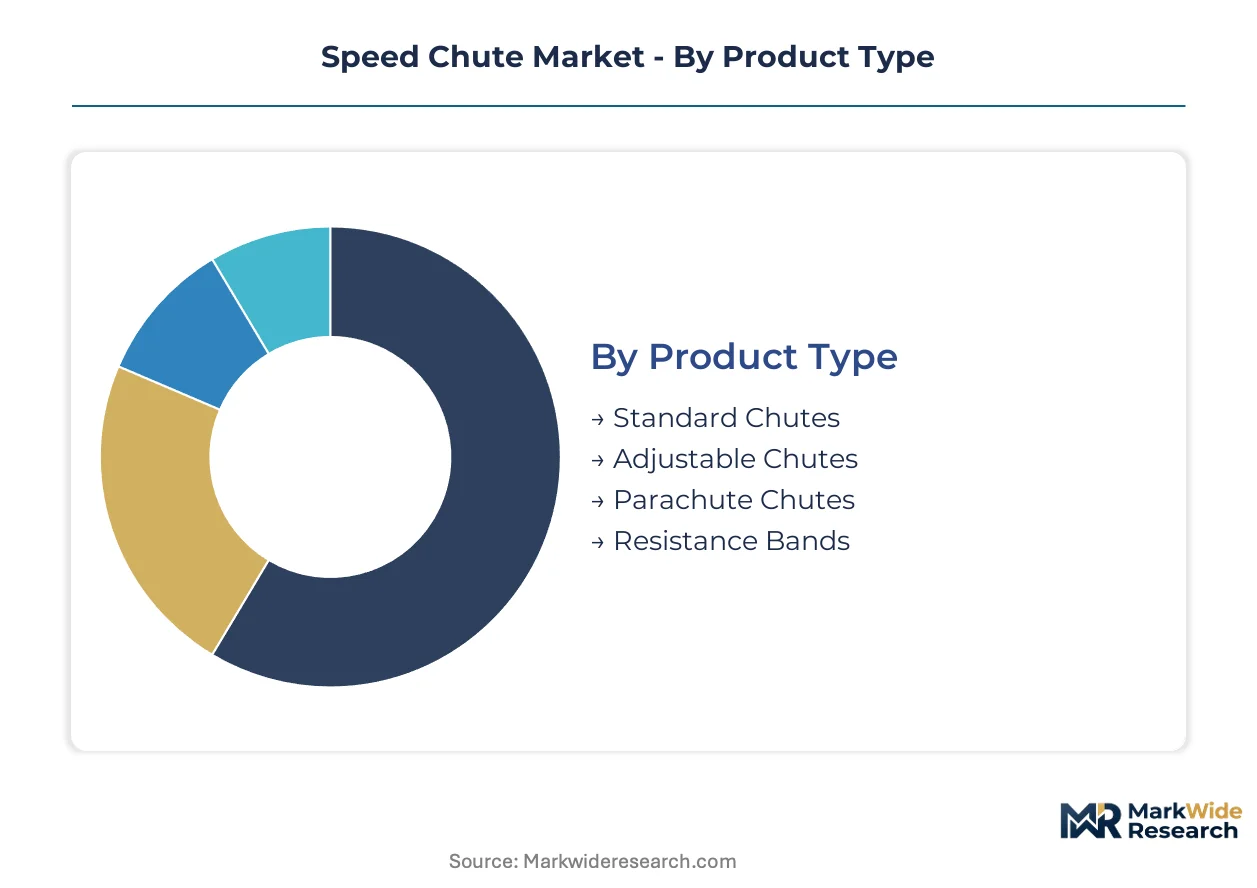
Product Type:
Adjustable resistance mechanisms are compressing replacement windows as fixed-drag systems face obsolescence pressure from variable-calibration alternatives.
- Standard Chutes:Fixed-resistance canopy systems constructed from single-layer ripstop nylon with fixed harness attachment points. Institutional bulk purchasing in Texas and California high school athletic programs sustains volume despite feature limitations.
- Adjustable Chutes:Multi-position release clip systems enable drag coefficient modification without equipment removal. Collegiate strength coaches in the Southeastern Conference prioritize these for periodization flexibility, driving premium positioning.
- Parachute Chutes:Military-derived canopy geometries with reinforced seam construction for high-velocity sprint applications.
- Resistance Bands:Elastic-based alternatives offering portability advantages for travel teams and individual athletes.
Standard chutes sit at the top of the volume ranking, with adjustable chutes climbing the fastest.
End User:
Cost tier stratification separates institutional procurement from individual purchase patterns across the customer base.
- Athletes:Individual competitors purchasing through direct-to-consumer channels or specialty retailers. Post-pandemic garage gym construction in suburban United States markets sustains demand for portable resistance systems with minimal setup requirements.
- Coaches:Staff-level procurement for team conditioning programs with budget constraints favoring multi-unit discounts.
- Fitness Enthusiasts:Home gym operators seeking equipment unbundled from facility memberships. This segment is expanding most quickly as residential fitness infrastructure investment persists.
- Sports Teams:Organizational purchasing with ISO 20957 compliance requirements and ASTM liability coverage thresholds driving vendor selection.
Sports teams anchor current revenue concentration, while fitness enthusiasts gain share fastest.
Material:
Supply concentration in Zhejiang Province fabric production clusters shapes input cost structures across material grades.
- Nylon:Ripstop weave configurations dominate professional-grade equipment with tear-strength specifications meeting military procurement standards.
- Polyester:Cost-optimized alternative for entry-level institutional purchasing with shorter expected service life.
- Lycra:Stretch-woven harness components providing anatomical conformity for extended training sessions. High-tear-strength breathable specifications create single-source vendor dependencies.
- Mesh:Ventilation panel integration reducing canopy oscillation at velocity while maintaining drag profile consistency.
Nylon commands the premium tier by performance specification, with mesh panel integration driving fastest specification growth.
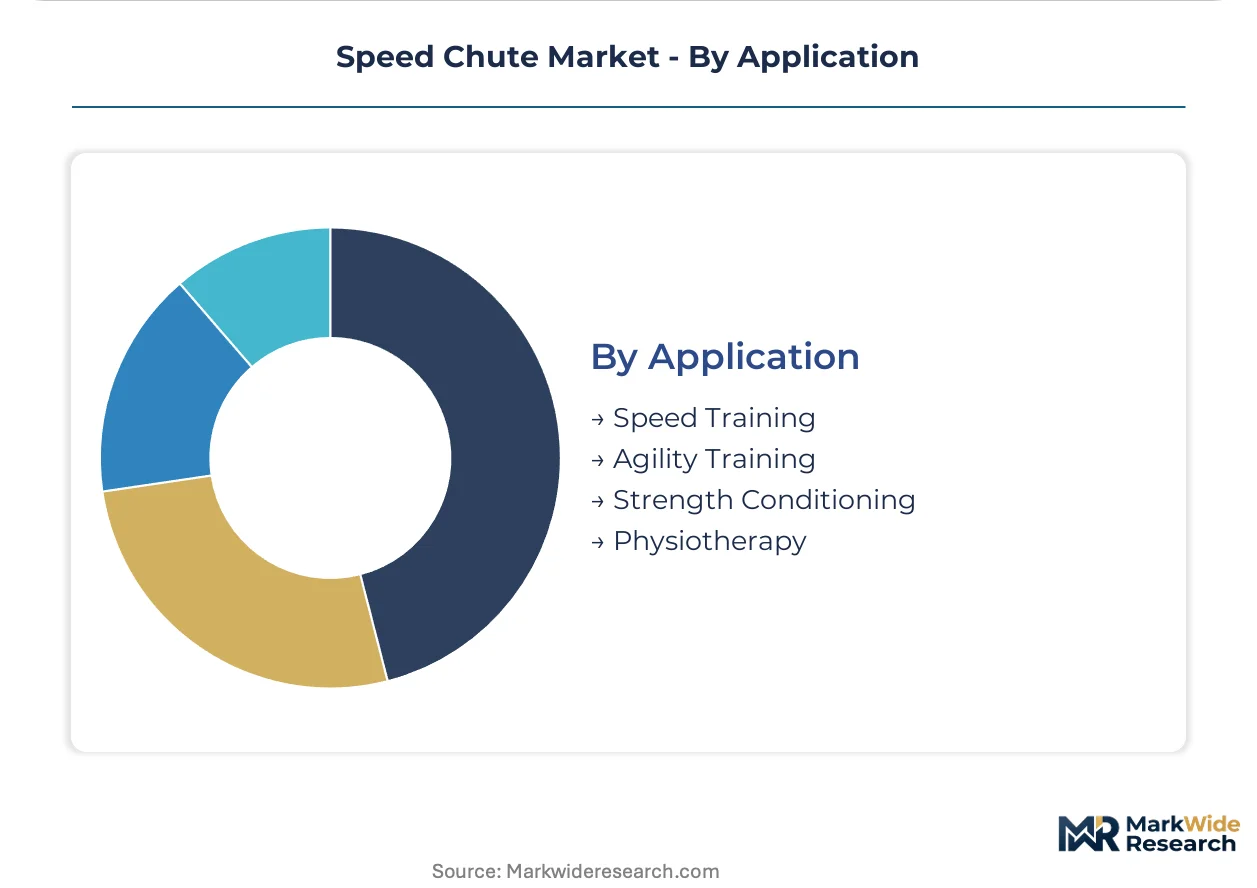
Application:
Maturity gradients separate established conditioning protocols from emerging therapeutic use cases.
- Speed Training:Linear sprint resistance protocols with documented drag coefficient optimization for variable velocity profiles. State-level concussion prevention mandates in Florida embed these systems into formal youth athletics curricula.
- Agility Training:Multi-directional movement patterns requiring quick-release mechanisms for resistance level automation during interval protocols.
- Strength Conditioning:Eccentric loading applications in collegiate weight rooms with integrated digital feedback systems.
- Physiotherapy:Controlled rehabilitation protocols with graduated resistance calibration for post-injury gait retraining.
Speed training holds the largest installed base, with physiotherapy applications showing steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Collegiate strength and conditioning coaches anchor demand concentration in the United States, while military procurement specialists in Canada and fitness facility operators in Germany sustain secondary demand poles.
United States
NCAA Division I athletic programs in Texas, California, and Florida drive institutional procurement volume for adjustable resistance systems. State-level concussion prevention mandates in these jurisdictions embed certified speed chutes into formal youth athletics conditioning curricula. Zhejiang Province fabric suppliers serve Los Angeles- and Dallas-based equipment distributors with extended lead times.
Canada
U Sports collegiate programs maintain lower resistance training equipment density than NCAA counterparts, presenting positioning opportunities for adjustable chute suppliers. Health Canada equipment safety guidelines influence procurement eligibility for institutional buyers. Toronto and Vancouver metropolitan areas concentrate private training facility investment in garage gym infrastructure.
Germany
Bundesliga football academies and Olympic training centers sustain professional-grade equipment demand with ISO 20957 compliance requirements. REACH regulations govern textile chemical safety for ripstop nylon imports into the European Union. Munich and Cologne host specialized fitness equipment distributors serving Central European markets.
China
Domestic fitness enthusiast segments expand through e-commerce direct-to-consumer channels in Shanghai and Beijing. GB standards for sports equipment safety apply to manufacturers serving both domestic and export markets. Zhejiang Province fabric production clusters supply technical nylon to North American and European equipment assemblers.
Australia
Australian Rules Football and rugby league conditioning programs drive institutional adoption of variable-resistance systems. TGA oversight of therapeutic goods influences physiotherapy application procurement in rehabilitation clinics. Sydney and Melbourne metropolitan areas concentrate specialty fitness retail and direct-to-consumer distribution infrastructure.
Speed Chute Market Competitive Landscape
Top-tier vendors anchor military-grade and professional sports procurement, while mid-tier fabricators compete on manufacturing scale for institutional bulk orders. The vendor base stratifies across parachute expertise derivatives, sporting goods specialists, and defense contractors with dual-use capabilities. Three archetypes dominate: load-bearing canopy specialists, direct-to-consumer fitness brands, and volume-scale textile manufacturers. Capacity expansion in Zhejiang fabric clusters and strategic partnerships with digital training platforms constitute the primary competitive moves.
Within the parachute expertise tier, Performance Designs and Strong Enterprises exemplify defense-to-sports technology transfer archetypes. SKLZ occupies a position representing direct-to-consumer fitness brand specialization with content-integrated hardware distribution. These three companies anchor the competitive structure without exhausting the vendor landscape.
| Leading Market Players |
|---|
| SKLZ |
| Strong Enterprises |
| Performance Designs |
| Precision Aerodynamics |
| Airborne Systems |
| Mills Manufacturing |
| FXC Corporation |
| Aerodyne Research |
| Parachute Systems |
| Others |
Value Network & Pricing Analysis
Certification-grade bifurcation between ISO 20957-compliant adjustable chutes and uncertified standard units manifests in pricing premiums of 40-60% for documented compliance, while simultaneously concentrating supply chain leverage among Zhejiang Province fabricators capable of meeting international testing protocols. This divergence forces North American assemblers to absorb extended lead times or sacrifice margin to secure qualified material streams.
Pricing Analysis
Bundled digital training content against unbundled hardware-only sales defines the pricing architecture. Subscription-integrated adjustable chutes from direct-to-consumer brands command recurring revenue premiums, while transactional per-unit pricing dominates institutional bulk procurement. Price differentiation hinges on ISO 20957 certification tier and customization depth for periodization protocols. Pricing pressure stems from weighted sled substitution in budget-constrained northern climate programs. High school athletic departments exhibit greatest price sensitivity; military special operations procurement shows least.
Supply Chain Analysis
Freight cost volatility from Zhejiang Province to Los Angeles and Dallas distribution hubs compresses landed margins for North American equipment assemblers. Supply concentrates in China for ripstop nylon and mesh ventilation panels, with secondary textile finishing in Vietnam and Bangladesh. Raw material dependencies include high-tear-strength breathable fabrics, magnetic quick-release hardware, and sensor-integrated telemetry modules. Single-source vulnerability pervades qualified mesh panel vendors. Distribution runs through specialty fitness equipment distributors and direct-to-consumer e-commerce platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
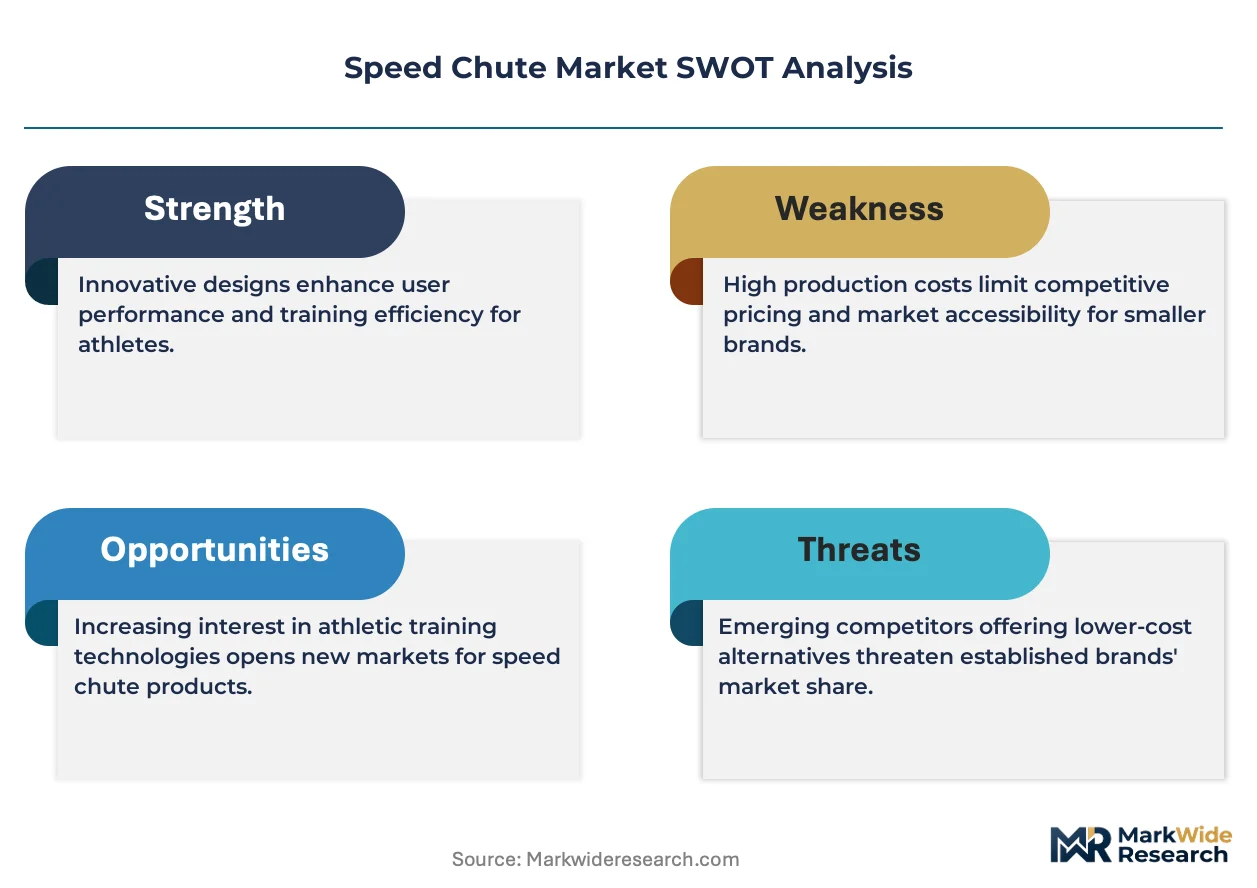
The Speed Chute Market functions as a stable compounder anchored by persistent post-pandemic home gym infrastructure investment and embedded institutional procurement cycles across collegiate athletics.
For Market Incumbents: Lock in supply chain position through captive relationships with Zhejiang fabricators qualified for ISO 20957 material specifications, while accelerating sensor-integrated product development to preempt specialized wearable partnerships. Sled-based resistance substitution threatens volume-positioned standard chute lines. Certification investment in ASTM liability documentation preserves institutional channel access. For New Entrants and Emerging Players: The mid-tier price-point gap between premium adjustable systems and commodity standard chutes offers positioning room for digitally-native brands with content-bundled offerings. Canadian U Sports programs present underpenetrated institutional demand relative to NCAA density. Fitness enthusiast direct-to-consumer acquisition through influencer partnership networks provides the most penetrable go-to-market vector. For Investors and Strategic Acquirers: Consolidation pressure builds where manufacturing scale advantages intersect with certification compliance burdens that exclude sub-scale competitors. Long-term viability favors vertically integrated players with captive textile supply and dual-use military-sports contract pathways. Acquisition targets include mid-tier fabricators with ISO 20957 documentation and established collegiate distribution relationships. Monitor state-level concussion prevention mandate expansion as inflection signal for institutional demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Investment | ISO 20957 compliance unlocks European distributor eligibility and institutional procurement pools. |
| Digital Content Integration | Subscription bundling with SKLZ-style training platforms reduces customer acquisition costs. |
| Backward Integration | Captive Zhejiang fabric relationships insulate against ripstop nylon supply volatility. |
| Geographic Expansion | Canadian U Sports penetration captures first-mover positioning in under-equipped collegiate markets. |
| Dual-Use Contracting | Military parachute expertise transfer opens special operations procurement alongside sports applications. |
Research Methodology
Direct dialogue with collegiate strength and conditioning coaches, military procurement specialists, fitness equipment distributors, and textile manufacturing executives grounded qualitative insights, cross-referenced against customs trade data, SEC filings from sporting goods companies, ISO certification registries, and state athletic association equipment procurement records. Bottom-up unit demand modeling triangulated against top-down market sizing from trade flow analysis.
Segmented outputs across product type, end user, material specification, and application dimensions populated the analytical framework across the projection horizon. CAGRs derived from replacement cycle analysis, institutional budget trajectory assessment, and home gym investment persistence indicators. Forecast inputs incorporated concussion prevention mandate adoption curves and sensor-integrated product penetration assumptions.
Caveats apply where Zhejiang supply disruptions, accelerated sled-based substitution, or ASTM standard revision timelines could materially shift the outlook. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor and Adventure Activities
Motorized Pool Tube Market
Outdoor and Adventure Activities
Outdoor Backpack Market
Outdoor and Adventure Activities
Hiking Gear and Equipment Market
Outdoor and Adventure Activities
Global Climbing Shoes Market
Outdoor and Adventure Activities
Rafting Equipment Market
Outdoor and Adventure Activities
Global Personal Watercraft Market
Outdoor and Adventure Activities
Global Ski Poles Market
Outdoor and Adventure Activities
Paragliding Equipment Market
Outdoor and Adventure Activities
Fat Bike Market
Outdoor and Adventure Activities
Hammocks Market
Outdoor and Adventure Activities
Global Hydration Backpack Market
Outdoor and Adventure Activities
Recreational Sports Activities Market
Outdoor and Adventure Activities
Kayak Market
Outdoor and Adventure Activities
Asia-Pacific Spectator Sports Market
Outdoor and Adventure Activities
Hydration Packs Market
Outdoor and Adventure Activities
Recreational Use Water Chute Market