
 Spain Artificial Turf Market | 2026-2036
Spain Artificial Turf Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Artificial Turf Market Analytics
Buyer concentration among municipal athletic facilities is expanding as regional governments consolidate procurement for sports infrastructure upgrades. SUMIGRAN leverages its manufacturing scale to serve large public tenders across Spain's autonomous communities. Easigrass anchors the residential landscaping channel through specialized dealer networks. Realturf competes on product specialization for elite sports performance surfaces.
Artificial turf consists of synthetic fiber piles—typically polyethylene, polypropylene, or nylon—tufted into permeable backings and often combined with infill materials to simulate natural grass play characteristics. The manufacturing process involves extrusion of polymer fibers, followed by tufting, coating with latex or polyurethane backing, and quality testing for pile height, density, and drainage rates. Sports Fields applications dominate volume due to FIFA and UEFA certification requirements for competitive pitches, while Landscaping generates premium margins in residential retrofit projects. PE fiber formulations lead installation volumes for their balance of softness and durability, whereas Nylon concentrates in high-wear athletic zones. Non-Infill systems are gaining traction in rooftop and constrained-access projects across Spanish urban centers.
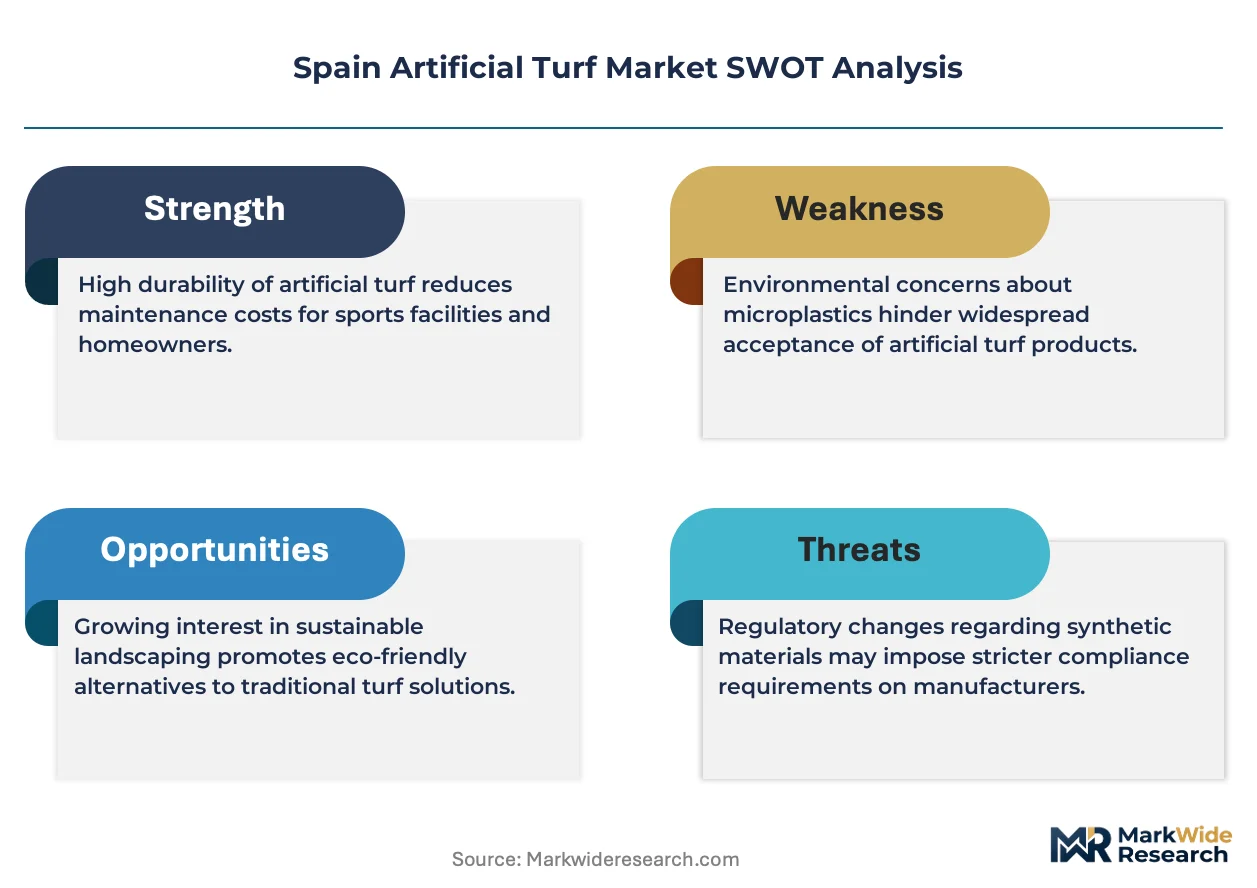
Spain's Ministry for the Ecological Transition enforces water-use restrictions under national drought decrees, directly limiting natural grass maintenance at public facilities. BIS-equivalent polymer standards and EU REACH compliance govern fiber chemical safety, while municipal procurement rules increasingly mandate recycled content in backing materials. Stakeholders must monitor evolving regional water pricing and green public procurement criteria to anticipate demand shifts in sports infrastructure planning.
Market Dynamics
Spain's artificial turf sector faces structural pressure from water scarcity mandates that eliminate natural grass maintenance as a viable option for public facilities, while polymer supply chains and certification requirements reshape competitive economics.
Growth Catalysts
- Ecological Transition Ministry drought decrees:National water-use restrictions force municipal sports complexes across Andalusia, Catalonia, and Valencia to abandon irrigation-dependent natural surfaces.
- Polyethylene fiber formulations:Advanced PE polymers deliver the softness-durability balance required for FIFA and UEFA certification, expanding eligible installation volumes for competitive pitches.
- Barcelona metropolitan infrastructure renewal:Concentrated public procurement for athletic facility upgrades generates sustained demand from consolidated municipal buyers.
Market Restraints
- Petrochemical input volatility:Polyethylene and polypropylene resin prices fluctuate with crude oil markets, compressing margin predictability for domestic installers.
- EU REACH compliance burden:Chemical safety documentation requirements for polymer fibers and latex backings extend product development timelines and testing costs.
- Natural grass renovation economics:Hybrid grass systems and improved drought-tolerant turf varieties retain cost advantages for low-use recreational fields in northern Spain's wetter climates.
Strategic Opportunities
- Non-infill system penetration:Rooftop installations and constrained-access urban projects across Madrid and Barcelona city centers favor lightweight surfaces eliminating sand and rubber infill logistics.
- Recycled content mandates:Green public procurement criteria from autonomous community governments increasingly specify post-consumer backing materials, rewarding early compliance investment.
- Residential landscaping retrofit:Dealer networks serving private homeowners in Costa del Sol and Balearic Islands generate premium margins beyond municipal sports contracts.
Industry Challenges
- Specialized installation labor scarcity:Proper seam welding, drainage gradient engineering, and infill distribution require certified technicians that outpace training program output.
- FIFA Quality Pro certification timelines:Elite sports surface validation demands extended field testing periods that delay revenue recognition on high-value competitive pitch contracts.
- Legacy natural grass maintenance contracts:Municipal procurement departments retain multi-year service agreements that slow synthetic conversion decision cycles despite regulatory pressure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Artificial Turf Market |
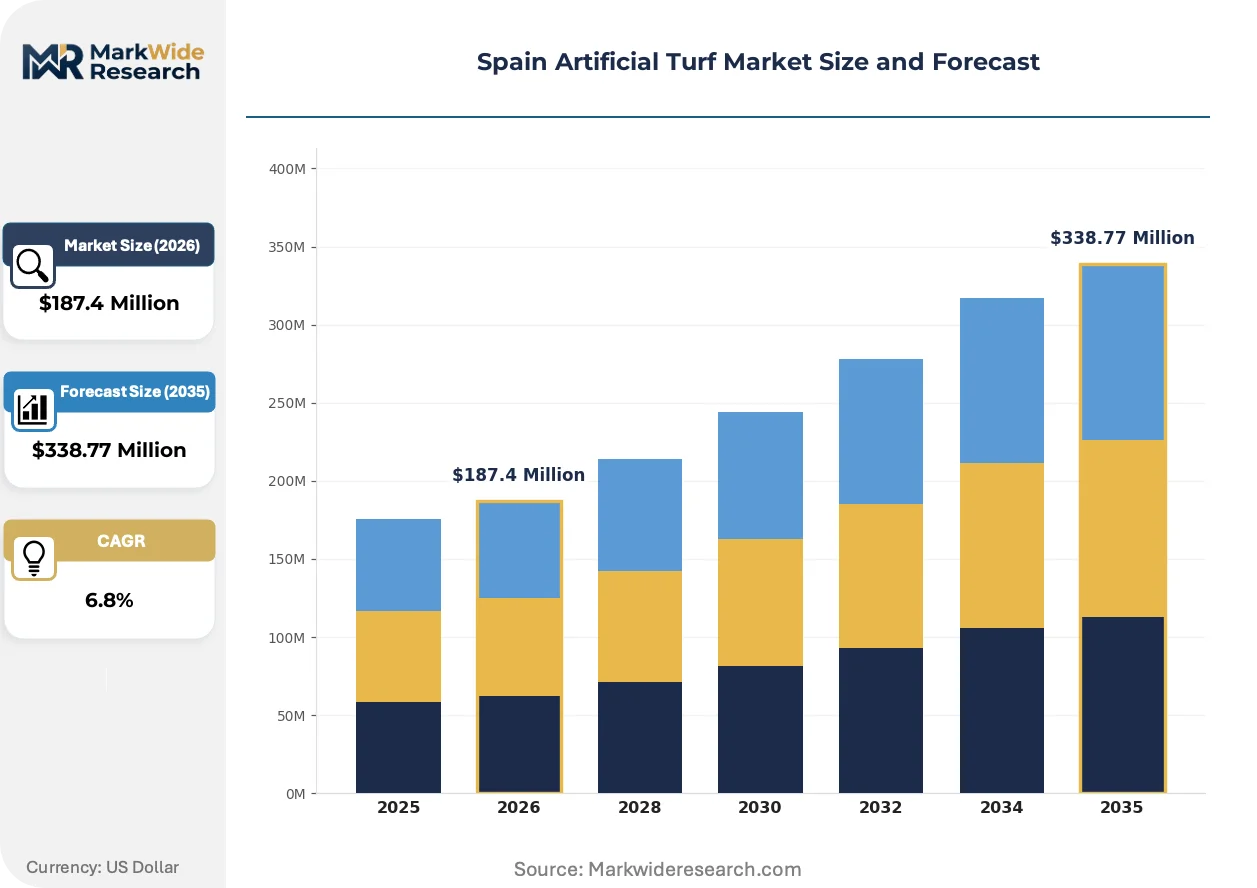
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PP, PE, Nylon, TPR Application: Sports Fields, Landscaping, Playgrounds, Rooftops End User: Athletic Facilities, Residential, Educational Institutions, Public Parks Installation Type: Infill, Non-Infill, Hybrid, Modular |
| Companies Covered | SUMIGRAN, Easigrass, Realturf, Evolution Grass, TodoCESPED – Arelux Group, INTERCESPED Césped Artificial, Best Garden, All Grass, Albergrass, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Artificial Turf Market Evolving Landscape
Water stress is forcing material science advances and procurement restructuring across Spain's sports infrastructure landscape, with polymer chemistry and installation methods evolving rapidly.
Non-infill synthetic surfaces are decentralizing project economics by eliminating heavy infill material transport and specialized handling equipment. Urban developers in Madrid's dense districts and Barcelona's rooftop sports facilities adopt these systems for logistics simplicity. The technology is decentralizing installation capacity requirements, allowing smaller regional contractors to compete for projects previously requiring capital-intensive infill management infrastructure.
Spain's Ministry for the Ecological Transition enforces escalating water pricing tiers under national drought contingency frameworks. Municipal facility operators face surcharges for groundwater extraction that render natural grass maintenance financially unsustainable. Andalusian and Extremaduran sports complexes respond fastest, accelerating synthetic conversion timelines to lock in fixed-cost surface economics.
Consolidated public tendering now dominates volume procurement as autonomous communities centralize sports infrastructure budgets. Regional governments replace fragmented municipal purchasing with standardized specifications and multi-site awards. This concentration is most visible in Catalonia's aggregated athletic facility renewal programs, where single contracts cover dozens of pitches across Barcelona's metropolitan municipalities.
Spain Artificial Turf Market Segmentation
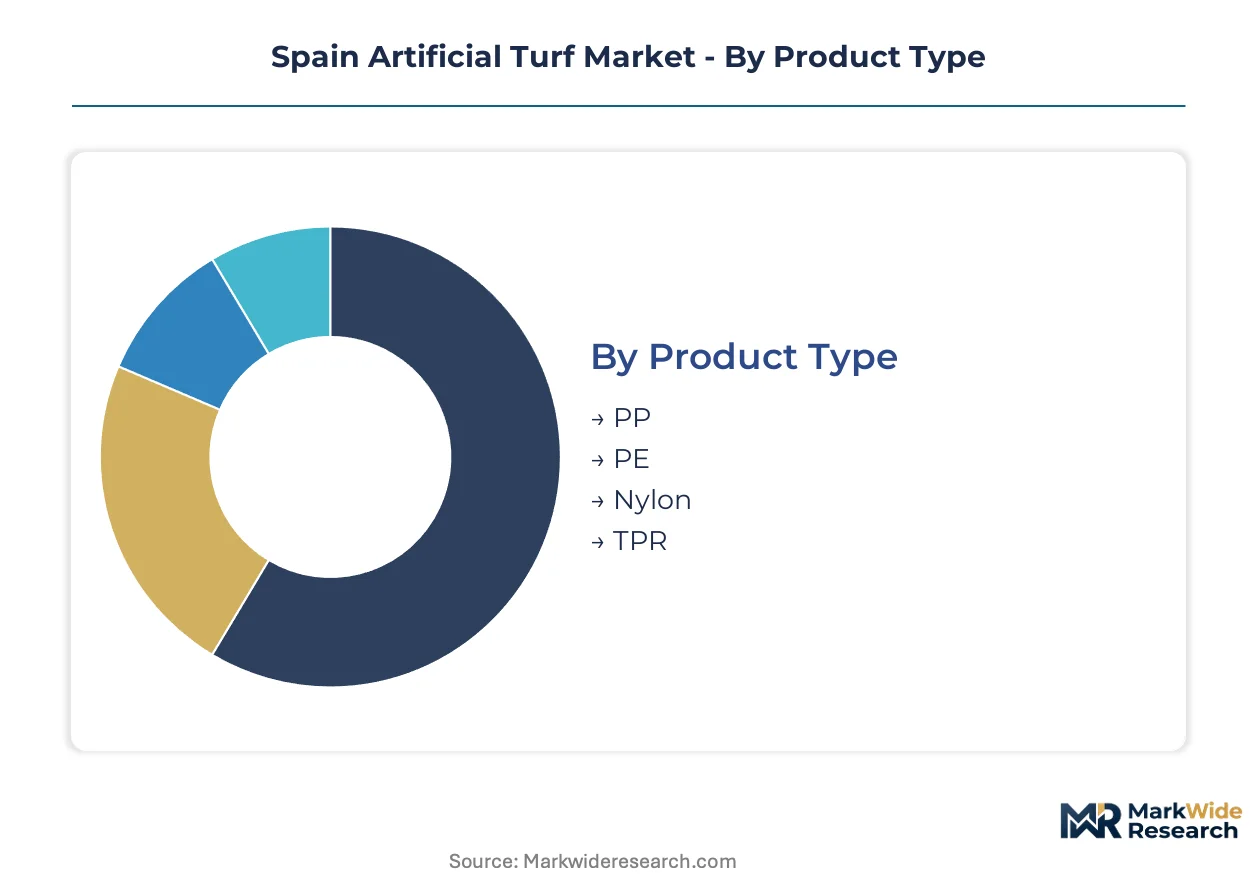
Spain's artificial turf market segments reflect divergent performance requirements across water-stressed geographies and installation constraints. Procurement patterns vary sharply between municipal athletic tenders demanding FIFA-certified durability and residential retrofit projects prioritizing aesthetic softness.
Product Type:
Polymer chemistry determines installation economics and regulatory compliance pathways for Spanish buyers.
- PE:Polyethylene fiber formulations balance softness with abrasion resistance, meeting UEFA durability standards for competitive pitches in Barcelona's metropolitan renewal zones. Andalusian municipal complexes favor PE for its lower surface temperature under extreme solar exposure.
- PP:Polypropylene dominates budget-constrained installations across Extremaduran public parks, trading some resilience for material cost advantages. Regional procurement offices specify PP for low-traffic recreational fields where certification is not required.
- Nylon:High-tenacity polymer engineered for elite sports zones with extreme wear patterns.
- TPR:Thermoplastic rubber infill alternatives addressing EU REACH chemical safety scrutiny.
PE leads volumes today; TPR is gaining share fastest.
Application:
Usage intensity and water access constraints reshape demand distribution across Spanish regions.
- Sports Fields:FIFA and UEFA certification requirements govern competitive pitch specifications, with Catalonia's consolidated municipal tenders driving concentrated volume. Drought decrees from Spain's Ministry for the Ecological Transition accelerate conversion timelines for irrigation-dependent natural grass facilities.
- Landscaping:Residential retrofit projects in Costa del Sol and Balearic Islands generate premium margins through specialized dealer networks. Private homeowners prioritize visual uniformity and elimination of maintenance labor over play-performance metrics.
- Playgrounds:Fall-height safety standards and shock-absorption certification dominate procurement criteria for educational institutions.
- Rooftops:Weight-constrained urban installations across Madrid's dense districts favor lightweight surface systems.
Sports Fields commands the largest revenue base; Rooftops climbs the fastest as urban density intensifies.
End User:
Budget cycles and regulatory exposure differentiate procurement behaviors across buyer categories.
- Athletic Facilities:Municipal sports complexes operate under national drought contingency frameworks that prohibit groundwater extraction for irrigation. Andalusian regional governments consolidate multi-site tenders, replacing fragmented municipal purchasing with standardized specifications.
- Residential:Private homeowners in water-stressed coastal provinces adopt synthetic surfaces for swimming pool perimeters and garden aesthetics. Dealer network density determines market penetration in Balearic Islands resort communities.
- Educational Institutions:School districts balance capital expenditure constraints against student safety certification requirements.
- Public Parks:Municipal maintenance departments evaluate total lifecycle costs against natural grass renovation economics in northern Spain's wetter climates.
Athletic Facilities anchors volume demand; Residential expands most quickly on premium pricing.
Installation Type:
Logistics complexity and site access constraints determine system selection for Spanish contractors.
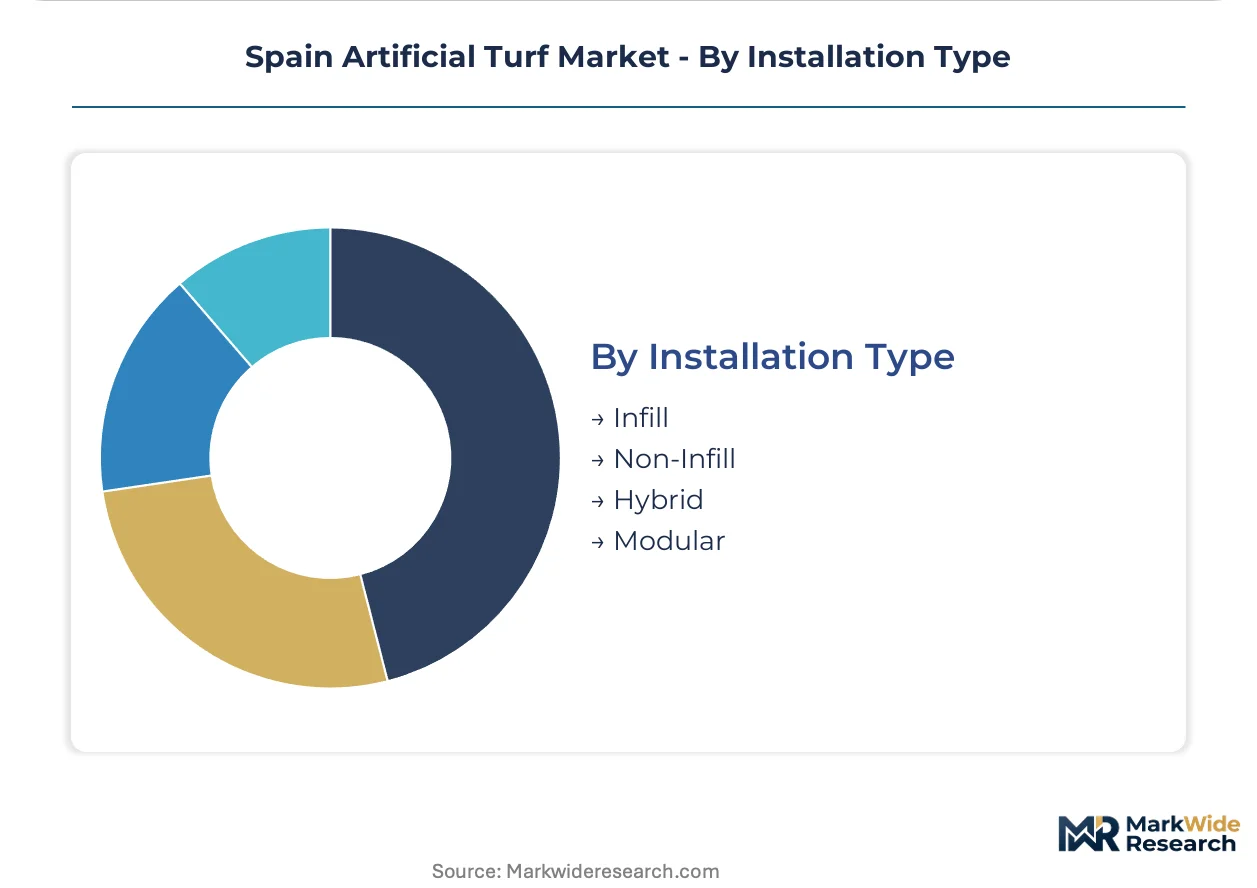
- Non-Infill:Elimination of sand and rubber granule transport enables rooftop and constrained-access projects across Barcelona's urban core. Smaller regional contractors compete effectively without capital-intensive infill management infrastructure.
- Infill:Traditional sand and rubber systems retain dominance for full-size competitive pitches requiring FIFA Quality Pro certification. Extended field testing timelines delay revenue recognition on high-value municipal contracts.
- Hybrid:Reinforced natural grass systems preserve play characteristics for elite venues with intensive maintenance budgets.
- Modular:Interlocking tile configurations serve temporary event surfaces and rapid-deployment scenarios.
Infill retains the largest installed base; Non-Infill shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's artificial turf sector emphasizes elite sports certification and industrial polymer innovation, whereas Spain's market accelerates conversion timelines driven by water scarcity mandates and municipal procurement consolidation.
Catalonia
Barcelona's metropolitan athletic infrastructure renewal programs concentrate demand through consolidated municipal tenders covering dozens of pitches simultaneously. The autonomous community's green public procurement criteria increasingly mandate recycled content in backing materials. Industrial fabricators cluster around the metropolitan zone to serve standardized multi-site awards.
Andalusia
Municipal sports complexes across Seville, Málaga, and Córdoba abandon irrigation-dependent natural surfaces under national drought contingency frameworks. Spain's Ministry for the Ecological Transition enforces escalating water pricing tiers that render groundwater extraction financially unsustainable. Regional governments consolidate procurement for sports infrastructure upgrades, replacing fragmented municipal purchasing.
Madrid
Urban density drives rooftop installations and constrained-access projects favoring lightweight non-infill systems across the capital's dense districts. The metropolitan area's dealer networks serve residential landscaping retrofits for private homeowners prioritizing swimming pool perimeters and garden aesthetics. Madrid-based contractors compete effectively without capital-intensive infill management infrastructure.
Valencia
Coastal water stress accelerates synthetic conversion timelines for public facilities across the province's municipal complexes. Regional procurement offices specify polypropylene for budget-constrained installations in low-traffic recreational fields. Valencia's sports infrastructure planners balance FIFA certification requirements against lifecycle cost economics.
Spain Artificial Turf Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Spain's artificial turf sector, creating a tiered structure where manufacturing scale, certification depth, and channel specialization determine positioning. The vendor base segments into three strategic archetypes: large-scale polymer processors serving consolidated public tenders, specialized installers targeting residential retrofit channels, and performance-focused engineers delivering elite sports surfaces. Dominant competitive moves include backward integration into polymer extrusion capacity and geographic expansion through autonomous community procurement frameworks.
Among manufacturing-scale specialists, SUMIGRAN anchors the tier serving large public tenders across Spain's autonomous communities through production volume advantages. Easigrass occupies a position exemplifying residential channel focus, with dealer network density determining penetration in Costa del Sol and Balearic Islands resort markets. Realturf represents the product specialization archetype, competing on elite sports performance surfaces requiring extended FIFA Quality Pro certification timelines.
| Leading Market Players |
|---|
| SUMIGRAN |
| Easigrass |
| Realturf |
| Evolution Grass |
| TodoCESPED – Arelux Group |
| INTERCESPED Césped Artificial |
| Best Garden |
| All Grass |
| Albergrass |
| Others |
Value Network & Pricing Analysis
Polyethylene resin costs cascade through three distinct pricing tiers as extrusion capacity concentrates among Iberian polymer processors serving municipal tender markets. Labor scarcity at the installation layer compounds margin pressure for certified seam welding technicians across Andalusian and Catalan project clusters.
Pricing Analysis
Capacity additions in Valencia and Murcia are reshaping price floors for polypropylene fiber grades, compressing spreads between budget municipal specifications and FIFA-certified surfaces. Three-tier pricing structure across premium, standard, and economy levels separates elite sports performance systems from recreational field installations. Cost compression in the economy tier is intensifying because regional procurement offices consolidate multi-site awards. Municipal athletic facilities exhibit highest price sensitivity, while residential landscaping buyers in Balearic resort markets absorb premium positioning.
Supply Chain Analysis
Polymer feedstock supply rests on Saudi Arabian and Qatari petrochemical complexes for polyethylene resin, with Italian and German specialty chemical producers dominating polyurethane backing formulations. Raw material dependencies span crude oil derivatives, calcium carbonate fillers, and UV stabilizer packages. Single-source vulnerability concentrates in latex backing imports subject to EU REACH documentation delays. Distribution runs through autonomous community procurement hubs rather than fragmented municipal purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spain's artificial turf sector represents a late-cycle quality story as drought contingency frameworks displace commodity natural grass specifications with certified synthetic alternatives demanding premium durability standards.
For Market Incumbents: Cement manufacturing scale advantages through backward integration into polymer extrusion capacity serving consolidated Andalusian and Catalan tenders. Lock in multi-year supply agreements with municipal procurement hubs before green public procurement criteria mandate recycled content thresholds. Certification investment in FIFA Quality Pro validation creates defensive moats against emerging regional installers lacking testing infrastructure. For New Entrants and Emerging Players: Capture rooftop installation niches across Madrid's dense urban districts where non-infill system logistics favor smaller contractors without capital-intensive infill management equipment. The residential landscaping channel in Costa del Sol resort communities offers lowest barriers to entry through dealer network partnerships rather than direct municipal tender competition. Lead with lightweight surface system specialization and rapid-deployment project capabilities. For Investors and Strategic Acquirers: Consolidation pressure builds where autonomous community procurement centralization eliminates sub-scale municipal installers lacking standardized specification expertise. The five-to-ten year viability window favors targets with captive polymer extrusion capacity and established FIFA certification relationships. Watch for inflection signals in regional water pricing tier escalations that accelerate conversion timelines beyond current procurement pipeline visibility.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Extrusion | Captive polyethylene supply secures margin control against petrochemical volatility. |
| FIFA Quality Pro Certification Investment | Elite sports validation opens consolidated municipal tender participation across Catalonia. |
| Recycled Content Backing Development | Preemptive compliance with green public procurement criteria from Valencia and Andalusia. |
| Non-Infill System Portfolio Expansion | Lightweight surfaces penetrate Madrid rooftop and constrained-access urban projects. |
| Dealer Network Density Buildout | Channel control captures premium residential margins in Balearic Islands resort markets. |
Research Methodology
Direct dialogue with municipal sports facility directors, polymer extrusion plant managers, certified installation contractors, and autonomous community procurement officers grounded qualitative findings. Secondary validation drew from Spain's Ministry for the Ecological Transition drought decree documentation, EU REACH chemical safety filings, Catalan and Andalusian public tender databases, and customs records of polymer resin imports. Bottom-up project pipeline enumeration triangulated against top-down autonomous community infrastructure budget allocations.
Bottom-up volume modeling tracked installation square footage by product type, application, and end user across Spain's seventeen autonomous communities. Segmentation dimensions included polymer chemistry grade, FIFA certification tier, infill system category, and regional water stress classification. CAGRs derived from regression analysis of historical conversion rates from natural grass to synthetic surfaces against regulatory enforcement intensity metrics. Forecast inputs incorporated municipal procurement cycle timing and drought contingency framework activation thresholds.
Petrochemical input volatility, EU regulatory timeline extensions, and municipal budget reallocation delays are the dominant revision risks across the projection horizon. Forecasts reflect documented assumptions regarding drought decree enforcement consistency and polymer supply chain stability. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor and Adventure Activities
Fat Bike Market
Outdoor and Adventure Activities
Snorkeling Market
Outdoor and Adventure Activities
Kayak Market
Outdoor and Adventure Activities
Power Sports Market
Outdoor and Adventure Activities
Recreation Services Market
Outdoor and Adventure Activities
US Spectator Sports Market
Outdoor and Adventure Activities
Recreational Use Water Chute Market
Outdoor and Adventure Activities
Kitesurf Kites Market
Outdoor and Adventure Activities
Adventure Sports and Activities Market
Outdoor and Adventure Activities
Hiking Cleats Market
Outdoor and Adventure Activities
North America Spectator Sports Market
Outdoor and Adventure Activities
Global Inflatable Outdoor Leisure Product Market
Outdoor and Adventure Activities
Climbing Harness Market
Outdoor and Adventure Activities
Asia-Pacific Spectator Sports Market
Outdoor and Adventure Activities
North America Personal Watercraft Market
Outdoor and Adventure Activities
Spain Sports Tourism Market