
 United Arab Emirates Coffee Roaster Market | 2026-2036
United Arab Emirates Coffee Roaster Market Size, Share, and Industry Trends Forecast 2026-2036
United Arab Emirates Coffee Roaster Market Insights
Specialty roasting technician shortages across the Gulf Cooperation Council region is unwinding capacity expansion plans for several equipment buyers. BKRY leverages its Dubai-based training academy to cultivate local talent pools and reduce dependency on expatriate operators. Five Elephant Roastery anchors its competitive stance through direct-source green coffee relationships that sustain consistent throughput on precision roasting equipment. The Espresso Lab dominates the high-end café segment with in-house roasting operations that control quality parameters from bean to cup.
A coffee roaster is a thermal processing machine that applies controlled heat between 180°C and 230°C to green coffee beans, initiating Maillard reactions and pyrolysis to develop aromatic compounds, solubility, and color for commercial brewing. The primary purpose spans flavor development, batch consistency, and shelf-life extension for retail and foodservice distribution. Drum roasters occupy the largest installed base across UAE commercial kitchens due to proven thermal uniformity and operator familiarity with traditional profiles. Small batch capacity systems represent the fastest-growing configuration as micro-roasteries proliferate in Dubai Design District and Al Quoz industrial zones. Specialty coffee shops command premium equipment specifications, driving margin concentration toward precision-controlled, data-logging roaster models.
MOHAP, the UAE's health regulator, mandates food-grade stainless steel contact surfaces and temperature validation protocols that shape equipment design standards for all imported roasting machinery. ESMA certification requirements for electrical safety and energy efficiency filter non-compliant suppliers from the UAE market, effectively raising competitive barriers. Stakeholders must monitor evolving Gulf Standardization Organization harmonization efforts that could unify technical specifications across Saudi Arabia, Kuwait, and the Emirates, altering procurement and compliance cost structures for roasting equipment deployed across multi-country café networks.
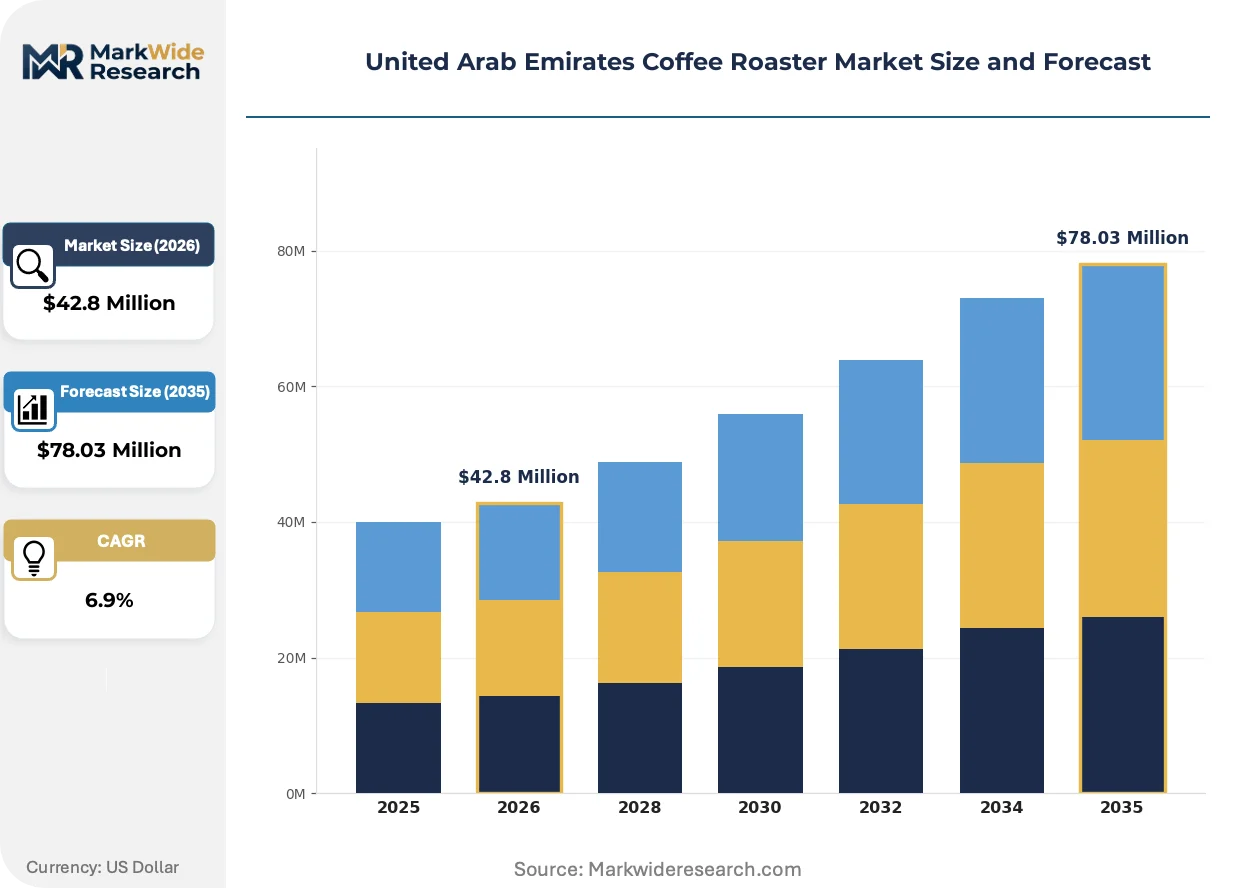
Market Dynamics
Specialty coffee culture across Dubai and Abu Dhabi is compressing equipment replacement cycles, as third-wave cafés demand data-logging precision roasters that outperform traditional drum systems on consistency metrics. This demand compression is reshaping supplier qualification criteria and technical service expectations throughout the Emirates.
Growth Catalysts
- ESMA energy efficiency mandates:Certification requirements for electrical safety and energy performance filter non-compliant imports, elevating standards for precision-controlled roasting systems that command premium positioning.
- Dubai Design District clustering:Micro-roastery proliferation in Al Quoz and D3 industrial zones concentrates equipment demand for small-batch configurations with rapid profile repeatability.
- Maillard reaction optimization:Advanced thermal profiling software enables artisanal operators to replicate signature roast curves, extending equipment utility beyond commodity production.
Market Restraints
- Specialized technician scarcity:Gulf Cooperation Council-wide shortages of certified roasting operators constrain throughput expansion for precision equipment owners.
- Green coffee price volatility:Arabica futures fluctuation compresses working capital available for complementary equipment procurement among independent roasters.
- MOHAP stainless steel mandates:Food-grade contact surface requirements elevate imported machinery costs, particularly for drum roasting chamber fabrications.
Strategic Opportunities
- Abu Dhabi specialty corridor:Lower third-wave café density versus Dubai presents whitespace for equipment deployment ahead of demand maturation.
- IoT-enabled predictive maintenance:Sensor-integrated roasting systems allow remote thermal monitoring, reducing dependency on on-site technical expertise.
- Gulf Standardization Organization harmonization:Unified technical specifications across Saudi Arabia, Kuwait, and the Emirates would streamline multi-country café network procurement.
Industry Challenges
- Roasting profile certification timelines:MOHAP temperature validation protocols extend commissioning periods for imported precision equipment.
- Legacy drum system integration:Established operators face operational friction retrofitting data-logging infrastructure onto traditional thermal platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Arab Emirates Coffee Roaster Market |
| Market Size in 2026 | $42.8 Million |
| Market Size in 2035 | $78.03 Million |
| CAGR (2026 – 2036) | 6.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Roaster Type: Drum Roaster, Air Roaster, Fluid Bed Roaster, Hybrid Roaster, Infrared Roaster Capacity: Small Batch, Medium Batch, Large Batch, Commercial Scale, Industrial Scale Application: Cafes, Specialty Coffee Shops, Foodservice Providers, Coffee Exporters, Hospitality Venues End User: Independent Roasters, Chain Roasteries, Distributors, Private Label Brands, Equipment Retailers |
| Companies Covered | BKRY, Five Elephant Roastery, The Espresso Lab, Orphans Coffee Roasters, Wild & Coffee Roasters, Cypher Urban Roastery, NTL Coffee Roasters, Guardian Coffee Roasters, Seed Coffee Roasters, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Arab Emirates Coffee Roaster Market Trends and Innovations
Digital thermal profiling and remote monitoring capabilities are redefining equipment value propositions across Emirati specialty coffee operations. Suppliers now compete on software ecosystems rather than hardware specifications alone.
Automated roast profiling software is bifurcating the installed base between precision-enabled specialty operators and traditional drum users. Third-wave cafés in Dubai's Al Quoz industrial zone adopt cloud-connected systems within eighteen-month replacement cycles. This technology compression is enabling consistent throughput without expatriate technician dependency.
MOHAP's stainless steel contact surface mandates are elevating fabrication standards for all imported roasting machinery. Equipment suppliers must redesign drum assemblies and cooling trays to comply with food-grade specifications before UAE market entry. Specialty coffee shops absorb these cost premiums through extended equipment financing structures.
Direct-source green coffee relationships are reshaping buyer equipment specifications across the Emirates. Roasteries controlling bean-to-cup supply chains prioritize precision thermal systems that protect origin character. This procurement pattern concentrates most visibly among Dubai-based operators with Ethiopian and Colombian direct-trade contracts.
United Arab Emirates Coffee Roaster Market Segmentation
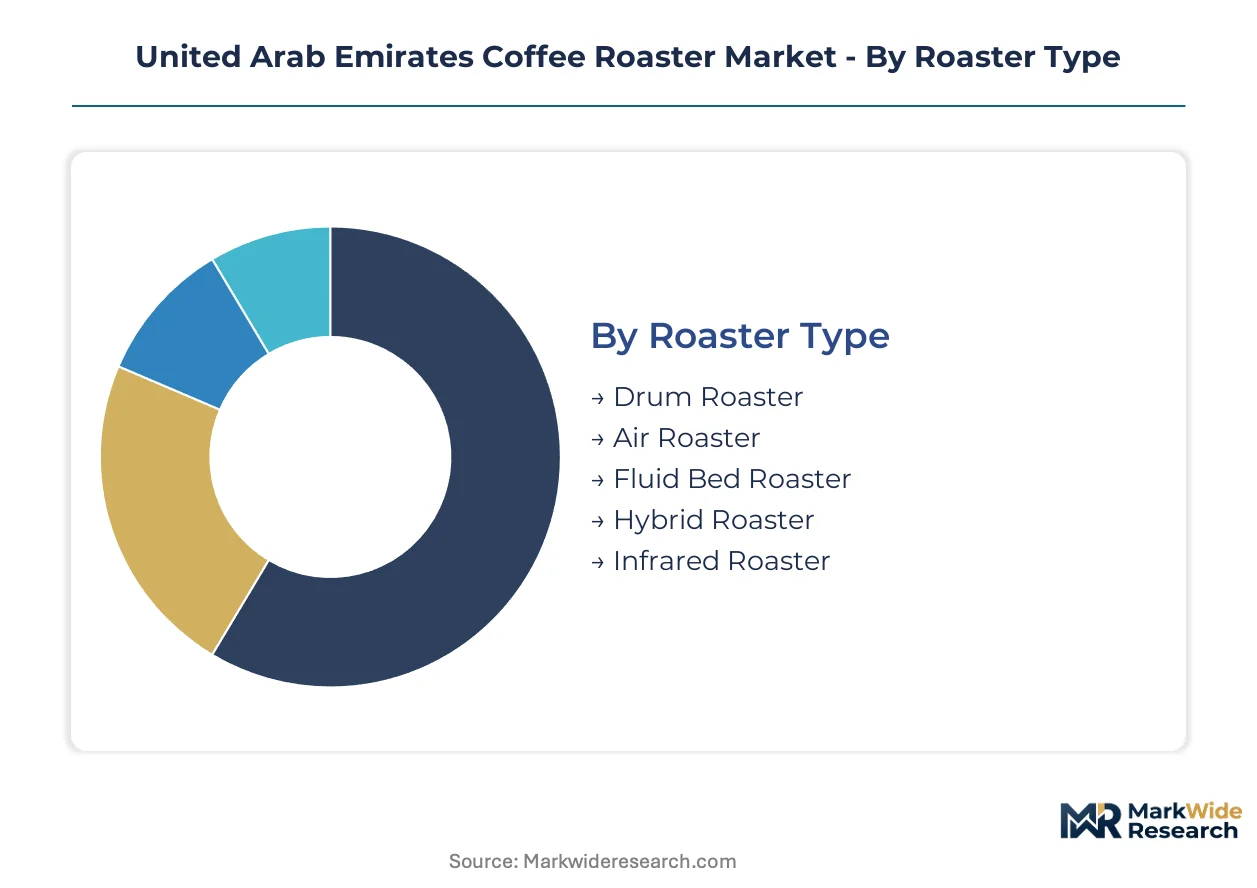
Equipment specification requirements diverge sharply across UAE roasting operations, with regulatory compliance costs and thermal precision demands creating distinct procurement tiers. Understanding these segment boundaries clarifies why certain configurations dominate Dubai's specialty corridor while others serve commodity-scale exporters.
Roaster Type:
MOHAP's food-grade stainless steel mandates and ESMA electrical safety certifications filter supplier eligibility differently across thermal transfer mechanisms, elevating capital barriers for certain configurations.
- Drum Roaster:Conduction-dominant systems with rotating steel cylinders provide thermal uniformity through direct bean-to-surface contact. Dubai's established café clusters favor these systems for profile repeatability, though MOHAP's stainless steel chamber requirements inflate fabrication costs for imported units.
- Air Roaster:Convection-driven thermal transfer suspends beans in heated air streams, enabling rapid roast development and cleaner cup profiles. Abu Dhabi's emerging specialty operators adopt these for reduced batch-to-batch variance without expatriate technician dependency.
- Fluid Bed Roaster:High-velocity hot air creates bean suspension with minimal mechanical agitation.
- Hybrid Roaster:Combined conduction-convection systems balance development speed with thermal control.
- Infrared Roaster:Radiant heat transfer enables precise surface temperature management for light roast preservation.
Established volume favors Drum Roaster; emerging adoption favors Air Roaster.
Capacity:
Batch size procurement patterns correlate with real estate costs and throughput requirements across Dubai's industrial zones versus Sharjah's peripheral manufacturing corridors.
- Small Batch:Systems processing under 15 kilograms per batch occupy minimal floor space and enable rapid product iteration. Dubai Design District micro-roasteries concentrate procurement here, absorbing premium pricing through equipment financing structures that amortize costs across high-margin retail operations.
- Commercial Scale:Mid-capacity configurations balance labor efficiency with product freshness mandates. Foodservice distributors across Abu Dhabi's hospitality corridor deploy these for centralized production serving multiple outlet locations under single MOHAP facility licenses.
- Medium Batch:Intermediate capacity serving transitioning operations between artisanal and volume production.
- Large Batch:Higher throughput systems for established roasteries with stable demand profiles.
- Industrial Scale:Continuous-flow configurations for export-oriented commodity processors.
Procurement concentrates heaviest in Small Batch for new entrants; Commercial Scale dominates replacement cycles among expanding operators.
Application:
End-use thermal precision requirements shape equipment specification divergence, with third-wave cupping standards imposing stricter profiling tolerances than commodity export or institutional foodservice.
- Specialty Coffee Shops:In-house roasting operations demand data-logging precision with Maillard reaction optimization software. Dubai's Al Quoz cluster drives specifications here, with operators prioritizing cloud-connected thermal monitoring over hardware acquisition cost.
- Coffee Exporters:Green bean processors require gentle, consistent roasting for sample preparation and quality verification. Jebel Ali Free Zone consolidates this demand, with logistics proximity reducing green coffee inventory carrying costs.
- Cafes:Smaller footprint operations with limited roasting ambition or outsourced bean supply.
- Foodservice Providers:Institutional kitchens prioritizing throughput over origin character preservation.
- Hospitality Venues:Hotel and resort operations with seasonal demand fluctuation and brand differentiation requirements.
Specialty Coffee Shops absorb the steepest price premiums; Coffee Exporters represent the most price-elastic demand segment.
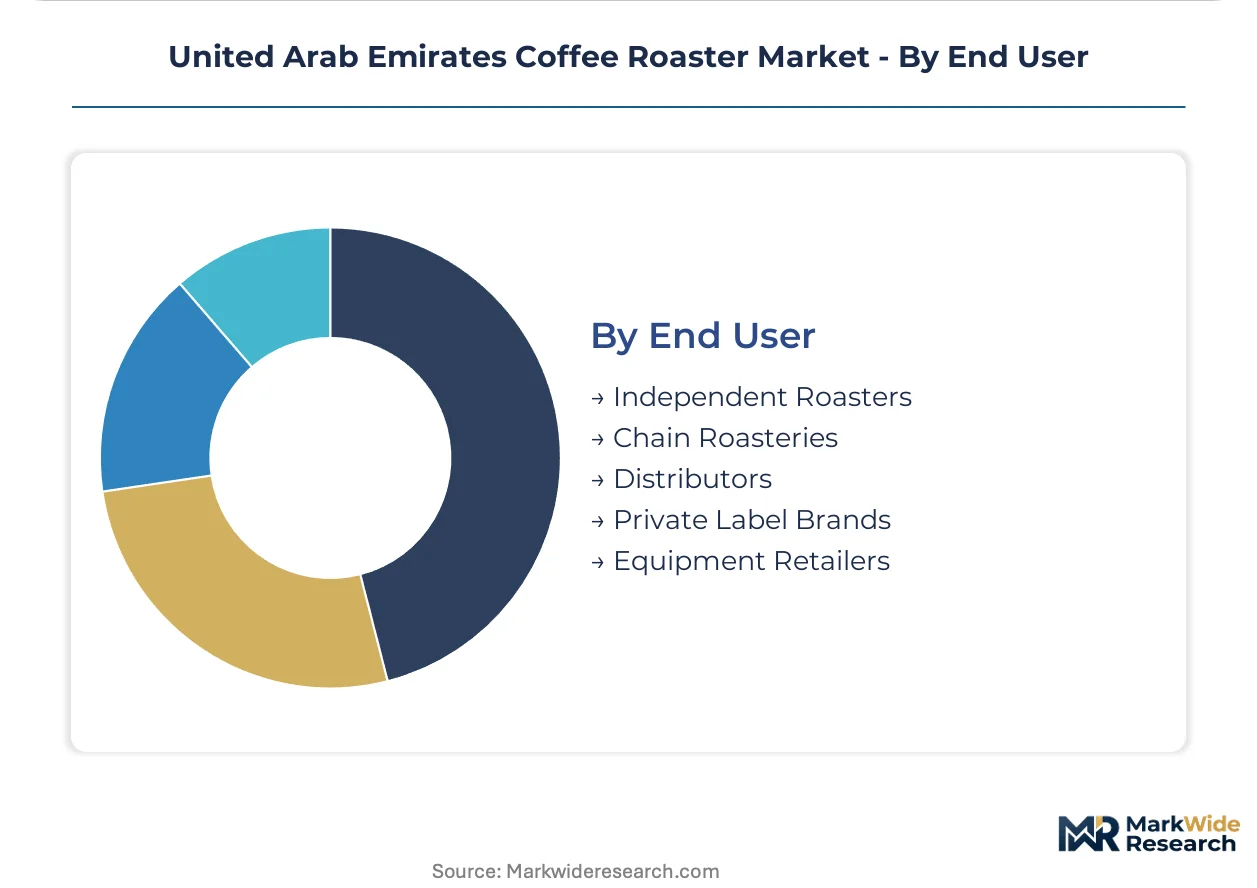
End User:
Buyer organizational structure determines financing access, technical service expectations, and multi-unit procurement leverage across the Emirates.
- Independent Roasters:Owner-operated facilities with direct green coffee sourcing relationships prioritize precision thermal systems protecting origin character. These operators cluster in Dubai's direct-trade ecosystem, absorbing ESMA-compliant equipment premiums through extended payment terms.
- Chain Roasteries:Multi-location operators standardize equipment platforms for profile consistency and maintenance efficiency. Their procurement scale enables vendor negotiation leverage unavailable to standalone competitors.
- Distributors:Third-party logistics providers with toll-roasting service models.
- Private Label Brands:Retailers outsourcing production with strict specification control.
- Equipment Retailers:Resellers and demonstration facility operators serving trial and training demand.
Independent Roasters drive premium specification adoption; Chain Roasteries concentrate volume procurement leverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment deployment patterns across the Emirates diverge sharply between Dubai's third-wave café density and Abu Dhabi's hospitality-driven procurement cycles. Sharjah's industrial zones absorb volume-oriented configurations, while Northern Emirates concentrate emerging micro-roastery entrants seeking lower real estate costs.
Dubai
Specialty coffee shops in Al Quoz and Dubai Design District drive premium equipment specifications for small-batch precision roasters. MOHAP's stainless steel contact surface mandates elevate fabrication costs for all imported machinery entering this cluster. Third-wave café density here exceeds other Gulf cities, compressing replacement cycles toward data-logging thermal systems.
Abu Dhabi
Hospitality venues and institutional foodservice providers concentrate demand for commercial-scale roasting configurations with centralized production capacity. The emirate's lower third-wave café density presents whitespace for equipment deployment ahead of demand maturation. Yas Island and Saadiyat hospitality corridors prioritize throughput over origin character preservation.
Sharjah
Industrial zone manufacturers and toll-roasting distributors favor medium-batch systems balancing labor efficiency with multi-outlet service capability. Peripheral real estate costs attract volume-oriented operators excluded from Dubai's premium locations. Jebel Ali Free Zone proximity enables green coffee logistics integration for export-oriented processors.
Northern Emirates
Ras Al Khaimah and Fujairah host emerging independent roasters seeking lower barrier entry points outside Dubai's competitive cluster. These operators prioritize financing-accessible equipment configurations over precision thermal specifications. Direct-source green coffee relationships remain less developed here, constraining premium equipment adoption.
United Arab Emirates Coffee Roaster Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with market structure reflecting the tension between café-operators with captive roasting demand and independent equipment fabricators serving distributed buyers. The vendor base separates into three strategic archetypes: vertically integrated café-roastery hybrids, standalone precision equipment specialists, and regional toll-roasting service providers. Competitive moves concentrate on training academy establishment to address technician scarcity, and direct-source green coffee contracting to secure throughput commitment for precision equipment owners.
Within the integrated café-roastery tier, BKRY anchors its position through Dubai-based training infrastructure addressing GCC-wide operator shortages. Five Elephant Roastery and The Espresso Lab exemplify precision equipment adopters leveraging direct-trade relationships to sustain consistent throughput on thermal profiling systems. These operators occupy positions where bean-to-cup control justifies premium capital deployment on data-logging configurations.
| Leading Market Players |
|---|
| BKRY |
| Five Elephant Roastery |
| The Espresso Lab |
| Orphans Coffee Roasters |
| Wild & Coffee Roasters |
| Cypher Urban Roastery |
| NTL Coffee Roasters |
| Guardian Coffee Roasters |
| Seed Coffee Roasters |
| Others |
Pricing and Supply Chain Analysis
Ninety-day green coffee inventory cycles anchor working capital intensity across UAE roasting operations, concentrating pricing power with direct-source importers while compressing margins for spot-market dependent buyers. This inventory-lead time structure elevates the strategic value of Ethiopian and Colombian origin contracts that stabilize input costs against Arabica futures volatility.
Pricing Analysis
Long-term equipment financing contracts dominate procurement for precision roasting systems, with ESMA-certified suppliers commanding premium positioning through bundled technical service agreements. Price differentiation hinges on thermal profiling software sophistication and MOHAP stainless steel compliance grade, with independent roasters showing highest sensitivity to upfront capital outlay while chain operators absorb premiums for standardization benefits. Cost compression in mid-tier drum configurations is intensifying because European and Asian manufacturers compete for Dubai Design District micro-roastery contracts.
Supply Chain Analysis
Inventory lead times for precision roasting systems extend 16-20 weeks from German, Italian, and Turkish fabrication facilities, constraining rapid capacity expansion for UAE specialty operators. Equipment supply draws from European thermal engineering specialists and East Asian electrical component manufacturers, with single-source vulnerability concentrated in proprietary software licensing for data-logging platforms. Distribution runs through Jebel Ali Free Zone consolidation hubs serving Dubai and Abu Dhabi café clusters, with Sharjah industrial zones absorbing volume-oriented configurations through peripheral logistics channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UAE coffee roaster market represents a high-growth disruption as ESMA energy efficiency mandates and MOHAP food-grade certification requirements accelerate equipment replacement cycles toward precision-enabled configurations.
For Market Incumbents: Compound defensive positioning through Dubai-based training academy expansion that addresses GCC-wide roasting technician scarcity, while securing exclusive distribution rights for European thermal profiling software to lock out Asian competitors. Capacity addition in Abu Dhabi's emerging hospitality corridor captures whitespace ahead of demand maturation, offsetting margin pressure from Al Quoz cluster saturation. For New Entrants and Emerging Players: After-sales technical service gaps in Northern Emirates present immediate white-space opportunity, with Ras Al Khaimah and Fujairah independent roasters underserved by incumbent field engineering coverage. Financing-accessible equipment leasing models penetrate this price-sensitive segment most effectively, bypassing Dubai's competitive density where established operators dominate direct-source green coffee relationships. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across data-logging precision roaster segments as software development costs displace pure hardware fabrication economics. Acquisition targets with captive training infrastructure and direct-trade green coffee contracts demonstrate strongest long-term viability through the projection horizon. The signal to monitor is GSO harmonization progress unifying technical specifications across Saudi Arabia, Kuwait, and the Emirates, which would reshape multi-country network procurement economics.| Strategic Initiative | Industry Significance |
|---|---|
| Training Academy Establishment | BKRY's Dubai infrastructure addresses GCC technician scarcity constraining competitor expansion. |
| Direct-Source Green Coffee Contracting | Five Elephant Roastery's Ethiopian relationships secure throughput commitment for precision equipment utilization. |
| IoT-Enabled Predictive Maintenance Platform | Sensor-integrated roasting systems reduce dependency on scarce on-site technical expertise. |
| ESMA Certification Pre-Compliance Investment | Early electrical safety validation accelerates market entry against filtered non-compliant imports. |
| Abu Dhabi Specialty Corridor Pre-Positioning | Lower third-wave café density presents equipment deployment whitespace ahead of demand maturation. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with roasting equipment procurement managers, café operations directors, and MOHAP regulatory compliance officers across Dubai, Abu Dhabi, and Sharjah; and secondary validation through ESMA certification databases, UAE customs import records, and Gulf Standardization Organization technical harmonization documents. Bottom-up equipment shipment analysis triangulated against top-down specialty coffee outlet expansion tracking.
Across the analysis window, the forecasting framework modeled volume and value trajectories through segmentation across roaster type, capacity tier, application, and end-user structure, with CAGRs derived from historical replacement cycle compression and regulatory mandate acceleration. Green coffee price volatility indices and technician availability metrics served as industry-specific forecast sensitivity inputs.
Underlying assumptions cover sustained ESMA enforcement intensity and stable Arabica futures trading ranges, with deviation risk concentrated in GSO harmonization timeline acceleration or MOHAP stainless steel mandate expansion. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coffee
Saudi Arabia Coffee Roaster Market
Coffee
Reusable Coffee Cup Market
Coffee
Take Out Coffee Market
Coffee
Coffee Grinder Market
Coffee
Canned Coffee Market
Coffee
Office Coffee Service (OCS) Market
Coffee
Out-Of-Home Coffee Market
Coffee
Coffee Pods and Capsules Market
Coffee
Espresso Powder Market
Coffee
Italy Coffee Market
Coffee
Coffee Roaster Machine Market
Coffee
Green Coffee Bean Extract Market
Coffee
North America Instant Coffee Market
Coffee
Coffee Pods Market
Coffee
Asia Pacific Coffee Market
Coffee
Portable Espresso Machines Market