
 Metabolism Drugs Market | 2026-2036
Metabolism Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Metabolism Drugs Market Foresight
Peptide-based active pharmaceutical ingredients are displacing small-molecule substrates in next-generation metabolic therapy manufacturing, which is realigning cost structures across the supply base. Novo Nordisk leverages its captive fermentation capacity to secure bulk peptide supply chains. Eli Lilly and Company anchors North American injectable capacity through dedicated biologics manufacturing campuses. Sanofi competes in oral-delivery innovation through sustained-release formulation platforms.
Metabolism drugs comprise pharmaceutical agents that modulate biochemical pathways governing energy homeostasis, including insulin secretion, glucagon suppression, lipolysis regulation, and hepatic glucose output, typically formulated as recombinant proteins, synthetic peptides, or small-molecule enzyme inhibitors requiring cold-chain distribution at two to eight degrees Celsius. These agents serve to restore glycemic control, reduce adipose tissue mass, or correct dyslipidemia in patients with endocrine or metabolic disorders. The therapy area dimension shows diabetes retaining the largest patient-treatment volume while obesity commands the fastest prescriber-uptake trajectory and premium reimbursement positioning. GLP-1 agonists dominate the product type landscape, though SGLT-2 inhibitors sustain growth in combination-therapy protocols across hospital and homecare channels.
The FDA oversees New Drug Application reviews for metabolic indications through its Division of Metabolism and Endocrinology Products, while the EMA's Committee for Medicinal Products for Human Use evaluates centralized marketing authorization requests for obesity and diabetes therapies across EU member states. Both agencies are tightening cardiovascular outcomes study requirements for novel weight-loss agents, which extends development timelines and elevates clinical trial investment thresholds for market entrants. Stakeholders must monitor evolving prior-authorization criteria from pharmacy benefit managers and national health technology assessment bodies to anticipate access-driven revenue volatility.
Market Dynamics
Injectable GLP-1 therapies are concentrating demand among North American hospital systems, forcing wholesale supply chain reconfiguration toward cold-chain biologics infrastructure and away from small-molecule distribution networks.
Growth Catalysts
- Medicare reimbursement expansion:United States federal coverage for weight-management pharmaceuticals removes prior-authorization friction for prescriber adoption in outpatient settings.
- Peptide fermentation capacity:Captive bioreactor investments by incumbent manufacturers secure bulk active pharmaceutical ingredient supply against substrate volatility.
- EMA obesity-treatment frameworks:Evolving centralized marketing authorization pathways accelerate patient access across EU member states for novel metabolic agents.
Market Restraints
- Cold-chain distribution cost:Two-to-eight-degree Celsius logistics requirements impose infrastructure capex penalties on regional distributors lacking biologics-handling certification.
- Cardiovascular outcomes study mandates:FDA and EMA tightening of pre-approval trial requirements extends development timelines and elevates clinical investment thresholds for market entrants.
- Injectable formulation dominance:Patient needle aversion and administration training burdens limit uptake in homecare channels compared to oral alternatives.
Strategic Opportunities
- Oral-delivery innovation:Sustained-release formulation platforms bypass injection requirements and expand addressable populations in pharmacy retail channels.
- Combination-therapy protocols:SGLT-2 inhibitor co-formulation with GLP-1 agonists creates differentiated positioning in hospital formularies seeking glycemic-adiposity dual control.
- Pharmacy benefit manager integration:Direct contracting with United States PBMs secures tiered formulary placement ahead of competitive therapeutic alternatives.
Industry Challenges
- Bioprocess engineering talent scarcity:Recombinant protein purification expertise concentrates among a limited pool of specialists, constraining manufacturing scale-up velocity.
- Prior-authorization administrative burden:Evolving HTA body criteria across EU member states create reimbursement uncertainty that fragments revenue forecasting reliability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metabolism Drugs Market |
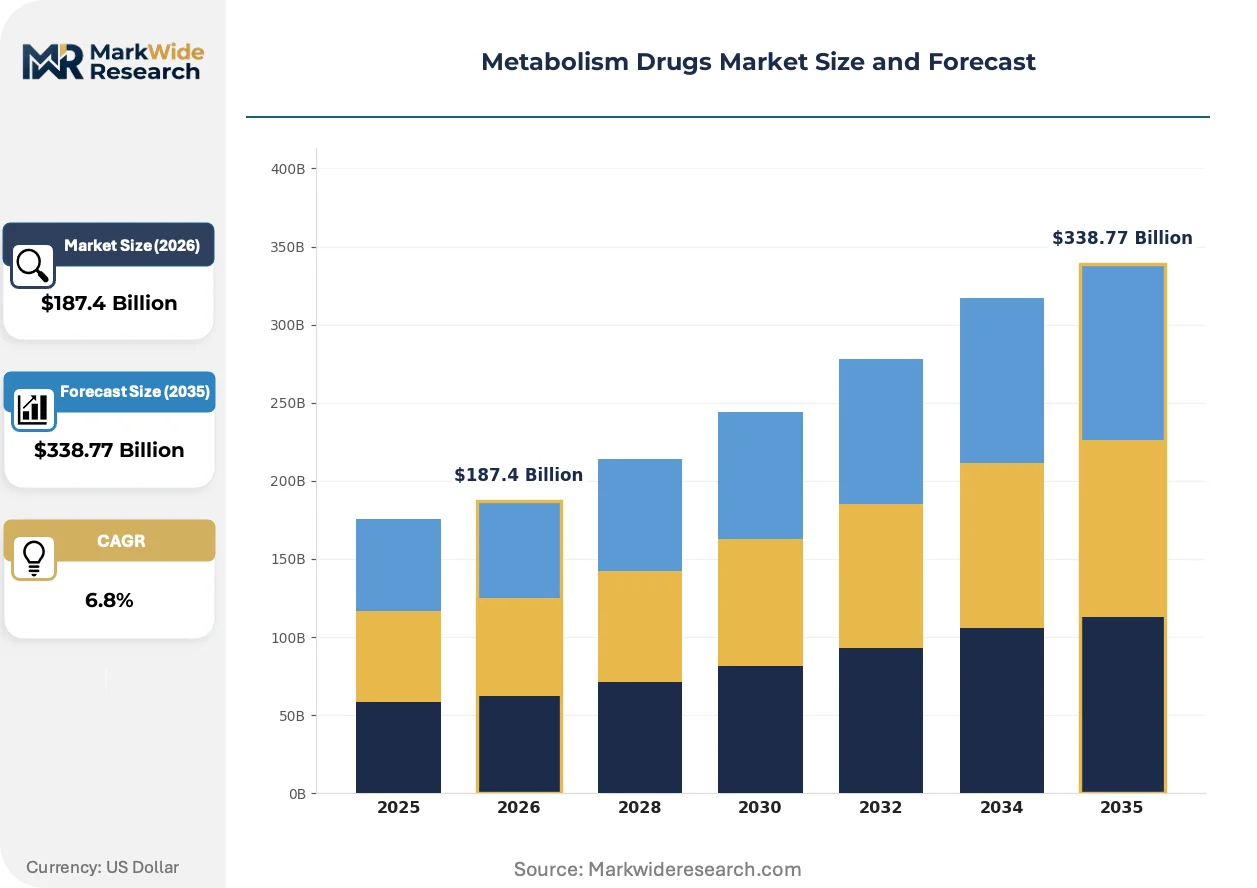
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $338.77 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulin, GLP-1 Agonists, SGLT-2 Inhibitors, Amylin Analogs Delivery Mode: Injectable, Oral, Transdermal, Inhalation End User: Hospitals, Clinics, Homecare, Pharmacies Therapy Area: Diabetes, Obesity, Hyperlipidemia, Metabolic Syndrome |
| Companies Covered | Novo Nordisk, Eli Lilly and Company, Merck & Co., Inc., Sanofi, AstraZeneca, Pfizer, Novartis, Boehringer Ingelheim, Johnson & Johnson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metabolism Drugs Market Shifts & Advancements
Metabolic therapy development is pivoting toward patient-administered delivery systems and real-world evidence generation, compressing traditional clinical trial timelines while expanding prescriber autonomy outside specialist settings.
Continuous glucose monitoring integration with automated insulin dosing is decentralizing glycemic management from endocrinology clinics to primary care and home settings. Family medicine practices across the United States are adopting sensor-augmented pump therapy at accelerating velocity. This shift is decentralizing patient volume away from academic medical centers toward community-based delivery networks.
The FDA's Division of Metabolism and Endocrinology Products is tightening cardiovascular safety documentation requirements for novel weight-loss agents. Pre-market trial investment thresholds have risen substantially for developmental-stage sponsors. Obesity-focused biologics face the steepest compliance burden, with several candidates delaying NDA submission to accumulate outcomes data.
Hospital procurement committees are unbundling metabolic drug purchasing from traditional group purchasing organization contracts. Individual health systems negotiate direct manufacturer agreements based on real-world utilization metrics rather than volume-tiered rebates. This pattern is most visible in United States integrated delivery networks seeking outcomes-based accountability clauses.
Metabolism Drugs Market Segmentation
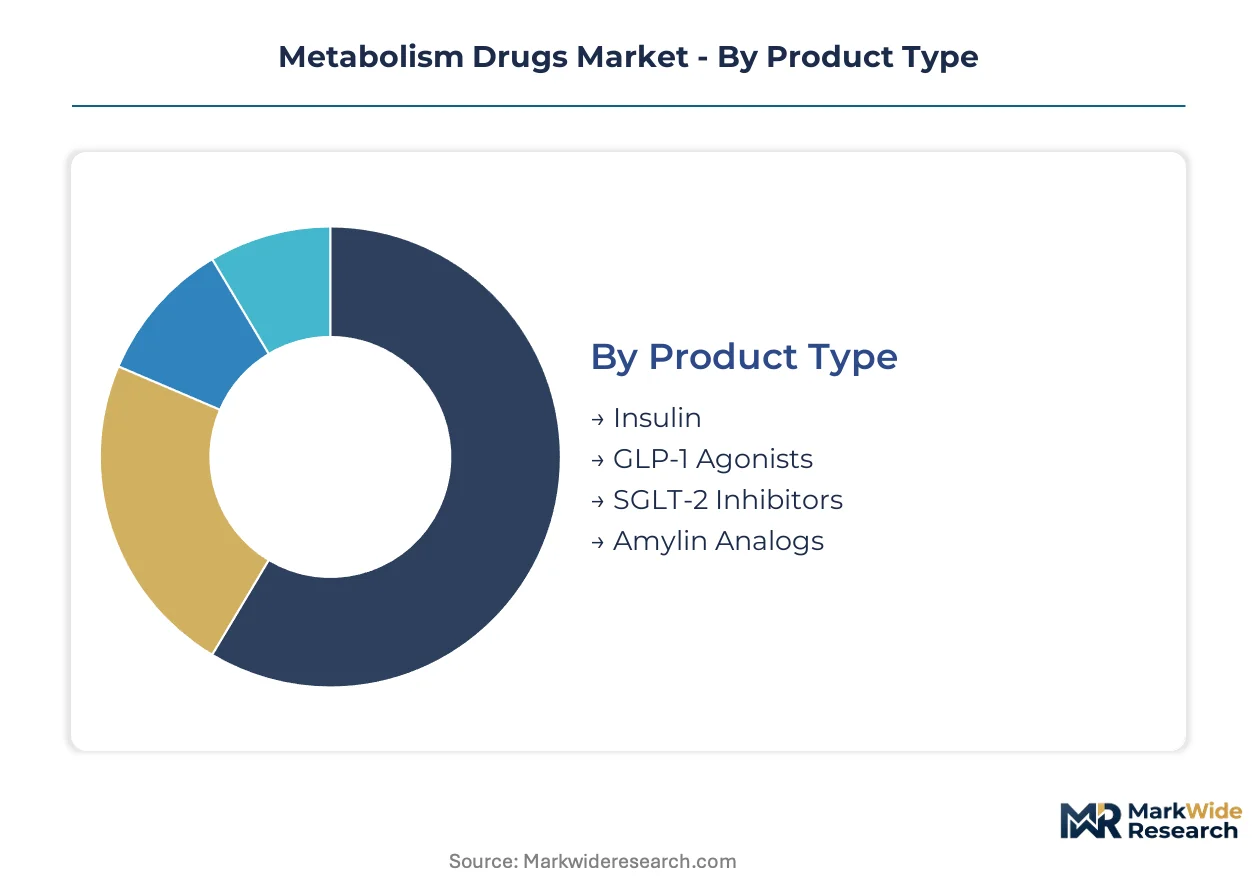
Segmentation in the metabolism drugs market determines manufacturing scale, distribution infrastructure, and reimbursement pathways. Each dimension—molecular class, delivery technology, care setting, and therapeutic indication—carries distinct cold-chain requirements, prescriber training burdens, and patient adherence profiles that reshape competitive positioning.
Product Type:
Standalone peptide therapies dominate hospital formularies, while small-molecule and combination agents embed more readily into retail pharmacy workflows.
- Insulin:Recombinant human and analog insulins require continuous cold-chain handling from fermentation through patient administration. Demand concentrates in United States Medicare channels where long-acting formulations anchor basal-bolus protocols. Biosimilar price compression is accelerating prescriber switching toward lower-cost alternatives.
- GLP-1 Agonists:Synthetic peptides modulating incretin pathways command premium reimbursement for obesity indications. United States integrated delivery networks are expanding formulary access as Medicare coverage removes prior-authorization barriers. Manufacturing capacity constraints limit supply expansion velocity.
- SGLT-2 Inhibitors:Oral small-molecule agents for glycemic control with cardiovascular benefit claims embed into combination-therapy regimens.
- Amylin Analogs:Adjunctive peptide therapies for postprandial glucose management serve niche populations in specialized endocrinology practices.
Insulin leads volumes today; GLP-1 Agonists is gaining share fastest.
Delivery Mode:
Cost tiers separate capital-intensive biologics infrastructure from standard pharmaceutical distribution, with patient convenience premiums widening price spreads.
- Injectable:Subcutaneous delivery systems for peptides and insulin analogs mandate two-to-eight-degree Celsius logistics and auto-injector device compatibility. Hospital systems across Germany and France are consolidating procurement around pre-filled pen formats. Cold-chain capex requirements disadvantage regional distributors lacking biologics certification.
- Oral:Small-molecule tablets and emerging peptide formulations bypass injection barriers and expand addressable populations in pharmacy retail. Sustained-release platform investments by French and Swiss manufacturers are compressing bioavailability gaps with parenteral alternatives.
- Transdermal:Patch-based delivery remains experimental for metabolic indications with limited commercial penetration.
- Inhalation:Pulmonary insulin delivery systems have exited major markets following clinical adoption failures.
Injectable formats capture the highest patient-treatment volumes; Oral delivery is expanding most quickly.
End User:
Customer type determines procurement authority, with hospital committees wielding formulary control while homecare channels prioritize patient self-administration convenience.
- Hospitals:Acute care institutions manage inpatient glycemic emergencies and initiate complex insulin regimens. Procurement committees in United States academic medical centers are unbundling metabolic drug purchasing from group purchasing organization contracts.
- Clinics:Outpatient endocrinology and primary care practices handle dose titration and therapeutic monitoring. Community-based networks in the United States are absorbing patient volume decentralizing from tertiary centers.
- Homecare:Self-administered injectable therapies require patient training programs and remote monitoring infrastructure.
- Pharmacies:Retail dispensing channels favor oral formulations with standard storage requirements and lower counseling burdens.
Hospitals anchor prescription volumes today; Homecare channels are climbing the fastest.
Therapy Area:
Maturity gradients separate decades-old diabetes management protocols from emerging obesity treatment frameworks still negotiating reimbursement pathways.
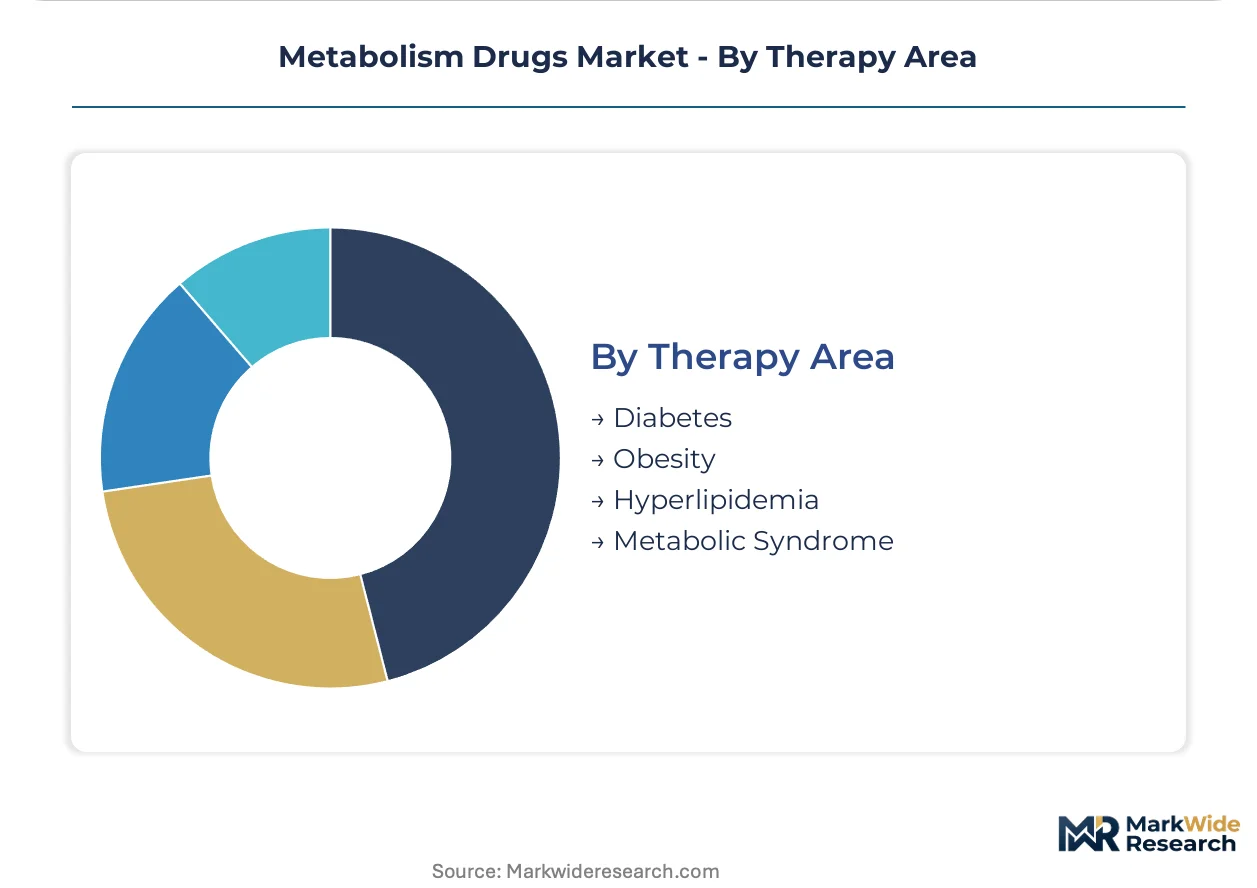
- Diabetes:Glycemic control indications encompass Type 1 and Type 2 disease management with established HbA1c monitoring infrastructure. Patient-treatment volumes concentrate in United States Medicare and European statutory health insurance systems with mature quality metrics.
- Obesity:Weight-management indications for GLP-1 agonists are reshaping prescriber behavior as cardiovascular outcomes data accumulates. United States reimbursement expansion is accelerating adoption ahead of European health technology assessment harmonization.
- Hyperlipidemia:Dyslipidemia correction through metabolic pathway modulation competes with established statin therapies.
- Metabolic Syndrome:Clustered risk factor management spans multiple drug classes without unified regulatory or reimbursement frameworks.
Diabetes leads patient-treatment volumes today; Obesity is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Research Triangle Park concentration in North Carolina anchors North American peptide manufacturing infrastructure for metabolic therapies. Federal reimbursement policy and biologics capacity investments are redrawing competitive boundaries across national markets.
United States
Medicare coverage expansion for weight-management pharmaceuticals removes prior-authorization barriers in outpatient settings. The FDA's Division of Metabolism and Endocrinology Products tightened cardiovascular outcomes documentation requirements for novel obesity agents. Indianapolis-based manufacturing campuses anchor North American injectable capacity for GLP-1 agonist supply.
Germany
Statutory health insurance systems drive demand for biosimilar insulin alternatives in diabetes management. The EMA's Committee for Medicinal Products for Human Use evaluates centralized marketing authorizations for obesity therapies across EU member states. The Rhine-Main biotech cluster around Frankfurt hosts fermentation capacity investments for recombinant peptide production.
Switzerland
Premium pricing for innovative metabolic agents sustains revenue margins despite smaller patient volumes. Swissmedic maintains rigorous pharmacovigilance standards for biologics registration that exceed baseline EU requirements. The Basel pharmaceutical corridor concentrates formulation expertise for sustained-release delivery platforms.
Japan
Aging demographics expand Type 2 diabetes treatment volumes through national health insurance channels. The PMDA's Sakigake designation system accelerates review timelines for metabolic therapies addressing unmet medical needs. The Kansai region around Osaka hosts contract manufacturing organizations specializing in recombinant protein purification.
India
Domestic biosimilar insulin production scales through PLI scheme incentives for active pharmaceutical ingredient manufacturing. The CDSCO streamlined approval pathways for biologics referencing European regulatory standards. Hyderabad's Genome Valley cluster attracts fermentation infrastructure investments from multinational metabolic drug sponsors.
Metabolism Drugs Market Competitive Landscape
Global majors compete with regional champions across manufacturing scale and distribution reach. The market structure concentrates around three to five integrated pharmaceutical conglomerates controlling captive peptide supply chains. Danish and American conglomerates exemplify vertical integration archetypes, while European and Swiss competitors occupy formulation-specialist positions. Capacity expansion in North American biologics campuses and strategic partnerships for oral-delivery technology licensing represent dominant competitive vectors.
Among the integrated pharmaceutical conglomerates, Novo Nordisk and Eli Lilly and Company exemplify the vertical-integration archetype through captive fermentation capacity and dedicated biologics manufacturing infrastructure. Sanofi occupies a distinct position emphasizing oral-delivery innovation through sustained-release formulation platforms. These three anchors represent divergent strategic postures within the metabolic therapy landscape.
| Leading Market Players |
|---|
| Novo Nordisk |
| Eli Lilly and Company |
| Merck & Co., Inc. |
| Sanofi |
| AstraZeneca |
| Pfizer |
| Novartis |
| Boehringer Ingelheim |
| Johnson & Johnson |
| Others |
Supply & Pricing Matrix
Medicare reimbursement expansion for weight-management pharmaceuticals in the United States is consolidating purchasing power among integrated delivery networks, forcing manufacturers to absorb cold-chain logistics costs while maintaining formulary access through outcomes-based contracting. This demand-side concentration compresses margins on injectable peptide therapies while rewarding suppliers with captive fermentation capacity.
Pricing Analysis
Input-cost pass-through from peptide fermentation substrate volatility anchors pricing dynamics, with recombinant protein purification expenses comprising the dominant cost tier. Three-tier pricing structure across premium, standard, and economy levels separates originator GLP-1 agonists from biosimilar insulins and small-molecule SGLT-2 inhibitors. Pricing pressure stems from biosimilar price compression in United States Medicare channels, where formulary directors extract volume-tiered rebates. Hospital procurement committees exhibit highest price sensitivity due to unbundled purchasing from group purchasing organizations, while specialty endocrinology practices retain lowest sensitivity for premium obesity agents.
Supply Chain Analysis
Domestic-content mandates under India's PLI scheme for active pharmaceutical ingredient manufacturing are reshaping sourcing patterns for biosimilar insulin production. Supply concentrates in Denmark and the United States for GLP-1 agonist bulk peptides, with India and China anchoring small-molecule substrate supply. Raw material dependencies center on recombinant yeast strains, chromatography resins, and pharmaceutical-grade excipients. Single-source vulnerability concentrates in specialized bioreactor engineering talent pools. Distribution runs through cold-chain certified logistics networks serving hospital systems and specialty pharmacy channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The metabolism drugs market functions as a stable compounder anchored by chronic disease prevalence expansion and durable reimbursement expansion for obesity therapeutics. Medicare coverage removal of prior-authorization barriers creates predictable demand visibility across the analysis window.
For Market Incumbents: Deploy captive fermentation capacity expansion as the primary defensive lever. Secure bulk peptide supply chains through backward integration into bioreactor infrastructure in the Research Triangle Park and Indianapolis manufacturing corridors. Counter biosimilar price compression by locking integrated delivery networks into multi-year outcomes-based contracts with real-world utilization metrics clauses. For New Entrants and Emerging Players: Capture oral-delivery formulation white space in European pharmacy retail channels where patient needle aversion limits injectable penetration. Target sustained-release platform licensing agreements with Swiss and French formulation specialists as the most penetrable entry vector. Pursue direct-to-clinic distribution models bypassing hospital formulary committee gatekeeping. For Investors and Strategic Acquirers: Asymmetric upside sits with contract manufacturing organizations possessing recombinant protein purification expertise in the Kansai and Genome Valley clusters. Long-term viability favors assets with demonstrated EMA centralized marketing authorization pathways and established cold-chain logistics certification. Watch for FDA cardiovascular outcomes study completion signals as inflection indicators for obesity agent valuation resets.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Captive bioreactor investments by Novo Nordisk and Eli Lilly secure bulk peptide supply against substrate volatility. |
| Regulatory Approval Pathway | EMA centralized marketing authorization accelerates patient access across EU member states for novel metabolic agents. |
| Licensing Agreement | Sustained-release platform partnerships enable oral-delivery innovation bypassing injection requirements in retail pharmacy. |
| Clinical Trial Advancement | Cardiovascular outcomes study accumulation satisfies FDA safety documentation requirements for obesity biologics. |
| Pipeline Diversification | SGLT-2 inhibitor co-formulation with GLP-1 agonists creates differentiated positioning in hospital formularies. |
Research Methodology
Bottom-up patient-treatment volume modeling reconciled against top-down manufacturing capacity tracking forms the analytical core of this study. Primary interviews with formulary directors, regulatory affairs leads, hospital procurement managers, and payer access specialists informed demand-side assumptions. Secondary validation drew from FDA New Drug Application filings, EMA centralized marketing authorization submissions, ClinicalTrials.gov protocol registries, and Medicare formulary databases. Cross-referencing bottom-up prescription volume estimates against top-down fermentation capacity disclosures enabled triangulation.
Historical trendline analysis of therapy area adoption curves and reimbursement expansion timelines anchored the forecast framework. Segmentation dimensions modeled encompass molecular class, delivery technology, care setting, and therapeutic indication across the projection horizon. CAGRs were derived from patient population growth trajectories, prescriber uptake velocity, and pricing elasticity assumptions specific to metabolic therapeutics. Forecast inputs incorporated cold-chain distribution cost inflation and biosimilar penetration scenarios.
Regulatory approval delays, reimbursement policy reversals, and manufacturing scale-up constraints are the dominant revision risks to the forecast envelope. Forecasts reflect documented assumptions regarding Medicare coverage durability and EMA obesity framework harmonization. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Middle East and Africa Plasma Fractionation Market
Biopharmaceuticals
In Situ Gel Drug Delivery Market
Biopharmaceuticals
Global Mono Vaccine Market
Biopharmaceuticals
Global Bruton Tyrosine Kinase (BTK) Inhibitors Market
Biopharmaceuticals
1-Step RT-PCR Kits Market
Biopharmaceuticals
Biologics Contract Development Market
Biopharmaceuticals
Antimycobacterial Drugs Market
Biopharmaceuticals
Daptomycin Market
Biopharmaceuticals
Large Macrolide Drugs Market
Biopharmaceuticals
HIV Market
Biopharmaceuticals
Global Infertility Drugs Market
Biopharmaceuticals
Rhu Albumin Market
Biopharmaceuticals
North America Insulin Pens Market
Biopharmaceuticals
Beta Interferon Market
Biopharmaceuticals
North America Biotechnology Market
Biopharmaceuticals
Plasmid DNA Manufacturing Market