
 Singapore Aerospace and Defense Market | 2026-2036
Singapore Aerospace and Defense Market Size, Share, and Industry Trends Forecast 2026-2036
Singapore Aerospace and Defense Market Analytics
Buyer concentration among Singapore government agencies is repositioning contract flows toward fewer prime vendors with multi-year sustainment obligations. ST Engineering leverages its domestic maintenance, repair and overhaul infrastructure to anchor military vehicle and naval systems support. Airbus SE competes across rotorcraft and fixed-wing platforms for Republic of Singapore Air Force requirements. Rolls-Royce plc sustains engine overhaul partnerships with SIA Engineering Company Limited for regional defense turbine servicing.
Singapore aerospace and defense encompasses the design, integration, testing and lifecycle support of military aircraft, unmanned aerial systems, guided munitions and naval combatants operating in tropical maritime environments with corrosion-resistant alloys and advanced avionics architectures. The sector serves national security objectives and regional stability partnerships through sovereign capability and foreign military sales channels. Military aircraft and naval vessels command the dominant procurement allocation under Singapore's defense budget structure, while cybersecurity technology within the avionics and simulation systems cluster attracts the fastest capability investment. Drones occupy a growing niche for maritime surveillance and littoral domain awareness missions.
Singapore's Defence Science and Technology Agency coordinates with the Civil Aviation Authority of Singapore and the Cyber Security Agency to set airworthiness, spectrum allocation and data protection standards for military-civil dual-use systems. These frameworks shape supplier qualification timelines and technology transfer protocols for foreign OEMs seeking access to Singaporean defense programs. Stakeholders must monitor MINDEF's next-generation fighter acquisition trajectory and indigenous unmanned systems development roadmap to align industrial participation strategies.
Market Dynamics
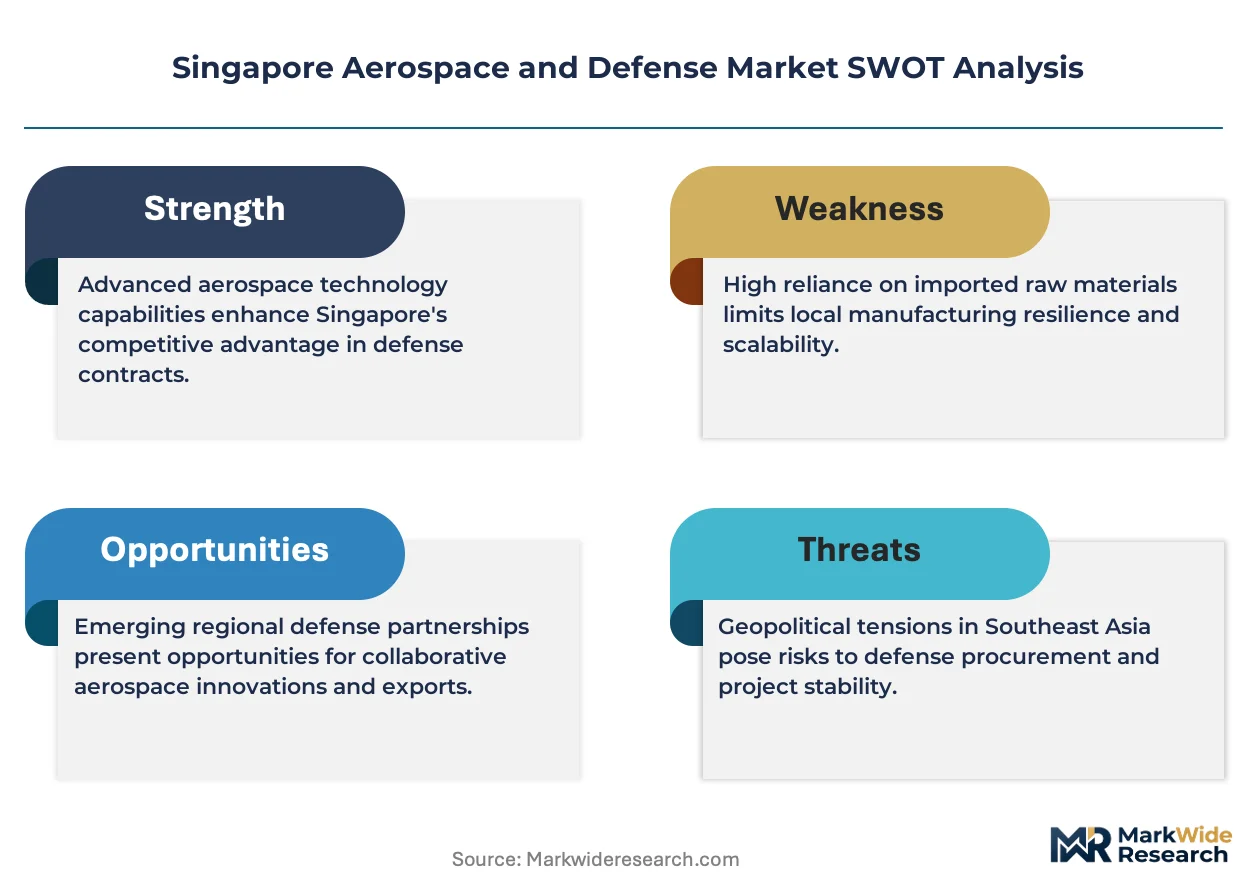
Singapore's defense procurement consolidation is concentrating contract flows toward domestic primes with multi-year sustainment obligations, compressing vendor diversity while extending platform lifecycle management horizons.
Growth Catalysts
- Digital Transformation Roadmap:MINDEF's cybersecurity capability investments are accelerating technology adoption across defense contractors for secure command-and-control architectures.
- Tropical Maritime Environment Requirements:Corrosion-resistant alloy specifications for naval combatants are sustaining specialized maintenance demand at Sembcorp Marine and Keppel shipyards.
- F-15SG Fleet Modernization:The Republic of Singapore Air Force's upgrade programs are directing engine overhaul volume toward established maintenance, repair and overhaul infrastructure.
Market Restraints
- Specialized Alloy Input Costs:Nickel-titanium shape memory alloys for tropical corrosion resistance face price volatility from concentrated Southeast Asian smelter supply.
- Foreign Military Sales Dependency:Platform acquisition remains tethered to US Defense Security Cooperation Agency approval timelines and congressional notification thresholds.
- Dual-Use Technology Transfer Friction:Singapore's Defence Science and Technology Agency imposes stringent foreign disclosure protocols that elongate OEM partnership negotiations.
Strategic Opportunities
- Maritime Surveillance Drone Deployment:Littoral domain awareness missions are expanding unmanned aerial system procurement for the Republic of Singapore Navy's coastal defense perimeter.
- Cyber-Physical Convergence:Integration of avionics systems with zero-trust network architectures is creating new qualification pathways for domestic engineering services.
- Regional Training Hub Positioning:Singapore's advanced simulation infrastructure can capture foreign military training contracts from ASEAN partner nations seeking F-16 transition programs.
Industry Challenges
- Airworthiness Certification Bottlenecks:The Civil Aviation Authority of Singapore's military-civil dual-use approval timelines create program schedule risk for modified commercial platforms.
- Legacy Platform Skill Attrition:F-16 mechanical systems expertise is concentrating among aging technician cohorts without sufficient pipeline replenishment from local polytechnic programs.
- Supply Chain Reconfiguration Costs:Semiconductor component sourcing for avionics upgrades requires non-recurring engineering investment to qualify alternative foundry sources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Singapore Aerospace and Defense Market |
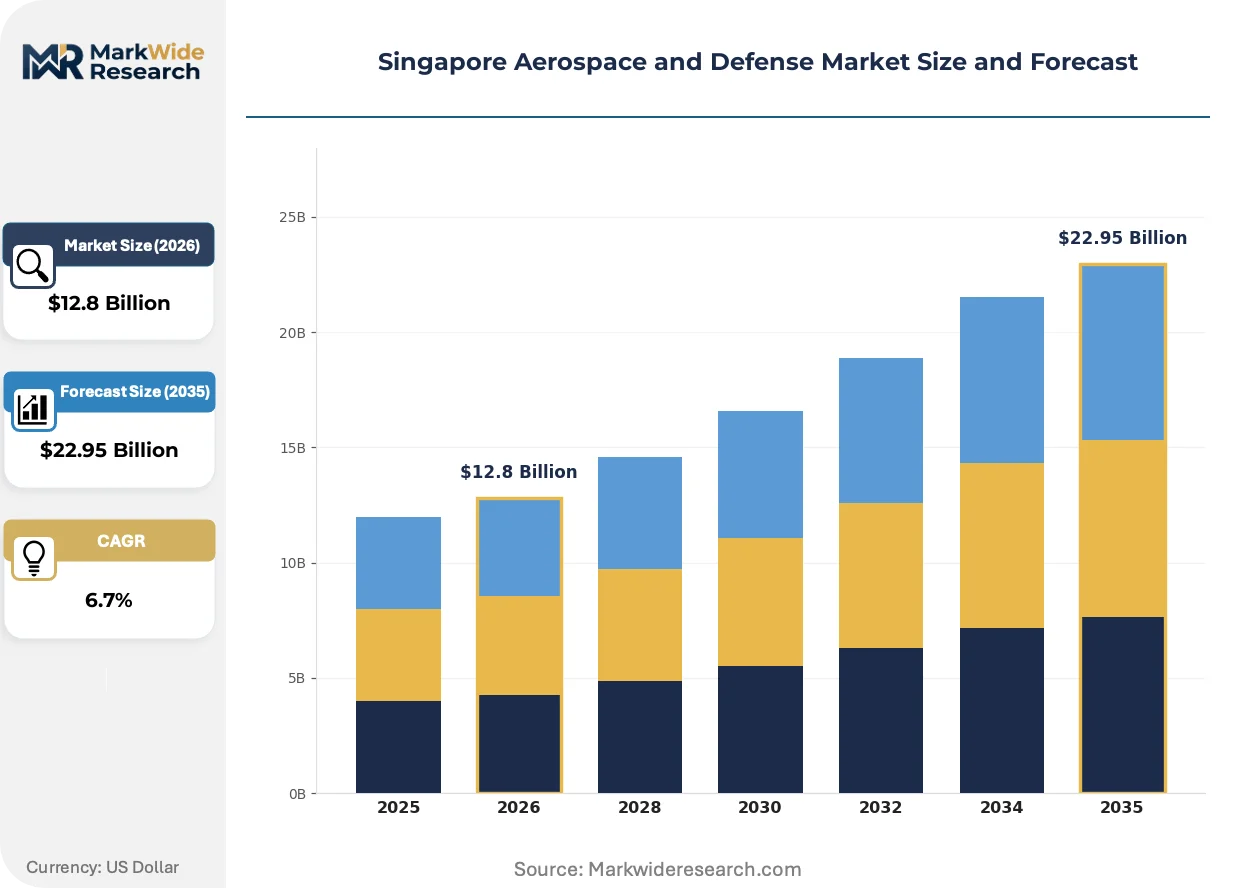
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.95 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Military Aircraft, Drones, Missiles, Naval Vessels Technology: Avionics, Robotics, Simulation Systems, Cybersecurity End User: Government Agencies, Defense Contractors, Research Institutions, OEMs Application: Surveillance, Combat Operations, Training, Maintenance Services |
| Companies Covered | RTX Corporation, Airbus SE, SIA Engineering Company Limited, Lockheed Martin Corporation, The Boeing Company, Singapore Technologies Engineering Ltd, General Electric Company, Pratt & Whitney, Rolls-Royce plc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Singapore Aerospace and Defense Market Evolving Landscape
Active electronically scanned array radar integration and sovereign unmanned systems development are compressing traditional platform upgrade cycles while expanding domestic engineering content requirements.
Artificial intelligence-enabled predictive maintenance algorithms are absorbing flight data analytics functions previously performed by scheduled inspection protocols. The Republic of Singapore Air Force is adopting these systems for F-15SG engine health monitoring on compressed implementation timelines. This capability shift is absorbing third-party diagnostic service roles into integrated platform manufacturer offerings.
Singapore's Cyber Security Agency has mandated zero-trust architecture compliance for all military-civil dual-use systems under its 2024 technology refresh guidelines. Defense contractors must demonstrate segmented network access controls to qualify for avionics integration contracts. The simulation and training systems segment is responding with air-ganged hardware-in-the-loop configurations that isolate classified mission data from commercial software environments.
Performance-based logistics contracts are displacing traditional time-and-material sustainment arrangements for major platform categories. The Republic of Singapore Navy's littoral mission vessel program is piloting availability-based contracting with domestic shipyards, transferring operational risk to contractors. This procurement evolution is most visible in naval surface combatant support, where ST Engineering Marine is consolidating subsystem vendor management under integrated performance guarantees.
Singapore Aerospace and Defense Market Segmentation
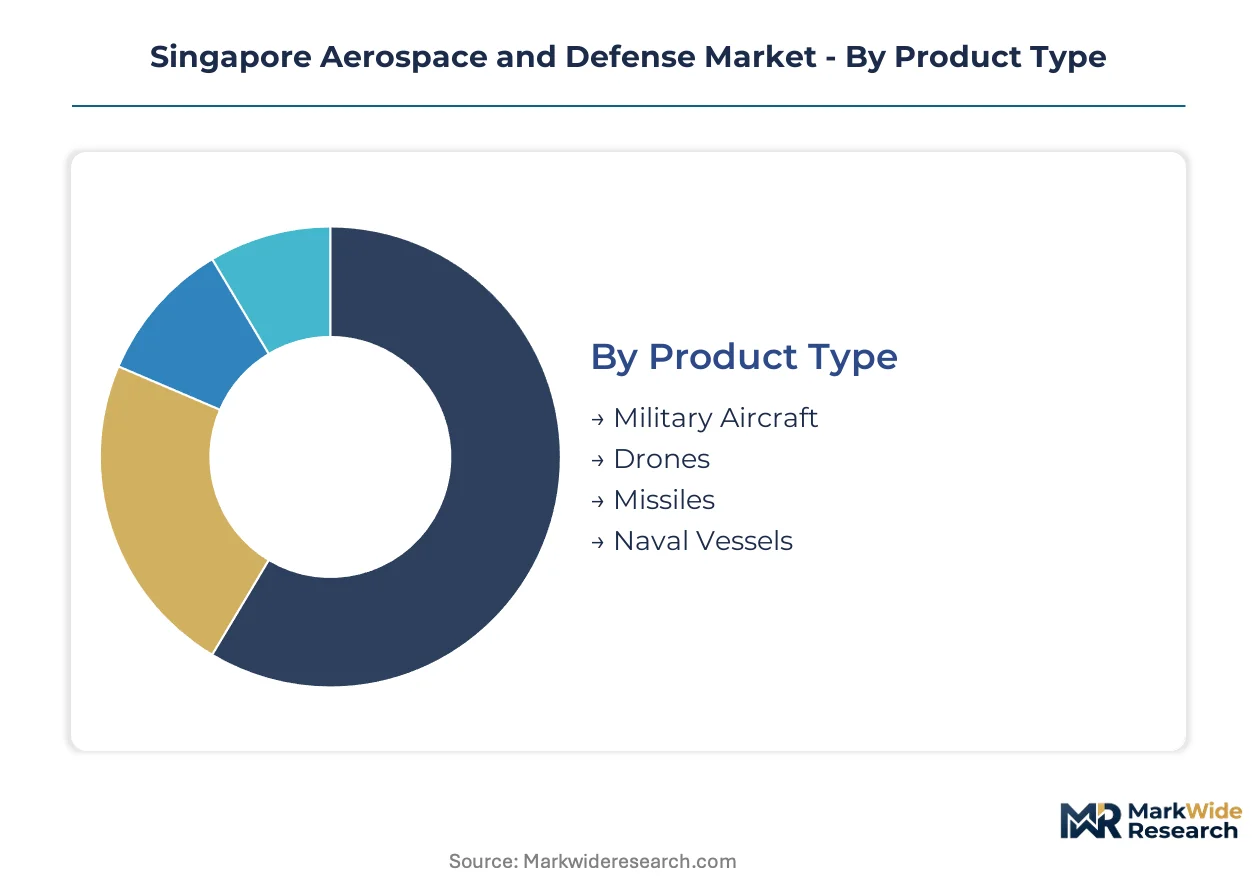
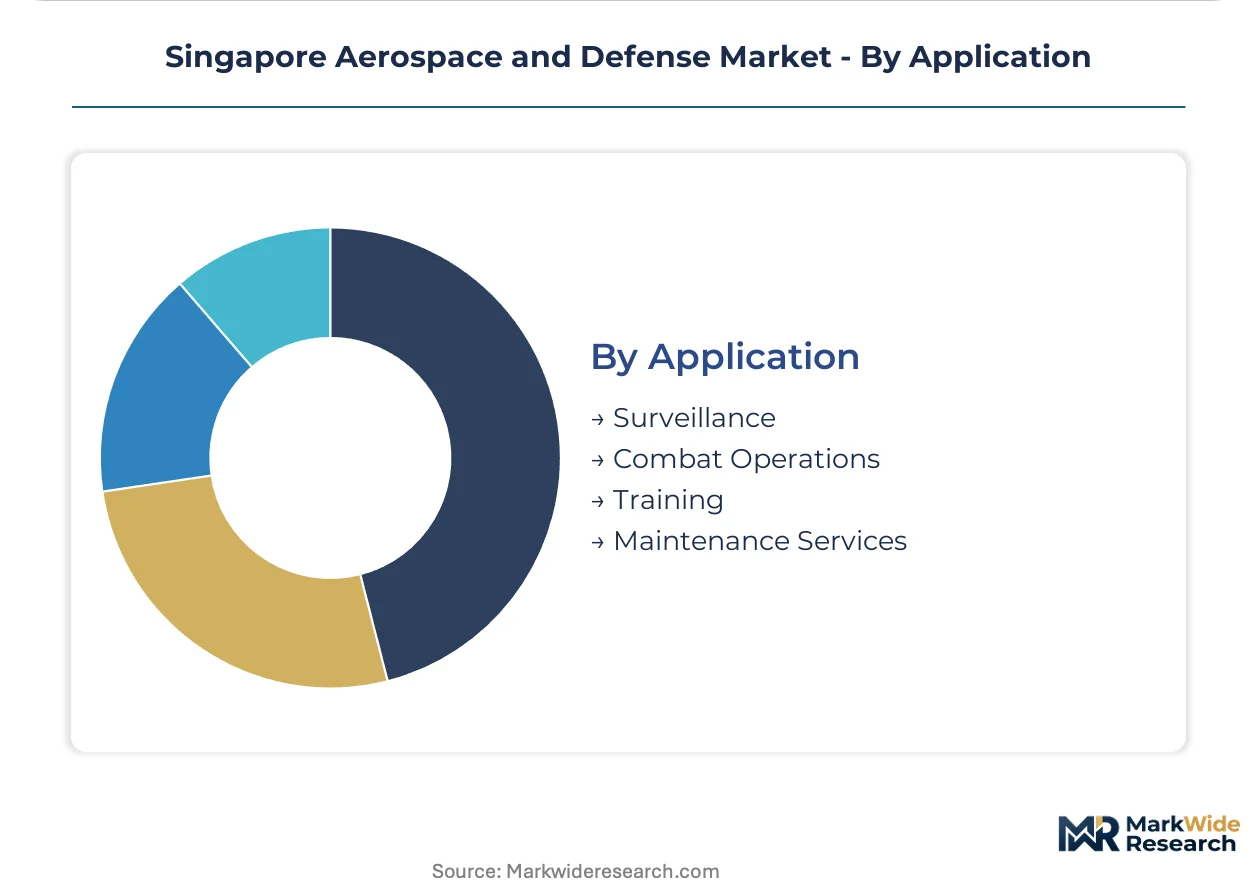
Singapore's defense procurement structure segments across four dimensions that shape vendor qualification pathways and contract allocation. Each category reflects distinct buyer decision criteria from MINDEF's capability development priorities.
Product Type:
Platform acquisition budgets concentrate on assets with the longest operational lifecycles and highest sustainment complexity.
- Military Aircraft:Fixed-wing platforms including F-15SG and F-16 fleets require specialized tropical environment modifications and integrated avionics architectures. Demand concentrates at Paya Lebar Air Base and Tengah Air Base where the Republic of Singapore Air Force operates combined strike and air defense missions under corrosion-resistant specifications.
- Naval Vessels:Surface combatants and littoral mission vessels constructed at Sembcorp Marine and Keppel shipyards utilize nickel-titanium alloys for tropical maritime endurance. The Republic of Singapore Navy's coastal defense perimeter drives fleet expansion with integrated command-and-control systems.
- Drones:Unmanned aerial systems for maritime surveillance and littoral domain awareness missions.
- Missiles:Guided munitions and precision strike systems integrated with platform avionics suites.
Military aircraft leads on scale; drones leads on momentum.
Technology:
Capability investment prioritizes systems that compress platform upgrade cycles while extending operational availability.
- Cybersecurity:Zero-trust network architectures mandated by Singapore's Cyber Security Agency for all military-civil dual-use systems. Defense contractors must demonstrate segmented access controls to qualify for integration contracts under the 2024 technology refresh guidelines.
- Avionics:Active electronically scanned array radar integration and flight data analytics for F-15SG engine health monitoring. The Republic of Singapore Air Force adopts predictive maintenance algorithms on compressed implementation timelines.
- Simulation Systems:Air-ganged hardware-in-the-loop configurations isolating classified mission data from commercial software environments.
- Robotics:Autonomous systems integration for maintenance and logistics applications in hazardous environments.
Avionics commands the largest procurement allocation; cybersecurity is climbing the fastest.
End User:
Contract flows diverge based on sovereign capability requirements versus foreign military sales channel access.
- Government Agencies:MINDEF and the Defence Science and Technology Agency direct procurement through long-term capability development plans with multi-year sustainment obligations concentrated among domestic primes.
- Defense Contractors:ST Engineering and SIA Engineering Company Limited anchor military vehicle and aircraft support through established maintenance infrastructure.
- OEMs:Foreign original equipment manufacturers including Airbus SE and Rolls-Royce plc navigate stringent technology transfer protocols for Singaporean defense program access.
- Research Institutions:Universities and defense laboratories supporting indigenous unmanned systems development and dual-use technology validation.
Government agencies dominate contract value; defense contractors capture the steepest expansion trajectory in sustainment services.
Application:
Operational requirements determine platform configuration specifications and lifecycle support intensity.
- Combat Operations:Integrated strike and air defense missions requiring hardened avionics architectures and precision munitions compatibility for the Republic of Singapore Air Force's operational squadrons.
- Maintenance Services:Performance-based logistics contracts displacing time-and-material arrangements, with availability-based contracting transferring operational risk to contractors for naval surface combatant support.
- Surveillance:Maritime domain awareness and littoral monitoring missions utilizing unmanned systems and radar networks.
- Training:Advanced simulation infrastructure capturing foreign military training contracts from ASEAN partner nations.
Maintenance services leads on contract duration; combat operations leads on technology refresh frequency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France commands aerospace exports through Rafale fighter diplomacy while Israel channels defense innovation into cyber-physical systems for tropical maritime environments. Both nations illustrate how specialized engineering cultures translate into distinct procurement channels for Southeast Asian defense buyers.
United States
F-15SG platform sustainment and Foreign Military Sales approvals anchor bilateral defense trade through the Defense Security Cooperation Agency. Congressional notification thresholds for major arms packages create procedural delays that Singaporean planners must navigate. The Arizona desert hosts Republic of Singapore Air Force training detachments at Luke Air Force Base, maintaining pilot proficiency on US soil.
France
Rafale fighter negotiations and Airbus rotorcraft supply sustain French industrial presence in Southeast Asian procurement cycles. The Direction Générale de l'Armement coordinates technology transfer protocols for naval combatant subsystems. Toulouse-based engineering teams support A330 multi-role tanker transport integration for Singapore's aerial refueling requirements.
United Kingdom
Rolls-Royce turbine servicing partnerships and BAE Systems avionics architectures penetrate Singaporean maintenance networks. The UK Ministry of Defence's Defence and Security Equipment International exhibition serves as annual venue for bilateral capability discussions. Derby engineering facilities process engine overhaul volume from Republic of Singapore Air Force F-15SG fleets.
Israel
Elbit Systems and Israel Aerospace Industries supply unmanned aerial systems and electronic warfare suites for littoral domain awareness missions. The Israeli Ministry of Defense's Directorate of Defense Research and Development facilitates rapid technology insertion cycles. Tel Aviv cybersecurity firms embed zero-trust architectures into Singaporean command-and-control infrastructure.
Japan
Mitsubishi Heavy Industries and Kawasaki Heavy Industries compete for regional maritime patrol aircraft requirements through defense equipment export frameworks. Japan's Ministry of Defense eased arms export restrictions in 2014, enabling industrial participation in Southeast Asian naval modernization. Tokyo-based trading houses coordinate submarine technology consultations with Singaporean defense planners.
Singapore Aerospace and Defense Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists for contract flows concentrated among Singapore government agencies. The vendor base stratifies across three tiers: domestic primes with multi-year sustainment obligations, foreign OEMs navigating technology transfer protocols, and engineering service providers anchoring maintenance infrastructure. Two dominant competitive moves structure rivalry: performance-based logistics contracting that transfers operational risk to vendors, and sovereign capability development that compresses foreign supplier access.
Within the domestic prime tier, Singapore Technologies Engineering Ltd and SIA Engineering Company Limited exemplify integrated engineering groups with captive maintenance infrastructure. RTX Corporation and Airbus SE occupy positions as foreign OEMs competing across fixed-wing and rotorcraft platform categories. Rolls-Royce plc anchors the engine overhaul specialist archetype through regional turbine servicing partnerships.
| Leading Market Players |
|---|
| RTX Corporation |
| Airbus SE |
| SIA Engineering Company Limited |
| Lockheed Martin Corporation |
| The Boeing Company |
| Singapore Technologies Engineering Ltd |
| General Electric Company |
| Pratt & Whitney |
| Rolls-Royce plc |
| Others |
Value Network & Pricing Analysis
Performance-grade certification divergence between MINDEF-qualified primes and sub-tier engineering vendors manifests in contract premiums for tropical corrosion specifications and compressed payment terms for commodity alloy suppliers. This bifurcation concentrates pricing power with domestic primes holding multi-year sustainment obligations while foreign OEMs absorb technology transfer compliance costs.
Pricing Analysis
Capacity additions in Southeast Asian nickel-titanium smelting are reshaping price floors for corrosion-resistant naval alloys, though aerospace-grade specifications retain premium spreads. Three-tier pricing structure across MINDEF-qualified, commercial-military dual-use, and commercial-only certification levels separates contract values by compliance depth. Pricing pressure stems from semiconductor component sourcing for avionics upgrades, with foundry qualification costs compressing margins on legacy platform retrofits. Government agencies exhibit lowest price sensitivity given sovereign capability mandates, while research institutions face strict budget caps on dual-use technology validation.
Supply Chain Analysis
Direct-to-MINDEF channels handle sovereign capability procurement, with foreign military sales flowing through Defense Security Cooperation Agency notification pathways. Geographic supply concentration centers on United States for F-15SG platform subsystems, France for Airbus rotorcraft architectures, and United Kingdom for Rolls-Royce turbine overhauls. Raw material dependencies include nickel-titanium shape memory alloys, gallium nitride semiconductors for AESA radar, and corrosion-resistant composite resins. Single-source vulnerability from concentrated Southeast Asian smelter supply for specialized alloys creates procurement schedule risk during demand surges.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Singapore aerospace and defense represents a late-cycle quality story as MINDEF's digital transformation roadmap redirects procurement toward cyber-physical integrated platforms with extended operational availability requirements.
For Market Incumbents: Extend performance-based logistics contract coverage to absorb operational risk from availability-based naval sustainment pilots. Deepen backward integration into nickel-titanium alloy processing to mitigate Southeast Asian smelter concentration. Anchor F-15SG engine health monitoring service roles against platform manufacturer diagnostic absorption. For New Entrants and Emerging Players: Digital-channel routes through Singapore's Cyber Security Agency certification pathways offer lowest barrier to entry for zero-trust architecture vendors. White-space targets include maritime surveillance drone subsystems for littoral domain awareness and AI-enabled predictive maintenance algorithms for compressed RSAF implementation timelines. Partner with Defence Science and Technology Agency on indigenous unmanned systems development roadmaps. For Investors and Strategic Acquirers: Consolidation pressure builds where performance-based logistics contracts concentrate vendor management under integrated guarantees. Five-to-ten year viability favors engineering service providers with captive MINDEF relationships and tropical environment specialization. Watch for F-16 mechanical systems expertise attrition as inflection signal for maintenance services acquisition timing.| Strategic Initiative | Industry Significance |
|---|---|
| Performance-Based Logistics Contracting | ST Engineering Marine transfers operational risk through availability-based naval sustainment guarantees. |
| Zero-Trust Architecture Certification | Cyber Security Agency compliance creates qualification pathway for avionics integration vendors. |
| Indigenous Unmanned Systems Development | Defence Science and Technology Agency roadmap compresses foreign OEM access for maritime surveillance. |
| Tropical Alloy Processing Integration | Sembcorp Marine and Keppel shipyards secure nickel-titanium supply against Southeast Asian smelter volatility. |
| Regional Training Hub Positioning | Singapore's simulation infrastructure captures ASEAN foreign military training contracts for F-16 transition programs. |
Research Methodology
Multiple input streams — primary interviews with MINDEF procurement officers, RSAF maintenance directors, and shipyard program managers; secondary validation through Defense Security Cooperation Agency notifications, Civil Aviation Authority of Singapore airworthiness filings, and Cyber Security Agency compliance guidelines; plus customs data on nickel-titanium alloy imports — were reconciled through bottom-up platform procurement tracking and top-down defense budget allocation analysis.
Historical contract award patterns were cross-referenced against expert panel inputs from defense procurement consultants and aerospace engineering specialists. Segmentation dimensions modeled include platform type, technology category, end-user tier, and application mission profile across the projection horizon. CAGRs were derived from capability development plan budget trajectories and foreign military sales pipeline visibility, with specific inputs from F-15SG modernization schedule acceleration and littoral mission vessel program expansion rates.
Foreign Military Sales approval delays, technology transfer protocol elongation, and specialized alloy price volatility are the dominant revision risks to forecast assumptions. Periodic stress-testing of base assumptions against MINDEF next-generation fighter acquisition announcements is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aerospace & Defense
Europe Commercial Aircraft Cabin Seating Market
Aerospace & Defense
America Airport Ground Handling Systems Market
Aerospace & Defense
Middle-East Aviation Market
Aerospace & Defense
Global Aircraft Cabin Upgrades Market
Aerospace & Defense
Loitering Munition System Market
Aerospace & Defense
Asia-Pacific Aircraft MRO Market
Aerospace & Defense
North America C5ISR Market
Aerospace & Defense
Drone Docking Station Market
Aerospace & Defense
Global Composite Materials Aluminum Alloys Aerospace Market
Aerospace & Defense
United States Drone Services Market
Aerospace & Defense
Asia-Pacific Satellite Manufacturing and Launch Systems Market
Aerospace & Defense
Americas Air Defense Systems Market
Aerospace & Defense
Global Healthcare Games and Simulation Market
Aerospace & Defense
North America Airborne ISR Market
Aerospace & Defense
North America Commercial Aircraft Cabin Lighting Market
Aerospace & Defense
Middle East Airport Operations Market