
 Automatic Cattle Waterer Market | 2026-2036
Automatic Cattle Waterer Market Size, Share, and Industry Trends Forecast 2026-2036
Automatic Cattle Waterer Market Outlook
Consolidation among dairy cooperatives in the Upper Midwest is repositioning procurement power toward fewer buyers with standardized equipment requirements. Ritchie Industries leverages its frost-free engineering heritage to dominate cold-climate installations across Wisconsin and Minnesota. Nelson Manufacturing competes through heated waterer specialization that sustains performance in sub-zero feedlot conditions. Behlen Country anchors its position via polyethylene tank manufacturing scale that controls cost curves for mid-sized beef operations.
An automatic cattle waterer is a thermostatically controlled or passively insulated drinking device that maintains potable water delivery to livestock across ambient temperature extremes, typically incorporating float valves, heating elements, or vacuum-sealed reservoirs rated for sustained outdoor exposure. Its primary commercial purpose centers on eliminating manual bucket hauling and ice breaking while reducing dehydration-related veterinary costs in confined animal feeding operations. Frost-free waterers lead product type demand in northern states where buried reservoir designs prevent freeze damage, while heated waterers capture premium margin pools from intensive dairy farms requiring constant flow regardless of weather severity. Gravity-fed configurations serve remote pasture rotations where electrical access remains limited, occupying a stable niche despite slower growth trajectories.
The USDA National Organic Program and FDA Veterinary Feed Directive jointly shape equipment specifications by mandating documented water access intervals and antimicrobial-free hydration systems that influence automatic waterer sensor integration. EPA agricultural runoff guidelines further constrain material choices by requiring polyethylene and stainless steel constructions that resist corrosion without leaching contaminants into groundwater tables. State-level animal welfare enforcement in Nebraska, Iowa, and Kansas adds installation compliance layers that favor below-ground and fixed mounting configurations over portable alternatives. Stakeholders must monitor evolving organic certification thresholds and regional drought contingency planning that could mandate flow-rate telemetry across federally subsidized operations.
Market Dynamics
Feedlot consolidation across Nebraska, Iowa, and Wisconsin is compressing buyer counts and forcing equipment standardization onto fewer procurement desks with volume leverage.
Growth Catalysts
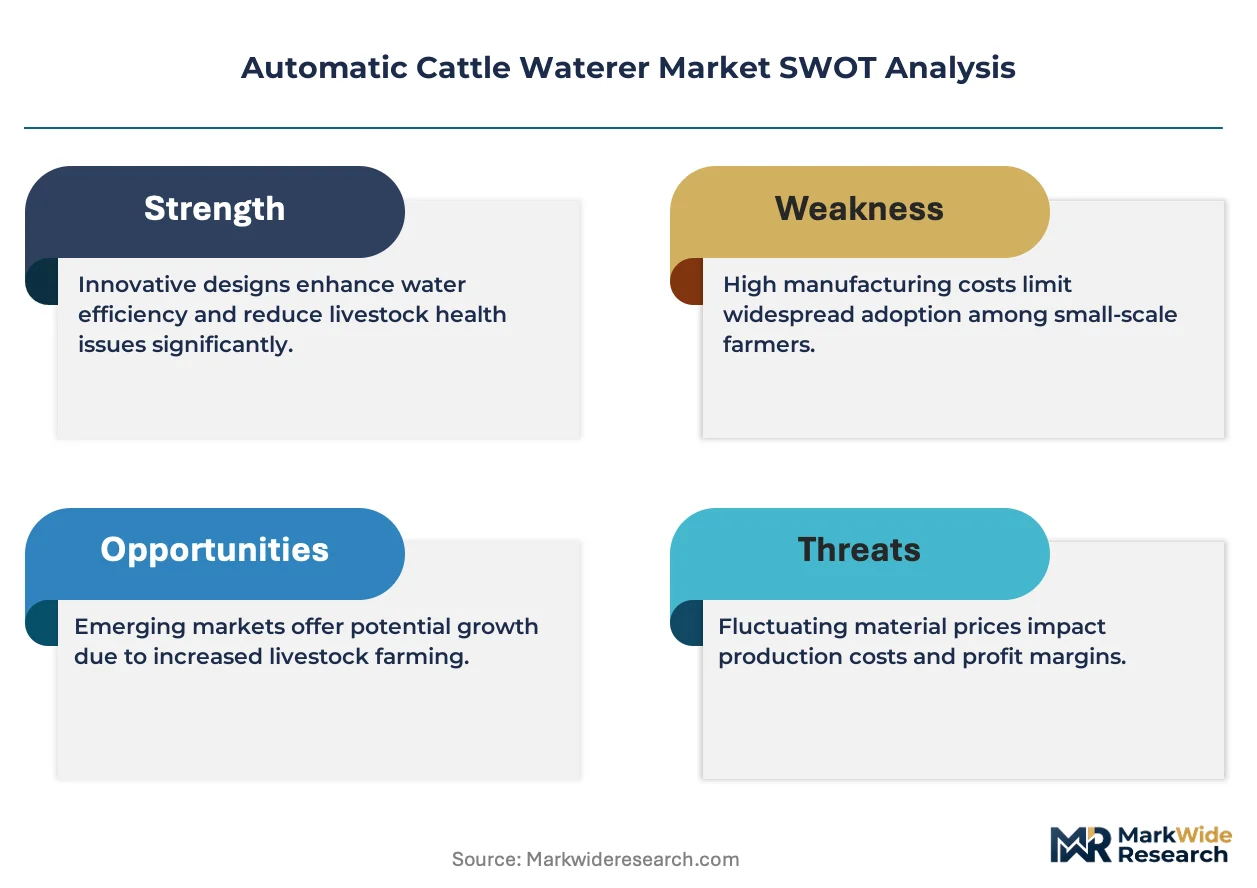
- USDA National Organic Program:Documentation mandates for consistent water access push conventional operations toward certified automatic waterer installations with integrated flow sensors.
- Dairy farm expansion:Upper Midwest cooperative consolidation creates procurement clusters demanding frost-free and heated systems with telemetry compatibility.
- Sub-zero engineering:Buried reservoir designs with vacuum-sealed insulation penetrate northern states where manual ice breaking previously dominated winter operations.
Market Restraints
- Copper and steel input volatility:Heating element manufacturing faces raw material price swings that compress margin pools for mid-tier suppliers.
- Electrical infrastructure gaps:Remote pasture rotations in Kansas and Nebraska lack grid access, limiting heated waterer penetration regardless of dairy farm consolidation.
- EPA agricultural runoff constraints:Material certification delays for polyethylene and stainless steel constructions extend product qualification timelines for new market entrants.
Strategic Opportunities
- Gravity-fed pasture systems:Unpowered configurations address electrical infrastructure gaps across western Kansas and eastern Colorado feedlot expansions.
- Flow-rate telemetry integration:Sensor-enabled documentation aligns with drought contingency planning requirements emerging from federally subsidized operations.
- State-level animal welfare enforcement:Below-ground mounting mandates in Iowa and Nebraska favor fixed-installation suppliers over portable equipment vendors.
Industry Challenges
- Livestock hydrology engineering talent:Specialized knowledge combining thermostatic control, veterinary hydration science, and agricultural infrastructure remains scarce in the Upper Midwest labor pool.
- Legacy system interoperability:Retrofitting existing barn plumbing for sensor-integrated waterers requires custom fabrication that extends installation timelines and strains contractor capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automatic Cattle Waterer Market |
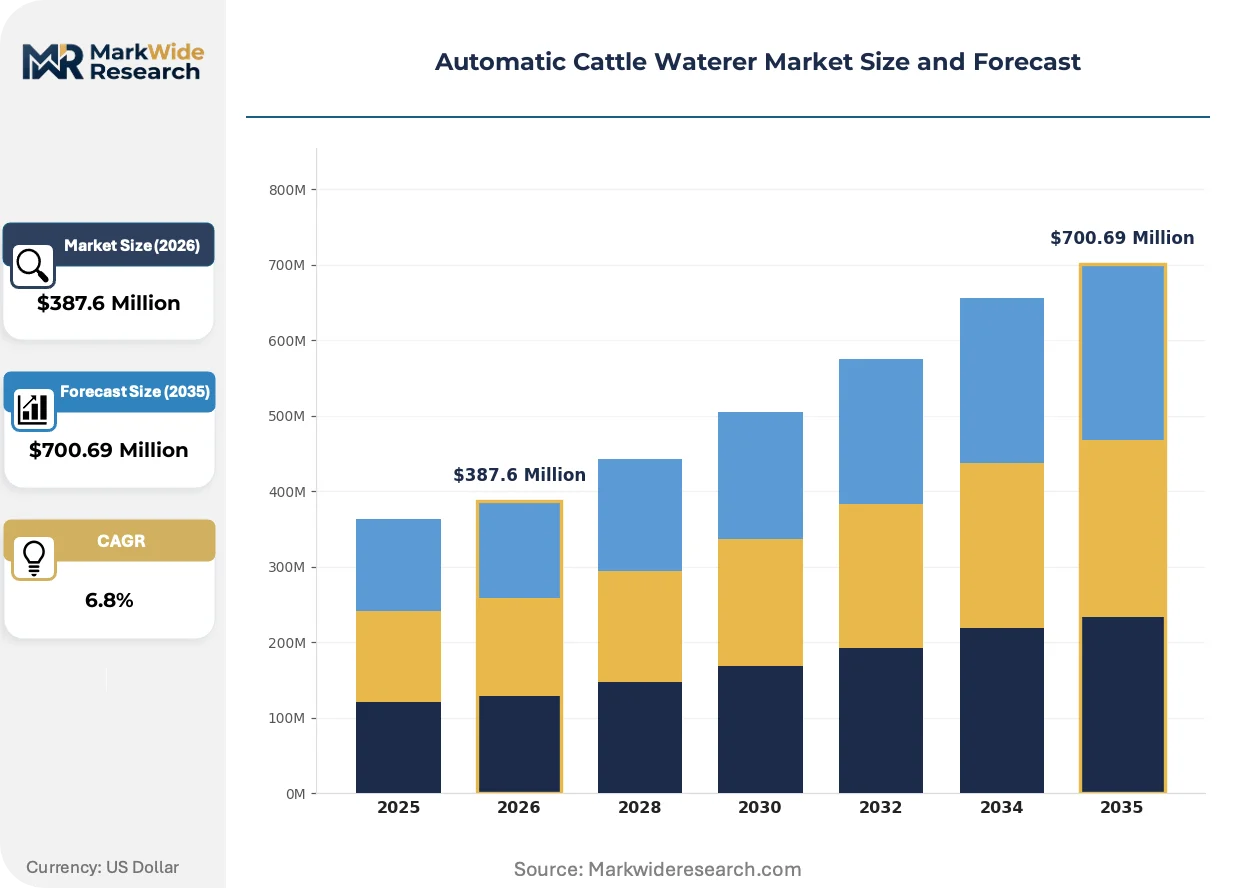
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frost-Free Waterers, Heated Waterers, Gravity-Fed Waterers, Float-Control Waterers End User: Dairy Farms, Beef Cattle Operations, Feedlots, Livestock Auctions Installation Type: Above Ground, Below Ground, Portable, Fixed Material: Stainless Steel, Plastic, Polyethylene, Concrete |
| Companies Covered | Ritchie Industries, Nelson Manufacturing, Behlen Country, Tusker Livestock, DP Waterer, Petersen Industries, Bohlmann Manufacturing, Ritchie Fount, Schauer Agrotronic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automatic Cattle Waterer Market Strategic Shifts
Equipment intelligence and regulatory documentation requirements are converging to reshape how hydration systems integrate with herd management software and compliance reporting workflows.
IoT-enabled flow monitoring is electrifying data capture across automatic cattle waterer installations. Dairy cooperatives in Wisconsin and Minnesota deploy sensor arrays that transmit real-time consumption metrics to centralized herd management platforms. This connectivity infrastructure is compressing the competitive window for equipment suppliers lacking API-compatible telemetry architectures.
USDA National Organic Program standards now mandate timestamped water access logs that influence equipment specification sheets. Dairy operations pursuing certification specify automatic waterers with integrated data-logging capabilities that eliminate manual recordkeeping. Frost-free system suppliers in the Upper Midwest accelerate firmware development to capture this compliance-driven replacement cycle.
Volume procurement contracts are consolidating supplier relationships across fewer buyer entities. Large-scale feedlot operators in Nebraska and Iowa negotiate multi-site equipment packages that bundle installation, maintenance, and telemetry subscriptions. This contract restructuring favors regional distributors with field service density over catalog-only vendors lacking technician networks.
Automatic Cattle Waterer Market Segmentation
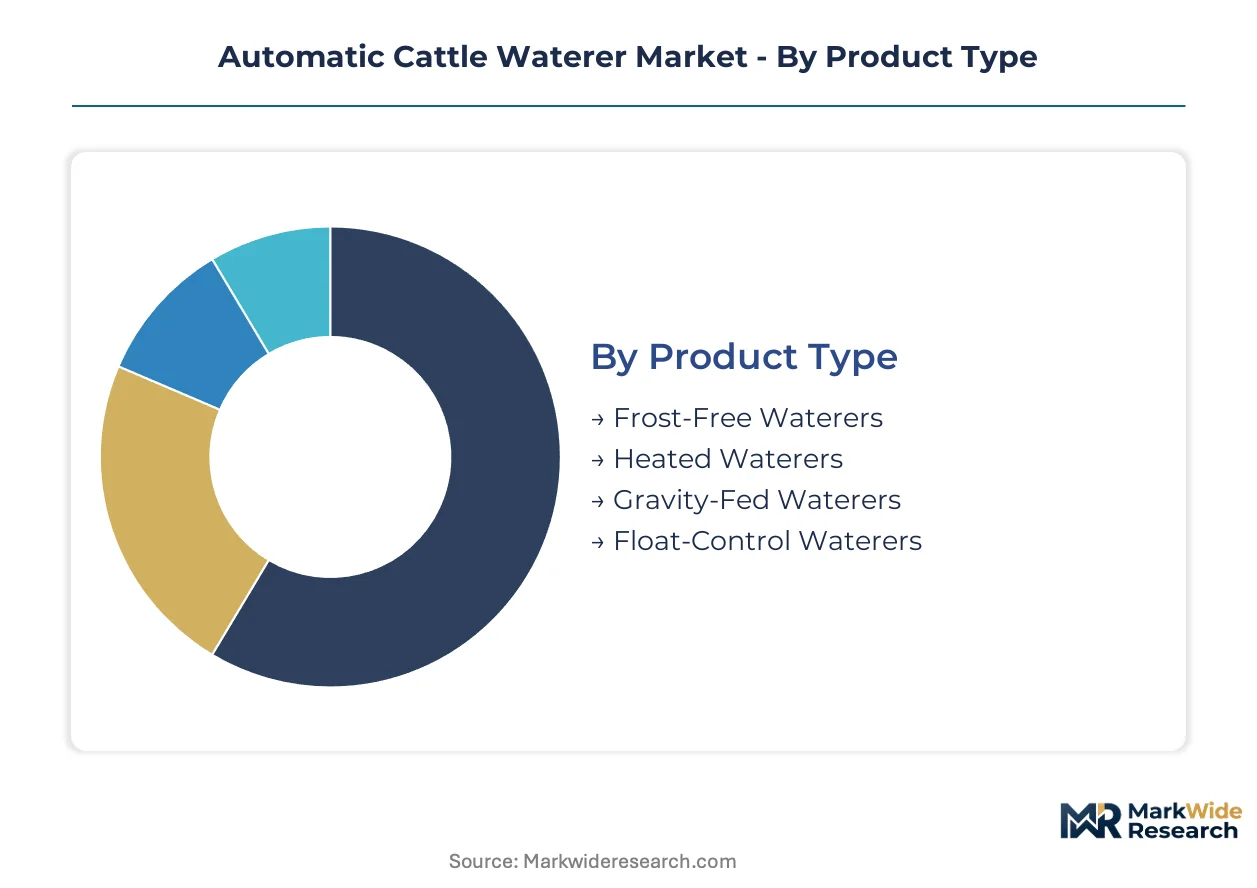
Automatic cattle waterer purchasing decisions hinge on climate severity, herd scale, and regulatory documentation burdens. Equipment specifications diverge sharply between frost-prone northern states and temperate zones, while organic certification requirements reshape sensor integration priorities across all buyer categories.
Product Type:
Cold-climate engineering requirements and electrical infrastructure availability determine equipment selection across Upper Midwest operations.
- Frost-Free Waterers:Buried reservoir designs with vacuum-sealed insulation eliminate freeze damage without continuous power draw. Demand concentrates in Wisconsin and Minnesota dairy cooperatives where USDA organic documentation requirements favor self-regulating thermal mass over electrically dependent alternatives.
- Heated Waterers:Thermostatically controlled elements sustain water flow in sub-zero feedlot conditions. Nebraska and Iowa intensive operations specify these systems despite electrical infrastructure costs, prioritizing constant hydration access for high-value finishing cattle.
- Gravity-Fed Waterers:Unpowered configurations serve remote Kansas and eastern Colorado pasture rotations where grid access remains limited.
- Float-Control Waterers:Mechanical valve systems dominate budget-conscious beef operations with moderate climate exposure.
Frost-free waterers lead on scale; heated waterers lead on momentum.
End User:
Herd size and veterinary oversight intensity shape procurement sophistication across customer categories.
- Dairy Farms:Upper Midwest cooperative consolidation drives volume procurement of telemetry-enabled systems. FDA Veterinary Feed Directive compliance and USDA National Organic Program documentation mandates push sensor integration into standard specifications.
- Beef Cattle Operations:Mid-sized ranches across Nebraska and Kansas prioritize polyethylene tank durability over connectivity features.
- Feedlots:Large-scale Nebraska and Iowa operators negotiate multi-site equipment packages bundling installation, maintenance, and data subscriptions.
- Livestock Auctions:Transitional hydration requirements favor portable configurations with rapid deployment capability.
Feedlots lead on scale; dairy farms lead on momentum.
Installation Type:
State-level animal welfare enforcement and permanence requirements structure mounting decisions.
- Below Ground:Buried reservoir configurations dominate Iowa and Nebraska installations where state regulations mandate fixed mounting for confined animal feeding operations. EPA agricultural runoff guidelines further favor subsurface placement for groundwater protection.
- Above Ground:Elevated tank systems serve temporary holding areas and auction facilities requiring relocation flexibility.
- Fixed:Permanent plumbing integration captures the majority of Upper Midwest dairy capital expenditure.
- Portable:Mobile units address rotational grazing patterns across western Kansas rangeland.
Below-ground installations lead on scale; fixed systems lead on momentum.
Material:
Corrosion resistance and contaminant leaching constraints dominate material qualification under federal environmental guidelines.
- Polyethylene:Rotational-molded tank construction controls cost curves for mid-sized beef operations while satisfying EPA non-leaching requirements. Behlen Country manufacturing scale anchors supply availability across Nebraska and Iowa procurement clusters.
- Stainless Steel:Grade 304 and 316 specifications dominate intensive dairy applications where antimicrobial surface properties support FDA Veterinary Feed Directive compliance protocols.
- Plastic:Injection-molded components serve price-sensitive segments with moderate durability requirements.
- Concrete:Precast reservoir structures anchor large-capacity permanent installations in feedlot environments.
Polyethylene leads on scale; stainless steel leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada's prairie provinces lag the United States in automated watering adoption despite comparable herd sizes, while Brazil's Mato Grosso operations accelerate mechanized hydration investments to match North American productivity benchmarks.
United States
Nebraska and Iowa feedlot consolidation compresses buyer counts toward volume procurement desks with standardized equipment requirements. USDA National Organic Program documentation mandates push sensor-integrated systems across Upper Midwest dairy cooperatives. Wisconsin's Fox Valley dairy cluster drives frost-free waterer specifications that eliminate freeze damage without continuous electrical draw.
Canada
Alberta and Saskatchewan beef operations confront sub-zero engineering requirements comparable to northern US states but with sparser electrical infrastructure across remote pasture rotations. Health Canada's agricultural equipment standards align with EPA material guidelines for polyethylene and stainless steel constructions. Calgary-based procurement clusters negotiate multi-site maintenance contracts bundling telemetry subscriptions with hardware installation.
Brazil
Mato Grosso and São Paulo feedlot expansions import frost-free engineering concepts adapted for tropical humidity corrosion rather than freeze protection. ANVISA veterinary oversight protocols influence hydration system specifications for export-certified beef operations. Campinas industrial corridors host emerging equipment assembly partnerships with North American component suppliers.
Germany
Bavarian dairy cooperatives deploy precision livestock farming technologies that integrate automatic waterer telemetry with herd management software platforms. EU Green Deal agricultural sustainability criteria constrain material choices toward recyclable polyethylene and energy-efficient heating elements. Munich-Stuttgart industrial corridors concentrate sensor fabrication capacity for export to European livestock operations.
Australia
New South Wales and Victoria drought contingency planning mandates flow-rate documentation across federally subsidized cattle operations. The country's national agricultural regulator enforces water access monitoring that favors telemetry-enabled installations regardless of herd scale. Queensland pastoral companies retrofit gravity-fed systems with solar-powered pump mechanisms to address electrical infrastructure gaps across remote station holdings.
Automatic Cattle Waterer Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across tiered market strata. The vendor base organizes around three strategic archetypes: regional fabrication specialists with cold-climate engineering heritage, diversified agricultural equipment conglomerates leveraging polyethylene manufacturing scale, and precision livestock technology integrators bundling sensor platforms with hydration hardware. Capacity expansion and strategic partnerships constitute the dominant competitive moves as suppliers seek field service density to capture volume procurement contracts.
Among Upper Midwest specialists, Ritchie Industries and Nelson Manufacturing exemplify the engineering-intensive archetype that dominates frost-free and heated system categories. Behlen Country occupies a position within the diversified manufacturing tier, leveraging rotational-molded tank production scale to anchor cost curves for mid-sized beef operations. These three entities represent the competitive core against which emerging telemetry-integrated challengers must differentiate.
| Leading Market Players |
|---|
| Ritchie Industries |
| Nelson Manufacturing |
| Behlen Country |
| Tusker Livestock |
| DP Waterer |
| Petersen Industries |
| Bohlmann Manufacturing |
| Ritchie Fount |
| Schauer Agrotronic |
| Others |
Value Chain & Pricing Dynamics
Captive polyethylene tank production in Nebraska and Iowa anchors cost curves for mid-sized beef operations while insulating integrated manufacturers from resin price volatility that squeezes standalone fabricators. This backward integration into rotational molding capacity concentrates pricing power among three regional specialists who bundle installation services with hardware sales, compressing margin pools for catalog-only distributors lacking field technician networks.
Pricing Analysis
Capacity additions in Iowa and Wisconsin are reshaping price floors for frost-free waterers as Behlen Country's rotational-molded tank scale drives three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on telemetry integration and USDA organic certification compatibility, with sensor-enabled systems commanding premium positioning against mechanical float-valve alternatives. Cost compression in heated waterer segments is intensifying because copper heating element sourcing faces commodity volatility, making dairy cooperatives the least price-sensitive buyers while mid-sized ranches in Kansas exhibit acute sensitivity to upfront capital expenditure.
Supply Chain Analysis
Domestic-content mandates in federally subsidized operations are reshaping sourcing patterns toward US-based polyethylene and stainless steel fabrication. Supply concentration centers on Nebraska, Iowa, and Minnesota for tank molding, with heating element subassemblies drawing from Mexico and domestic electrical component suppliers. Raw material dependencies include polyethylene resin, grade 304/316 stainless steel, and copper thermostatic elements. Single-source vulnerability in vacuum-sealed insulation membrane supply creates structural risk. Distribution runs through regional agricultural equipment dealers with certified installation capabilities rather than direct-to-farm e-commerce channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where USDA National Organic Program documentation mandates create sustained replacement demand across conventional operations seeking certification. Equipment specification sheets now embed compliance features as standard rather than optional, permanently elevating procurement sophistication.
For Market Incumbents: Lock in telemetry architecture partnerships with herd management software platforms before API compatibility becomes table stakes. Deepen field service density across Wisconsin and Minnesota dairy clusters to defend against emerging precision livestock technology integrators. Prioritize backward integration into sensor fabrication or exclusive supplier agreements with Munich-Stuttgart component specialists to secure margin position against heating element cost volatility.
For New Entrants and Emerging Players: Capture gravity-fed pasture system demand across western Kansas and eastern Colorado where electrical infrastructure gaps exclude incumbent heated-waterer specialists. Target feedlot expansion corridors in Nebraska and Iowa with unpowered configurations that satisfy state animal welfare enforcement without requiring grid connectivity. Pursue bundling partnerships with rotational grazing consultants who specify mobile equipment for client operations.
For Investors and Strategic Acquirers: Roll-up economics work for regional fabrication specialists with cold-climate engineering heritage because feedlot consolidation compresses buyer counts toward volume procurement desks demanding multi-site maintenance contracts. Focus acquisition screening on entities with frost-free vacuum-seal IP and existing USDA organic certification reference installations. Watch for inflection when drought contingency planning mandates flow-rate telemetry across federally subsidized operations, signaling sensor-integrated system replacement cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Telemetry Platform Integration | API-compatible sensor architectures capture USDA organic documentation mandates across Upper Midwest dairy cooperatives. |
| Backward Integration into Rotational Molding | Captive polyethylene tank production insulates margin pools from resin price volatility in Nebraska procurement clusters. |
| Multi-Site Service Contract Bundling | Installation-maintenance-telemetry packages align with feedlot consolidation toward volume procurement desks in Iowa. |
| Gravity-Fed Product Line Expansion | Unpowered configurations address electrical infrastructure gaps across Kansas and Colorado pasture rotations. |
| Frost-Free Vacuum-Seal IP Development | Buried reservoir thermal mass engineering eliminates freeze damage without continuous power draw in Minnesota winters. |
Study Parameters
Multiple input streams — equipment specification database analysis, regulatory filing review, and procurement contract examination — were reconciled against primary field intelligence. Dairy cooperative operations managers, feedlot procurement directors, agricultural equipment dealership principals, and USDA organic certification inspectors provided structured interviews. Secondary validation drew from EPA agricultural runoff guideline documents, FDA Veterinary Feed Directive compliance protocols, and state-level animal welfare enforcement records. Bottom-up unit shipment estimates triangulated against top-down addressable market sizing across product type and installation category segments.
Historical volume trajectories were cross-referenced against panel-based input from industry participants to anchor projection parameters across the analysis window. Segmentation dimensions modeled include climate severity tier, herd scale category, regulatory documentation burden level, and electrical infrastructure availability. CAGRs were derived through regression-based trend extrapolation moderated by technology diffusion curves. Forecast inputs incorporated organic certification penetration rates and feedlot consolidation velocity indices without specifying annual milestones.
Commodity price volatility in copper and steel, regulatory threshold adjustments for organic certification, and electrical grid expansion timelines across remote pasture regions are the dominant revision risks. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Livestock Equipment
Nigeria Horse Riding Equipment Market
Livestock Equipment
Cattle Handling Systems Market
Livestock Equipment
Cattle Supplies Market
Livestock Equipment
Livestock Identification Market
Livestock Equipment
Animal Cage Market
Livestock Equipment
Poultry Feeder Market
Livestock Equipment
Automatic Hog Feeder Market
Livestock Equipment
Animal Feeding Equipment Market
Livestock Equipment
Electric Fencing Market
Livestock Equipment
China Horse Riding Equipment Market
Livestock Equipment
Slaughtering Equipment Market
Livestock Equipment
Cattle Grooming Chute Market
Livestock Equipment
Cattle Farm Equipment Market
Livestock Equipment
Animal Workstations Market
Livestock Equipment
Livestock Trailers Market
Livestock Equipment
Rabbit Hutches Market