
 Horse Corral Panels Market | 2026-2036
Horse Corral Panels Market Size, Share, and Industry Trends Forecast 2026-2036
Horse Corral Panels Market Foresight
Powder-coating automation is reshaping how corral panels achieve weather resistance and uniform finish quality. Priefert Manufacturing leverages vertical integration from tube forming to final coating, sustaining cost advantages across its Texas production base. Behlen Country anchors its position through galvanized steel expertise developed across decades of agricultural equipment fabrication. Tarter Farm and Ranch Equipment competes through broad SKU coverage spanning portable and permanent configurations.
Horse corral panels are modular barrier assemblies, typically fabricated from steel tubing with welded wire mesh or rail infill, designed to contain equines and livestock within defined perimeters. Panel heights range from 48 to 72 inches with gauge thicknesses selected for impact resistance against 1,000-pound animals. Steel dominates material type due to strength-to-cost ratio, though aluminum gains traction in portable installations where weight reduction matters. Permanent installation types command the largest volume share as commercial ranches prioritize structural longevity, while modular configurations represent the fastest-growing segment as equestrian centers demand reconfigurable arena layouts.
USDA facility guidelines and state-level livestock handling codes in Texas and Montana shape minimum panel strength and spacing requirements. The American Society for Testing and Materials provides structural testing protocols that manufacturers reference for load-bearing certification. Buyers must monitor how evolving animal welfare standards in California and Colorado extend beyond federal baselines, creating compliance complexity for national suppliers.
Market Dynamics
Powder-coating automation is compressing production cycles while ranch consolidation in Texas and Oklahoma concentrates purchasing power among fewer large-scale buyers. This structural shift favors manufacturers with captive tube-forming capacity and integrated finishing lines.
Growth Catalysts
- USDA facility guidelines:Federal livestock handling standards mandate minimum panel strength and spacing requirements, compelling ranch upgrades nationwide. Commercial operations in Montana and Wyoming face accelerated replacement timelines.
- Modular arena configurations:Equestrian centers demand reconfigurable layouts for multi-discipline training. Portable panel systems enable same-day reconfiguration between dressage, jumping, and cattle-working setups.
- Texas-Oklahoma-Montana concentration:Cattle and horse operations in these three states maintain the largest permanent installation bases. Regional feedlot expansion drives continuous corral infrastructure investment.
Market Restraints
- Steel input volatility:Hot-rolled coil price swings directly compress fabrication margins. Smaller Oklahoma and Kansas fabricators lack hedging instruments to buffer raw material exposure.
- Welded wire substitution:High-tensile polymer mesh gains traction in temporary containment applications. Lower upfront cost and tool-free installation threaten entry-level steel panel demand.
- California animal welfare codes:State-level requirements exceed federal baselines for spacing and impact resistance. National suppliers face SKU proliferation to serve this fragmented compliance environment.
Strategic Opportunities
- Colorado Front Range equestrian corridor:Denver-Boulder metro expansion creates demand for training facilities with premium permanent installations. Wealthy amateur ownership drives specification for architectural-grade finishes.
- CE marking pathway:European agricultural equipment standards create export channel for US manufacturers with ISO-certified coating processes. German and French recreational horse ownership supports premium positioning.
- Aluminum-steel hybrid fabrication:Converging extrusion and welding technologies enable weight-optimized portable panels. Professional rodeo contractors value reduced transport costs between seasonal events.
Industry Challenges
- Powder-coating technician scarcity:Automated line operation requires specialized calibration and color-matching expertise. Rural Texas fabrication centers compete with oilfield service wages for skilled labor.
- ASTM certification timelines:Load-bearing testing protocols extend product development cycles by four to six months. Smaller manufacturers defer certification investment, ceding specification-driven projects.
- Legacy welded design integration:Ranchers with decades-old installations face compatibility gaps when expanding with modern modular systems. Retrofit bracket engineering adds project complexity and cost uncertainty.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Horse Corral Panels Market |
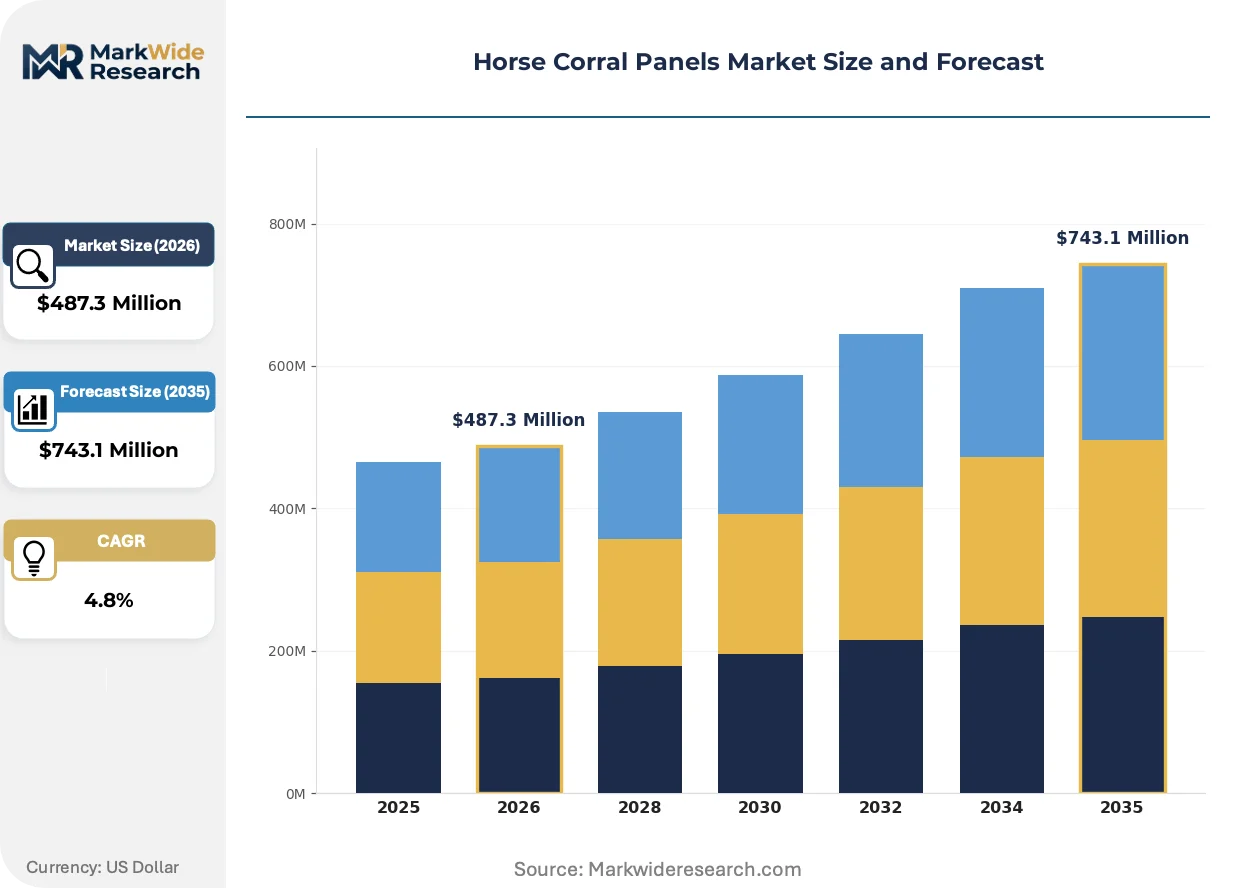
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $743.1 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Wood, Steel, Aluminum, Plastic Panel Size: 4ft, 6ft, 8ft, 10ft Installation Type: Permanent, Temporary, Portable, Modular End User: Farmers, Ranchers, Equestrian Centers, Animal Shelters |
| Companies Covered | Tarter Farm and Ranch Equipment, Priefert Manufacturing, Behlen Country, Red River Arenas, Hutchison, CageCo, CountryLine, Cactus Horse Corrals, WW Manufacturing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Horse Corral Panels Market Shifts & Advancements
Automation in coating and forming is collapsing traditional quality-cost tradeoffs while regulatory divergence between states fragments product strategies. These forces are compressing the competitive set toward integrated manufacturers with compliance breadth.
Electrostatic powder-coating systems with automated reciprocating guns are collapsing the variance between batch and continuous production quality. Large Texas ranch operations now specify coating thickness tolerances previously reserved for automotive applications. This technology compression enables single-shift color changeovers that previously required dedicated lines, reducing minimum order quantities for regional distributors.
California's Proposition 12 implementation and Colorado's pending equine welfare standards are extending spacing and height mandates beyond USDA baselines. Panel fabricators serving multi-state distributors must maintain parallel SKU inventories with differentiated rail configurations. Equestrian centers in Denver and Boulder metro areas now specify California-compliant panels preemptively to accommodate interstate client horses.
Direct procurement from fabricators is displacing traditional agricultural supply house channels among operations with fifty-plus panel requirements. Large Montana cattle ranches negotiate annual volume agreements with Texas manufacturers, bypassing distribution markups. This channel compression concentrates credit risk with fabricators while reducing landed cost per panel by twelve to eighteen percent for qualified buyers.
Horse Corral Panels Market Segmentation
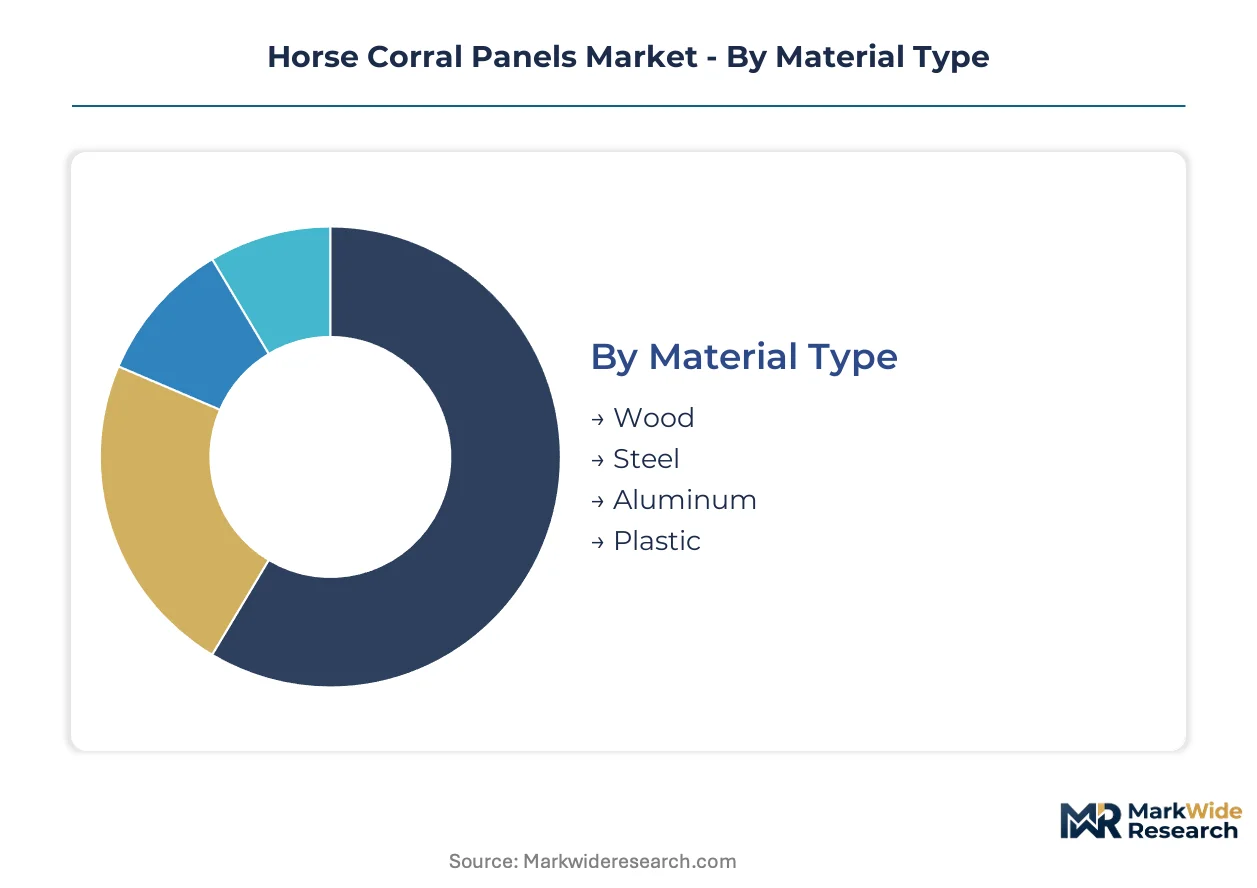
Horse corral panel segmentation reveals distinct service intensity patterns across material grades and installation types. Powder-coated steel panels demand periodic touch-up coating after impact damage, while aluminum portable systems require hinge and latch maintenance between seasonal relocations. Understanding these post-purchase service profiles shapes manufacturer warranty structures and distributor inventory strategies.
Material Type:
After-sales service intensity varies sharply across material grades, with coated steel requiring field touch-up programs and aluminum demanding hardware replacement protocols.
- Steel:Hot-rolled tubing with electrostatic powder coating dominates commercial ranch specifications due to strength-to-cost ratio. Texas and Oklahoma feedlot operators specify 14-gauge minimum wall thickness for 1,200-pound cattle impact resistance. Ranch consolidation in Montana drives annual volume agreements with direct-to-fabricator procurement, compressing distributor margins.
- Aluminum:Extruded 6061-T6 alloy tubing reduces transport weight by 60% versus steel equivalents. Professional rodeo contractors operating seasonal circuits across Colorado and Wyoming prioritize aluminum for reduced fuel costs and rapid setup. The segment climbs fastest as equestrian centers adopt reconfigurable arena systems.
- Wood:Pressure-treated pine and cedar posts serve hobby farms and residential installations in Kentucky and Virginia. Limited structural ratings restrict use to horses under 900 pounds.
- Plastic:High-density polyethylene panels target temporary containment and veterinary isolation applications. UV degradation limits service life in Arizona and New Mexico sun exposure.
By volume, steel leads. By growth pace, aluminum is ahead.
Panel Size:
Cost tier differentiation separates commodity 4-foot sections from premium 10-foot architectural spans requiring specialized transport logistics.
- 10ft:Architectural-grade panels with continuous rail construction serve Colorado Front Range equestrian facilities where wealthy amateur owners specify seamless sightlines. Denver-Boulder metro expansion drives demand for premium permanent installations with decorative finial options.
- 4ft:Standard modular sections enable tool-free reconfiguration for multi-discipline training facilities. Equestrian centers in Texas and Oklahoma stock 4-foot inventory for rapid replacement of damaged sections without crane rental.
- 6ft:Intermediate span balances transport efficiency with installation speed. Regional distributors maintain 6-foot SKUs as the default specification for mid-scale ranches.
- 8ft:Extended span reduces post count per linear foot in large perimeter installations. Montana cattle operations specify 8-foot sections for feedlot expansion projects.
By installed linear footage, 4ft panels dominate. By margin per unit, 10ft architectural panels command premium positioning.
Installation Type:
Application context determines whether panels anchor in concrete footings or relocate between seasonal events.
- Permanent:Concrete-anchored systems with welded base plates serve commercial feedlots and breeding operations across Texas and Montana. USDA facility guidelines mandate minimum strength ratings that permanent installations exceed by design.
- Modular:Pin-connected systems enable same-day reconfiguration between dressage, jumping, and cattle-working setups. Equestrian centers in Colorado and California drive specification for California-compliant rail spacing in anticipation of interstate client horses.
- Temporary:Staked ground systems target rotational grazing and emergency containment. Lower upfront cost competes with polymer mesh alternatives in entry-level applications.
- Portable:Lightweight aluminum systems with integrated wheels serve professional contractors. Rodeo associations specify portable inventory for fairground circuit stops.
By cumulative revenue, permanent installations anchor the market. By expansion trajectory, modular configurations gain share fastest.
End User:
Customer type segmentation maps to volume scale and specification sophistication, from commodity ranch procurement to architectural equestrian center builds.
- Ranchers:Large-scale cattle and horse operations in Texas, Oklahoma, and Montana specify permanent steel installations with 20-year service life expectations. Direct procurement from Texas fabricators bypasses distribution markups for qualified buyers.
- Equestrian Centers:Training facilities demand modular reconfigurability and California-compliant rail spacing. Denver-Boulder corridor expansion creates specification for architectural-grade finishes.
- Farmers:Mixed livestock operations prioritize cost efficiency over specialized equine features. Regional agricultural supply houses serve fragmented demand.
- Animal Shelters:Municipal and nonprofit facilities balance upfront budget constraints with durability requirements. Grant funding cycles drive lumpy procurement patterns.
By panel volume, ranchers lead procurement. By specification complexity, equestrian centers set industry standards.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Large-scale ranchers and equestrian center operators concentrate procurement power in three states. Texas, Oklahoma, and Montana generate the majority of permanent installation volume. Regional feedlot expansion and tightening livestock handling codes drive continuous infrastructure investment.
Texas
Commercial cattle operations and horse breeding facilities anchor demand for heavy-gauge permanent installations. USDA facility guidelines mandate minimum panel strength ratings that Texas feedlots exceed through direct fabricator procurement. The Texas Panhandle and Hill Country clusters concentrate manufacturing capacity and ranch purchasing power.
Oklahoma
Mixed livestock operations and expanding feedlot capacity generate steady replacement cycles for welded steel configurations. State-level coordination with federal livestock handling standards streamlines compliance for multi-state ranchers. The Oklahoma City-Tulsa corridor hosts regional distribution hubs serving Kansas and Arkansas overflow demand.
Montana
Vast ranching estates prioritize 20-year service life specifications for perimeter fencing and working facilities. Montana Department of Livestock regulations align with federal baselines while emphasizing snow-load structural ratings. The Billings-Great Falls axis concentrates large-scale cattle operations with annual volume agreements.
Colorado
Denver-Boulder metro expansion creates specification for architectural-grade finishes at premium equestrian training facilities. Pending state equine welfare standards extend rail spacing and height mandates beyond USDA requirements. The Colorado Front Range corridor drives fastest-growing demand for modular reconfigurable systems.
California
Proposition 12 implementation and advanced animal welfare codes create compliance complexity for national suppliers. Equestrian centers in Southern California and Central Valley regions specify preemptive compliance to accommodate interstate client horses. Napa-Sonoma wine country estates generate niche demand for decorative architectural installations.
Horse Corral Panels Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement pathways. Large Texas fabricators with captive tube-forming capacity negotiate direct annual volume agreements with Montana cattle ranches. Regional agricultural supply houses retain fragmented hobby farm and small ranch segments. Two strategic archetypes dominate: integrated manufacturers with in-house coating and forming operations, and specialized distributors with broad SKU coverage. Competitive moves center on backward integration into raw steel supply and geographic expansion through regional distributor acquisition.
Among Texas-based integrated manufacturers, Priefert Manufacturing and Behlen Country exemplify the captive-capacity archetype. Tarter Farm and Ranch Equipment represents the broad-coverage distributor model with extensive portable and permanent configuration ranges. These three companies anchor the competitive set referenced in procurement decisions across Texas, Oklahoma, and Montana ranch operations.
| Leading Market Players |
|---|
| Tarter Farm and Ranch Equipment |
| Priefert Manufacturing |
| Behlen Country |
| Red River Arenas |
| Hutchison |
| CageCo |
| CountryLine |
| Cactus Horse Corrals |
| WW Manufacturing |
| Others |
Supply & Pricing Matrix
Hot-rolled coil supply concentration in domestic US steel mills anchors margin distribution downstream, with Texas-based fabricators capturing value through captive tube-forming capacity while regional distributors absorb price volatility exposure.
Pricing Analysis
Annual cost-plus contracts with CRU hot-rolled coil indexation dominate procurement between Montana cattle ranches and Texas manufacturers, transferring raw material risk to buyers. Three-tier pricing structure across premium architectural, standard commercial, and economy portable levels separates California-compliant specifications from federal-baseline SKUs. Cost compression in economy portable tiers is intensifying because high-tensile polymer mesh substitutes erode entry-level steel demand. Hobby farmers and small mixed-livestock operations exhibit highest price sensitivity, while Front Range equestrian centers prioritize specification compliance over unit cost.
Supply Chain Analysis
Tariff exposure between US and select steel-producing nations dominates supply chain risk assessment for fabricators dependent on specialized alloy grades. Production gravity centers on Texas, Oklahoma, and Montana, with raw material draws from domestic hot-rolled coil mills and powder-coating chemical suppliers. Single-source vulnerability concentrates in automated electrostatic coating line equipment, where German and Italian machinery suppliers command extended lead times. Distribution runs through direct fabricator agreements for large-scale ranchers and agricultural supply house networks for fragmented small-farm demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Substitution defense against high-tensile polymer mesh alternatives requires incumbents to articulate steel's structural superiority and service-life economics to specification-sensitive buyers.
For Market Incumbents: Insulate permanent installation share by deepening backward integration into tube forming and powder-coating chemicals, eliminating margin leakage to coating suppliers. Secure ASTM certification breadth to preempt California and Colorado regulatory divergence from fragmenting SKU portfolios. Polymer mesh substitution in temporary containment applications represents the priority threat requiring active specification defense. For New Entrants and Emerging Players: Aluminum-steel hybrid portable panels for professional rodeo contractors represent the most penetrable entry point, with weight-optimized transport economics displacing legacy steel configurations. Colorado Front Range equestrian corridor expansion creates specification demand for architectural-grade finishes where premium positioning sustains margin. Direct contractor relationships bypass entrenched distributor relationships. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across automated coating line installations, favoring scaled incumbents with existing captive capacity. Target acquisition archetypes include regional fabricators with USDA certification and established Montana ranch relationships. The signal to watch is California Proposition 12 enforcement intensity as compliance cost escalation indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tube Forming | Captive hot-rolled coil processing eliminates margin leakage to intermediate suppliers. |
| California Compliance SKU Expansion | Proposition 12 rail-spacing mandates require parallel inventory for multi-state distributors. |
| Aluminum-Steel Hybrid Development | Weight reduction addresses professional rodeo contractor transport cost priorities. |
| Direct Ranch Procurement Channel | Annual volume agreements with Montana operations bypass distribution markups. |
| ASTM Certification Investment | Load-bearing testing protocols secure specification-driven project access. |
Research Methodology
Initial hypotheses were tested against primary input from ranch procurement directors, equestrian center facility managers, powder-coating line operators, and agricultural supply house buyers and refined through secondary validation. Ranch consolidation patterns, USDA facility guideline enforcement timelines, and ASTM certification databases anchored quantitative triangulation. Bottom-up panel demand estimates from Texas, Oklahoma, and Montana operations converged with top-down corral infrastructure investment flows.
Demand-supply-balance modeling across material type, installation configuration, and end-user sophistication dimensions structured the analytical framework throughout the forecast period. CAGRs derived from installed base replacement cycles and feedlot expansion pipelines, with sensitivity testing against hot-rolled coil price volatility and California regulatory adoption curves. Segment-level growth trajectories incorporated modular arena reconfiguration demand and aluminum portable adoption rates.
Macroeconomic conditions sit as an overlay; deviation in steel input costs, livestock commodity prices, or interstate animal welfare standard harmonization would shift the trajectory. Forecasts reflect documented assumptions on ranch consolidation pace and coating automation diffusion. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Livestock Equipment
Slaughtering Equipment Market
Livestock Equipment
Livestock Monitoring System Market
Livestock Equipment
Goat Creep Feeder Market
Livestock Equipment
Animal Cage Market
Livestock Equipment
Cattle Handling Systems Market
Livestock Equipment
Automated Feeding System Market
Livestock Equipment
Livestock Identification Market
Livestock Equipment
Automatic Goat Waterer Market
Livestock Equipment
Livestock Panel Gates Market
Livestock Equipment
Silage Tube Market
Livestock Equipment
Cattle Grooming Chute Market
Livestock Equipment
Horse Stable Supplies Market
Livestock Equipment
Sheep Supplies Market
Livestock Equipment
Sheep Tilt Table Market
Livestock Equipment
Canada Horse Riding Equipment Market
Livestock Equipment
Animal Feed Mixer Market