
 Sheep Handling Equipment Market | 2026-2036
Sheep Handling Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Sheep Handling Equipment Market Analytics
Commercial feedlot operations is hardening as the dominant demand vertical, displacing traditional small-farm procurement across major sheep-producing regions. Gallagher leverages its trans-Tasman distribution network to sustain channel control in Australia and New Zealand. Tru-Test anchors its position through technology leadership in electronic weighing and data-capture integration. Ritchie Agricultural competes on manufacturing scale, with Scottish fabrication facilities supplying high-volume chute orders across the British Isles.
Sheep handling equipment encompasses mechanical and electromechanical systems designed to constrain, direct, weigh, shear, or medically process ovines, typically fabricated from galvanized steel or aluminum with working-load ratings exceeding 500 kg per unit. These systems reduce animal stress, handler injury incidence, and labor hours during high-frequency operations such as drenching, dagging, and drafting. Chutes and handling gates capture the largest installed base, though shearing equipment commands the deepest margin pools due to precision-engineered blade metallurgy and replacement-part dependency. Steel dominates material selection for permanent infrastructure, while high-density polyethylene gains share in portable yard systems where weight reduction determines transport economics.
FDA guidelines on veterinary pharmaceutical residue testing shape equipment design, as integrated drench guns and injectors must meet calibration traceability standards. Australian Work Health and Safety regulators enforce crush-protection protocols that dictate gate-latch geometry and hydraulic-pressure limits. CE marking under EU machinery directives restricts market access for non-conforming imports, creating compliance barriers for smaller fabricators. Stakeholders must monitor how carbon-border adjustments and scrap-steel pricing volatility reshape material cost structures and sourcing geography.
Market Dynamics
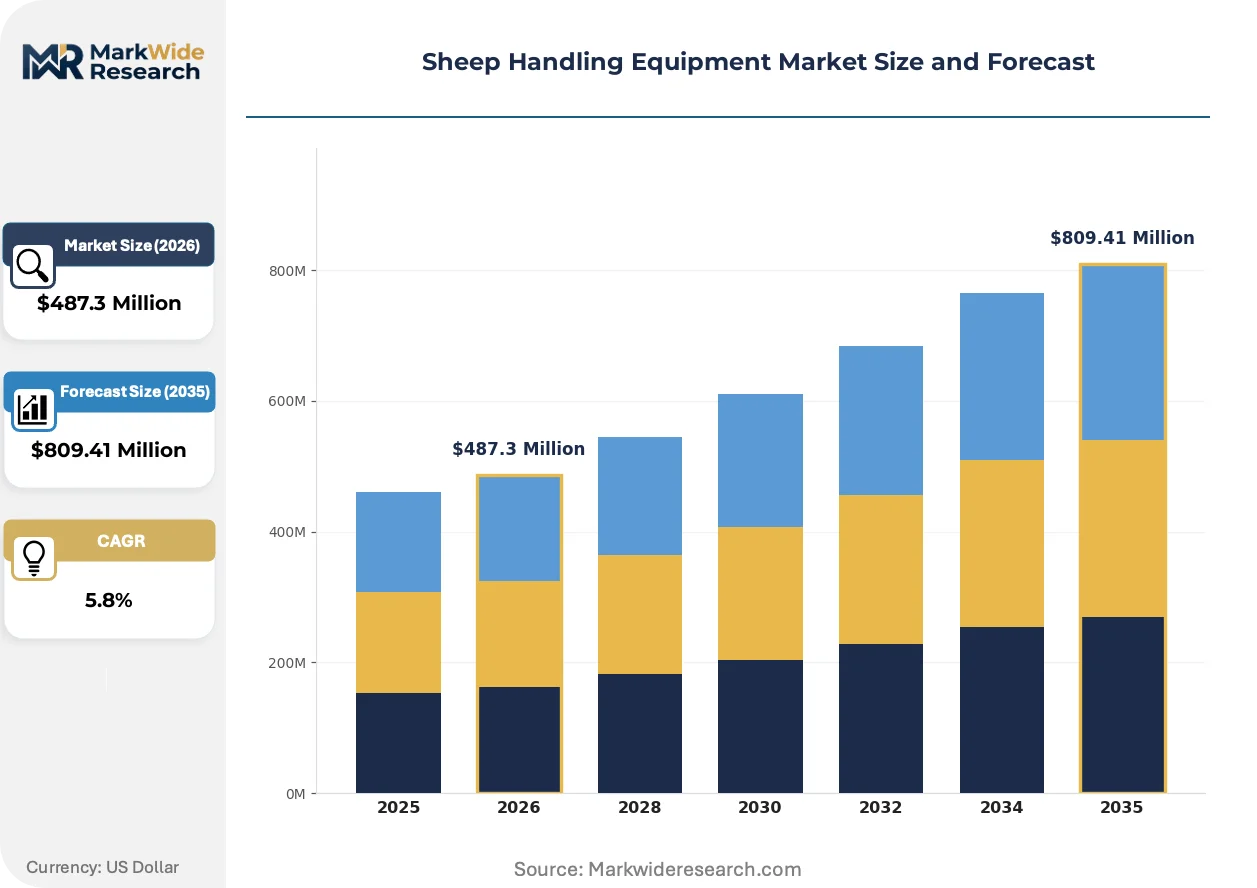
Commercial feedlot consolidation across Australia's New South Wales corridor is compressing replacement cycles and hardening specifications for automated handling systems as labor costs climb and operator liability exposure widens.
Growth Catalysts
- CE marking machinery directives:European Union safety mandates for crush-resistant gate designs are accelerating equipment refresh rates among British Isles fabricators and their export customers.
- Electronic data-capture integration:Commercial stations are retrofitting chutes with RFID-linked weighing systems to meet veterinary pharmaceutical traceability requirements under FDA residue-testing protocols.
- New South Wales station consolidation:Large-scale commercial operators in this corridor are standardizing on high-capacity hydraulic drafting systems, displacing traditional small-farm procurement.
Market Restraints
- Scrap-steel pricing volatility:Galvanized steel fabrication costs fluctuate with commodity markets, squeezing margin pools for permanent infrastructure manufacturers.
- TGA crush-protection protocol compliance:Australian Work Health and Safety gate-latch geometry and hydraulic-pressure specifications extend engineering cycles for non-domestic suppliers.
- High-density polyethylene substitution:Portable yard systems fabricated from HDPE reduce transport costs for seasonal operators, limiting addressable demand for steel-intensive permanent installations.
Strategic Opportunities
- Carbon-border adjustment positioning:EU Green Deal compliance requirements create first-mover advantage for fabricators with verified low-emission steel sourcing and energy-efficient hydraulic designs.
- Shearing equipment aftermarket:Precision-engineered blade metallurgy and replacement-part dependency generate recurring revenue streams deeper than chute and gate sales.
- Remote monitoring convergence:Integration of IoT load-cell diagnostics with cloud-based herd management platforms opens subscription revenue models for handling-system OEMs.
Industry Challenges
- Hydraulic-system technician scarcity:Commercial feedlots struggle to source certified maintenance personnel for automated chute systems in rural Australian corridors.
- CE marking certification timelines:European conformity assessment procedures for novel electromechanical designs delay market entry by 8-14 months for non-EU fabricators.
- Legacy yard reconfiguration:Existing permanent steel infrastructure constrains retrofit compatibility with modular automated drafting components.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sheep Handling Equipment Market |
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $809.41 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chutes, Crates, Shearing Equipment, Handling Gates Material: Steel, Aluminum, High-Density Polyethylene, Wood End User: Farmers, Feedlots, Veterinarians, Agricultural Cooperatives Size: Small-Scale Farms, Medium-Sized Farms, Large-Scale Farms, Commercial Operations |
| Companies Covered | Colorado Lamb & Wool, Gallagher, Tru-Test, Sheepmaster, Premier 1 Supplies, Ritchie Agricultural, Kerbl, Murray Farmcare Ltd., Real Tuff Livestock Equipment, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sheep Handling Equipment Market Evolving Landscape
Equipment design is bifurcating between heavy-gauge permanent infrastructure for consolidated commercial stations and lightweight portable systems for seasonal contractors, with digital integration becoming the non-negotiable specification across both categories.
Aluminum framing is absorbing share in portable handling systems where weight reduction determines transport economics between seasonal grazing properties. Contract shearing crews operating across New Zealand's South Island are standardizing on aluminum chutes that cut trailer payload by 40 percent versus galvanized steel equivalents. This material shift is absorbing demand from traditional steel fabricators and compressing addressable market scope for permanent-yard specialists.
EU machinery safety directives under CE marking now mandate documented failure-mode analysis for hydraulic crush systems, forcing design teams to embed pressure-relief redundancy and emergency manual overrides. Scottish fabrication facilities serving the British Isles market have retooled welding protocols to meet these traceability requirements. High-volume chute orders from Irish commercial stations now specify EN ISO 12100-compliant risk assessment documentation as a contract precondition.
Buyer concentration among large-scale station operators is consolidating procurement authority into centralized technical committees that unbundle after-sales service from equipment purchase. New South Wales commercial feedlots now negotiate separate maintenance contracts with regional hydraulic service networks rather than OEM service departments. This pattern is most visible across Australia's eastern seaboard, where station consolidation has reduced the number of decision-making entities by half over the past decade.
Sheep Handling Equipment Market Segmentation
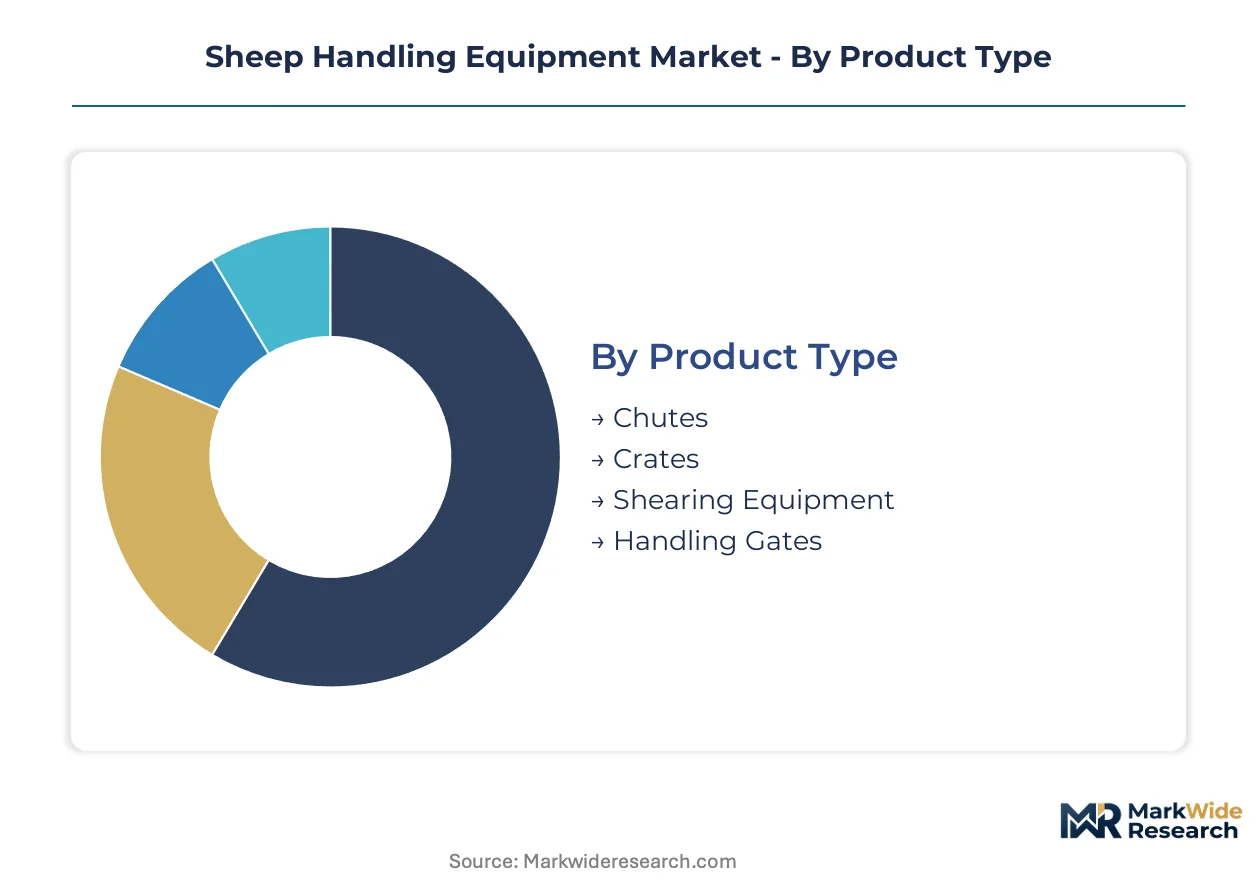
Sheep handling equipment procurement patterns diverge sharply across operational scale and mobility requirements. Equipment specifications harden with farm size, while material selection tracks transport frequency and climate exposure.
Product Type:
Customization intensity ranges from standardized gate assemblies to fully integrated hydraulic systems with telemetry integration.
- Chutes:Galvanized steel or aluminum fabrication with working-load ratings exceeding 500 kg, designed for high-throughput drafting and drenching operations. Australian commercial feedlots in New South Wales specify hydraulic-actuated models with RFID-linked load cells to meet TGA pharmaceutical traceability protocols. CE marking compliance for crush-resistant designs now extends engineering cycles for British Isles fabricators.
- Handling Gates:Modular panel systems fabricated from heavy-gauge steel or HDPE, configured into yard layouts for flock direction and isolation. Consolidated stations across Australia's eastern seaboard drive replacement demand for automated latch mechanisms that reduce operator injury exposure under Work Health and Safety regulations.
- Shearing Equipment:Precision-engineered blade systems with replacement-part dependency generating recurring revenue.
- Crates:Portable restraint units for individual animal medical processing and veterinary examination.
Most installed capacity flows through Chutes. Expansion is steepest in Handling Gates.
Material:
Cost tier stratification separates permanent infrastructure investments from seasonal contractor mobility requirements.
- Steel:Galvanized heavy-gauge fabrication dominates permanent yard infrastructure, with crush-resistant gate designs mandated under EU machinery directives. Scottish fabrication facilities supply high-volume chute orders across the British Isles, though scrap-steel pricing volatility compresses margin pools.
- High-Density Polyethylene:Rotationally molded panels cut transport weight by 40 percent versus steel equivalents, absorbing demand from New Zealand contract shearing crews operating across South Island seasonal grazing properties. HDPE substitution limits addressable demand for steel-intensive permanent installations among mobile operators.
- Aluminum:Framing systems for portable chutes where payload reduction determines trailer economics.
- Wood:Legacy construction material retaining niche presence in low-budget or traditional farmstead applications.
Steel retains the deepest installed base. HDPE is gaining share fastest among seasonal contractors.
End User:
Customer type determines specification complexity and after-sales service bundling.
- Feedlots:Commercial operations with centralized procurement authority negotiating unbundled maintenance contracts with regional hydraulic service networks rather than OEM service departments. New South Wales station consolidation has halved decision-making entities across Australia's eastern seaboard over the past decade.
- Farmers:Dispersed small-holdings with price-sensitive procurement patterns and legacy yard reconfiguration constraints.
- Veterinarians:Specialized practitioners requiring portable restraint equipment with pharmaceutical residue testing calibration traceability.
- Agricultural Cooperatives:Pooled purchasing entities standardizing equipment specifications across member operations.
Feedlots command the steepest specification escalation. Farmers represent the broadest addressable base.
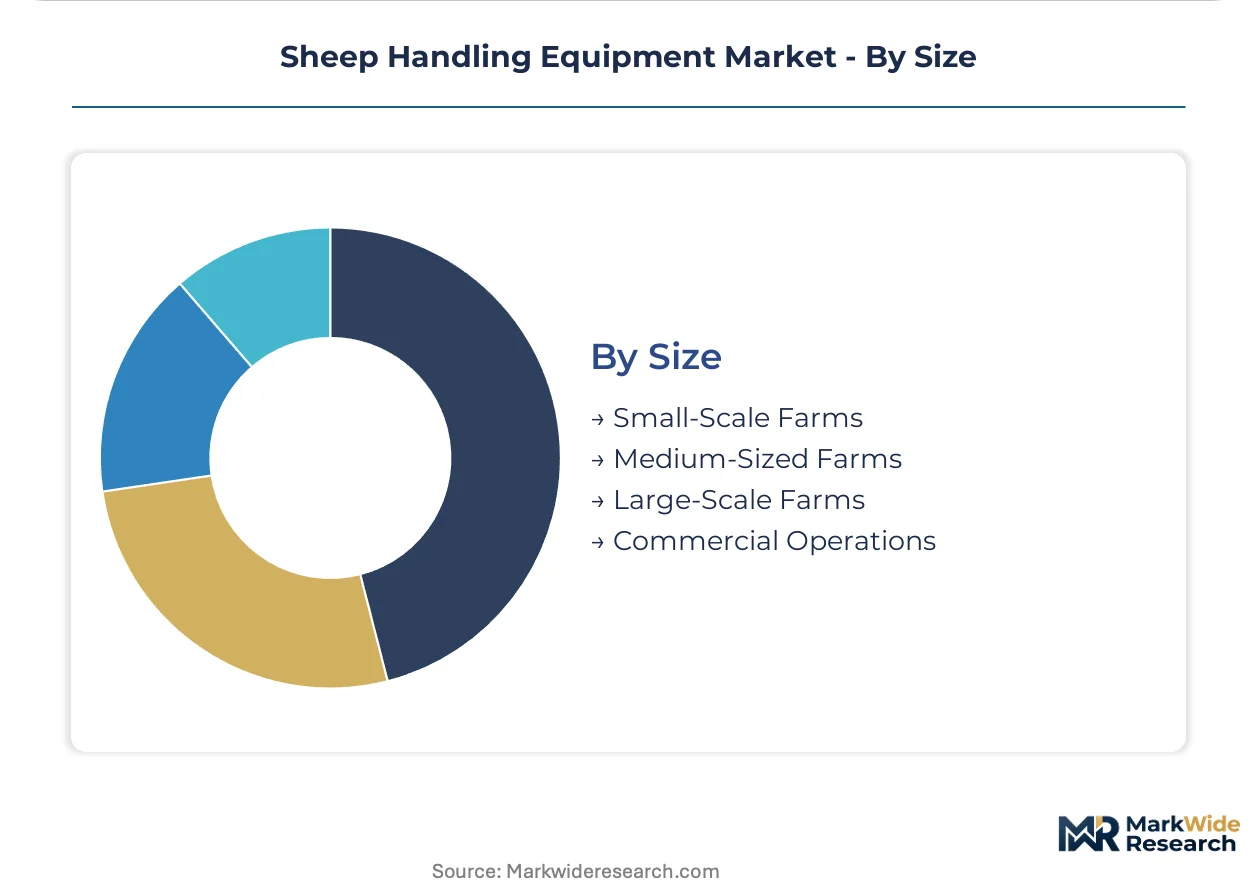
Size:
Operational scale directly dictates automation level and capital intensity per animal unit.
- Commercial Operations:Large-scale stations standardizing on high-capacity hydraulic drafting systems with IoT load-cell diagnostics and cloud-based herd management integration. These operators drive specification hardening as labor costs climb and operator liability exposure widens across Australian corridors.
- Large-Scale Farms:Properties with sufficient throughput to justify semi-automated chute investments but lacking centralized technical committees.
- Medium-Sized Farms:Operations balancing equipment durability against capital constraint, often selecting modular components for phased yard upgrades.
- Small-Scale Farms:Holdings with manual handling systems and extended replacement cycles, increasingly displaced from manufacturer priority segments.
Commercial Operations absorb the premium technology pipeline. Medium-Sized Farms present the contested middle ground for supplier positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping manufacturing footprints as fabricators relocate to jurisdictions with lower compliance burdens while maintaining CE marking access through modular assembly strategies. Production migration follows divergent labor-cost trajectories and machinery-safety enforcement intensity across major sheep-producing economies.
Australia
Commercial feedlot consolidation across New South Wales is compressing equipment replacement cycles as station operators standardize on high-capacity hydraulic drafting systems. TGA crush-protection protocols under Work Health and Safety regulations mandate specific gate-latch geometries and hydraulic-pressure limits that extend engineering validation for imported systems. The New South Wales corridor from Dubbo to Wagga Wagga anchors domestic demand, with centralized technical committees now unbundling maintenance contracts from equipment procurement.
New Zealand
Contract shearing crews operating across seasonal grazing properties are driving aluminum-framed portable system adoption to cut trailer payload by 40 percent versus steel equivalents. The country's agricultural safety regulator enforces operator injury-prevention standards that shape restraint equipment specifications. South Island seasonal operators concentrate demand in Canterbury and Otago regions, where mobility requirements override permanent infrastructure investment.
United Kingdom
Scottish fabrication facilities serving the British Isles market have retooled welding protocols to meet EN ISO 12100-compliant risk assessment documentation now mandatory under CE marking machinery directives. Irish commercial stations specify crush-resistant gate designs with documented failure-mode analysis as contract preconditions. Fabrication clusters in Scotland and Northern England supply high-volume chute orders, though certification timelines delay market entry for non-EU component suppliers.
United States
FDA veterinary pharmaceutical residue-testing protocols shape integrated drench gun and injector calibration requirements, driving RFID-linked data-capture retrofit demand among commercial wool operations. OSHA agricultural safety standards influence handler injury-prevention specifications for automated restraint systems. Western range states including Texas and Colorado concentrate feedlot-scale procurement, though fragmented land ownership patterns limit consolidation velocity compared to Australian benchmarks.
Germany
EU Green Deal carbon-border adjustment mechanisms are creating first-mover advantage for fabricators with verified low-emission steel sourcing and energy-efficient hydraulic designs. CE marking compliance under machinery directives restricts market access for non-conforming imports, elevating domestic fabrication competitiveness. Agricultural machinery clusters in Bavaria and Baden-Württemberg are integrating IoT load-cell diagnostics with cloud-based herd management platforms to capture subscription revenue models.
Sheep Handling Equipment Market Competitive Landscape
Technology licensing dominates the current landscape as specialist fabricators partner with electronics OEMs to embed RFID and telemetry capabilities without captive semiconductor development. The vendor base stratifies across three tiers: integrated multinational agricultural equipment groups with trans-Tasman distribution networks; regional steel fabricators with CE marking certification capabilities; and portable-system specialists exploiting aluminum and HDPE material substitution. Portfolio diversification and geographic expansion through distribution partnerships represent the dominant competitive vectors, with backward integration into precision-machined components emerging as a secondary thrust.
Within the integrated multinational tier, Gallagher and Tru-Test exemplify divergent positioning archetypes—one leveraging trans-Tasman channel control, the other anchoring technology leadership in electronic data-capture integration. Ritchie Agricultural occupies a position among European-scale fabricators with Scottish production assets serving CE marking-mandated demand across the British Isles. These three entities represent the competitive spectrum from distribution-intensive to technology-differentiated to manufacturing-scale positioning.
| Leading Market Players |
|---|
| Colorado Lamb & Wool |
| Gallagher |
| Tru-Test |
| Sheepmaster |
| Premier 1 Supplies |
| Ritchie Agricultural |
| Kerbl |
| Murray Farmcare Ltd. |
| Real Tuff Livestock Equipment |
| Others |
Value Network & Pricing Analysis
EU Green Deal carbon-border adjustment mechanisms gate qualified supply for premium-tier equipment, restricting market access to fabricators with verified low-emission steel sourcing and documented EN ISO 12100-compliant risk assessments. This environmental mandate compresses margin pools for non-compliant competitors while elevating pricing power among certified suppliers serving commercial feedlot procurement committees.
Pricing Analysis
Distributor margins of 15-25 percent separate factory-gate equipment from end-user pricing across Australian and British Isles channels. Three-tier pricing structure across premium, standard, and economy levels tracks CE marking certification status, hydraulic system complexity, and after-sales service bundling. Pricing pressure stems from scrap-steel commodity volatility squeezing permanent infrastructure manufacturers. Small-scale farmers exhibit highest price sensitivity, while consolidated New South Wales commercial stations prioritize specification compliance over unit cost.
Supply Chain Analysis
Freight costs for aluminum-framed portable systems run 40 percent below steel equivalents, reshaping material economics for seasonal New Zealand contractors. Manufacturing concentrates in Scotland for CE marking-mandated British Isles demand, Australia for TGA-compliant domestic supply, and Bavaria for EU Green Deal-certified production. Galvanized steel feedstock, precision-machined hydraulic components, and RFID sensor modules constitute critical input dependencies. Single-source vulnerability concentrates in semiconductor-dependent load-cell diagnostics. Distribution runs through trans-Tasman agricultural equipment networks and regional hydraulic service partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where CE marking machinery directives and TGA crush-protection protocols continuously escalate equipment specifications and replacement demand.
For Market Incumbents: Lock in channel control through exclusive maintenance contracts with New South Wales commercial feedlots, displacing unbundled regional hydraulic service networks. Deepen backward integration into precision-machined blade metallurgy for shearing equipment aftermarket capture. CE marking certification timelines for novel electromechanical designs represent the critical barrier against Asian fabrication entrants. For New Entrants and Emerging Players: IoT-enabled remote diagnostics platforms offer a technology-first wedge into the underserved medium-sized farm segment lacking centralized technical committees. Target aluminum-framed portable system white space across New Zealand South Island seasonal operators. Pursue veterinary pharmaceutical traceability retrofit contracts as the lowest-resistance go-to-market path. For Investors and Strategic Acquirers: Roll-up economics work for regional steel fabricators with dormant CE marking capabilities because EU machinery safety directives are compressing viable supplier counts. Five-to-ten year viability hinges on carbon-border adjustment positioning. Acquisition target archetype: Scottish or Northern English fabrication assets with EN ISO 12100 documentation infrastructure. Signal to watch: Irish commercial station tender specifications mandating crush-resistant gate designs with documented failure-mode analysis.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Certification Investment | Scottish fabrication facilities retooled welding protocols to capture Irish commercial station contracts. |
| Backward Integration into Blade Metallurgy | Precision-engineered shearing components generate recurring revenue deeper than chute sales. |
| IoT Load-Cell Diagnostics Integration | Bavarian clusters embed cloud-based herd management to capture subscription revenue models. |
| Aluminum Framing Capacity Expansion | New Zealand South Island contractors cut trailer payload by 40 percent versus steel equivalents. |
| Regional Hydraulic Service Partnership | New South Wales feedlots unbundle maintenance from OEM service departments. |
Research Methodology
Multiple input streams — structured interviews with commercial feedlot procurement directors, agricultural equipment distributors, and hydraulic system technicians, alongside regulatory filings from TGA and CE marking conformity bodies — were reconciled against customs trade data, SEC filings of listed agricultural equipment groups, and industry association production statistics. Bottom-up equipment shipment tracking and top-down macroeconomic agricultural investment indicators provided triangulation anchors.
Historical volume trajectories were cross-referenced against expert panel assessments of replacement cycle compression and consolidation velocity across the projection horizon. Segmentation modeling captured product type, material substitution patterns, operational scale tiers, and regional regulatory clusters. CAGRs derived from fitted growth curves incorporating labor cost trajectories, safety mandate implementation schedules, and commodity input price assumptions.
The model holds under continued regulatory enforcement intensity and feedlot consolidation momentum; deviation in scrap-steel pricing stability or CE marking certification delays would shift equipment refresh timing. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Livestock Equipment
Starter Feed Market
Livestock Equipment
China Horse Riding Equipment Market
Livestock Equipment
Goat Creep Feeder Market
Livestock Equipment
Livestock Carrier Market
Livestock Equipment
Livestock Farm Equipment Market
Livestock Equipment
Wire Livestock Panels Market
Livestock Equipment
Robotics Milking Systems Market
Livestock Equipment
Livestock Trailers Market
Livestock Equipment
Rabbit Hutches Market
Livestock Equipment
Milking Equipment Market
Livestock Equipment
Chicken Coop Market
Livestock Equipment
Nigeria Horse Riding Equipment Market
Livestock Equipment
Goat Handling Equipment Market
Livestock Equipment
Livestock Monitoring System Market
Livestock Equipment
Cattle Farm Equipment Market
Livestock Equipment
Cow Lifting Harness Market