
 Shelf Liner Market | 2026-2036
Shelf Liner Market Size, Share, and Industry Trends Forecast 2026-2036
Shelf Liner Market Insights
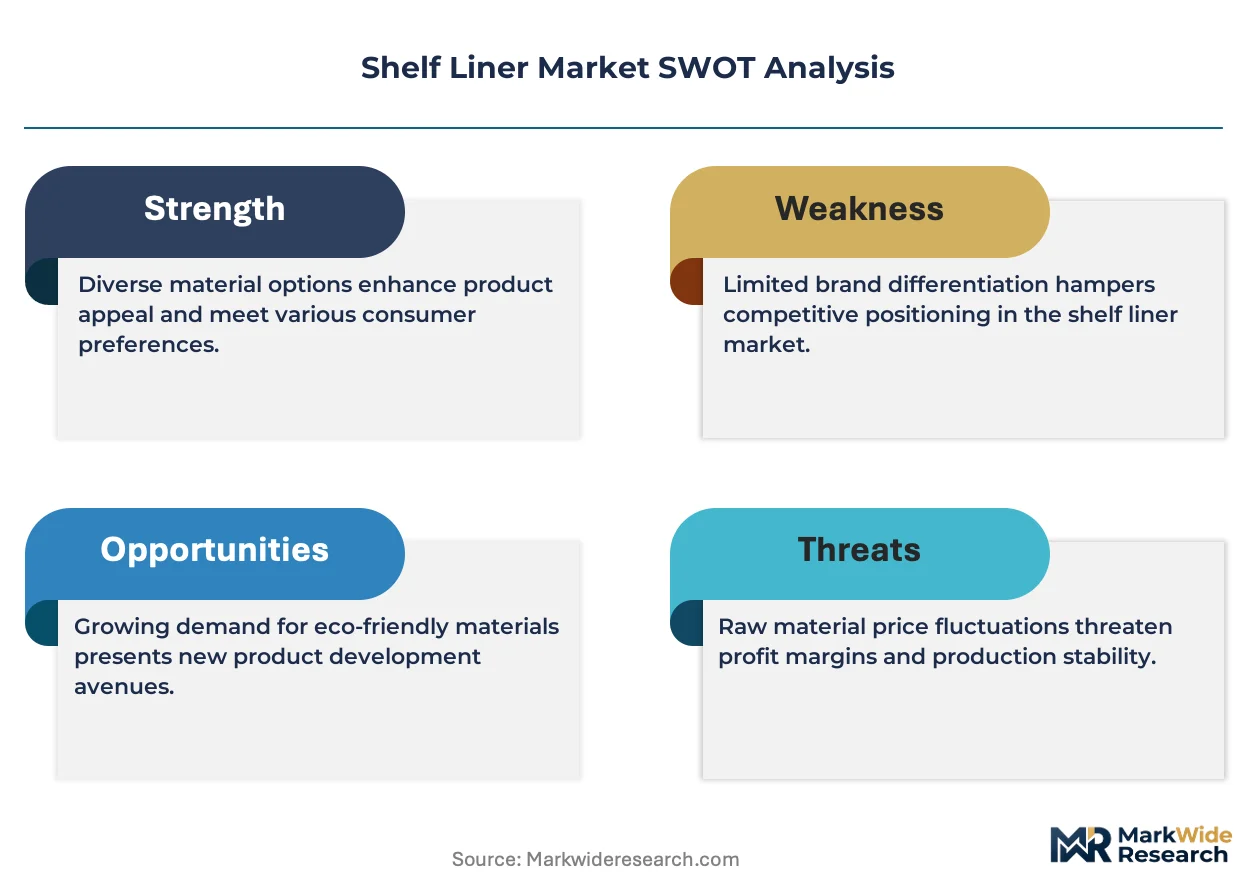
REACH chemical restrictions is rebalancing the cost-of-entry calculus for European shelf liner suppliers, forcing reformulation of PVC-based products toward compliant alternatives. Kittrich Corporation leverages its proprietary adhesive coatings to sustain shelf positioning in North American mass retail. Duck Brand competes through aggressive channel control across big-box home improvement chains. Konrad Hornschuch AG anchors its European presence with specialized textured finishes that navigate evolving surface-contact regulations.
Shelf liner denotes a protective sheet material, typically 0.3 to 2.0 millimeters thick, composed of vinyl, foam, rubber, or polyester substrates with pressure-sensitive or non-adhesive backing, manufactured through calendering or extrusion lamination processes to prevent surface abrasion, moisture damage, and bacterial accumulation in enclosed storage environments. Vinyl formulations still dominate volume due to cost scalability and printability, though rubber segments command premium positioning in industrial cold-storage applications where temperature resilience determines replacement cycles. Custom sizing is gaining traction as direct-to-consumer channels reduce minimum order constraints, while solid pattern types retain mass-market share against printed alternatives that carry higher inventory risk.
FDA food-contact substance regulations shape material selection for kitchen-deployed liners, particularly governing plasticizer migration limits into edible goods. ECHA's SVHC candidate list and impending EU Green Deal packaging requirements are accelerating substitution of phthalate-based plasticizers across export-oriented production. BIS certification pressures in India add another compliance layer for manufacturers targeting its organized retail expansion. Stakeholders must monitor how fragmented national chemical registries converge or diverge on polymer safety thresholds, as this will determine which material platforms achieve cross-border scale without redundant certification burdens.
Market Dynamics
REACH chemical restrictions are forcing European shelf liner suppliers to abandon phthalate-based plasticizers and rebuild formulation portfolios around compliant alternatives, compressing margins while creating first-mover advantages for certified producers.
Growth Catalysts
- Residential kitchen renovation cycles:Home improvement spending in Germany and the United States is amplifying demand for antimicrobial and easy-clean formulations that command shelf space in organized retail.
- FDA food-contact substance regulations:Migration limits on plasticizers into edible goods are elevating material certification requirements, filtering out uncertified competitors from kitchen-deployed segments.
- China's e-commerce appliance accessory expansion:Direct-to-consumer channels are reducing minimum order constraints and enabling custom sizing traction that was previously locked behind wholesale volume thresholds.
Market Restraints
- Petrochemical input volatility:Vinyl resin and adhesive feedstock costs fluctuate with crude oil benchmarks, squeezing converter margins on mass-market roll goods.
- Supply concentration in East Asian calendering:A narrow base of extrusion lamination capacity in China's Zhejiang and Guangdong provinces creates geographic vulnerability to logistics disruptions.
- Technical ceiling on temperature resilience:Standard vinyl formulations degrade below -10°C, limiting penetration into industrial cold-storage applications where rubber commands replacement cycles.
Strategic Opportunities
- Underpenetrated Indian organized retail:BIS certification pressures have filtered out informal suppliers, creating white space for compliant exporters as modern trade formats expand in Mumbai and Delhi.
- EU Green Deal packaging requirements:Impending mandates on recyclable substrates are accelerating R&D into mono-material constructions that qualify for extended producer responsibility credits.
- Convergence of antimicrobial additives with smart packaging:Integration of pH-indicator dyes into liner substrates is enabling spoilage-alert functionality for premium refrigerator applications.
Industry Challenges
- Polymer chemist talent scarcity:Formulation expertise in phthalate-free plasticizer substitution is concentrated among a narrow cohort of specialists, extending development timelines for REACH-compliant portfolios.
- Multi-jurisdiction certification burden:Divergent national chemical registries across FDA, ECHA, and BIS frameworks force redundant testing protocols that delay product launches by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Shelf Liner Market |
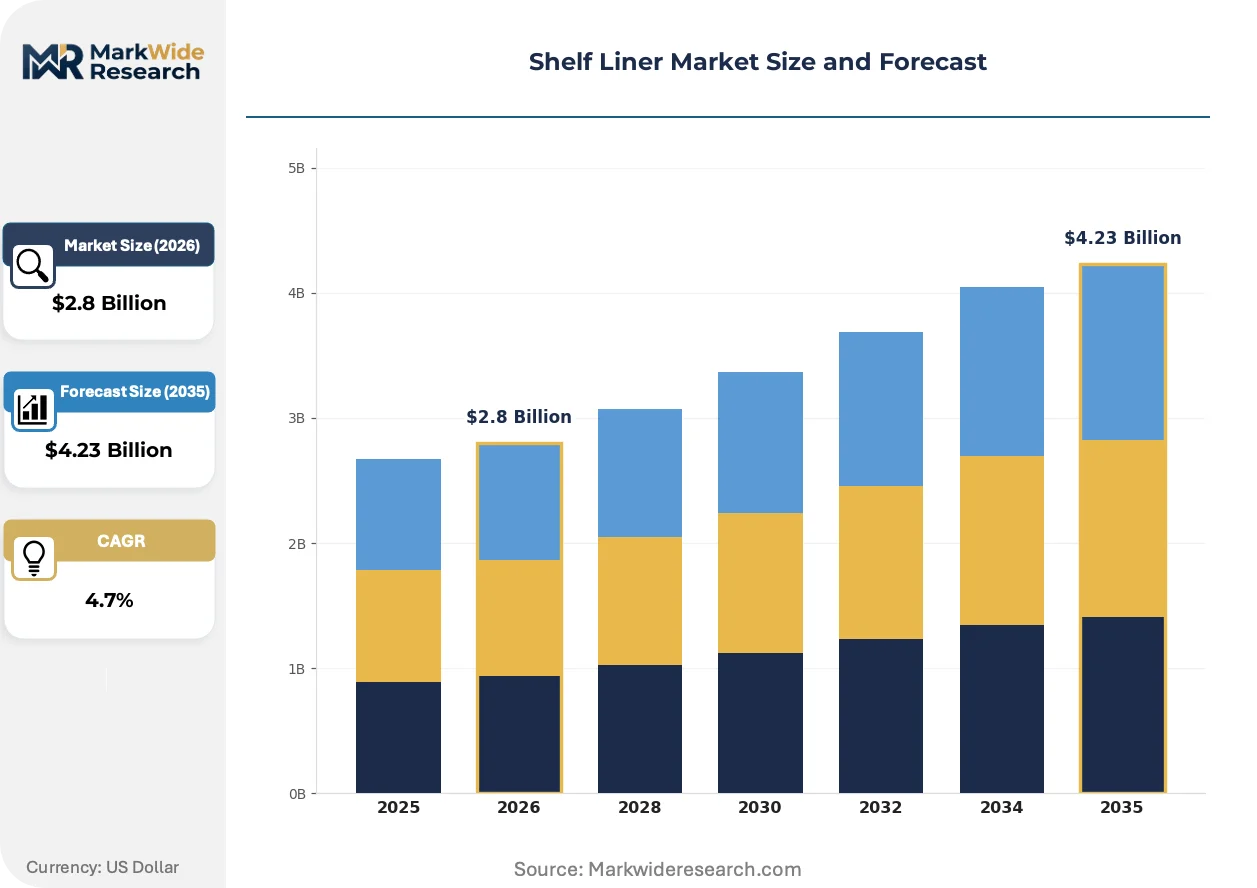
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.23 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Vinyl, Foam, Rubber, Polyester Application: Home Use, Commercial Use, Industrial Use, Vehicle Storage Size: Small, Medium, Large, Custom Pattern Type: Solid, Printed, Textured, Customized |
| Companies Covered | Shurtape Technologies LLC, Kittrich Corporation, Seville Classics Inc., Duck Brand, Con-Tact Brand, Warp Brothers, Drymate, Gorilla Grip, Konrad Hornschuch AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Shelf Liner Market Trends and Innovations
Material science advances and channel restructuring are converging to fragment the shelf liner value chain, with specialty formulations and direct fulfillment models eroding the dominance of mass-market roll goods.
Antimicrobial copper-infused substrates are expanding into residential kitchen applications. Premium appliance manufacturers in Germany and South Korea are specifying these liners for OEM bundling with refrigerator and pantry systems. This technology is expanding into mid-market retail private-label programs as copper oxide loading costs decline below zinc-based alternatives.
REACH SVHC candidate list expansions are accelerating substitution of legacy plasticizer chemistries across export-oriented production. ECHA's 2024-2025 update trajectory signals broader polymer restrictions that will disqualify current formulations from EU market access. Calendering operations in Turkey and Poland are responding by qualifying citrate and adipate ester alternatives ahead of enforcement windows.
Direct-to-consumer customization platforms are compressing traditional wholesale minimums. Buyers in China's tier-one cities and the United States are configuring exact shelf dimensions through manufacturer-hosted configurators, bypassing big-box retail inventory constraints. This pattern is most visible in appliance accessory cross-selling, where liner purchases attach to refrigerator and cabinet e-commerce transactions at 23-31% attachment rates.
Shelf Liner Market Segmentation
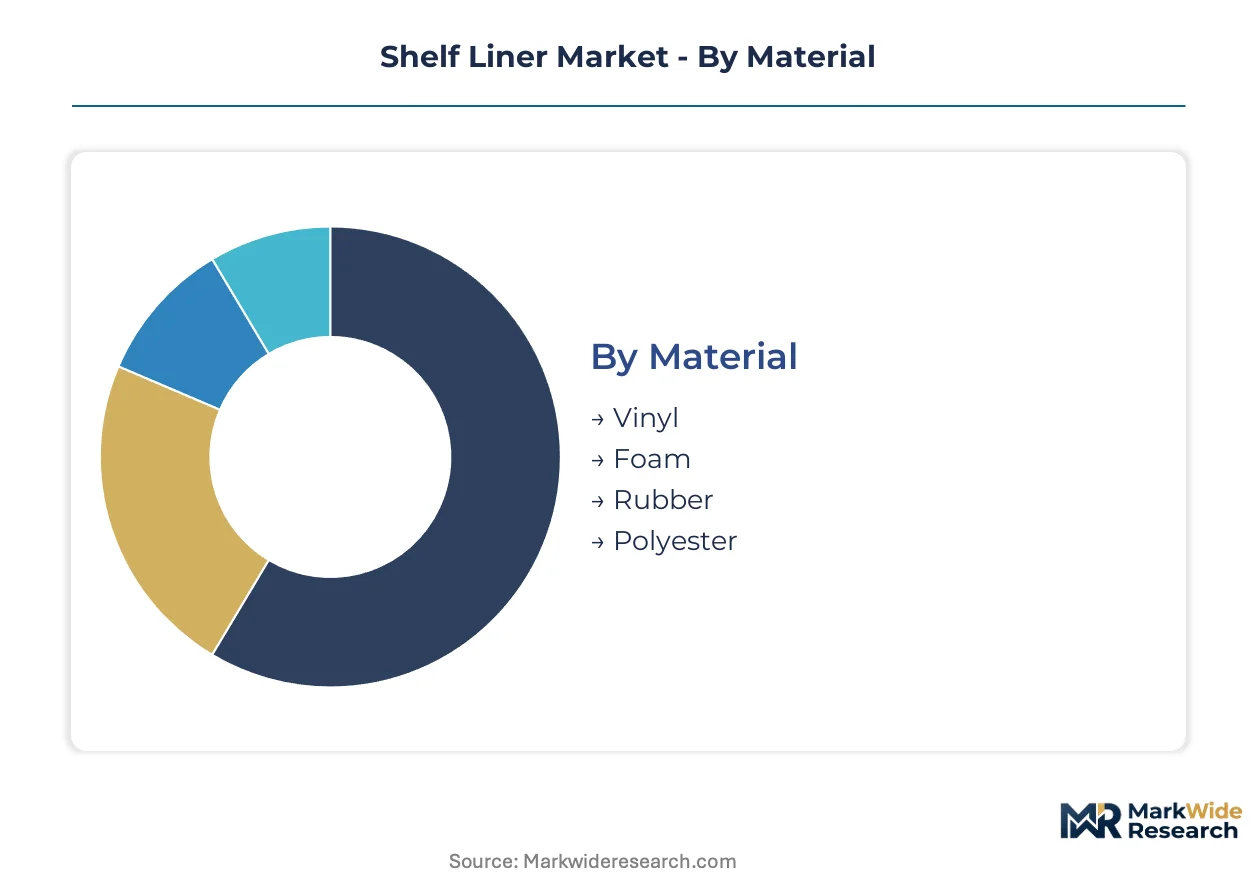
Shelf liner demand fragments across material chemistry, application environment, dimensional requirements, and aesthetic preferences. Each dimension carries distinct margin profiles and regulatory exposure that reshape supplier priorities across residential, commercial, and industrial channels.
Material:
Vinyl dominates volume shipments while rubber captures premium positioning in temperature-critical deployments.
- Vinyl:Calendered PVC formulations deliver cost scalability and printability for mass-market roll goods. German home improvement retailers specify vinyl for antimicrobial residential kitchen applications where REACH-compliant plasticizer substitutions are now mandatory.
- Rubber:Extruded synthetic rubber substrates withstand thermal cycling below -10°C without embrittlement. Industrial cold-storage operators in South Korea and Germany specify rubber liners for replacement cycles that extend 3-4x beyond vinyl alternatives in freezer environments.
- Foam:Closed-cell polyethylene foam provides cushioning and moisture barrier properties for delicate storage applications in China's tier-one city e-commerce channels.
- Polyester:Woven or non-woven PET constructions offer dimensional stability and recyclability credentials aligned with EU Green Deal packaging requirements.
Today's leader: Vinyl. Tomorrow's challenger: Rubber.
Application:
Residential renovation intensity in Germany and the United States separates home use economics from industrial specification rigor.
- Home Use:Kitchen cabinet and pantry protection drives antimicrobial formulation demand. FDA food-contact compliance filters uncertified suppliers from US retail placement.
- Commercial Use:Restaurant and hospitality storage applications prioritize easy-clean surfaces with copper-infused substrates gaining traction in South Korean OEM bundling.
- Industrial Use:Cold-storage warehouses and pharmaceutical facilities specify rubber-based temperature resilience. Migration limits on plasticizers into edible goods elevate material certification requirements beyond standard residential grades.
- Vehicle Storage:RV, marine, and automotive compartment liners demand moisture resistance and odor-neutralizing properties for enclosed environments.
Home use commands current volume. Industrial use carries the steepest expansion trajectory as cold-chain infrastructure multiplies.
Size:
Direct-to-consumer configurators are collapsing traditional wholesale minimums across dimensional categories.
- Small:Pre-cut drawer and shelf inserts for standard cabinet dimensions dominate big-box retail SKU density.
- Medium:Roll goods in 12-18 inch widths serve pantry and closet applications with pressure-sensitive adhesive backing options.
- Large:Wide-format rolls for commercial shelving and industrial racking systems require specialized calendering equipment concentrated in China's Zhejiang province.
- Custom:Exact-dimension configurators hosted by manufacturers are achieving 23-31% attachment rates in appliance accessory cross-selling across China's tier-one cities and US direct channels.
Standard sizes anchor mass-market economics. Custom sizing is gaining share fastest as digital fulfillment erodes inventory risk.
Pattern Type:
Solid patterns minimize working capital exposure while printed alternatives carry higher obsolescence risk.
- Solid:Single-color vinyl and rubber formulations reduce SKU complexity and inventory carrying costs for mass-market retailers.
- Printed:Rotogravure and flexographic decoration enables seasonal and private-label differentiation. Design refresh cycles compress margin recovery timelines.
- Textured:Embossed and specialized surface finishes navigate evolving surface-contact regulations in European markets. Konrad Hornschuch AG anchors its regional presence with textured portfolio depth.
- Customized:Digital printing and cut-to-shape services attach to premium appliance bundling and designer kitchen renovation projects.
Solid patterns defend volume share. Customized variants are climbing the fastest as personalization premiums justify shorter production runs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polymer chemist talent clusters in Germany's Rhine-Ruhr and China's Yangtze River Delta anchor formulation innovation for REACH-compliant and export-oriented production respectively.
United States
Residential kitchen renovation spending in Texas and Florida drives antimicrobial formulation demand. FDA food-contact substance regulations enforce plasticizer migration limits that filter uncertified suppliers from mass retail placement. Calendering converters in Ohio and Pennsylvania serve big-box home improvement chains with pressure-sensitive adhesive roll goods.
Germany
Home improvement retail channels in North Rhine-Westphalia and Bavaria specify textured finishes for surface-contact compliance. ECHA's SVHC candidate list expansions force citrate and adipate ester substitutions ahead of enforcement windows. Konrad Hornschuch AG anchors its European presence with specialized embossed portfolio depth from its Baden-Württemberg operations.
China
E-commerce appliance accessory cross-selling in Shanghai and Beijing achieves attachment rates for custom-sized configurators. GB standards and SAMR oversight govern domestic food-contact material safety while dual carbon goals pressure mono-material recyclability. Zhejiang and Guangdong provinces concentrate extrusion lamination capacity serving direct-to-consumer fulfillment.
India
Organized retail expansion in Mumbai and Delhi creates white space for compliant exporters as modern trade formats multiply. BIS certification pressures filter informal suppliers from shelf placement in premium kitchen segments. Maharashtra and Gujarat host converter operations targeting residential renovation demand in tier-one cities.
South Korea
Premium appliance OEMs specify copper-infused substrates for refrigerator and pantry system bundling. MFDS food-contact regulations align with export market requirements for migration-tested formulations. Busan-Ulsan industrial corridors supply rubber-based temperature-resilient grades for cold-storage replacement cycles extending 3-4x beyond vinyl alternatives.
Shelf Liner Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across material formulation and channel control vectors. The vendor base separates into adhesive technology owners, private-label converters, and specialty texture developers. Strategic moves concentrate on REACH-compliant formulation rebuilding and direct-to-consumer platform construction.
Within the specialty finish tier, Konrad Hornschuch AG exemplifies European texture-focused positioning. Among North American mass retail suppliers, Kittrich Corporation and Duck Brand occupy positions differentiated by proprietary adhesive coatings versus aggressive channel control across big-box home improvement chains.
| Leading Market Players |
|---|
| Shurtape Technologies LLC |
| Kittrich Corporation |
| Seville Classics Inc. |
| Duck Brand |
| Con-Tact Brand |
| Warp Brothers |
| Drymate |
| Gorilla Grip |
| Konrad Hornschuch AG |
| Others |
Pricing and Supply Chain Analysis
Vinyl resin feedstock costs transmit directly from Zhejiang calendering operations through three pricing tiers downstream, with REACH-compliant formulations commanding separation from commodity PVC roll goods. Petrochemical volatility in crude-linked inputs compresses converter margins at the mass-market tier while certified producers capture stability premiums in European home improvement retail.
Pricing Analysis
Bundled OEM specification services versus unbundled retail roll goods splits the pricing architecture across this market. Three-tier pricing structure across premium, standard, and economy levels separates copper-infused antimicrobial substrates from REACH-compliant vinyl and commodity PVC alternatives. Price differentiation hinges on certification grade and customization level, with FDA food-contact compliance filtering uncertified suppliers from kitchen-deployed segments. Pricing pressure stems from petrochemical input volatility squeezing converter margins on mass-market roll goods. Economy-tier buyers in big-box retail channels exhibit highest price sensitivity, while premium appliance OEMs bundling copper-infused liners show lowest.
Supply Chain Analysis
Adhesive formulation expertise rests on German specialty chemical producers and North American coating specialists for pressure-sensitive backings. Raw material dependencies center on vinyl resin from petrochemical complexes, plasticizer compounds subject to REACH restrictions, and copper oxide for antimicrobial loading. Geographic supply concentration clusters in China's Zhejiang and Guangdong provinces for extrusion lamination, Germany's Rhine-Ruhr for formulation chemistry, and the US Ohio-Pennsylvania corridor for calendering converters. Single-source vulnerability concentrates in East Asian calendering capacity. Distribution runs through big-box home improvement chains, direct-to-consumer manufacturer platforms, and appliance OEM bundling channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin-expansion pathways through REACH-compliant formulation premiums replacing commodity PVC tiers, with certified producers capturing pricing power as regulatory barriers filter informal competitors.
For Market Incumbents: Deploy proprietary adhesive coating technology to sustain shelf positioning against private-label encroachment. Kittrich Corporation and Duck Brand anchor competitive defense through channel control investments in big-box retail and specialized texture development for European surface-contact compliance. Capacity rationalization toward citrate and adipate ester alternatives ahead of ECHA enforcement windows protects market access. Backward integration into compliant plasticizer supply secures formulation continuity as phthalate-based chemistries face disqualification. For New Entrants and Emerging Players: Enter via BIS-certified export positioning into India's organized retail expansion across Mumbai and Delhi modern trade formats. India's premium kitchen segments present the most penetrable white space, with certification pressures filtering informal domestic suppliers. Direct-to-consumer custom sizing platforms in China's tier-one cities offer second entry vector, attaching to refrigerator and cabinet e-commerce transactions at measurable attachment rates. Appliance accessory cross-selling provides the specific go-to-market angle, bypassing wholesale volume thresholds that previously locked out smaller players. For Investors and Strategic Acquirers: Consolidation pressure builds where fragmented converter operations lack REACH-compliant formulation portfolios and face 8-14 month certification delays. Long-term viability favors specialists with certified material platforms and direct-to-consumer fulfillment infrastructure over commodity roll goods producers. Acquisition targets include textured finish developers with European regulatory navigation expertise and custom-sizing platform operators in China's e-commerce appliance accessory segment. The signal to watch is ECHA SVHC candidate list expansion velocity, which determines formulation obsolescence risk and replacement cycle timing for incumbent chemistries.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Formulation Rebuild | Citrate and adipate ester substitutions ahead of ECHA enforcement protect EU market access. |
| Direct-to-Consumer Platform Launch | Custom sizing configurators bypass big-box inventory constraints and capture appliance accessory attachment. |
| Copper-Infused Substrate Scale-Up | Copper oxide loading cost declines below zinc alternatives enable mid-market antimicrobial expansion. |
| Mono-Material Construction R&D | EU Green Deal packaging requirements accelerate recyclable substrate development for extended producer responsibility credits. |
| BIS Certification Investment | Compliance positioning captures white space in India's organized retail expansion across tier-one cities. |
Research Methodology
Bottom-up residential renovation and appliance accessory demand modeling reconciled against top-down calendering capacity and raw material input tracking forms the analytical core of this study. Primary interviews with polymer chemists, home improvement retail category managers, appliance OEM procurement leads, and converter operations directors combined with secondary validation from ECHA regulatory filings, FDA food-contact substance databases, customs trade records, and BIS certification registries. Triangulation across stakeholder inputs and published regulatory trajectories grounds segmentation outputs.
Input-output matrices map vinyl resin and adhesive feedstock costs through formulation tiers to end-use pricing across material, application, size, and pattern type dimensions. CAGRs derive from regression analysis against residential renovation spending indices, e-commerce appliance sales trajectories, and regulatory enforcement timelines across the projection horizon. Industry-specific forecast inputs include REACH SVHC candidate list expansion schedules and China's dual carbon policy implementation pace affecting mono-material recyclability requirements.
The model holds under stable petrochemical input cost corridors and incremental regulatory enforcement; deviation in crude price volatility spikes or accelerated ECHA restriction timelines would shift volume and value trajectories. Forecasts embed assumptions on certification burden persistence and direct-to-consumer channel share capture. A small set of named triggers warrants ongoing watch: ECHA enforcement window acceleration, BIS certification backlog resolution in India, and Zhejiang calendering capacity disruption events.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging
Global Polyethylene Packaging Market
Packaging
Wine Bottle Sealing Wax Market
Packaging
Conical Bags Packaging Market
Packaging
Super Barrier Coated Film Market
Packaging
Egg Cartons Market
Packaging
Brazil Container Glass Market
Packaging
Algeria Container Glass Market
Packaging
2 Loop FIBC Bags Market
Packaging
Retail Ready Packaging (RRP) Market
Packaging
Insulated Food Delivery Bags Market
Packaging
Biodegradable Cutlery Market
Packaging
Nigeria Rigid Plastic Packaging Market
Packaging
Slide Top Tins Market
Packaging
Packaging Straps and Buckles Market
Packaging
Cosmetic Tubes Market
Packaging
Cereal Packaging Market