
 Mining Explosives Market | 2026-2036
Mining Explosives Market Size, Share, and Industry Trends Forecast 2026-2036
Mining Explosives Market Intelligence
Australian bulk emulsion producers is broadening manufacturing footprints across Southeast Asian contract mining zones. Orica Limited leverages integrated blast design software to anchor technology leadership in digital fragmentation optimization. MAXAM sustains deep backward integration into ammonium nitrate supply through captive manufacturing complexes in Iberia and Latin America. Dyno Nobel competes on packaged emulsion portability for remote quarrying sites where infrastructure constraints limit bulk delivery economics.
Mining explosives encompass chemical formulations—principally ammonium nitrate-fuel oil blends, water-in-oil emulsions, and gelatinous slurries—engineered to generate controlled gas expansion for rock fragmentation in extractive operations, with detonation velocities typically ranging from 2,500 to 6,000 meters per second depending on density and sensitization method. Emulsion formulations command the largest product type position due to superior water resistance and oxygen balance efficiency in wet bench environments, while ANFO retains cost dominance in dry, large-diameter blasthole applications where moisture exposure remains minimal. Coal mining applications generate the steadiest demand baseline through thermal and metallurgical fuel requirements, though metal mining segments exhibit faster trajectory acceleration linked to copper and lithium extraction intensity for electrification supply chains.
Australia's Work Health and Safety Act, enforced through state-level mining regulators, mandates blast vibration monitoring and fugitive emission controls that elevate product performance thresholds for permissible explosive categories. The US Bureau of Alcohol, Tobacco, Firearms and Explosives imposes stringent storage, transport, and purchaser licensing frameworks that constrain market entry for non-integrated distributors lacking established compliance infrastructure. China's SAMR and MIIT coordinate ammonium nitrate industrial policy through GB standard certifications and anti-diversion tracking systems that reshape formulation chemistry toward lower-sensitivity alternatives. Stakeholders must monitor evolving fragmentation-as-a-service contracting models where explosive suppliers assume direct liability for muckpile geometry outcomes rather than pure product volume sales.
Market Dynamics
Emulsion explosive formulations are displacing ANFO in wet bench mining environments across Chile, Peru, and Australia, compressing procurement toward integrated blast design services rather than standalone product volume sales.
Growth Catalysts
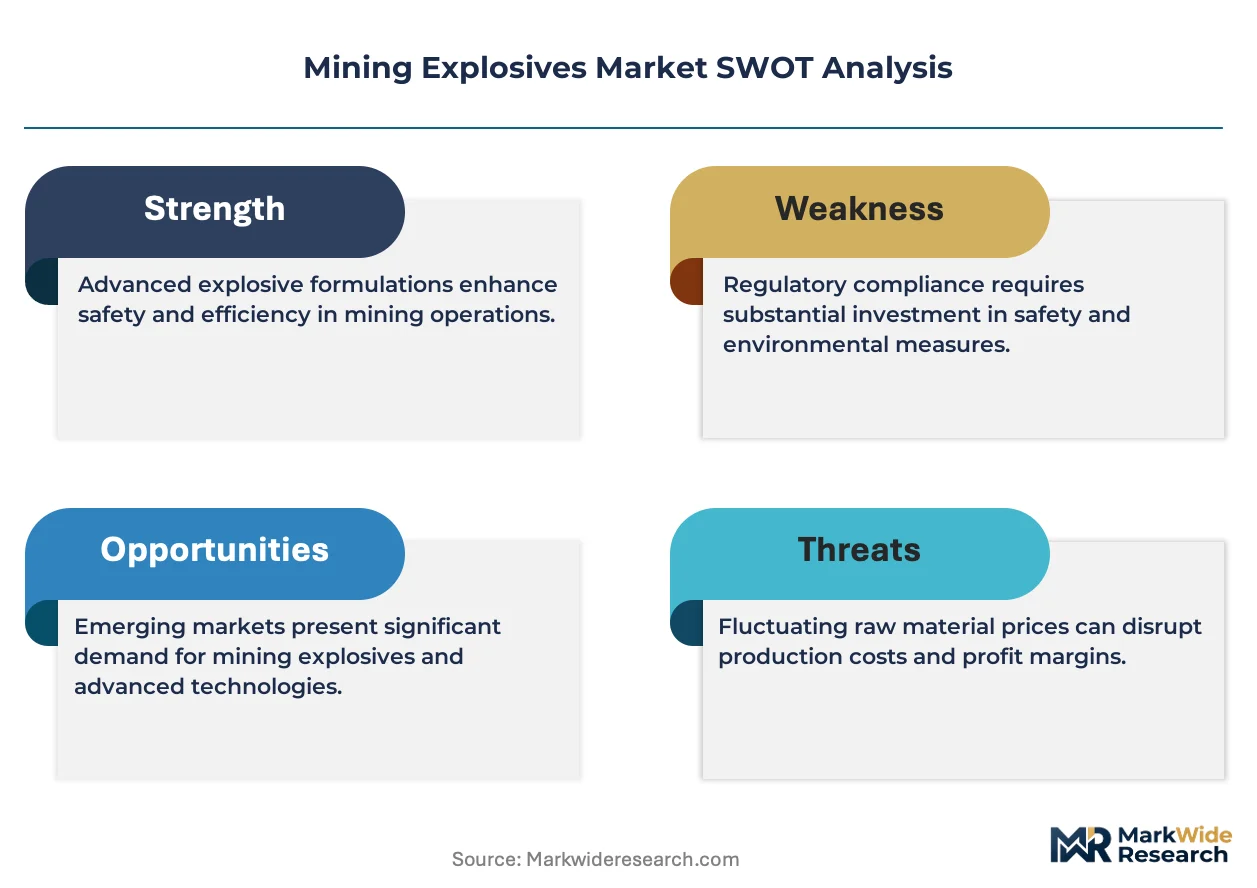
- Copper-lithium extraction intensity:Electrification supply chains in Chile and Argentina are accelerating consumption of water-resistant emulsion systems for deep underground metal operations.
- MIIT traceability mandates:China's ammonium nitrate tracking requirements are forcing formulation shifts toward lower-sensitivity chemistry that meets GB standard certifications.
- Bulk delivery infrastructure:Australia's Pilbara iron ore belt operators are consolidating procurement around pump-truck emulsion systems that reduce handling labor and blasthole loading time.
Market Restraints
- Ammonium nitrate price volatility:Natural gas feedstock cost swings and fertilizer market competition constrain margin stability for explosive manufacturers without captive nitrate supply.
- US ATF licensing barriers:The Bureau of Alcohol, Tobacco, Firearms and Explosives storage and transport frameworks block non-integrated distributors from entering established mining supply chains.
- Water-gel technical limitations:Gelatinous slurry formulations suffer density inconsistency in high-altitude operations above 4,000 meters, restricting deployment in Andean copper zones.
Strategic Opportunities
- Fragmentation-as-a-service models:Suppliers can capture value through outcome-based contracts assuming direct liability for muckpile geometry rather than tonnage-based pricing.
- Southeast Asian contract mining:Indonesian and Philippine open-pit coal and nickel operations present white space for bulk emulsion producers expanding from Australian manufacturing bases.
- Digital blast optimization convergence:Integration of drill pattern software with real-time vibration monitoring creates bundled service offerings that lock in multi-year supply agreements.
Industry Challenges
- Shot-firer certification scarcity:Australia's state-level mining regulators enforce blast vibration competency requirements that outpace vocational training program output in Queensland and Western Australia.
- Legacy ANFO infrastructure stranding:Dry-climate mining operations face capital write-downs when converting bulk ANFO handling systems to emulsion-compatible pump and hose configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mining Explosives Market |
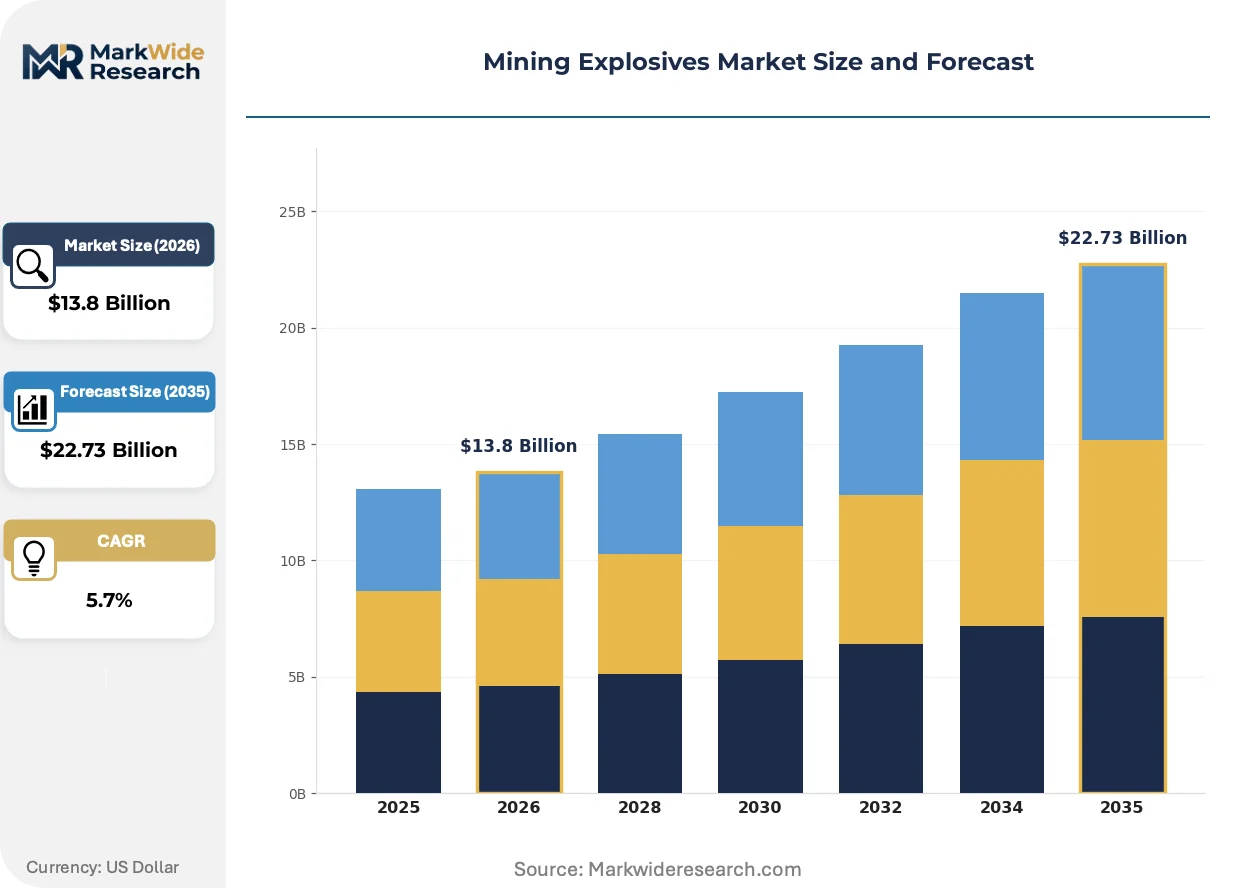
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $22.73 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Emulsions, ANFO, Water Gels, Slurry Explosives Application: Coal Mining, Metal Mining, Quarrying, Construction Delivery Mode: Bulk Delivery, Packaged Delivery, On-Site Mixing, Pre-Mixed End User: Mining Companies, Contractors, Government Agencies, Industrial Users |
| Companies Covered | MAXAM, AECI Group, Orica Limited, Solar Industries India Ltd, Austin Powder Company, ENAEX, Sasol Limited, BME, Dyno Nobel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mining Explosives Market Strategic Shifts & Innovations
Controlled gas expansion chemistry is converging with telemetry and automation systems, compressing the traditional separation between explosive manufacturing, blast design engineering, and post-dig productivity measurement.
Electronic detonation systems is unifying timing precision with blast vibration control in underground metal operations. Chilean copper miners are adopting these programmable initiation networks at pace to reduce wall damage and ore dilution. The technology is unifying fragmentation outcomes with downstream crushing energy requirements, forcing explosive suppliers to assume performance guarantees previously held by mining contractors.
REACH chemical registration requirements in Europe are tightening emulsion sensitizer classifications and restricting certain fuel oil blends in cross-border transport. Manufacturers serving EU-based mining multinationals are reformulating water-in-oil matrices to maintain oxygen balance while eliminating substances subject to authorization lists. Underground limestone and salt producers in Germany and Poland are absorbing compliance costs through longer tender cycles and consolidated supplier panels.
Buyer organizations are consolidating explosive procurement through mine-site-level framework agreements rather than corporate volume contracts. Tier-one iron ore operators in Western Australia are unbundling blast design from drilling services, creating direct commercial relationships with explosive technology providers. This pattern concentrates most visibly in the Pilbara region, where three operators account for the majority of emulsion consumption and demand integrated digital fragmentation platforms.
Mining Explosives Market Segmentation
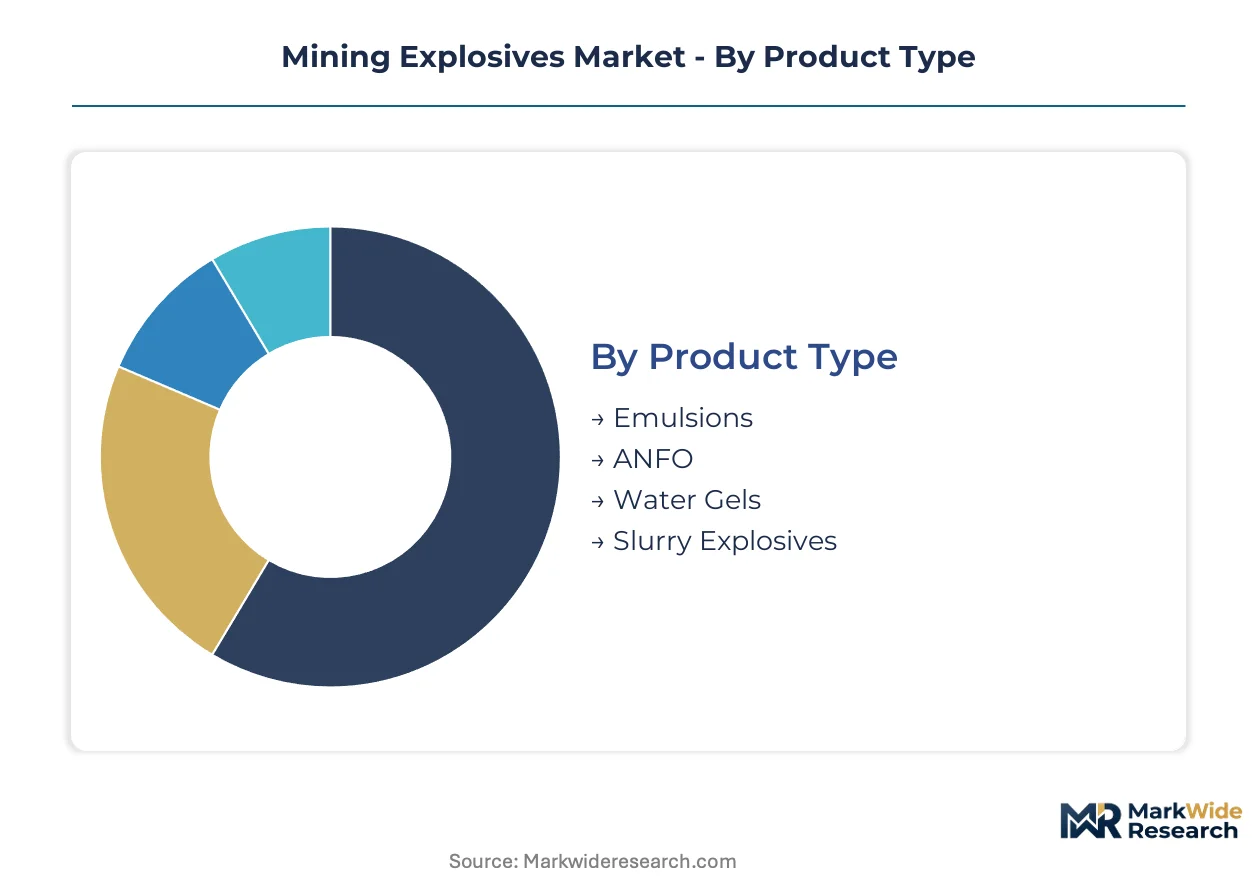
Explosive selection in mining operations hinges on bench moisture conditions, blasthole diameter economics, and downstream fragmentation requirements. Procurement patterns diver sharply between integrated mine operators optimizing total drill-and-blast cost and contract miners prioritizing equipment portability.
Product Type:
Moisture exposure at the blast face determines formulation choice more than any other single variable.
- Emulsions:Water-in-oil matrices disperse ammonium nitrate micro-droplets within continuous fuel phases, achieving superior water resistance for wet bench environments. Chilean and Peruvian underground copper operations favor pumpable bulk emulsions for deep hole loading where groundwater infiltration degrades ANFO performance.
- ANFO:Porous ammonium nitrate prills absorb diesel fuel to create low-cost, oxygen-balanced blends detonating at 3,500-4,500 meters per second. Australia's Pilbara iron ore belt sustains substantial ANFO consumption in dry, large-diameter blastholes where bulk delivery infrastructure minimizes handling costs.
- Water Gels:Suspension of oxidizer salts in aqueous solution with cross-linked gelling agents provides moderate water resistance at intermediate cost points. Gelatinous consistency limits altitude deployment above 4,000 meters due to density instability.
- Slurry Explosives:Saturated solutions of ammonium nitrate with suspended sensitizers offer high-density loading for hard rock fragmentation. Formulations require specialized mixing equipment at point of use.
Volume sits with ANFO in dry-climate bulk operations; growth tilts toward emulsions as wet bench mining expands.
Application:
Rock hardness and ore value per ton dictate sensitivity-to-cost tradeoffs across extractive segments.
- Metal Mining:Copper and lithium extraction in Chile, Argentina, and Australia demands water-resistant emulsion systems for selective blasting that minimizes ore dilution. Electrification supply chains accelerate consumption intensity as underground operations deepen.
- Coal Mining:Thermal and metallurgical fuel requirements generate steady baseline demand through surface and underground operations. ANFO dominates where seam moisture remains manageable and fragmentation tolerance is higher.
- Quarrying:Dimension stone and aggregate producers favor packaged emulsion portability for dispersed sites lacking bulk infrastructure. Dyno Nobel competes aggressively in this segment with cartridge-based loading systems.
- Construction:Tunneling and road-cut projects require precisely controlled blast vibration limits near populated areas. Electronic detonation timing and specialized low-density formulations predominate.
Coal mining anchors current volume; metal mining climbs fastest on copper-lithium extraction intensity.
Delivery Mode:
Capital intensity of loading infrastructure versus labor cost shapes procurement economics.
- Bulk Delivery:Pump-truck systems deliver non-sensitized emulsion precursors to blastholes, reducing handling labor and loading time. Australia's Pilbara operators consolidated procurement around this mode for iron ore production.
- Packaged Delivery:Cartridge and bagged formats suit remote quarrying and construction where site infrastructure cannot support bulk handling. Premium pricing reflects logistics complexity.
- On-Site Mixing:Mobile manufacturing units produce emulsion at the blast face from ammonium nitrate solution and fuel oil, eliminating transport of hazardous finished product. Requires trained personnel and quality control protocols.
- Pre-Mixed:Factory-sensitized products arrive ready for direct loading, simplifying procurement for small-scale operators without formulation expertise.
Bulk delivery commands scale economics; packaged formats defend margin in infrastructure-constrained niches.
End User:
Liability structures and technical capability determine supplier relationship depth.
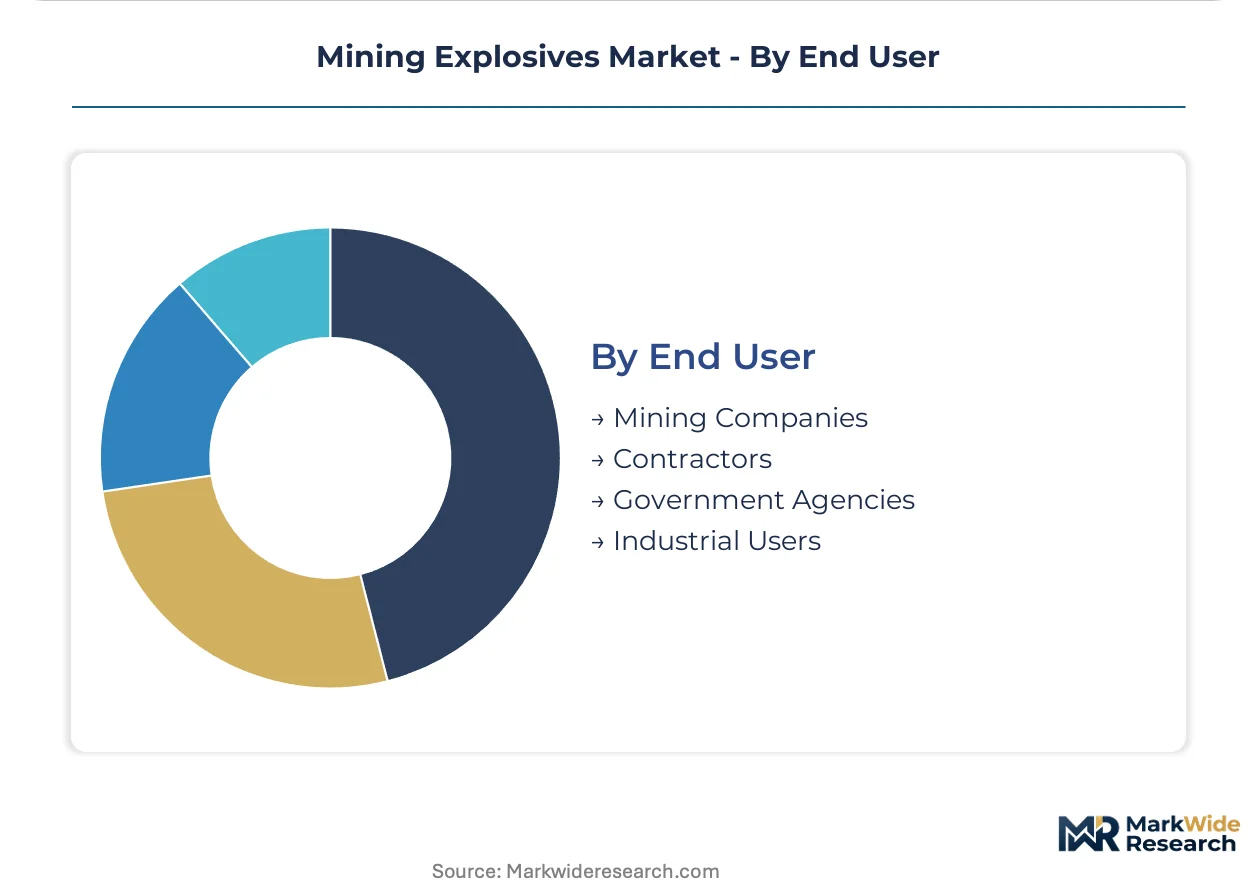
- Mining Companies:Integrated operators like Pilbara iron ore majors unbundle blast design from drilling services, creating direct contracts with explosive technology providers for multi-year framework agreements.
- Contractors:Mining services firms prioritize equipment flexibility and rapid site mobilization, favoring packaged products and portable mixing systems over fixed bulk infrastructure.
- Government Agencies:State-owned mining enterprises in resource-nationalist jurisdictions impose local content requirements and technology transfer conditions on explosive supply contracts.
- Industrial Users:Cement, salt, and limestone producers consume smaller volumes with less technical sophistication, often relying on distributor intermediaries.
Mining companies concentrate procurement volume; contractors represent the expanding service-model frontier.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ammonium nitrate feedstock availability and copper-lithium extraction intensity anchor geographic demand distribution across mining explosives consumption centers.
Australia
Pilbara iron ore operators drive bulk emulsion procurement through pump-truck delivery systems that minimize blasthole loading labor. The country's Work Health and Safety Act mandates blast vibration monitoring and fugitive emission controls that elevate product performance thresholds. Western Australia's state mining regulators enforce competency requirements for shot-firers that outpace vocational training output in Queensland.
Chile
Underground copper operations in the Atacama Desert accelerate water-resistant emulsion consumption as electrification supply chains deepen extraction intensity. The national mining regulator enforces storage and transport frameworks that constrain non-integrated distributors lacking established compliance infrastructure. Antofagasta and Calama mining clusters adopt electronic detonation systems to reduce wall damage and ore dilution in deep shaft operations.
China
MIIT mandates on ammonium nitrate traceability force formulation shifts toward lower-sensitivity chemistry that meets GB standard certifications. SAMR coordinates industrial policy through anti-diversion tracking systems that reshape product chemistry standards. Shanxi and Inner Mongolia coal basins sustain substantial ANFO consumption where seam moisture remains manageable.
Peru
Andean copper zones above 4,000 meters face technical limitations with gelatinous slurry density consistency, restricting water-gel deployment in high-altitude operations. The Ministry of Energy and Mines imposes local content requirements on explosive supply contracts for state-associated projects. Cerro de Pasco and La Oroya mining corridors favor pumpable bulk emulsions for groundwater-infiltrated blastholes.
United States
The Bureau of Alcohol, Tobacco, Firearms and Explosives imposes stringent storage, transport, and purchaser licensing frameworks that block market entry for distributors without compliance infrastructure. Powder River Basin coal operators maintain ANFO dominance in dry, large-diameter applications. Arizona copper districts and Nevada gold belts concentrate procurement around integrated blast design services rather than standalone product volume sales.
Mining Explosives Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue digital fragmentation optimization and outcome-based contracting models. The vendor base concentrates around integrated manufacturers with captive ammonium nitrate supply and regional distributors serving infrastructure-constrained quarrying sites. Three archetypes dominate: backward-integrated chemical conglomerates with global manufacturing footprints, technology-led specialists bundling blast design software with product delivery, and portable-system providers targeting remote construction and quarrying. Competitive moves center on geographic expansion into Southeast Asian contract mining zones and M&A activity consolidating regional distribution networks.
Among Australia-based technology leaders, Orica Limited exemplifies the digital-integrated archetype through blast design software platforms. MAXAM and Dyno Nobel occupy positions spanning manufacturing scale and packaged-product portability respectively. These three anchors represent the competitive spectrum from bulk delivery infrastructure dominance to cartridge-based flexibility for dispersed sites.
| Leading Market Players |
|---|
| MAXAM |
| AECI Group |
| Orica Limited |
| Solar Industries India Ltd |
| Austin Powder Company |
| ENAEX |
| Sasol Limited |
| BME |
| Dyno Nobel |
| Others |
Cost & Logistics Intelligence
Shot-firer certification scarcity in Western Australia and Queensland widens the spread between premium integrated-service contracts and economy-tier product-only sales. Labor-cost differentials between state-level mining jurisdictions translate directly into pricing-tier stratification across bulk emulsion procurement.
Pricing Analysis
Warranty and blast-performance guarantees separate premium-tier offerings from unbundled product sales in this market. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by certification grade and after-sales technical support depth. Pricing pressure stems from natural gas feedstock volatility squeezing ammonium nitrate producers without captive supply. Contract miners in Southeast Asian nickel operations exhibit highest price sensitivity; Pilbara iron ore majors with multi-year framework agreements show lowest.
Supply Chain Analysis
Single-source vulnerability sits with ammonium nitrate feedstock concentrated in Russia, Ukraine, and Trinidad and Tobago. Manufacturing draws from natural gas derivatives, porous prill substrates, and specialized emulsifier chemicals. Tariff exposure on cross-border sensitizer shipments creates structural risk for European-serving producers. Distribution runs through mine-site-level framework agreements rather than corporate volume contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around backward-integrated chemical conglomerates as ammonium nitrate price volatility forces out non-captive distributors.
For Market Incumbents: Anchor technology leadership through digital fragmentation optimization platforms that lock in multi-year Pilbara supply agreements. Deepen captive ammonium nitrate manufacturing in Iberia and Latin America to defend margin stability against feedstock volatility. Electronic detonation integration represents the critical R&D lever for underground copper contracts. For New Entrants and Emerging Players: Begin with Southeast Asian contract mining zones where Australian bulk emulsion producers are expanding manufacturing footprints. Indonesian open-pit nickel and Philippine coal operations present the most penetrable white space. Fragmentation-as-a-service contracting models offer the strongest go-to-market angle for technology-led specialists. For Investors and Strategic Acquirers: The window for entry favors technology-led specialists with blast design software platforms and regional distribution networks in Southeast Asia. Long-term viability centers on outcome-based liability structures replacing tonnage-based pricing. Watch electronic detonation adoption rates in Chilean underground copper as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ammonium Nitrate | Captive feedstock supply insulates margins from natural gas volatility affecting Russian and Ukrainian producers. |
| Digital Fragmentation Platform Deployment | Orica's blast design software anchors technology leadership in Pilbara iron ore multi-year agreements. |
| Southeast Asian Manufacturing Expansion | Australian bulk emulsion producers broaden footprints into Indonesian nickel and Philippine coal contract mining. |
| Electronic Detonation System Integration | Chilean copper miners adopt programmable initiation networks to reduce wall damage and ore dilution. |
| Fragmentation-as-a-Service Contracting | Suppliers assume direct liability for muckpile geometry outcomes rather than pure product volume sales. |
Research Approach
Multi-period observation of emulsion adoption rates, ANFO displacement patterns, and electronic detonation penetration anchored the trend analysis, supplemented by interviews with shot-firer training program directors, state mining regulator compliance officers, procurement leads at Pilbara iron ore operators, and technical R&D directors at emulsion manufacturers. Secondary validation drew from Australian Work Health and Safety Act enforcement records, China's MIIT GB standard certification databases, US ATF licensing frameworks, SEC 10-K filings of listed explosive producers, and customs/trade data on ammonium nitrate cross-border flows. Bottom-up product-type volume estimates triangulated against top-down regional demand aggregation.
Input-output matrices modeled demand across product type, application, delivery mode, and end user segmentation dimensions throughout the forecast period. CAGRs derived from slope analysis of historical consumption intensity against projected copper-lithium extraction expansion and electrification supply chain buildout. Industry-specific forecast inputs included China's anti-diversion tracking system implementation timelines and Australia's state-level shot-firer certification output capacity.
Feedstock price volatility, regulatory diversion-control tightening, and workforce certification bottlenecks are the dominant revision risks warranting scenario-band sensitivity testing. Forecasts reflect documented assumptions on emulsion displacement velocity and bulk delivery infrastructure deployment rates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Lime Manufacturing Market
Industrial Chemicals
Dimethylacetamide (Dmac) Market
Industrial Chemicals
Antiscalant Market
Industrial Chemicals
Diisobutylaluminum Chloride Market
Industrial Chemicals
1-Octanol Market
Industrial Chemicals
US Anhydrous Hydrogen Fluoride Market
Industrial Chemicals
Lime Market
Industrial Chemicals
Permeate Market
Industrial Chemicals
Deoiler Chemicals Market
Industrial Chemicals
Quenching Fluids and Salts Market
Industrial Chemicals
Bleaching Clay Market
Industrial Chemicals
Dicumyl Peroxide Market
Industrial Chemicals
Ferric Chloride As Etchant Market
Industrial Chemicals
Hydrogen Sulphide Market
Industrial Chemicals
North America Paper Machine Oil Market
Industrial Chemicals
Pesticide Inert Ingredients Market