
 Shea Butter Market | 2026-2036
Shea Butter Market Size, Share, and Industry Trends Forecast 2026-2036
Shea Butter Market Analysis
ECOCERT organic certification is redrawing competitive boundaries in shea butter sourcing. AAK AB leverages its West African crushing network to sustain traceable supply chains from Ghana and Burkina Faso. Cargill Incorporated anchors its position through direct farmer partnerships that bypass conventional commodity brokers. BASF SE differentiates via refined shea fractions tailored to cosmetic-grade specifications.
Shea butter is a triglyceride fat extracted from the nuts of Vitellaria paradoxa, containing oleic and stearic acids that confer solid-to-melt transition properties ideal for emulsion stability. The raw material undergoes mechanical pressing or solvent extraction, followed by filtration and optional refining to remove color and odor for pharmaceutical and cosmetic use. Refined shea butter commands the largest volume share among product types due to its neutral sensory profile and broader formulation compatibility. Organic shea butter carries the fastest expansion trajectory as clean-label mandates from European and North American cosmetics manufacturers tighten specification requirements. Cosmetics and personal care applications absorb the dominant value share, with food-grade shea finding steady use in confectionery coatings across Belgian and Swiss chocolate producers.
EC No 1223/2009 and REACH enforcement through ECHA constrain unverified shea claims in EU cosmetic labeling. FDA cosmetic ingredient regulations and USDA organic standards govern parallel compliance obligations for US-bound shea products. Stakeholders must monitor evolving deforestation-free supply chain mandates under the EU Deforestation Regulation, which will reshape origin documentation requirements for West African shea exports.
Market Dynamics
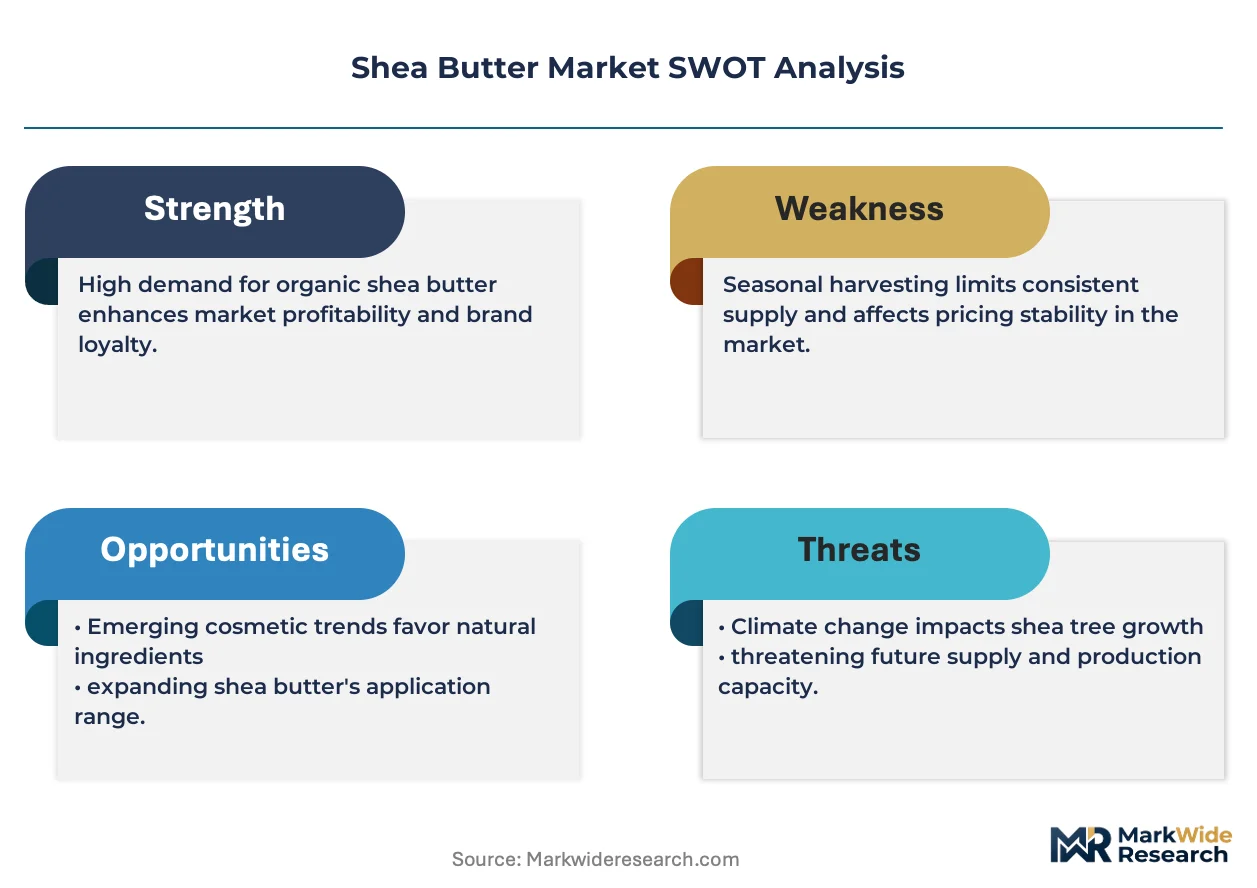
EU Deforestation Regulation documentation mandates are compressing West African supply chains into traceable, certified pathways, eliminating informal broker layers and forcing direct processor-farmer relationships.
Growth Catalysts
- REACH traceability mandates:ECHA enforcement of EC No 1223/2009 compels cosmetics formulators to document shea origin through certified supply chains, eliminating unverified sources.
- Clean-label cosmetics:Premium personal care brands in France and Germany now specify organic-grade shea butter as a non-negotiable formulation input.
- Mechanical pressing technology:Cold-press extraction methods preserve bioactive triterpene content, meeting pharmaceutical-grade specifications for dermatological applications.
Market Restraints
- Input cost volatility:Shea nut prices fluctuate with Sahel rainfall patterns, exposing processors to margin compression during drought cycles in Burkina Faso and Mali.
- Supply concentration risk:Over 80% of exportable shea originates from Ghana, Nigeria, and Burkina Faso, creating single-origin vulnerability to regional instability.
- Substitution threat:Mango butter and cocoa butter compete in confectionery coatings, particularly among Belgian and Swiss chocolate producers seeking price-stable alternatives.
Strategic Opportunities
- Underpenetrated North American food sector:US confectionery and bakery applications remain underdeveloped relative to cosmetic use, presenting volume expansion potential.
- EU Green Deal bioeconomy incentives:Circular economy funding streams favor shea-derived oleochemicals as renewable feedstocks for surfactant production.
- Blockchain verification systems:Distributed ledger technology enables real-time traceability from cooperative to finished product, satisfying EUDR audit requirements.
Industry Challenges
- Certification timeline compression:ECOCERT and USDA Organic audits require 12-18 month conversion periods for conventional shea operations, delaying market access.
- Skill gaps in quality control:Laboratory capacity for free fatty acid and peroxide value testing remains scarce in upcountry crushing facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Shea Butter Market |
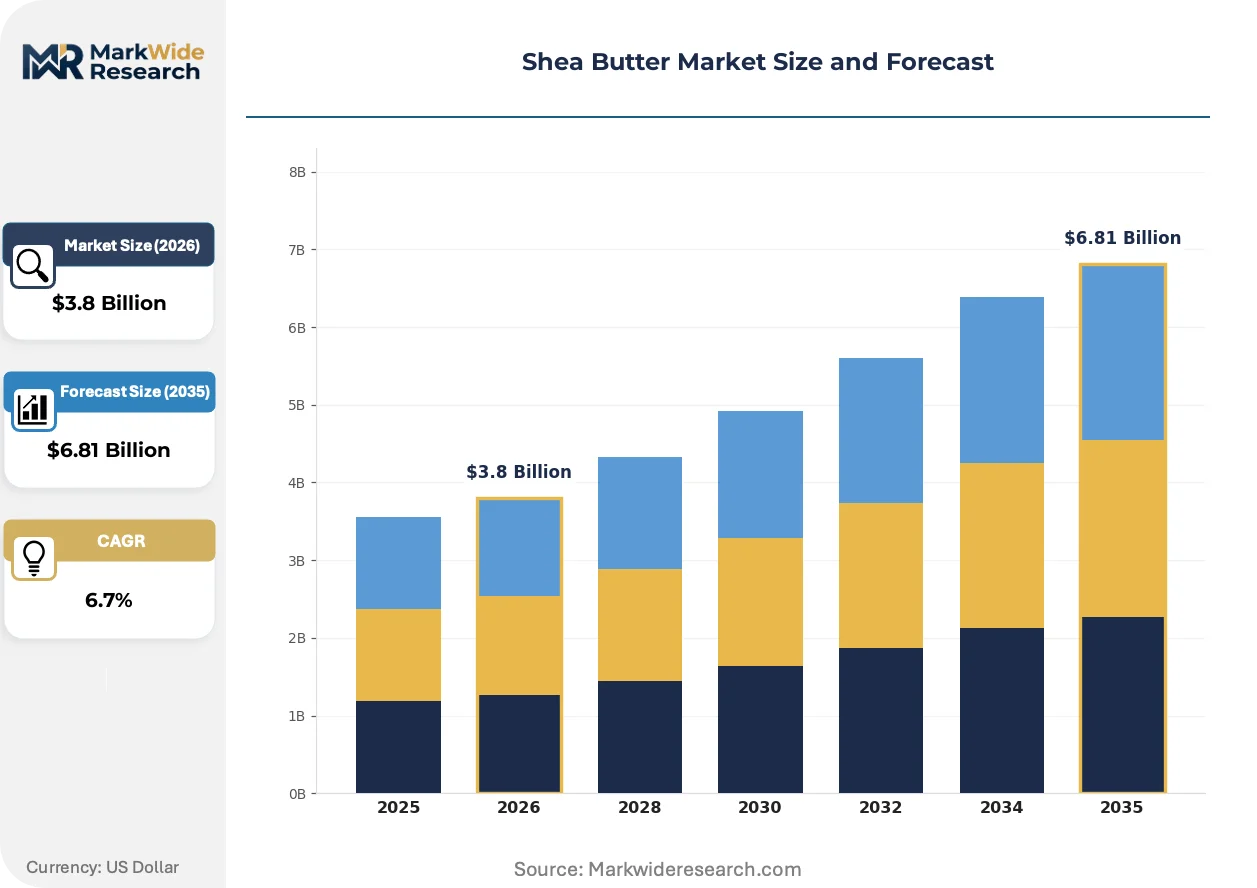
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Raw Shea Butter, Refined Shea Butter, Organic Shea Butter, Whipped Shea Butter Application: Cosmetics, Food Industry, Pharmaceuticals, Personal Care End User: Manufacturers, Retailers, Consumers, Distributors Distribution Channel: Online, Supermarkets, Health Stores, Specialty Stores |
| Companies Covered | BASF SE, Cargill Incorporated, AAK AB, Olvea Group, Bunge Loders Croklaan, Ghana Nuts Company Limited, Sophim S.A., The Savannah Fruits Company, Clariant AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Shea Butter Market Emerging Trajectories
Clean-label mandates and deforestation-free sourcing requirements are restructuring how shea moves from West African cooperatives to European and North American formulators, with technology and policy acting as twin accelerants.
Supercritical CO2 extraction is fragmenting the traditional shea fractionation landscape. This solvent-free technology isolates stearin and olein fractions with precise melting point control, enabling tailored functionality for stick cosmetics and whipped formulations. Niche cosmetic laboratories in France and Germany are adopting these systems to bypass conventional refining infrastructure and command premium positioning.
EU Deforestation Regulation geolocation requirements reshape origin documentation obligations for all shea entering European customs territories. Processors must now provide polygon mapping of collection zones and cooperative registration data, increasing compliance overhead but creating competitive moats for operators with established traceability systems. French and German importers are consolidating supplier relationships to reduce audit complexity.
Direct-procurement contracts between end-users and West African cooperatives are displacing spot-market purchasing through commodity brokers. Large cosmetics manufacturers in France now negotiate multi-year offtake agreements with named women's cooperatives in Ghana, locking volume and securing EUDR-compliant documentation. This shift compresses intermediary margins while transferring price risk to formulators with balance sheet capacity.
Shea Butter Market Segmentation

Segmentation in shea butter reveals how certification grades, application specifications, and channel economics split value capture across the supply chain. Each dimension exposes different margin structures and compliance burdens for processors and brands.
Product Type:
Refined and organic grades dominate export flows to European cosmetic manufacturers, while raw shea serves regional West African food and traditional medicine markets.
- Raw Shea Butter:Unfiltered extract retains natural coloration and nutty aroma with elevated free fatty acid content. Ghanaian and Nigerian domestic processors supply regional soap makers and traditional healers, constrained by inconsistent quality standards and limited cold-chain infrastructure.
- Refined Shea Butter:Bleached and deodorized through chemical or physical refining to achieve neutral sensory profile. French and German cosmetics formulators specify this grade for mass-market emulsion stability, driven by REACH documentation requirements for consistent batch specifications.
- Organic Shea Butter:ECOCERT or USDA Organic certified with full traceability from cooperative to crushing facility. Clean-label mandates from premium personal care brands in France accelerate procurement of this grade despite 15-20% price premiums.
- Whipped Shea Butter:Aerated cosmetic preparation blended with carrier oils for direct-to-consumer skincare. Small-batch producers in North American health stores favor this format for retail margin capture, limited by short shelf-life and temperature sensitivity.
Refined shea commands the established base. The steepest expansion runs through organic certification tiers.
Application:
Volume concentration varies sharply by margin structure, with pharmaceutical specifications commanding premium pricing against commoditized food coatings.
- Cosmetics:Emulsion base for lotions, lip balms, and hair conditioners leveraging solid-to-melt transition properties. Formulators in France and Germany now require EUDR-compliant documentation for shea sourcing, shifting procurement toward direct cooperative contracts.
- Food Industry:Cocoa butter equivalent in confectionery coatings for Belgian and Swiss chocolate producers. Substitution pressure from mango butter intensifies during shea nut price spikes driven by Sahel drought cycles.
- Pharmaceuticals:Dermatological-grade base for eczema treatments and wound healing formulations. Cold-pressed extraction preserves bioactive triterpenes meeting pharmacopeial specifications, with demand concentrated in German and Swiss compounding pharmacies.
- Personal Care:Mass-market soaps and shampoos utilizing refined shea for label claims. Retailers in Germany and the Netherlands drive private-label specification of this grade for price-positioned product lines.
Cosmetics applications absorb dominant value share. Pharmaceuticals deliver the steepest margin expansion trajectory.
End User:
Procurement scale and compliance capability separate industrial buyers from fragmented retail channels.
- Manufacturers:Cosmetic and food processing companies with dedicated quality laboratories and EUDR audit readiness. Direct offtake agreements with Ghanaian cooperatives lock volume for French and German formulators with balance sheet capacity.
- Retailers:Health store chains and supermarket private-label programs specifying certified-sustainable shea for consumer-facing claims. German drugstore chains now mandate organic certification for shea-containing product lines.
- Consumers:Direct purchasers of raw or whipped shea through cooperatives and fair-trade platforms. This channel remains concentrated in North American and European ethical consumption segments with price inelasticity for provenance stories.
- Distributors:Commodity brokers and specialty ingredient traders handling spot-market shea without origin documentation. EU Deforestation Regulation implementation is compressing this channel's viability for European-bound shipments.
Manufacturers control volume aggregation. Consumer-direct channels are climbing fastest on traceability premiums.
Distribution Channel:
Channel selection determines certification burden and margin retention for shea processors.
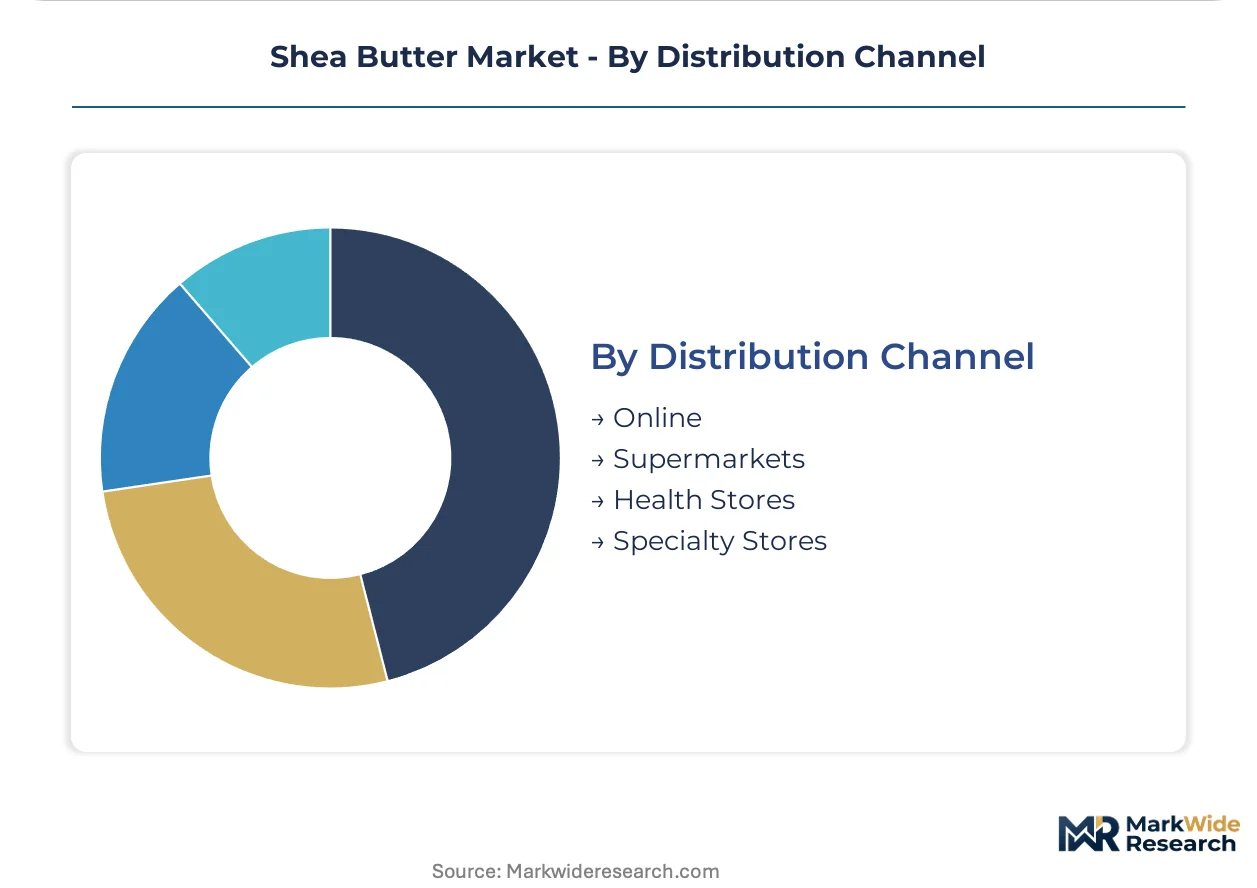
- Online:Direct-to-consumer platforms and B2B ingredient marketplaces enabling cooperative-to-brand transactions. Blockchain verification systems embedded in these channels satisfy EUDR geolocation requirements for French and German importers.
- Supermarkets:Mass retail placement for personal care and food-grade shea products. Private-label penetration in German and Dutch supermarkets drives specification of refined, deodorized grades at volume-discounted terms.
- Health Stores:Specialty retail channel for organic and whipped shea preparations. French and German health store networks emphasize ECOCERT and Fairtrade certification as shelf-placement criteria.
- Specialty Stores:Cosmetic ingredient suppliers and compounding pharmacies serving formulators. Swiss and German pharmaceutical-grade distributors maintain cold-chain handling for high-specification shea fractions.
Supermarkets anchor volume throughput. Online channels are gaining share fastest on traceability transparency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cosmetics manufacturers in France and Germany drive premium-grade shea procurement through direct cooperative contracts, while food processors in Belgium and Switzerland anchor confectionery demand. Regulatory enforcement through ECHA and the EU Deforestation Regulation compresses supply chains into traceable, certified pathways across all major import markets.
France
Premium personal care brands in Paris and Lyon now mandate ECOCERT organic shea as a non-negotiable formulation input. ANSM enforces EC No 1223/2009 compliance for cosmetic ingredient traceability, eliminating unverified sources from supply chains. The Île-de-France cluster hosts formulators negotiating multi-year offtake agreements with Ghanaian women's cooperatives to secure EUDR-compliant documentation.
Germany
Mass-market drugstore chains and compounding pharmacies in Hamburg and Munich specify refined shea for emulsion stability and dermatological applications. ECHA REACH enforcement compels documentation of shea origin through certified supply chains, with geolocation requirements reshaping importer-supplier relationships. The North Rhine-Westphalia region concentrates pharmaceutical-grade distributors maintaining cold-chain handling for high-specification shea fractions.
Belgium
Confectionery manufacturers in Brussels and Antwerp utilize shea as a cocoa butter equivalent in chocolate coatings, facing substitution pressure from mango butter during price spikes. The Federal Agency for the Safety of the Food Chain enforces origin documentation aligned with EU Deforestation Regulation implementation. Flemish processors are consolidating supplier relationships to reduce EUDR audit complexity and secure volume commitments.
Switzerland
Swiss chocolate producers and pharmaceutical compounders in Zurich and Basel demand cold-pressed shea preserving bioactive triterpenes for dermatological formulations. Swissmedic oversees pharmacopeial specifications for wound healing and eczema treatment applications. The Basel pharmaceutical cluster drives specification of laboratory-tested shea with precise free fatty acid and peroxide value documentation.
United States
North American cosmetics and underpenetrated food sector buyers in New Jersey and California are expanding procurement of certified-sustainable shea. FDA cosmetic ingredient regulations and USDA organic standards govern parallel compliance obligations for imported shea products. Direct-to-consumer platforms and B2B ingredient marketplaces in California embed blockchain verification systems to satisfy emerging traceability demands from brand formulators.
Shea Butter Market Vendor Landscape
Player mix skews toward integrated agribusiness conglomerates with West African crushing networks and specialty oleochemical refiners with cosmetic-grade fractionation capabilities. The structure concentrates around processors with direct farmer partnerships and established ECOCERT certification pathways. Two strategic archetypes dominate: vertically integrated seed processors controlling origin documentation, and refined fraction specialists tailoring stearin-olein splits for formulation-specific functionality. Competitive moves center on multi-year cooperative offtake agreements and supercritical CO2 extraction technology licensing to bypass conventional refining infrastructure.
Within the integrated processor tier, BASF SE and Cargill Incorporated exemplify archetypes with established traceability systems and direct procurement relationships in Ghana and Burkina Faso. Among specialty refiners, AAK AB occupies a position representing West African crushing network consolidation, while Sophim S.A. sits within the French-German cosmetic-grade fractionation segment. Clariant AG anchors the specialty chemicals vector with refined shea derivatives for emulsion applications. These named entities represent competitive positioning patterns rather than specific strategic actions or market share claims.
| Leading Market Players |
|---|
| BASF SE |
| Cargill Incorporated |
| AAK AB |
| Olvea Group |
| Bunge Loders Croklaan |
| Ghana Nuts Company Limited |
| Sophim S.A. |
| The Savannah Fruits Company |
| Clariant AG |
| Others |
Supply Flow & Price Mechanics
Multi-year offtake agreements between French cosmetics manufacturers and Ghanaian women's cooperatives lock in volume commitments while anchoring price visibility against Sahel rainfall volatility. These contracts transfer price risk to formulators with balance sheet capacity while eliminating spot-market exposure for processors.
Pricing Analysis
Cost-plus contracts with shea nut indexation dominate procurement between West African crushers and European refiners. Three-tier pricing structure across organic, refined, and raw grades separates ECOCERT-certified supply from deodorized industrial grades and unfiltered regional product. Pricing pressure stems from mango butter substitution in Belgian confectionery during drought-driven nut price spikes. Mass-market personal care manufacturers in Germany exhibit highest price sensitivity, while French premium brands absorb organic premiums with minimal volume elasticity.
Supply Chain Analysis
Tema port congestion and overland transit from Burkina Faso interior constitute chokepoints that concentrate exportable shea through Ghanaian crushing infrastructure. Ghana, Nigeria, and Burkina Faso anchor global supply, with shea nut availability, mechanical pressing capacity, and ECOCERT audit readiness as critical inputs. Single-origin vulnerability to regional instability in the Sahel creates structural risk. Distribution runs through direct processor-brand contracts that displace commodity brokers under EU Deforestation Regulation enforcement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Shea butter sits in early-cycle expansion as clean-label mandates penetrate North American food applications and pharmaceutical-grade specifications harden in European dermatology. Traceability premiums and deforestation-free sourcing requirements create durable tailwinds for certified supply chains.
For Market Incumbents: Consolidate crushing capacity in Ghana and Burkina Faso through cooperative equity stakes that secure EUDR-compliant geolocation documentation. Deepen backward integration into shea nut collection networks to bypass drought-driven spot price volatility. Lock multi-year offtake agreements with French formulators before certification timeline compression delays competitor market access. For New Entrants and Emerging Players: Lead with blockchain-verified direct procurement platforms targeting underpenetrated US confectionery and bakery segments. North American food-grade shea presents the most penetrable white space against established cosmetic demand concentration. Position through B2B ingredient marketplaces that embed real-time traceability for brand formulators seeking EUDR-ready documentation without internal compliance infrastructure. For Investors and Strategic Acquirers: Capital is best deployed toward West African processors with established ECOCERT pathways and named cooperative relationships that satisfy EU Deforestation Regulation audit requirements. Long-term viability centers on traceability infrastructure rather than commodity trading margins. Watch for inflection when EU Green Deal bioeconomy funding redirects toward shea-derived oleochemicals as renewable surfactant feedstocks.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Year Cooperative Offtake Agreements | Locks volume for French formulators while transferring price risk from West African processors. |
| Supercritical CO2 Extraction Licensing | Enables French and German cosmetic laboratories to bypass conventional refining infrastructure. |
| Blockchain Geolocation Verification | Satisfies EUDR polygon mapping requirements for Ghanaian cooperative collection zones. |
| Organic Certification Conversion | Opens ECOCERT-compliant pathways to premium pricing tiers in German drugstore chains. |
| Cold-Press Pharmaceutical Capacity | Captures bioactive triterpene premiums from Swiss compounding pharmacies and German dermatology. |
Methodological Framework
Operator-level perspectives from shea cooperative managers, crushing facility quality directors, French cosmetics formulators, German drugstore procurement leads, and Belgian confectionery technologists anchored the qualitative base. Secondary validation drew from ECHA REACH guidance documents, ECOCERT certification standards, EU Deforestation Regulation implementation texts, Ghana Export Promotion Authority trade data, and SEC filings from listed oleochemical processors. Bottom-up volume estimates from cooperative production data triangulated against top-down import statistics from French and German customs authorities.
Sensitivity analysis tested forecast outputs against variable shea nut price scenarios, ECOCERT conversion timeline delays, and EUDR enforcement intensity gradients across the projection horizon. Segmentation modeling spanned product grade tiers, application end-uses, and regional regulatory clusters. CAGRs derived from historical volume trajectories adjusted for policy inflection points and technology adoption curves. Forecast inputs incorporated Sahel rainfall pattern correlations with nut availability and cold-press capacity expansion timelines in Ghana and Burkina Faso.
The analysis sits within stated boundaries; outcomes outside sustained EU Deforestation Regulation enforcement or accelerated North American food sector penetration would require recalibration. Forecasts reflect documented assumptions regarding certification audit capacity and cooperative consolidation trajectories. Practitioners should keep alternative scenarios live as EU Green Deal funding allocations and blockchain verification technology costs evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Chemicals
Dead Sea Mud Cosmetics Market
Cosmetic Chemicals
Organic Cosmetic Ingredients Market
Cosmetic Chemicals
Cosmetics Contract Manufacturing Market
Cosmetic Chemicals
Personal Care Chemicals Market
Cosmetic Chemicals
Skin Lightening Products Market
Cosmetic Chemicals
Face Primer Market
Cosmetic Chemicals
Canada Eyeshadow Stick and Blush Stick Market
Cosmetic Chemicals
Cosmetics and Personal Care Ingredients Market
Cosmetic Chemicals
Global Skin Lightening Market
Cosmetic Chemicals
Europe Hyaluronic Acid-Based Dermal Fillers Market
Cosmetic Chemicals
Cosmetic UV Absorbers Market
Cosmetic Chemicals
Jojoba Oil Derivatives Market
Cosmetic Chemicals
Gemstone Cosmetics Powder Market
Cosmetic Chemicals
Cosmetic Kaolin Powder Market
Cosmetic Chemicals
Compound Camphor Ointment Market
Cosmetic Chemicals
Lanolin Nipple Cream Market