
 South America Vegetable Seed Market | 2026-2036
South America Vegetable Seed Market Size, Share, and Industry Trends Forecast 2026-2036
South America Vegetable Seed Market Analytics
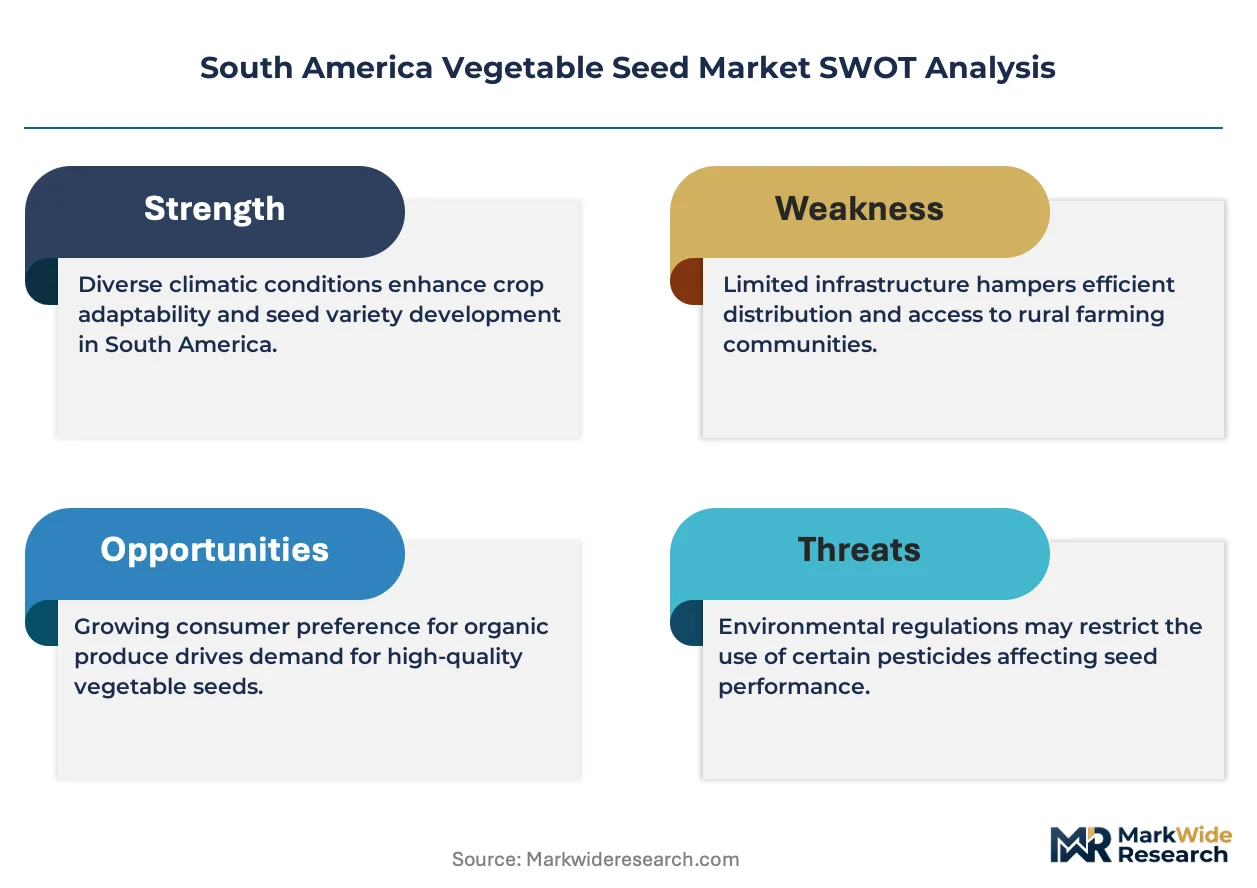
Intellectual property licensing revenue from proprietary germplasm is reshaping margin distribution across the South America Vegetable Seed Market. Bayer AG leverages its trait-stacked vegetable portfolio to sustain premium positioning in Brazilian greenhouse operations. Syngenta Group anchors its regional presence through localized breeding stations in Chile and Peru. Groupe Limagrain competes via specialized carrot and lettuce genetics tailored to Andean altitude conditions.
Vegetable seeds comprise dormant embryonic plants encapsulated within protective testas, engineered for specific germination rates, disease resistance loci, and abiotic stress tolerance thresholds that determine field establishment success. Their primary commercial purpose centers on transferring standardized genetic performance from breeding programs to commercial production systems across diverse agroecological zones. Hybrid seeds capture dominant value pools due to yield heterosis and farmer replant restrictions, while organic seeds represent the fastest-expanding category as Brazilian and Argentine export-oriented growers pursue EU organic equivalence compliance. Open-pollinated varieties retain structural importance among smallholder cooperatives seeking seed sovereignty and lower input costs.
Brazil's national seed regulator, MAPA, enforces cultivar registration and seed quality standards under Law 10.711, directly conditioning market access for foreign suppliers. ANVISA oversees pesticide-seed trait stacking approvals, creating dual compliance pathways for biotechnology-enhanced varieties. Argentina's INASE certification requirements and Chile's phytosanitary export protocols further fragment regulatory navigation. Stakeholders must monitor evolving equivalence agreements between Mercosur seed standards and EU organic certification frameworks to anticipate germplasm flow disruptions.
Market Dynamics
Hybrid trait stacking is compressing breeding cycles across South America while climate volatility forces rapid cultivar turnover in Brazil's Central-West corridor.
Growth Catalysts
- Protected agriculture corridors:São Paulo's greenhouse clusters drive demand for high-germination hybrid tomato and pepper varieties with uniform fruit set.
- EU organic equivalence frameworks:Brazilian export growers pursue certification compliance, expanding contract seed production for European supermarket chains.
- Phytosanitary digitization:Argentina's INASE electronic certification system accelerates cross-border germplasm flows from Chilean breeding stations.
Market Restraints
- Input cost volatility:Phosphorus-based seed coatings face price pressure from fertilizer export restrictions affecting Argentine processing facilities.
- Supply concentration risk:Parent line production clusters in southern Chile create single-point vulnerability for Andean carrot and lettuce genetics.
- Regulatory friction:Brazil's ANVISA trait-stacking approval timelines extend commercialization windows for virus-resistant squash varieties.
Strategic Opportunities
- Underpenetrated geographies:Colombia's Cundinamarca highland valleys lack hybrid onion seed distribution networks serving processing industry demand.
- Technology convergence:CRISPR-edited disease resistance loci combine with marker-assisted selection to compress breeding cycles for tropical spinach cultivars.
- Regulatory tailwinds:Mercosur seed standard harmonization proposals would streamline cultivar registration across Brazilian, Argentine, and Paraguayan territories.
Industry Challenges
- Skill specialization gaps:Quantitative genetics expertise for polyploid vegetable crops remains concentrated in Chilean public research institutes.
- Certification timeline compression:Organic seed multiplication protocols require three-year field isolation cycles that conflict with annual cultivar refresh demands.
- IP licensing complexity:Terminator technology restrictions and farmer-saved seed exemptions create enforcement asymmetries across national boundaries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Vegetable Seed Market |
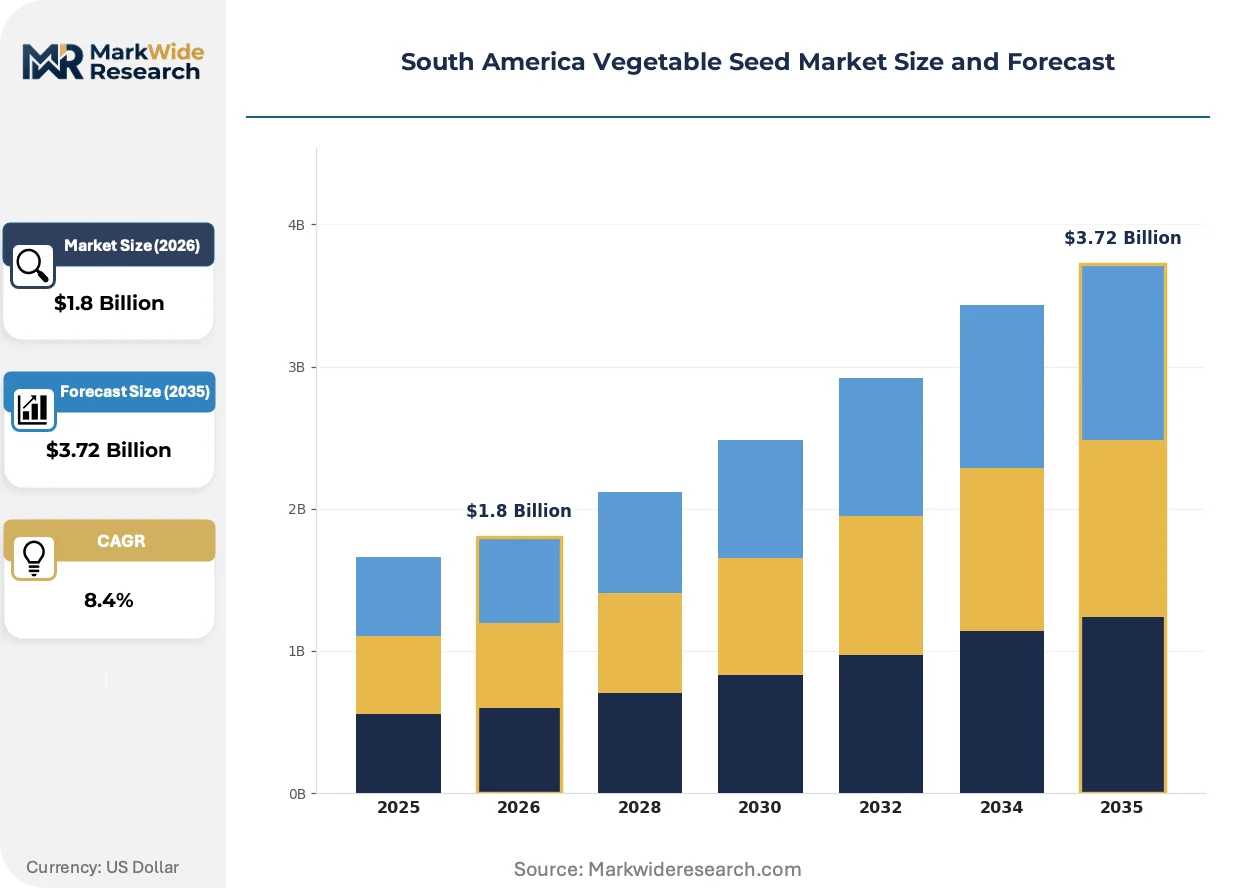
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.72 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hybrid Seeds, Open-Pollinated Seeds, Organic Seeds, GMO Seeds Crop Type: Tomato, Lettuce, Carrot, Cucumber Distribution Channel: Wholesale, Retail, Online, Direct Sales End User: Farmers, Commercial Growers, Home Gardeners, Agricultural Cooperatives |
| Companies Covered | Syngenta Group, Bayer AG, BASF SE, Groupe Limagrain, Rijk Zwaan Zaadteelt en Zaadhandel BV, Sakata Seeds Corporation, KWS SAAT SE & Co KGaA, Enza Zaden, Bejo Zaden BV, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Vegetable Seed Market Evolving Landscape
Digital phenotyping platforms are collapsing the gap between greenhouse selection and field performance validation across South American breeding programs.
Genomic selection algorithms is virtualizing early-stage yield prediction by replacing multi-location field trials with predictive models trained on historical performance databases. Brazilian protected agriculture operators adopt these platforms to accelerate hybrid tomato cultivar release schedules. The technology is virtualizing traditional germplasm evaluation infrastructure, compressing five-year breeding pipelines into eighteen-month cycles.
Argentina's INASE phytosanitary certification tightening for imported germplasm creates compliance bottlenecks for foreign seed suppliers entering the domestic market. The regulation forces parent line producers to establish localized quarantine facilities or partner with domestic multiplication agents. Small-scale vegetable cooperatives in Mendoza and Córdoba provinces face disproportionate documentation burdens, shifting procurement toward pre-certified hybrid distributors.
Direct-to-grower digital seed ordering is displacing traditional agrochemical retailer intermediaries in Brazil's Mato Grosso soybean-vegetable rotation belts. Large commercial operations contract proprietary germplasm through breeder-managed platforms that bundle genetic performance guarantees with agronomic advisory services. This channel compression concentrates most visible in Central-West states where single-source procurement contracts now cover eighty percent of hybrid pepper seed volume.
South America Vegetable Seed Market Segmentation
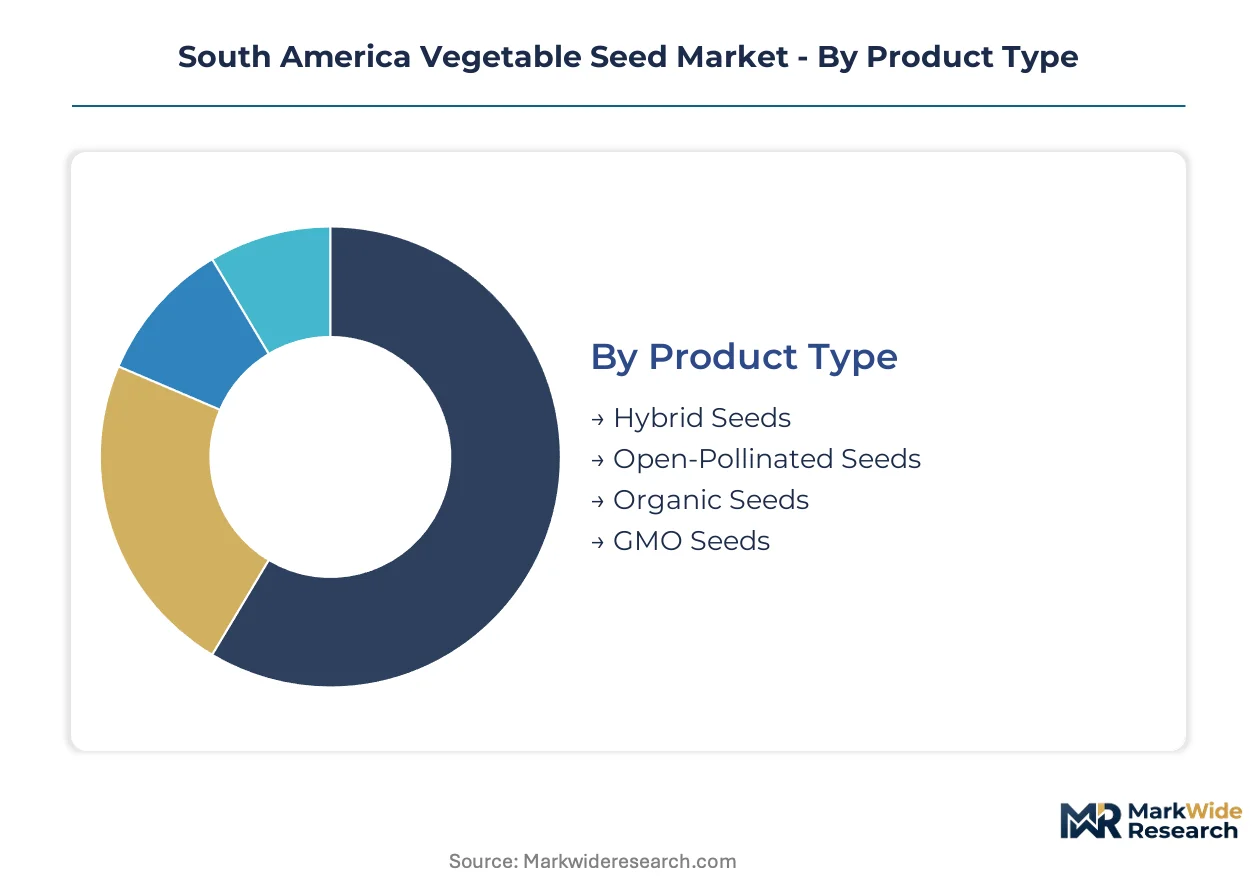
Vegetable seed segmentation across South America reflects divergent germplasm strategies between export-oriented commercial operations and input-constrained smallholders. Each dimension captures distinct value chain configurations, from trait-stacked hybrid licensing to cooperative-saved open-pollinated varieties.
Product Type:
Use-case spectrum spans high-input greenhouse operations requiring genetic uniformity to low-input systems prioritizing seed sovereignty and cost minimization.
- Hybrid Seeds:Cross-pollinated F1 varieties engineered for heterosis expression, disease resistance stacking, and synchronized maturity windows. Demand concentrates in São Paulo's protected agriculture corridors where Bayer AG and Syngenta Group license proprietary tomato and pepper germplasm under performance-guaranteed contracts.
- Open-Pollinated Seeds:Self-fertile varieties maintaining stable genetic expression across generations without controlled pollination infrastructure. Smallholder cooperatives in Brazil's Northeast and Argentina's interior provinces favor these for seed sovereignty and elimination of annual licensing fees.
- Organic Seeds:Multiplication protocols certified under EU organic equivalence frameworks for three-year field isolation cycles.
- GMO Seeds:Transgenic trait insertion for virus-resistant squash and insect-tolerant eggplant subject to ANVISA approval timelines.
The dominant share belongs to Hybrid Seeds, while Organic Seeds is closing the gap fastest.
Crop Type:
Volume concentration maps to processing industry location and protected agriculture infrastructure density.
- Tomato:Determinate and indeterminate growth habit varieties selected for brix content, shelf-life extension, and mechanical harvest compatibility. Brazil's Central-West rotation belts and São Paulo greenhouse clusters drive hybrid tomato seed procurement, with climate stress accelerating cultivar turnover for heat-tolerant fruit set.
- Lettuce:Crisphead, romaine, and leaf types bred for tipburn resistance and downy mildew tolerance. Andean altitude corridors in Peru and Chile concentrate specialized lettuce genetics development, with Groupe Limagrain targeting highland temperature differentials.
- Carrot:Nantes and Imperator types with root uniformity specifications for processing industry contracts.
- Cucumber:Parthenocarpic slicing and pickling types for protected cultivation systems.
Tomato commands the largest acreage commitment, though Lettuce is expanding most quickly in highland export zones.
Distribution Channel:
Channel economics reflect customer scale, technical support requirements, and working capital availability.
- Wholesale:Volume aggregation through agricultural cooperatives and regional distributors serving multi-farm procurement networks. Brazil's Mato Grosso soybean-vegetable rotation belts rely on wholesale channels for hybrid pepper seed bulk purchasing.
- Retail:Counter sales through agrochemical retailers with limited technical advisory capacity.
- Online:Direct-to-grower digital platforms displacing traditional intermediaries in Central-West states.
- Direct Sales:Breeder-managed contracts bundling germplasm with agronomic performance guarantees.
Wholesale retains structural importance for cooperative procurement, yet Direct Sales is gaining share fastest among large commercial operations.
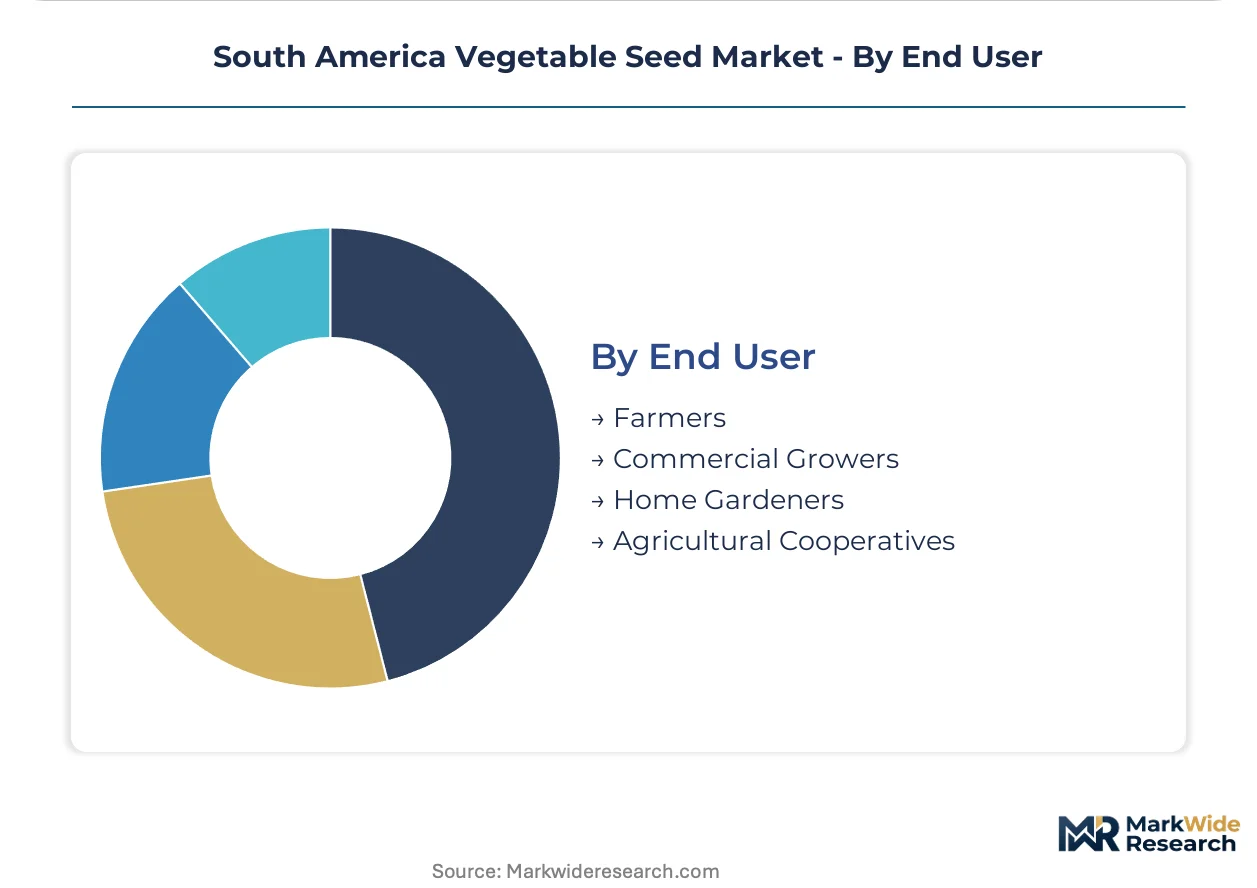
End User:
Customer segmentation reveals divergent price sensitivity, technical sophistication, and certification compliance requirements.
- Commercial Growers:Export-oriented operations pursuing EU organic equivalence and supermarket chain contract specifications. These stakeholders dominate hybrid tomato and pepper seed demand in São Paulo's greenhouse clusters.
- Farmers:Individual producers in Brazil's Central-West and Argentina's Pampas region operating mixed crop-livestock systems.
- Home Gardeners:Small-scale urban and peri-urban consumers with minimal technical support requirements.
- Agricultural Cooperatives:Member-owned enterprises aggregating procurement power and managing shared seed storage infrastructure.
Commercial Growers account for the dominant procurement volume, while Agricultural Cooperatives are expanding their collective purchasing fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Parent line production clusters in southern Chile and localized breeding stations across the Andean corridor concentrate germplasm development capacity. Brazilian import demand and Argentine regulatory requirements pull seed flows toward distinct compliance pathways. Cross-border phytosanitary digitization is compressing certification timelines for regional germplasm trade.
Brazil
São Paulo's protected agriculture corridors and Central-West soybean-vegetable rotation belts drive hybrid tomato and pepper seed procurement. ANVISA oversees pesticide-seed trait stacking approvals alongside MAPA cultivar registration under Law 10.711, creating dual compliance pathways for biotechnology-enhanced varieties. Mato Grosso states now see direct-to-grower digital platforms displace traditional agrochemical retailer intermediaries for eighty percent of hybrid pepper seed volume.
Argentina
Mendoza and Córdoba provinces host small-scale vegetable cooperatives facing documentation burdens from INASE phytosanitary certification tightening for imported germplasm. The national seed regulator's electronic certification system accelerates cross-border germplasm flows from Chilean breeding stations. Buenos Aires corridor processing industry demand pulls specialized carrot and lettuce genetics through pre-certified hybrid distributor networks.
Chile
Localized breeding stations in central valleys anchor specialized lettuce genetics development for Andean altitude conditions. The country's phytosanitary export protocols create compliance infrastructure for regional germplasm distribution. Southern Chile parent line production clusters represent single-point vulnerability for Andean carrot and lettuce genetics supply security.
Colombia
Cundinamarca highland valleys lack hybrid onion seed distribution networks despite processing industry demand expansion. The country's national seed regulator enforces cultivar registration requirements that condition market access for foreign suppliers. Bogotá corridor protected agriculture operators pursue EU organic equivalence compliance for export-oriented spinach and lettuce production.
Peru
Andean altitude corridors concentrate specialized lettuce genetics breeding for highland temperature differentials. The country's phytosanitary regulator maintains export certification protocols for EU-bound vegetable seed shipments. Lima coastal valleys host processing industry contract production demanding uniform root specifications for carrot and onion cultivars.
South America Vegetable Seed Market Competitive Landscape
Multinational agrochemical conglomerates and specialized vegetable breeding houses split the market between trait-stacked hybrid licensing and altitude-adapted germplasm development. Bayer AG leverages its vegetable portfolio for premium positioning in Brazilian greenhouse operations. Syngenta Group anchors regional presence through Chilean and Peruvian breeding stations. Groupe Limagrain competes via Andean-specialized carrot and lettuce genetics. Dominant competitive moves include intellectual property licensing revenue capture and direct-to-grower digital platform deployment.
Within the multinational agrochemical tier, Bayer AG and Syngenta Group exemplify trait-stacked portfolio strategies, while Groupe Limagrain occupies a position as altitude-specialized genetics provider. BASF SE and KWS SAAT SE & Co KGaA represent European-origin breeding houses with South American distribution networks. Sakata Seeds Corporation anchors the Asia-Pacific-origin specialist segment. These players sit within distinct archetypes: integrated agrochemical-seed conglomerates, regional breeding station operators, and crop-specific genetics specialists.
| Leading Market Players |
|---|
| Syngenta Group |
| Bayer AG |
| BASF SE |
| Groupe Limagrain |
| Rijk Zwaan Zaadteelt en Zaadhandel BV |
| Sakata Seeds Corporation |
| KWS SAAT SE & Co KGaA |
| Enza Zaden |
| Bejo Zaden BV |
| Others |
Value Network & Pricing Analysis
Single-source parent line production clusters in southern Chile determine both premium-mid-economy pricing spreads and supply chain vulnerability profiles across the South America Vegetable Seed Market. ANVISA trait-stacking approval timelines and INASE phytosanitary certification requirements create regulatory chokepoints that compress margins at standard tiers while inflating premiums for pre-certified germplasm.
Pricing Analysis
MAPA cultivar registration under Law 10.711 dictates the pricing tier structure across Brazilian territories. Three-tier pricing separates performance-guaranteed breeder contracts from wholesale distributor markups and cooperative-saved open-pollinated seed economics. Certification grade and volume scale differentiate price bands, with EU organic equivalence compliance commanding substantial premiums. Cost compression in standard-tier hybrid pepper seed is intensifying because direct-to-grower digital platforms displace traditional agrochemical retailer intermediaries. Smallholder cooperatives in Brazil's Northeast exhibit highest price sensitivity, while São Paulo greenhouse operators prioritize genetic performance guarantees over unit cost.
Supply Chain Analysis
Chilean phytosanitary export protocols as restricted-technology controls limit germplasm flow velocities from southern Chile parent line facilities. Supply concentration rests on Chile, Brazil, and Argentina as the dominant geographic nodes, with Peruvian Andean breeding stations gaining specialized lettuce genetics share. Raw material dependencies include phosphorus-based seed coatings, controlled-pollination infrastructure, and quarantine facility capacity. Single-source vulnerability concentrates in southern Chile carrot and lettuce parent line clusters. Distribution runs through breeder-managed direct contracts for large commercial operations, wholesale cooperative networks for smallholders, and emerging digital platforms in Brazil's Central-West corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among São Paulo greenhouse operators and Mato Grosso commercial growers through direct-to-grower digital procurement consolidation. This shift compresses intermediary margins and restructures channel economics across hybrid seed distribution.
For Market Incumbents: Build IP licensing moats around CRISPR-edited disease resistance loci and marker-assisted selection platforms to defend against technology convergence threats from emerging breeding houses. Deepen backward integration into Chilean parent line production to secure supply sovereignty. Invest in ANVISA pre-approval cultivar pipelines to compress commercialization windows for virus-resistant squash varieties. For New Entrants and Emerging Players: Colombia's Cundinamarca highland valleys represent the most penetrable entry point, with hybrid onion seed distribution gaps unaddressed despite processing industry demand expansion. Andean altitude-specialized lettuce genetics for highland temperature differentials offer second-mover advantage against established altitude players. Pursue EU organic equivalence certification as the primary go-to-market angle to access Brazilian export-oriented commercial grower contracts. For Investors and Strategic Acquirers: Mercosur seed standard harmonization proposals reshape the acquisition landscape by streamlining cultivar registration across Brazilian, Argentine, and Paraguayan territories. Long-term viability over the projection horizon favors altitude-specialized breeding stations with established quarantine infrastructure and localized multiplication capacity. Target acquisition archetypes include Chilean public research institute spinouts holding quantitative genetics expertise for polyploid vegetable crops. Monitor INASE electronic certification system adoption rates as the critical inflection signal for cross-border germplasm flow acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Grower Digital Platform Deployment | Bayer AG and Syngenta Group leverage breeder-managed contracts to capture São Paulo greenhouse procurement volume. |
| Localized Breeding Station Expansion | Chilean and Peruvian facilities anchor altitude-adapted lettuce genetics development for Andean export zones. |
| EU Organic Equivalence Certification Investment | Brazilian commercial growers secure supermarket chain contracts through three-year field isolation protocol compliance. |
| CRISPR-Edited Trait Pipeline Development | Marker-assisted selection compresses tropical spinach breeding cycles from multi-year field trials to predictive genomic models. |
| Phytosanitary Digitization Partnership | Argentina's INASE electronic certification accelerates cross-border parent line flows from Chilean multiplication facilities. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with vegetable seed breeding directors, MAPA regulatory affairs specialists, greenhouse operations managers, cooperative procurement heads, and ANVISA compliance officers. Secondary validation drew from MAPA cultivar registration databases, INASE certification records, EU organic equivalence framework documentation, Mercosur trade flow statistics, and Chilean export phytosanitary filings. Bottom-up acreage and procurement volume estimates were triangulated against top-down market value reconstructions.
Calibration against historical cultivar release cycles and adoption curves anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type hierarchy, crop-specific genetic requirements, distribution channel economics, and end-user scale classifications. CAGRs were derived from trend extrapolation of hybrid adoption rates, organic certification expansion trajectories, and protected agriculture infrastructure investment patterns. Climate stress indices and regulatory approval timeline distributions served as vegetable seed-specific forecast inputs.
Practitioners should monitor ANVISA trait-stacking approval velocity, INASE certification requirement amendments, and Mercosur harmonization ratification progress for early signals of forecast deviation. Forecasts reflect assumptions regarding continued EU organic equivalence framework stability and sustained Chilean parent line production capacity. Material shifts in phytosanitary digitization adoption rates or germplasm export control tightening would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
South America Seed Market
Seeds
Organic Seed Market
Seeds
Vegetable Seed Protein Market
Seeds
Global Sports Turf Seed Market
Seeds
Celery Seed Oil Market
Seeds
South America Forage Seed Market
Seeds
Sesame Seeds Market
Seeds
Europe Sesame Seed Market
Seeds
Mexico Seed Market
Seeds
Garlic Chive Seeds Market
Seeds
Cowpeas Market
Seeds
Eucommia Seed Oil Market
Seeds
Garden Seeds Market
Seeds
Europe Quinoa Seed Market
Seeds
Global Alfalfa Seed Market
Seeds
Pumpkin Seeds Market