
 Europe Chia Seeds Market | 2026-2036
Europe Chia Seeds Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Chia Seeds Market Intelligence
Asset-light contract farming and third-party processing arrangements is fragmenting competitive control across the Europe chia seeds landscape. Benexia Europa S.A. anchors South American supply linkages through dedicated grower networks in Paraguay and Bolivia. Glanbia PLC leverages its nutrition ingredient platform to extend chia protein isolates into sports nutrition formulations. Naturkost Übelhör GmbH & Co. KG dominates Central European organic distribution through long-standing retailer relationships in Germany and Austria.
Chia seeds are oval-shaped seeds of Salvia hispanica containing approximately 30-35% oil, 15-25% protein, and 35-40% dietary fiber by weight, with alpha-linolenic acid comprising over 60% of the oil fraction. The seeds form hydrophilic mucilage when hydrated, a functional property exploited in egg replacement, texture modification, and clean-label binding across European food manufacturing. Organic product type commands premium shelf positioning in German and French supermarkets, though conventional chia sustains volume leadership through price-sensitive bakery and pet food channels. Online retail distribution is accelerating fastest among direct-to-consumer wellness brands, while specialty stores occupy the margin-rich niche for heirloom and single-origin chia variants.
EFSA novel food authorizations govern chia seed and chia oil market entry, with specific purity thresholds for pesticide residues and heavy metals shaping import sourcing from Latin America. EU Organic Regulation 2018/848 certification requirements filter supplier eligibility, particularly for German and Austrian private-label programs. REACH compliance for chia oil cosmetic applications adds formulation cost layers for personal care entrants. Stakeholders must monitor EFSA health claim evaluation pathways for omega-3 positioning, as approved claims would unlock pharmaceutical-channel pricing tiers and reshape competitive investment priorities across the value chain.
Market Dynamics
EFSA novel food authorizations and EU Organic Regulation 2018/848 certification requirements are fragmenting supplier eligibility while concentrating procurement power among German and Austrian private-label programs with compliant Latin American supply chains.
Growth Catalysts
- Clean-label bakery integration:Spanish and Italian food processors exploit chia's hydrophilic mucilage properties for egg replacement and texture modification, eliminating synthetic additives from ingredient decks.
- EFSA novel food streamlining:Accelerated approval pathways for chia oil and seed variants reduce time-to-market for health supplement brands in Germany and France.
- Nordic functional food concentration:Organic chia oil demand clusters in Scandinavian wellness markets, driven by omega-3 positioning in premium functional beverages and infant nutrition.
Market Restraints
- Latin American supply concentration:Paraguay and Bolivia dominate raw seed sourcing, exposing European processors to weather-induced crop volatility and currency fluctuation risks.
- REACH compliance cost layers:Cosmetic-grade chia oil entrants face elevated formulation expenses for personal care applications, compressing margin structures versus food-grade alternatives.
- Flaxseed substitution threat:Established omega-3 alternatives with lower price points and deeper retail penetration limit chia's addressable market in price-sensitive bakery channels.
Strategic Opportunities
- French pharmaceutical-channel positioning:Pending EFSA health claim approvals for omega-3 cardiovascular benefits would unlock prescription-tier pricing and reshape investment priorities across the value chain.
- Direct-to-consumer wellness acceleration:Online retail distribution channels are capturing margin-rich segments among subscription-based nutrition brands bypassing traditional wholesale structures.
- Pet food functionalization:Conventional chia sustains volume leadership through integration into premium pet nutrition formulations targeting digestive health and coat quality positioning.
Industry Challenges
- Organic certification timeline compression:EU Organic Regulation 2018/848's stricter residue thresholds and traceability documentation requirements extend supplier onboarding cycles for Central European distributors.
- Specialty agronomy skill scarcity:Contract farming networks require trained agronomists capable of managing Salvia hispanica cultivation protocols, a capability concentrated among South American grower cooperatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Chia Seeds Market |
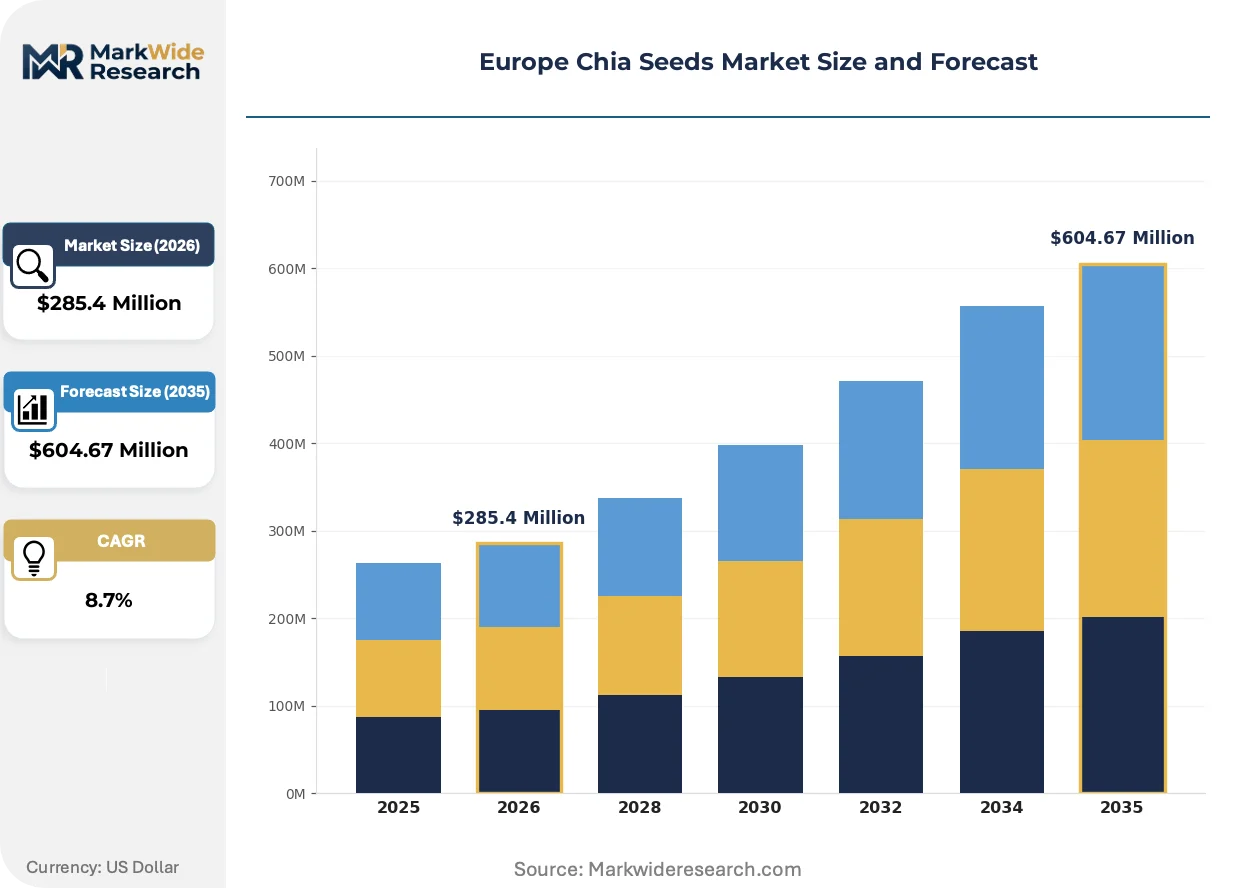
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $604.67 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic, Conventional, Raw, Processed End User: Food & Beverage, Health Supplements, Personal Care, Pet Food Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Food Service Form: Whole Seeds, Ground Seeds, Oil, Ready-to-Eat |
| Companies Covered | The Chia Co., Nutiva, Mamma Chia, Benexia Europa S.A., Garden of Life, Navitas Organics, Chia Bia, Glanbia PLC, Naturkost Übelhör GmbH & Co. KG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Chia Seeds Market Strategic Shifts & Innovations
Microencapsulation and cold-press extraction technologies are reshaping chia oil stability and bioavailability profiles, while regulatory clarity on novel food applications accelerates format diversification beyond whole seeds.
Cold-pressed chia oil microencapsulation is collapsing the stability limitations that previously constrained beverage and infant formula applications. German functional food manufacturers are adopting spray-dried chia oil powders at accelerated pace, replacing fish oil in vegan omega-3 formulations. This technological shift is collapsing the format barrier between oil and powder segments, enabling single-ingredient positioning across previously incompatible product categories.
EFSA's evolving stance on chia seed novel food authorizations is tightening purity thresholds for pesticide residues and heavy metals. This regulatory pressure is forcing Latin American suppliers to invest in dedicated organic cultivation blocks and third-party laboratory verification infrastructure. French and German import intermediaries are most affected, responding by consolidating procurement relationships with certified grower networks in Paraguay and Bolivia.
Specialty stores and direct-to-consumer channels are displacing conventional wholesale distribution for heirloom and single-origin chia variants. Wellness brands in Austria and Switzerland are building subscription models around provenance storytelling and small-batch processing claims. This channel rotation is most visible in Alpine urban centers, where consumers demonstrate willingness to absorb premium pricing for traceability documentation and artisanal processing narratives.
Europe Chia Seeds Market Segmentation
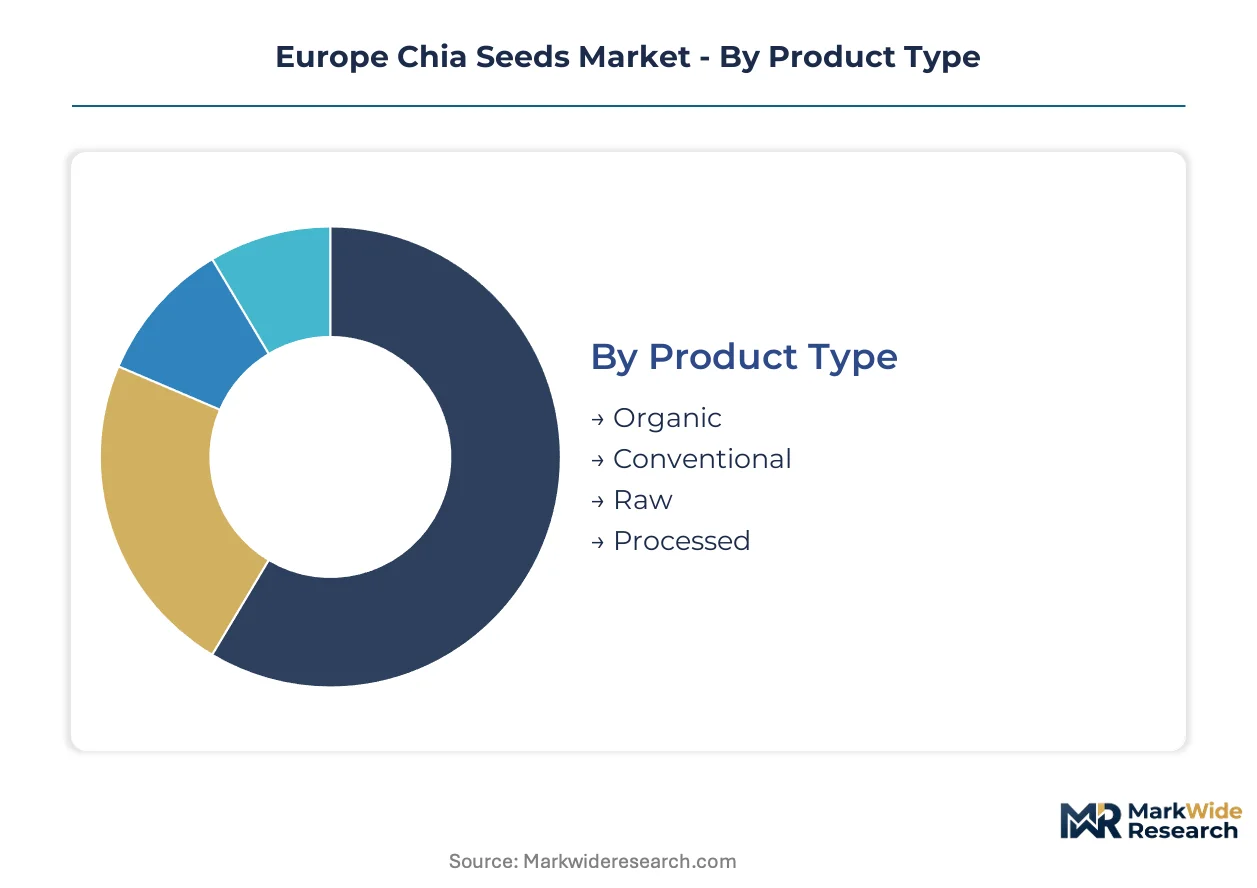
Chia seed segmentation in Europe reflects divergent supply chain economics and regulatory compliance burdens across organic certification tiers, end-use applications, and distribution channels. Each dimension carries distinct margin structures and growth trajectories that reshape procurement priorities for processors and retailers.
Product Type:
Mature conventional supply lines dominate volume throughput while emerging organic certification requirements fragment supplier eligibility.
- Organic:EU Organic Regulation 2018/848 compliance mandates residue thresholds and traceability documentation that extend supplier onboarding cycles. German and Austrian private-label programs concentrate procurement power among certified grower networks in Paraguay and Bolivia, absorbing premium pricing for shelf positioning in French and German supermarkets.
- Conventional:Price-sensitive bakery and pet food channels sustain volume leadership through Latin American supply concentration. Weather-induced crop volatility and currency fluctuation risks from Paraguay and Bolivia sourcing expose European processors to input cost instability.
- Raw:Unprocessed seeds retain maximum oil and protein integrity for ingredient manufacturers with in-house milling capabilities.
- Processed:Pre-cleaned and graded formats reduce handling costs for mid-scale food processors lacking dedicated seed preparation infrastructure.
Conventional handles the majority of throughput; organic is the fastest mover on share.
End User:
Application diversity spans food-grade commodity markets to pharmaceutical-channel positioning, with regulatory clarity determining addressable margin tiers.
- Food & Beverage:Spanish and Italian processors exploit hydrophilic mucilage properties for egg replacement and texture modification in clean-label bakery lines. EFSA novel food authorizations govern chia seed and chia oil market entry, with specific purity thresholds shaping import sourcing strategies.
- Health Supplements:German and French brands are expanding chia-based SKUs as accelerated approval pathways reduce time-to-market. Pending EFSA health claim approvals for omega-3 cardiovascular benefits would unlock prescription-tier pricing.
- Personal Care:REACH compliance for chia oil cosmetic applications adds formulation cost layers, compressing margin structures versus food-grade alternatives.
- Pet Food:Premium pet nutrition formulations targeting digestive health and coat quality positioning sustain volume demand for conventional grades.
Food & Beverage commands the largest volume base; Health Supplements is expanding most quickly on regulatory tailwinds.
Distribution Channel:
Channel economics separate margin-rich direct relationships from price-competitive wholesale structures.
- Online Retail:Subscription-based nutrition brands in Austria and Switzerland bypass traditional wholesale structures through provenance storytelling and small-batch processing claims. Alpine urban centers demonstrate willingness to absorb premium pricing for traceability documentation.
- Supermarkets:German and French retail chains drive organic product type shelf positioning through long-standing supplier relationships with Central European distributors.
- Specialty Stores:Heirloom and single-origin chia variants occupy niche positioning for artisanal processing narratives.
- Food Service:Industrial-scale bakery and beverage manufacturers source conventional grades through contracted intermediaries.
Supermarkets handle the majority of throughput; Online Retail is gaining share fastest on direct-to-consumer wellness acceleration.
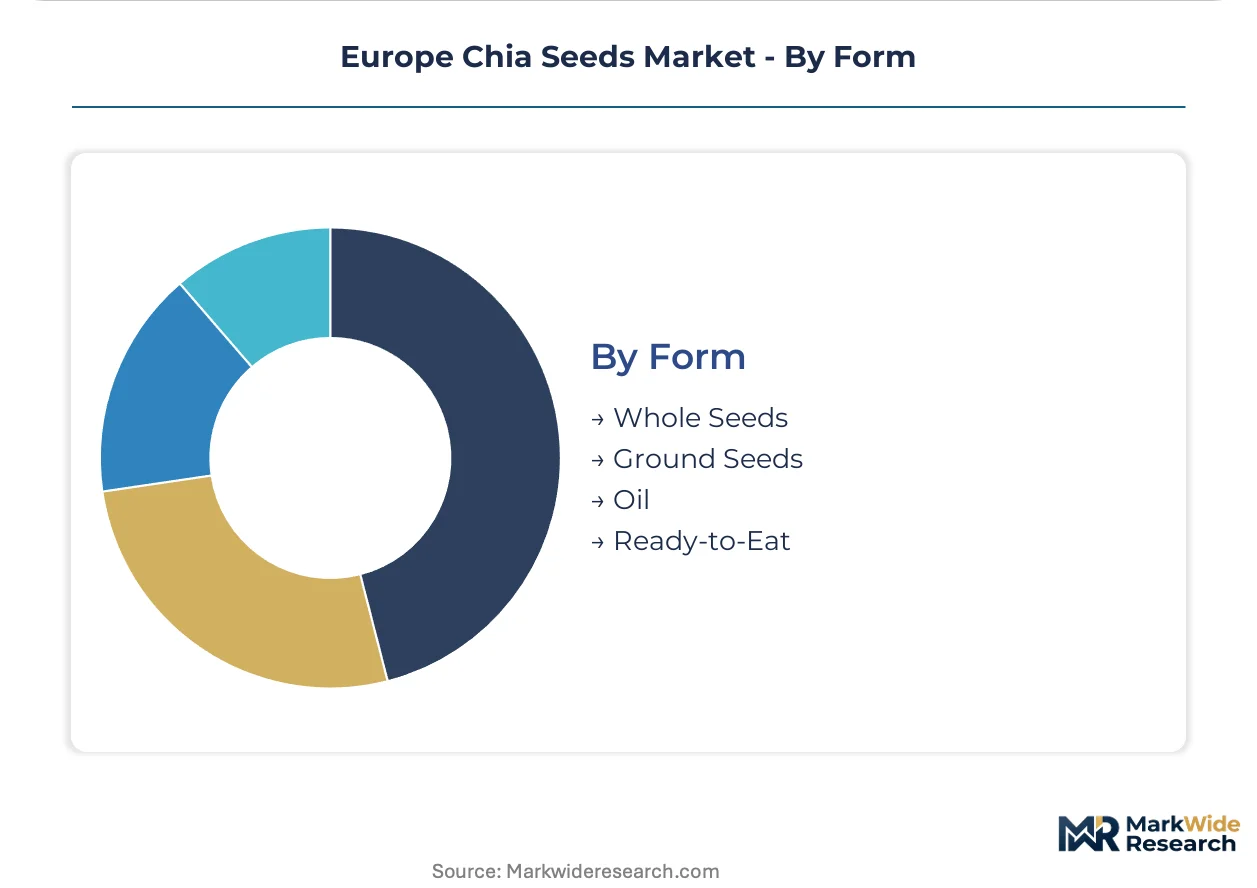
Form:
Processing intensity determines application compatibility and stability profiles across incompatible product categories.
- Whole Seeds:Intact seeds retain maximum shelf stability for retail packaging and home hydration applications.
- Ground Seeds:Milled formats enable immediate nutrient bioavailability and seamless integration into flour-based formulations.
- Oil:Cold-press extraction and microencapsulation technologies are collapsing stability limitations that previously constrained beverage and infant formula applications. German functional food manufacturers adopt spray-dried chia oil powders to replace fish oil in vegan omega-3 formulations.
- Ready-to-Eat:Pre-hydrated and seasoned formats target convenience-oriented consumers in direct-to-consumer channels.
Whole Seeds handles the majority of throughput; Oil is climbing the fastest on microencapsulation technology adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German and French health supplement buyers concentrate premium-grade demand, while Spanish and Italian food processors anchor clean-label bakery integration across Mediterranean manufacturing corridors.
Germany
Private-label organic programs at Aldi Süd and Rewe Group absorb premium chia volumes for shelf-stable retail positioning. EFSA novel food authorizations streamline ingredient access for Berlin-based wellness brands expanding chia-based SKUs. Bavarian functional food clusters around Munich leverage cold-press extraction infrastructure for omega-3 oil microencapsulation.
France
Pending EFSA health claim approvals for cardiovascular positioning concentrate pharmaceutical-channel investment around Lyon and Paris. ANSM cosmetic ingredient oversight shapes REACH compliance layering for chia oil personal care entrants. Provençal organic distribution networks consolidate procurement from certified Paraguayan grower cooperatives.
Spain
Clean-label bakery processors in Catalonia exploit chia's hydrophilic mucilage for egg replacement in industrial-scale formulations. Spanish food safety agency AESAN enforces EFSA-aligned residue thresholds for Latin American seed imports. Valencia-based contract manufacturers integrate ground chia into gluten-free flour blends for export markets.
Italy
Artisanal pasta and baked goods producers in Emilia-Romagna adopt chia enrichment for protein-fortified regional specialties. Italian Ministry of Health novel food notifications govern chia oil cosmetic applications alongside food-grade pathways. Milan metropolitan wellness retailers command premium positioning for single-origin chia variants.
Nordic Region
Swedish and Danish functional beverage formulators concentrate organic chia oil demand for infant nutrition and vegan omega-3 positioning. Swedish Food Agency organic certification alignment with EU Regulation 2018/848 filters supplier eligibility for Stockholm-based distributors. Oslo and Copenhagen urban centers demonstrate subscription-model uptake for traceability-documented chia products.
Europe Chia Seeds Market Key Industry Players
Channel-controlling players compete with product-specialist players across fragmented procurement tiers. German and Austrian distributors leverage long-standing retailer relationships to dominate organic shelf positioning. South American supply-anchored entities control raw seed access through dedicated grower networks. Three strategic archetypes emerge: compliance-heavy organic certifiers, scale-driven conventional processors, and provenance-focused direct-to-consumer brands. Competitive moves concentrate on backward integration into Latin American cultivation blocks and portfolio diversification toward chia oil microencapsulation formats.
Among South American supply-anchored entities, Benexia Europa S.A. represents the dedicated grower network archetype with Paraguay and Bolivia linkages. Glanbia PLC occupies a position within nutrition ingredient platform players extending chia protein isolates into sports nutrition. Naturkost Übelhör GmbH & Co. KG exemplifies Central European organic distribution specialists with entrenched German and Austrian retailer relationships. These three entities anchor distinct competitive vectors without overlapping strategic positioning.
| Leading Market Players |
|---|
| The Chia Co. |
| Nutiva |
| Mamma Chia |
| Benexia Europa S.A. |
| Garden of Life |
| Navitas Organics |
| Chia Bia |
| Glanbia PLC |
| Naturkost Übelhör GmbH & Co. KG |
| Others |
Cost & Logistics Intelligence
Paraguayan and Bolivian grower cooperatives anchor upstream seed supply, concentrating margin capture with EFSA-compliant import intermediaries in France and Germany who command pharmaceutical-channel premiums. Organic certification under EU Regulation 2018/848 stratifies pricing power across the value chain, with residue-tested lots absorbing cost premiums that downstream private-label programs partially offset through volume commitments.
Pricing Analysis
Certification grade under EU Organic Regulation 2018/848 creates the primary spread between organic and conventional tiers, with EFSA novel food purity thresholds adding a secondary differentiation layer for pharmaceutical-grade chia oil. Three-tier pricing structure across organic premium, conventional standard, and pet food economy levels reflects input cost stratification from Latin American sourcing. Cost compression in conventional grades is intensifying because flaxseed substitution limits pricing power in price-sensitive bakery channels. Pet food manufacturers demonstrate highest price sensitivity, while Nordic functional beverage formulators absorb organic premiums for infant nutrition positioning.
Supply Chain Analysis
Extended payment terms from German and Austrian distributors to Paraguayan grower cooperatives compress working capital cycles for upstream suppliers, forcing reliance on supply-chain finance facilities. Raw seed sourcing draws from Bolivia, Paraguay, and Argentina, with organic cultivation blocks concentrated among certified cooperatives in the Gran Chaco region. Single-source vulnerability to weather-induced crop volatility in these South American production zones exposes European processors to input disruption. Distribution runs through Rotterdam and Hamburg port intermediaries for conventional grades, while organic certified lots bypass commodity exchanges through direct grower-processor contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EFSA health claim evaluation pathways for omega-3 cardiovascular positioning fragment the competitive landscape into regulatory-fast and regulatory-slow archetypes, creating acquisition opportunities for compliance-heavy specialists. Clean-label bakery integration and direct-to-consumer wellness acceleration generate distinct demand niches with divergent margin profiles.
For Market Incumbents: Harden EFSA novel food compliance infrastructure against pending purity threshold tightening, locking in pharmaceutical-channel access before health claim approvals unlock prescription-tier pricing. Deepen backward integration into certified organic cultivation blocks in Paraguay to secure residue-compliant supply for German private-label programs. Absorb flaxseed substitution pressure through chia protein isolate diversification into sports nutrition formats. For New Entrants and Emerging Players: Online subscription channels for traceability-documented single-origin chia in Alpine urban centers represent the most penetrable entry point, bypassing entrenched supermarket wholesale structures. Microencapsulation technology licensing from German functional food clusters enables beverage and infant formula applications without capital-heavy extraction infrastructure. Target provenance storytelling and small-batch processing claims as the primary go-to-market angle. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed Central European organic distributors holding long-standing retailer relationships in Germany and Austria. Five-to-ten year viability hinges on EFSA health claim approval timing and subsequent pharmaceutical-channel pricing tier emergence. Monitor EFSA omega-3 cardiovascular benefit evaluation announcements as the critical inflection signal for value chain investment priority shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Organic Cultivation | Paraguayan grower cooperative control secures EU 2018/848 residue compliance for pharmaceutical-channel access. |
| Chia Oil Microencapsulation Technology Licensing | Spray-dried powder formats collapse stability barriers for German vegan omega-3 beverage formulations. |
| Direct-to-Consumer Subscription Model Launch | Alpine urban provenance storytelling captures margin-rich segments bypassing conventional wholesale structures. |
| EFSA Novel Food Compliance Infrastructure Investment | Accelerated approval pathways reduce time-to-market for French health supplement brand expansion. |
| Pet Food Functionalization Partnership | Conventional grade volume placement targets digestive health positioning in premium pet nutrition channels. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with chia seed importers, organic certification specialists, EFSA regulatory consultants, and German supermarket category buyers; and secondary validation through EU TRACES trade data, EFSA novel food authorization registers, organic certification body disclosures, and customs import records. Bottom-up volume modeling triangulated against top-down market sizing from ingredient platform revenue disclosures.
Forecast inputs span organic versus conventional grade splits, food-grade versus pharmaceutical-channel end-use segmentation, and online retail versus supermarket distribution channel shares across the projection horizon. CAGRs derive from regression analysis against EFSA approval timeline scenarios and Nordic functional food adoption curves. Modeled variables include microencapsulation technology penetration rates and EU Organic Regulation 2018/848 certification timeline compression effects.
Macroeconomic conditions sit as an overlay; deviation in euro-to-South American currency exchange rates or Latin American drought frequency would shift the trajectory. Forecasts reflect documented assumptions around EFSA health claim evaluation pacing and EU organic certification threshold stability. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Crambe Abyssinica Seed Oil Market
Seeds
India Forage Seed Market
Seeds
South America Vegetable Seed Market
Seeds
Sweet Corn Seeds Market
Seeds
Vietnam Seed Market
Seeds
Philippines Rice Seed Market
Seeds
Sri Lanka Seed Market
Seeds
Helianthus Annuus (Sunflower) Market
Seeds
Europe Quinoa Seed Market
Seeds
Mexico Seed Market
Seeds
Faba Beans Market
Seeds
Global Wheat Seed Market
Seeds
Fruit Tomatoes Seed Market
Seeds
Africa Chia Seeds Market
Seeds
Europe Cannabis Seeds Market
Seeds
Australia Forage Seed Market