
 Global Seed Market | 2026-2036
Global Seed Market Size, Share, and Industry Trends Forecast 2026-2036
Global Seed Market Outlook
The EU Green Deal is consolidating demand around climate-resilient germplasm as European growers face tightening sustainability mandates. Bayer leverages its trait pipeline to anchor positions in glyphosate-tolerant row crops. Corteva Agriscience sustains R&D intensity across hybrid corn and soybean platforms. Syngenta Group competes through integrated crop solutions that bundle seed with crop protection chemistry.
Seed refers to a mature ovule containing an embryonic plant, stored nutrients, and a protective coat, engineered or selected for specific germination rates, vigor, and resistance profiles to serve as the foundational input for crop production and food systems. Cereals occupy the largest volume share due to wheat and rice staple demand, while genetically modified traits capture premium pricing in markets with regulatory acceptance. Hybrid varieties dominate margin pools in vegetables and corn where farmer willingness to pay for yield stability runs highest.
The USDA, EFSA, and China's Ministry of Agriculture collectively shape approval pathways for biotech traits, germplasm import protocols, and seed treatment chemistries. These frameworks determine which varieties reach farmers and how quickly novel genetics cross borders. Stakeholders must monitor evolving gene-editing classifications as regulatory divergence between major growing regions intensifies sourcing complexity.
Market Dynamics
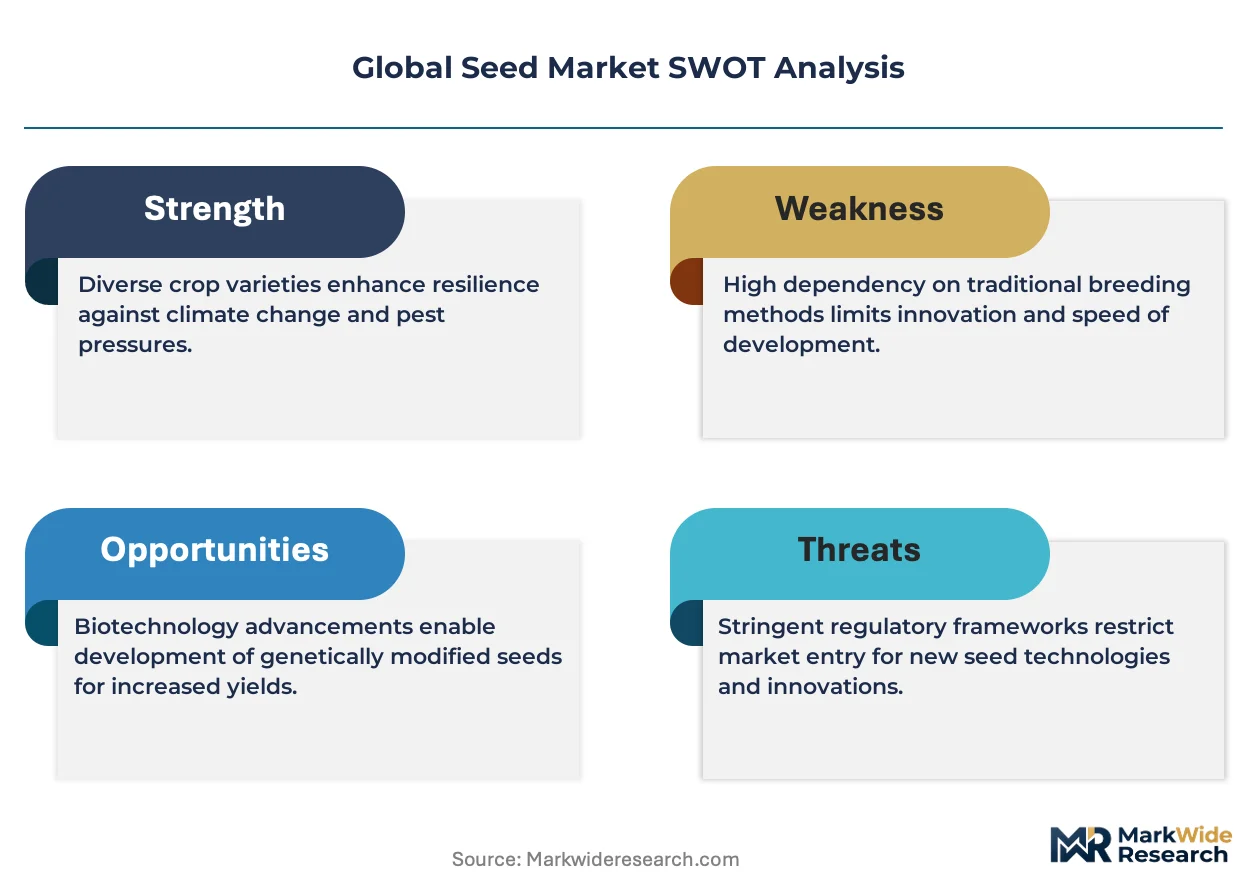
Biotechnology patent cliffs and divergent gene-editing classifications across the USDA, EFSA, and China's Ministry of Agriculture are forcing seed companies to maintain parallel regulatory dossiers, inflating R&D overhead and compressing time-to-market for novel traits.
Growth Catalysts
- EU Green Deal sustainability mandates:European growers face tightening crop-input requirements that favor climate-resilient germplasm with documented carbon-footprint reductions.
- Brazilian soybean procurement intensity:Commercial agriculture expansion in Mato Grosso and Goiás drives concentrated demand for high-yielding biotech-enhanced varieties.
- Gene-editing advancement:CRISPR-Cas9 applications accelerate trait development timelines for drought tolerance and disease resistance profiles.
Market Restraints
- Regulatory fragmentation:Divergent approval pathways between the USDA, EFSA, and China's Ministry of Agriculture create redundant field-trial requirements and delay commercial launches.
- Input cost volatility:Fertilizer and energy price swings squeeze farmer margins, reducing willingness to pay premium prices for certified seed.
- Trait licensing concentration:Patent thickets around glyphosate tolerance and insect-resistance genes limit independent breeding program access.
Strategic Opportunities
- Indian smallholder penetration:Hybrid rice and millet varieties remain underdeployed across Bihar and Uttar Pradesh, offering volume expansion potential.
- Carbon credit bundling:Seed-plus-sequestration contracts align with EU Green Deal compliance frameworks and create recurring revenue streams.
- Digital agronomy convergence:Integration of IoT field sensors with predictive germplasm selection optimizes planting prescriptions for variable soils.
Industry Challenges
- Phytosanitary certification delays:Cross-border germplasm movement requires multi-jurisdiction phyto-sanitary permits that stall breeding material exchange.
- Trait-stacking complexity:Pyramiding multiple biotech traits into elite lines extends development cycles and raises regulatory submission costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Seed Market |
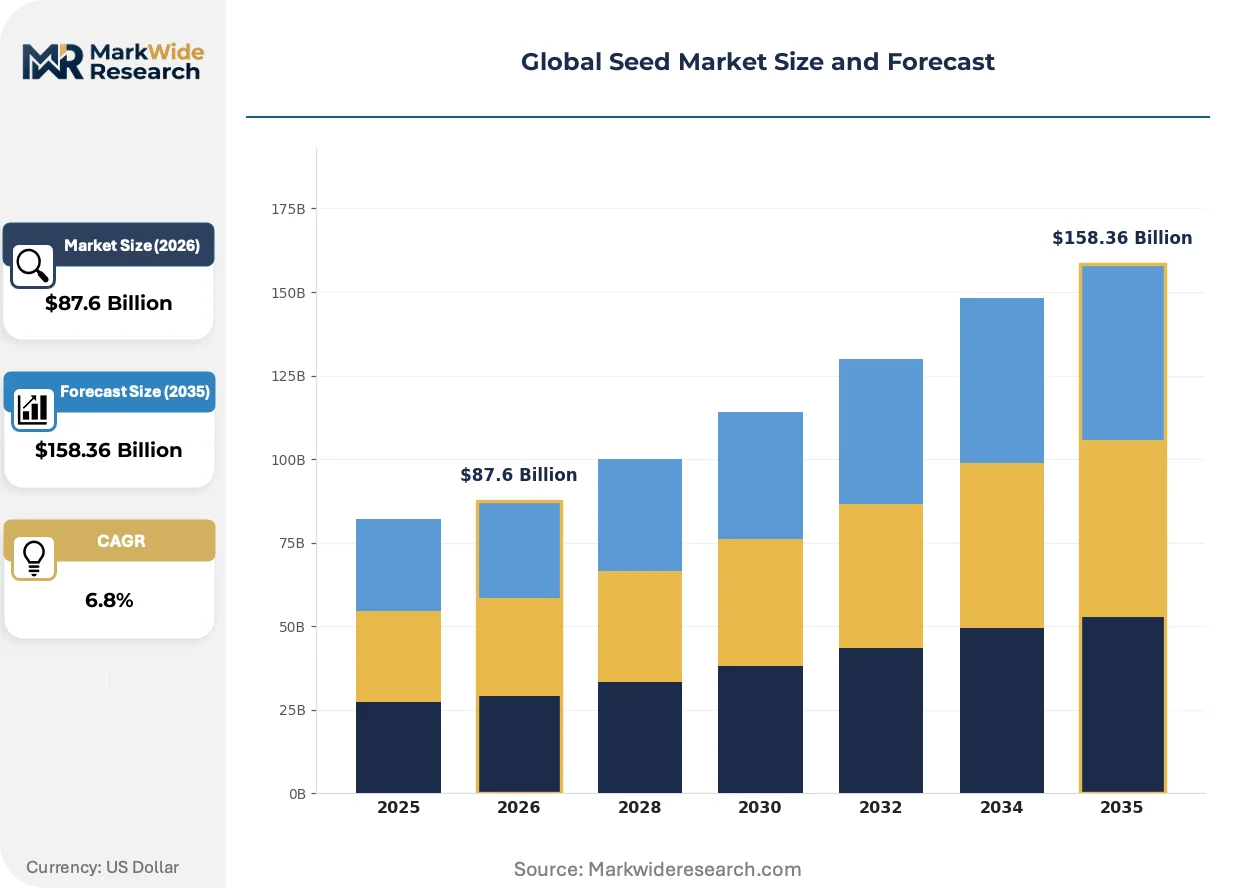
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $158.36 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cereals, Vegetables, Fruits, Oilseeds End Use: Agriculture, Horticulture, Home Gardening, Research Trait: Genetically Modified, Organic, Hybrid, Conventional Packaging Type: Bags, Bulk Containers, Seed Packs, Others |
| Companies Covered | Bayer, Corteva Agriscience, Syngenta Group, BASF, Groupe Limagrain, KWS SAAT, Sakata Seed Corporation, Land O'Lakes, Takii, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Seed Market Strategic Shifts
Digital phenotyping platforms and machine-learning trait prediction are compressing traditional breeding cycles. These tools enable real-time genotype-environment matching that was previously impossible at scale.
High-throughput phenotyping platforms combine drone-mounted multispectral sensors with automated greenhouse imaging to capture plant performance metrics across thousands of plots simultaneously. Large-scale corn and soybean breeding programs in the US Corn Belt deploy these systems to accelerate parent selection. This infrastructure is automating data collection pipelines that previously required manual scoring teams, reducing per-line evaluation costs and expanding the genetic diversity accessible to commercial programs.
REACH and the EU Green Deal are tightening residue limits on seed-treatment chemistries and mandating full lifecycle carbon disclosures for crop inputs. European seed companies now face compliance costs for neonicotinoid alternatives and biostimulant coating formulations. Vegetable seed producers in the Netherlands and Spain are restructuring supply chains to meet CSRD reporting requirements ahead of the 2027 enforcement window.
Farmer buying committees and cooperative procurement pools are displacing individual dealer relationships for major row-crop purchases. These aggregated buyers negotiate volume discounts and performance guarantees that fragment brand loyalty. This pattern concentrates purchasing power most visibly across the Brazilian Cerrado, where soybean growers in Mato Grosso have consolidated input procurement through regional cooperatives.
Global Seed Market Segmentation
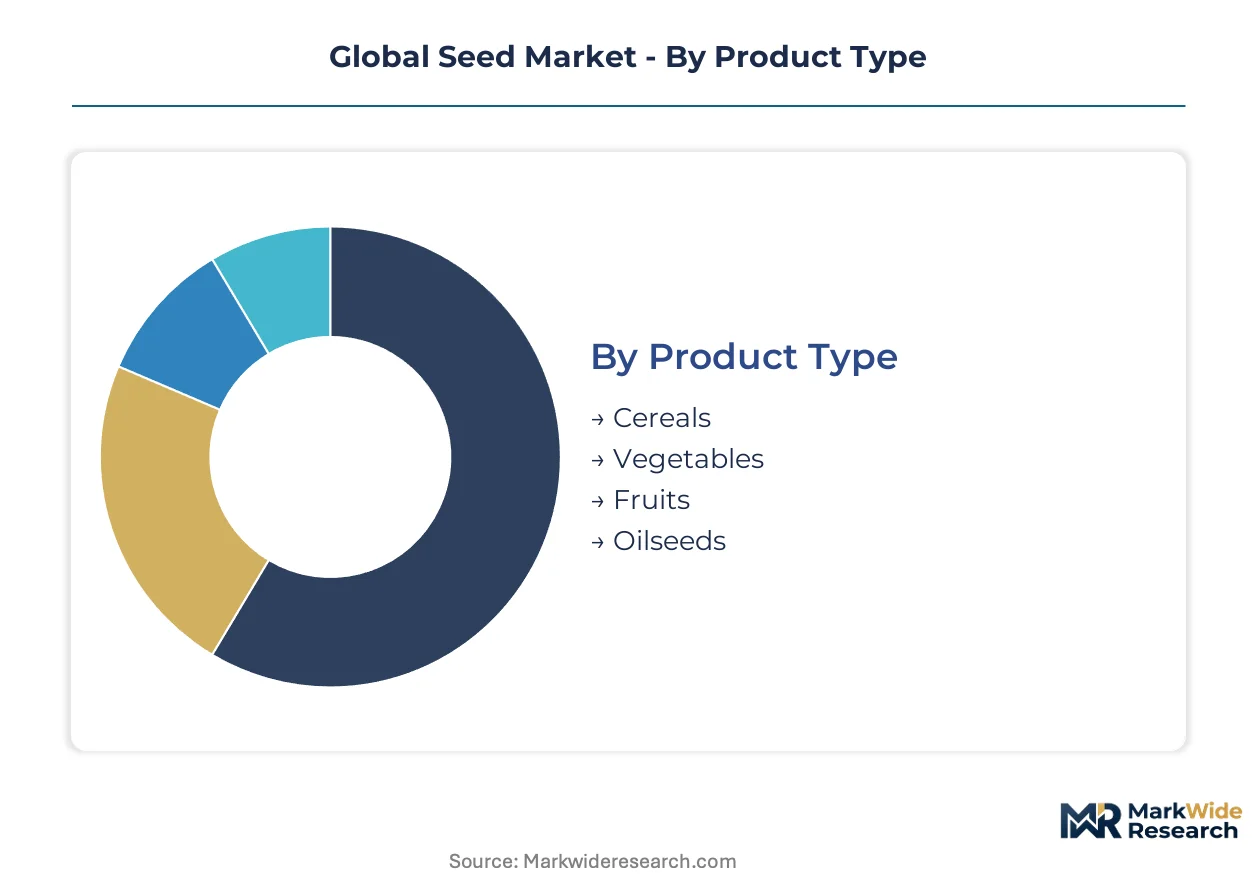
Seed market segmentation reflects divergent breeding investments, regulatory acceptance thresholds, and farmer willingness to pay for yield stability. Each axis—product type, end use, trait platform, and packaging—carries distinct margin structures and distribution requirements.
Product Type:
Genetic complexity and breeding cycle length determine commercial priority across crop categories.
- Cereals:Wheat, rice, and maize germplasm commands the largest procurement volumes globally. Demand concentrates in India and China where national food security programs subsidize certified seed distribution to smallholders.
- Oilseeds:Soybean and canola varieties integrate herbicide-tolerance and high-oleic traits that capture premium pricing in Brazilian and US commercial agriculture. Patent licensing fees stack onto base seed costs.
- Vegetables:Hybrid tomato, pepper, and brassica lines generate concentrated margin pools through proprietary inbred parent protection.
- Fruits:Rootstock and scion combinations for perennial orchards require longer development timelines and nursery propagation partnerships.
Mature deployment sits with cereals. Newer deployment is concentrated in oilseeds with stacked-trait architectures.
End Use:
Scale requirements and technical support intensity separate commercial buyers from retail channels.
- Agriculture:Row-crop operations in Mato Grosso and Iowa purchase biotech-enhanced varieties through cooperative procurement pools with performance guarantees. Volume contracts dominate this channel.
- Horticulture:Greenhouse operators in the Netherlands and Spain demand disease-resistant vegetable germplasm with documented carbon-footprint reductions for EU Green Deal compliance.
- Research:Public breeding programs and gene banks require phytosanitary-certified material with full provenance documentation for germplasm exchange protocols.
- Home Gardening:Retail seed packets through garden centers carry lower price points and minimal technical support.
Revenue concentration favors agriculture. Fastest expansion is occurring in horticulture with sustainability-linked procurement.
Trait:
Regulatory jurisdiction determines which trait platforms reach farmers.
- Genetically Modified:Glyphosate-tolerant and insect-resistant maize and soybean dominate US and Brazilian acreage. USDA and ANVISA approval pathways enable rapid commercialization.
- Hybrid:Controlled pollination systems protect parent line identity in corn and vegetable breeding. Farmer willingness to pay for yield stability runs highest here.
- Conventional:Open-pollinated varieties persist in markets with biotech moratoriums and organic certification requirements.
- Organic:Certified organic seed must meet multi-year land conversion standards and prohibited substance lists under USDA Organic and EU Organic regulations.
Hybrid technology anchors mature revenue streams. Gene-edited varieties are gaining share fastest where EFSA and USDA classifications permit reduced regulatory burdens.
Packaging Type:
Unit economics and treatment shelf life dictate format selection.
- Bulk Containers:Tote bags and super sacks serve large-scale corn and soybean planting operations with treated seed delivered direct to farm storage.
- Bags:Multi-layer paper and polymer sacks protect germination rates through humidity barriers for rice and wheat distribution.
- Seed Packs:Retail-sized foil pouches with printed variety information target home gardeners and small-scale horticulture.
- Others:Pelleting and encrusting formats for precision planting equipment represent emerging format innovation.
Volume leadership rests with bulk containers. Format innovation is concentrating in precision-compatible pelleting for mechanized vegetable planting.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mato Grosso anchors the most concentrated seed procurement corridor globally, where Brazilian soybean growers operate cooperatives that negotiate volume contracts for biotech-enhanced varieties direct from multinational breeders.
United States
The US Corn Belt drives global demand for stacked-trait corn and soybean germplasm. USDA approval pathways enable rapid commercialization of glyphosate-tolerant and insect-resistant varieties. Iowa and Illinois cluster the densest breeding trial infrastructure, with automated phenotyping platforms deployed across thousands of hybrid evaluation plots.
Brazil
Commercial agriculture expansion in Goiás and Mato Grosso concentrates procurement of Intacta RR2 Pro soybean varieties. ANVISA regulatory alignment with USDA frameworks accelerates trait approval timelines. The Cerrado biome anchors South America's largest hybrid corn seed consumption corridor.
China
National food security programs subsidize certified wheat and rice seed distribution to smallholders across Henan and Shandong provinces. The Ministry of Agriculture shapes germplasm import protocols and biotech trait approval pathways. Yangtze River Delta research institutes concentrate public breeding investment for climate-resilient rice varieties.
India
Hybrid rice and millet varieties remain underdeployed across Bihar and Uttar Pradesh smallholder systems. The central government's PLI scheme for agriculture inputs channels investment toward domestic seed multiplication infrastructure. Punjab and Haryana cluster the most intensive wheat seed replacement programs.
Germany
EFSA regulatory frameworks and the EU Green Deal mandate carbon-footprint disclosures for crop inputs entering Dutch and Spanish horticulture supply chains. KWS SAAT anchors European sugar beet and cereal breeding from its Einbeck headquarters. Bavarian research clusters concentrate precision phenotyping infrastructure for drought-tolerance trait development.
Global Seed Market Competitive Environment
The competitive structure tilts toward integrated life-science conglomerates with captive trait pipelines and germplasm libraries. Three to five multinational groups control the majority of biotech-enabled row-crop genetics through patent-protected trait licensing networks. Strategic archetypes separate into trait-integrated conglomerates, regional hybrid specialists, and vegetable germplasm pure-plays. Consolidation through seed-biotech mergers and exclusive distribution partnerships represents the dominant competitive moves reshaping market access.
Among trait-integrated conglomerates, Bayer and Corteva Agriscience exemplify the archetype of crop-science divisions leveraging glyphosate-tolerance and insect-resistance patent estates to anchor row-crop positions. Syngenta Group occupies a position bridging seed with crop protection chemistry bundling. BASF represents the specialty-input vector with concentrated vegetable and cotton germplasm positions.
| Leading Market Players |
|---|
| Bayer |
| Corteva Agriscience |
| Syngenta Group |
| BASF |
| Groupe Limagrain |
| KWS SAAT |
| Sakata Seed Corporation |
| Land O'Lakes |
| Takii |
| Others |
Value Chain & Pricing Dynamics
Cooperative procurement pools across Mato Grosso and Goiás are consolidating purchase volumes for biotech-enhanced soybean and corn varieties, forcing breeders to restructure contract terms and compress margin structures for large-account retention.
Pricing Analysis
Yield-per-hectare guarantees anchor value-based pricing for Intacta RR2 Pro soybean and stacked-trait corn hybrids in Brazilian and US commercial agriculture. Three-tier pricing structure across premium, standard, and economy levels separates performance-guaranteed germplasm from basic certified seed and open-pollinated varieties. Cost compression in standard-tier hybrids is intensifying because farmer margins face pressure from fertilizer and energy price volatility. Smallholder segments across Bihar and Uttar Pradesh exhibit highest price sensitivity, while Iowa and Mato Grosso row-crop operations accept premium positioning for documented yield stability.
Supply Chain Analysis
Domestic-content mandates under India's PLI scheme for agriculture inputs are reshaping sourcing patterns for hybrid rice and millet multiplication infrastructure. Parent line production concentrates in the United States, Brazil, and Germany, with germplasm development anchored in Iowa, Mato Grosso, and Bavarian research clusters. Trait licensing fees, phytosanitary certification protocols, and neonicotinoid alternative chemistries constitute critical input dependencies. Single-source vulnerability around glyphosate-tolerance patent estates creates concentration risk. Distribution runs through cooperative procurement pools and regional dealer networks, with direct-to-farm bulk delivery displacing traditional wholesale channels for large-scale operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around trait-integrated conglomerates with captive germplasm libraries, as regulatory fragmentation and R&D overhead inflation force subscale breeders toward exit or acquisition.
For Market Incumbents: To counter patent cliff exposure around first-generation glyphosate tolerance, Bayer and Corteva Agriscience must deepen backward integration into gene-editing platforms and accelerate CRISPR-Cas9 trait pipeline development. Securing exclusive distribution partnerships with Mato Grosso cooperative procurement pools locks in volume commitments against emerging regional hybrid specialists. For New Entrants and Emerging Players: Capture underdeployed hybrid rice and millet penetration across Bihar and Uttar Pradesh smallholder systems, where PLI scheme infrastructure investment lags varietal demand. A seed-plus-extension service bundling model—pairing germplasm with digital agronomy prescriptions—overcomes brand loyalty barriers against established incumbents. For Investors and Strategic Acquirers: The window for entry favors vegetable germplasm pure-plays with proprietary inbred parent protection and CSRD-compliant carbon-footprint documentation. Monitor EFSA gene-editing classification rulings as the inflection signal: favorable reclassification would unlock acquisition premiums for CRISPR-enabled breeding programs currently carrying regulatory discount valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Trait Pipeline Diversification | CRISPR-Cas9 investment reduces regulatory submission risk across USDA, EFSA, and China's Ministry of Agriculture pathways. |
| Cooperative Procurement Partnership | Exclusive volume contracts with Mato Grosso pools secure acreage commitments against price erosion. |
| Carbon Credit Bundling | Seed-plus-sequestration contracts align with EU Green Deal compliance and create recurring revenue streams. |
| Digital Phenotyping Scale-Up | Drone-mounted multispectral platforms compress breeding cycles for drought-tolerance trait development. |
| Domestic Multiplication Infrastructure | PLI scheme-aligned facilities in India reduce import dependency and capture smallholder volume expansion. |
Study Parameters
Independent corroboration across seed company R&D executives, cooperative procurement managers, and regulatory affairs specialists underwrites the qualitative findings. Primary interviews with breeding program directors, phytosanitary certification officers, and digital agronomy platform engineers combined with secondary validation from USDA approval databases, EFSA guidance documents, ANVISA regulatory filings, and customs germplasm trade records. Bottom-up variety-level volume estimates and top-down national acreage statistics triangulate market sizing.
Rate-of-change decomposition separates volume growth from price mix effects across the projection horizon. Segmentation dimensions modeled include product type, end-use channel, trait platform, and packaging format, with additional granularity on biotech regulatory cluster and farmer scale archetype. CAGRs derive from acreage penetration curves, trait adoption rates, and replacement cycle dynamics. Forecast inputs incorporate EU Green Deal compliance cost trajectories and Brazilian commercial agriculture expansion patterns.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to gene-editing regulatory reclassification and phytosanitary protocol harmonization. Forecasts reflect documented assumptions on trait approval timelines and farmer willingness-to-pay elasticity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Europe Vegetable Seed Market
Seeds
Nepal Seeds Market
Seeds
Organic Chia Seeds Market
Seeds
Seed Health Market
Seeds
China Forage Seed Market
Seeds
South Africa Seed Market
Seeds
Europe Seed Market
Seeds
Global Packaged Chia Seeds Market
Seeds
Europe Chia Seeds Market
Seeds
Africa Peas Market
Seeds
Australia Forage Seed Market
Seeds
Mexico Vegetable Seed Market
Seeds
South America Seed Market
Seeds
Myanmar Rice Seed Market
Seeds
Custom Selected Seed Market
Seeds
Spain Forage Seed Market