
 Global Soybean Seed Market | 2026-2036
Global Soybean Seed Market Size, Share, and Industry Trends Forecast 2026-2036
Global Soybean Seed Market Foresight
Asset-light licensing and royalty-based trait partnerships is tilting competitive dynamics toward firms with deep germplasm libraries rather than capital-intensive field operations. Bayer AG leverages its broad patent estate in herbicide-tolerant traits to sustain recurring revenue streams across multiple seed brands. Corteva Agriscience anchors North American breeding programs with integrated biotechnology pipelines. Syngenta Group competes through stacked-trait portfolios that span both temperate and tropical soybean geographies.
Soybean seed constitutes the reproductive propagule of Glycine max, typically bred for protein content exceeding 40%, oil concentration near 20%, and resistance to cyst nematode or sudden death syndrome pathogens. Its primary commercial purpose centers on establishing high-yielding stands for subsequent grain harvest, crush processing, or direct livestock feed integration. Genetically modified seed types command the dominant value share due to stacked-trait premiums and farmer willingness to pay for weed and insect management simplification. Oil extraction applications represent the fastest-expanding end-use segment as renewable diesel facilities multiply. Pelletized and coated seed forms capture disproportionate margin pools through precision planting compatibility and biological additive encapsulation.
The USDA Animal and Plant Health Inspection Service governs interstate movement and environmental release of biotech soybean events, while Brazil's CTNBio evaluates stacked-trait biosafety for tropical cultivation zones. China's Ministry of Agriculture and Rural Affairs maintains import approval lists that determine which biotech events enter the world's largest soybean purchase flow. Stakeholders must monitor asynchronous trait approvals across importing and exporting jurisdictions, as regulatory misalignment disrupts seed trade corridors and crush facility sourcing protocols.
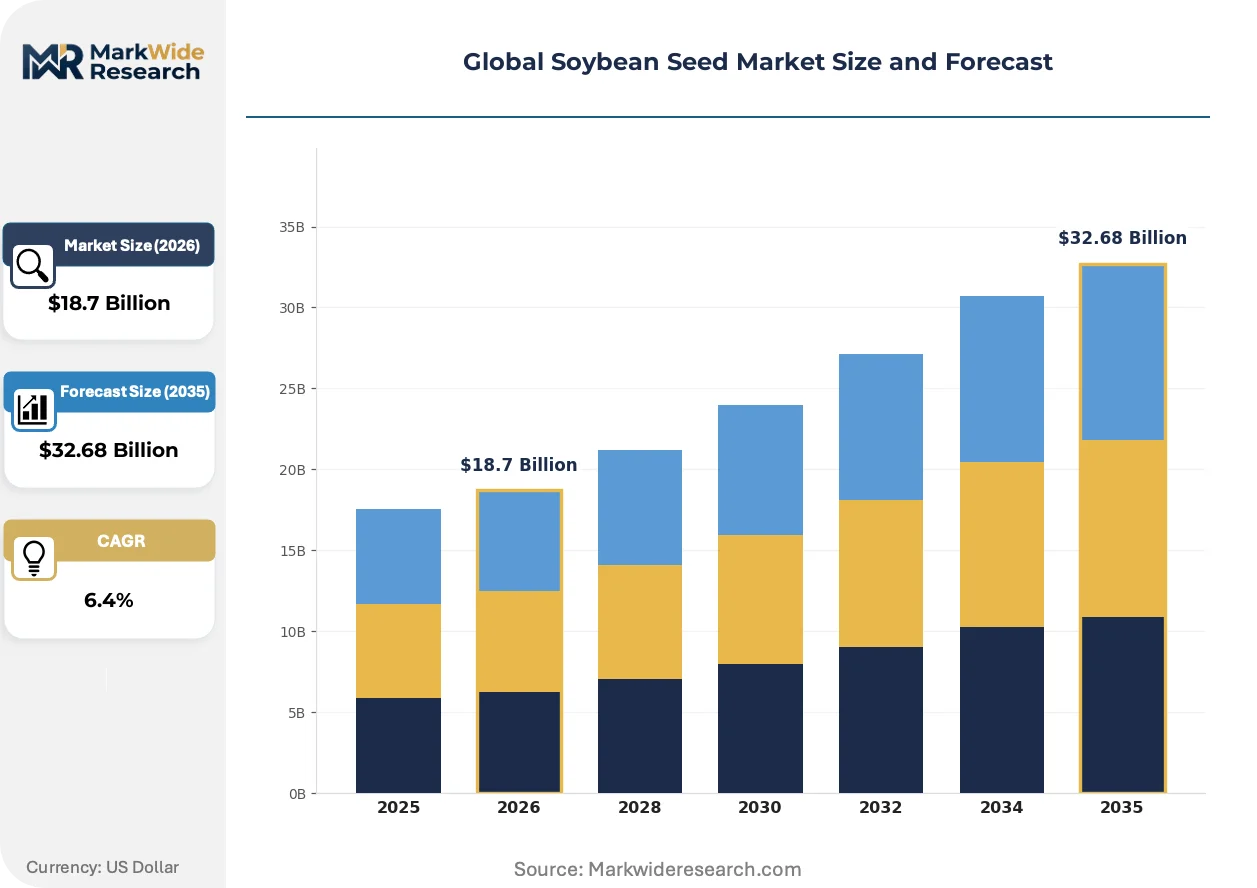
Market Dynamics
Stacked-trait seed licensing is concentrating value capture among germplasm-rich firms while fragmenting downstream distribution, as royalty stacking and asynchronous trait approvals across Brazil, China, and the US force breeders into complex cross-licensing webs that reshape competitive boundaries.
Growth Catalysts
- Renewable diesel expansion:Biofuel producers in the US Midwest and Brazilian Southeast are contracting dedicated high-oil soybean acreage, creating pull-through demand for specialized seed varieties with elevated lipid profiles.
- CTNBio regulatory streamlining:Brazil's national biosafety regulator has accelerated stacked-gene approval timelines, reducing commercialization lag for tropical-adapted trait combinations targeting the Cerrado expansion zones.
- Precision planting adoption:Pelletized and coated seed formats compatible with variable-rate planting equipment are commanding farmer willingness to pay for biological additive encapsulation and emergence uniformity.
Market Restraints
- Phosphorus input cost volatility:Fertilizer price swings tied to natural gas benchmarks and export restrictions from major phosphate rock suppliers compress seed margin structures and working capital cycles.
- Trait approval asynchrony:China's Ministry of Agriculture and Rural Affairs maintains import approval lists that lag event deregulation in origin countries, creating trade corridor disruptions and crush facility sourcing protocol complications.
- Gene editing regulatory ambiguity:Divergent classification of CRISPR-derived varieties as genetically modified or conventional across key jurisdictions fragments breeding investment and commercialization pathways.
Strategic Opportunities
- Sub-Saharan Africa cultivation:Underdeveloped soybean seed markets in Zambia, Nigeria, and Ethiopia present first-mover advantages for heat-tolerant germplasm adapted to low-input systems and emerging poultry feed demand.
- Carbon intensity scoring:EU Renewable Energy Directive sustainability criteria and emerging US clean fuel standards create premium market segments for verified low-carbon-intensity soybean production with traceable seed provenance.
- Biological seed treatment convergence:Integration of microbials and biostimulants into coating formulations addresses farmer demand for synthetic chemical reduction while opening recurring revenue streams beyond genetic trait royalties.
Industry Challenges
- Quantitative genetics talent scarcity:Breeding programs face acute shortages of computational biologists capable of integrating genomic selection models with multi-environment yield trial data.
- Regulatory data protection expiration:Erosion of exclusive reference variety protections in key markets accelerates generic seed competition and compresses innovation return timelines for trait developers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Soybean Seed Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Seed Type: Conventional, Genetically Modified, Organic, Hybrid End Use/Application: Livestock Feed, Oil Extraction, Food Products, Biofuel Production, Industrial Use Form: Pelletized, Coated, Bulk, Treated Customer Type: Seed Companies, Agricultural Cooperatives, Independent Farmers, Agro-dealers, Research Institutions |
| Companies Covered | KWS SAAT SE & Co. KGaA, BASF SE, Bayer AG, Stine Seed Company, Limagrain, Corteva Agriscience, Advanta Seeds - UPL, AgReliant Genetics, Syngenta Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Soybean Seed Market Shifts & Advancements
Digital breeding infrastructure and sustainability-linked procurement are compressing variety development cycles while fragmenting traditional seed distribution hierarchies, forcing incumbents to rebuild competitive moats around data assets rather than field scale alone.
Genomic selection platforms combining high-density marker arrays with environmental covariates are virtualizing early-generation yield prediction, allowing breeders to discard inferior lines before field testing. Major temperate-zone breeding programs have adopted these tools for over half of selection decisions. The technology is virtualizing capital allocation toward molecular validation labs and away from multi-location yield trial networks.
EU Green Deal Farm-to-Fork targets for pesticide reduction are tightening trait performance thresholds for herbicide-tolerant varieties marketed in European import markets. Crush facilities and food manufacturers are demanding expanded event disclosure and sustainability certification. Latin American exporters are responding by segregating supply chains and accelerating low-residue variety development.
Farmer purchasing through direct-to-farm digital platforms and cooperative aggregation networks is displacing traditional retail dealer relationships for volume soybean seed transactions. Large-scale operations in Brazil's Mato Grosso and the US Corn Belt are negotiating multi-year trait licensing agreements independent of brand loyalty. This channel compression is most visible in regions where planting windows are narrow and logistics coordination outweighs in-store agronomic advice.
Global Soybean Seed Market Segmentation
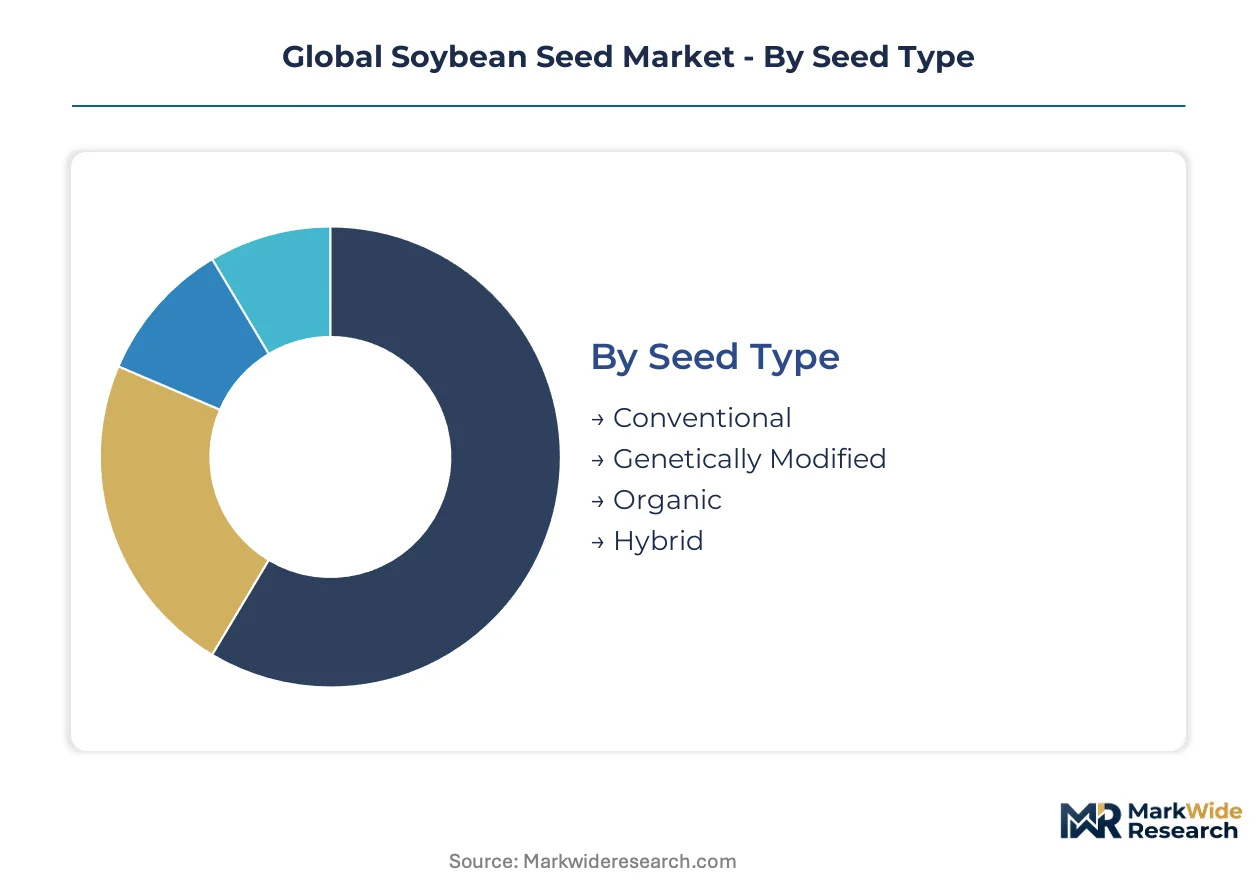
Segmentation in the soybean seed market determines breeding investment cycles, regulatory pathways, and margin capture. Trait developers structure R&D pipelines around seed type and end-use specifications, while distribution networks calibrate service intensity to customer scale and purchasing sophistication.
Seed Type:
Cycle times vary dramatically across this dimension, with gene-edited varieties compressing development windows while stacked-trait GMO seeds endure prolonged regulatory review phases.
- Genetically Modified:Stacked-trait varieties incorporating herbicide tolerance and insect resistance dominate commercial plantings in Brazil, the US, and Argentina. Farmers in Mato Grosso and Iowa pay premiums for simplified weed management protocols and reduced spray passes. Regulatory asynchrony between CTNBio, USDA-APHIS, and China's MOARA extends commercialization timelines.
- Conventional:Non-transgenic germplasm retains substantial acreage in European import-dependent markets and organic transition zones. Seed companies in France and Germany maintain conventional breeding programs to supply food-grade crush facilities with non-GMO verification.
- Organic:Certified varieties must trace parent stock through multi-year isolation protocols. Demand concentrates in German and Dutch food manufacturing supply chains where EU organic labeling commands shelf price premiums.
- Hybrid:Cytoplasmic male-sterile systems enable controlled pollination for specific trait stacking. Limited commercial penetration outside experimental programs in China and India due to higher seed production costs.
Genetically Modified anchors the volume base while Organic gains share at the steepest rate.
End Use/Application:
Application-driven segmentation reshapes lipid and protein specifications, with crush facilities now dictating fatty acid profiles through backward contracting.
- Oil Extraction:High-oleic varieties with elevated lipid concentrations serve renewable diesel facilities in Louisiana, California, and Rotterdam. US Midwest crushers are contracting dedicated acreage with oil content premiums above standard commodity beans.
- Biofuel Production:Low-carbon-intensity scoring under EU RED and emerging US clean fuel standards creates segregated supply chains. Brazilian crushers in São Paulo state are developing traceability systems for certified sustainable production.
- Livestock Feed:High-protein meal specifications dominate poultry and swine ration formulation in Vietnam, Indonesia, and Mexico. Argentine export crushers optimize protein content for Southeast Asian feed mill procurement.
- Food Products:Identity-preserved varieties with specific isoflavone profiles supply Japanese tofu manufacturers and US soy milk processors. Non-GMO and organic certifications required for European retail placement.
- Industrial Use:Bioplastics and lubricant feedstock applications remain niche, concentrated in German chemical processing clusters and US biobased material startups.
Livestock Feed generates the largest absolute volume while Biofuel Production climbs the fastest.
Form:
Physical seed treatment investments concentrate where precision planting adoption has reached critical mass among large-scale operations.
- Pelletized:Uniform sizing enables pneumatic meter accuracy at high planting speeds. Brazilian Cerrado farms above 5,000 hectares specify pelletized delivery for 24-hour planting window completion.
- Coated:Biological additive encapsulation integrates rhizobia inoculants, micronutrients, and fungicides into single-pass application. US Corn Belt cooperatives are converting acreage to coated formats for labor reduction.
- Treated:Synthetic chemical fungicide and insecticide coatings address specific soil-borne pathogen pressure in high-residue no-till systems. Common in Argentine Humid Pampas where SDS and SCN pressure coexist.
- Bulk:Untreated raw seed persists in low-input systems and farmer-saved seed networks across Sub-Saharan Africa and smallholder Latin American operations.
Bulk retains the widest geographic footprint while Coated expands most quickly in mechanized farming zones.
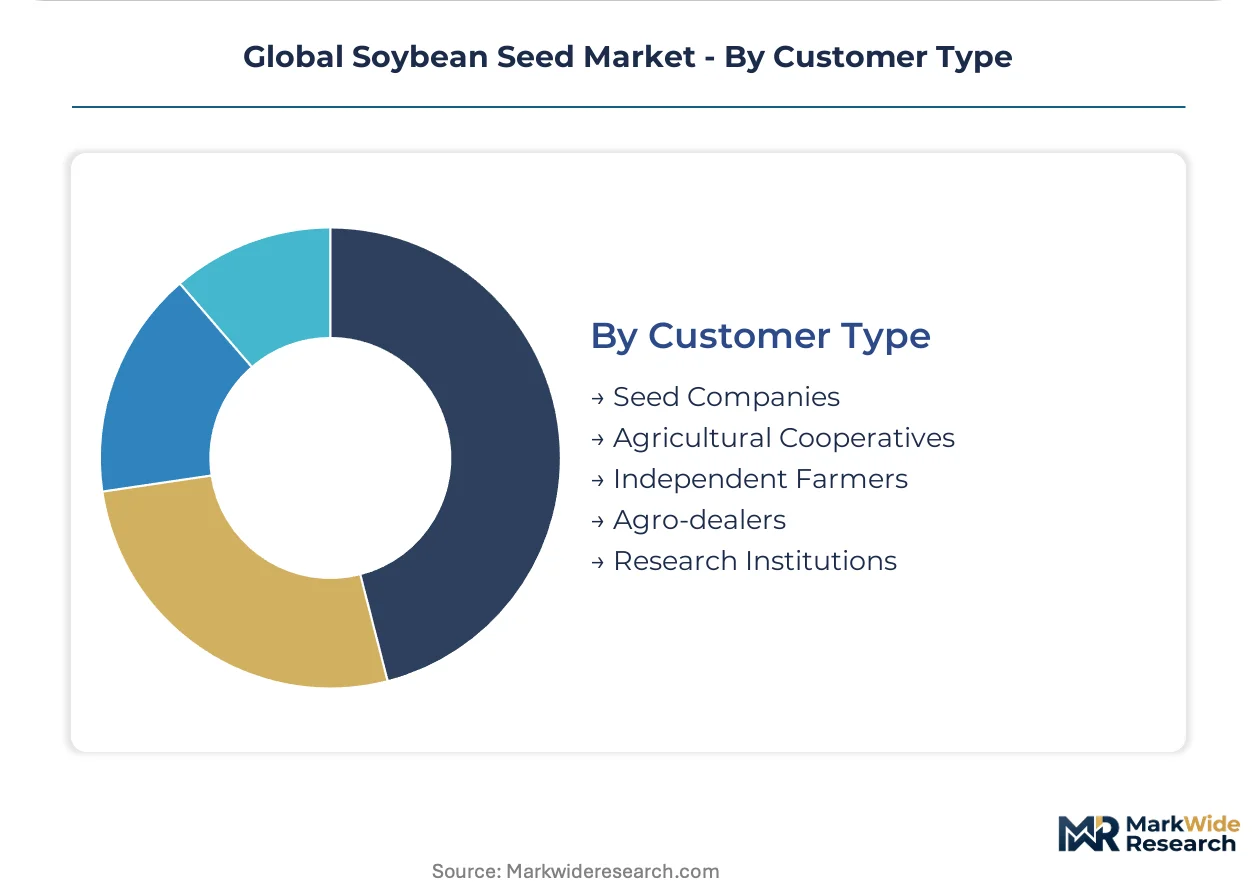
Customer Type:
Purchasing sophistication and volume scale determine service bundling, with the largest operators negotiating direct trait licenses outside traditional retail channels.
- Agricultural Cooperatives:Aggregated procurement in Brazil's Mato Grosso and the US Corn Belt enables multi-year trait licensing at scale. Cooperatives are displacing independent dealers for volume transactions.
- Independent Farmers:Sub-500 hectare operations rely on agronomic advice bundled with seed purchases through local dealer networks. Price sensitivity highest in this segment during fertilizer cost spikes.
- Seed Companies:Germplasm licensors and trait developers source parental lines and biotechnology events for proprietary variety development. Bayer and Corteva maintain captive breeding pipelines.
- Agro-dealers:Retail distribution intermediaries face margin compression as direct-to-farm digital platforms and cooperative aggregation capture volume flows.
- Research Institutions:Public breeding programs in India, China, and Brazil access germplasm collections for pre-commercial variety development and farmer participatory selection trials.
Agricultural Cooperatives command the steepest volume growth trajectory while Independent Farmers remain the numerically dominant purchaser category.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's CTNBio regulatory streamlining and the US Inflation Reduction Act biofuel incentives are redrawing geographic investment priorities for trait developers and seed distributors.
United States
Renewable diesel facility construction in Louisiana and Iowa pulls high-oleic soybean contracts from seed companies. USDA-APHIS governs interstate biotech event movement. The Corn Belt corridor from Des Moines to Champaign anchors precision planting adoption for coated seed formats.
Brazil
Cerrado expansion zones in Mato Grosso and Goiás drive demand for tropical-adapted stacked-trait varieties. CTNBio accelerated approval timelines reduce commercialization lag for gene combinations. São Paulo state crushers develop traceability systems for EU-bound low-carbon-intensity exports.
China
MOARA import approval lists determine which biotech events enter crush facilities processing Brazilian and US origin beans. Domestic breeding programs in Heilongjiang province pursue germplasm adaptation for northern latitudes. Yangtze River Delta feed mills specify protein content thresholds for poultry ration formulation.
Argentina
Humid Pampas no-till systems sustain demand for sudden death syndrome and cyst nematode resistant varieties. The national seed institute (INASE) certifies genetic purity standards for export-oriented production. Rosario corridor crush facilities optimize protein profiles for Southeast Asian feed procurement.
India
Maharashtra and Madhya Pradesh soybean belts attract heat-tolerant germplasm trials for poultry feed integration. FSSAI food safety standards govern oil extraction facility licensing. Indore trading hubs intermediate between farmer-saved seed networks and formal certified distribution.
Global Soybean Seed Market Competitive Landscape
On the supply side, the industry is consolidating around germplasm-rich firms with deep patent estates in herbicide-tolerant and insect-resistant traits. Three archetypes dominate: integrated life-science conglomerates with captive biotechnology pipelines, regional seed specialists with strong farmer relationships, and trait licensors operating asset-light royalty models. Competitive moves center on cross-licensing webs for stacked-trait combinations and direct-to-farm digital platform investments that displace traditional dealer networks.
Within the integrated conglomerate tier, Bayer AG and Corteva Agriscience occupy positions defined by broad patent portfolios and multi-brand distribution reach. BASF SE exemplifies the chemical-seed convergence archetype through its agricultural solutions division. KWS SAAT SE & Co. KGaA represents the European family-owned specialist model with century-long breeding program continuity. These three anchors illustrate how scale, research intensity, and geographic focus stratify competitive positioning without requiring uniform strategic postures.
| Leading Market Players |
|---|
| KWS SAAT SE & Co. KGaA |
| BASF SE |
| Bayer AG |
| Stine Seed Company |
| Limagrain |
| Corteva Agriscience |
| Advanta Seeds - UPL |
| AgReliant Genetics |
| Syngenta Group |
| Others |
Supply & Pricing Matrix
Mato Grosso's seed conditioning and trait licensing infrastructure anchors global germplasm flows, with concentrated processing capacity in Sorriso and Lucas do Rio Verde translating directly into royalty negotiation leverage for stacked-trait developers serving Brazilian Cerrado expansion zones.
Pricing Analysis
Certification level (CTNBio-approved stacked-trait versus conventional non-GMO) creates the primary spread in soybean seed pricing, with three-tier pricing structure across premium, standard, and economy levels reflecting trait complexity and royalty stacking depth. Pricing pressure stems from phosphorus input cost volatility compressing working capital cycles for distributors. Large agricultural cooperatives in Brazil and the US Corn Belt exhibit lowest price sensitivity due to multi-year trait licensing agreements, while independent farmers below 500 hectares face acute margin pressure during fertilizer cost spikes.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from germplasm licensors to regional distributors have become critical liquidity bridges during input cost volatility. Parent stock production concentrates in the United States, Brazil, and Argentina, with breeding nurseries drawing from phosphorus fertilizers, proprietary trait events, and cytoplasmic male-sterile lines. Single-source vulnerability around Chinese MOARA import approval lists disrupts trade corridors. Distribution runs through agricultural cooperatives and direct-to-farm digital platforms that displace traditional agro-dealer networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Soybean seed market fragmentation accelerates as renewable diesel procurement creates specialized high-oleic segments, biofuel sustainability scoring fragments supply chains, and precision planting adoption splinters seed form preferences—each trend carving defensible niches for differentiated positioning.
For Market Incumbents: Harden germplasm library depth through exclusive trait licensing and cross-licensing webs that block competitor stacked-trait combinations. Expand captive breeding pipeline capacity in Mato Grosso and Iowa to defend against asset-light trait licensors. Prioritize biological seed treatment integration to capture recurring revenue beyond genetic trait royalties. For New Entrants and Emerging Players: Sub-Saharan Africa cultivation zones in Zambia and Nigeria offer first-mover terrain for heat-tolerant germplasm adapted to low-input poultry feed systems. Carbon intensity scoring under EU RED creates premium segment entry for verified low-carbon production with traceable seed provenance. Partner with regional cooperatives for biological additive encapsulation rather than competing on trait stacks. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors germplasm-rich specialists with deep computational biology capabilities over capital-intensive field operators. Long-term viability hinges on genomic selection platform maturity and regulatory data protection durability. Watch CTNBio approval velocity and Chinese MOARA list synchronization as inflection indicators for stacked-trait commercialization timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Trait Stacking Licensing Agreement | Cross-licensing webs with CTNBio-approved events accelerate tropical variety commercialization in Brazilian Cerrado zones. |
| Biological Seed Treatment Integration | Microbial encapsulation into coatings captures recurring revenue streams beyond genetic trait royalties for precision planting compatibility. |
| Direct-to-Farm Digital Platform | Cooperative aggregation networks displace traditional agro-dealer margins in Mato Grosso and US Corn Belt volume transactions. |
| Carbon Intensity Verification Program | EU RED compliance and emerging US clean fuel standards create premium market segments for traceable seed provenance. |
| Genomic Selection Infrastructure | High-density marker arrays with environmental covariates virtualize yield prediction and compress variety development cycles. |
Research Methodology
Desk research of regulatory filings from USDA-APHIS, CTNBio, and China's MOARA preceded structured interviews with soybean breeding program directors, trait licensing executives, cooperative procurement managers, and crush facility sourcing leads. Secondary validation drew from customs trade data, seed certification records, and biofuel facility construction disclosures. Bottom-up acreage and variety adoption estimates triangulated against top-down market value reconstructions.
Assumptions held CTNBio regulatory streamlining and US Inflation Reduction Act biofuel incentives as baseline conditions, while varying phosphorus input cost trajectories and Chinese import approval synchronization across scenarios. Segmentation modeling spanned seed type, end-use application, physical form, and customer purchasing archetype. CAGRs derived from logistic diffusion curves for precision planting adoption and renewable diesel capacity buildouts, with trait royalty rates and seed treatment premiums as industry-specific forecast inputs.
Practitioners should monitor asynchronous trait approval patterns and gene editing regulatory classification shifts for early signals of commercialization timeline compression or extension. Forecasts reflect assumptions around CTNBio velocity, MOARA list alignment, and biofuel policy continuity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Africa Chia Seeds Market
Seeds
Myanmar Rice Seed Market
Seeds
Flax Crop Market
Seeds
Garlic Chive Seeds Market
Seeds
Grass Seed Market
Seeds
Europe Quinoa Seed Market
Seeds
Myanmar Seed Market
Seeds
Sesame Seeds Market
Seeds
Southeast Asia Vegetable Seed Market
Seeds
India Rice Seed Market
Seeds
Mexico Seed Market
Seeds
Asia-Pacific Seed Market
Seeds
North America Tomato Seed Market
Seeds
Asia-Pacific Cannabis Seeds Market
Seeds
China Vegetable Seed Market
Seeds
United States Seed Market