
 Recycled Materials Packaging Solutions Market | 2026-2036
Recycled Materials Packaging Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Recycled Materials Packaging Solutions Market Analytics
European paperboard mills are shifting capacity toward kraft liner grades with certified recycled fiber content. Mondi plc leverages integrated pulp-to-paper operations across Central Europe to sustain cost-advantaged supply of recycled corrugated solutions. DS Smith plc anchors its competitive position through closed-loop recycling partnerships with major retail chains in the United Kingdom and France. Amcor plc differentiates via multi-material flexible packaging platforms that incorporate mechanically recycled polyethylene terephthalate streams.
Recycled materials packaging solutions encompass containers, films, wraps, and protective structures manufactured from reprocessed post-consumer or post-industrial feedstocks, typically requiring contamination thresholds below 5 percent and melt-flow indices calibrated to virgin resin equivalents for blow-molding or thermoforming compatibility. These systems serve primarily to reduce virgin resource extraction while maintaining barrier performance for shelf-stable and perishable goods. Flexible packaging commands the widest addressable footprint due to its lightweighting advantages, though rigid containers capture disproportionate margin pools in premium personal care and electronics segments where dimensional stability and aesthetic finish carry premium pricing. Recycled paper grades dominate volume in the food and beverage channel, driven by direct substitution of expanded polystyrene and folding carton structures in quick-service and ready-meal applications.
The European Commission's Packaging and Packaging Waste Regulation, alongside California's extended producer responsibility framework under CalRecycle, and India's BIS recycled content labeling standards, collectively reshape product design specifications and market access conditions for imported and domestic packaging alike. Compliance with these overlapping regimes necessitates traceability systems and third-party chain-of-custody certification that add fixed cost but create defensible supplier-customer relationships. Stakeholders must monitor divergence between regional recycled content percentage mandates and the actual recovery infrastructure capacity available to supply compliant feedstocks at commercial scale.
Market Dynamics
The EU Green Deal's packaging waste directives are tightening recycled content mandates across member states, forcing converters to reengineer supply chains around certified post-consumer feedstock streams with traceable chain-of-custody documentation.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Binding recycled content thresholds for plastic packaging accelerate converter investment in decontamination and extrusion capacity across Germany, France, and Italy.
- Food and beverage procurement mandates:Major retail chains now specify minimum post-consumer recycled content in corrugated and flexible formats, pulling supply from certified mills.
- Rhine-Ruhr industrial clustering:Concentrated R&D infrastructure for chemical recycling and mechanical reprocessing creates localized feedstock security for packaging converters.
Market Restraints
- Post-consumer resin price volatility:Baled PET and HDPE feedstock costs fluctuate with crude oil benchmarks and collection seasonality, compressing converter margins.
- German mechanical recycling concentration:Overreliance on Rhine-Ruhr reprocessors creates geographic supply risk if energy costs spike or capacity constraints emerge.
- Contamination threshold limitations:Current optical sorting and washing technologies struggle to consistently deliver sub-5% contamination rates required for food-contact flexible films.
Strategic Opportunities
- Spain and Eastern European expansion:Underdeveloped collection infrastructure and lower converter density create first-mover advantages for integrated recyclers entering these markets.
- Pharmaceutical secondary packaging:Emerging demand for recycled-content folding cartons in OTC and generic drug segments where barrier requirements are less stringent than primary blister packs.
- Chemical recycling scale-up:Pyrolysis and depolymerization technologies enable food-grade quality from mixed plastic waste streams currently rejected by mechanical processors.
Industry Challenges
- Food-contact certification timelines:EFSA novel food and recycling process approvals require 18-24 month evaluation windows, delaying commercialization of new recycled feedstock streams.
- Legacy extrusion equipment retrofit costs:Existing blown film and thermoforming lines require screw, die, and cooling modifications to handle variable melt-flow indices of recycled resins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Recycled Materials Packaging Solutions Market |
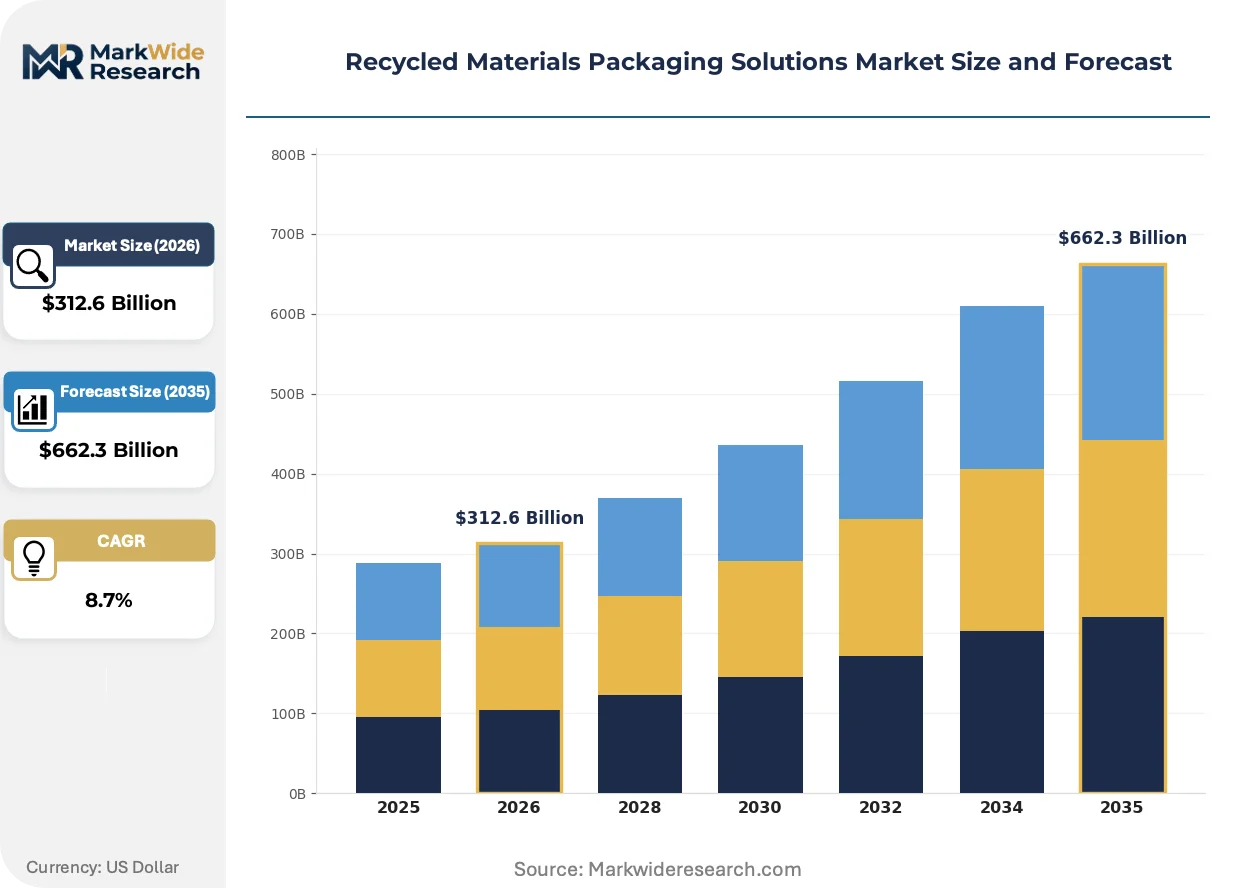
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $662.3 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Packaging, Rigid Containers, Labels, Pouches Material: Recycled PET, Recycled HDPE, Recycled Paper, Biodegradable Plastics End Use Industry: Food & Beverage, Personal Care, Household Products, Electronics Packaging Type: Pallets, Boxes, Bags, Film |
| Companies Covered | Mondi plc, Tetra Pak International S.A., Amcor plc, DS Smith plc, Berry Global, Inc., Smurfit WestRock plc, Sealed Air Corporation, Ball Corporation, International Paper Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Recycled Materials Packaging Solutions Market Evolving Landscape
Digital watermarking and blockchain traceability systems are reshaping how converters demonstrate compliance with extended producer responsibility frameworks and brand-owner sustainability commitments.
Advanced decontamination technologies for super-clean PET flake are converging with near-infrared sorting systems to enable closed-loop food-contact applications previously restricted to virgin resin. European beverage bottlers in Germany and France are adopting these systems at commercial scale. This convergence is compressing the quality gap between mechanical recycling outputs and virgin polymer specifications.
The EU Green Deal's packaging waste directives are mandating minimum recycled content percentages with phased implementation timelines. Industrial consequence includes accelerated capital deployment into chemical recycling infrastructure where mechanical routes cannot meet food-contact purity standards. Flexible packaging converters in Italy and Spain face the steepest compliance curves due to legacy reliance on multilayer barrier structures with limited recyclability.
Brand-owner procurement teams are consolidating supplier bases around converters with integrated recycling partnerships and third-party certification. Direct contracting between retailers and paperboard mills is displacing traditional merchant distribution channels for corrugated and cartonboard grades. This pattern is most visible in the United Kingdom and France where major grocery chains have established closed-loop partnerships with specific mill operators.
Recycled Materials Packaging Solutions Market Segmentation
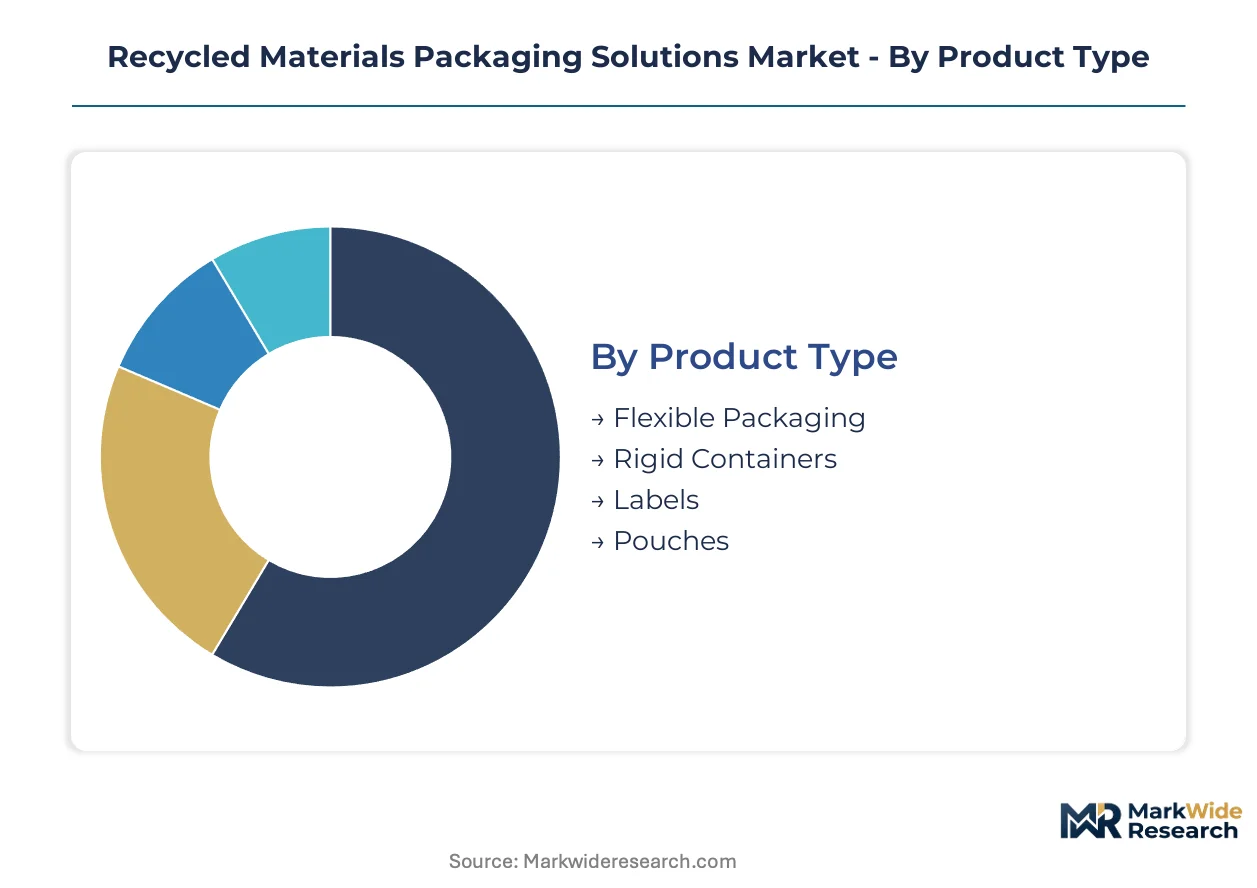
Converters must align product portfolios with divergent technical specifications across material streams and end-use certifications. Each segmentation axis reveals distinct margin structures and compliance burdens that reshape supplier positioning.
Product Type:
Performance specifications vary sharply across structural formats, with barrier requirements and mechanical integrity dictating viable recycled feedstock grades.
- Flexible Packaging:Multilayer films and wraps incorporate mechanically recycled polyethylene and polypropylene streams with calibrated melt-flow indices for blown-film extrusion. Demand concentrates in German and French retail private-label applications where lightweighting targets intersect with EU Green Deal mandates for recycled content thresholds.
- Rigid Containers:Bottles, jars, and thermoformed trays require higher dimensional stability and optical clarity, typically sourced from super-clean recycled PET flake with sub-5% contamination rates. Italian converters serving premium personal care brands face steepest compliance curves due to legacy reliance on virgin resin for aesthetic finish.
- Labels:Pressure-sensitive and shrink-sleeve formats utilize recycled paper facestocks and recycled PET carrier films. The segment expands through direct substitution of virgin substrates in beverage and logistics applications.
- Pouches:Stand-up and flat pouches integrate recycled polyethylene layers with aluminum or metallized barriers. Adoption accelerates in quick-service food segments where shelf-life extension meets circularity commitments.
Mature deployment sits with flexible packaging. Newer deployment is concentrated in rigid containers.
Material:
Feedstock chemistry determines processing routes, contamination tolerance, and end-use eligibility under food-contact regulations.
- Recycled PET:Super-clean flake and pellet grades achieve food-contact certification through advanced decontamination and EFSA novel recycling process approvals. German beverage bottlers anchor commercial-scale adoption, with Rhine-Ruhr reprocessors supplying certified feedstock streams.
- Recycled HDPE:Milk jug and detergent bottle regrind serves non-food rigid applications with less stringent purity requirements. French converters leverage established collection infrastructure for household product containers.
- Recycled Paper:Kraft liner and corrugated medium grades with certified post-consumer fiber content dominate volume in food and beverage channels. UK retail chains have established closed-loop partnerships with specific mill operators for cartonboard supply.
- Biodegradable Plastics:PLA and PHA variants from agricultural waste streams serve niche applications where composting infrastructure supports end-of-life claims. Spanish packaging converters pilot these materials in fresh produce segments with shorter shelf-life requirements.
Recycled paper commands the widest installed base. Recycled PET displays the steepest expansion trajectory as chemical recycling scales.
End Use Industry:
Barrier specifications and regulatory exposure vary substantially across consumer and industrial segments.
- Food & Beverage:Primary and secondary packaging with direct food contact requires EFSA-approved recycling processes and traceable chain-of-custody documentation. German quick-service chains and French retail cooperatives specify minimum post-consumer recycled content in corrugated and flexible formats.
- Personal Care:Premium cosmetics and skincare brands prioritize aesthetic finish and dimensional stability, often accepting higher cost premiums for recycled-content rigid containers with virgin-equivalent optical properties.
- Household Products:Cleaning and detergent segments tolerate higher color variation and lower clarity standards, enabling broader incorporation of mixed-color recycled HDPE streams.
- Electronics:Protective packaging and transit cases demand electrostatic discharge properties and impact resistance, with recycled expanded polystyrene and molded pulp gaining share in premium device segments.
Food and beverage anchors volume demand. Electronics represents the fastest-climbing segment as circularity commitments extend to supply chain packaging.
Packaging Type:
Unit load and primary containment functions dictate scale economies and logistics integration requirements.
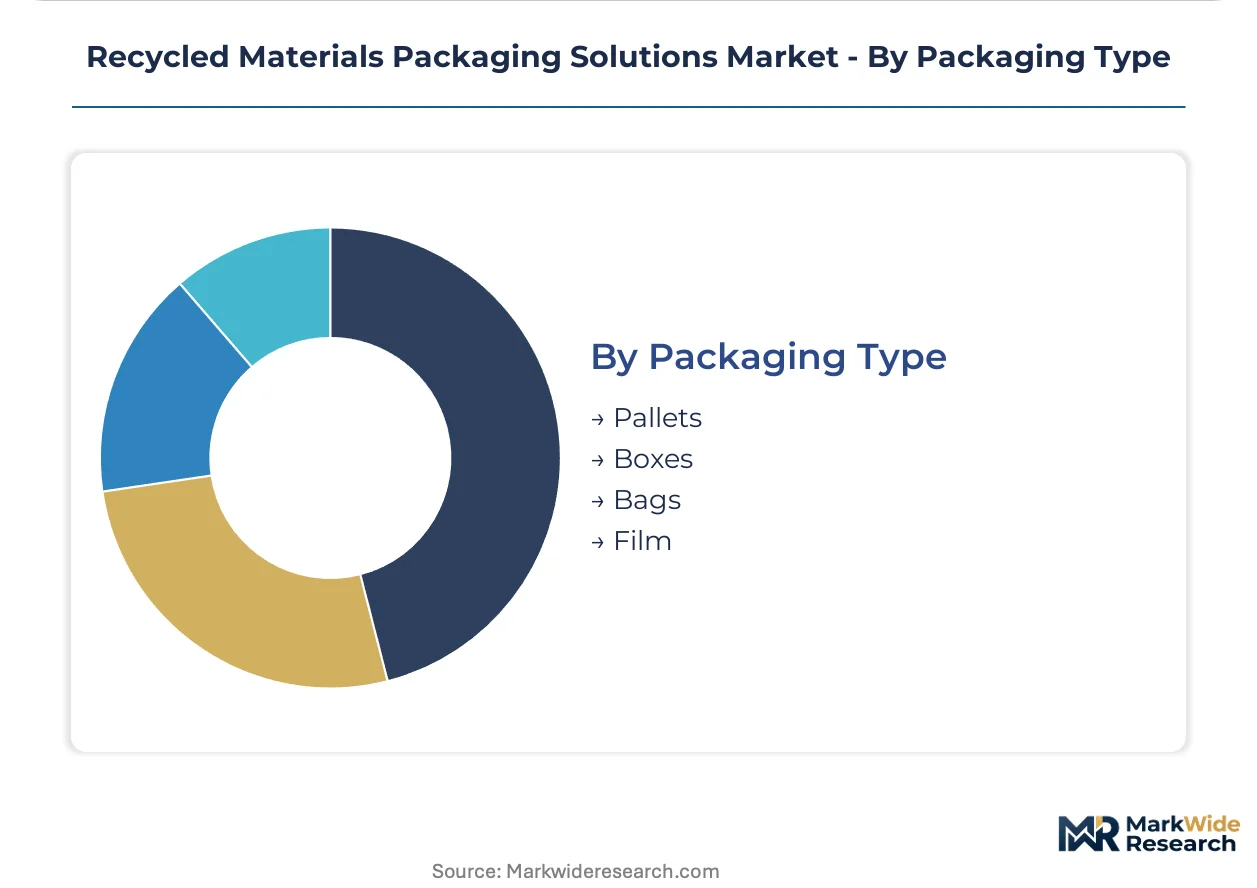
- Pallets:Recycled HDPE and mixed-plastic lumber substitutes for virgin wood in closed-loop logistics systems. German automotive suppliers and French retail distribution centers pilot these formats for durability and moisture resistance.
- Boxes:Corrugated containers with certified recycled linerboard content serve the broadest cross-section of industrial and consumer applications. Direct contracting between retailers and paperboard mills is displacing traditional merchant channels in the United Kingdom.
- Bags:Recycled polyethylene shopping and shipping bags face divergent regulatory treatment across EU member states, with France and Italy imposing stricter thickness and reusability standards than Eastern European markets.
- Film:Stretch wrap and shrink film applications incorporate recycled linear low-density polyethylene with modified cling and puncture properties. Italian converters develop these grades for pallet unitization in food distribution.
Boxes retain the deepest supply base penetration. Film applications are gaining share fastest as stretch-hood and collation formats expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Post-consumer resin collection networks in Germany anchor European feedstock supply for recycled packaging converters. Rhine-Ruhr mechanical reprocessing clusters supply certified flake grades to food-contact film producers across the continent.
Germany
Automotive and retail logistics demand pulls recycled corrugated and stretch film volumes into the Rhine-Ruhr industrial corridor. EU Green Deal packaging waste directives mandate minimum recycled content thresholds with phased compliance deadlines. Düsseldorf-based chemical recycling pilots convert mixed plastic waste into food-grade pellet streams for flexible packaging converters.
France
Retail cooperatives and quick-service chains specify post-consumer recycled content in private-label flexible packaging. Extended producer responsibility frameworks under French environmental codes tighten collection targets for household plastic waste. Lyon-area converters develop multilayer pouch structures incorporating mechanically recycled polyethylene for fresh produce applications.
United Kingdom
Grocery chains establish direct contracting relationships with paperboard mills for closed-loop cartonboard supply. CalRecycle-aligned sustainability procurement standards influence multinational brand owner specifications across British operations. Manchester-Teeside packaging clusters expand decontamination capacity for super-clean PET flake serving beverage bottlers.
Italy
Premium personal care brands drive demand for recycled-content rigid containers with virgin-equivalent optical properties. National packaging consortiums align with EU Packaging and Packaging Waste Regulation implementation timelines. Bologna-Modena converter networks retrofit extrusion lines to handle variable melt-flow indices of post-industrial polypropylene regrind.
Spain
Underdeveloped collection infrastructure and lower converter density create expansion opportunities for integrated recyclers. BIS-aligned recycled content labeling standards influence export-oriented packaging producers serving Indian market requirements. Barcelona-area chemical recycling ventures pilot pyrolysis systems for mixed plastic waste currently rejected by mechanical processors.
Recycled Materials Packaging Solutions Market Competitive Landscape
Global majors compete with regional champions across integrated pulp-to-paper operations and specialized flexible film platforms. The vendor base organizes around three strategic archetypes: integrated paperboard producers with captive recycling assets, multi-material packaging specialists with chemical recycling partnerships, and regional converters with closed-loop retail relationships. Dominant competitive moves include backward integration into post-consumer resin collection networks and strategic partnerships with brand owners for certified chain-of-custody documentation.
Within the integrated paperboard tier, Mondi plc and DS Smith plc exemplify operators with captive pulp-to-paper infrastructure and retail chain partnerships. Amcor plc occupies a position among multi-material specialists developing mechanically recycled polyethylene terephthalate platforms for flexible packaging applications. These three entities represent divergent strategic postures on vertical integration depth and geographic concentration.
| Leading Market Players |
|---|
| Mondi plc |
| Tetra Pak International S.A. |
| Amcor plc |
| DS Smith plc |
| Berry Global, Inc. |
| Smurfit WestRock plc |
| Sealed Air Corporation |
| Ball Corporation |
| International Paper Company |
| Others |
Value Network & Pricing Analysis
Polymer chemist concentrations in the Rhine-Ruhr corridor anchor labor-cost differentials that widen pricing-tier spreads between certified food-contact grades and industrial non-food streams. German mechanical reprocessors command premium wages that flow through to converter pricing, while Eastern European facilities operate on narrower margins with less stringent certification overhead.
Pricing Analysis
Certified chain-of-custody documentation and EFSA novel food approval status are bundled into premium-tier quotations, while standard grades exclude traceability systems and after-sales technical support. Three-tier pricing structure across premium, standard, and economy levels separates EFSA-approved food-contact flake from industrial-grade regrind and mixed-color pooled material. Price differentiation hinges on contamination thresholds and melt-flow consistency, with sub-5% contamination rates commanding substantial premiums over 10-15% tolerance grades. Cost compression in the standard tier is intensifying because baled PET feedstock costs fluctuate with crude oil benchmarks and collection seasonality. Quick-service retail chains exhibit highest price sensitivity due to volume procurement mandates, while pharmaceutical secondary packaging buyers accept premium positioning for optical clarity assurances.
Supply Chain Analysis
EFSA novel food and recycling process approvals function as qualification gates that filter feedstock eligibility for food-contact applications, with 18-24 month evaluation windows creating supply bottlenecks. Geographic supply concentration centers on Germany, France, and Italy as anchor reprocessing hubs, with Spain and Eastern Europe emerging as expansion frontiers. Raw material dependencies draw from post-consumer baled PET, HDPE milk jug collections, and kraft liner recovered fiber pools. Single-source vulnerability runs through Rhine-Ruhr mechanical recycling clusters where energy cost spikes or capacity constraints would cascade across European converter networks. Distribution runs through direct contracting relationships between major retail chains and certified mill operators, displacing traditional merchant channels for corrugated and cartonboard grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around converters with integrated recycling partnerships and third-party certification capabilities, as EU Green Deal packaging waste directives force sub-scale operators out of compliance reach. Margin compression from post-consumer resin price volatility accelerates exit pressure on non-integrated players lacking captive feedstock security.
For Market Incumbents: Cement backward integration into post-consumer resin collection networks to secure certified feedstock streams ahead of tightening EU Packaging and Packaging Waste Regulation thresholds. Lock in long-term offtake agreements with major retail chains for closed-loop corrugated supply, defending against chemical recycling entrants that bypass mechanical purity limitations. Prioritize EFSA novel food approval pipelines for super-clean flake grades to maintain food-contact positioning against emerging pyrolysis competitors.
For New Entrants and Emerging Players: Direct-to-brand digital procurement platforms offer route-to-market acceleration for specialized recycled-content formats, bypassing entrenched merchant distribution channels. Target Spain and Eastern European markets where underdeveloped collection infrastructure and lower converter density create first-mover advantages for integrated recyclers. Focus initial deployment on pharmaceutical secondary packaging segments where barrier requirements are less stringent than primary blister packs, enabling faster certification timelines.
For Investors and Strategic Acquirers: Re-rating potential sits with chemical recycling ventures given EFSA food-contact approval acceleration for pyrolysis and depolymerization outputs. Long-term viability favors operators with geographic diversification beyond Rhine-Ruhr concentration risk and multi-material platform flexibility spanning rigid containers and flexible films. Watch EFSA approval timelines for novel recycling processes as inflection indicator for mechanical-to-chemical recycling value migration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Collection Networks | Captive post-consumer resin supply secures compliance with EU Green Deal recycled content mandates. |
| EFSA Novel Food Approval Investment | Food-contact certification for super-clean flake opens premium pricing tiers in beverage bottling segments. |
| Chemical Recycling Scale-Up | Pyrolysis capacity converts mixed plastic waste streams currently rejected by mechanical processors. |
| Closed-Loop Retail Partnerships | Direct contracting with grocery chains displaces merchant channels for corrugated and cartonboard grades. |
| Geographic Expansion to Spain and Eastern Europe | Underdeveloped collection infrastructure creates first-mover advantages for integrated recyclers entering these markets. |
Research Methodology
Trade association filings, EU regulatory databases, and customs import-export records formed the secondary backbone, cross-referenced against primary interviews with packaging converters, retail procurement directors, and mechanical recycling plant managers. Bottom-up volume estimates triangulated with top-down spending analysis across food and beverage, personal care, and electronics end-use segments. Primary fieldwork captured operational data on contamination thresholds, melt-flow indices, and extrusion line retrofit requirements.
Historical trendline analysis established baseline growth patterns across flexible packaging, rigid containers, and paperboard grades, with projections built through driver-linked elasticity modeling over the analysis window. Segmentation dimensions spanned material chemistry, product format, end-use industry, and geographic production cluster. CAGRs derived from weighted average of demand-pull factors and supply-push constraints, incorporating EFSA approval pipeline velocities and chemical recycling capacity buildout schedules as industry-specific forecast inputs.
Inputs from regulatory filings and converter operational disclosures were available through the study window; gaps in real-time baled PET spot pricing and confidential EFSA evaluation timelines introduce uncertainty bands around near-term margin projections. Forecasts reflect assumptions on EU member state implementation pacing for recycled content mandates and mechanical recycling yield improvements. A model refresh is warranted upon material change in EFSA novel food approval timelines or Rhine-Ruhr energy cost trajectories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Solutions
Patisserie Packaging Market
Packaging Solutions
North America E-Commerce Packaging Market
Packaging Solutions
Global Bespoke Packaging Market
Packaging Solutions
Shelf Stable Packaging Market
Packaging Solutions
Halal Packaging Market
Packaging Solutions
Panel Level Packaging Market
Packaging Solutions
Anti-Counterfeit Clothing Packaging Market
Packaging Solutions
Global Lithium Ion Battery Packaging Solutions Market
Packaging Solutions
United States Contract Packaging Market
Packaging Solutions
United Kingdom Packaging Market
Packaging Solutions
Hermetic Packaging Market
Packaging Solutions
Australia Contract Packaging Market
Packaging Solutions
Vacuum Skin Packaging Market
Packaging Solutions
Global Packaging Market
Packaging Solutions
Packaging Solutions Market
Packaging Solutions
Supplements and Nutrition Packaging Market