
 Middle East and Africa Contract Packaging Market | 2026-2036
Middle East and Africa Contract Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Contract Packaging Market Foresight
Saudi Arabia's plastics conversion sector is repositioning toward pharmaceutical-grade cleanroom capacity. Charles Kendall Group leverages its Gulf logistics networks to serve defense and aerospace packaging requirements. Promo Pack Solutions LLC anchors its operations in Dubai's Jebel Ali Free Zone, sustaining proximity to re-export corridors across East Africa and the Levant.
Contract packaging encompasses outsourced primary and secondary packaging execution performed by third-party providers on behalf of brand owners, typically involving automated filling, sealing, labelling, and assembly processes under client specifications and quality protocols. Flexible packaging commands significant volume share in the Middle East and Africa contract packaging landscape due to its lightweight properties and suitability for ambient distribution networks across high-temperature climates. Pharmaceutical end-user demand is expanding fastest among segment categories, driven by track-and-trace compliance requirements and the absence of in-house packaging infrastructure at emerging biotech manufacturers across the region.
SFDA in Saudi Arabia and the UAE's Ministry of Industry and Advanced Technology enforce pharmaceutical serialization standards that compel brand owners to validate contract packagers against Good Manufacturing Practice protocols. South Africa's national pharmaceutical regulator mandates comparable traceability standards, tightening qualification criteria for outsourced operations. Stakeholders must monitor evolving halal certification requirements for food and cosmetic packaging, as Gulf state authorities expand jurisdiction over supply chain integrity claims.
Market Dynamics
Pharmaceutical serialization mandates across Gulf Cooperation Council states and South Africa are forcing brand owners to outsource packaging execution to qualified contract providers, compressing qualification timelines and reshaping vendor selection criteria throughout the region.
Growth Catalysts
- SFDA serialization protocols:Saudi Arabia's pharmaceutical regulator mandates unit-level traceability, compelling domestic and multinational drug manufacturers to validate third-party packagers against Good Manufacturing Practice standards.
- Flexible film conversion:Food processors across the United Arab Emirates, Qatar, and Kuwait are converting ambient-stable product lines to lightweight pouches and sachets suited to regional distribution networks.
- Biotech infrastructure gaps:Emerging pharmaceutical manufacturers in Egypt and Nigeria lack in-house packaging lines, creating immediate demand for contract serialization and secondary assembly services.
Market Restraints
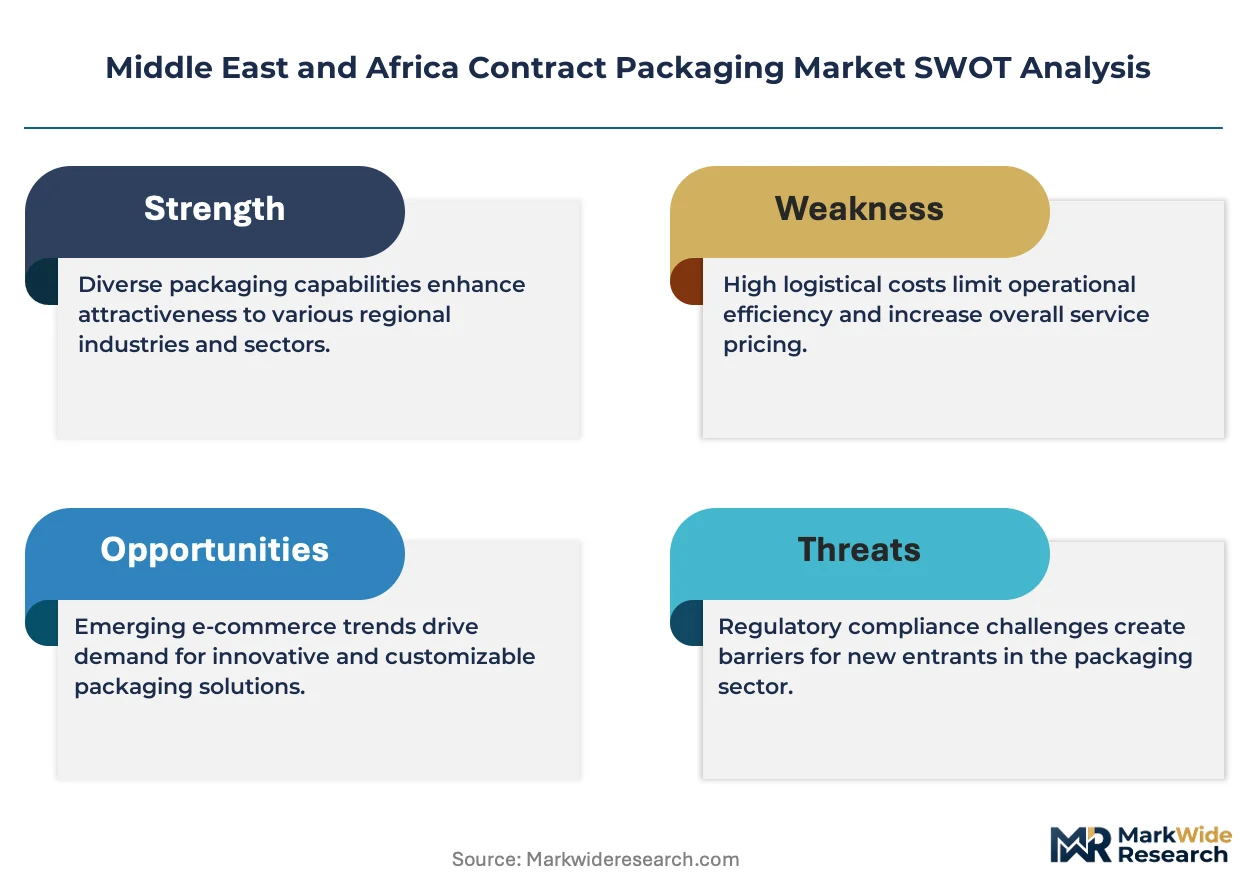
- Polymer feedstock volatility:Resin prices for polyethylene and polypropylene fluctuate with crude oil benchmarks, squeezing margin structures for flexible packaging specialists serving FMCG clients.
- Cleanroom capex concentration:Pharmaceutical-grade packaging capacity clusters in Dubai's Jebel Ali Free Zone and Riyadh's industrial corridors, limiting geographic redundancy for time-sensitive drug launches.
- Halal certification fragmentation:Divergent authority standards between UAE's Emirates Authority for Standardization and Metrology and Saudi Standards, Metrology and Quality Organization create compliance friction for cross-border cosmetic and nutraceutical shipments.
Strategic Opportunities
- East African corridor expansion:Contract packagers operating from Dubai's logistics free zones can extend re-export services to Kenya, Ethiopia, and Tanzania as pharmaceutical distribution networks formalize.
- Aseptic beverage formats:UHT milk and juice processors in Saudi Arabia and Egypt seek ambient-stable carton and bottle packaging partnerships to replace refrigerated supply chains.
- Track-and-trace technology convergence:Integration of RFID serialization with blockchain verification protocols creates premium service tiers for high-value pharmaceutical and luxury cosmetic brands.
Industry Challenges
- Qualified technician scarcity:Pharmaceutical packaging lines require operators trained in cleanroom protocols and automated serialization equipment, with limited vocational pipeline capacity across the Levant and North Africa.
- Dual certification timelines:Contract packagers serving both EU export and domestic Gulf markets must simultaneously satisfy EMA Good Manufacturing Practice and local health authority inspections, extending facility qualification periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Contract Packaging Market |
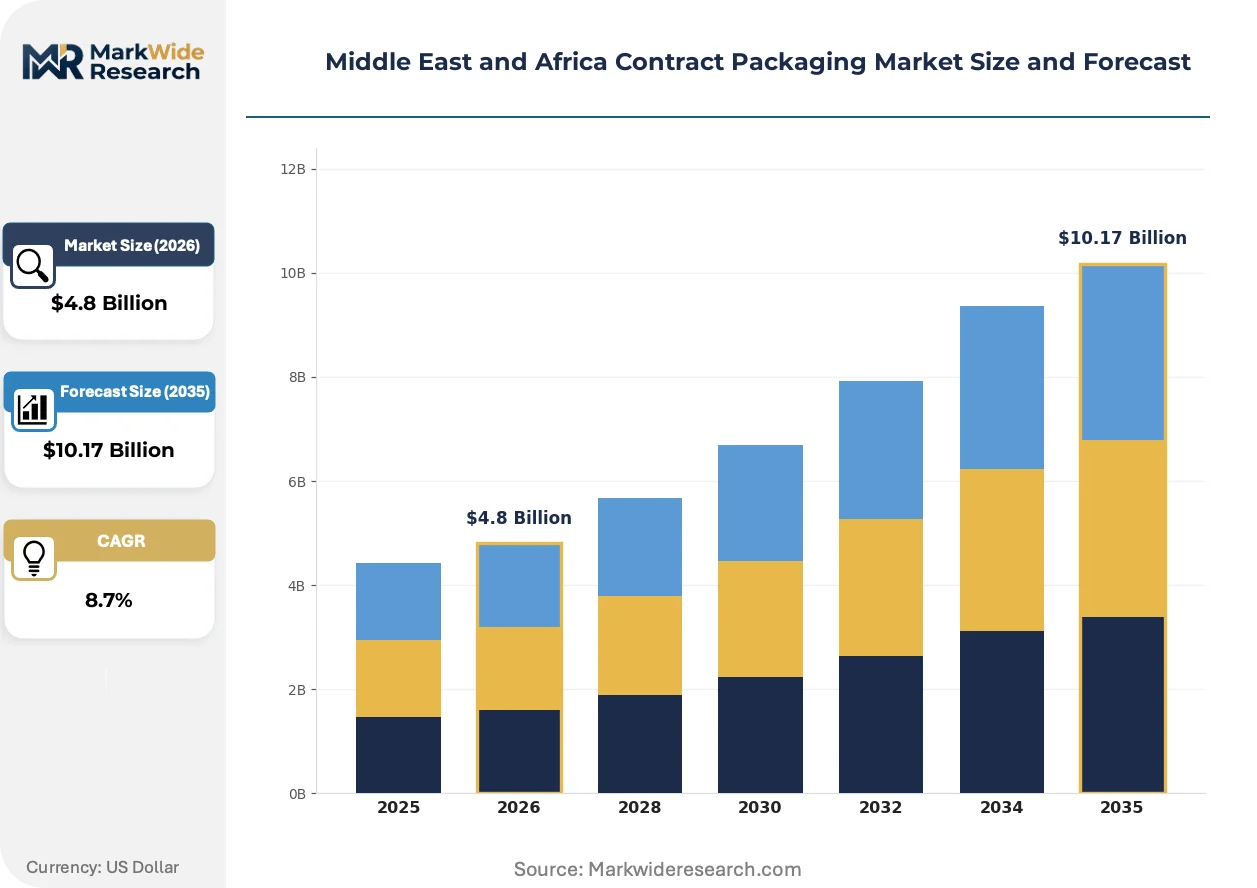
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Packaging, Rigid Containers, Shrink Labels, Bottles End User: Food & Beverage, Pharmaceuticals, Cosmetics, Electronics Packaging Type: Cartons, Pouches, Tapes, Clamshells Service Type: Filling, Sealing, Labelling, Assembly |
| Companies Covered | Charles Kendall Group, Collaborative Packing Solutions, Promo Pack Solutions LLC, Wrapsa (Pty) Ltd., Joypak (Pty) Ltd., StrongPack Ltd., Al Bustan Co-Packing LLC, Al Sharaf Repacking Services, Gulf Trading and Refrigerating LLC, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Contract Packaging Market Shifts & Advancements
Digital printing and smart packaging technologies are compressing production runs and enabling personalized batch execution, while regulatory convergence around traceability standards accelerates automation investment across pharmaceutical and food verticals.
Digital inkjet printing for variable data and short-run flexible packaging is overtaking conventional rotogravure for promotional and seasonal SKU production. Regional confectionery and personal care brands in the United Arab Emirates and Saudi Arabia are adopting digital workflows to reduce minimum order quantities from hundreds of thousands to tens of thousands of units. This technology shift is compressing inventory carrying costs and enabling rapid market testing for flavor and formulation variants.
South Africa's national pharmaceutical regulator has mandated comparable serialization standards to European Union Falsified Medicines Directive frameworks, requiring two-dimensional data matrix codes on prescription drug packaging by specified enforcement dates. Domestic contract packagers must retrofit existing lines with vision systems and aggregation software or risk disqualification from government tender participation. Biotech startups without legacy infrastructure are bypassing retrofitting entirely by selecting qualified contract partners from launch.
Direct-to-retailer procurement models are displacing traditional distributor intermediation for packaged food and beverage products in Gulf Cooperation Council markets. Hypermarket chains including Carrefour UAE and Lulu Group International are negotiating direct supply agreements with contract packagers for private-label ambient goods, compressing margin pools previously captured by wholesale layers. This channel restructuring concentrates volume with packagers demonstrating retailer-specific compliance certification and just-in-time replenishment capability.
Middle East and Africa Contract Packaging Market Segmentation
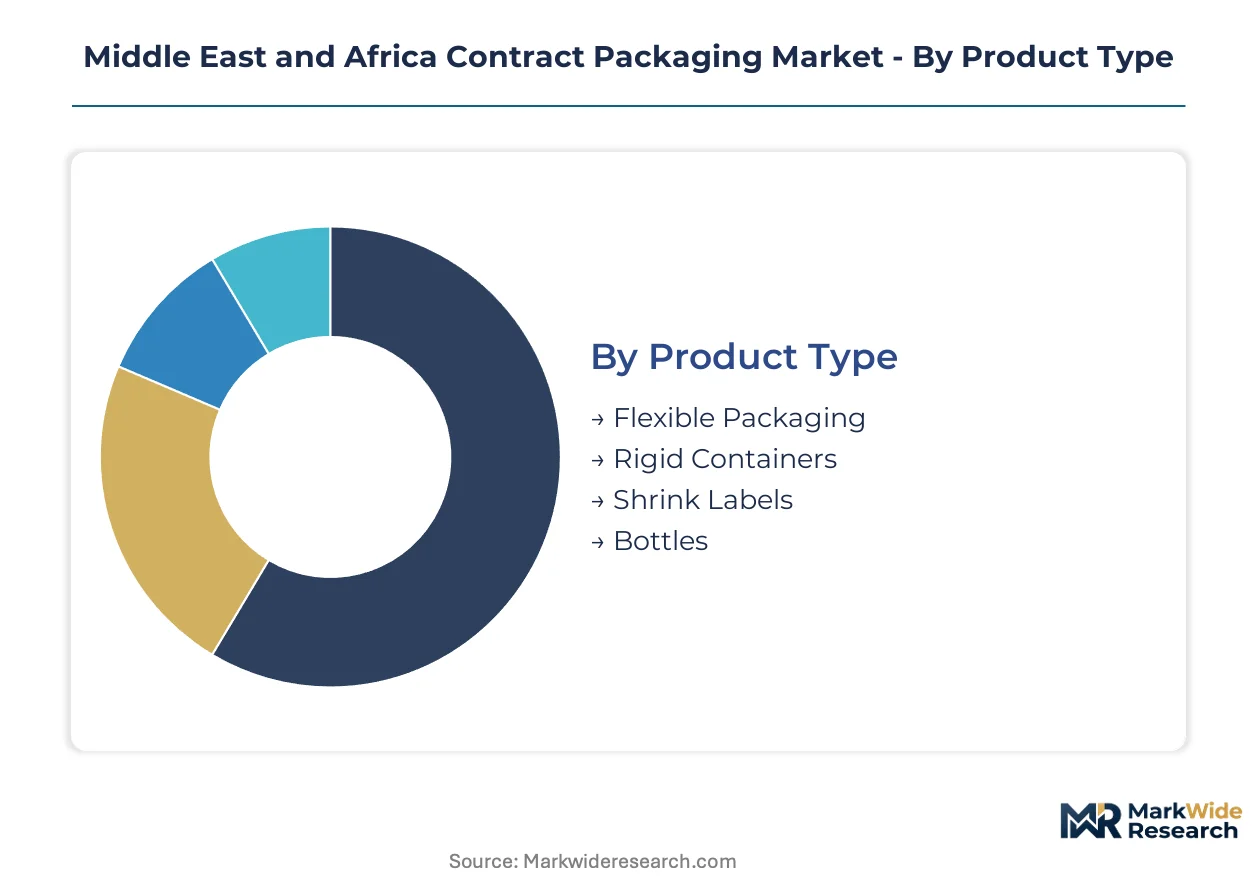
Segmentation in the Middle East and Africa contract packaging market reveals divergent margin profiles and qualification barriers across material formats and service tiers. Pharmaceutical-grade cleanroom capacity commands premium pricing while flexible packaging volumes concentrate in ambient-stable food applications across Gulf Cooperation Council distribution networks.
Product Type:
Volume concentration versus premium pricing splits sharply across material categories, with lightweight formats dominating unit economics and rigid formats capturing value-intensive pharmaceutical applications.
- Flexible Packaging:Polyethylene and polypropylene films configured as pouches, sachets, and laminated structures for ambient distribution across high-temperature climates. Food processors in the United Arab Emirates, Qatar, and Kuwait are converting product lines to lightweight formats that reduce freight costs across regional logistics networks. Polymer feedstock volatility tied to crude oil benchmarks squeezes margin structures for specialists serving FMCG clients.
- Rigid Containers:Injection-molded and thermoformed plastic containers, jars, and canisters requiring dimensional stability for moisture-sensitive formulations. Pharmaceutical serialization mandates under Saudi Arabia's SFDA and South Africa's national health regulator are forcing brand owners to validate third-party packagers against Good Manufacturing Practice standards for these formats.
- Shrink Labels:Polyvinyl chloride and polyethylene terephthalate glycol films applied through heat-tunnel contraction for contour branding and tamper evidence.
- Bottles:Blow-molded high-density polyethylene and polyethylene terephthalate containers for liquid and semi-solid products across beverage and personal care applications.
Mature deployment sits with Flexible Packaging. Newer deployment is concentrated in Rigid Containers.
End User:
Customer-type segmentation distinguishes between regulated industries requiring traceability infrastructure and consumer sectors prioritizing speed-to-market and format innovation.
- Food & Beverage:Ambient-stable and chilled product categories requiring high-throughput filling, sealing, and secondary assembly. Direct-to-retailer procurement models at Carrefour UAE and Lulu Group International are displacing traditional distributor intermediation, concentrating volume with packagers demonstrating retailer-specific compliance certification.
- Pharmaceuticals:Prescription and over-the-counter drug packaging subject to serialization, aggregation, and Good Manufacturing Practice validation. Biotech startups in Egypt and Nigeria without legacy infrastructure are bypassing capital expenditure entirely by selecting qualified contract partners from launch.
- Cosmetics:Fragrance, skincare, and color cosmetic packaging requiring aesthetic precision and halal certification compliance for Gulf state distribution.
- Electronics:Anti-static and protective packaging for component and finished goods distribution through Dubai's logistics free zones.
Food & Beverage captures the highest volume throughput. Pharmaceuticals are climbing the fastest on compliance-driven outsourcing.
Packaging Type:
Format selection tracks distribution channel requirements, with shelf-ready and e-commerce-compatible structures gaining preference over traditional configurations.
- Cartons:Paperboard folding cartons for secondary packaging and shelf-ready display, printable through digital inkjet workflows for short-run promotional execution.
- Pouches:Stand-up and flat flexible formats with reseal features for ambient-stable food and beverage products across GCC retail networks.
- Tapes:Pressure-sensitive and water-activated adhesive tapes for case sealing and tamper-evident closure in logistics applications.
- Clamshells:Thermoformed clear plastic enclosures for retail display and theft deterrence in electronics and high-value consumer goods.
Carton deployment dominates established retail channels. Pouch formats are gaining share fastest through e-commerce and convenience retail expansion.
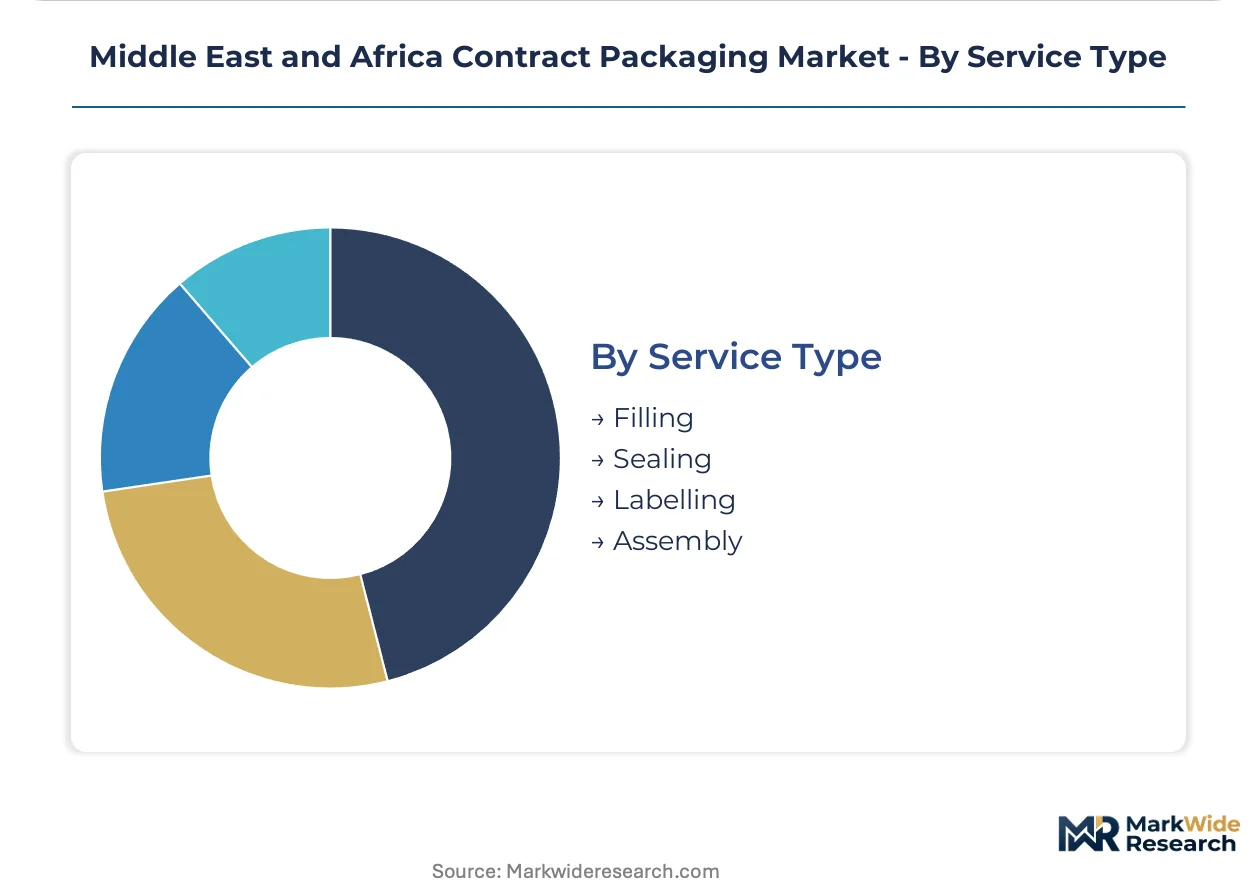
Service Type:
Service depth correlates with customer technical capabilities, with full-service integration preferred by emerging manufacturers lacking in-house packaging infrastructure.
- Filling:Automated liquid, powder, and semi-solid dispensing into primary containers under controlled environmental conditions.
- Sealing:Heat, induction, and ultrasonic closure technologies ensuring package integrity across ambient distribution networks.
- Labelling:Pressure-sensitive, shrink-sleeve, and in-mould decoration incorporating variable data serialization for pharmaceutical traceability.
- Assembly:Kit construction, multi-component bundling, and secondary packaging execution for complex product configurations.
Labelling services carry the highest regulatory burden. Assembly services are expanding most quickly through kit-format pharmaceutical and diagnostic product launches.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Petrochemical feedstock availability along the Arabian Gulf anchors contract packaging capacity expansion across the Middle East and Africa region. Polyethylene and polypropylene resin supplies from Saudi Arabia's Eastern Province and Qatar's Ras Laffan Industrial City enable flexible packaging conversion at competitive unit economics. Distribution networks radiate from Dubai's logistics free zones toward East African and Levantine markets.
United Arab Emirates
Pharmaceutical serialization mandates from the Ministry of Industry and Advanced Technology are compressing qualification timelines for contract packagers serving both domestic and re-export markets. Dubai's Jebel Ali Free Zone hosts concentrated cleanroom capacity for pharmaceutical-grade packaging, with packagers leveraging proximity to Al Maktoum International Airport for time-sensitive drug distribution across the Gulf and East Africa.
Saudi Arabia
The Saudi Food and Drug Authority enforces unit-level traceability requirements that compel domestic and multinational drug manufacturers to validate third-party packagers against Good Manufacturing Practice standards. Riyadh's industrial corridors and the Eastern Province's Jubail Industrial City are attracting plastics conversion investments repositioned toward pharmaceutical-grade cleanroom capacity.
South Africa
The country's national pharmaceutical regulator mandates serialization standards comparable to European Union frameworks, requiring two-dimensional data matrix codes on prescription drug packaging. Gauteng province, centered on Johannesburg and Pretoria, concentrates contract packaging operations serving domestic pharmaceutical manufacturers expanding outsourced operations to meet compliance deadlines.
Egypt
Emerging biotech manufacturers in Cairo and Alexandria lack in-house packaging infrastructure, creating immediate demand for contract serialization and secondary assembly services. The country's central pharmaceutical regulator is tightening qualification criteria for outsourced operations, with packagers in the Greater Cairo region retrofitting lines with vision systems and aggregation software.
Nigeria
Pharmaceutical distribution network formalization in Lagos and Abuja is creating demand for contract packaging partnerships capable of serialization compliance. Packagers operating from Lagos State industrial zones are positioning to serve emerging biotech manufacturers bypassing capital expenditure through qualified contract relationships from product launch.
Middle East and Africa Contract Packaging Market Competitive Landscape
Global majors compete with regional champions across qualification speed and regulatory intimacy in the Middle East and Africa contract packaging market. The vendor base clusters around Dubai's logistics free zones and Riyadh's industrial corridors, with tiered capabilities separating pharmaceutical-grade cleanroom operators from high-volume flexible packaging specialists. Two strategic archetypes dominate: Gulf-based logistics-integrated packagers leveraging free zone advantages, and South African specialists with established pharmaceutical validation histories. Competitive moves concentrate on capacity expansion in pharmaceutical-grade cleanrooms and strategic partnerships with biotech startups lacking packaging infrastructure.
Within the logistics-integrated tier, Charles Kendall Group and Promo Pack Solutions LLC exemplify Gulf-based operators leveraging free zone positioning for defense, aerospace, and consumer goods packaging requirements. Charles Kendall Group anchors its operations on established Gulf logistics networks, while Promo Pack Solutions LLC sustains proximity to re-export corridors across East Africa and the Levant from Dubai's Jebel Ali Free Zone. Wrapsa (Pty) Ltd. represents the South African pharmaceutical validation archetype, occupying a position shaped by domestic serialization mandates and established relationships with regional drug manufacturers.
| Leading Market Players |
|---|
| Charles Kendall Group |
| Collaborative Packing Solutions |
| Promo Pack Solutions LLC |
| Wrapsa (Pty) Ltd. |
| Joypak (Pty) Ltd. |
| StrongPack Ltd. |
| Al Bustan Co-Packing LLC |
| Al Sharaf Repacking Services |
| Gulf Trading and Refrigerating LLC |
| Others |
Supply & Pricing Matrix
Polyethylene resin futures tied to Brent crude benchmarks cascade through contract packaging tiers, compressing margins for flexible film specialists serving Gulf Cooperation Council food processors while amplifying pricing power for pharmaceutical-grade cleanroom operators with polymer hedging programs.
Pricing Analysis
Service bundling separates validated pharmaceutical serialization packages from unbundled flexible film conversion quotes. Three-tier pricing structure across premium, standard, and economy levels tracks certification depth, with Good Manufacturing Practice validation commanding substantial premiums over basic food-grade capacity. Pricing pressure stems from polymer feedstock volatility squeezing FMCG-facing specialists. Food processors exhibit highest price sensitivity, while biotech startups lacking infrastructure accept premium rates for turnkey compliance.
Supply Chain Analysis
Regional distribution centers in Dubai's Jebel Ali Free Zone and Riyadh's industrial corridors anchor hub-and-spoke patterns radiating toward East African and Levantine markets. Polyethylene and polypropylene resin supplies from Saudi Arabia's Eastern Province and Qatar's Ras Laffan Industrial City feed conversion operations. Single-source vulnerability concentrates in pharmaceutical-grade cleanroom capacity clustering around Dubai and Riyadh. Distribution runs through logistics free zones with re-export privileges to sub-Saharan markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Contract packaging is becoming a vertical-integration race as multinational consumer goods firms and pharmaceutical manufacturers seek captive control over serialization-compliant capacity and polymer conversion operations.
For Market Incumbents: Extend cleanroom certification portfolios to capture biotech startup launches in Egypt and Nigeria before competitors retrofit lines. Lock in long-term polymer supply agreements with Saudi Arabia's Eastern Province producers to defend margin structures against resin volatility. Prioritize dual EMA-Gulf qualification to serve EU export and domestic markets simultaneously. For New Entrants and Emerging Players: Biotech startups in Cairo and Alexandria represent the most penetrable customer segment, lacking in-house packaging infrastructure and requiring immediate serialization partnerships. Target pharmaceutical-grade pouch formats for ambient-stable vaccines and diagnostics as the fastest-expanding white space. Pursue direct procurement relationships with Carrefour UAE and Lulu Group International to bypass wholesale intermediation layers. For Investors and Strategic Acquirers: Distressed-cycle entries favor South African pharmaceutical validation specialists in Gauteng province as domestic serialization mandates compress qualification timelines for subscale operators. Long-term viability hinges on regulatory intimacy rather than scale alone. Watch for SFDA enforcement acceleration as the inflection signal triggering consolidation among underqualified Gulf packagers.| Strategic Initiative | Industry Significance |
|---|---|
| Pharmaceutical-Grade Cleanroom Expansion | SFDA and UAE Ministry of Industry mandates force brand owners to validate third-party packagers against Good Manufacturing Practice protocols. |
| Polymer Feedstock Hedging Programs | Flexible packaging specialists serving GCC food processors lock in polyethylene contracts to stabilize margins against crude-linked volatility. |
| Dual Certification Investment | Packagers simultaneously pursuing EMA and Gulf health authority approvals capture EU export and domestic pharmaceutical volumes. |
| Direct-to-Retailer Channel Development | Hypermarket chains including Carrefour UAE and Lulu Group International displace distributor intermediation for private-label ambient goods. |
| East African Corridor Logistics Integration | Dubai-based packagers extend re-export services to Kenya, Ethiopia, and Tanzania as pharmaceutical distribution networks formalize. |
Research Methodology
Document review covered regulatory filings from Saudi Arabia's SFDA and South Africa's national pharmaceutical regulator, trade flow databases tracking polymer resin movements through GCC customs zones, and pharmaceutical packaging qualification standards, complemented by interviews with contract packaging operations directors, pharmaceutical regulatory affairs leads at biotech manufacturers, polymer procurement managers at flexible film converters, and logistics coordinators at Dubai free zone operators. Secondary validation drew from customs records, industry association capacity surveys, and health authority inspection reports. Bottom-up facility capacity modeling and top-down end-use demand estimation were triangulated against reported contract values.
Segmented outputs across material format, end-use vertical, service tier, and geographic regulatory cluster were generated across the projection horizon. CAGRs were derived from fitted growth curves incorporating pharmaceutical serialization mandate enforcement schedules, biotech startup formation rates, and flexible packaging conversion capacity additions. Key inputs included polymer price index trajectories, cleanroom qualification timeline distributions, and direct-to-retailer procurement penetration rates.
Caveats apply where SFDA enforcement acceleration, polymer supply disruptions from Eastern Province production facilities, or halal certification standard divergence between Emirates Authority for Standardization and Metrology and Saudi Standards, Metrology and Quality Organization could materially shift the outlook. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Solutions
Single Dose Packaging Market
Packaging Solutions
Interior Packaging Market
Packaging Solutions
Suspension and Retention Packaging Market
Packaging Solutions
Portable UV Sanitizing Boxes Market
Packaging Solutions
Global Noise Control Enclosures Packaging Market
Packaging Solutions
India E-Commerce Packaging Market
Packaging Solutions
Contract Packaging Market
Packaging Solutions
Transport Packaging Market
Packaging Solutions
Saudi Arabia Packaging Market
Packaging Solutions
Hermetic Packaging Market
Packaging Solutions
Australia Contract Packaging Market
Packaging Solutions
Contract Packaging and Fulfillment Service Market
Packaging Solutions
Global Coding and Marking Solutions Market
Packaging Solutions
Europe Temperature Controlled Packaging Solutions Market
Packaging Solutions
Packaging Solutions Market
Packaging Solutions
Mexico Packaging Market