
 Digital Media Adapters Market | 2026-2036
Digital Media Adapters Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Media Adapters Market Analysis
Silicon is shifting toward more efficient system-on-chip architectures that reduce thermal load and enable smaller form factors in streaming hardware. Google LLC leverages its Android TV platform to anchor software-hardware integration across multiple OEM partnerships. Apple Inc. sustains premium positioning through proprietary silicon and closed ecosystem control. Roku, Inc. dominates the North American streaming stick segment through aggressive content aggregation and retail channel presence.
Digital media adapters are compact intermediary devices that convert network-delivered or stored audiovisual content into HDMI-compatible signals for display on televisions and monitors, typically supporting resolutions up to 4K with HDR processing and hardware-accelerated codec decoding. Their primary commercial purpose is to extend the functional lifespan of non-smart displays while enabling over-the-top content access without full television replacement. Streaming sticks lead unit volume due to sub-fifty-dollar entry pricing and impulse-purchase channel placement, while media hubs capture disproportionate margin pools through expanded storage, local media serving, and advanced connectivity options. The wireless technology segment grows fastest as Wi-Fi 6E and emerging Wi-Fi 7 standards reduce latency for 4K streaming, though Ethernet retains structural importance in commercial and hospitality deployments where network stability is paramount.
The Federal Communications Commission enforces Part 15 emissions standards that all streaming devices must clear before US market entry, while the HDMI Forum licenses connector specifications that govern physical interoperability and content protection handshake protocols. European CE marking requirements under the Radio Equipment Directive shape product design for regional distribution, and China's MIIT certification mandates specific wireless frequency compliance for domestic sales. Stakeholders must monitor evolving content protection standards and regional wireless spectrum reallocations that could obsolete existing hardware architectures or trigger compliance-driven replacement cycles.
Market Dynamics
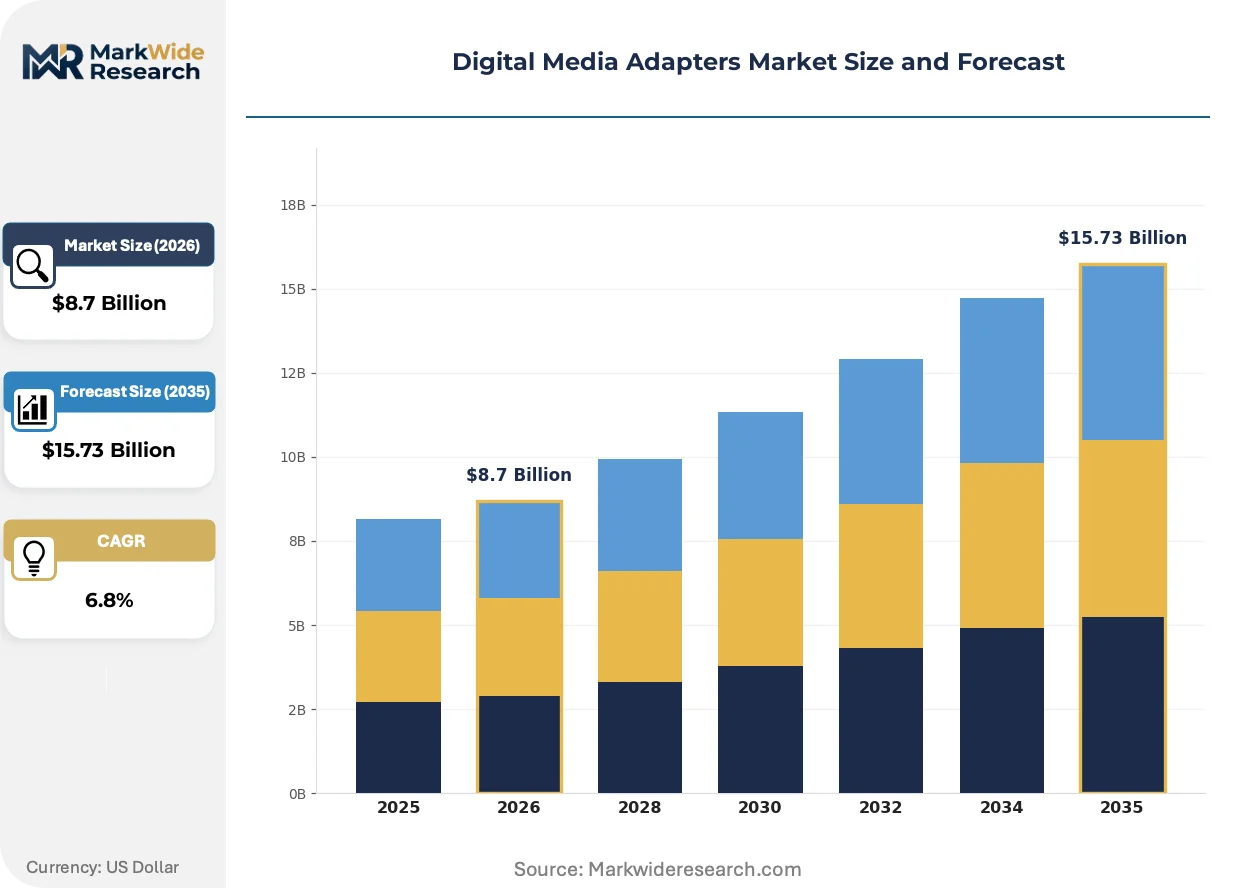
Wi-Fi 6E and Wi-Fi 7 silicon integration is compressing hardware refresh cycles as consumers replace aging adapters to unlock lower-latency 4K streaming, forcing OEMs to accelerate chipset procurement and thermal design investments.
Growth Catalysts
- Residential cord-cutting acceleration:US households abandoning cable subscriptions are purchasing streaming sticks to retrofit legacy televisions, expanding the installed base of addressable displays.
- FCC Part 15 compliance frameworks:Device authorization requirements create certification barriers that favor established manufacturers with testing infrastructure, consolidating shelf space at major retailers.
- Silicon efficiency gains:Advanced system-on-chip architectures reduce power consumption and thermal load, enabling smaller form factors that lower logistics costs and expand retail channel placement.
Market Restraints
- HDMI Forum licensing costs:Connector specification and HDCP content protection handshake fees add per-unit costs that compress margins at sub-fifty-dollar price points.
- Foundry concentration in Taiwan:Advanced node semiconductor fabrication relies on limited geographic supply sources, exposing production schedules to regional disruption risks.
- Smart TV substitution pressure:Integrated streaming applications in new television purchases reduce the addressable market for external adapter hardware over multi-year replacement cycles.
Strategic Opportunities
- India broadband infrastructure expansion:Government-funded fiber deployment and 5G fixed wireless access are creating first-time streaming households requiring low-cost adapter solutions.
- Commercial hospitality retrofit demand:Hotels and extended-stay properties are upgrading guest room entertainment systems to support casting and app-based content without full television replacement.
- Wi-Fi 7 ecosystem convergence:Multi-gigabit wireless standards enable uncompressed 4K streaming that eliminates Ethernet dependency, opening wireless-only product categories for premium positioning.
Industry Challenges
- CE marking timeline compression:European Radio Equipment Directive certification requirements are extending product launch schedules as testing backlogs accumulate at notified bodies.
- Codec licensing complexity:Patent pools for HEVC, AV1, and emerging VVC standards create royalty stacking risks that complicate BOM forecasting and margin planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Media Adapters Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Streaming Stick, Media Hub, Set-Top Box, HDMI Adapter Technology: Wireless, Wired, Bluetooth, Ethernet End User: Residential, Commercial, Educational, Hospitality Distribution Channel: Online Retail, Specialty Stores, Direct Sales, Distributors |
| Companies Covered | Roku, Inc., Apple Inc., Google LLC, Amazon.com, Inc., Samsung Electronics Co., Ltd., NETGEAR Inc., Cisco Systems, Inc., Sony Corporation, Western Digital Technologies, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Media Adapters Market Emerging Trajectories
Silicon integration and wireless protocol evolution are collapsing the functional gap between streaming sticks and premium media hubs, compressing the premium tier's differentiation basis while expanding addressable use cases.
System-on-chip designs incorporating CPU, GPU, and dedicated AV1 decode blocks are unifying processing architectures that previously required discrete components. Mid-tier OEMs are adopting these integrated platforms to reduce PCB area and thermal solution costs. This unification is compressing the hardware gap between economy streaming sticks and premium media hubs, forcing vendors to differentiate through software and content aggregation rather than raw specification.
China's MIIT certification mandates for wireless frequency compliance are tightening domestic market entry requirements for imported streaming hardware. Manufacturers must submit to SAR testing and local representative obligations that extend time-to-market by eight to twelve weeks. Domestic Chinese brands with established MIIT relationships are capturing shelf space that foreign competitors forfeit during extended approval periods.
Enterprise procurement teams in the hospitality sector are consolidating vendor relationships around managed device platforms that combine hardware, firmware updates, and content curation into single contracts. Traditional transactional distribution through consumer electronics wholesalers is losing share to vertical specialists offering white-label software integration. This consolidation is most visible in the United States, where major hotel chains are standardizing room entertainment systems across thousands of properties.
Digital Media Adapters Market Segmentation
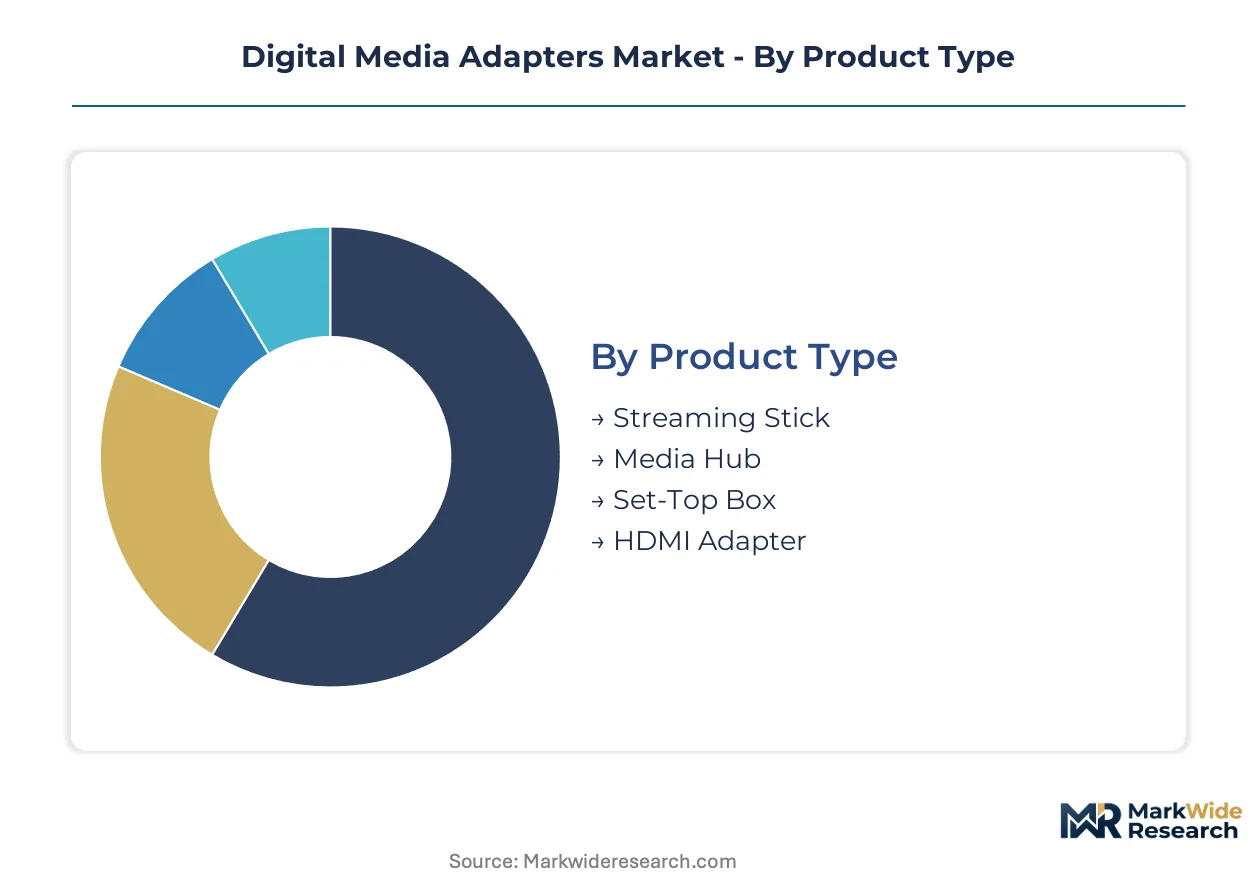
Product architecture and connectivity standards fragment the Digital Media Adapters Market into distinct compliance and certification pathways. Each segment carries unique regulatory burdens that reshape procurement timelines and margin structures for OEMs.
Product Type:
Streaming sticks face streamlined FCC Part 15 certification due to minimal RF emissions, while media hubs trigger more extensive HDMI Forum licensing for HDCP handshake protocols and expanded storage subsystems.
- Streaming Stick:Compact dongle form factor integrating system-on-chip architectures with direct HDMI insertion. Demand concentrates in United States residential cord-cutting households where sub-fifty-dollar pricing enables impulse retail placement. FCC emissions testing completes faster than larger form factors due to reduced thermal load and simplified shielding requirements.
- Media Hub:Expanded chassis housing local storage arrays, additional connectivity ports, and advanced thermal management. Commercial hospitality deployments in United States hotel chains drive procurement volume for managed device platforms requiring firmware update infrastructure. CE marking timelines extend eight to twelve weeks due to Radio Equipment Directive complexity for multi-radio configurations.
- Set-Top Box:Operator-tethered devices with conditional access modules and carrier-specific firmware.
- HDMI Adapter:Signal conversion bridges enabling legacy display compatibility with modern streaming sources.
Streaming sticks sit at the top of the volume ranking, with media hubs climbing the fastest.
Technology:
Silicon procurement costs and thermal design investments stratify sharply across connectivity architectures, with wireless integration demanding more advanced foundry nodes.
- Wireless:Wi-Fi 6E and emerging Wi-Fi 7 silicon enabling multi-gigabit throughput for uncompressed 4K streaming. Residential retrofit applications in China and India concentrate demand as broadband infrastructure expands. MIIT certification mandates in China extend approval timelines for imported hardware lacking domestic representative structures.
- Wired:USB-C and proprietary connector implementations for power and data convergence. Educational institutional procurement favors wired configurations for classroom deployment reliability. Simpler electromagnetic compatibility testing reduces certification costs versus wireless alternatives.
- Bluetooth:Peripheral pairing and audio offload functionality in compact form factors.
- Ethernet:Physical layer stability for commercial and hospitality installations where network consistency outweighs installation flexibility.
Wireless configurations capture the steepest expansion trajectory as Wi-Fi 7 ecosystem convergence accelerates replacement cycles.
End User:
Procurement authority and device management requirements create divergent sales cycles, with enterprise segments demanding multi-year service contracts absent from consumer transactions.
- Residential:Individual household purchases driven by cord-cutting acceleration and legacy television retrofit needs. United States market concentration reflects higher cable subscription abandonment rates. Direct-to-consumer online retail channels dominate with minimal installation support requirements.
- Commercial:Corporate deployment of meeting room casting solutions and digital signage adapters. Extended sales cycles incorporate IT security review and network integration testing. Vertical specialists displace traditional consumer electronics wholesalers through white-label software bundling.
- Educational:K-12 and higher institutional procurement with volume pricing and extended warranty demands.
- Hospitality:Hotel and extended-stay property upgrades requiring remote management and guest content aggregation platforms.
Residential volume leads all end-user categories, though hospitality procurement is expanding most quickly through managed service consolidation.
Distribution Channel:
Channel selection determines margin retention and customer acquisition cost structures, with direct sales capturing premium pricing in enterprise segments.
- Online Retail:E-commerce platforms enabling price transparency and comparison shopping for consumer segments. Amazon and specialized electronics marketplaces dominate United States residential purchasing. Logistics infrastructure requirements favor lightweight streaming stick form factors over heavier media hubs.
- Specialty Stores:Physical retail with assisted selling and immediate product demonstration. India urban centers concentrate foot traffic for first-time streaming adapter purchasers. Staff training investments focus on Wi-Fi setup troubleshooting for less technically proficient buyers.
- Direct Sales:Manufacturer-controlled channels for enterprise and hospitality volume contracts.
- Distributors:Intermediary inventory holding for regional market coverage and smaller retailer supply.
Online retail holds the volume leadership position, while direct sales gains share fastest through enterprise procurement consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen anchors the global manufacturing base for streaming hardware system-on-chip assembly and wireless module integration.
United States
Cord-cutting households in the United States purchased streaming sticks to retrofit legacy televisions as cable subscription abandonment accelerated. FCC Part 15 emissions certification creates compliance barriers that favor established manufacturers with domestic testing infrastructure. Silicon Valley hardware incubators concentrate venture funding for next-generation thermal management solutions in compact form factors.
China
Broadband infrastructure expansion in tier-two cities generated first-time streaming adapter demand among households upgrading from broadcast television. MIIT certification mandates for wireless frequency compliance extend approval timelines for imported hardware lacking domestic representative structures. Shenzhen manufacturing clusters dominate system-on-chip assembly and wireless module integration for export markets.
India
Government-funded fiber deployment and 5G fixed wireless access created first-time streaming households requiring low-cost adapter solutions. TRAI regulations on over-the-top content carriage shape platform availability and hardware bundling arrangements. Bangalore technology corridors concentrate software development for regional content aggregation partnerships.
Germany
Commercial hospitality procurement teams in Germany consolidated vendor relationships around managed device platforms combining hardware and firmware updates. CE marking requirements under the Radio Equipment Directive extend product launch schedules as testing backlogs accumulate at notified bodies. Munich industrial zones concentrate precision manufacturing for premium media hub thermal solutions.
Japan
Residential consumers in Japan replaced aging adapters to unlock Wi-Fi 6E silicon for lower-latency 4K streaming applications. METI efficiency standards for consumer electronics shape power consumption requirements and standby mode regulations. Tokyo metropolitan clusters concentrate semiconductor distribution networks for advanced node procurement.
Digital Media Adapters Market Vendor Landscape
Strategic partnerships dominate the current landscape as OEMs align with content platforms to secure software-hardware integration advantages. The vendor base stratifies across three tiers: platform-integrated technology giants, specialized streaming hardware manufacturers, and contract-assembled white-label suppliers. Premium positioning depends on proprietary silicon control and closed ecosystem management. Competitive moves concentrate on technology licensing for codec decode blocks and geographic expansion into broadband-emerging markets.
Among platform-integrated technology giants, Google LLC and Apple Inc. exemplify divergent ecosystem strategies. Google LLC anchors the open-partnership archetype through Android TV licensing across multiple OEM relationships. Apple Inc. occupies a position within the closed-ecosystem tier through proprietary silicon and vertical control over hardware-software integration. Roku, Inc. sits within the content-aggregation specialist category, representing the retail channel dominance archetype through streaming stick volume placement.
| Leading Market Players |
|---|
| Roku, Inc. |
| Apple Inc. |
| Google LLC |
| Amazon.com, Inc. |
| Samsung Electronics Co., Ltd. |
| NETGEAR Inc. |
| Cisco Systems, Inc. |
| Sony Corporation |
| Western Digital Technologies, Inc. |
| Others |
Supply Flow & Price Mechanics
Captive silicon sourcing from Taiwan-based foundries anchors both cost structures and margin leverage for streaming hardware OEMs. This integration choice concentrates procurement power among vendors with multi-year wafer supply agreements, while forcing price competition onto second-tier assemblers dependent on spot-market chip availability.
Pricing Analysis
Input-cost pass-through from advanced node semiconductor procurement shapes tiered pricing across streaming stick and media hub categories. Three-tier pricing structure across premium, standard, and economy levels separates Roku and Apple positioning from white-label alternatives, with HDMI Forum licensing fees and AV1 codec royalties driving differentiation. Cost compression in the sub-fifty-dollar economy tier is intensifying because MIIT certification delays extend Chinese market entry timelines for import-dependent brands. Hospitality procurement teams exhibit the least price sensitivity due to bundled managed-service contracts, while Indian residential households show maximum elasticity to entry-level sticker prices.
Supply Chain Analysis
Reverse-logistics flows for streaming hardware remain underdeveloped, with end-of-life devices rarely captured for component recovery or refurbishment. Manufacturing concentrates in China, Taiwan, and Vietnam, with Shenzhen clusters handling system-on-chip assembly and Dongguan facilities managing final device integration. Silicon wafers, HDMI controller chips, and Wi-Fi 6E/7 radio modules constitute critical input dependencies. Single-source vulnerability around Taiwan Semiconductor Manufacturing capacity exposes production schedules to regional disruption risks. Distribution runs through Amazon and Walmart e-commerce platforms for residential volume, while direct enterprise contracts bypass wholesale intermediaries for hospitality and commercial segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in digital media adapters rests on silicon efficiency gains compressing thermal solution costs and enabling premium-tier wireless-only product positioning. System-on-chip integration shifts value capture toward software-aggregation layers.
For Market Incumbents: Lock in multi-year foundry allocation for Wi-Fi 7 silicon to secure supply priority during transition cycles. Deepen Android TV platform partnerships to defend against smart TV substitution pressure. Accelerate FCC pre-certification testing infrastructure investments to extend retailer shelf-space advantages over import-dependent challengers.
For New Entrants and Emerging Players: TRAI regulations in India open a window for low-cost adapter solutions bundling with regional content platforms. Target government-funded fiber deployment zones for first-mover household penetration. Pursue white-label hospitality contracts through vertical specialists displacing traditional electronics wholesalers.
For Investors and Strategic Acquirers: Roll-up economics work for managed-device platform specialists because enterprise procurement consolidation favors single-vendor contracts spanning hardware, firmware, and content curation. Focus on targets with established MIIT relationships in China and FCC testing infrastructure in the United States. Monitor Wi-Fi 7 ecosystem adoption rates as inflection indicator for replacement cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Platform Integration | Unified SoC architectures reduce PCB area and thermal costs for compact streaming stick form factors. |
| Regulatory Pre-Certification Investment | FCC Part 15 and MIIT testing infrastructure accelerates time-to-market versus import-dependent competitors. |
| Hospitality Managed Service Bundling | White-label software integration captures enterprise procurement consolidation away from consumer wholesalers. |
| Wireless-Only Product Category Development | Wi-Fi 7 multi-gigabit throughput eliminates Ethernet dependency for premium residential positioning. |
| Regional Content Platform Partnership | India and China licensing agreements differentiate hardware through localized streaming aggregation. |
Methodological Framework
Bottom-up residential and commercial deployment modeling reconciled against top-down semiconductor procurement tracking forms the analytical core. Primary interviews with streaming hardware OEM procurement directors, FCC certification consultants, hospitality technology managers, and retail category buyers combined with secondary validation against SEC filings, customs import records, and FCC equipment authorization databases. Triangulation across supply-side foundry capacity disclosures and demand-side broadband infrastructure deployment timelines anchored volume estimates.
Input-output matrices mapped system-on-chip unit economics against end-user price elasticity across product tiers. Segmentation dimensions modeled include product architecture, connectivity standard, end-user vertical, and distribution channel, with regional regulatory clusters treated as separate forecast strata. CAGRs derived from replacement cycle analysis and broadband penetration trajectories across the analysis window. Wi-Fi protocol adoption curves and codec licensing cost structures served as hardware-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under MIIT certification timeline disruptions and foundry capacity allocation shocks. Forecasts reflect assumptions around cord-cutting acceleration rates and smart TV substitution thresholds. Practitioners should monitor FCC spectrum reallocation proceedings and Wi-Fi 7 silicon yield rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Media and Entertainment Technologies
Global Virtual Event Platform Market
Digital Media and Entertainment Technologies
Digital Scent Technology Market
Digital Media and Entertainment Technologies
Europe Digital Scent Technology Market
Digital Media and Entertainment Technologies
North America Digital Scent Technology Market
Digital Media and Entertainment Technologies
United States Digital OOH Advertising Market
Digital Media and Entertainment Technologies
Video Switchers Market
Digital Media and Entertainment Technologies
Digital OOH Market
Digital Media and Entertainment Technologies
VR Content Creation Services Market
Digital Media and Entertainment Technologies
Healthcare Gamification Market