
 Kenya ICT Market | 2026-2036
Kenya ICT Market Size, Share, and Industry Trends Forecast 2026-2036
Kenya ICT Market Insights
Modular service bundling is broadening buyer choice across Kenya's ICT landscape as enterprises shift from discrete hardware purchases to integrated cloud-software-service packages. Safaricom PLC leverages its M-Pesa financial rails to anchor enterprise digital transformation contracts. Airtel Networks Kenya Limited competes on aggressive data pricing for SME connectivity. Liquid Intelligent Technologies Kenya Limited extends its fiber backbone dominance into cloud and cybersecurity resale.
Information and communications technology in Kenya encompasses hardware infrastructure, software platforms, managed services, and cloud solutions delivered through terrestrial fiber, mobile networks, and submarine cable systems operating at latency thresholds below 150 milliseconds to European and Asian exchanges. Its primary commercial purpose is enabling transaction processing, data analytics, and remote collaboration for enterprises, government agencies, and educational institutions. Hardware procurement still occupies the largest revenue pool among product types, though cloud solutions represent the fastest-expanding margin segment as hyperscaler partnerships deepen. Government and educational institutions constitute the most price-sensitive customer type, while corporates drive premium cybersecurity and artificial intelligence adoption. Deployment mode preferences are shifting from on-premises installations toward hybrid architectures that retain sensitive data locally while bursting compute workloads to cloud-based platforms.
The Communications Authority of Kenya enforces spectrum allocation and quality-of-service benchmarks that directly shape operator capital expenditure cycles and infrastructure rollout timelines. The Central Bank of Kenya's digital lending regulations and data protection standards compel financial services providers to invest in compliant cybersecurity and cloud storage architectures. Stakeholders must monitor regulatory harmonization between national data localization requirements and cross-border cloud service agreements to anticipate compliance cost trajectories and partnership restructuring needs.
Market Dynamics
Cloud migration mandates from the Central Bank of Kenya are compressing procurement cycles as financial institutions abandon legacy data center architectures for compliant hybrid deployments.
Growth Catalysts
- Data Protection Act compliance deadlines:Financial services providers must upgrade encryption and audit trails, driving cybersecurity services procurement.
- Konza Technopolis infrastructure buildout:Government-backed fiber and power investments are attracting hyperscaler edge node deployments.
- Submarine cable capacity expansion:Mombasa landing stations for new fiber pairs are lowering international bandwidth costs for enterprise buyers.
Market Restraints
- Power reliability deficits:Diesel generator dependency inflates total cost of ownership for data center operators outside Nairobi.
- Import duty structures:East African Community tariffs on networking hardware compress reseller margins.
- Spectrum auction delays:Communications Authority of Kenya licensing bottlenecks constrain 5G network rollout timelines.
Strategic Opportunities
- County-level e-government platforms:Devolution mandates require 47 county governments to digitize revenue collection and land registries.
- AgriTech sensor networks:Tea and coffee cooperatives seek IoT soil monitoring tied to mobile money payment rails.
- Carbon credit verification infrastructure:Voluntary carbon markets demand blockchain-anchored MRV (measurement, reporting, verification) systems.
Industry Challenges
- Cloud architecture certification gaps:Shortage of AWS, Azure, and Google Cloud certified engineers delays enterprise migration timelines.
- Legacy core banking integration:Mainframe-era transaction systems resist API-native connectivity without expensive middleware layers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kenya ICT Market |
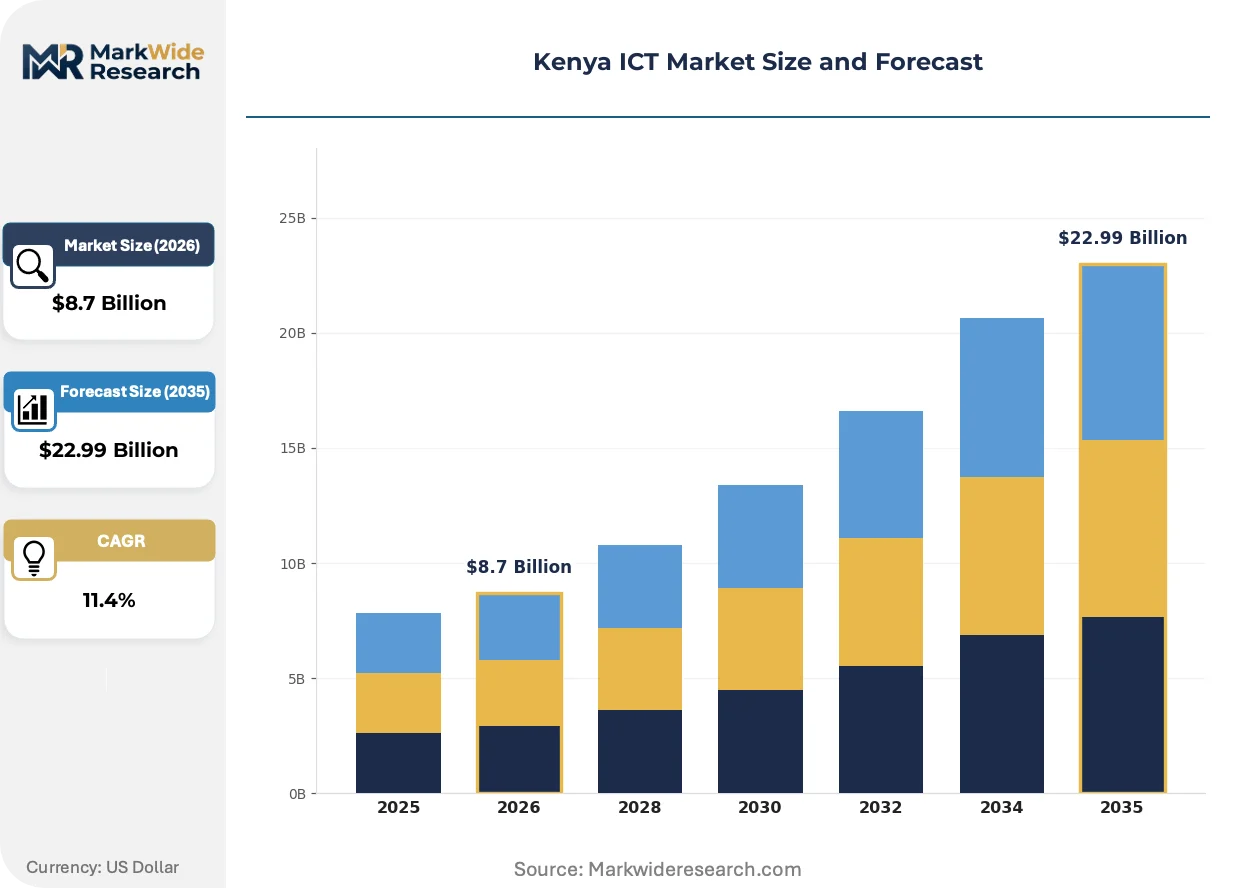
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hardware, Software, Services, Cloud Solutions Customer Type: Corporates, SMEs, Government, Educational Institutions Technology: IoT, Big Data, Artificial Intelligence, Cybersecurity Deployment Mode: On-Premises, Cloud-Based, Hybrid, Virtual |
| Companies Covered | Safaricom PLC, Airtel Networks Kenya Limited, Telkom Kenya Limited, Liquid Intelligent Technologies Kenya Limited, Huawei Technologies Co., Ltd., Microsoft Corporation, Oracle Corporation, IBM, SEACOM Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kenya ICT Market Trends and Innovations
Artificial intelligence deployment patterns are bifurcating between centralized model training and edge inference workloads, reshaping data center design priorities across Kenyan enterprise buyers.
Machine learning operations (MLOps) tooling is automating model lifecycle management from experimentation through production monitoring. Tier-one banks and mobile network operators are adopting these platforms to compress fraud detection deployment cycles from months to weeks. The shift is automating compliance documentation for Central Bank of Kenya algorithmic decision audits.
The Data Protection Act enforcement guidelines from the Office of the Data Protection Commissioner are mandating privacy impact assessments before cloud procurement. Financial institutions now embed legal review into technical evaluation workflows. This regulatory friction is lengthening vendor selection cycles but improving contract terms for data residency guarantees.
Enterprise buyers are consolidating vendor relationships around integrated platform contracts rather than point-solution procurement. Manufacturing and logistics firms now prioritize single-provider bundles spanning connectivity, cloud compute, and endpoint security. This preference shift is most visible in Nairobi's industrial zones where procurement teams lack specialized technical evaluation capacity.
Kenya ICT Market Segmentation
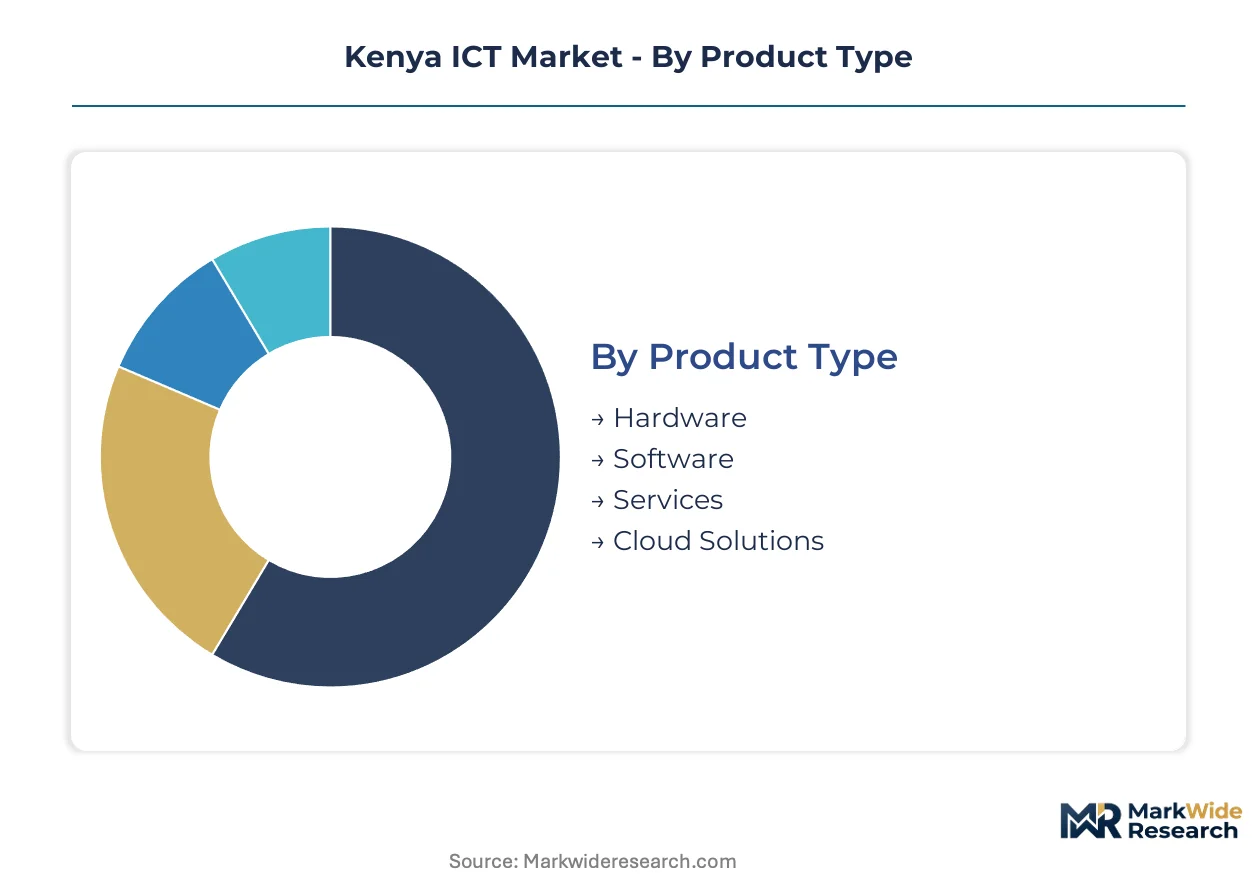
Segmentation clarity shapes procurement strategy for Kenyan enterprises navigating regulatory compliance and infrastructure constraints. Buyers optimize spend across product types and deployment modes while balancing data sovereignty mandates against cloud economics.
Product Type:
Hardware components function as standalone infrastructure investments requiring physical installation and maintenance, while software and cloud solutions embed into broader service ecosystems with recurring revenue structures.
- Hardware:Servers, networking equipment, and endpoint devices constitute the foundational layer of enterprise ICT estates. Procurement concentrates among Nairobi-based financial institutions and Konza Technopolis data center operators facing Central Bank of Kenya compliance deadlines for encrypted storage infrastructure.
- Software:Enterprise applications span ERP, CRM, and vertical-specific platforms delivered through perpetual licenses or subscription models. Demand clusters in Mombasa logistics corridors where port operators and shipping agencies require customs integration and vessel tracking systems.
- Services:Managed IT, system integration, and technical support engagements address capability gaps in enterprise IT departments. County governments across Kenya's 47 devolved units procure these services for revenue collection platform deployment.
- Cloud Solutions:IaaS, PaaS, and SaaS offerings from hyperscaler partners and local resellers enable workload migration without capital-intensive infrastructure builds. SME adoption accelerates in manufacturing zones seeking burst compute for seasonal demand spikes.
Volume placements concentrate in Hardware; the faster expansion belongs to Cloud Solutions.
Customer Type:
Procurement sophistication varies sharply across buyer categories, with corporates demanding enterprise-grade SLAs while government entities prioritize lowest-compliant-bid mechanisms.
- Corporates:Large enterprises across banking, telecommunications, and manufacturing sectors drive premium cybersecurity and AI solution adoption. Tier-one banks in Nairobi allocate substantial ICT budgets to MLOps platforms and fraud detection infrastructure.
- SMEs:Small and medium enterprises favor bundled connectivity and cloud packages with predictable monthly expenditures. Airtel Networks Kenya Limited and Safaricom PLC compete aggressively for this segment through simplified procurement portals.
- Government:National and county government entities operate under Public Procurement and Asset Disposal Act frameworks with extended evaluation cycles. The 47 county governments represent a distributed demand base for land registry digitization and revenue automation.
- Educational Institutions:Universities and technical colleges prioritize cost optimization in connectivity and learning management systems. Institutions in secondary cities face bandwidth constraints that shape hybrid deployment preferences.
Revenue concentration sits with Corporates; Educational Institutions expand most quickly as tertiary enrollment drives campus infrastructure modernization.
Technology:
Technology adoption patterns reflect infrastructure readiness, with IoT deployments constrained by cellular coverage gaps outside urban corridors and AI workloads requiring specialized compute access.
- IoT:Sensor networks and connected device deployments span agriculture, logistics, and utilities monitoring. Tea and coffee cooperatives in the Rift Valley deploy soil moisture and weather monitoring tied to M-Pesa payment rails for input financing.
- Big Data:Data lake architectures and analytics platforms enable transaction pattern recognition and predictive modeling. Mobile network operators leverage subscriber behavior datasets for churn prediction and service personalization.
- Artificial Intelligence:Machine learning model development and inference workloads bifurcate between centralized training and edge deployment. Tier-one banks adopt MLOps tooling to compress fraud detection deployment cycles under Central Bank of Kenya audit requirements.
- Cybersecurity:Threat detection, identity management, and encryption services address Data Protection Act compliance mandates. Financial services providers upgrade audit trails and breach notification systems ahead of regulatory enforcement milestones.
Investment intensity clusters in Cybersecurity; Artificial Intelligence claims the steepest expansion trajectory as model deployment tooling matures.
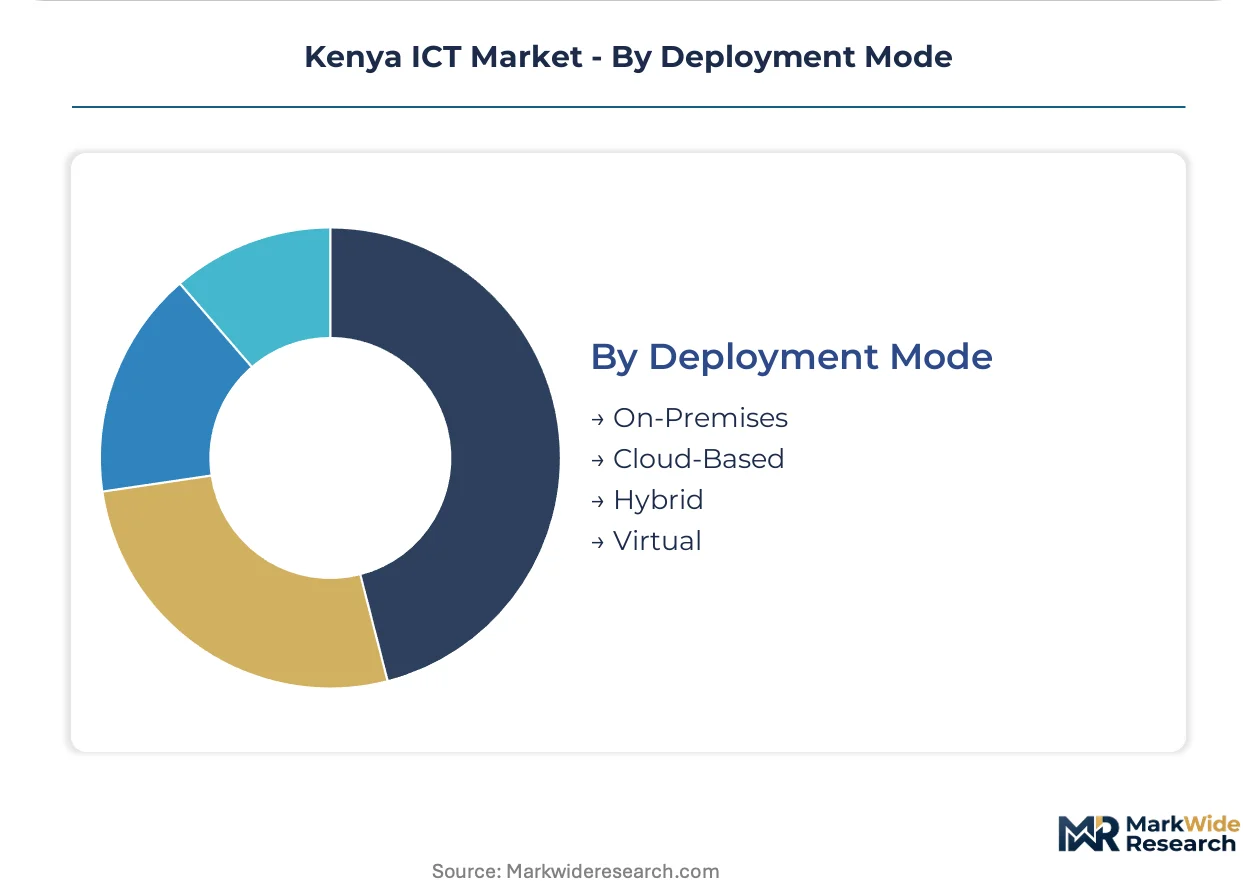
Deployment Mode:
Architecture decisions balance data sovereignty requirements against operational agility, with sensitive workloads retained locally and variable compute burst to cloud platforms.
- On-Premises:Legacy data center installations retain core banking systems and citizen biometric databases under direct institutional control. Mainframe-era transaction systems resist API-native connectivity without expensive middleware layers.
- Cloud-Based:Full public cloud deployment suits development environments and non-sensitive collaboration workloads. Startups and digital-native enterprises in Nairobi's tech hubs favor this model for speed-to-market.
- Hybrid:Mixed architectures retain sensitive data locally while bursting compute workloads to cloud platforms. Financial institutions adopt this model to satisfy Central Bank of Kenya data localization requirements while accessing hyperscaler AI services.
- Virtual:Desktop and infrastructure virtualization enables remote workforce support and disaster recovery capabilities. County government offices deploy virtual desktop infrastructure to standardize endpoint management across dispersed locations.
Installed base dominance belongs to On-Premises; Hybrid architectures gain share fastest as compliance-conscious institutions navigate sovereignty and scalability tradeoffs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in Nairobi's Konza Technopolis and Mombasa's cable landing zones, while consumption spreads across 47 county governments and enterprise clusters. The Communications Authority of Kenya shapes rollout timelines through spectrum allocation decisions.
Nairobi Metropolitan Area
Corporate headquarters and financial institutions drive premium cybersecurity and cloud procurement. The Central Bank of Kenya's digital lending regulations compress migration timelines for tier-one banks. Konza Technopolis anchors hyperscaler edge node deployments through government-backed fiber investments.
Mombasa and Coastal Region
Submarine cable landing stations for SEACOM and other fiber pairs lower international bandwidth costs. Port operators and shipping agencies demand customs integration and vessel tracking systems. The Kenya Ports Authority digitization mandates accelerate logistics software procurement cycles.
Rift Valley Region
Tea and coffee cooperatives deploy IoT soil monitoring tied to mobile money payment rails for input financing. Agricultural extension services require last-mile connectivity for real-time price dissemination. Nakuru and Eldoret host growing SME manufacturing zones seeking burst compute capacity.
Western Kenya
Sugar processing and grain milling enterprises adopt basic ERP and inventory management platforms. County governments in Kisumu and surrounding areas digitize land registries and revenue collection under devolution mandates. Educational institutions drive campus connectivity modernization as tertiary enrollment expands.
Northern and Arid Counties
Mobile network operators extend coverage for pastoralist livestock insurance and mobile money services. Off-grid solar-powered base stations address power reliability deficits outside urban corridors. The national broadband strategy targets universal access through satellite and wireless backhaul combinations.
Kenya ICT Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Kenya's ICT landscape. Mobile network operators leverage existing subscriber bases to cross-sell enterprise solutions. Hyperscaler partnerships and local system integrators form two additional strategic archetypes. Capacity expansion in fiber backbone and cloud node deployment represents the dominant competitive moves, alongside strategic partnerships for cybersecurity service bundling.
Within the mobile-centric tier, Safaricom PLC and Airtel Networks Kenya Limited occupy positions as connectivity anchors for SME and consumer segments. Liquid Intelligent Technologies Kenya Limited exemplifies the infrastructure-specialist archetype through fiber backbone extension into adjacent cloud and security services. Among international technology providers, Microsoft Corporation and Oracle Corporation represent the hyperscaler and enterprise software vectors respectively.
| Leading Market Players |
|---|
| Safaricom PLC |
| Airtel Networks Kenya Limited |
| Telkom Kenya Limited |
| Liquid Intelligent Technologies Kenya Limited |
| Huawei Technologies Co., Ltd. |
| Microsoft Corporation |
| Oracle Corporation |
| IBM |
| SEACOM Ltd. |
| Others |
Pricing and Supply Chain Analysis
County government procurement clusters across Kenya's 47 devolved units anchor contract-based pricing for integrated ICT bundles, with Public Procurement and Asset Disposal Act frameworks mandating lowest-compliant-bid mechanisms that compress reseller margins on hardware imports.
Pricing Analysis
Margin tightening in enterprise cloud subscriptions reflects hyperscaler partner fee structures and local data residency compliance costs. Three-tier pricing structure across premium, standard, and economy levels separates tier-one banks with MLOps budgets from SMEs seeking burst compute. Cost-down pressure on hardware resellers accelerates because East African Community tariffs on networking equipment inflate landed costs. Educational institutions exhibit highest price sensitivity; corporates absorb premiums for cybersecurity certification tiers.
Supply Chain Analysis
Dual-sourcing requirements from tier-one banks mandate qualified reseller relationships with both hyperscaler direct channels and local system integrators for redundancy. Hardware supply concentrates in China, Taiwan, and South Korea for servers and networking equipment. Component dependencies span semiconductor chips, lithium-ion backup batteries, and fiber-optic cable sheathing. Single-source vulnerability persists for specialized encryption hardware subject to export control classifications. Distribution runs through Nairobi-based value-added resellers with Mombasa port clearance capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Kenya's ICT market sits in a cloud-transition phase as hybrid architectures displace on-premises data centers under Central Bank of Kenya compliance mandates.
For Market Incumbents: To counter hyperscaler direct-to-enterprise bypass threats, Safaricom PLC and Liquid Intelligent Technologies Kenya Limited should deepen fiber-cloud integration bundles and secure tier-one bank MLOps platform certifications. Channel control through exclusive county government system integration contracts provides defensive moats against price-aggressive entrants. For New Entrants and Emerging Players: The Data Protection Act enforcement guidelines from the Office of the Data Protection Commissioner in Kenya open a window for specialized privacy impact assessment consultancies and encrypted storage appliance resellers. County-level e-government digitization mandates represent the most penetrable segment, with land registry automation projects lacking qualified bidders. A go-to-market angle anchored in Kisumu and Eldoret manufacturing zones bypasses Nairobi incumbent saturation. For Investors and Strategic Acquirers: Distressed-cycle entries favor cloud-reseller specialists with Central Bank of Kenya compliance credentials in Kenya's secondary cities. Long-term viability hinges on hyperscaler partnership durability and fiber backbone access rights. The signal to watch is Communications Authority of Kenya spectrum auction timing, which would unlock 5G infrastructure capex cycles and reshape mobile edge compute economics.| Strategic Initiative | Industry Significance |
|---|---|
| Hyperscaler Edge Node Deployment | Konza Technopolis fiber investments attract AWS, Azure, and Google Cloud localized compute capacity. |
| County Government System Integration | Devolution mandates create recurring revenue streams for land registry and revenue automation platforms. |
| Cybersecurity Service Bundling | Data Protection Act compliance deadlines drive demand for managed encryption and audit trail services. |
| AgriTech IoT Network Expansion | Tea and coffee cooperative sensor deployments tie soil monitoring to M-Pesa input financing rails. |
| Submarine Cable Capacity Addition | Mombasa landing station investments lower international bandwidth costs for enterprise buyers. |
Research Methodology
Document review covered Communications Authority of Kenya spectrum allocation records, Central Bank of Kenya digital lending circulars, and county government procurement disclosures, complemented by interviews with chief technology officers at tier-one banks, IT procurement officers at manufacturing enterprises, hyperscaler partner program managers, and system integration specialists at Nairobi-based resellers. Secondary validation drew from SEC filings of listed technology providers, submarine cable operator capacity announcements, and East African Community customs tariff schedules. Bottom-up county-level demand aggregation and top-down ICT spend-to-GDP ratio analysis provided triangulation.
Cross-referencing historical procurement cycle patterns against expert panel inputs on regulatory compliance timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include deployment mode architecture preferences, customer type procurement sophistication tiers, product type margin structures, and technology adoption readiness by regional infrastructure maturity. CAGRs were derived from elasticity-adjusted spend trajectories. Industry-specific forecast inputs encompass Central Bank of Kenya audit requirement rollout schedules and Konza Technopolis infrastructure buildout milestones.
The model assumes a particular technology adoption path; alternative pathways for edge AI inference deployment would alter the outlook if hyperscaler node placement accelerates beyond government-backed fiber timelines. Forecasts reflect documented assumptions on regulatory enforcement intensity and infrastructure completion schedules. Deviation in Communications Authority of Kenya licensing velocity or East African Community tariff reclassification would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Europe Electronic Contract Manufacturing and Design Services Market
Digital Solutions
Weather Forecasting Systems and Solutions Market
Digital Solutions
Boat Navigation Software Market
Digital Solutions
Global Personalization Engines Market
Digital Solutions
Ad Network Software Market
Digital Solutions
Key Management As a Service (Kmaas) Market
Digital Solutions
Europe ICT Market
Digital Solutions
Global Drilling Data Management Systems Market
Digital Solutions
Europe Digital Marketing Software Market
Digital Solutions
Passenger Ticket Vending Machine Market
Digital Solutions
Global Asset Tracking and Inventory Management Solutions Market
Digital Solutions
POS Restaurant Management System Market
Digital Solutions
Global Data Virtualization Market
Digital Solutions
Germany Content Services Platform Market
Digital Solutions
Smart and Connected Offices Market
Digital Solutions
Cloud Service Assurance Market