
 Home Blood Testing Devices Market | 2026-2036
Home Blood Testing Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Home Blood Testing Devices Market Foresight
FDA 510(k) premarket notification volume for home-use blood analyzers is restructuring the cost-of-entry calculus for device startups and mid-tier manufacturers alike. Abbott Laboratories leverages its vertically integrated strip production to sustain price competitiveness across retail pharmacy channels. Roche Diagnostics anchors its position through specialized coagulation testing algorithms that integrate with hospital electronic health records. Siemens Healthineers competes by dominating the hemoglobin meter segment in European and Asian regulatory jurisdictions.
Home blood testing devices are portable diagnostic instruments that analyze capillary blood samples through electrochemical or optical biosensor reactions, typically requiring sample volumes between 0.3 and 1.1 microliters and delivering results within 5 to 60 seconds for glucose or coagulation parameters. Their primary commercial purpose is to enable non-clinical users to monitor chronic conditions, medication efficacy, or wellness biomarkers without laboratory infrastructure. Glucose meters occupy the largest installed base and margin pool across retail channels, while connected devices with Bluetooth connectivity represent the fastest-expanding technological feature category as remote patient monitoring reimbursement codes expand. Disposable test strips generate recurring revenue streams that exceed hardware margins by substantial multiples, concentrating manufacturer R&D investment on strip chemistry durability and lot-to-lot consistency.
FDA clearance requirements, EU MDR classification for self-testing devices, and ISO 15197 accuracy standards collectively shape product development timelines, clinical validation costs, and geographic market access sequencing for manufacturers. HIPAA compliance obligations for data-transmitting devices add architectural constraints to mobile app integration and cloud storage design decisions. Stakeholders must monitor evolving Medicare coverage determinations for remote monitoring codes and corresponding state-level telehealth parity laws that dictate reimbursement accessibility for connected home testing platforms.
Market Dynamics
Connected glucose and coagulation monitors are compressing the traditional clinical-laboratory value chain by embedding cellular and Bluetooth transmission directly into handheld form factors, bypassing the need for intermediary data collection infrastructure.
Growth Catalysts
- Medicare reimbursement expansion:Remote patient monitoring codes now cover connected home testing devices in the United States, accelerating household penetration among chronic disease populations.
- ISO 15197 accuracy mandates:Tightening international standards for glucose meter precision are forcing quality upgrades that improve clinical acceptance and expand prescriber willingness to recommend home monitoring.
- Capillary sampling miniaturization:Electrochemical biosensor chemistry advances have reduced required blood volumes below 0.5 microliters, removing pain barriers for pediatric and elderly users.
Market Restraints
- Precious metal input volatility:Platinum and palladium price swings in electrochemical sensor electrodes compress hardware margins and complicate long-term strip pricing contracts.
- FDA 510(k) backlog concentration:Premarket notification review timelines for novel coagulation algorithms create regulatory bottlenecks that favor established filers with dedicated regulatory affairs teams.
- Optical reader substitution threat:Smartphone camera-based colorimetric assays for hemoglobin and cholesterol are capturing wellness-oriented consumers who reject dedicated hardware purchases.
Strategic Opportunities
- Indian pharmacy chain integration:Organized retail pharmacy networks in Tier-2 and Tier-3 cities present first-mover opportunities for localized glucose meter distribution at price points below multinational benchmarks.
- EU MDR self-testing classification:The European Medical Device Regulation's streamlined pathway for lay-user devices creates faster market access for connected monitoring platforms with embedded clinical decision support.
- AI-enabled pattern recognition:Machine learning integration with continuous glucose data streams is automating hypoglycemic event prediction, opening subscription revenue models beyond hardware and consumables.
Industry Challenges
- HIPAA-compliant cloud architecture:Real-time data transmission from home devices to provider EHR systems requires specialized health information security expertise that strains mid-tier engineering teams.
- Lot-to-lot chemistry consistency:Maintaining electrochemical sensor reproducibility across millions of test strips demands statistical process control capabilities that smaller manufacturers struggle to scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Home Blood Testing Devices Market |
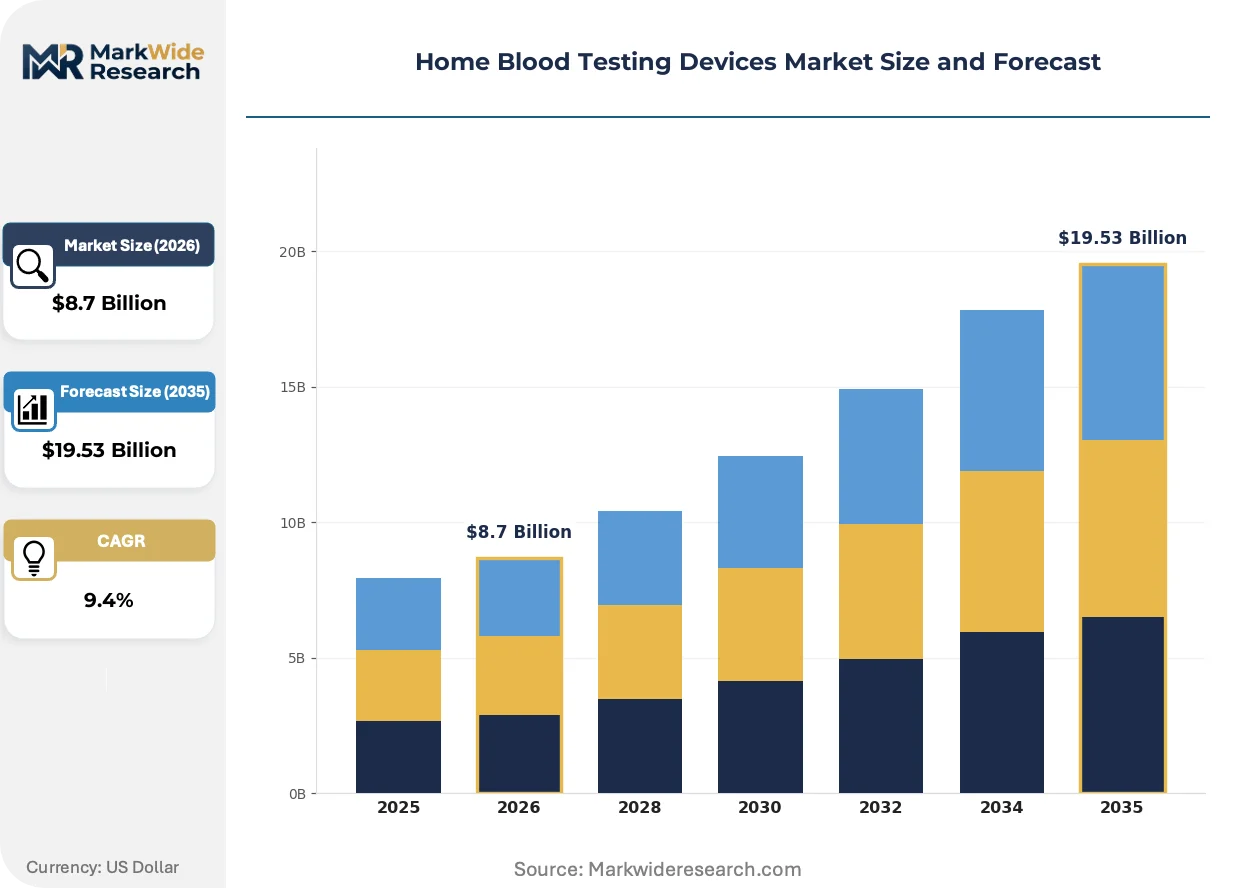
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glucose Meters, Cholesterol Meters, Hemoglobin Meters, Coagulation Test Devices Delivery Mode: Self-Monitoring, Remote Monitoring, Connected Devices, Lab Integration End User: Patients, Healthcare Providers, Pharmacies, Wellness Centers Technological Feature: Bluetooth Connectivity, Mobile App Integration, Disposable Test Strips, Data Analysis Software |
| Companies Covered | Abbott Laboratories, Roche Diagnostics, Siemens Healthineers, Dexcom, Becton Dickinson and Company, ACON Laboratories, Quidel Corporation, Everlywell, PHC Holdings Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Home Blood Testing Devices Market Shifts & Advancements
Microfluidics, artificial intelligence, and regulatory harmonization are converging to transform home blood testing from episodic measurement toward continuous, predictive health monitoring without laboratory intermediation.
Lab-on-a-chip microfluidic cartridges are automating multi-analyte panels from single capillary samples, enabling simultaneous glucose, ketone, and hematocrit quantification in devices smaller than conventional glucose meters. Chronic disease management programs at integrated health systems are adopting these platforms to reduce outpatient lab visit frequency. The technology is automating the consolidation of previously separate testing workflows into unified home monitoring experiences.
EU MDR Article 10 post-market surveillance requirements are mandating systematic real-world performance data collection from self-testing devices, forcing manufacturers to build cloud infrastructure for ongoing clinical evidence generation. This obligation is compressing time-to-market for new entrants lacking established quality management systems. Hemoglobin and coagulation monitoring segments face the steepest compliance cost escalation as notified bodies apply stricter scrutiny to anticoagulation patient safety.
Direct-to-consumer subscription models are displacing pharmacy-centric strip purchasing for connected device users, with automated reorder algorithms triggered by actual usage patterns rather than calendar-based refills. This shift is fragmenting the traditional retail channel dominance of glucose meter brands. The United States exhibits the most pronounced channel migration as telehealth-integrated remote monitoring platforms bundle hardware, consumables, and clinical oversight into single monthly fees.
Home Blood Testing Devices Market Segmentation
Home blood testing devices fragment across four distinct dimensions that govern pricing architecture, regulatory pathways, and channel economics. Product type determines the underlying biosensor chemistry and consumable revenue model. Delivery mode shapes data infrastructure requirements and reimbursement eligibility. End user dictates sales motion and clinical validation burden. Technological feature drives upgrade cycles and subscription revenue potential.
Product Type:
Replacement cycles vary sharply across product categories, with glucose meters refreshing every 18-24 months while specialized coagulation devices extend toward 36-month horizons.
- Glucose Meters:Electrochemical biosensor platforms quantifying blood glucose through enzymatic reactions with glucose oxidase or dehydrogenase chemistry. Demand concentrates among Type 1 and Type 2 diabetes patients in the United States, where Medicare remote monitoring reimbursement compresses out-of-pocket costs below $15 monthly for connected models.
- Coagulation Test Devices:Prothrombin time and INR measurement systems employing optical or electromechanical clot detection for anticoagulation therapy management. Patient self-testing protocols for warfarin therapy are expanding fastest in Germany and the United Kingdom under streamlined EU MDR self-testing classifications.
- Cholesterol Meters:Reflectance photometry or electrochemical strips measuring total cholesterol, HDL, and triglycerides from capillary samples. Lipid panel monitoring drives pharmacy channel placements in India and Brazil.
- Hemoglobin Meters:Optical density readers for point-of-care hemoglobin quantification, deployed in anemia screening programs and surgical pre-assessment workflows. Siemens Healthineers dominates European and Asian regulatory jurisdictions for this segment.
Volume placements concentrate in glucose meters; the faster expansion belongs to coagulation test devices.
Delivery Mode:
Cost tier stratification separates premium connected platforms from economy self-monitoring devices, with remote monitoring bundles commanding 3-4x hardware-plus-service annual revenue.
- Self-Monitoring:Standalone devices without data transmission, requiring manual log-keeping for clinical review. Lowest price tier sustains emerging market penetration in Tier-2 and Tier-3 Indian cities.
- Connected Devices:Bluetooth or cellular-enabled meters transmitting results to cloud platforms and provider dashboards. United States reimbursement codes now cover cellular transmission fees, accelerating household penetration among chronic disease populations.
- Remote Monitoring:Comprehensive platforms bundling hardware, consumables, clinical oversight, and automated reorder algorithms into monthly subscriptions. Fastest-expanding delivery mode as telehealth-integrated programs displace pharmacy-centric strip purchasing.
- Lab Integration:Devices designed for seamless data export to hospital laboratory information systems and electronic health records. Roche Diagnostics anchors this segment through specialized coagulation testing algorithms.
Revenue per user peaks with remote monitoring; connected devices gain share fastest as reimbursement frameworks mature.
End User:
Application focus shifts diagnostic accuracy requirements, with healthcare providers demanding ISO 15197-tightened precision while wellness centers prioritize ease-of-use and multi-analyte flexibility.
- Patients:Individual chronic disease sufferers and wellness-conscious consumers purchasing through retail pharmacy or direct-to-consumer channels. Pain sensitivity drives demand for sub-0.5 microliter sample volumes among pediatric and elderly users.
- Healthcare Providers:Physician practices and integrated health systems deploying devices for chronic disease management programs. Clinical acceptance hinges on EHR integration and HIPAA-compliant cloud architecture.
- Pharmacies:Retail and hospital pharmacy chains stocking devices for over-the-counter sale and prescription fulfillment. Abbott Laboratories leverages vertically integrated strip production to sustain price competitiveness across this channel.
- Wellness Centers:Corporate wellness programs, fitness facilities, and preventive health clinics conducting biometric screenings. Smartphone camera-based colorimetric assays threaten dedicated hardware purchases in this segment.
Patient volume dominates unit shipments; healthcare providers drive the steepest average selling price expansion.
Technological Feature:
Maturity gradients separate established consumable-dependent strips from emerging software-centric revenue models, with data analysis platforms capturing recurring subscription economics.
- Disposable Test Strips:Single-use electrochemical or optical biosensors generating recurring revenue streams that exceed hardware margins by substantial multiples. Lot-to-lot chemistry consistency demands statistical process control capabilities that strain smaller manufacturers.
- Bluetooth Connectivity:Wireless data transmission enabling smartphone pairing and cloud upload without cellular subscription costs. Fastest-adopted technological feature as remote patient monitoring reimbursement codes expand.
- Mobile App Integration:iOS and Android applications providing trend visualization, medication reminders, and caregiver alerts. HIPAA compliance obligations add architectural constraints to health information security design.
- Data Analysis Software:AI-enabled pattern recognition platforms automating hypoglycemic event prediction and personalized dosing recommendations. Machine learning integration opens subscription revenue models beyond hardware and consumables.
Disposable test strips anchor current revenue; data analysis software represents the fastest-climbing margin contributor.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States households account for the steepest demand concentration in connected monitoring platforms, with Medicare reimbursement codes compressing out-of-pocket costs below fifteen dollars monthly for cellular-enabled glucose meters. Pharmacy channel partnerships and telehealth-integrated remote monitoring programs accelerate household penetration among chronic disease populations.
United States
FDA 510(k) premarket notification volume for home-use blood analyzers restructures cost-of-entry calculus for device startups and mid-tier manufacturers. Medicare remote patient monitoring reimbursement codes now cover connected home testing devices, accelerating household penetration. Pharmacy channel partnerships in metropolitan clusters concentrate device distribution through retail chains.
Germany
Patient self-testing protocols for warfarin therapy expand fastest under streamlined EU MDR self-testing classifications for lay-user devices. The national pharmaceutical regulator applies stricter scrutiny to anticoagulation patient safety, elevating compliance costs. Industrial concentration in Baden-Württemberg hosts specialized coagulation testing algorithm development.
India
Organized retail pharmacy networks in Tier-2 and Tier-3 cities present first-mover opportunities for localized glucose meter distribution at price points below multinational benchmarks. The Central Drugs Standard Control Organization regulates self-testing device imports and domestic manufacturing. Maharashtra and Gujarat clusters concentrate contract manufacturing for electrochemical biosensor platforms.
Japan
Pharmaceutical and Medical Devices Agency clearance pathways for over-the-counter glucose assays compress time-to-market for new entrants with established quality management systems. METI industrial policy supports connected device development for aging population chronic disease management. Tokyo-Osaka corridor concentrates R&D investment in capillary sampling miniaturization technologies.
United Kingdom
National Health Service chronic disease management programs adopt lab-on-a-chip microfluidic platforms to reduce outpatient lab visit frequency. Medicines and Healthcare products Regulatory Agency aligns with EU MDR post-market surveillance requirements for systematic real-world performance data collection. Greater London anchors telehealth-integrated remote monitoring platform deployment.
Home Blood Testing Devices Market Competitive Landscape
United States producers anchor one tier; European specialists hold algorithm-intensive coagulation and hemoglobin segments. The vendor base stratifies across three tiers: multinational conglomerates with vertically integrated strip production, mid-tier manufacturers competing on price in emerging markets, and digital-native direct-to-consumer platforms. Three strategic archetypes dominate: hardware-plus-consumables incumbents, connected platform integrators, and subscription-based remote monitoring services. Competitive moves concentrate on strategic partnerships with pharmacy chains and portfolio diversification into multi-analyte microfluidic cartridges.
Within the multinational conglomerate tier, Abbott Laboratories and Roche Diagnostics exemplify divergent defensive strategies. Abbott leverages captive supply of test strip chemistry to sustain price competitiveness across retail pharmacy channels. Roche anchors its position through specialized coagulation testing algorithms that integrate with hospital electronic health records. Siemens Healthineers occupies a distinct position in hemoglobin meter segments across European and Asian regulatory jurisdictions.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Roche Diagnostics |
| Siemens Healthineers |
| Dexcom |
| Becton Dickinson and Company |
| ACON Laboratories |
| Quidel Corporation |
| Everlywell |
| PHC Holdings Corporation |
| Others |
Supply & Pricing Matrix
Capillary sampling miniaturization below 0.5 microliters compresses manufacturing cost curves while concentrating electrochemical biosensor production in Maharashtra and Gujarat contract clusters. This dual effect simultaneously expands addressable user bases among pediatric and elderly populations and tightens supplier leverage over strip chemistry pricing.
Pricing Analysis
Volume placements concentrate in economy self-monitoring tiers while margins accrue to remote monitoring bundles commanding 3-4x annual revenue per user. Price differentiation rests on ISO 15197 certification grade and Bluetooth connectivity integration, with FDA-cleared connected devices sustaining premium positioning against uncertified wellness alternatives. Pricing pressure stems from smartphone camera-based colorimetric assays capturing wellness-oriented consumers who reject dedicated hardware purchases. Retail pharmacy channels exhibit highest price sensitivity, while healthcare provider segments absorb premium EHR-integrated platforms.
Supply Chain Analysis
Direct-to-consumer subscription channels handle connected device demand, bypassing traditional retail pharmacy intermediaries. Electrochemical biosensor production concentrates in India, China, and Germany manufacturing clusters. Raw material dependencies include platinum and palladium for sensor electrodes, glucose oxidase enzyme formulations, and medical-grade polymer substrates. Supply chain risk centers on precious metal price volatility compressing hardware margins. Distribution runs through organized retail pharmacy networks in Tier-2 and Tier-3 Indian cities, direct-to-consumer platforms in the United States, and hospital procurement systems in Germany and the United Kingdom.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electrochemical sensor electrode manufacturing capacity constraints prop pricing power for established strip chemistry producers, sustaining margin pools despite hardware commoditization pressures.
For Market Incumbents: Hedge against optical reader substitution threats by accelerating AI-enabled pattern recognition development for hypoglycemic event prediction. Captive supply of test strip chemistry sustains price competitiveness, while HIPAA-compliant cloud architecture investments defend healthcare provider segment access against digital-native entrants. For New Entrants and Emerging Players: Direct-to-consumer subscription platforms offer the most penetrable route, displacing pharmacy-centric strip purchasing through automated reorder algorithms triggered by actual usage patterns. Target Tier-2 and Tier-3 Indian cities through organized retail pharmacy partnerships at price points below multinational benchmarks. EU MDR self-testing classification streamlines lay-user device market access for connected monitoring platforms. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by multinational conglomerates seeking microfluidic multi-analyte platform capabilities. Long-term viability favors manufacturers with statistical process control capabilities for lot-to-lot chemistry consistency at scale. Watch FDA 510(k) premarket notification clearance velocity as inflection indicator for competitive entry cost dynamics.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Premarket notification volume restructures cost-of-entry calculus for device startups. |
| Hospital System Partnership | EHR integration with Roche Diagnostics algorithms anchors clinical acceptance. |
| Software Companion Development | AI-enabled pattern recognition automates hypoglycemic event prediction. |
| Reimbursement Strategy | Medicare remote monitoring codes accelerate connected device household penetration. |
| CE Marking Pathway | EU MDR self-testing classification compresses time-to-market for lay-user devices. |
Research Methodology
Document review covered FDA 510(k) filings, EU MDR notified body guidance, CMS Medicare coverage determinations, and ISO 15197 accuracy standards, complemented by interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and regulatory affairs leads at device manufacturers. Secondary validation drew from hospital procurement databases, pharmacy channel sales data, and clinical validation study publications. Bottom-up and top-down triangulation reconciled unit shipment estimates with revenue aggregation across product type and delivery mode segments.
Segment-level outputs across glucose meters, coagulation devices, cholesterol meters, and hemoglobin analyzers were modeled through the projection horizon, with delivery mode stratification capturing self-monitoring, connected, remote monitoring, and lab integration tiers. CAGRs were derived from patient population growth, reimbursement code expansion trajectories, and technology adoption curve analysis. Forecast inputs included capillary sampling miniaturization timelines, precious metal price volatility assumptions, and telehealth parity law adoption patterns.
The model holds under stable FDA review timelines and Medicare reimbursement continuity; deviation in EU MDR notified body capacity or precious metal supply disruptions would shift volume and value trajectories. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Self-Urinary Infection Testing Market
Testing Services
Rapid Antigen Testing Market
Testing Services
Cholesterol Testing Services Market
Testing Services
Nicotine Testing Market
Testing Services
Cerebrospinal Fluid (CSF) Testing Market
Testing Services
Pneumonia Testing Market
Testing Services
At-Home Testing Market
Testing Services
Blood Testing Market
Testing Services
Global Electronystagmography Testing Market
Testing Services
Prothrombin Time Testing Market
Testing Services
Global HIV Self Test Kits Market
Testing Services
Home DNA Testing Market
Testing Services
Addison Disease Testing Market
Testing Services
Medical Device Testing Services Market
Testing Services
Procalcitonin Reagent Test Kit Market
Testing Services
Faecal Calprotectin Testing Market