
 Genetic Toxicology Testing Market | 2026-2036
Genetic Toxicology Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Genetic Toxicology Testing Market Analysis
ICH M7 is consolidating the cost-of-entry calculus for genetic toxicology testing by mandating two complementary in silico predictions and expert review for pharmaceutical impurities. Charles River Laboratories leverages its integrated discovery-to-safety platform to anchor large-molecule and small-molecule genotoxicity programs across North America and Europe. Eurofins Scientific sustains a dense laboratory network that competes on turnaround time for Ames and chromosomal aberration studies. Thermo Fisher Scientific differentiates through captive supply of reagent kits, instruments, and bioinformatics tools that extend its influence upstream from service provision.
Genetic toxicology testing evaluates DNA damage, gene mutations, and chromosomal alterations induced by chemical or biological agents using standardized bacterial, mammalian, or computational systems. The Ames Test employs Salmonella typhimurium strains with defined mutations to detect base-pair or frameshift mutagens, while the Comet Assay quantifies single-strand DNA breaks at the individual cell level for mechanistic hazard identification. In vitro testing occupies the largest revenue share due to regulatory acceptance and throughput advantages, though high-throughput screening is gaining fastest as pharmaceutical sponsors compress preclinical timelines. Bioinformatics represents the highest-margin segment, where predictive toxicology platforms reduce animal study burden and accelerate regulatory submission packages.
The FDA, EPA, and EMA collectively shape demand through mutagenicity testing mandates that vary by product class and exposure scenario. ICH guidelines harmonize genotoxicity battery requirements across the FDA and EMA jurisdictions, while the EPA maintains distinct protocols for environmental chemical registration under the Toxic Substances Control Act. Stakeholders must monitor the convergence of organ-on-chip validation with existing OECD Test Guidelines, as this technological shift could redraw the boundary between in vitro screening and definitive hazard classification.
Market Dynamics
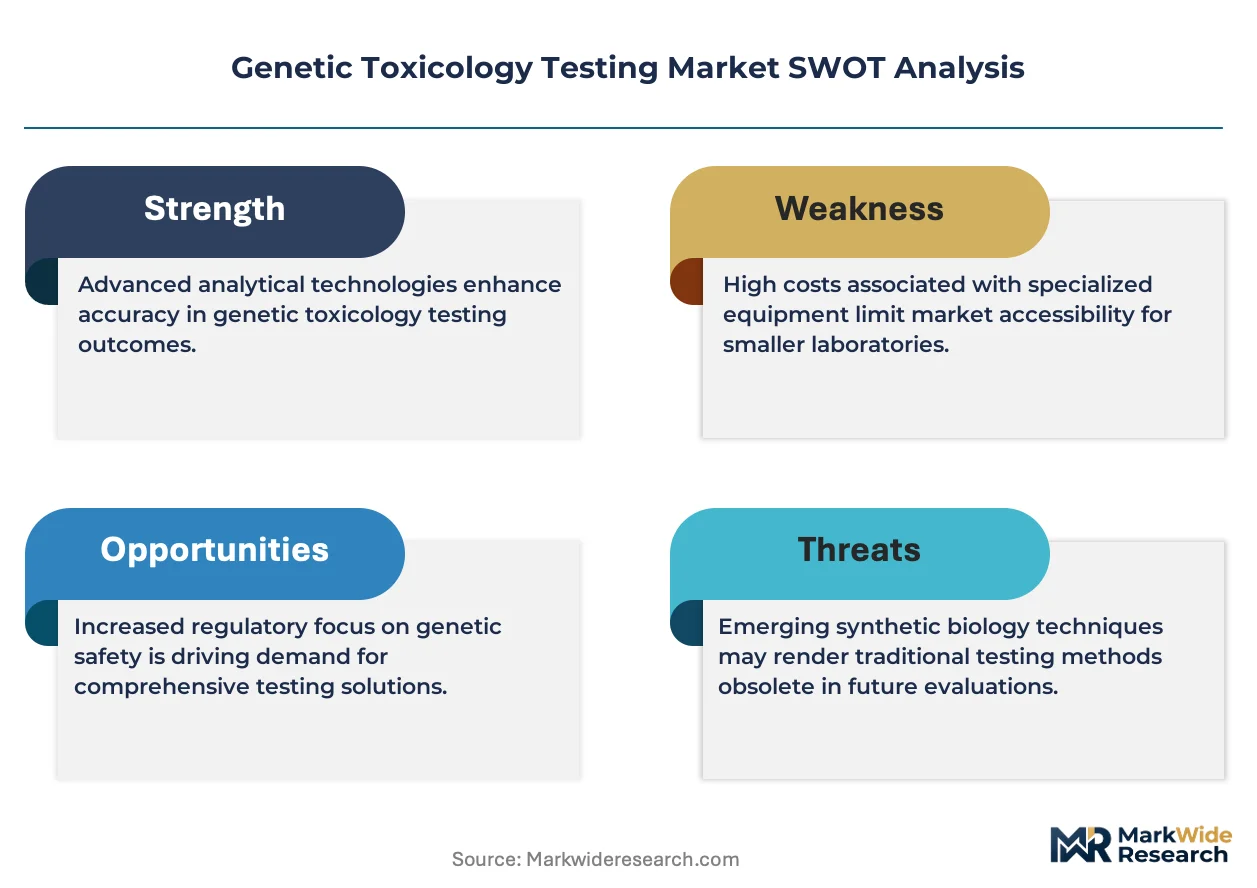
ICH M7 guideline harmonization across FDA and EMA jurisdictions is compressing testing timelines while elevating the technical threshold for market entry, forcing sponsors to integrate computational toxicology earlier in candidate selection workflows.
Growth Catalysts
- ICH M7 Guideline Expansion:The FDA and EMA now mandate dual in silico predictions with expert review for all pharmaceutical impurities, expanding the addressable service base for predictive toxicology providers.
- Biopharmaceutical Pipeline Density:United States-based sponsors are advancing more small-molecule oncology candidates into preclinical stages, each requiring standardized bacterial mutagenicity and chromosomal aberration batteries.
- Organ-on-Chip Validation:Microphysiological systems are achieving regulatory qualification status for specific genotoxicity endpoints, opening substitution pathways for traditional mammalian cell assays.
Market Restraints
- Reagent Supply Concentration:Salmonella typhimurium tester strains and specialized cell lines depend on a narrow base of cryogenic repositories, creating single-point vulnerability for contract research organizations.
- Specialized Technical Labor:Expertise in QSAR model validation and mechanistic toxicology interpretation remains scarce, inflating salary benchmarks for computational toxicologists.
- Validation Burden for Novel Platforms:OECD Test Guideline recognition for high-content screening and transcriptomic signatures requires multi-year, multi-laboratory validation campaigns that delay commercialization.
Strategic Opportunities
- Environmental Chemical Registration:The EPA's Toxic Substances Control Act modernization is expanding mutagenicity data requirements for industrial chemicals, creating adjacent demand beyond pharmaceutical applications.
- Japan's PMDA Alignment:Japanese regulators are adopting ICH M7 principles for active pharmaceutical ingredients, opening service expansion for laboratories with existing FDA and EMA track records.
- AI-Augmented Pathway Analysis:Machine learning integration with adverse outcome pathway frameworks is enabling mechanistic hazard classification that satisfies regulatory weight-of-evidence standards.
Industry Challenges
- Cross-Platform Data Harmonization:Sponsors struggle to reconcile divergent output formats between legacy LIMS systems and modern cloud-based toxicology data management platforms.
- Study Director Certification Bottlenecks:OECD Good Laboratory Practice requirements for genotoxicity study directors create training pipeline constraints that limit laboratory expansion velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Genetic Toxicology Testing Market |
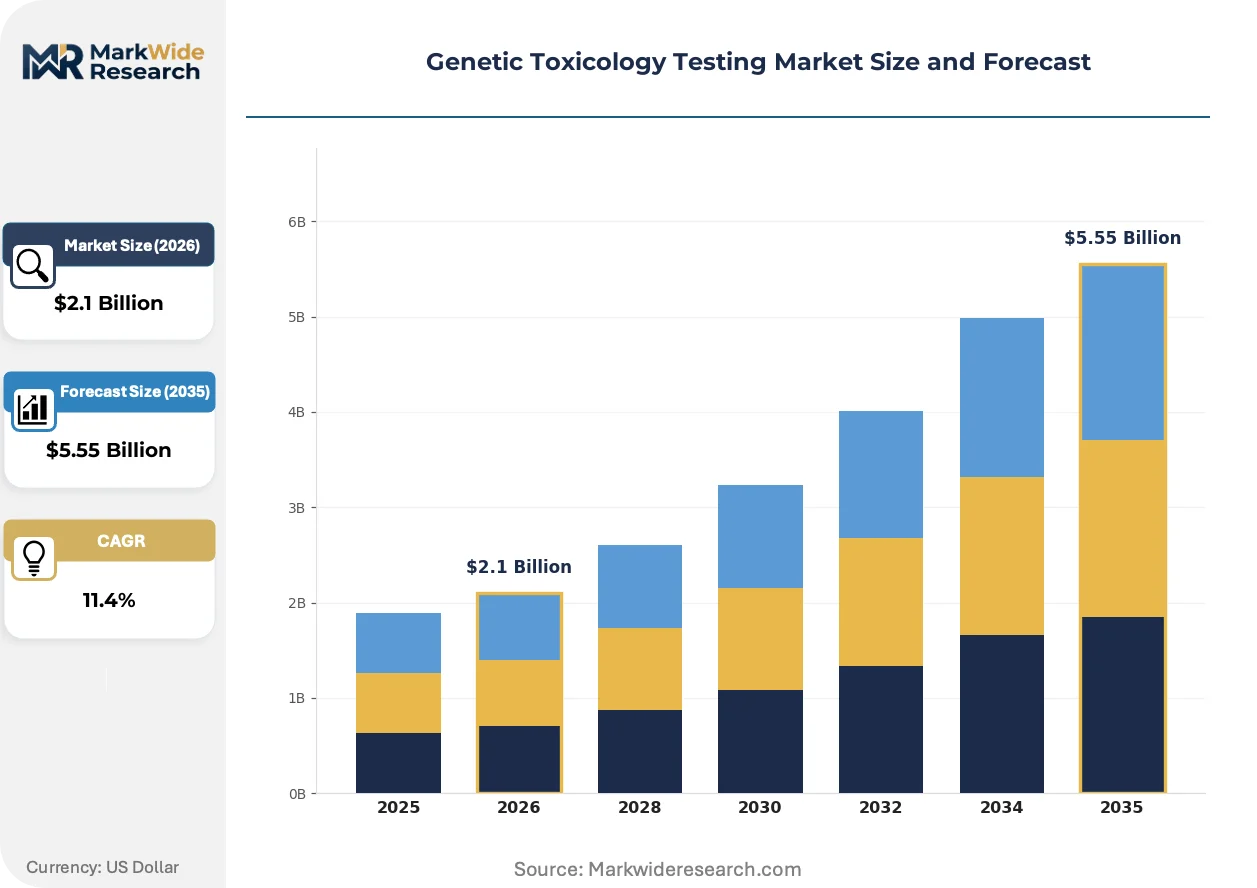
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $5.55 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Test Type: Ames Test, Chromosomal Aberration Test, Micronucleus Test, Comet Assay Technology: In Vitro Testing, In Vivo Testing, High-Throughput Screening, Bioinformatics End User: Pharmaceutical Companies, Biotechnology Firms, Research Laboratories, Academic Institutions Application: Drug Development, Environmental Testing, Regulatory Compliance, Safety Assessment |
| Companies Covered | Laboratory Corporation of America Holdings, SGS SA, Charles River Laboratories, Scantox Group, Inotiv, Eurofins Scientific, WuXi AppTec, Merck KGaA, Thermo Fisher Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Genetic Toxicology Testing Market Emerging Trajectories
Computational toxicology platforms are absorbing analytical workloads that previously demanded weeks of mammalian cell culture, while regulatory agencies simultaneously tighten evidentiary standards for in silico predictions.
High-throughput transcriptomic screening is overtaking traditional gene mutation assays for early hazard identification. Pharmaceutical sponsors in the United States and Germany are deploying these platforms at candidate-to-lead transition stages. The compression from 28-day turnaround to 72-hour data generation is overtaking established service pricing structures and forcing contract research organizations to reconfigure capacity allocation.
The EPA's New Approach Methodologies policy framework is accepting qualified in vitro and computational data for chemical registration decisions. Industrial chemical manufacturers are redirecting registration budgets from two-year rodent bioassays toward integrated testing strategies. Agricultural and specialty chemical segments in the United States are responding fastest, with several major registrants submitting organotypic skin and liver model data for genotoxicity endpoints.
Pharmaceutical procurement teams are unbundling genotoxicity screening from integrated safety assessment contracts. Large-molecule developers in Massachusetts and California are awarding standalone Ames and chromosomal aberration studies to specialized toxicology boutiques rather than full-service contract research organizations. This disaggregation is most pronounced among mid-cap biotech sponsors with limited internal toxicology infrastructure.
Genetic Toxicology Testing Market Segmentation
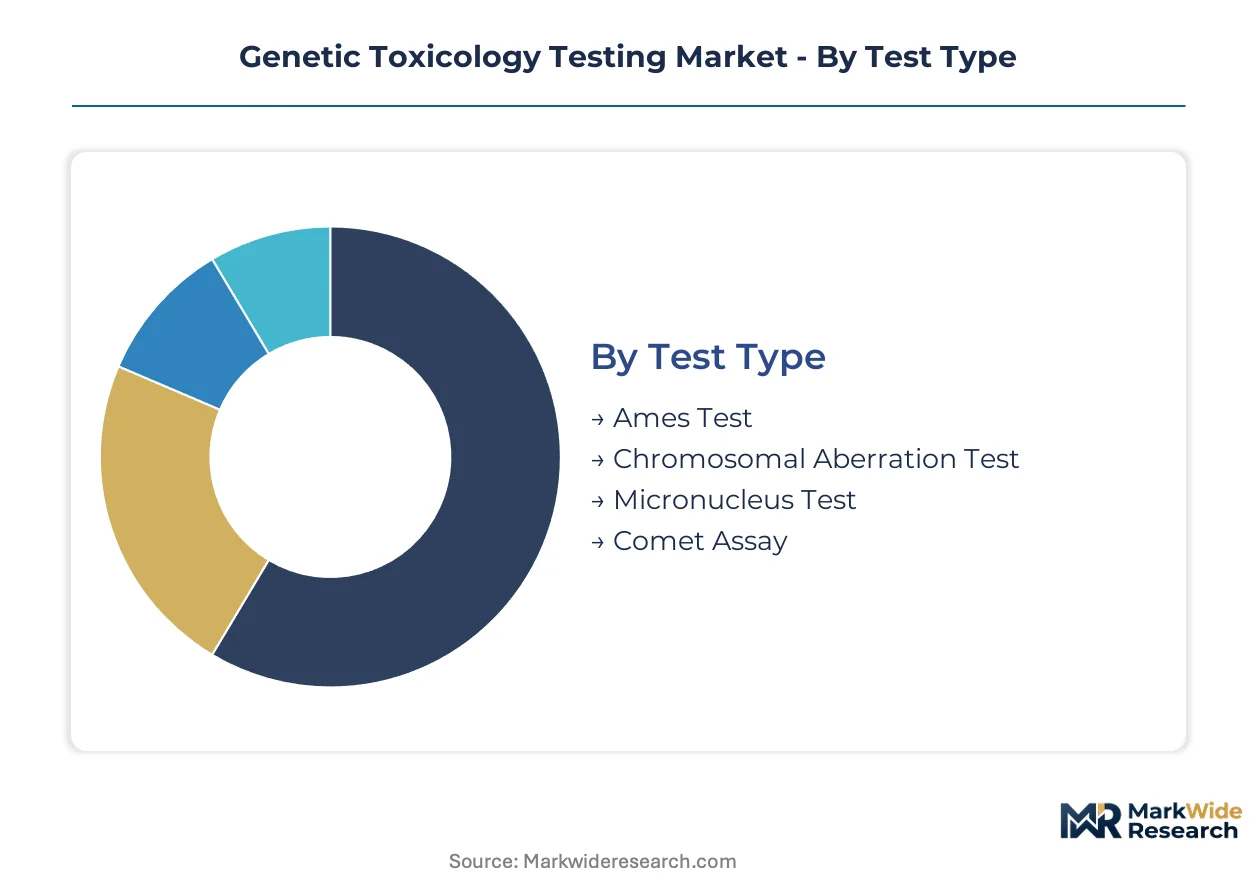
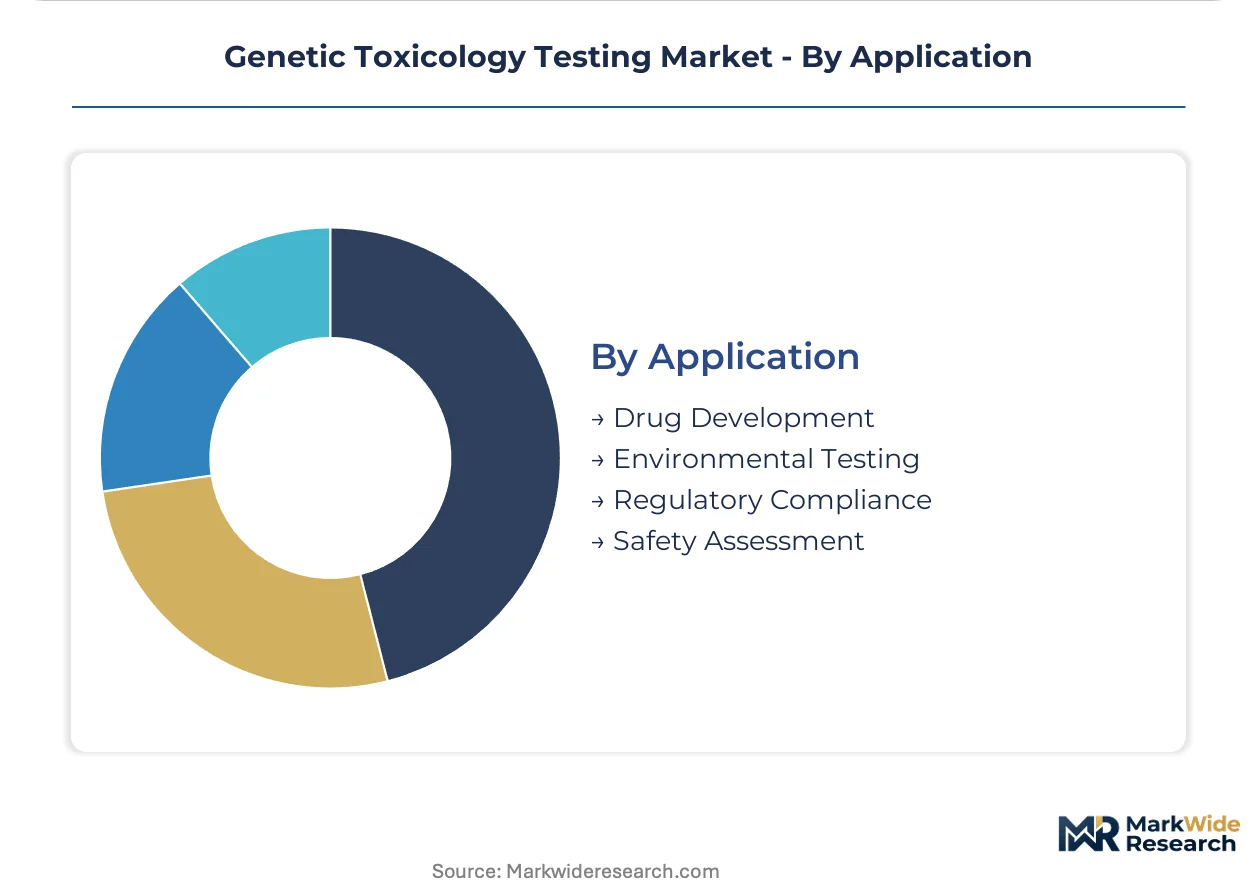
Genetic toxicology testing segments reflect divergent regulatory acceptance timelines and capital intensity requirements. Pharmaceutical sponsors select test modalities based on compound class, regulatory pathway, and internal capacity for mechanistic interpretation.
Test Type:
Replacement cycles in genotoxicity testing accelerate as regulatory agencies qualify novel methods that reduce mammalian cell dependency.
- Ames Test:Salmonella typhimurium bacterial reversion assays detect base-pair substitutions and frameshift mutations with standardized OECD 471 protocols. Pharmaceutical sponsors in the United States deploy Ames batteries for early-stage candidate triage under FDA ICH S2(R1) guidelines, compressing timelines from weeks to days.
- Chromosomal Aberration Test:Mammalian cell cytogenetic assays identify clastogenic damage through metaphase analysis of structural chromosome alterations. Demand concentrates among European sponsors preparing EMA-compliant IND packages, where in vitro chromosomal aberration remains mandatory despite rising organ-on-chip substitution pressures.
- Micronucleus Test:In vivo rodent erythrocyte assays quantify chromosomal damage through micronuclei enumeration in bone marrow or peripheral blood.
- Comet Assay:Single-cell gel electrophoresis detects DNA strand breaks at the individual cell level for mechanistic hazard identification.
Ames Test sits at the top of the volume ranking, with Comet Assay climbing the fastest as mechanistic toxicology gains regulatory weight.
Technology:
Cost tiers in genetic toxicology technology separate capital-light service providers from integrated platform operators with captive instrumentation.
- In Vitro Testing:Mammalian and bacterial cell-based assays occupy established regulatory acceptance with standardized OECD protocols. United States contract research organizations leverage in vitro batteries for pharmaceutical sponsors seeking IND-enabling data under compressed timelines.
- High-Throughput Screening:Automated multi-well platforms process thousands of compounds simultaneously using reporter gene or cell viability endpoints. Massachusetts and California biotech clusters deploy these systems at candidate-to-lead transitions, displacing traditional 28-day mammalian assays with 72-hour data generation.
- In Vivo Testing:Rodent micronucleus and transgenic mutation assays retain regulatory primacy for definitive hazard classification.
- Bioinformatics:QSAR models and expert systems predict genotoxic potential from molecular structure with ICH M7-mandated dual algorithm requirements.
In Vitro Testing commands the largest revenue base, while High-Throughput Screening expands most quickly as pharmaceutical procurement teams unbundle screening from integrated safety contracts.
End User:
Customer type segmentation tracks divergent outsourcing maturity between large pharmaceutical organizations and capacity-constrained biotech ventures.
- Pharmaceutical Companies:Large-molecule and small-molecule developers maintain internal toxicology groups for core programs while outsourcing specialized genotoxicity batteries. United States-based sponsors with dense oncology pipelines drive standardized Ames and chromosomal aberration study volume.
- Biotechnology Firms:Mid-cap developers with limited internal infrastructure award standalone genotoxicity studies to specialized boutiques rather than full-service contract research organizations. Massachusetts and California clusters exhibit pronounced disaggregation trends in procurement patterns.
- Research Laboratories:Government and independent research facilities conduct mechanistic toxicology studies and method validation campaigns.
- Academic Institutions:University toxicology programs generate foundational research on adverse outcome pathways and novel assay development.
Pharmaceutical Companies anchor current demand volumes, with Biotechnology Firms gaining share fastest as sponsor fragmentation accelerates.
Application:
Application segmentation reflects divergent regulatory stringency between pharmaceutical safety packages and industrial chemical registration requirements.
- Drug Development:IND-enabling and NDA-supporting genotoxicity batteries follow ICH S2(R1) and ICH M7 guidelines with defined test sequences. FDA and EMA jurisdictions mandate bacterial mutagenicity, in vitro chromosomal aberration, and in vivo micronucleus assays for small-molecule candidates.
- Regulatory Compliance:Impurity qualification and specification testing under ICH M7 requires dual in silico predictions with expert review for pharmaceutical manufacturers. EMA-aligned sponsors in Germany and Switzerland drive specialized computational toxicology service demand.
- Environmental Testing:EPA TSCA registration and industrial chemical hazard classification employ modified genotoxicity protocols.
- Safety Assessment:Integrated testing strategies combine multiple endpoints for weight-of-evidence hazard classification across product categories.
Drug Development maintains volume leadership, with Regulatory Compliance expanding most steeply as ICH M7 adoption broadens across FDA and EMA jurisdictions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized toxicologists and computational biologists cluster in jurisdictions with dense pharmaceutical R&D ecosystems and harmonized regulatory frameworks. The geographic distribution of genetic toxicology testing demand tracks biopharmaceutical pipeline density and regulatory agency sophistication.
United States
FDA's ICH M7 implementation and EPA's New Approach Methodologies policy create dual regulatory pull for predictive and in vitro toxicology services. Massachusetts and California biotech clusters drive standalone genotoxicity screening procurement from specialized boutiques. The FDA maintains the most advanced qualification pathway for organ-on-chip systems substituting traditional mammalian assays.
Germany
EMA-aligned sponsors in Baden-Württemberg and Bavaria sustain demand for chromosomal aberration studies under centralized European regulatory review. REACH compliance obligations for industrial chemicals expand mutagenicity data requirements beyond pharmaceutical applications. The country's dense contract research infrastructure competes on OECD Good Laboratory Practice certification density.
Switzerland
Swissmedic adoption of ICH M7 principles for active pharmaceutical ingredient qualification opens service expansion for laboratories with existing FDA track records. Basel and Zurich host concentrated pharmaceutical headquarters driving outsourced safety assessment demand. The country's regulatory alignment with both EMA and FDA creates dual-jurisdiction service opportunities.
Japan
PMDA's progressive alignment with ICH M7 guidelines for mutagenic impurities expands computational toxicology service addressability. Tokyo and Osaka pharmaceutical clusters require localized study director certification under OECD Good Laboratory Practice. The country's regulator maintains distinct validation requirements for novel in vitro platforms that delay method substitution timelines.
United Kingdom
MHRA post-Brexit regulatory autonomy preserves ICH guideline alignment while creating separate submission pathways for genotoxicity data packages. London and Cambridge biotech sponsors disaggregate safety screening from integrated discovery contracts. The country's Medicines and Healthcare products Regulatory Agency participates actively in OECD Test Guideline development for transcriptomic signatures.
Genetic Toxicology Testing Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across a tiered market structure where service breadth and technical depth define positioning boundaries. The vendor base separates into integrated platform operators with captive reagent supply, full-service contract research organizations with global laboratory networks, and specialized boutiques competing on turnaround velocity for standardized assays. Two dominant competitive moves reshape positioning: pharmaceutical procurement teams unbundle genotoxicity screening from integrated safety contracts, and laboratories pursue OECD Test Guideline recognition for novel high-content platforms.
Within the integrated platform tier, Thermo Fisher Scientific exemplifies archetype positioning through captive supply of instruments and bioinformatics tools extending influence upstream from service provision. Charles River Laboratories and Eurofins Scientific occupy distinct positions in the full-service contract research space, with the former anchoring large-molecule and small-molecule programs across North America and Europe while the latter competes on laboratory network density and turnaround compression for standardized bacterial and mammalian assays.
| Leading Market Players |
|---|
| Laboratory Corporation of America Holdings |
| SGS SA |
| Charles River Laboratories |
| Scantox Group |
| Inotiv |
| Eurofins Scientific |
| WuXi AppTec |
| Merck KGaA |
| Thermo Fisher Scientific |
| Others |
Supply Flow & Price Mechanics
Salmonella typhimurium tester strain procurement costs cascade through contract research organization pricing tiers, compressing margins at the economy service level while premium laboratories with OECD Good Laboratory Practice certification capture pricing power. Cryogenic repository concentration in the United States and Europe creates input cost asymmetry that pharmaceutical sponsors absorb through bundled discovery-to-safety contracts or standalone genotoxicity screening unbundling.
Pricing Analysis
The bundled-versus-unbundled service split separates integrated contract research organization pricing from specialized toxicology boutique rates. Three-tier pricing structure across premium, standard, and economy levels reflects OECD certification density, study director experience, and turnaround velocity. Cost compression in the standard tier is intensifying because high-throughput screening automation reduces per-sample labor content. Mid-cap biotechnology firms with limited internal toxicology infrastructure exhibit highest price sensitivity, while large pharmaceutical sponsors prioritize regulatory submission reliability over unit cost.
Supply Chain Analysis
OECD Good Laboratory Practice certification gating restricts viable supplier pools to laboratories with validated quality systems and trained study directors. Cryogenic repositories in the United States, Germany, and Japan supply Salmonella typhimurium strains and specialized mammalian cell lines that service providers draw from under exclusive licensing arrangements. Single-source vulnerability concentrates in the tester strain supply base, where repository consolidation creates chokepoint risk for bacterial mutagenicity assays. Distribution runs through direct laboratory-to-sponsor contracting for pharmaceutical applications, with environmental chemical registration channels feeding through regulatory consultancy intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where ICH M7 guideline tightening shifts sponsor procurement toward dual-certified laboratories with computational and wet-lab capabilities. The demand drift toward premium specifications accelerates as regulatory agencies demand weight-of-evidence packages combining in silico predictions with mechanistic follow-up studies.
For Market Incumbents: Hedge against organ-on-chip substitution by securing early-adopter relationships with FDA qualification pathway participants. Invest in OECD Test Guideline validation campaigns for transcriptomic signature platforms before regulatory acceptance widens. Defensive consolidation of cryogenic repository access through exclusive strain licensing agreements protects input cost position against emerging competitors. For New Entrants and Emerging Players: Enter via the standalone genotoxicity screening segment where mid-cap biotechnology sponsors disaggregate procurement from full-service contract research organizations. Target Massachusetts and California clusters with compressed turnaround value propositions for Ames and chromosomal aberration batteries. A computational toxicology-first go-to-market angle bypasses capital-intensive mammalian cell culture infrastructure requirements. For Investors and Strategic Acquirers: Consolidation pressure builds where sponsor procurement teams unbundle safety screening from integrated discovery contracts, fragmenting volume across subscale service providers. Laboratories with captive bioinformatics platforms and existing FDA track records present acquisition archetypes with durable competitive moats. Watch for organ-on-chip regulatory qualification announcements as inflection indicators that redraw the boundary between screening and definitive hazard classification.| Strategic Initiative | Industry Significance |
|---|---|
| OECD Test Guideline Validation Campaign | Regulatory recognition for novel high-content screening platforms accelerates method substitution timelines. |
| Captive Cryogenic Repository Licensing | Exclusive Salmonella typhimurium strain access insulates input cost position from supply concentration risk. |
| Computational Toxicology Platform Acquisition | Dual in silico prediction capability satisfies ICH M7 mandates and commands premium service pricing. |
| Organ-on-Chip Regulatory Qualification | FDA pathway participation positions laboratories for mammalian assay substitution revenue capture. |
| Biotechnology Cluster Geographic Expansion | Massachusetts and California presence captures disaggregated standalone screening procurement volume. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with drug development executives, regulatory affairs leads, contract research organization study directors, and pharmaceutical procurement managers with secondary validation against FDA filings, EMA submissions, OECD Test Guideline documentation, and ClinicalTrials.gov records. Bottom-up service provider revenue aggregation and top-down pharmaceutical R&D expenditure allocation were cross-referenced for triangulation.
Segment-weighting approaches distributed value across test type, technology, end user, and application dimensions, with regional regulatory cluster heterogeneity incorporated as an overlay factor. CAGRs were derived from modeled progression of in vitro testing, high-throughput screening, and bioinformatics adoption curves against pharmaceutical pipeline density and ICH guideline implementation timelines. Forecast inputs included sponsor outsourcing ratio assumptions and organ-on-chip regulatory qualification probability assessments.
Inputs from primary stakeholder interviews and regulatory agency documentation were available through the study window; gaps in emerging platform commercialization timelines introduce uncertainty bands around high-throughput screening and bioinformatics growth trajectories. Forecasts reflect assumptions regarding ICH M7 adoption velocity and EPA New Approach Methodologies policy implementation scope. A model refresh is warranted upon material change in organ-on-chip regulatory qualification status or OECD Test Guideline recognition for transcriptomic signatures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Global Legionella Testing Market
Testing Services
Global Anti Thrombin III Testing Market
Testing Services
Staphylococcus Aureus Testing Market
Testing Services
Creatinine Testing Market
Testing Services
Biomarker Testing Services Market
Testing Services
Biological Indicator Vials Market
Testing Services
Urodynamic Testing Market
Testing Services
Global Biological Safety Testing Market
Testing Services
Ferritin Testing Market
Testing Services
Calprotectin Testing Market
Testing Services
Specific Protein Testing Market
Testing Services
Pancreatic Elastase Testing Market
Testing Services
Global Nitric Oxide Test Market
Testing Services
Addison Disease Testing Market
Testing Services
Anti-Asthma TDM Assay Kits Market
Testing Services
Beta-Hydroxybutyrate Testing Market