
 Self-Testing Market | 2026-2036
Self-Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Self-Testing Market Analysis
At-home users are reorganizing demand patterns in the Self-Testing Market, shifting volume from clinic-based procurement toward direct-to-consumer channels. Abbott leverages biosensor miniaturization to sustain technology leadership in glucose monitoring. Johnson & Johnson anchors brand strength across pregnancy and fertility self-test segments through pharmacy shelf dominance. F. Hoffmann-La Roche Ltd. competes on clinical-grade accuracy positioned for wellness monitoring applications.
Self-testing encompasses diagnostic devices and consumables designed for operation by non-professional users outside clinical settings, typically requiring specimen volumes under 50 microliters and producing results within 15 minutes through enzymatic, immunochemical, or electrochemical detection methods. These products serve chronic disease surveillance, infection screening, and metabolic tracking where convenience and privacy outweigh laboratory precision. Blood glucose test strips retain the largest revenue pool due to daily-use frequency among diabetic populations, while HIV self-tests represent the fastest-expanding category as stigma reduction and OTC availability broaden addressable populations. Lateral flow assays dominate manufacturing scale because of low-cost roll-to-roll production, though biosensors capture margin concentration through semiconductor-compatible fabrication and smartphone connectivity.
FDA OTC clearance frameworks, EU MDR Class C device requirements, and WHO prequalification standards collectively determine market access timelines and clinical claim permissibility for self-testing manufacturers. The FDA's template for HIV self-test authorization now extends to hepatitis C and sexually transmitted infection panels, compressing regulatory pathways for follow-on entrants. Stakeholders must monitor whether WHO prequalification expansion into self-testing categories unlocks procurement contracts in low-resource health systems.
Market Dynamics
Pharmacy-direct distribution networks are compressing procurement cycles and forcing manufacturers to bypass traditional clinical procurement channels entirely, restructuring how diagnostic consumables reach end-users.
Growth Catalysts
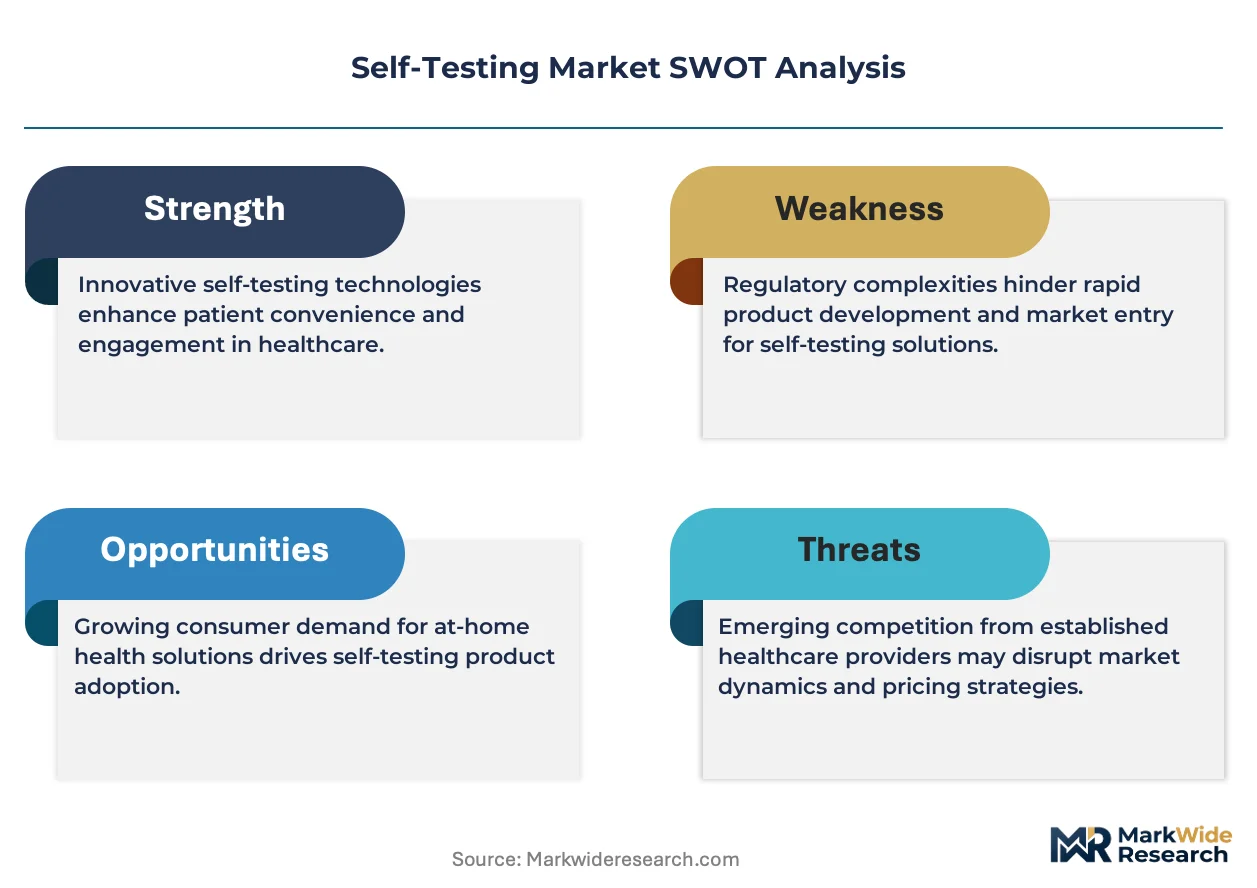
- FDA OTC Authorization Pathway:The FDA's template for HIV self-test clearance now extends to hepatitis C and sexually transmitted infection panels, compressing regulatory timelines for follow-on infectious disease diagnostics.
- Biosensor Semiconductor Fabrication:Roll-to-roll manufacturing of electrochemical sensors enables smartphone-connected glucose monitors that transmit encrypted data directly to care teams.
- Germany's Pharmacy Network Density:Direct-to-consumer distribution through Apotheke channels supports high-frequency repeat purchasing for chronic disease surveillance among aging populations.
Market Restraints
- Enzyme Reagent Cost Volatility:Biosensor manufacturing depends on stabilized glucose oxidase and horseradish peroxidase supplies concentrated among three specialty chemical producers.
- WHO Prequalification Gaps:Absence of streamlined self-testing prequalification standards blocks procurement contracts in low-resource health systems across sub-Saharan Africa and South Asia.
- Lateral Flow Sensitivity Floors:Immunochromatographic assays face fundamental detection limits for early-stage HIV and hepatitis C viral loads, restricting clinical claim permissibility.
Strategic Opportunities
- Japan's Super-Aging Prefectures:Aichi and Kanagawa prefectures present concentrated demand for home-based cholesterol and kidney function monitoring among populations over 75.
- EU MDR Class C Streamlining:Conformity assessment body harmonization for in-vitro diagnostic devices reduces certification duplication across member states.
- Telehealth Platform Integration:Remote patient monitoring vendors seek API-compatible self-testing devices that auto-populate electronic health records without manual data entry.
Industry Challenges
- Electrochemical Engineer Scarcity:Biosensor development requires specialized expertise in potentiostat circuit design and reference electrode stabilization that outpaces university pipeline output.
- CE-IVDR Technical Documentation Burden:Performance evaluation reports and post-market surveillance systems demand dedicated regulatory affairs headcount that strains mid-cap manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Self-Testing Market |
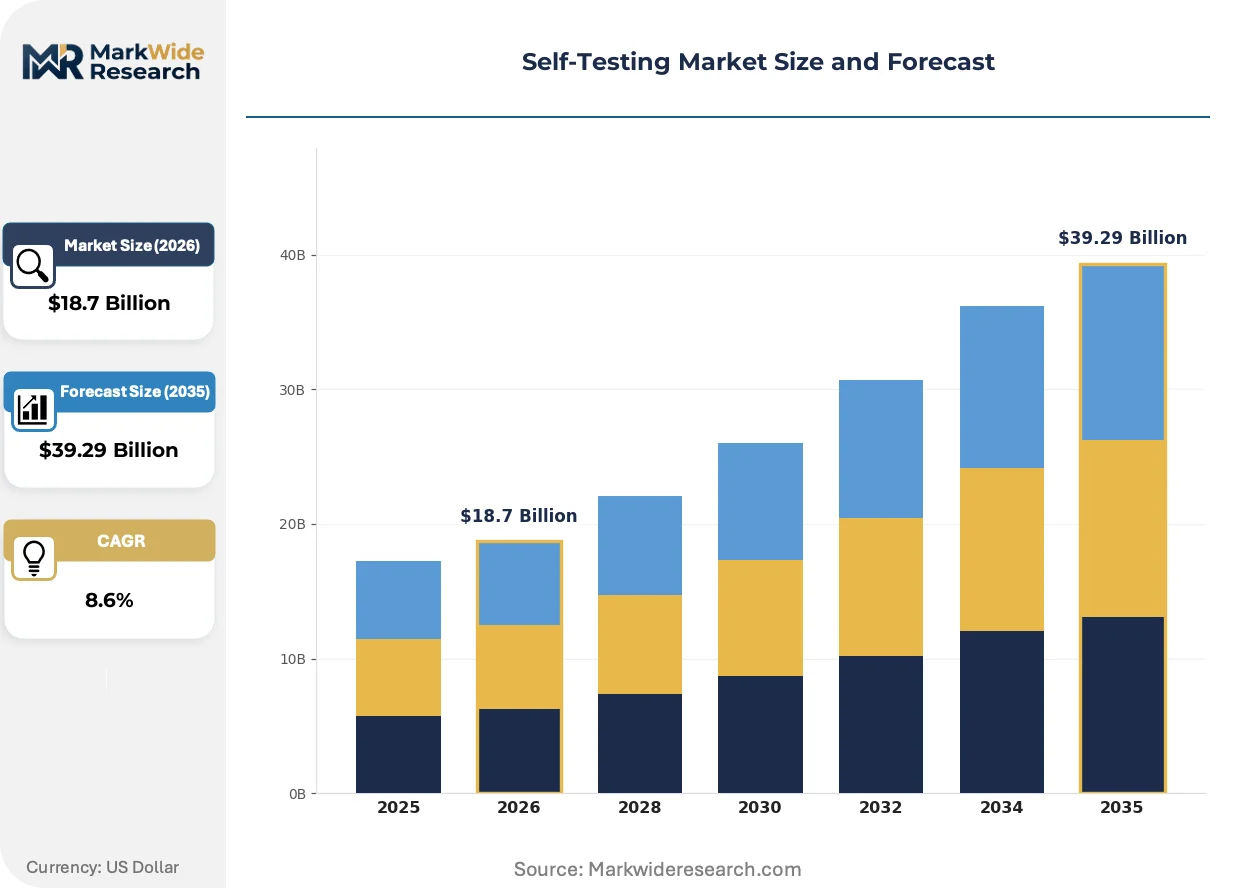
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $39.29 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blood Glucose Test Strips, Pregnancy Tests, Cholesterol Testing Kits, HIV Self-Tests End User: At-Home Users, Healthcare Professionals, Pharmacies, Specialized Clinics Technology: Immunoassay, Optical Sensing, Biosensors, Lateral Flow Assays Application: Chronic Disease Management, Preventive Healthcare, Drug Testing, Wellness Monitoring |
| Companies Covered | OraSure Technologies, Inc., Johnson & Johnson, Abbott, Cardinal Health, Siemens Healthineers, F. Hoffmann-La Roche Ltd., Quidel Corporation, Geratherm Medical AG, Becton, Dickinson and Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Self-Testing Market Emerging Trajectories
Diagnostic hardware is converging with consumer electronics supply chains, forcing traditional medical device manufacturers to adopt semiconductor fabrication methods and mobile-first software architectures.
CMOS-integrated electrochemical sensors are miniaturizing reference electrodes and potentiostat circuits onto single silicon dies. Wearable manufacturers in the United States and South Korea are adopting these chips for continuous glucose monitoring patches that eliminate finger-prick sampling. This integration is miniaturizing device footprints below one square centimeter while collapsing bill-of-materials costs toward consumer electronics levels.
The FDA's over-the-counter authorization framework for infectious disease self-tests is expanding beyond HIV to encompass hepatitis C and select sexually transmitted infection panels. This regulatory expansion compresses clinical trial requirements for manufacturers with predicate device pathways. Infectious disease diagnostics now face accelerated 510(k) clearance timelines that previously required prescription-labeled precursors.
Consumers in the United States and Germany are bypassing physician intermediaries for routine metabolic surveillance, purchasing cholesterol and HbA1c tests directly through pharmacy e-commerce portals. Pharmacy chains are responding with subscription-based replenishment programs that lock in annual consumable commitments. This channel migration is most visible among diabetic populations aged 45-65 who manage multiple chronic conditions through self-directed monitoring protocols.
Self-Testing Market Segmentation
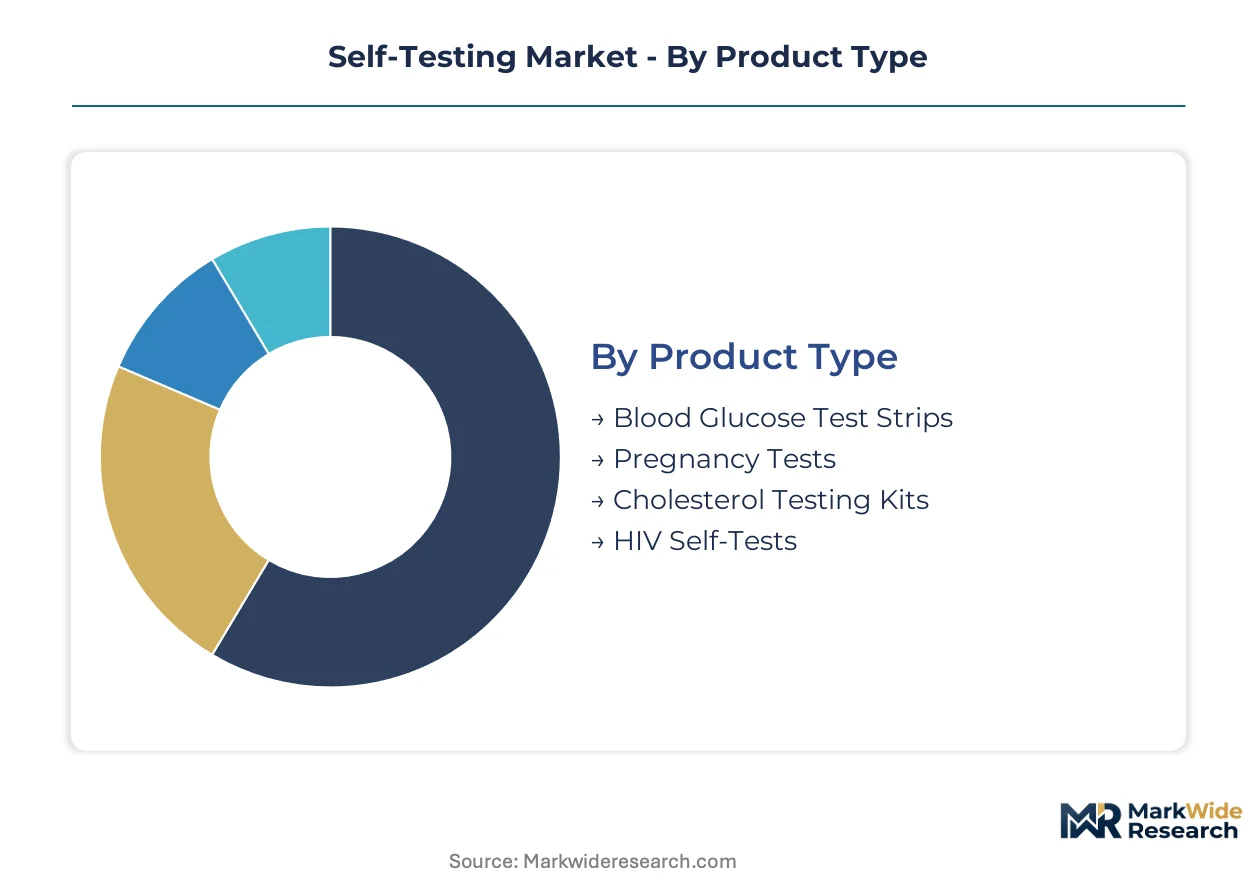
Self-testing manufacturers face divergent substitution pressures across product architectures. Blood glucose strips confront continuous monitoring wearables. Lateral flow assays compete with smartphone-connected biosensors. Segment selection determines regulatory pathway complexity and margin durability.
Product Type:
Substitution pressure concentrates in metabolic monitoring segments where wearable biosensors threaten traditional consumable models.
- Blood Glucose Test Strips:Electrochemical sensors requiring sub-1 microliter blood samples and 5-second readouts. Daily-use frequency among diabetic populations in the United States and Germany sustains volume despite continuous glucose monitor encroachment.
- HIV Self-Tests:Immunochromatographic lateral flow devices detecting antibodies in oral fluid or whole blood. FDA OTC authorization and stigma reduction in pharmacy-direct channels drive demand expansion among previously untested populations.
- Pregnancy Tests:hCG-detecting lateral flow cassettes with digital readout variants commanding price premiums.
- Cholesterol Testing Kits:Enzymatic dry chemistry strips measuring total cholesterol, HDL, and triglycerides from capillary blood.
Blood glucose test strips retain volume leadership; HIV self-tests hold the steepest expansion curve.
End User:
Channel migration from clinical procurement to direct-to-consumer purchasing restructures demand concentration and pricing power.
- At-Home Users:Non-professional operators performing specimen collection and result interpretation without clinical supervision. Privacy preferences and convenience priorities in Japan's aging prefectures accelerate category growth.
- Pharmacies:Apotheke networks in Germany and chain pharmacies in the United States functioning as fulfillment nodes for subscription replenishment programs.
- Healthcare Professionals:Point-of-care deployers requiring CLIA-waived or equivalent regulatory status for non-laboratory settings.
- Specialized Clinics:Fertility centers and sexual health clinics utilizing self-test adjuncts for patient triage and monitoring.
At-home users command the largest addressable population; pharmacies capture the highest repeat-purchase frequency.
Technology:
Manufacturing scale and margin concentration split between roll-to-roll paper diagnostics and semiconductor-fabricated electrochemical sensors.
- Biosensors:CMOS-integrated potentiostat circuits with reference electrode stabilization on single silicon dies. South Korean and United States wearable manufacturers adopt these for continuous glucose monitoring patches eliminating finger-prick sampling.
- Lateral Flow Assays:Nitrocellulose membrane-based immunochromatographic strips produced via high-throughput roll-to-roll coating. Cost floors below one dollar per test enable infectious disease screening at scale in resource-limited settings.
- Immunoassay:Enzyme-linked detection formats requiring reader instrumentation for quantitative output.
- Optical Sensing:Colorimetric and fluorescence-based detection systems for multi-analyte panels.
Lateral flow assays dominate unit volume; biosensors concentrate value capture and technology differentiation.
Application:
Reimbursement alignment and out-of-pocket willingness-to-pay create divergent margin profiles across clinical versus wellness-positioned use cases.
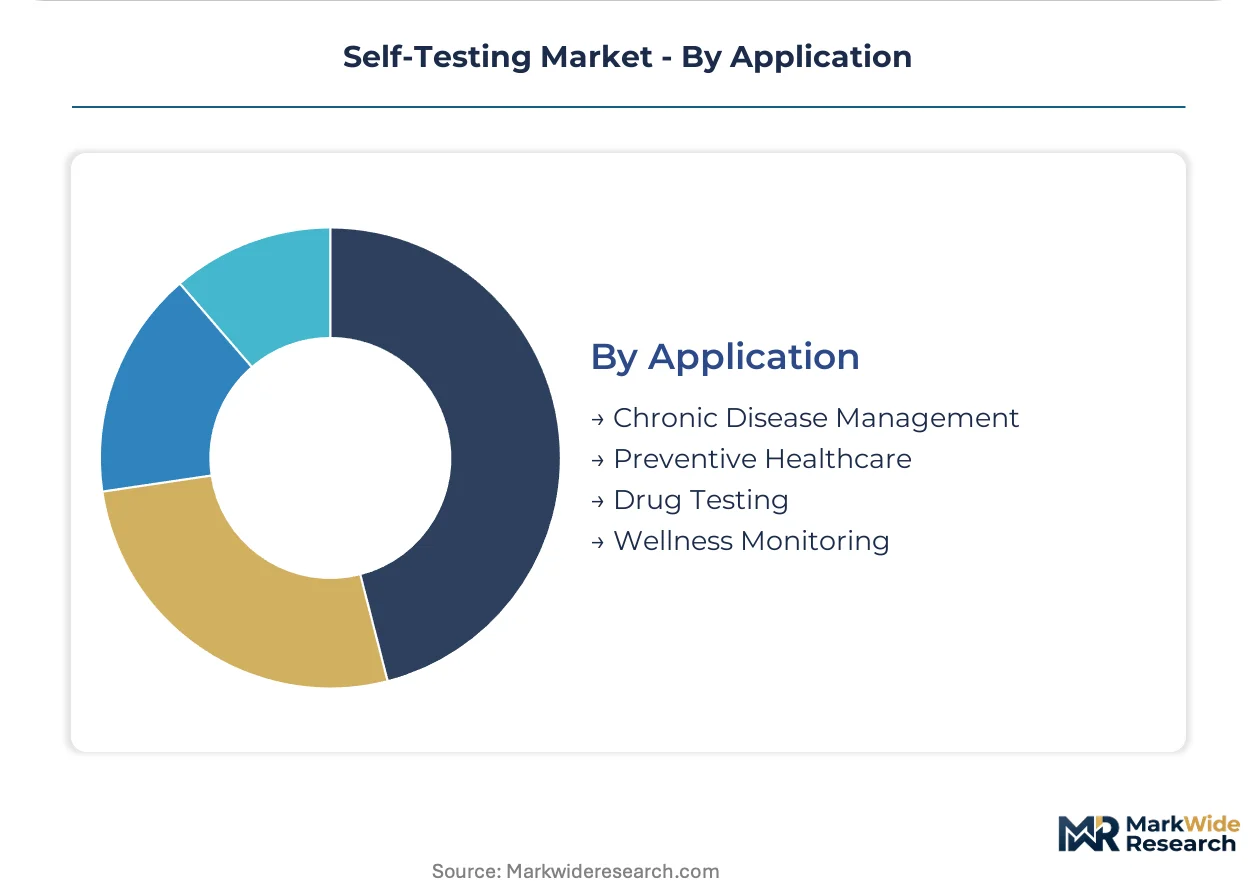
- Chronic Disease Management:Diabetes, cardiovascular, and renal function monitoring requiring daily or weekly testing cadence. Germany's statutory health insurance reimbursement for HbA1c self-tests sustains compliance-driven demand.
- Wellness Monitoring:Fitness-oriented metabolic tracking and preventive health screening without diagnosed condition requirements. United States consumers aged 45-65 purchase cholesterol and vitamin D panels through pharmacy e-commerce portals.
- Preventive Healthcare:Infectious disease screening and early detection protocols.
- Drug Testing:Employment and forensic applications utilizing urine and oral fluid matrices.
Chronic disease management anchors revenue stability; wellness monitoring gains share fastest among discretionary spenders.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export lateral flow consumables to pharmacy networks across the European Union, while United States biosensor specialists supply continuous monitoring hardware to East Asian wearable device assemblers.
United States
Pharmacy chains in California and Texas operate subscription replenishment programs for diabetic test strips, locking in annual consumable commitments from aging populations. FDA OTC authorization frameworks now extend to hepatitis C and sexually transmitted infection panels, compressing clearance timelines for infectious disease diagnostics. Boston-area biotech clusters host electrochemical engineering talent pools developing smartphone-connected glucose monitors.
Germany
Apotheke network density in Bavaria and North Rhine-Westphalia supports high-frequency repeat purchasing for HbA1c and cholesterol self-tests among statutory health insurance beneficiaries. EU MDR Class C device requirements and conformity assessment body harmonization reduce certification duplication across member states. The Baden-Württemberg medical technology corridor concentrates lateral flow manufacturing capacity serving EU-wide pharmacy distribution.
Japan
Aichi and Kanagawa prefectures present concentrated demand for home-based kidney function and cholesterol monitoring among populations over 75, with convenience stores doubling as diagnostic pickup points. PMDA streamlined review pathways for designated self-testing devices accelerate market entry for foreign manufacturers. Tokyo-Osaka logistics corridors enable next-day replenishment of glucose test strips to suburban aging clusters.
China
Domestic manufacturers in Jiangsu and Zhejiang provinces supply enzymatic test strips to pharmacy chains serving tier-one city diabetic populations, while export-oriented production serves Southeast Asian markets. NMPA innovation review channels for breakthrough diagnostic devices reduce registration timelines for electrochemical sensor platforms. The Yangtze River Delta hosts roll-to-roll coating facilities producing nitrocellulose membranes at sub-dollar unit costs.
United Kingdom
London and Southeast England pharmacy e-commerce portals drive direct-to-consumer purchasing of wellness-oriented metabolic panels among consumers aged 45-65. MHRA post-Brexit regulatory autonomy permits streamlined UKCA marking pathways for self-testing devices with predicate EU approvals. The Oxford-Cambridge biotech corridor incubates optical sensing startups developing multi-analyte smartphone readers.
Self-Testing Market Vendor Landscape
Listed leaders compete with private specialists across technology differentiation and channel access dimensions. The vendor base stratifies between multinational conglomerates with semiconductor fabrication capabilities and mid-cap lateral flow specialists serving price-sensitive infectious disease screening segments. Three archetypes dominate: integrated biosensor-platform developers, pharmacy-shelf brand anchors, and contract manufacturing organizations with roll-to-roll membrane coating expertise. Competitive moves concentrate on strategic partnerships with telehealth platforms and backward integration into stabilized enzyme supply chains.
Within the integrated diagnostic-platform tier, Abbott and F. Hoffmann-La Roche Ltd. occupy positions exemplifying clinical-grade accuracy positioning for wellness monitoring applications. Johnson & Johnson represents the pharmacy-shelf brand anchor archetype, with its corporate structure supporting broad retail distribution reach. OraSure Technologies, Inc. sits within the infectious disease specialization segment, its corporate designation indicating focused diagnostic development rather than diversified healthcare conglomeration.
| Leading Market Players |
|---|
| OraSure Technologies, Inc. |
| Johnson & Johnson |
| Abbott |
| Cardinal Health |
| Siemens Healthineers |
| F. Hoffmann-La Roche Ltd. |
| Quidel Corporation |
| Geratherm Medical AG |
| Becton, Dickinson and Company |
| Others |
Supply Flow & Price Mechanics
FDA OTC authorization frameworks gate both supply qualification and price differentiation simultaneously, as manufacturers without predicate device pathways face extended clinical trial timelines that compress margin structures while certified competitors capture pharmacy-direct premiums.
Pricing Analysis
Next-generation biosensor platforms command three-to-five-fold premiums over legacy electrochemical strips, while prior-generation lateral flow cassettes face commoditization in infectious disease screening. Three-tier pricing structure across premium, standard, and economy levels separates smartphone-connected continuous monitors from pharmacy-shelf glucose meters from bulk-procured hospital-grade consumables. Price differentiation hinges on FDA clearance tier and semiconductor integration depth. Cost compression in standard-tier lateral flow production is intensifying because Chinese membrane manufacturers are expanding roll-to-roll capacity. Pharmacy-direct at-home users exhibit highest price sensitivity; specialized clinics purchasing CLIA-waived devices show lowest.
Supply Chain Analysis
Strategic stockpiling of stabilized enzyme reagents dominates inventory strategy among biosensor manufacturers confronting three-producer concentration in glucose oxidase supply. Manufacturing concentrates in China, Germany, and the United States. Production draws from nitrocellulose membranes, CMOS silicon wafers, and stabilized peroxidase enzyme preparations. Single-source vulnerability in South Korean potentiostat chip supply threatens continuous monitor assembly lines. Distribution runs through pharmacy chain replenishment programs and hospital GPO contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are inflecting as telehealth API interoperability transforms self-testing devices from standalone consumables into data-layer infrastructure, with auto-populated EHR integration becoming the dominant ecosystem battleground.
For Market Incumbents: Consolidate backward integration into stabilized enzyme supply chains to defend against reagent cost volatility threatening biosensor margins. Lock in exclusive pharmacy chain subscription programs before continuous monitor wearables displace finger-prick strip volumes. Abbott and Roche semiconductor fabrication capabilities represent the critical defensive moat. For New Entrants and Emerging Players: Anchor in Japan's super-aging prefectures where kidney function and cholesterol self-tests face limited domestic competition and PMDA streamlined review accelerates market entry. Target wellness monitoring applications among United States consumers aged 45-65 bypassing physician intermediaries. Partner with telehealth platforms seeking API-compatible device integration. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across lateral flow manufacturing as roll-to-roll automation collapses unit production costs. Five-to-ten year viability favors mid-cap specialists with WHO prequalification trajectory and emerging market procurement access. Watch FDA OTC authorization expansion into hepatitis C and STI panels as signal for infectious disease diagnostic valuation inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Telehealth API Integration | Auto-populated EHR connectivity transforms device economics through data-layer subscription revenues. |
| Backward Enzyme Integration | In-house glucose oxidase production insulates margins from three-supplier concentration risk. |
| Pharmacy Subscription Lock-In | Annual replenishment commitments secure volume visibility against continuous monitor substitution. |
| WHO Prequalification Pursuit | Streamlined standards unlock procurement contracts in sub-Saharan African health systems. |
| CMOS Sensor Miniaturization | Semiconductor-compatible fabrication enables wearable patch form factors below one square centimeter. |
Methodological Framework
Desk research of FDA 510(k) clearance databases, EU MDR technical documentation filings, and WHO prequalification status records preceded structured interviews with diagnostic platform engineering directors, pharmacy chain procurement managers, and telehealth platform integration specialists. Primary fieldwork with GPO contract administrators and hospital biomedical engineering heads combined with secondary validation against CMS Medicare reimbursement schedules and German statutory health insurance formulary data. Bottom-up unit demand modeling triangulated against top-down manufacturer revenue disclosures.
Variance decomposition across technology generation, regulatory pathway tier, and distribution channel structure anchored the analytical framework throughout the projection horizon. Segmentation dimensions modeled include product architecture, end-user procurement mode, detection technology, and application clinical versus wellness positioning. CAGRs derived from fitted growth curves incorporating FDA authorization timeline acceleration and pharmacy-direct channel migration rates. Biosensor semiconductor yield improvements and lateral flow membrane cost curves served as industry-specific forecast inputs.
Material uncertainties — enzyme reagent supply disruptions, WHO prequalification standard delays, and continuous monitor wearable substitution velocity — sit outside the modeled envelope. Forecasts reflect assumptions regarding regulatory pathway stability and pharmacy network density persistence. Revision becomes warranted when continuous glucose monitor penetration crosses thresholds that collapse finger-prick strip replacement rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Ovulation Test Kit Market
Testing Services
Anderson Cascade Impactor Market
Testing Services
Nicotine Testing Market
Testing Services
Active B12 Test Market
Testing Services
Hemotransmissive Infections Testing Market
Testing Services
Pharmaceutical Analytical Testing Market
Testing Services
Europe Point-Of-Care-Testing (POCT) Market
Testing Services
Fecal Occult Testing Market
Testing Services
Global CA 125 Test Market
Testing Services
Europe IVD Regulatory Affairs Outsourcing Market
Testing Services
Thrombophilia Testing Market
Testing Services
Global Cholesterol Testing Products and Services Market
Testing Services
Global Legionella Testing Market
Testing Services
Minimal Residual Disease Testing Market
Testing Services
Creatinine Testing Market
Testing Services
Global Specimen Validity Testing Market