
 Global Campaign Management Software Market | 2026-2036
Global Campaign Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Campaign Management Software Market Foresight
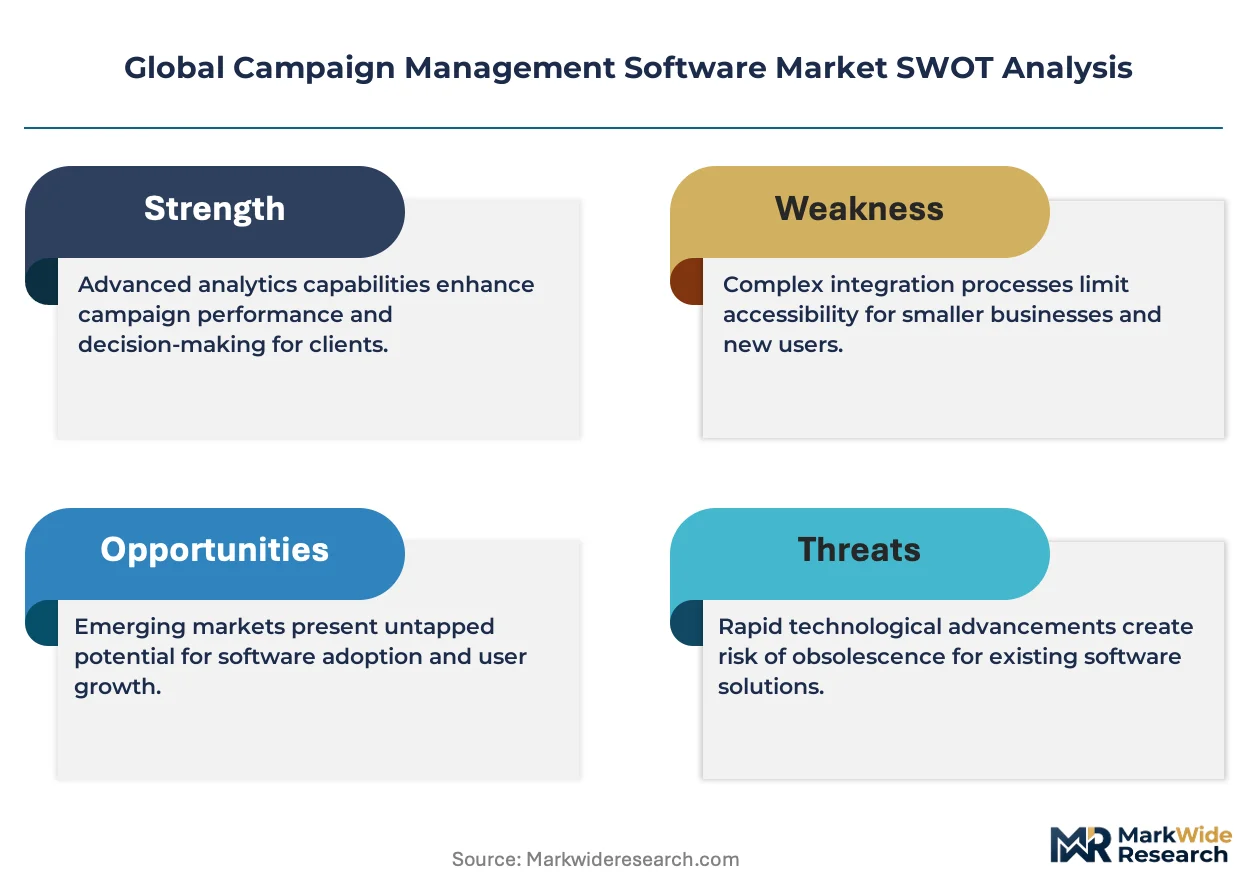
Subscription-based financing and asset-light SaaS leasing is tilting competitive dynamics toward vendors with recurring revenue engineering. Salesforce leverages extensive AppExchange integrations to sustain platform stickiness across enterprise accounts. Adobe anchors creative-to-campaign workflows that differentiate its offering from pure-play competitors. SAP competes through embedded ERP-campaign connectivity that controls data flow for manufacturing and retail conglomerates.
Campaign management software comprises cloud-native and on-premise applications that orchestrate multichannel marketing execution through audience segmentation, content personalization, and performance attribution engines. The technology processes behavioral signals, demographic profiles, and engagement histories to automate message delivery across email, social, paid media, and direct channels. Cloud-based deployment leads structural growth due to elastic infrastructure scaling and reduced capital burden for mid-market adopters. Customer analytics within the solution layer captures concentrated margin pools as enterprises prioritize first-party data activation over third-party tracking. Demand generation applications dominate bookings, though customer retention modules are accelerating as subscription businesses prioritize lifetime value metrics.
The EU AI Act and GDPR constrain automated profiling and cross-border data flows, compelling vendors to architect consent-aware campaign engines with auditable decision trails. The FCC and state-level privacy frameworks in the United States add compliance fragmentation that shapes product roadmaps and geographic feature availability. Stakeholders must monitor regulatory divergence between jurisdictions to determine whether to build unified global platforms or regionally siloed compliance editions.
Market Dynamics
The EU AI Act is forcing campaign management vendors to rearchitect automated decision engines around explainability requirements, while first-party data deprecation is compressing third-party targeting capabilities across major advertising ecosystems.
Growth Catalysts
- Retail chain consolidation:Enterprise retailers are unifying martech stacks around single-platform campaign orchestration to reduce vendor fragmentation and improve cross-channel attribution precision.
- GDPR consent automation:European enterprises are investing in consent-aware campaign engines that embed auditable decision trails directly into customer journey workflows.
- Cloud-native infrastructure:Elastic scaling capabilities are reducing capital barriers for mid-market adopters migrating from on-premise campaign systems.
Market Restraints
- Cross-border data friction:GDPR and divergent national implementations are fragmenting campaign execution across EU member states, requiring regionally siloed compliance architectures.
- Identity resolution collapse:Browser-level cookie deprecation and mobile identifier restrictions are degrading audience matching accuracy in programmatic channels.
- Talent scarcity:Shortage of engineers skilled in privacy-preserving machine learning is extending implementation timelines for AI-driven personalization modules.
Strategic Opportunities
- India's digital acceleration:TRAI's data localization mandates and surging e-commerce penetration are creating demand for compliant campaign infrastructure among domestic retail conglomerates.
- Clean room convergence:Integration of differential privacy techniques with campaign management platforms is enabling privacy-safe audience collaboration between competing advertisers.
- Subscription economy pivot:B2B SaaS vendors are expanding retention-focused campaign modules as customer lifetime value metrics displace lead volume KPIs.
Industry Challenges
- Legacy system entanglement:Enterprises running decades-old customer databases face complex data migration and schema reconciliation when modernizing campaign stacks.
- Attribution model warfare:Platform-specific measurement methodologies from major ad networks are creating conflicting performance narratives that erode C-suite confidence in campaign ROI reporting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Campaign Management Software Market |
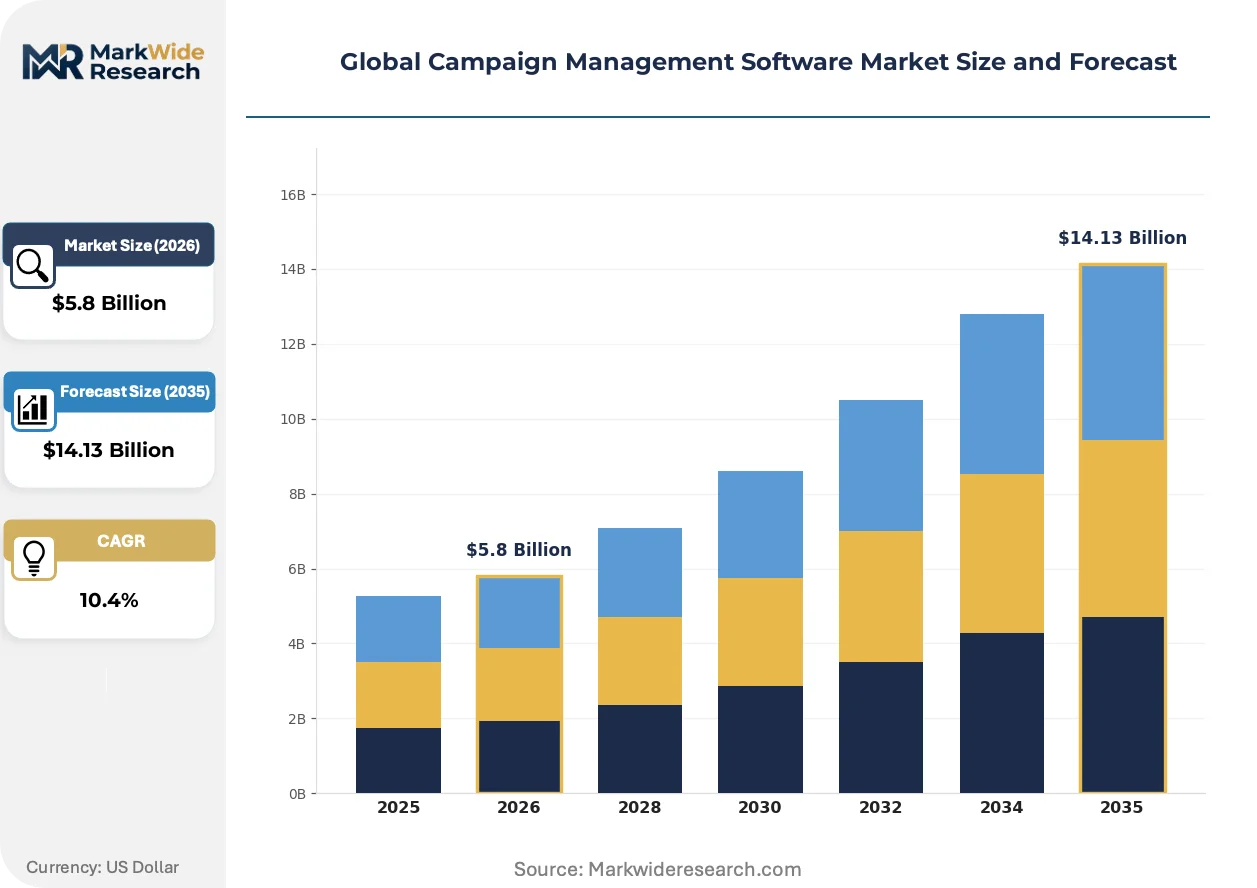
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $14.13 Billion |
| CAGR (2026 – 2036) | 10.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, Hosted Solution: Customer Analytics, Email Marketing, Social Media Management, Lead Management, Event Management Application: Demand Generation, Brand Awareness, Customer Retention, Product Launch, Market Research End User: Retail Chains, Telecommunications Firms, Financial Services, Manufacturing Corporations, Travel Agencies |
| Companies Covered | Salesforce, Adobe, Oracle, HubSpot, Zoho Corporation, IBM, SAP, Microsoft, Spotler CRM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Campaign Management Software Market Shifts & Advancements
Real-time customer data platforms are merging with campaign execution layers, collapsing the latency between insight generation and message deployment while embedding governance controls directly into operational workflows.
Composable CDP architecture is virtualizing the traditional monolithic customer database into API-first data services. Mid-market retailers and direct-to-consumer brands are adopting modular components at accelerated procurement cycles. This virtualization is compressing vendor switching costs and enabling best-of-breed stack configurations that bypass platform lock-in.
The EU AI Act's risk-based classification system is mandating human-in-the-loop review for high-risk automated profiling in consumer credit and insurance campaigns. Vendors are retrofitting decision engines with explainable AI modules that generate audit trails for supervisory authorities. Financial services advertisers in Germany and France are piloting these architectures ahead of enforcement deadlines.
Outcome-based pricing models are displacing seat-based SaaS subscriptions in enterprise negotiations. Marketing procurement teams at Fortune 500 manufacturers are tying vendor compensation to attributable revenue lifts rather than software access fees. This shift is most pronounced in the United States, where marketing operations leaders possess mature attribution infrastructure and negotiating leverage.
Global Campaign Management Software Market Segmentation
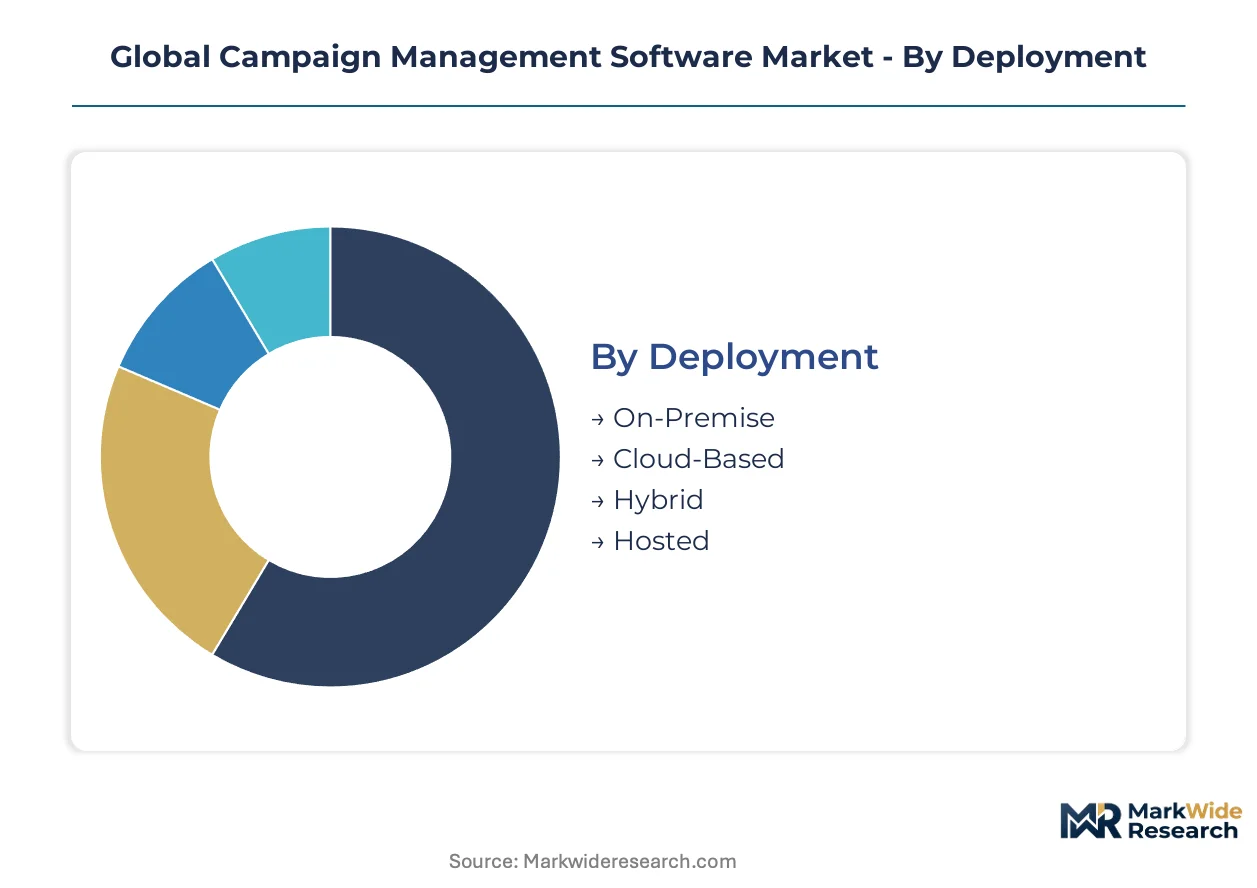
Campaign management software segments reflect divergent infrastructure maturity and data sovereignty requirements across enterprise buyers. Deployment mode determines compliance architecture, while solution type maps directly to margin capture in first-party data activation.
Deployment:
Mature cloud-native options dominate procurement cycles, though hybrid architectures are gaining traction among regulated industries.
- Cloud-Based:Elastic infrastructure enables real-time audience segmentation without capital expenditure burdens. German automotive manufacturers and US retail chains are standardizing on multi-tenant SaaS to consolidate martech vendor stacks.
- On-Premise:Single-tenant installations maintain data residency for financial services compliance. French banking conglomerates and Japanese insurance carriers mandate air-gapped campaign execution for credit product targeting under EU AI Act and local financial regulations.
- Hybrid:Split workloads process PII in private infrastructure while leveraging public cloud for anonymized analytics. UK telecommunications providers deploy this model to satisfy GDPR data localization without sacrificing computational scale.
- Hosted:Managed private cloud delivers dedicated tenancy with vendor-operated maintenance. Italian luxury retail houses prefer this model to preserve brand data exclusivity while outsourcing infrastructure operations.
Cloud-Based handles the majority of throughput; Hybrid is climbing the fastest on share as regulated sectors seek compliance flexibility.
Solution:
Customer-facing modules concentrate revenue, while backend analytics command premium pricing through data engineering scarcity.
- Customer Analytics:First-party data activation engines unify behavioral signals across touchpoints. US direct-to-consumer brands and Indian e-commerce platforms invest here as third-party cookie deprecation accelerates.
- Email Marketing:Deliverability optimization and dynamic content personalization remain workhorse applications. German B2B manufacturers rely on this channel for account-based marketing execution.
- Social Media Management:Native API integrations orchestrate paid and organic execution across platforms. Brazilian consumer goods companies prioritize this for influencer campaign coordination.
- Lead Management:Scoring algorithms and nurture workflow automation convert prospect engagement into sales pipeline. Australian SaaS vendors embed this tightly with CRM systems.
- Event Management:Virtual and hybrid experience orchestration with attendee journey tracking. UAE hospitality groups and Singapore conference organizers drive adoption here.
Customer Analytics commands the highest contract values; Lead Management is expanding most quickly as B2B subscription businesses prioritize pipeline velocity.
Application:
Demand-side use cases absorb the largest software budgets, though retention applications are displacing acquisition-focused spending in mature markets.
- Demand Generation:Multi-channel prospect acquisition campaigns with attribution modeling. US technology vendors and South Korean electronics manufacturers allocate the largest procurement budgets to this application.
- Customer Retention:Lifecycle marketing automation reducing churn in subscription businesses. Nordic telecommunications operators and Canadian SaaS providers are reorienting spend here as acquisition costs escalate.
- Brand Awareness:Reach and frequency optimization across programmatic and social channels. Mexican consumer packaged goods companies invest during market entry phases.
- Product Launch:Coordinated go-to-market orchestration with cross-functional campaign timelines. Swiss pharmaceutical firms and Israeli medical device manufacturers deploy this for regulatory-compliant launch sequencing.
- Market Research:Survey deployment and panel management integrated with campaign feedback loops. Japanese automotive suppliers use this for concept testing prior to mass marketing investment.
Demand Generation maintains the largest installed base; Customer Retention is gaining share fastest as lifetime value metrics displace lead volume KPIs.
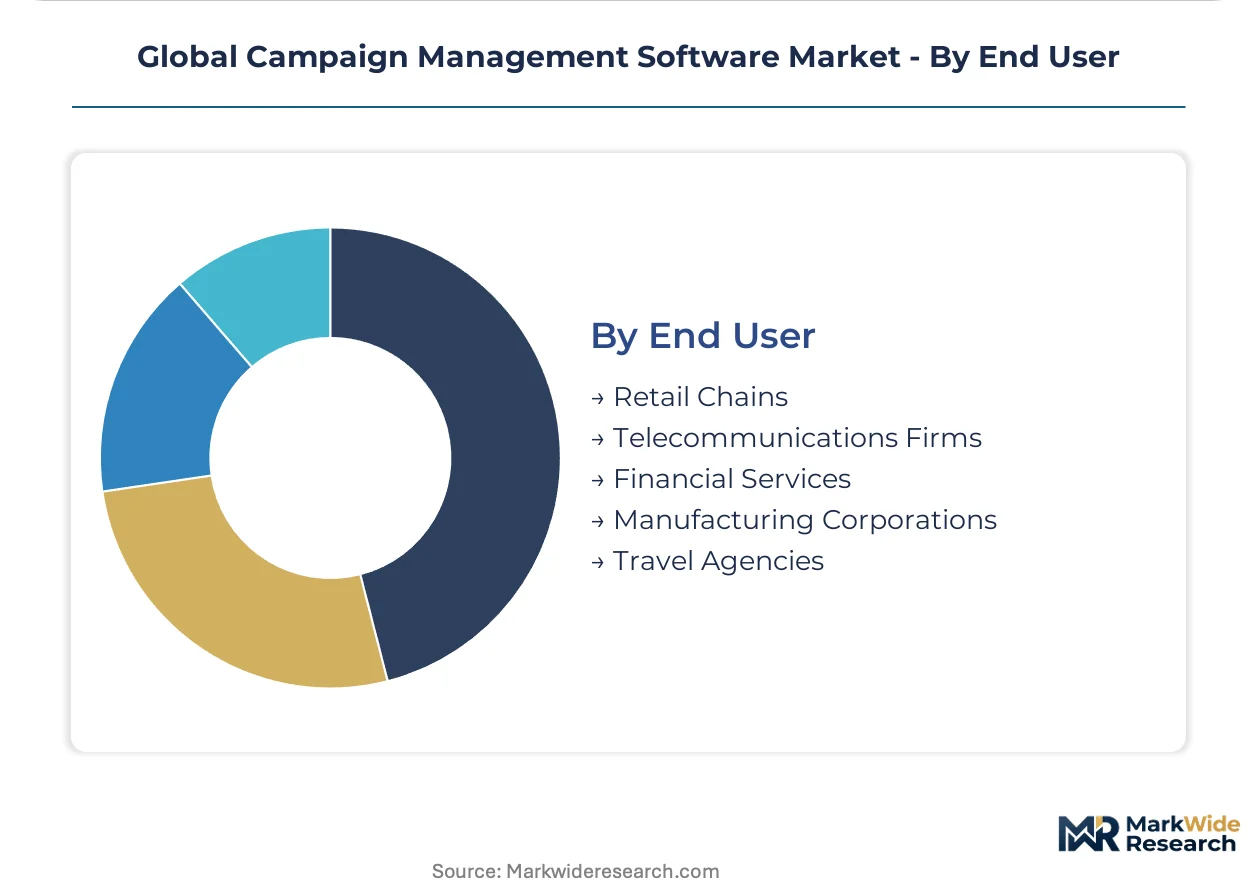
End User:
Retail concentration drives platform standardization, while financial services fragmentation creates specialized compliance requirements.
- Retail Chains:Omnichannel campaign orchestration unifying in-store and digital touchpoints. US big-box retailers and French luxury department stores are consolidating around unified execution layers.
- Financial Services:Consent-aware profiling with explainable AI audit trails for credit and insurance campaigns. German banks and Dutch insurers pilot EU AI Act-compliant architectures ahead of enforcement deadlines.
- Telecommunications Firms:Subscriber lifecycle management with churn prediction and upsell campaign automation. Indian mobile operators and Brazilian carriers invest heavily here amid price war pressures.
- Manufacturing Corporations:B2B account-based marketing with dealer and distributor co-op campaign support. Italian industrial equipment makers and Japanese precision manufacturers prioritize this segment.
- Travel Agencies:Dynamic packaging and personalized itinerary marketing with real-time inventory integration. UAE airline groups and Spanish hotel chains drive demand in this vertical.
Retail Chains account for the dominant share of platform revenue; Financial Services is expanding most steeply as regulatory compliance creates vendor switching opportunities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU AI Act enforcement deadlines and state-level privacy fragmentation in the United States are accelerating procurement of compliant campaign infrastructure. Enterprises in Germany and France pilot explainable AI architectures ahead of regulatory deadlines. India's TRAI data localization mandates and Japan's METI digital transformation incentives are expanding addressable markets for consent-aware platforms.
United States
FCC privacy frameworks and state-level regulations like CCPA are fragmenting compliance requirements across jurisdictions. Marketing procurement teams at Fortune 500 manufacturers negotiate outcome-based vendor contracts tied to attributable revenue lifts. New York and San Francisco enterprise clusters drive standardization around unified campaign execution layers.
Germany
EU AI Act high-risk profiling rules and GDPR consent automation requirements dominate vendor selection criteria. Bundesbank-supervised financial institutions mandate explainable decision trails for credit product targeting. Berlin and Munich technology corridors host pilot deployments of auditable campaign engines ahead of enforcement deadlines.
India
TRAI data localization mandates and surging e-commerce penetration create demand for compliant infrastructure among domestic retail conglomerates. RBI guidelines on customer data protection constrain cross-border campaign execution for financial services advertisers. Bangalore and Mumbai enterprise clusters invest in first-party data activation as third-party cookie deprecation accelerates.
Japan
METI digital transformation subsidies and PMDA marketing compliance frameworks shape enterprise procurement patterns. Manufacturing conglomerates in Osaka and Nagoya deploy account-based campaign modules for B2B dealer networks. Tokyo-headquartered telecommunications operators prioritize subscriber lifecycle management with churn prediction capabilities.
United Kingdom
UK GDPR divergence from EU frameworks and Financial Conduct Authority marketing conduct rules create specialized compliance requirements. Telecommunications providers in London deploy hybrid cloud architectures processing PII in private infrastructure while leveraging public cloud for anonymized analytics. Manchester and Birmingham retail chains consolidate martech stacks around single-platform orchestration.
Global Campaign Management Software Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered competitive strata. Enterprise software conglomerates anchor the premium segment through platform integration advantages, while pure-play vendors capture mid-market share through specialized workflow depth. Three archetypes dominate: ecosystem-integrated suites, vertical-specialized modules, and API-first composable layers. Consolidation momentum concentrates around strategic partnerships embedding campaign engines within broader enterprise stacks, with geographic expansion into regulated Asian markets representing the second dominant vector.
Within the ecosystem-integrated tier, Salesforce and Adobe occupy positions defined by workflow adjacency rather than standalone campaign functionality. Salesforce leverages AppExchange integration density to sustain platform stickiness across enterprise accounts, while Adobe anchors creative-to-campaign workflows that differentiate its offering from infrastructure-focused competitors. SAP exemplifies the ERP-embedded archetype, with manufacturing and retail conglomerates prioritizing data flow control through pre-existing enterprise relationships. Oracle and Microsoft represent cloud-hyperscaler entrants competing through infrastructure scale and existing productivity suite penetration. HubSpot and Zoho Corporation sit within the mid-market specialist stratum, with procurement cycles compressing as composable architecture reduces switching costs.
| Leading Market Players |
|---|
| Salesforce |
| Adobe |
| Oracle |
| HubSpot |
| Zoho Corporation |
| IBM |
| SAP |
| Microsoft |
| Spotler CRM |
| Others |
Supply & Pricing Matrix
EU AI Act compliance costs and cross-border data localization mandates determine both pricing tier spreads and supply chain shape for campaign management software vendors. The regulatory chokepoint forces architecture investments that stratify vendor economics while fragmenting infrastructure deployment across jurisdictional boundaries.
Pricing Analysis
Deployment complexity creates the primary spread between cloud-native SaaS tiers and air-gapped on-premise installations. Subscription pricing stratifies across premium, standard, and economy tiers based on consent-automation depth and explainable AI audit capabilities. Pricing pressure stems from outcome-based contracting models displacing seat-based subscriptions among Fortune 500 procurement teams. Mid-market adopters exhibit highest price sensitivity, while German financial services and Japanese insurance carriers absorb premium tiers for compliance-grade isolation.
Supply Chain Analysis
Single-source dependency on hyperscaler infrastructure in the United States, Germany, and India dominates supply chain risk for campaign management platforms. Cloud compute and storage capacity draws from Amazon Web Services, Microsoft Azure, and Google Cloud regions, with data residency requirements tethering processing to local availability zones. Tariff exposure between the United States and China threatens hardware cost structures for on-premise appliance vendors. Distribution runs through direct enterprise sales teams and systems integrator partnerships, with Accenture and Deloitte embedding campaign engines within broader digital transformation contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates around consent-aware campaign engines as EU AI Act enforcement and state-level privacy divergence create specialized vendor niches. First-party data activation demand splits procurement between integrated suites and modular best-of-breed components.
For Market Incumbents: Pre-empt composable architecture erosion by embedding explainable AI modules directly into core workflow engines before enforcement deadlines harden switching costs. Defensive consolidation through API-first acquisition targets in India's TRAI-compliant infrastructure market preserves data flow control against pure-play challengers. Vertical integration into clean room technology partnerships secures privacy-safe audience collaboration capabilities that differentiate against hyperscaler entrants. For New Entrants and Emerging Players: Pursue white-space capture in hybrid deployment architectures serving UK telecommunications providers and Italian luxury retail houses seeking GDPR-compliant elasticity without full cloud migration. India's domestic retail conglomerates present the most penetrable geography given TRAI localization mandates and limited incumbent penetration. Go-to-market positioning through outcome-based pricing with attributable revenue guarantees bypasses procurement resistance to unproven vendors. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertical-specialist modules with embedded compliance architectures over horizontal platform breadth. Long-term viability across the analysis window hinges on first-party data engineering capabilities as third-party signal deprecation accelerates. Acquisition target archetype: privacy-preserving machine learning engineering teams with EU AI Act deployment experience. Signal to watch: regulatory divergence between US state frameworks and federal preemption attempts creating compliance complexity premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Explainable AI Module Development | EU AI Act audit trail requirements in Germany and France mandate retrofitting decision engines with supervisory review capabilities. |
| Clean Room Technology Partnership | Differential privacy integration enables privacy-safe audience collaboration between competing advertisers in programmatic channels. |
| Hybrid Cloud Architecture Launch | Split workload models satisfy GDPR data localization for UK telecommunications providers without sacrificing computational scale. |
| Outcome-Based Pricing Transition | Fortune 500 manufacturers tie vendor compensation to attributable revenue lifts rather than software access fees. |
| India Market Geographic Expansion | TRAI data localization mandates and surging e-commerce penetration create demand among domestic retail conglomerates. |
Research Methodology
The analysis maps cloud-native deployment, on-premise installation, hybrid architecture, and hosted private cloud segments, each validated through CTOs, IT procurement officers, platform engineers, and channel partners. Primary interviews with marketing operations leaders at US retail chains, German automotive manufacturers, and Indian e-commerce platforms combined with secondary validation against SEC filings, hyperscaler capex disclosures, and EU regulatory enforcement notices. Bottom-up sizing of vendor bookings and top-down triangulation against enterprise software expenditure surveys anchored volume estimates.
Assumptions held fixed include EU AI Act enforcement timelines and third-party cookie deprecation schedules across major browsers, while variables included cloud adoption rates in regulated industries and outcome-based contracting penetration among Fortune 500 manufacturers. Segmentation dimensions modeled encompass deployment mode, solution type, application use case, and end-user vertical across the projection horizon. CAGRs derived from logistic diffusion curves fitted to historical martech stack consolidation patterns, with inputs from first-party data activation investment surveys and privacy-preserving machine learning talent availability indices.
Sensitivities concentrate around regulatory divergence between US state privacy frameworks and federal preemption, plus talent scarcity extending implementation timelines for AI-driven personalization modules. Forecasts reflect documented assumptions on compliance cost pass-through rates and mid-market procurement cycle compression. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Exploration and Production (E&P) Software Market
Software & Services
Job Description Management Software Market
Software & Services
Mobile Enterprise Application Development Platform Market
Software & Services
Global Online Form Builder Software Market
Software & Services
Fitness App Market
Software & Services
Global Virtual Desktop Market
Software & Services
Application Virtualization Market
Software & Services
Global Application Development Software Market
Software & Services
HACCP Software Market
Software & Services
CAM Software Market
Software & Services
Cloud Communication Platform Software Market
Software & Services
Global Online Proofing Software Market
Software & Services
UK Applicant Tracking System Market
Software & Services
Solar Rooftop Design Software Market
Software & Services
Load Balancing Software Market
Software & Services
North America Automotive Software Market