
 Radio Propagation Software Market | 2026-2036
Radio Propagation Software Market Size, Share, and Industry Trends Forecast 2026-2036
Radio Propagation Software Market Analytics
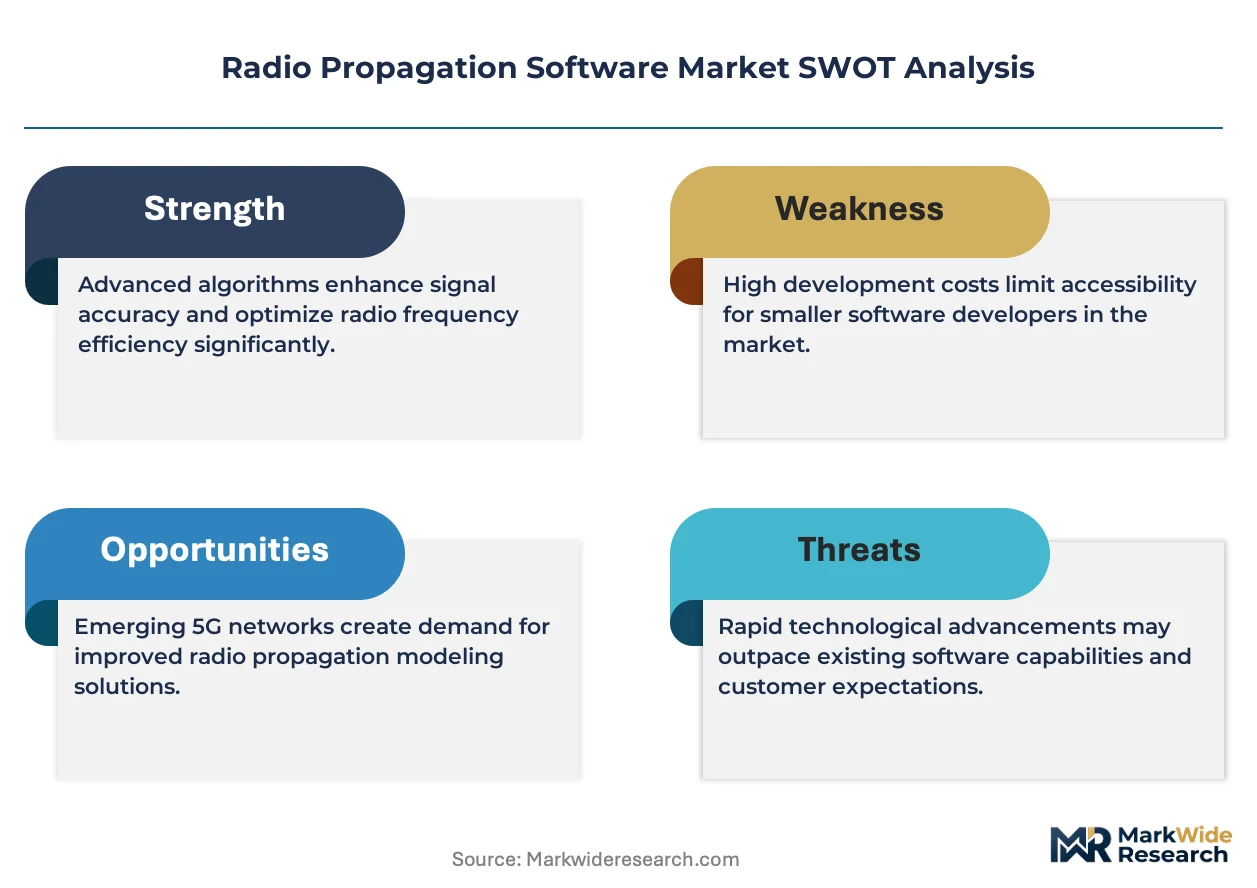
Defense and aerospace procurement is decoupling from legacy commercial telecom spending as sovereign spectrum management needs intensify. ATDI leverages its long-standing military customer base across NATO member states to sustain contract visibility. Remcom anchors its position through electromagnetic simulation specialization that extends into radar cross-section analysis. Forsk competes aggressively on price in emerging 5G private network deployments across Southeast Asia and the Middle East.
Radio propagation software comprises computational tools that model electromagnetic wave behavior across terrain, buildings, and atmospheric conditions using ray-tracing, empirical path-loss models, and full-wave solvers with frequency precision to the megahertz level. These platforms enable network planners to predict signal coverage, optimize base station placement, and ensure regulatory compliance before physical infrastructure deployment. Cloud-based deployment is gaining traction fastest among engineering firms that require elastic compute for large-scale urban modeling projects. On-premise installations still dominate government agency and defense accounts where data sovereignty requirements block external hosting. Simulation tools command the deepest margin pools due to their integration with hardware-in-the-loop testing workflows and multi-year licensing structures.
The FCC's Part 27 spectrum rules and NTIA federal coordination requirements shape product development priorities for vendors selling into US government accounts. ETSI's harmonized spectrum standards and the EU Radio Equipment Directive create compliance baselines that European vendors must embed natively. Japan's MIC technical conditions for 5G millimeter-wave deployment add another certification layer for tools targeting dense urban small-cell planning. Stakeholders must weigh sovereign data requirements against cloud scalability when selecting deployment architectures for multi-country network rollouts.
Market Dynamics
AI-native channel modeling in 3GPP Release 18 is compressing traditional empirical methods while sovereign spectrum mandates force procurement bifurcation between defense-grade and commercial tools. Vendors must now maintain dual certification tracks for NATO interoperability and civilian 5G deployment.
Growth Catalysts
- FCC Part 27 spectrum reallocation:Federal mandates for mid-band repurposing accelerate demand for millimeter-wave planning tools across US infrastructure contractors.
- 5G campus network auctions:Germany's Bundesnetzagentur licensing programs create specialized procurement pools for private industrial network designers.
- Ray-tracing acceleration:GPU-based electromagnetic solvers reduce urban simulation cycles from weeks to hours, expanding addressable use cases for engineering consultancies.
Market Restraints
- Compute cost volatility:Cloud-based full-wave simulations face unpredictable pricing from hyperscaler GPU instance rates, squeezing project margins for mid-size firms.
- Defense supply concentration:NATO-aligned certification requirements limit vendor eligibility to established military contractors, blocking new entrants from sovereign accounts.
- Legacy empirical model lock-in:Existing network operators resist migrating from Okumura-Hata calibrations despite accuracy limitations in dense urban environments.
Strategic Opportunities
- India's smart city deployments:Ministry of Urban Affairs infrastructure programs generate demand for terrain-integrated planning tools across 100 designated municipalities.
- Digital twin convergence:Integration with building information modeling platforms creates bundled service opportunities for construction-engineering consortia.
- EU Radio Equipment Directive harmonization:Cross-border certification mutual recognition reduces compliance overhead for vendors serving multiple member states.
Industry Challenges
- Computational electromagnetics talent scarcity:PhD-level expertise in full-wave solvers concentrates in academic institutions and defense labs, limiting commercial hiring pipelines.
- Multi-standard certification timelines:Simultaneous FCC, ETSI, and MIC validation requirements extend product release cycles by 8-14 months for global tool suites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Radio Propagation Software Market |
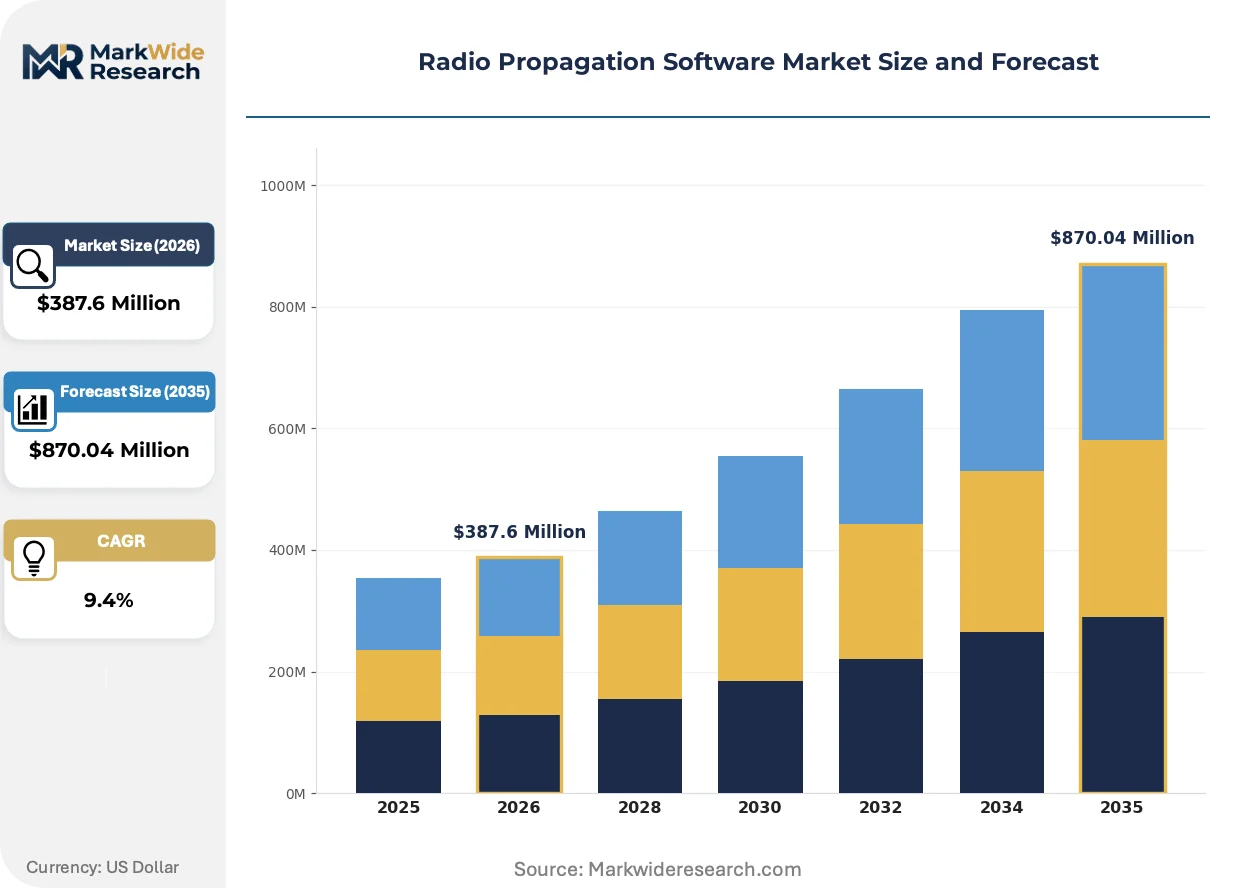
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $870.04 Million |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Simulation Tools, Planning Software, Measurement Solutions, Research Applications End User: Telecommunication Providers, Government Agencies, Research Institutes, Engineering Firms Deployment: On-Premise, Cloud-Based, Hybrid Solutions, Local Server Application: Network Design, Signal Strength Analysis, Coverage Mapping, Interference Analysis |
| Companies Covered | ATDI, Remcom, Forsk, EDX Wireless, SoftWright, Keysight Technologies, Siradel, Altair Engineering, RadioSoft, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Radio Propagation Software Market Evolving Landscape
Generative AI architectures are embedding directly into propagation workflows, compressing manual parameter tuning while regulatory fragmentation accelerates region-specific feature development. Cloud-native deployment architectures now dominate new procurement outside classified environments.
Neural network-based channel estimation is automating empirical model calibration for non-line-of-sight scenarios. Tier-one infrastructure vendors in South Korea and Japan deploy these tools for subway and stadium deployments. The technology is automating what previously required weeks of drive-test validation, collapsing network design cycles.
ETSI's harmonized spectrum standards and the EU AI Act's risk classification framework now mandate explainable propagation predictions for safety-critical applications. Automotive OEMs deploying V2X systems in Germany and France must document model traceability. Tool vendors are embedding audit trails and uncertainty quantification modules to satisfy conformity assessment bodies.
Engineering procurement teams now unbundle software licenses from mandatory training and support contracts. Large European utilities and Asian telecom operators negotiate direct API access for integration with proprietary network management platforms. This shift is most visible in Germany's industrial 5G segment, where Fraunhofer IIS reference implementations drive preference for modular, interoperable tool architectures over monolithic suites.
Radio Propagation Software Market Segmentation
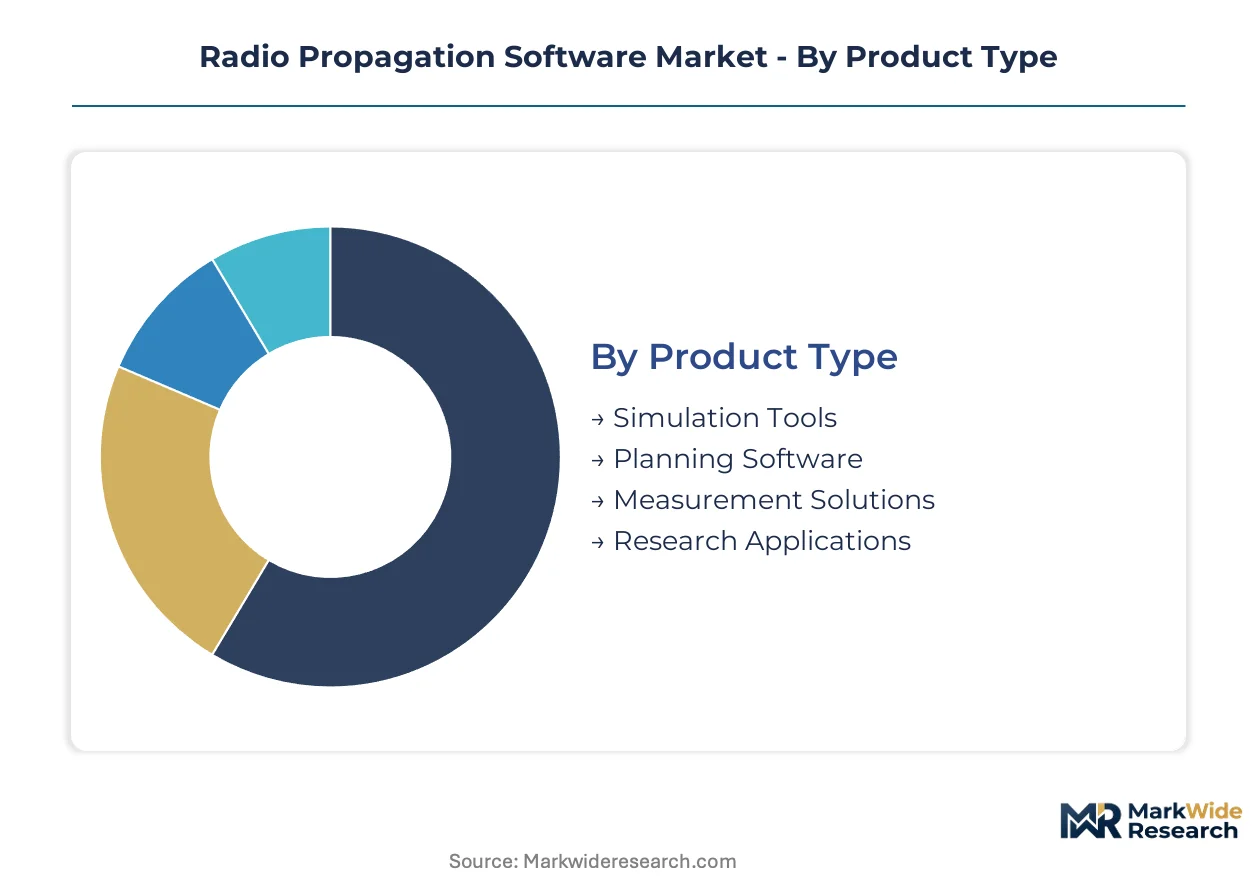
Radio propagation software segments diverge sharply by integration depth. Standalone planning tools serve discrete project workflows while embedded simulation engines power continuous network optimization platforms. Procurement patterns track this fault line: engineering firms favor modular point solutions, telecom operators demand native integration with existing infrastructure stacks.
Product Type:
Integration depth separates standalone simulation suites from embedded propagation kernels that ship inside broader network management platforms.
- Simulation Tools:Full-wave electromagnetic solvers and ray-tracing engines execute deterministic propagation modeling with frequency precision to the megahertz level. Defense agencies in Germany and France drive procurement for hardware-in-the-loop configurations that integrate with radar cross-section testing workflows. NATO interoperability certification requirements limit vendor eligibility to established military contractors.
- Planning Software:Empirical path-loss calculators and coverage optimizers target commercial network deployment cycles. Telecommunication providers in South Korea and Japan deploy these for dense urban small-cell placement where Okumura-Hata calibrations still dominate despite accuracy limitations.
- Measurement Solutions:Drive-test automation and field validation platforms from vendors like Rohde & Schwarz collapse weeks of manual data collection into hours.
- Research Applications:Academic-licensed solvers with open parameter architectures support Fraunhofer IIS and similar institutional programs.
Simulation Tools lead volumes today; Research Applications are gaining share fastest.
End User:
Customer type determines deployment architecture: classified environments mandate on-premise sovereignty while commercial operators pursue cloud elasticity.
- Telecommunication Providers:Tier-one mobile network operators in Japan and Germany operate multi-standard tool portfolios spanning 4G optimization through 5G millimeter-wave planning. MIC technical conditions and EU Radio Equipment Directive compliance requirements force simultaneous FCC, ETSI, and MIC validation cycles that extend procurement timelines.
- Government Agencies:Spectrum regulators and defense procurement offices impose data sovereignty requirements that block external hosting. The FCC's Part 27 spectrum rules and NTIA federal coordination requirements shape product development priorities for US government accounts.
- Research Institutes:Fraunhofer IIS programs and similar institutional initiatives generate specialized demand for modular, interoperable architectures over monolithic suites.
- Engineering Firms:Mid-size consultancies unbundle software licenses from mandatory training contracts and negotiate direct API access for proprietary platform integration.
Telecommunication Providers anchor current revenue; Government Agencies show the steepest expansion trajectory.
Deployment:
Architecture choice reflects data classification level and compute elasticity requirements across project scales.
- On-Premise:Air-gapped installations serve defense and intelligence community accounts where NATO-aligned certification requirements block cloud alternatives. Germany's industrial 5G segment shows persistent preference for local infrastructure despite higher capital intensity.
- Cloud-Based:GPU-accelerated electromagnetic solvers reduce urban simulation cycles from weeks to hours. Engineering consultancies in Singapore and the UAE leverage hyperscaler instances for elastic compute during large-scale modeling projects.
- Hybrid Solutions:Sensitive preprocessing executes locally while compute-intensive ray-tracing bursts to cloud instances.
- Local Server:Single-tenant configurations address mid-market firms with intermittent project volumes.
On-Premise dominates classified segments; Cloud-Based is climbing the fastest among commercial engineering procurement.
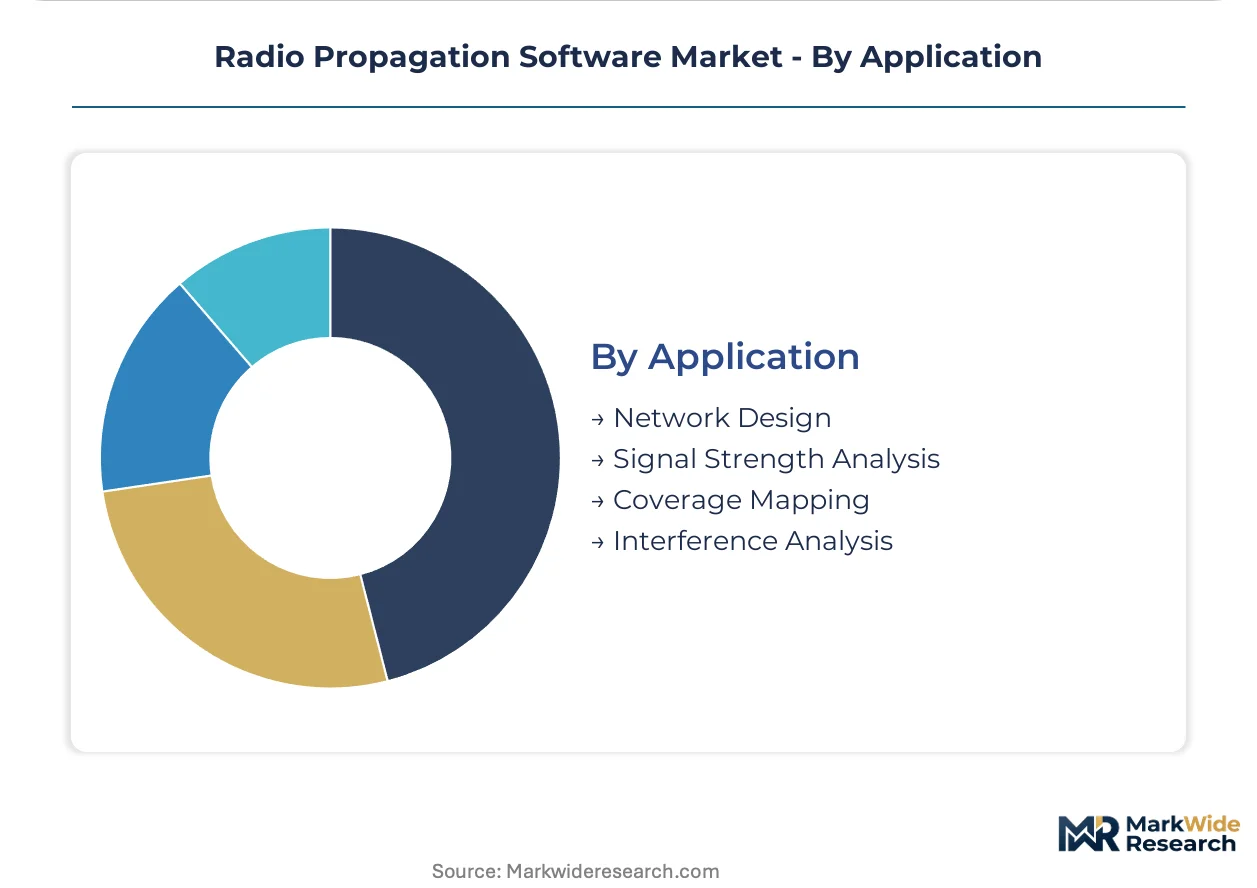
Application:
Use case maturity varies: coverage mapping commands established toolchains while interference analysis demands emerging AI-native capabilities.
- Network Design:Base station placement optimization integrates terrain databases, building information models, and atmospheric condition libraries. India's Ministry of Urban Affairs smart city programs generate demand across 100 designated municipalities for terrain-integrated planning tools.
- Signal Strength Analysis:Neural network-based channel estimation automates empirical model calibration for non-line-of-sight scenarios in subway and stadium deployments across South Korea.
- Coverage Mapping:Traditional drive-test validation workflows face displacement by predictive simulation in early project phases.
- Interference Analysis:Co-channel and adjacent-channel conflict resolution requires explainable propagation predictions under the EU AI Act's risk classification framework for safety-critical V2X applications.
Network Design commands the deepest installed base; Interference Analysis shows the most rapid technology refresh cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing procurement toward jurisdictions with harmonized certification frameworks. Vendors now optimize product roadmaps around specific national spectrum mandates rather than pursuing universal tool suites.
United States
The FCC's Part 27 spectrum reallocation and NTIA federal coordination requirements drive specialized procurement from defense contractors and infrastructure planners. Military accounts mandate NATO-aligned certification tracks that block non-aligned vendors. The Washington-Boston corridor concentrates federal system integrators upgrading legacy electromagnetic simulation stacks.
Germany
Bundesnetzagentur 5G campus network auctions and Fraunhofer IIS research programs generate concentrated demand for modular, interoperable architectures. The EU Radio Equipment Directive and AI Act's explainable prediction mandates shape product specifications. Munich and Stuttgart host industrial consortia deploying private network planning tools for automotive V2X applications.
Japan
METI and MIC technical conditions for 5G millimeter-wave deployment add certification layers for dense urban small-cell planning tools. Tier-one mobile operators operate multi-standard portfolios spanning 4G optimization through millimeter-wave rollout. Tokyo-Osaka corridor engineering firms pursue GPU-accelerated cloud solvers for subway and stadium deployments.
South Korea
Ministry of Science and ICT infrastructure programs accelerate neural network-based channel estimation adoption for non-line-of-sight scenarios. Domestic telecom operators automate drive-test validation workflows that previously required weeks of manual collection. Seoul's Pangyo Techno Valley clusters vendors integrating AI-native propagation modules into continuous network optimization platforms.
India
Ministry of Urban Affairs smart city programs across 100 designated municipalities generate demand for terrain-integrated planning tools. TRAI spectrum allocation frameworks and local content requirements influence vendor selection criteria. Bangalore and Hyderabad engineering consultancies unbundle software licenses from mandatory training contracts to negotiate direct API access.
Radio Propagation Software Market Competitive Landscape
Dual certification track maintenance dominates the current landscape as vendors split development resources between defense-grade and commercial tool suites. The vendor base concentrates around established military contractors with NATO interoperability credentials and specialized electromagnetic simulation houses with ray-tracing acceleration capabilities. Three archetypes define positioning: legacy defense contractors sustaining long-term service relationships, commercial 5G specialists competing on deployment speed, and academic spin-offs commercializing research-grade solvers. Portfolio diversification and geographic expansion through localized certification partnerships represent the dominant competitive moves.
Within the defense-contractor archetype, ATDI leverages its NATO member state footprint to sustain sovereign account visibility. Remcom anchors the specialized simulation tier through electromagnetic solver expertise that extends into radar cross-section analysis. Forsk occupies the commercial price-competitive position, targeting emerging 5G private network deployments with streamlined procurement frameworks. These three exemplify how vendor strategy diverges based on certification heritage and customer-type concentration.
| Leading Market Players |
|---|
| ATDI |
| Remcom |
| Forsk |
| EDX Wireless |
| SoftWright |
| Keysight Technologies |
| Siradel |
| Altair Engineering |
| RadioSoft |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up simulation specialists anchor supply concentration across NATO-aligned certification tracks, translating sovereign procurement requirements into disciplined pricing tiers that separate defense-grade tool suites from commercial deployments.
Pricing Analysis
Distributor margins in the 15-25% range separate hardware-in-the-loop configurations from standalone planning licenses. Pricing stratifies across NATO-certified, ETSI-compliant, and uncertified tiers based on validation depth and after-sales engineering support bundling. Cost compression in cloud-based GPU instances is intensifying because hyperscaler rate volatility squeezes project margins for mid-size engineering consultancies. Government agencies exhibit the lowest price sensitivity due to data sovereignty mandates, while Southeast Asian telecom operators negotiate aggressively on per-seat licensing.
Supply Chain Analysis
GPU compute supply rests on Taiwanese semiconductor foundries and South Korean memory producers for ray-tracing acceleration hardware. Software development draws from electromagnetic simulation talent pools concentrated in France, Germany, and the United States. Single-source vulnerability in CUDA-optimized solver libraries creates dependency risk for vendors pursuing GPU-native architectures. Distribution runs through direct enterprise sales teams for defense accounts and value-added resellers serving commercial engineering firms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in AI-native channel modeling modules, where automation of empirical calibration commands premium pricing over legacy path-loss tools.
For Market Incumbents: Hedge against neural network-based channel estimation displacement by embedding generative AI architectures into existing hardware-in-the-loop workflows. Fortify NATO interoperability certification moats through exclusive R&D partnerships with Fraunhofer IIS and similar institutional programs. Acquire specialized ray-tracing acceleration firms to consolidate electromagnetic solver talent pools. For New Entrants and Emerging Players: Mid-size Indian engineering consultancies represent the most penetrable buyer archetype, with unmet demand for terrain-integrated planning tools under Ministry of Urban Affairs smart city programs. Target API-first modular architectures that bypass monolithic suite procurement cycles. Pursue localized certification partnerships with BIS and TRAI to satisfy local content requirements. For Investors and Strategic Acquirers: Valuations sit cheapest among academic spin-offs commercializing research-grade solvers with open parameter architectures. Long-term viability hinges on dual-use technology pivots between defense and commercial 5G deployment. Watch Bundesnetzagentur campus network auction velocity as the inflection indicator for private industrial network tool demand.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Native Channel Modeling Integration | 3GPP Release 18 compliance automates empirical calibration, collapsing network design cycles for subway and stadium deployments. |
| NATO Interoperability Certification Investment | Dual-track validation unlocks sovereign defense accounts in Germany, France, and US federal procurement pools. |
| Cloud-Native Solver Architecture Migration | GPU-accelerated elastic compute addresses Singapore and UAE engineering consultancy demand for large-scale urban modeling. |
| API-First Modular Platform Development | Fraunhofer IIS reference implementations drive preference for interoperable architectures over monolithic suites in Germany's industrial 5G segment. |
| Localized Regulatory Partnership Formation | BIS and TRAI alignment satisfies India's local content requirements for Ministry of Urban Affairs smart city tool procurement. |
Research Methodology
Multiple input streams — primary interviews with network planning directors, defense procurement officers, and electromagnetic simulation R&D leads; secondary validation through FCC Part 27 filings, ETSI harmonized standards documentation, and 3GPP release specifications; plus hyperscaler capex disclosures for GPU infrastructure trends — were reconciled through bottom-up vendor revenue aggregation and top-down addressable market sizing.
Historical deployment patterns were cross-referenced against expert panel inputs spanning deployment model, end-user type, application complexity, and regional regulatory cluster segmentation. CAGRs were derived from elasticity-adjusted adoption curves incorporating AI-native channel modeling penetration rates and sovereign spectrum reallocation timelines. Forecast inputs included Bundesnetzagentur auction schedules, MIC technical condition evolution, and GPU instance pricing trajectories.
Underlying measurement precision varies by segment; on-premise defense installations carry tighter precision than emerging cloud-based commercial deployments due to classified procurement disclosure limitations. Forecasts reflect documented assumptions around 3GPP Release 18 adoption velocity and sovereign data localization enforcement intensity. A small set of triggers — FCC mid-band reallocation timing, EU AI Act conformity assessment body rulings on explainable propagation, and India's smart city program funding continuity — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
North America Telecom Expense Management Services Software Market
Software & Services
ID Photo Software Market
Software & Services
Systems Administration Management Tools Market
Software & Services
HR Management Software (Personnel and Organization) Market
Software & Services
UI Design Software Market
Software & Services
Know Your Customer Software Market
Software & Services
Testing As a Service (Taas) Market
Software & Services
B2B Gateway Software Market
Software & Services
Global Quantum Computing Software Market
Software & Services
Global Remote Desktop Management Market
Software & Services
Global Customer Success Software Market
Software & Services
Global VR Game Engine Software Market
Software & Services
Cloud Backup and Recovery Software Market
Software & Services
Global Rapid Application Development Market
Software & Services
RFP Software Market
Software & Services
CGI Software Market