
 Procurement Software Market | 2026-2036
Procurement Software Market Size, Share, and Industry Trends Forecast 2026-2036
Procurement Software Market Intelligence
The divergence in R&D investment for artificial intelligence is redrawing the lines of competition in this market. Large enterprise suite providers like SAP Ariba leverage their vast resources to embed predictive analytics into contract and spend management. In contrast, cloud-native specialists such as Coupa differentiate with user-centric design and rapid feature deployment. Procurify focuses on serving mid-market companies with streamlined purchasing workflows.
Procurement software comprises a suite of digital tools designed to automate and manage an organization's source-to-pay lifecycle. These platforms integrate modules that handle processes from vendor selection to invoice reconciliation, often using API-based architectures for interoperability. Cloud-based deployment models now dominate the market over traditional on-premises installations due to scalability and lower upfront costs. Within solution offerings, spend analysis and supplier management modules are foundational, while contract management automation represents a high-margin growth area.
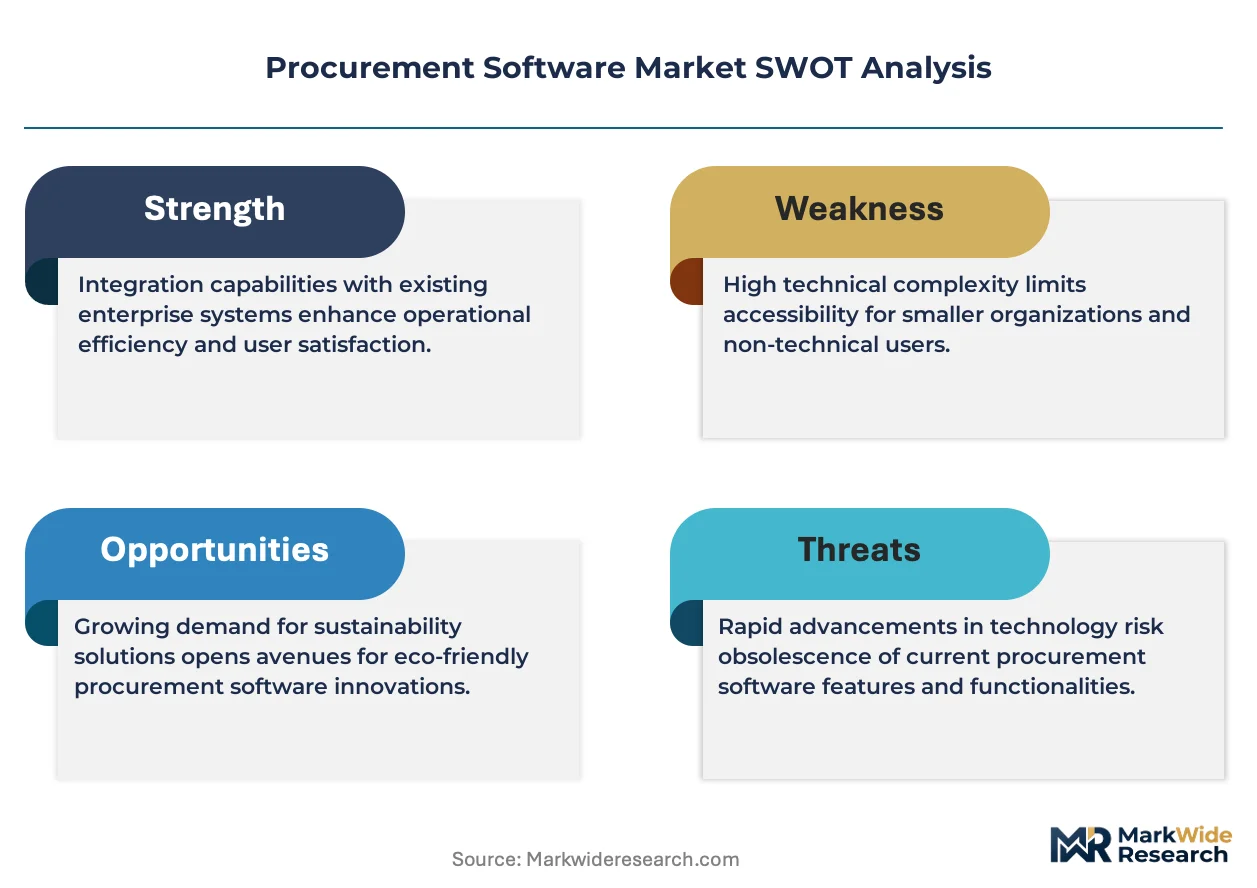
Regulatory frameworks significantly influence software feature development and adoption. The EU's General Data Protection Regulation (GDPR) mandates strict controls over supplier data, while the U.S. Sarbanes-Oxley Act (SOX) drives demand for auditable purchasing processes. These compliance requirements shape the design of contract and supplier management modules. Key vendor selection decisions will hinge on a platform’s ability to manage ESG data and mitigate third-party risk effectively.
Market Dynamics
The imperative to embed environmental, social, and governance criteria into core business operations is the central force shaping the procurement software market. Regulatory mandates and investor pressure are compelling organizations to move beyond cost savings and adopt platforms for comprehensive supplier risk and sustainability management.
Growth Catalysts
- ESG Compliance Mandates:Regulations such as the EU's Corporate Sustainability Reporting Directive (CSRD) require detailed tracking of supplier emissions and social practices, directly spurring adoption of platforms with advanced supplier information management modules.
- Manufacturing Sector Digitization:Advanced manufacturing clusters in Germany and Japan are integrating procurement software for enhanced supply chain visibility, seeking to mitigate disruption risks and improve production planning through real-time data.
- API-First Architectures:The demand for interoperability with existing enterprise resource planning (ERP) and finance systems is a significant catalyst, favoring cloud-native solutions built on flexible API-based architectures over rigid legacy platforms.
Market Restraints
- High Total Cost of Ownership:The significant upfront investment for enterprise-grade suites, encompassing licensing, complex implementation, and employee training, remains a primary barrier for many small and mid-sized enterprises.
- Data Silo Complexity:Implementation success is often hindered by fragmented data stored in disparate legacy systems across an organization, which complicates data migration and limits the effectiveness of analytics modules. *Integration Challenges with Legacy ERPs: Deeply customized on-premises ERP systems from providers like Oracle or SAP create substantial technical hurdles for integrating modern, cloud-based procurement tools, leading to extended deployment timelines.
Strategic Opportunities
- Mid-Market Penetration in Asia:There is a substantial opportunity in developing economies, particularly in Southeast Asia, where mid-market companies are beginning their digital transformation and require scalable, cost-effective procurement solutions.
- Industry-Specific Verticals:Developing tailored procurement platforms for highly regulated sectors such as pharmaceuticals or aerospace, which have unique compliance, quality, and traceability requirements, offers a path to high-margin growth.
- Generative AI Integration:Embedding generative AI into contract analysis and spend management modules to automate summary generation, identify risk, and suggest negotiation tactics presents a clear avenue for product differentiation.
Industry Challenges
- Analytical Talent Scarcity:A persistent shortage of procurement and supply chain professionals with advanced data analytics skills limits the ability of organizations to extract maximum value from sophisticated software investments.
- Supplier Onboarding Friction:The operational challenge of onboarding thousands of suppliers onto a new platform, many of whom may lack technical sophistication, can create significant delays and user adoption hurdles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Procurement Software Market |
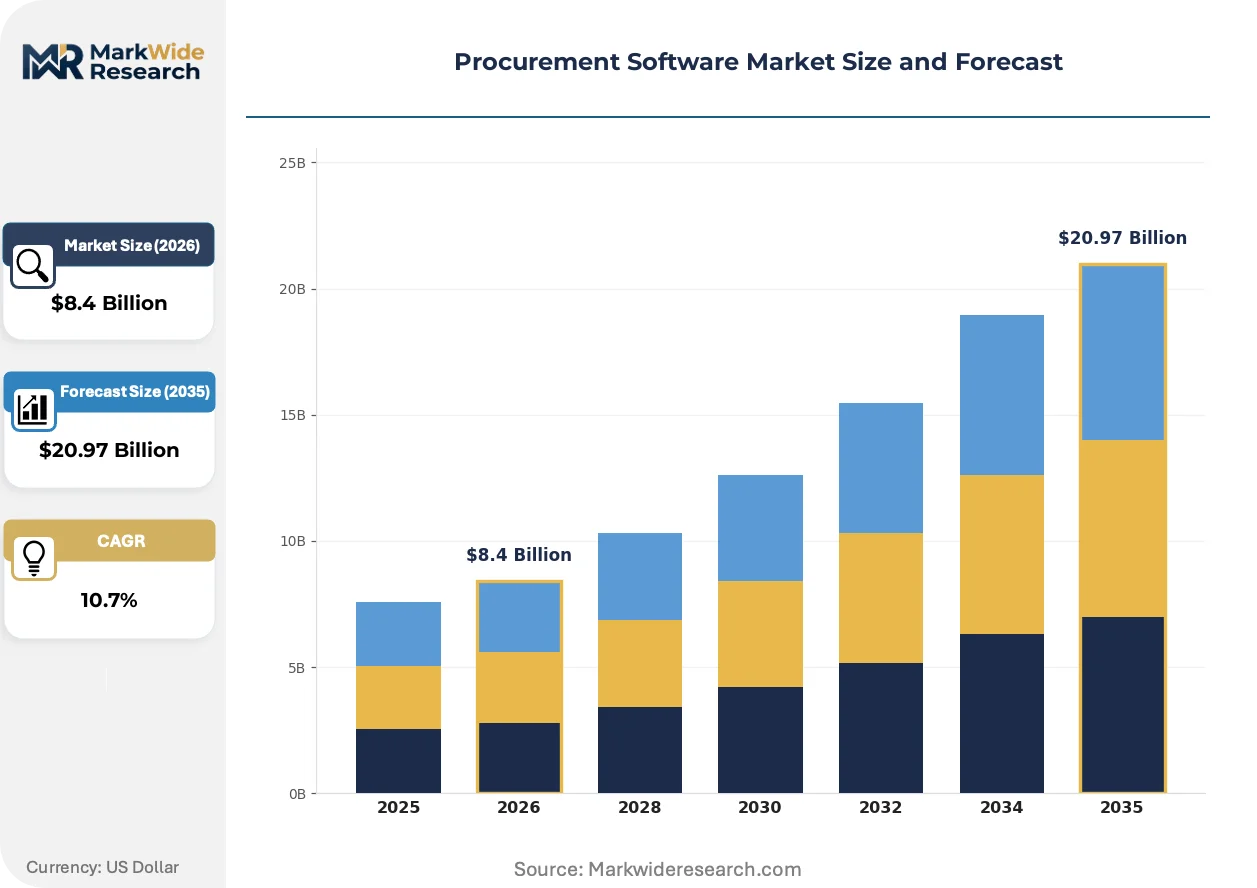
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $20.97 Billion |
| CAGR (2026 – 2036) | 10.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, Hosted Solution/Offering: Spend Analysis, Supplier Management, Contract Management, Purchase Order Management, Invoice Automation Application: Strategic Sourcing, Supplier Risk Management, Compliance Management, Inventory Optimization End User Industry Vertical: Manufacturing, Telecommunications, Government Agencies, Education Institutions, Hospitality |
| Companies Covered | Precoro, Oracle Procurement Cloud, SAP Ariba, GEP SMART, Procurify, Coupa, Vroozi, Tradeshift, Ivalua, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Procurement Software Market Strategic Shifts & Innovations
The core evolution in procurement software is the pivot from process automation to predictive intelligence. AI and machine learning are being embedded not just to streamline workflows, but to actively guide strategic decisions in sourcing, risk management, and spend optimization.
Autonomous procurement agents are software bots powered by AI to handle routine purchasing tasks without human intervention. Large enterprises in the retail and consumer goods sectors are actively piloting these agents to manage high-volume, low-value "tail spend" categories. The deployment of these bots is miniaturizing the transactional workload for human buyers, enabling them to focus on strategic sourcing and complex negotiations.
Implementation of the U.S. Uyghur Forced Labor Prevention Act (UFLPA) creates stringent new requirements for supply chain transparency. The regulation effectively requires importers to prove their goods are not connected to specific regions in China, placing the burden of proof on the company. This directly impacts software vendors, who must now enhance their supplier management modules with detailed traceability and documentation capabilities for clients in the electronics and apparel industries.
A preference for platform-based ecosystems is supplanting the traditional reliance on monolithic, single-vendor suites. This shift disrupts the legacy enterprise sales model, as procurement leaders increasingly assemble a "best-of-breed" technology stack using specialized applications connected via open APIs. This modular approach is most visible among agile, technology-forward companies in North America and Europe that prioritize flexibility and rapid innovation.
Procurement Software Market Segmentation
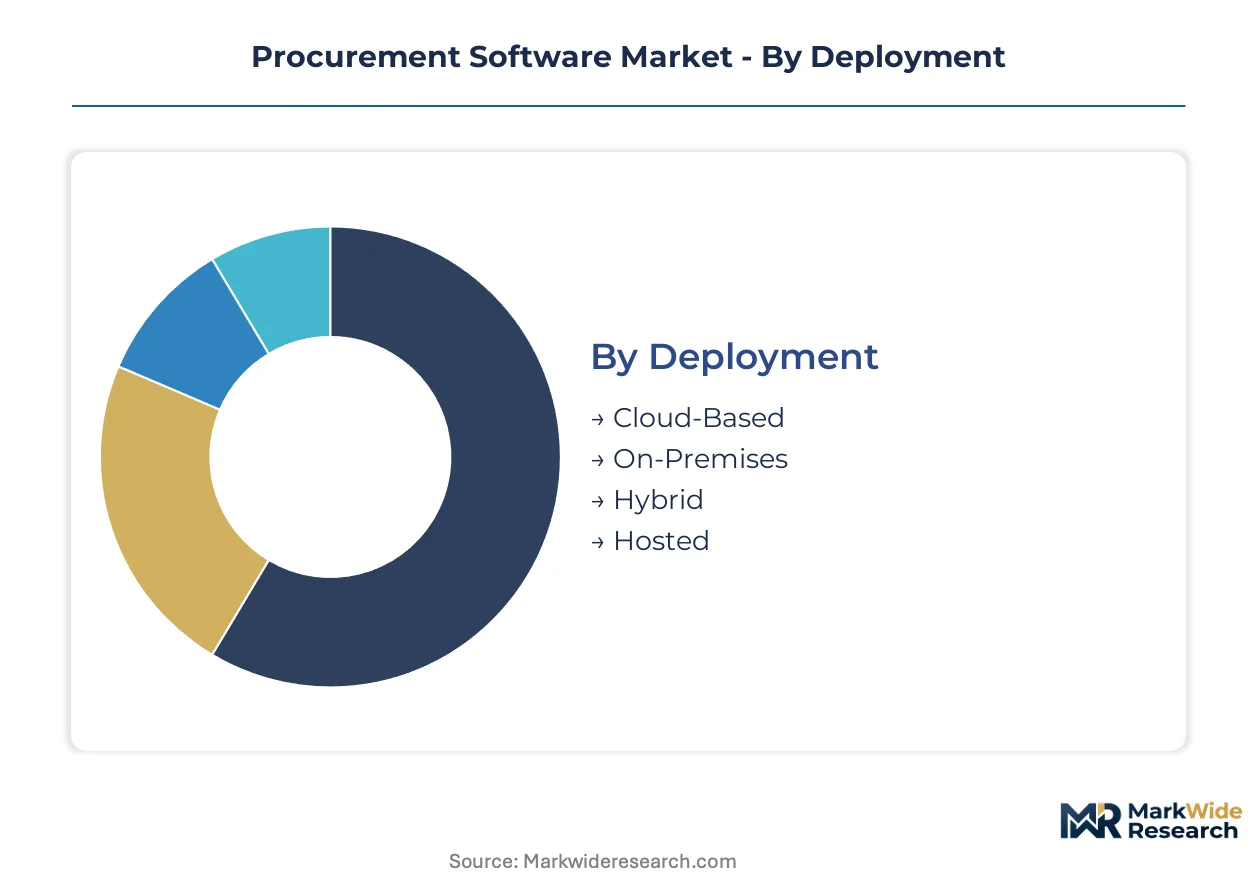
Understanding market segmentation is critical for identifying specific demand patterns and competitive pressures within the procurement software landscape. Different deployment models, solution types, application areas, and end-user industries exhibit varied growth trajectories and technological requirements.
Deployment:
The deployment segment faces significant substitution pressure, with modern cloud-based solutions rapidly displacing traditional on-premises installations. This shift reflects a broader enterprise trend towards flexible, scalable infrastructure.
- Cloud-Based:These solutions are hosted on remote servers and accessed via the internet, offering elasticity and lower upfront infrastructure costs. Demand concentrates in agile, technology-forward companies in North America and Europe, driven by the need for rapid deployment and continuous updates.
- On-Premises:Software installed and run on a company's own servers, providing full control over data and customization. Large enterprises with stringent security requirements or complex legacy systems, particularly in Germany's manufacturing sector, often retain these deployments.
- Hybrid:This model combines elements of both on-premises and cloud deployments, allowing organizations to maintain sensitive data locally while leveraging cloud services for scalability.
- Hosted:A third-party provider manages the software on their own servers, often offering more managed services than pure cloud solutions.
Cloud-Based retains volume leadership; Hybrid holds the steepest expansion curve.
Solution/Offering:
Solution offerings can be categorized by their foundational nature versus their premium, high-value capabilities. Core functionalities like spend analysis are essential, while advanced modules such as contract management drive higher margins.
- Spend Analysis:These modules collect, cleanse, and categorize an organization's purchasing data to identify cost-saving opportunities and improve budgeting. Manufacturing companies in Japan utilize these tools to optimize material costs and supplier relationships.
- Supplier Management:Platforms designed to manage vendor relationships, performance, and compliance, including onboarding, risk assessment, and communication. The EU's CSRD regulations are compelling European businesses to invest in these solutions for robust supplier tracking.
- Contract Management:Tools that automate the creation, execution, and management of contracts, including version control and renewal tracking.
- Purchase Order Management:Systems that streamline the creation, approval, and tracking of purchase orders, ensuring adherence to purchasing policies.
- Invoice Automation:Software that automates the processing of invoices, from receipt to payment, reducing manual effort and errors.
Investment priorities are shifting towards Contract Management as Purchase Order Management matures.
Application:
Procurement software applications address a range of critical business challenges, from optimizing sourcing strategies to mitigating third-party risks. Each application provides distinct value propositions to organizations seeking operational improvements.
- Strategic Sourcing:This application focuses on identifying and evaluating suppliers, negotiating contracts, and managing supplier relationships to achieve long-term cost savings and value. Companies within advanced manufacturing clusters in Germany leverage strategic sourcing for competitive advantage.
- Supplier Risk Management:Solutions that assess, monitor, and mitigate financial, operational, and reputational risks associated with an organization's supplier base. The U.S. Uyghur Forced Labor Prevention Act drives demand for these capabilities within electronics and apparel industries.
- Compliance Management:Tools that ensure purchasing activities adhere to internal policies, regulatory requirements, and ethical standards.
- Inventory Optimization:Applications that help manage stock levels, reduce carrying costs, and prevent stockouts by integrating procurement data with demand forecasting.
The integration of Strategic Sourcing with Supplier Risk Management offers enhanced operational efficiency.
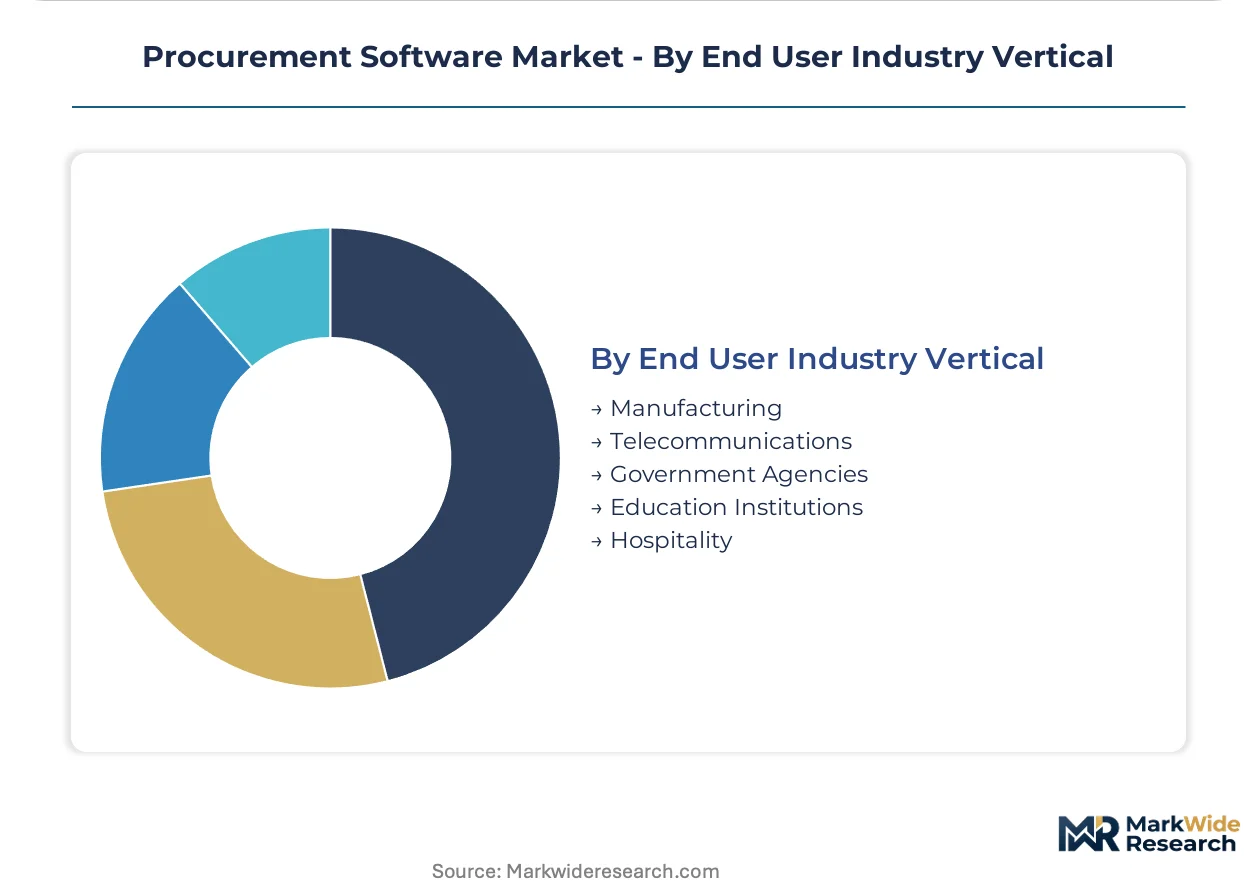
End User Industry Vertical:
The diverse needs of various end-user industries create distinct demand profiles for procurement software. Each sector requires tailored functionalities to address its unique regulatory, operational, and supply chain complexities.
- Manufacturing:This sector utilizes procurement software for enhanced supply chain visibility, production planning, and raw material sourcing. Advanced manufacturing hubs in Germany and Japan are significant adopters of these platforms.
- Telecommunications:Companies in this industry deploy procurement solutions to manage complex network equipment, services, and infrastructure contracts. These firms often require robust contract management modules.
- Government Agencies:Public sector entities use procurement software for transparent, auditable purchasing processes and compliance with specific regulations. The U.S. Sarbanes-Oxley Act influences demand for auditable systems in American government bodies.
- Education Institutions:These organizations leverage procurement platforms for managing diverse supplier bases, including academic supplies, facilities services, and IT equipment.
- Hospitality:The hospitality sector employs procurement software to manage food and beverage supplies, operating equipment, and service contracts across multiple properties.
Manufacturing drives significant platform customization, while Government Agencies represent a growing demand for tailored solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power asymmetry is evident between North American and Asian markets for procurement software. US enterprises often command premium solutions, while Asian markets prioritize cost-effective, scalable platforms. This divergence shapes vendor strategies and deployment models across continents.
United States
Demand for procurement software in the United States is driven by the need for advanced analytics and supplier risk management. The U.S. Sarbanes-Oxley Act mandates auditable purchasing processes, influencing feature development. Technology hubs like Silicon Valley actively integrate AI-powered solutions for strategic sourcing.
Germany
German manufacturers require robust procurement software for supply chain visibility and ESG compliance. The EU's Corporate Sustainability Reporting Directive (CSRD) necessitates detailed supplier tracking capabilities. Advanced manufacturing clusters in Bavaria leverage these platforms for enhanced production planning.
Japan
Japanese enterprises prioritize spend analysis and inventory optimization to maintain lean operations. METI initiatives encourage digital transformation across industrial sectors, including procurement. Manufacturing centers in Nagoya utilize these tools to optimize material costs and supplier relationships.
India
India's mid-market companies are rapidly adopting procurement solutions for digital transformation and cost efficiency. The Goods and Services Tax (GST) framework drives demand for integrated invoice automation and compliance features. Technology parks in Bengaluru are seeing increased implementation of cloud-based purchasing workflows.
China
Chinese firms seek procurement software to manage complex supply chains and navigate evolving trade regulations. Government policies supporting industrial digitization encourage the adoption of cloud-native platforms. Manufacturing hubs in the Yangtze River Delta integrate these systems for improved supplier management and risk mitigation.
Procurement Software Market Key Industry Players
Concentration sits with large enterprise suite providers offering comprehensive source-to-pay platforms. The market exhibits a tiered structure, with established players competing against agile cloud-native specialists and niche mid-market providers. Strategic archetypes include integrated suite vendors, specialized SaaS providers, and regional solution developers. Dominant competitive moves involve portfolio diversification through advanced AI integration and strategic partnerships to extend market reach.
Within the integrated enterprise suite archetype, SAP Ariba exemplifies a vendor leveraging vast resources to embed predictive analytics into contract and spend management. Coupa represents a cloud-native specialist known for user-centric design and rapid feature deployment. Procurify occupies a position serving mid-market companies with streamlined purchasing workflows, offering scalable and cost-effective solutions. These companies anchor different segments of the market, each addressing distinct customer needs and operational scales.
| Leading Market Players |
|---|
| Precoro |
| Oracle Procurement Cloud |
| SAP Ariba |
| GEP SMART |
| Procurify |
| Coupa |
| Vroozi |
| Tradeshift |
| Ivalua |
| Others |
Cost & Logistics Intelligence
Subscription-based software contracts lock in recurring revenue streams and provide predictable access to advanced procurement functionalities for enterprises. This structure ensures stability for both vendors and users, supporting continuous feature development and platform enhancements.
Pricing Analysis
Configured-to-order pricing for enterprise-grade procurement suites contrasts sharply with standardized SaaS tiers for mid-market solutions. Subscription models dominate, with price differentiation driven by the level of customization required and the depth of after-sales support. Pricing softness reflects intense competition from cloud-native specialists, particularly for foundational modules. Mid-market companies exhibit higher price sensitivity compared to large enterprises requiring extensive integration.
Supply Chain Analysis
The United States and Germany anchor the development and adoption of sophisticated procurement software, alongside Japan for lean operations. The supply chain for procurement software relies heavily on a skilled talent pool for software engineering and data science. Analytical talent scarcity represents a structural risk, limiting the effective deployment of advanced AI modules. Distribution runs primarily through direct sales teams and strategic channel partnerships with system integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market faces a capability-scarcity challenge, particularly in advanced data analytics skills required to fully leverage sophisticated procurement platforms.
For Market Incumbents: Consolidate core offerings by integrating advanced AI capabilities into existing contract and spend management modules. This approach counters the threat from agile cloud-native specialists by offering comprehensive, predictive analytics. Invest in robust data governance frameworks to manage ESG data, a critical lever for compliance-driven adoption.
For New Entrants and Emerging Players: Anchor in underserved mid-market segments in developing economies like Southeast Asia, offering cost-effective, scalable cloud-based solutions. Focus on industry-specific verticals such as pharmaceuticals, leveraging unique compliance requirements for product differentiation. A go-to-market angle emphasizing rapid deployment and user-centric design will attract digital transformation initiatives.
For Investors and Strategic Acquirers: Niche SaaS providers with specialized AI capabilities in contract analysis or supplier risk management represent attractive acquisition targets. Long-term viability depends on platforms that effectively address ESG compliance and third-party risk mitigation over a five-to-ten-year window. The signal to watch is the accelerating adoption rate of generative AI features by procurement leaders.
| Strategic Initiative | Industry Significance |
|---|---|
| AI-Powered Contract Automation | Automates summary generation and risk identification, accelerating contract lifecycle management. |
| ESG Data Integration | Enables compliance with directives like CSRD, enhancing supplier transparency. |
| Mid-Market Cloud Expansion | Captures growth in developing economies seeking scalable, affordable solutions. |
| Industry-Specific Verticalization | Tailors platforms for highly regulated sectors, driving higher-margin adoption. |
| API-First Platform Development | Ensures seamless interoperability with legacy ERP systems, reducing integration hurdles. |
Research Approach
Findings reconcile primary fieldwork against secondary review of SEC filings, industry association reports, and government regulatory documents. The study involved interviews with procurement officers, CTOs, platform engineers, and integration specialists to gather qualitative insights. Both bottom-up and top-down triangulation methods ensured data consistency and market sizing accuracy.
The analysis modeled segmentation dimensions including deployment model, solution offering, application area, end-user industry vertical, and organization size. Growth rates were derived from historical data trends and projected market drivers across the analysis window. Enterprise software spending trends and regulatory compliance budgets served as key industry-specific forecast inputs.
Decision-makers should treat outputs as directional under current market dynamics and regulatory frameworks; material deviation would warrant model refresh. Key risk factors include unforeseen rapid technological shifts in AI or significant global economic downturns. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Time and Attendance Management Software Market
Software & Services
Digital Onboarding Platform Market
Software & Services
G Suite Technology Services Market
Software & Services
Global Online Proofing Software Market
Software & Services
Global Customer Journey Mapping Software Market
Software & Services
Software As a Service (Saas) Market
Software & Services
On-Call Scheduling Software Market
Software & Services
Enterprise Mobility Software Market
Software & Services
Global Knowledge Management Software Market
Software & Services
Global Storm Tracking Apps Market
Software & Services
Systems Administration Management Tools Market
Software & Services
Global Construction Management Software Market
Software & Services
Global Third-Party Logistics Software Market
Software & Services
Global Cloud Based Collaboration Software Market
Software & Services
Tableau Services Market
Software & Services
Embedded Hypervisor Market