
 Europe Printing Software Market | 2026-2036
Europe Printing Software Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Printing Software Market Analytics
Buyer concentration among large European enterprises is consolidating as multinational corporations centralize print infrastructure under unified software platforms. HP Inc leverages its hardware-software bundling strategy to anchor enterprise accounts across Western Europe. Canon Inc competes through managed print services integration that extends software touchpoints into document workflows. PaperCut Software International Pty Ltd specializes in cross-platform print management that navigates heterogeneous IT environments common in European universities and government bodies.
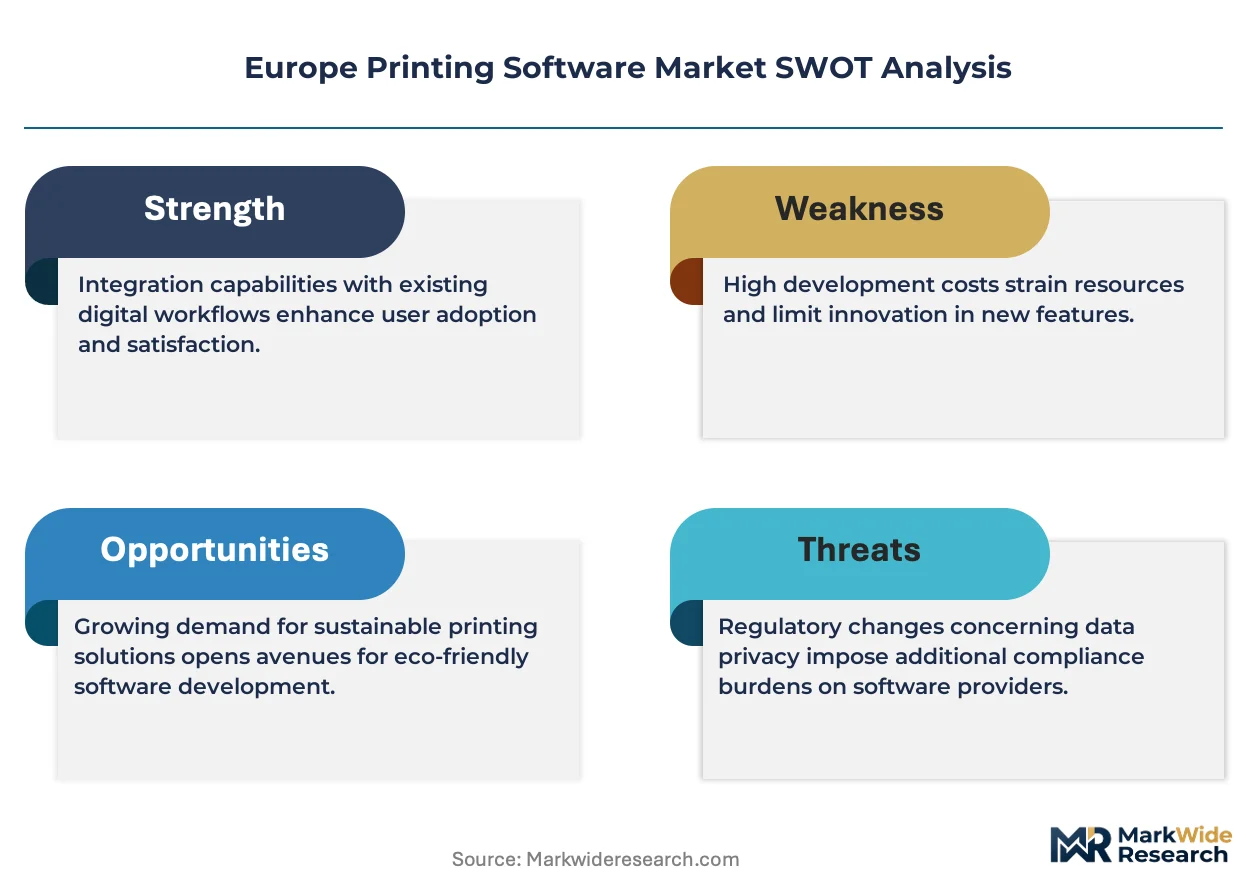
Europe printing software encompasses applications that manage, optimize, and secure document output across networked printer fleets, typically integrating print job routing, user authentication, cost allocation, and device monitoring through standardized protocols such as IPP and SNMP. The primary commercial purpose centers on reducing operational expenditure while enforcing document security and environmental compliance across decentralized organizations. Cloud-based deployment leads segment momentum as CIOs prioritize SaaS models that minimize on-premise infrastructure overhead. Print optimization solutions command attention from margin-conscious procurement teams seeking to reduce consumables waste aligned with EU sustainability directives. Workflow automation within the solution category shows accelerating traction among financial services firms in London and Frankfurt that require audit-compliant document pipelines.
REACH and RoHS frameworks constrain hardware-software bundle compositions by restricting hazardous substances in printer components, indirectly shaping software development priorities for device lifecycle management. The EU AI Act introduces emerging compliance obligations for automated document classification features embedded in advanced printing platforms. GDPR mandates govern print job data retention and user tracking functionalities, forcing vendors to engineer privacy-by-design architectures. Stakeholders must monitor how the CSRD's extended reporting requirements will expand demand for carbon footprint tracking modules within print management dashboards.
Market Dynamics
Cloud migration pressure from CIOs is compressing deployment timelines for print management vendors, forcing architectural pivots from perpetual license models toward consumption-based SaaS delivery.
Growth Catalysts
- EU Green Deal paper waste mandates:Procurement teams in German manufacturing clusters now require carbon tracking dashboards as standard RFP criteria, expanding software attach rates.
- Hybrid workforce print sprawl:Distributed employee footprints across London financial services and Paris consulting firms are driving demand for secure pull-print authentication.
- GDPR audit trail requirements:Document output logging has become a compliance necessity for healthcare networks in the Netherlands and insurance groups in Switzerland.
Market Restraints
- On-premise infrastructure sunk costs:Large enterprises in Italy and Spain face write-down friction when migrating legacy print servers to cloud-native architectures.
- Printer hardware vendor lock-in:Proprietary embedded software stacks from dominant hardware OEMs limit third-party management platform penetration in French public sector tenders.
- Skills gap in print security:European IT departments report shortages of staff trained in IPP-over-HTTPS configuration and secure pull-print deployment.
Strategic Opportunities
- CSRD carbon reporting integration:Scope 3 emissions tracking modules embedded in print dashboards will capture sustainability-driven procurement budgets in Nordic enterprise accounts.
- AI-powered document classification:Convergence of machine learning with output management creates upsell potential for automated sensitivity labeling in Frankfurt banking compliance workflows.
- Underpenetrated Eastern European SMEs:Polish and Romanian mid-market manufacturers show low existing adoption of fleet optimization tools, presenting greenfield SaaS conversion potential.
Industry Challenges
- Heterogeneous device fleet integration:Mixed-vendor printer environments common in Belgian universities and Austrian hospitals require complex driver standardization and SNMP mapping.
- EU AI Act compliance timelines:Automated document routing algorithms must undergo conformity assessment, creating product development delays for vendors embedding classification features.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Printing Software Market |
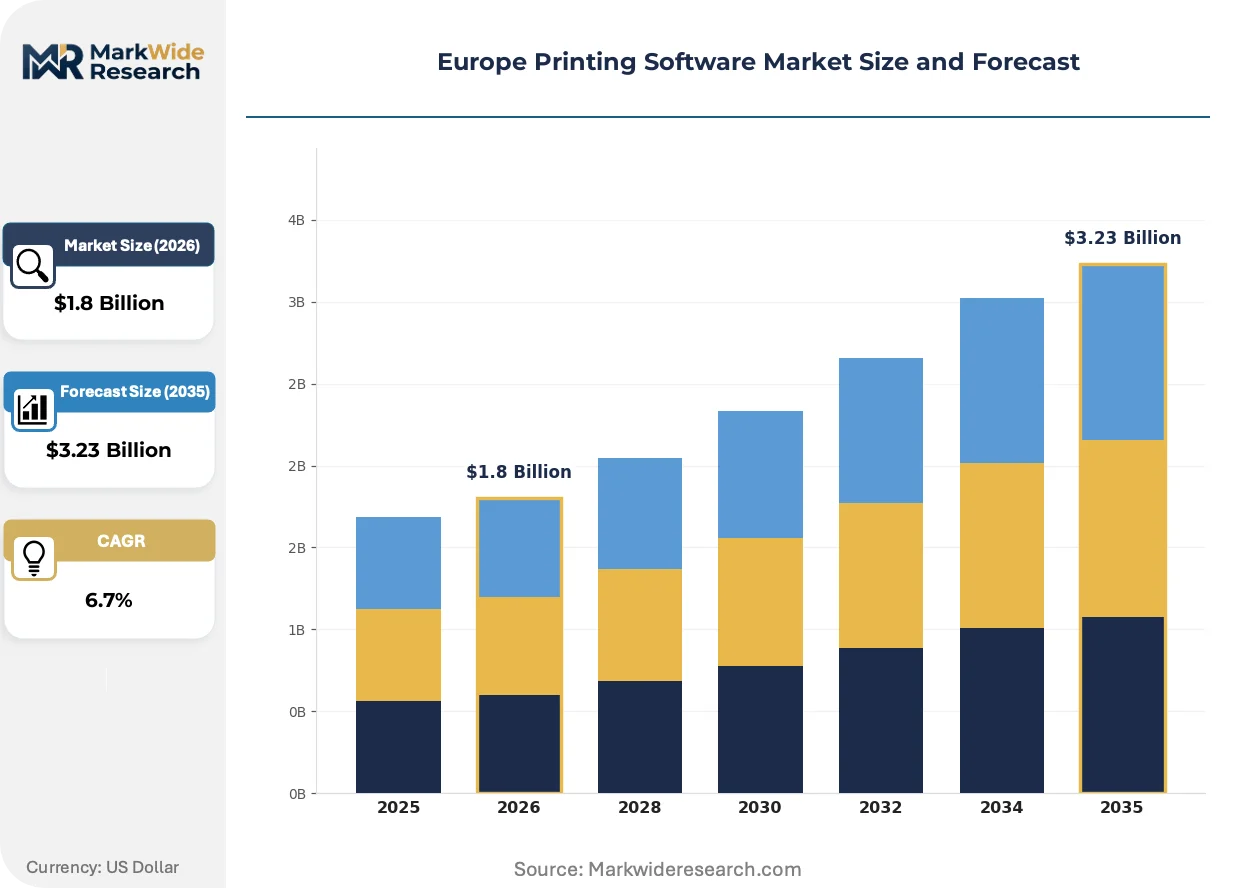
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-premise, Cloud-based, Hybrid, Remote End User: SMEs, Large Enterprises, Educational Institutions, Government Solution: Document Management, Print Optimization, Workflow Automation, Security Product Type: Desktop Software, Mobile Application, Web Application, Management Tools |
| Companies Covered | Canon Inc, HP Inc, Xerox Holdings Corp, PaperCut Software International Pty Ltd, PrinterLogic, ThinPrint GmbH, ePaper Ltd, Process Fusion, Tungsten Automation Corporation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Printing Software Market Evolving Landscape
Software-defined print infrastructure is displacing hardware-centric management paradigms, with API-first architectures enabling deeper integration into enterprise workflow stacks.
Containerized microservices architectures for print job processing are modularizing deployment options for mid-market customers. German automotive suppliers and Dutch logistics firms are adopting these modular stacks to isolate authentication, routing, and accounting functions. This modularizing trend compresses vendor switching costs and accelerates feature release cycles.
REACH substance restrictions and RoHS hazardous material limits are reshaping hardware-software bundle economics. Printer OEMs must now engineer software modules that extend device lifecycle visibility to meet circular economy reporting. French electronics distributors and Italian office equipment lessors are prioritizing vendors with integrated asset retirement tracking.
Subscription-based consumption models are displacing perpetual license purchases among procurement functions. British higher education institutions and Scandinavian municipal governments now specify monthly active user pricing in competitive tenders. This shift concentrates vendor relationships with platforms demonstrating clear total cost of ownership reduction within 18-month evaluation windows.
Europe Printing Software Market Segmentation
Segmentation in Europe printing software reveals how deployment architectures, user scale, and functional requirements reshape procurement priorities. Vendors must align pricing models and integration complexity to distinct capital expenditure profiles across German manufacturing floors, UK financial services towers, and Nordic municipal networks.
Deployment:
Cloud-based configurations demand the lowest upfront capital outlay, while on-premise installations require substantial server infrastructure and IT staffing investments.
- On-premise:Perpetual licensing with dedicated server farms dominates Italian and Spanish enterprises with legacy print infrastructure. Sunk hardware costs and specialized IT headcount requirements create migration friction for CIOs evaluating SaaS alternatives.
- Cloud-based:Subscription models eliminate capital expenditure for server procurement and reduce IT overhead. German automotive suppliers and Dutch logistics clusters prioritize this architecture for rapid fleet scaling across distributed manufacturing sites.
- Hybrid:Mixed architectures preserve sensitive document processing on-premise while routing standard jobs through cloud queues. Belgian healthcare networks and Austrian hospital systems deploy this model to balance GDPR data sovereignty with operational flexibility.
- Remote:Edge-deployed agents manage print resources for home-office workforces without VPN tunneling. London consulting firms and Paris professional services groups adopted these configurations during workforce dispersal mandates.
Most installed capacity flows through on-premise legacy stacks. Expansion is steepest in cloud-based delivery.
End User:
Procurement sophistication varies sharply by organizational scale, with large enterprises commanding volume discounts and SMEs prioritizing per-seat economics.
- Large Enterprises:Centralized procurement functions negotiate enterprise-wide platform licenses spanning multi-country operations. Frankfurt banking groups and Zurich insurance conglomerates mandate API-first architectures for ERP integration.
- SMEs:Mid-market manufacturers in Poland and Romania exhibit low existing adoption of fleet optimization tools, presenting greenfield conversion potential for SaaS vendors with simplified onboarding.
- Educational Institutions:British universities and Scandinavian technical colleges require cross-platform compatibility for heterogeneous device fleets accumulated through decades of ad-hoc purchasing.
- Government:French public sector tenders and German municipal procurement frameworks specify carbon tracking dashboards and circular economy reporting as mandatory evaluation criteria.
Large enterprises anchor current revenue concentration. SMEs are gaining share fastest as vendor pricing models compress to serve mid-market budgets.
Solution:
Functional depth determines integration complexity, with workflow automation requiring the most extensive API development and security modules demanding ongoing threat response investment.
- Print Optimization:Consumables tracking and job routing algorithms reduce paper waste and toner expenditure. German manufacturing procurement teams now require embedded carbon footprint modules to satisfy EU Green Deal compliance obligations.
- Workflow Automation:Document pipeline orchestration with audit trail generation serves compliance-heavy sectors. Financial services firms in London and Frankfurt deploy these tools for regulatory reporting and transaction documentation.
- Document Management:Repository integration and version control for printed output archives. Healthcare networks in the Netherlands utilize these capabilities for patient record retention mandated by national data protection authorities.
- Security:Pull-print authentication and encryption protocols protect sensitive output in distributed environments. Swiss insurance groups and Luxembourg wealth managers prioritize these features for client confidentiality assurance.
Print optimization commands the largest installed base. Workflow automation is climbing the fastest as compliance requirements tighten.
Product Type:
Development resource allocation shifts dramatically by interface modality, with mobile applications requiring continuous OS compatibility testing and web applications demanding scalable backend infrastructure.
- Management Tools:Administrative dashboards for fleet monitoring and policy enforcement. IT departments at Scandinavian municipal governments specify these interfaces for centralized oversight of dispersed printer populations.
- Web Application:Browser-based submission portals eliminate client-side installation requirements. British higher education institutions favor this delivery mode for device-agnostic student access.
- Desktop Software:Native client installations with deep OS integration for driver management. Legacy enterprise environments in Italy and Spain maintain these deployments for compatibility with specialized output devices.
- Mobile Application:Smartphone-based job submission and secure release authentication. Hybrid workforces across Paris consulting firms and Amsterdam creative agencies drive adoption for location-independent printing.
Management tools process the highest transaction volumes. Mobile applications are expanding most quickly as workforce mobility patterns stabilize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands deeper print infrastructure investment than France, though both markets accelerate cloud migration under divergent procurement frameworks. The EU Green Deal and GDPR enforcement reshape software requirements unevenly across national regulatory implementations.
Germany
Automotive suppliers in Baden-Württemberg and North Rhine-Westphalia drive fleet optimization procurement tied to carbon reporting mandates. The KBA enforces circular economy documentation standards that extend software lifecycle tracking obligations. Munich industrial corridors now require embedded Scope 3 emissions modules as standard tender criteria.
United Kingdom
London financial services firms prioritize workflow automation for audit-compliant document pipelines amid FCA scrutiny. The Information Commissioner's Office enforces strict print job data retention limits under UK GDPR derivations. Edinburgh and Manchester professional services clusters adopt secure pull-print authentication for hybrid workforces.
France
Public sector tenders in Île-de-France specify proprietary hardware-software bundles that constrain third-party platform penetration. ANSM and CNIL jointly govern healthcare document output logging requirements. Lyon and Marseille municipal procurement frameworks mandate carbon tracking dashboards for circular economy compliance.
Netherlands
Healthcare networks in Randstad cities deploy hybrid architectures balancing GDPR data sovereignty with cloud operational flexibility. The Dutch Data Protection Authority enforces stringent user tracking limitations on print management systems. Eindhoven logistics clusters adopt containerized microservices for distributed manufacturing site scaling.
Poland
Mid-market manufacturers in Silesian and Greater Poland voivodeships exhibit low existing fleet optimization adoption, presenting greenfield SaaS conversion potential. The Polish Financial Supervision Authority extends audit trail requirements to insurance document workflows. Kraków and Wrocław emerging tech corridors attract vendor expansion targeting underpenetrated SME segments.
Europe Printing Software Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across fragmented procurement channels. Hardware-software bundling from printer OEMs anchors enterprise accounts, while independent vendors penetrate heterogeneous IT environments through cross-platform compatibility. Three archetypes dominate: integrated hardware-software providers, managed print services platforms, and standalone cloud-native specialists. M&A activity concentrates on SaaS capability acquisition, while geographic expansion targets Eastern European greenfield accounts.
Within the hardware-integrated tier, HP Inc and Canon Inc occupy positions exemplifying enterprise bundling strategies. PaperCut Software International Pty Ltd represents the independent specialist archetype navigating mixed-vendor environments common in universities and government bodies. These three anchors illustrate the competitive tension between proprietary ecosystem control and open-platform flexibility that shapes procurement outcomes across German automotive corridors and British higher education institutions.
| Leading Market Players |
|---|
| Canon Inc |
| HP Inc |
| Xerox Holdings Corp |
| PaperCut Software International Pty Ltd |
| PrinterLogic |
| ThinPrint GmbH |
| ePaper Ltd |
| Process Fusion |
| Tungsten Automation Corporation |
| Others |
Value Network & Pricing Analysis
EU Green Deal paper waste mandates gate qualified supply and premium-tier pricing access for vendors serving German automotive suppliers and French public sector buyers. Procurement teams now embed carbon tracking dashboards as mandatory RFP criteria, forcing software providers to absorb compliance development costs or forfeit high-margin enterprise contracts.
Pricing Analysis
Capacity additions in cloud-native SaaS architectures are reshaping price floors for print management platforms across Europe. Three-tier pricing structure across premium, standard, and economy levels segments by integration complexity and API depth, with Frankfurt banking groups and Zurich insurance conglomerates commanding volume discounts while Polish SME manufacturers exhibit acute price sensitivity. Cost compression in standard-tier subscriptions is intensifying because hyperscaler infrastructure commoditizes backend delivery. German automotive procurement teams show least price sensitivity when carbon reporting modules demonstrate Scope 3 compliance.
Supply Chain Analysis
Domestic-content mandates under EU circular economy frameworks are reshaping sourcing for hardware-software bundles in French public sector tenders. Software development concentrates in Germany, the United Kingdom, and Australia, with cloud infrastructure feeding from Irish and Dutch hyperscaler regions. Raw material dependencies span semiconductor components for embedded printer controllers, rare earth elements for imaging hardware, and cobalt for battery-backed edge devices. Single-source vulnerability runs through proprietary embedded stacks from dominant printer OEMs. Distribution runs through direct enterprise sales teams and managed print service provider channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through SaaS conversion of legacy perpetual-license installed bases, with subscription economics capturing lifetime value from previously one-time transactions.
For Market Incumbents: Extend API-first architecture investments to anchor ERP integration requirements from Frankfurt banking groups and London financial services firms. Consolidate position through backward integration into containerized microservices stacks that accelerate feature release cycles. Counter emerging cloud-native specialists by embedding CSRD carbon reporting modules as standard rather than premium-tier offerings.
For New Entrants and Emerging Players: Cloud marketplace distribution routes unlock rapid scaling without field sales infrastructure investments. Target underpenetrated Polish and Romanian mid-market manufacturers with simplified onboarding workflows and per-seat pricing below incumbent enterprise floors. Penetrate through mobile-first authentication modules that address hybrid workforce print sprawl in Paris consulting firms and Amsterdam creative agencies.
For Investors and Strategic Acquirers: Roll-up economics work for standalone cloud-native specialists because fragmented SME adoption across Eastern Europe lacks category consolidation. Five-to-ten-year viability hinges on SaaS retention metrics exceeding legacy perpetual-license churn patterns. Monitor AI-powered document classification feature penetration in Frankfurt compliance workflows as inflection indicator for premium-tier pricing power.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API-first architectures satisfy ERP connectivity mandates from Zurich insurance conglomerates. |
| Acquisition of Specialist Firm | Containerized microservices capabilities compress deployment timelines for Dutch logistics clusters. |
| Geographic Expansion | Eastern European SME penetration captures greenfield SaaS conversion in Polish manufacturing corridors. |
| Product Launch | CSRD-embedded carbon dashboards satisfy mandatory tender criteria in French municipal procurement. |
| Strategic Partnership | Hyperscaler alliances reduce infrastructure costs for mid-market subscription pricing competitiveness. |
Research Methodology
Direct dialogue with CIOs, IT procurement officers, managed print service providers, and platform integration specialists anchored qualitative findings. Secondary validation drew from SEC filings of listed printer OEMs, EU tender documentation databases, hyperscaler capex disclosures, and GDPR enforcement case registers. Bottom-up and top-down triangulation cross-checked vendor shipment estimates against enterprise software spending surveys.
Bottom-up modeling projected adoption curves by deployment architecture, organization size, vertical sector, integration complexity, and regional regulatory cluster. Top-down validation anchored aggregate market sizing to IT services spending benchmarks and enterprise software growth patterns across the analysis window. CAGR derivation incorporated cloud migration velocity assumptions, EU Green Deal compliance timeline acceleration, and AI feature penetration rates in financial services document workflows.
The model assumes a particular technology adoption path; alternative pathways for edge-deployed print agents would alter the outlook if VPN-less home-office infrastructure becomes preferred over cloud queue routing. Forecasts reflect assumptions about GDPR enforcement consistency and EU AI Act conformity assessment timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
PLM Software Market
Software & Services
Global Software Composition Analysis Market
Software & Services
Quick Service Restaurants (QSR) IT Market
Software & Services
EDA Tools Market
Software & Services
Collaborative Whiteboard Software Market
Software & Services
Global Distribution Software Market
Software & Services
Asia-Pacific Digital Signage Software Market
Software & Services
Global Server Management Software Market
Software & Services
Computational Medicine and Drug Discovery Software Market
Software & Services
Waterway Transportation Software Solutions Market
Software & Services
Japan IT Services Market
Software & Services
Global User Research and User Testing Software Market
Software & Services
Preschool Education Software Market
Software & Services
Spain HR Payroll Software Market
Software & Services
MCAD Software Market
Software & Services
North America IT Services Market