
 Embedded Graphical User Interface (GUI) Development Software Market | 2026-2036
Embedded Graphical User Interface (GUI) Development Software Market Size, Share, and Industry Trends Forecast 2026-2036
Embedded Graphical User Interface (GUI) Development Software Market Foresight
Automotive-grade HMI certification is rotating toward ISO 26262-aligned toolchains as OEMs demand functional safety guarantees for instrument clusters. Qt Company leverages its automotive design-studio footprint across European and Asian OEM programs. NXP Semiconductors anchors its software strategy through tight integration with its i.MX application processor roadmaps. Rightware specializes in real-time 3D rendering engines purpose-built for digital cockpit consolidation.
Embedded GUI development software comprises toolchains, libraries, and design environments that generate pixel-accurate, resource-constrained interfaces for microcontrollers and application processors, typically operating within 16 MB to 512 MB RAM budgets and requiring deterministic frame rates below 33 milliseconds. Cross-platform solutions now dominate new license growth as engineering teams seek single-codebase deployment across Linux, QNX, and RTOS targets. Automotive end-user demand leads absolute revenue contribution, while medical devices represents the fastest-expanding margin pool due to FDA validation requirements and extended support contracts.
FDA 21 CFR Part 820 quality-system requirements and EU MDR software classification rules shape validation documentation burdens for medical device GUIs, directly influencing vendor R&D allocation toward pre-certified component libraries. IEC 62304 medical software lifecycle standards and ISO 13485 quality management further segment the competitive landscape between general-purpose and vertically certified tool providers. Stakeholders must monitor whether functional safety certifications become a mandatory procurement filter beyond automotive into industrial machinery and clinical equipment segments.
Market Dynamics
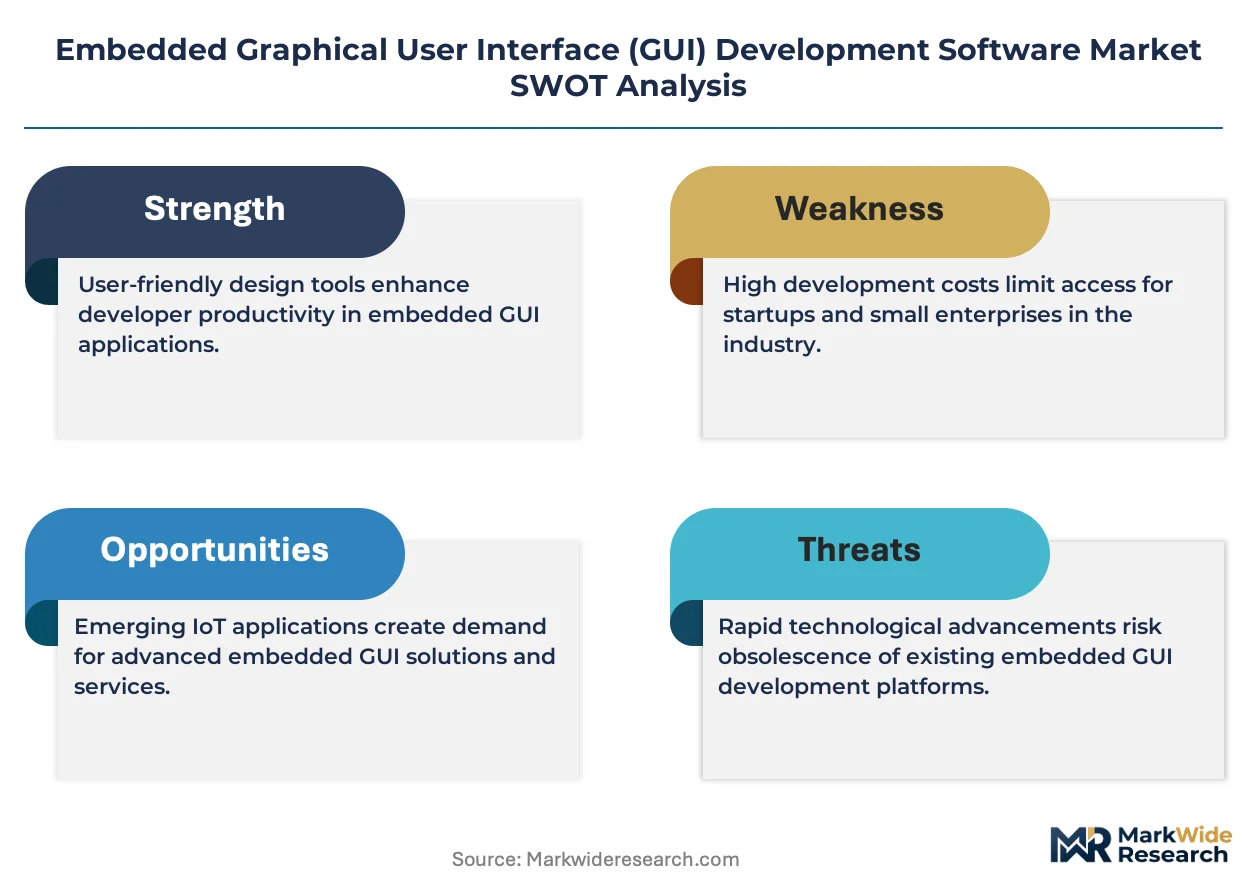
Automotive OEM consolidation around digital cockpit architectures is compressing vendor qualification cycles while elevating functional safety certification from preference to procurement prerequisite.
Growth Catalysts
- EU AI Act compliance mandates:Connected vehicle interface requirements are accelerating validation-toolchain procurement across Stuttgart and Munich supplier clusters.
- Medical device software classification:FDA 21 CFR Part 820 and EU MDR documentation burdens are extending support contract durations for GUI component libraries.
- Cross-platform deployment economics:Single-codebase toolchains spanning Linux, QNX, and RTOS targets are reducing per-platform engineering overhead.
Market Restraints
- Silicon supply concentration:Tight i.MX and comparable application processor allocation is constraining software-hardware co-development timelines.
- Certification cost escalation:ISO 26262 functional safety toolchain qualification is adding six-figure validation expenditures per OEM program.
- RTOS fragmentation:Proprietary real-time operating system ecosystems are fragmenting driver development and raising porting costs.
Strategic Opportunities
- Industrial machinery safety migration:IEC 61508 certification requirements for human-machine interfaces are expanding addressable market beyond automotive.
- India medical device manufacturing:CDSCO and BIS quality system alignment is creating demand for pre-certified GUI components in diagnostic equipment.
- Edge AI interface convergence:Neural network accelerator integration with rendering pipelines is enabling predictive HMI personalization.
Industry Challenges
- Functional safety engineer scarcity:ISO 26262 and IEC 62304 certified developers command premium compensation and extended recruitment cycles.
- Legacy instrument cluster migration:Mechanical gauge replacement programs require pixel-perfect behavioral replication under deterministic timing constraints.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Embedded Graphical User Interface (GUI) Development Software Market |
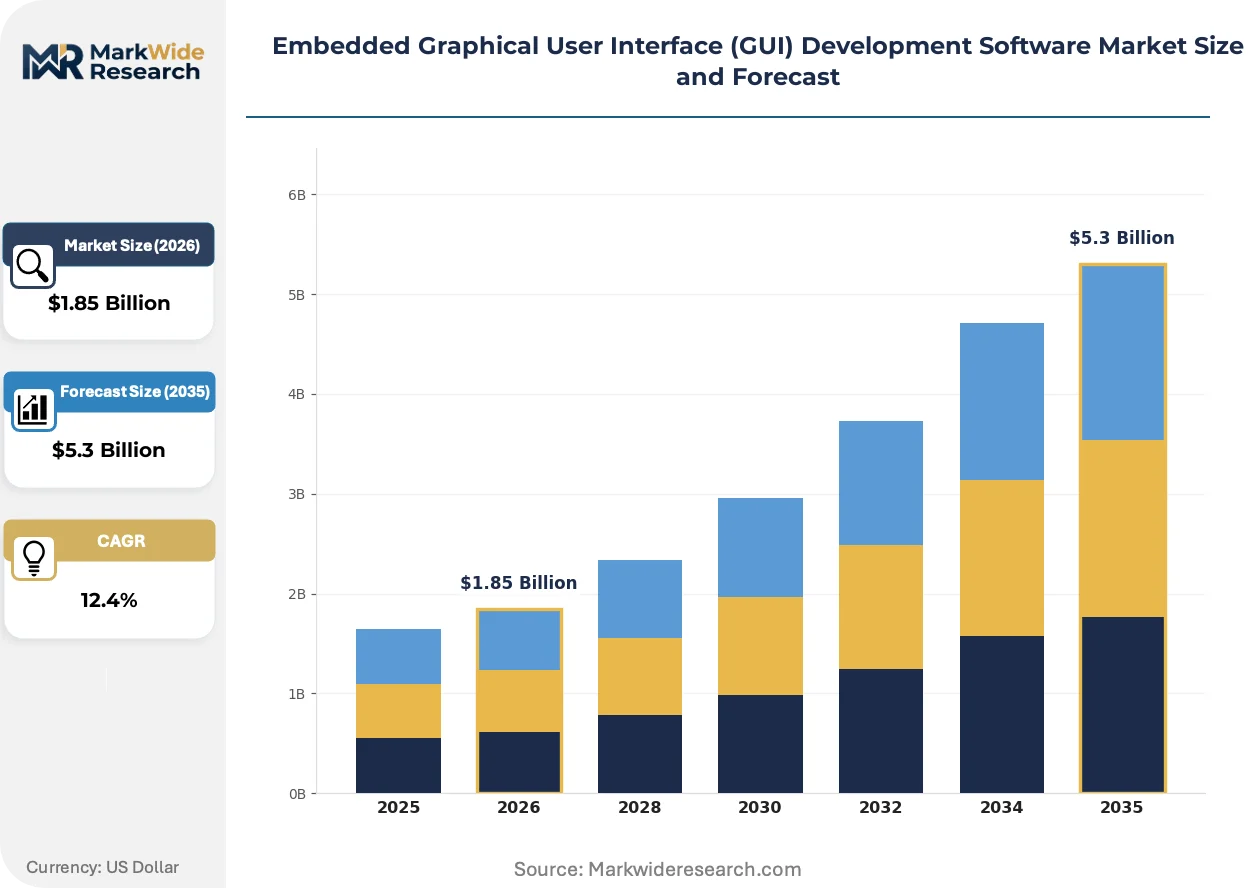
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $5.3 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Native Software, Web-Based Tools, Cross-Platform Solutions, Frameworks Development Language: C++, Java, Python, JavaScript End User: Automotive, Consumer Electronics, Medical Devices, Industrial Machinery User Experience: Touchscreen Interfaces, Voice-Controlled Systems, Gesture-Based Controls, Adaptive GUIs |
| Companies Covered | STMicroelectronics, Analog Devices, Qt Company, Microchip Technology, Embarcadero Technologies, The MathWorks, NXP Semiconductors, Rightware, Microsoft Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Embedded Graphical User Interface (GUI) Development Software Market Shifts & Advancements
Real-time 3D rendering engines are consolidating multiple display surfaces into unified digital cockpit experiences while regulatory frameworks harden software liability boundaries.
Vector graphics acceleration hardware is displacing raster-based rendering pipelines in resource-constrained microcontroller deployments. Tier-1 suppliers in Germany are adopting GPU-accelerated SVG engines for instrument clusters below 128 MB RAM budgets. This displacement is compressing middleware licensing models toward per-unit royalties rather than upfront toolchain fees.
EU AI Act algorithmic transparency requirements are mandating explainable interface logging for safety-critical automotive functions. OEMs must now document decision pathways rendered on driver displays during automated system interventions. German KBA type-approval processes are incorporating these documentation standards into homologation checklists.
Subscription-based design tool licensing is replacing perpetual seat purchases among mid-tier automotive suppliers. Cloud-hosted collaborative environments are displacing on-premise asset management for distributed engineering teams. This shift is most visible in Asian OEM programs where engineering partners span multiple time zones.
Embedded Graphical User Interface (GUI) Development Software Market Segmentation

Segmentation in embedded GUI development software reveals how certification requirements, resource constraints, and interface modalities fragment procurement patterns across automotive, medical, and industrial verticals. Engineers select toolchains based on deterministic timing guarantees, safety integrity levels, and silicon target compatibility rather than generic usability metrics.
Product Type:
Substitution pressure from open-source alternatives concentrates most intensely on framework and web-based offerings, where community-supported libraries erode commercial licensing value.
- Cross-Platform Solutions:Single-codebase deployment spanning Linux, QNX, and RTOS targets eliminates per-platform engineering duplication. Automotive OEMs in Germany and Japan prioritize these toolchains for digital cockpit programs requiring functional safety certification alignment.
- Native Software:Purpose-built compilers and linkers optimize binary size for microcontrollers operating below 64 MB RAM. Medical device manufacturers in the United States specify native toolchains to satisfy FDA 21 CFR Part 820 traceability requirements for Class II diagnostic equipment.
- Web-Based Tools:Browser-hosted design environments enable distributed engineering collaboration across time zones. Asian OEM programs leverage cloud-hosted asset pipelines for supplier coordination.
- Frameworks:Pre-certified widget libraries accelerate ISO 26262 and IEC 62304 validation documentation. Industrial machinery OEMs adopt safety-certified frameworks to compress IEC 61508 compliance timelines.
Cross-Platform Solutions retain volume leadership; Native Software holds the steepest expansion curve.
Development Language:
Cost tier stratification separates memory-safe languages commanding premium engineering rates from legacy codebases requiring specialized maintenance expertise.
- C++:Deterministic memory management and hardware abstraction layer access dominate automotive instrument cluster development. Stuttgart-based Tier-1 suppliers mandate C++17 or later for ASIL-B and above applications.
- JavaScript:WebAssembly compilation targets enable browser-grade interfaces on resource-constrained edge devices. Consumer electronics manufacturers in South Korea deploy JavaScript-based rendering for smart appliance touchscreens.
- Python:Rapid prototyping workflows accelerate medical device GUI validation cycles before C++ porting for production. Diagnostic equipment startups in India leverage Python for iterative design-test loops.
- Java:Android Runtime compatibility drives adoption for infotainment systems requiring Google Automotive Services integration. Cross-platform abstraction layers reduce driver development overhead.
C++ dominates automotive procurement; JavaScript is climbing fastest in consumer electronics.
End User:
Application-specific certification burdens create divergent margin structures, with medical and automotive verticals absorbing validation costs that consumer segments reject.
- Automotive:Digital cockpit consolidation demands real-time 3D rendering with deterministic frame rates below 33 milliseconds. KBA type-approval processes in Germany now incorporate EU AI Act algorithmic transparency documentation for automated system interfaces.
- Medical Devices:FDA 21 CFR Part 820 and EU MDR software classification rules extend support contract durations for pre-certified component libraries. Extended validation timelines sustain premium pricing for IEC 62304-aligned toolchains.
- Industrial Machinery:IEC 61508 functional safety requirements for human-machine interfaces expand addressable market beyond automotive. Safety integrity level certification drives procurement decisions for operator panels.
- Consumer Electronics:Volume scale and rapid refresh cycles prioritize development velocity over certification depth. Smart home device manufacturers optimize for BOM cost rather than safety documentation.
Automotive commands absolute revenue contribution; Medical Devices shows the steepest margin expansion.
User Experience:
Maturity differentials separate established touchscreen deployments from emerging modalities requiring sensor fusion and inference hardware integration.
- Touchscreen Interfaces:Capacitive multi-touch with haptic feedback dominates instrument cluster and medical monitor deployments. GPU-accelerated SVG engines displace raster pipelines in sub-128 MB RAM budgets.
- Adaptive GUIs:Machine learning-driven interface personalization adjusts information density based on driver cognitive load or patient alert status. Edge AI accelerator integration enables predictive HMI adaptation.
- Voice-Controlled Systems:Natural language processing pipelines require acoustic model optimization for automotive cabin noise profiles. Cloud-edge hybrid architectures balance latency against vocabulary flexibility.
- Gesture-Based Controls:Time-of-flight camera integration enables touchless interaction for sterile medical environments. Industrial safety applications leverage gesture recognition for hands-free machinery operation.
Touchscreen Interfaces retain deployment volume leadership; Adaptive GUIs command the steepest R&D investment trajectory.

Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies. Medical device manufacturers in the United States absorb premium toolchain costs for FDA validation, while consumer electronics producers in South Korea prioritize per-unit licensing minimization. German automotive suppliers occupy the middle ground, trading cost for functional safety certification depth.
United States
FDA 21 CFR Part 820 compliance drives procurement of pre-certified GUI component libraries for diagnostic equipment. Class II medical device software classification rules extend vendor support contract durations. Boston and San Diego clusters concentrate diagnostic imaging HMI development.
Germany
KBA type-approval processes mandate EU AI Act algorithmic transparency documentation for automated vehicle interfaces. ISO 26262 functional safety toolchain qualification adds six-figure validation expenditures per OEM program. Stuttgart and Munich Tier-1 supplier clusters anchor European digital cockpit development.
China
MIIT cybersecurity certification frameworks tighten software validation for connected vehicle interfaces. GB standards alignment pressures domestic GUI toolchain vendors toward automotive-grade certification. Yangtze River Delta electronics manufacturing bases absorb cross-platform solutions for smart appliance touchscreens.
Japan
METI industrial safety guidelines elevate IEC 61508 certification requirements for human-machine interfaces in factory automation. JIS standards segmentation creates procurement filters between general-purpose and safety-certified tool providers. Nagoya automotive engineering corridors consolidate instrument cluster HMI programs.
India
CDSCO and BIS quality system alignment generates demand for pre-certified GUI components in diagnostic equipment manufacturing. PLI scheme incentives attract medical device production to domestic facilities. Karnataka and Telangana electronics manufacturing clusters scale embedded software engineering capacity.
Embedded Graphical User Interface (GUI) Development Software Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the embedded GUI development software market. Semiconductor-integrated software vendors leverage silicon roadmaps for co-development lock-in, while independent design-tool specialists command premium positioning through functional safety certification depth. Three archetypes dominate: silicon-anchored platform vendors, safety-certified toolchain specialists, and cross-platform abstraction layer providers. Consolidation pressure is accelerating through strategic partnerships between semiconductor manufacturers and design-environment vendors, alongside vertical integration of rendering engines into application processor reference designs.
Within the semiconductor-anchored tier, NXP Semiconductors and STMicroelectronics exemplify platform vendors integrating software strategy with silicon roadmaps. Qt Company occupies a position among independent toolchain specialists serving automotive and industrial certification requirements. These three entities represent the dominant competitive anchors spanning silicon-to-software integration, functional safety depth, and cross-platform deployment economics.
| Leading Market Players |
|---|
| STMicroelectronics |
| Analog Devices |
| Qt Company |
| Microchip Technology |
| Embarcadero Technologies |
| The MathWorks |
| NXP Semiconductors |
| Rightware |
| Microsoft Corporation |
| Others |
Supply & Pricing Matrix
Twenty-six-week lead times for ISO 26262-certified toolchain validation concentrate pricing power among Stuttgart and Munich suppliers, compressing margins for second-tier vendors unable to absorb six-figure qualification expenditures. This inventory-to-certification lag anchors procurement decisions toward pre-certified component libraries, elevating after-sales support contracts as the dominant lifetime value driver.
Pricing Analysis
Extended support and validation documentation services now generate higher lifetime value than initial licensing fees. Three-tier pricing structure across premium, standard, and economy levels separates ASIL-D certified automotive toolchains from industrial-grade and consumer electronics offerings. Cost compression in the economy tier intensifies as open-source alternatives erode basic framework licensing. Medical device manufacturers show least price sensitivity due to FDA 21 CFR Part 820 documentation burdens, while consumer electronics OEMs prioritize per-unit royalty minimization.
Supply Chain Analysis
TSMC advanced node allocation for automotive-grade application processors constrains software-hardware co-development timelines across Germany, Japan, and South Korea. The embedded GUI toolchain ecosystem draws from NXP i.MX and STMicroelectronics silicon roadmaps, pre-certified widget libraries, and cloud-hosted design environments. Single-source vulnerability concentrates around German Tier-1 supplier clusters for functional safety certification. Distribution runs through direct OEM program engagements rather than channel intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Embedded GUI development software functions as a service-attach opportunity where validation documentation and extended support contracts expand faster than perpetual license sales. Recurring revenue from FDA and EU MDR compliance services now outpaces new seat growth.
For Market Incumbents: Shield market position by deepening functional safety certification depth beyond automotive into IEC 61508 industrial machinery segments. Acquire specialist rendering engine capabilities to consolidate digital cockpit toolchain offerings. Open-source framework substitution threatens mid-tier licensing value; counter through pre-certified component library bundling. For New Entrants and Emerging Players: Post-certification support gaps in Indian medical device manufacturing present the most penetrable white-space target. CDSCO and BIS quality system alignment creates demand for validation documentation services that incumbents under-serve. Pursue partnership-based entry with Karnataka and Telangana electronics manufacturing clusters rather than direct OEM engagement. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because FDA 21 CFR Part 820 and EU AI Act compliance burdens deepen moats around certified toolchain providers. Target acquisition profiles center on IEC 62304-aligned medical software specialists and GPU-accelerated rendering engine developers. Monitor EU AI Act implementation timelines as the critical inflection signal for validation-toolchain demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Functional Safety Certification Expansion | IEC 61508 alignment opens industrial machinery HMI procurement beyond automotive concentration. |
| Pre-Certified Component Library Development | FDA 21 CFR Part 820 traceability requirements compress validation timelines for Class II device manufacturers. |
| Cloud-Hosted Collaborative Design Environment | Asian OEM programs with distributed engineering teams displace on-premise asset management. |
| GPU-Accelerated Vector Graphics Integration | SVG engine displacement of raster pipelines enables sub-128 MB RAM instrument cluster deployment. |
| Edge AI Interface Convergence | Neural network accelerator integration enables predictive HMI personalization for adaptive GUIs. |
Research Methodology
A spread of perspectives from automotive platform engineers, medical device regulatory affairs leads, Tier-1 supplier procurement managers, and industrial machinery safety officers converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against SEC filings, EU MDR guidance documents, FDA 510(k) clearance databases, and automotive production registration data. Bottom-up license volume estimates triangulated against top-down OEM R&D expenditure analysis.
Segmentation dimensions modeled span product type, development language, end-user vertical, and user experience modality across the projection horizon. Deployment model, safety integrity level, and silicon target compatibility formed additional analytical layers. CAGRs derived from historical license growth patterns, OEM program pipeline visibility, and regulatory implementation timelines. Automotive digital cockpit consolidation velocity and medical device software classification rule evolution served as key forecast inputs.
Forecasts assume regulatory continuity in FDA 21 CFR Part 820, EU AI Act, and EU MDR enforcement regimes; material policy shifts would require re-modeling validation documentation demand curves. Practitioners should keep alternative scenarios live as EU AI Act algorithmic transparency implementation and MIIT cybersecurity certification evolution unfold.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Embedded Software Market
Software & Services
Backend-As-A-Service Market
Software & Services
Business Analytics Software Market
Software & Services
Saas-Based Expense Management Market
Software & Services
Global Personalisation Software Market
Software & Services
Neurodiverse Workforce Productivity Tools Market
Software & Services
Scanning and Migration Software Market
Software & Services
Global Construction Punch List Software Market
Software & Services
Global Professional Service Automation (PSA) Software Market
Software & Services
Cloud Enterprise Application Software Market
Software & Services
Email Marketing Software Market
Software & Services
Europe Workforce Management Software Market
Software & Services
Global Auto Dealer Software Market
Software & Services
Newsroom Software Market
Software & Services
Orchestration Tools Market
Software & Services
Metal Recycling Software Market