
 Server Operating System Market | 2026-2036
Server Operating System Market Size, Share, and Industry Trends Forecast 2026-2036
Server Operating System Market Intelligence
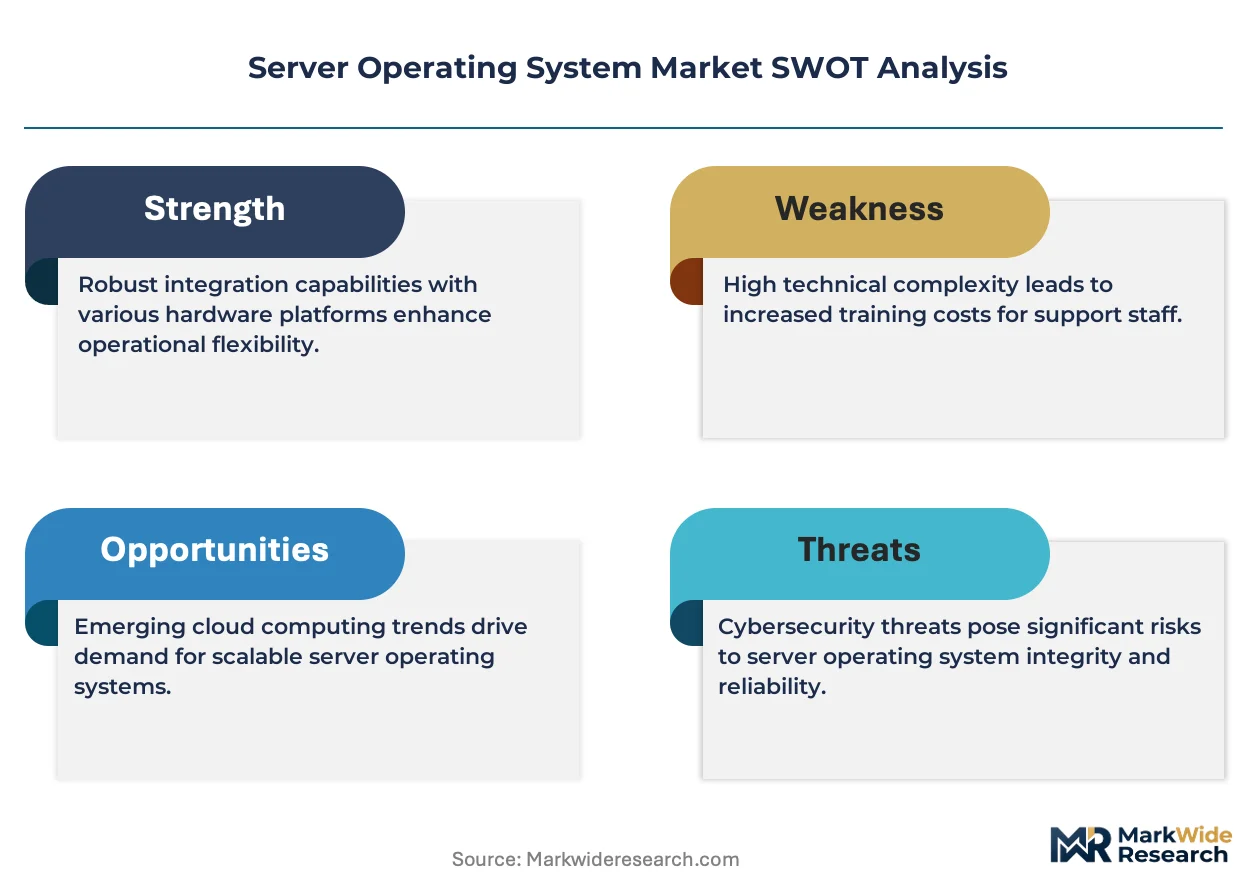
Linux kernel expertise is bifurcating the talent pool into enterprise distribution specialists and cloud-native container engineers, constraining legacy data center expansion while unlocking edge and hybrid deployments. Microsoft Corporation sustains dominance in enterprise directory-integrated environments through Windows Server's Active Directory ecosystem. Red Hat Inc. leads commercial open-source subscription models with RHEL's security certification portfolio. Canonical Ltd. specializes in lightweight, cloud-optimized Ubuntu Server editions for hyperscale operators.
A server operating system is system software that manages hardware resources, provides core services such as process scheduling, memory allocation, and network protocol stacks, and supports multi-user access with privilege isolation typically through POSIX-compliant or NT kernel architectures. Its primary purpose is to host applications, databases, and virtualized workloads with uptime guarantees measured in months between reboots. Linux distributions command the highest volume in cloud and HPC installations due to licensing flexibility and kernel customization depth. Windows Server retains margin concentration in regulated enterprises dependent on Microsoft-centric productivity stacks. Hybrid deployment architectures are expanding fastest as organizations maintain on-premises sovereignty while bursting to public cloud capacity.
FCC guidelines on communications infrastructure resilience, EU NIS2 Directive mandates for essential entity software patching, and Japan's METI cybersecurity framework for critical infrastructure collectively elevate compliance costs while creating procurement preference for certified distributions. ISO 27001 and Common Criteria certification now function as market access gates for government and financial sector tenders. Stakeholders must monitor whether sovereign AI compute initiatives fragment kernel standardization or reinforce consolidated vendor ecosystems.
Market Dynamics
Kernel specialization is fragmenting talent pools as hyperscalers demand container-optimized distributions while regulated enterprises cling to certified legacy stacks, creating parallel supply constraints and premium pricing tiers.
Growth Catalysts
- EU NIS2 Directive:Mandatory patching timelines for essential entities are accelerating refresh cycles for certified distributions in critical infrastructure operators.
- AI training clusters:GPU-dense data centers are consuming bare-metal Linux deployments at unprecedented density, pulling specialized kernel engineering talent toward cloud-native optimization.
- Sovereign cloud mandates:Germany's Gaia-X specifications and Japan's METI cybersecurity framework are disqualifying non-certified vendors from government tenders.
Market Restraints
- Kernel engineer scarcity:Deep expertise in real-time scheduling and memory management is concentrating among hyperscale employers, inflating enterprise hiring costs.
- Certification lag:Common Criteria EAL4+ validation cycles extend 18-24 months, freezing product roadmaps for security-sensitive buyers.
- License fragmentation:GPL enforcement actions and dual-licensing disputes are injecting legal uncertainty into commercial derivative distributions.
Strategic Opportunities
- Edge orchestration:Lightweight immutable OS images for factory robotics and autonomous vehicle ECUs remain undersupplied outside automotive captive programs.
- Confidential computing:Hardware-based attestation in AMD SEV-SNP and Intel TDX is creating demand for kernel-level trust verification in financial services.
- India's data localization:MeitY guidelines for government cloud are mandating domestic hosting, opening procurement channels for locally certified distributions.
Industry Challenges
- POSIX compliance drift:Container runtimes and eBPF instrumentation are bypassing traditional syscall interfaces, complicating application portability testing.
- SBOM generation at scale:SPDX and CycloneDX documentation for kernel modules and driver ecosystems is consuming release engineering resources without automated tooling maturity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Server Operating System Market |
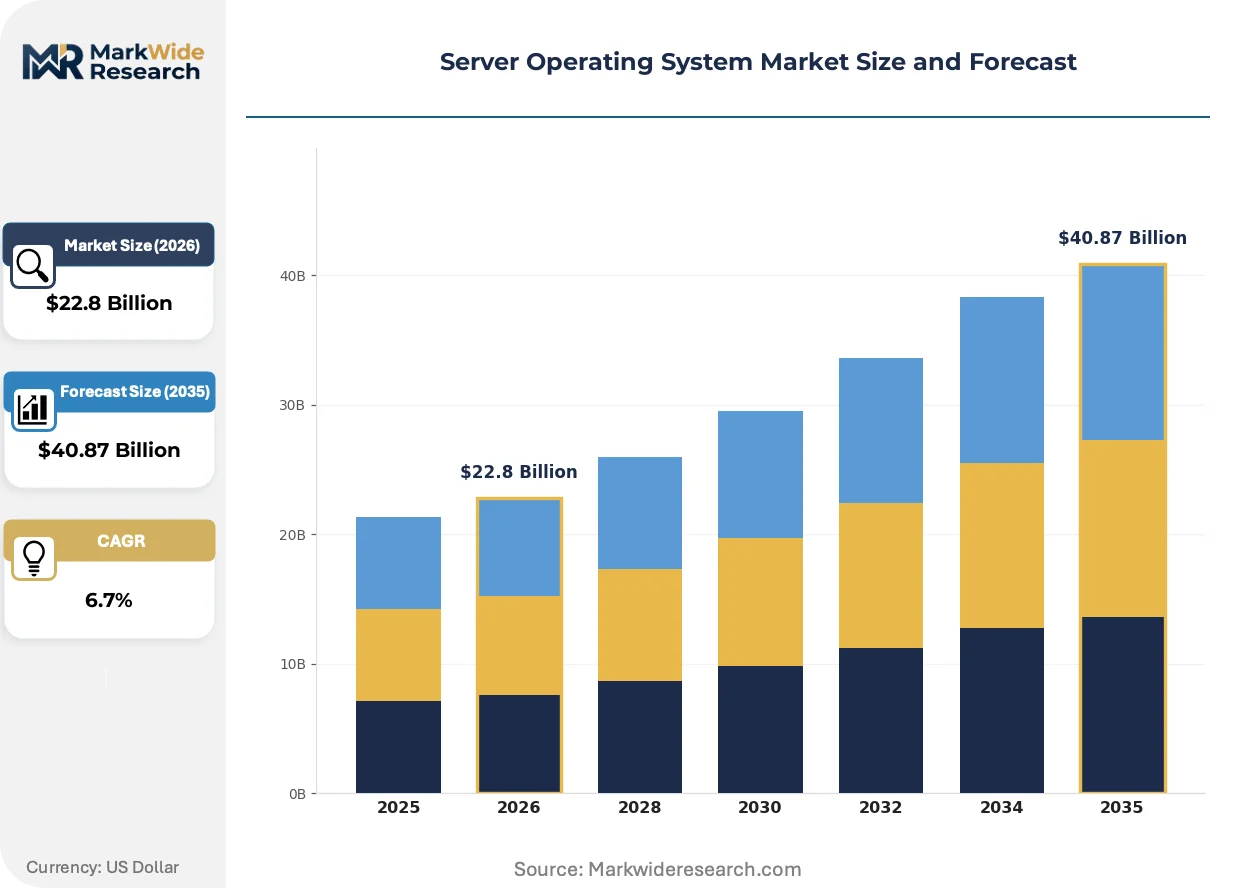
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $40.87 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Virtualized Type: Linux, Windows Server, Unix, BSD End User: SMBs, Enterprises, Government Agencies, Educational Institutions Application: Web Hosting, Database Management, Virtualization, File Storage |
| Companies Covered | Oracle Corporation, IBM Corporation, Microsoft Corporation, Cisco Systems Inc., Canonical Ltd., Red Hat Inc., Amazon Web Services Inc., Dell Technologies Inc., SUSE Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Server Operating System Market Strategic Shifts & Innovations
Immutable infrastructure patterns are displacing mutable server management, while regulatory pressure on software supply chains is elevating formal verification and attestation to procurement prerequisites.
Kernel architectures are bifurcating into two incompatible optimization paths. Real-time patches for industrial control systems prioritize deterministic latency bounds. Meanwhile, cloud-native kernels sacrifice POSIX compatibility for startup speed and memory density. Hyperscalers are adopting the latter at scale, forcing enterprise distribution vendors to maintain dual codebases or cede the container host layer to specialized competitors.
The EU Cybersecurity Act's Common Criteria certification scheme is tightening market access gates for critical infrastructure tenders. Vendors without EAL4+ evaluations face automatic disqualification from energy and transport procurement. German and French utilities are consolidating supplier lists around pre-certified distributions, compressing competitive diversity in European regulated segments.
Consumption models are rotating from perpetual licenses toward metered subscription billing tied to core-hour utilization. Financial services buyers in Singapore and Switzerland are demanding usage-based pricing with automatic security patch inclusion. This unbundles traditional support contracts and pressures vendors to operationalize continuous delivery pipelines without breaking change guarantees.
Server Operating System Market Segmentation
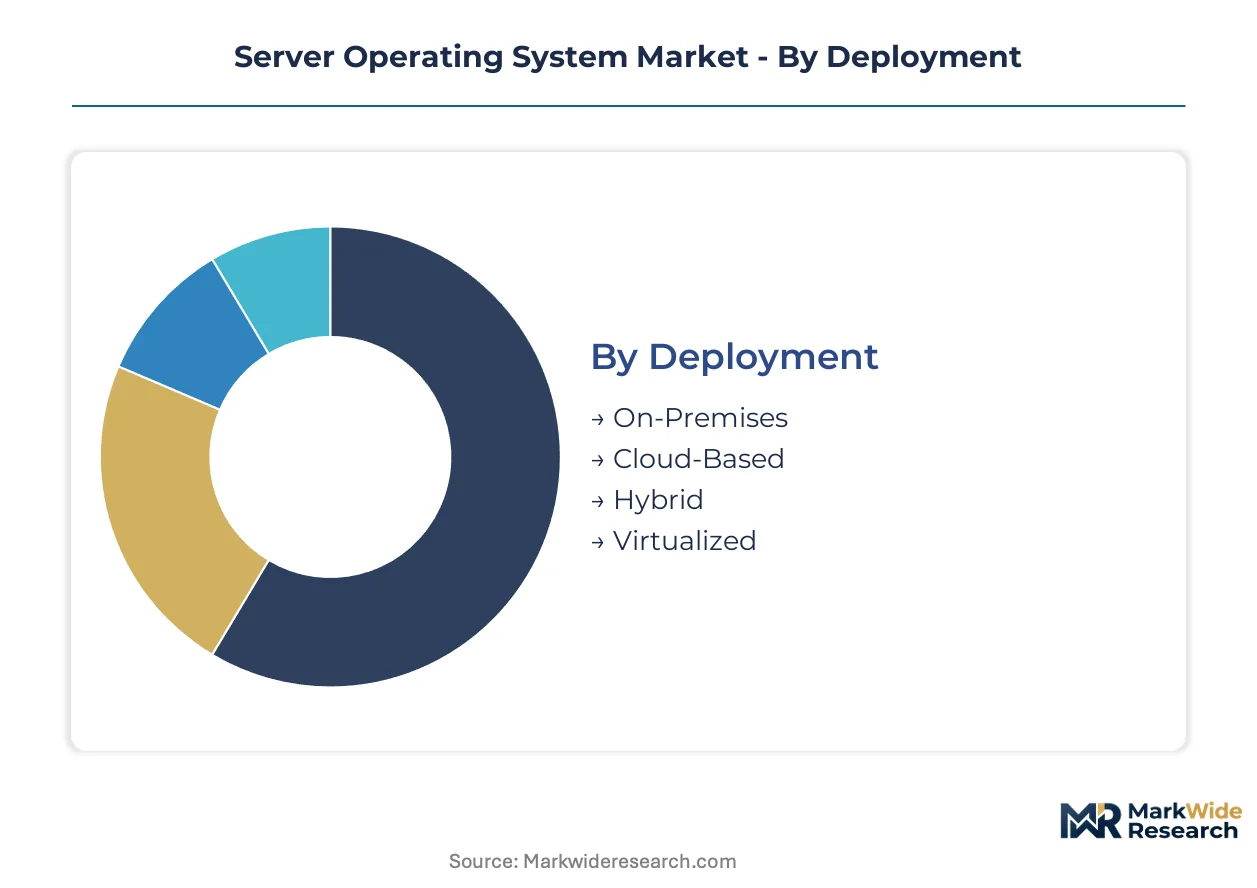
Server operating system procurement patterns diverge sharply across deployment topology, kernel architecture, and compliance sensitivity. Segment boundaries determine pricing power, certification requirements, and talent acquisition strategies for vendors.
Deployment:
Margin pools concentrate in hybrid orchestration layers where enterprises pay premiums for unified management across sovereignty boundaries.
- On-Premises:Bare-metal installations in sovereign data centers require Common Criteria EAL4+ certification for critical infrastructure tenders. German utilities and Japanese financial institutions are consolidating procurement around pre-certified distributions, compressing vendor diversity.
- Cloud-Based:Hyperscale operators consume container-optimized kernels at unprecedented density, pulling engineering talent toward memory-density optimizations and away from POSIX compliance. Metered subscription billing tied to core-hour utilization is displacing perpetual licenses.
- Hybrid:Burst capacity architectures spanning on-premises sovereignty and public cloud elasticity command implementation premiums. Singapore and Swiss financial services buyers demand automatic security patch inclusion without breaking change guarantees.
- Virtualized:Hypervisor-optimized distributions prioritize deterministic resource allocation for multi-tenant workloads. Legacy VMware and KVM ecosystems retain entrenched positions in regulated enterprise data centers.
On-Premises holds installed capacity. Cloud-Based is rotating up the share rankings.
Type:
Commercial significance tracks certification depth and licensing flexibility rather than raw installation volume.
- Linux:Kernel customization depth enables GPU-dense AI training clusters and edge robotics deployments. GPL enforcement actions and dual-licensing disputes inject legal uncertainty into commercial derivative distributions.
- Windows Server:Active Directory ecosystem lock-in sustains margin concentration in Microsoft-centric productivity stacks. Directory-integrated environments retain procurement preference among regulated enterprises dependent on Office 365 workflows.
- Unix:Legacy AIX and Solaris installations persist in banking core systems where migration costs exceed maintenance premiums. IBM and Oracle support contracts function as technical insurance policies for risk-averse CIOs.
- BSD:FreeBSD and OpenBSD distributions command network infrastructure and security appliance niches where licensing permissiveness enables proprietary fork development. Netflix and WhatsApp infrastructure teams maintain significant in-house BSD engineering.
Windows Server holds installed capacity. Linux is climbing the fastest among new procurement decisions.
End User:
Budget authority and compliance burden create four distinct purchasing modalities with incompatible sales cycles.
- SMBs:Price-sensitive buyers prioritize turnkey managed services over in-house kernel expertise. Canonical Ubuntu Pro and Red Hat Developer subscriptions lower entry barriers for sub-thousand-server operators.
- Enterprises:Fortune 500 procurement teams negotiate enterprise license agreements with custom security patch SLAs. Multi-year contracts bundle directory services, virtualization management, and threat intelligence feeds.
- Government Agencies:EU NIS2 Directive and Japan METI cybersecurity framework mandate domestic hosting and certified patching timelines. India's MeitY guidelines for government cloud are opening procurement channels for locally certified distributions.
- Educational Institutions:Research computing clusters consume academic licensing tiers with reduced support obligations. University HPC centers drive adoption of container-native kernels for reproducible science workflows.
Enterprises hold installed capacity. Government Agencies are gaining share fastest through sovereign cloud mandates.
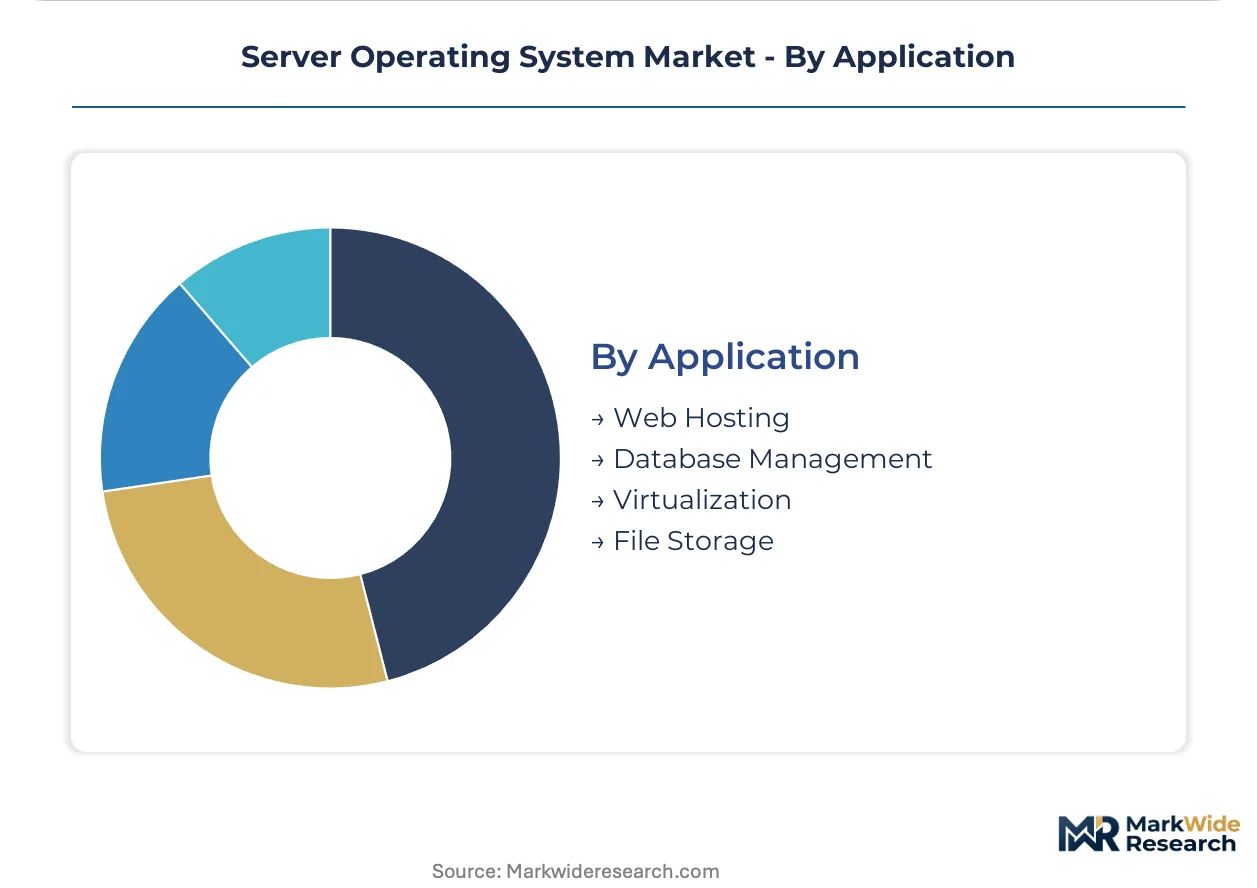
Application:
Workload characteristics determine kernel optimization priorities and hardware affinity requirements.
- Web Hosting:Shared hosting providers and CDN operators demand immutable OS images with sub-second boot times. Lightweight distributions displace full-stack installations at hyperscale edge locations.
- Database Management:Oracle, SQL Server, and PostgreSQL workloads require real-time scheduling patches for deterministic I/O latency. In-memory analytics clusters push kernel memory management to terabyte-scale address spaces.
- Virtualization:Kernel-based Virtual Machine (KVM) and Xen hypervisors depend on paravirtualization support and hardware-assisted nested paging. VMware ESXi compatibility layers influence distribution selection for brownfield migrations.
- File Storage:Distributed filesystems like Ceph and Lustre require kernel-level network stack optimizations for RDMA and NVMe-oF protocols. Object storage gateways prioritize erasure coding acceleration in user-space drivers.
Web Hosting holds installed capacity. Virtualization is rotating up the share rankings through private cloud consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FCC guidelines on communications infrastructure resilience anchor procurement patterns in the United States. EU NIS2 Directive mandates reshape European essential entity requirements. Japan's METI cybersecurity framework governs critical infrastructure software selection across Asia-Pacific.
United States
Hyperscale cloud operators and AI training clusters drive bare-metal Linux consumption at unprecedented density. FCC resilience guidelines mandate patching timelines for communications infrastructure operators. Northern Virginia data center corridors concentrate sovereign cloud deployments as government agencies expand classified facility footprints.
Germany
Gaia-X specifications disqualify non-certified vendors from federal and utility tenders. EU NIS2 Directive mandates 24-hour patching windows for essential energy and transport entities. Frankfurt and Berlin industrial zones consolidate procurement around pre-certified RHEL and SUSE distributions for manufacturing automation systems.
Japan
Financial institutions and automotive manufacturers demand kernel-level trust verification for confidential computing workloads. METI cybersecurity framework mandates domestic hosting for critical infrastructure software. Tokyo-Osaka corridor hosts sovereign AI compute initiatives with strict certification requirements for government cloud deployments.
India
MeitY guidelines for government cloud mandate domestic data localization, opening procurement channels for locally certified distributions. Central and state government digitization programs accelerate server refresh cycles. Bengaluru and Hyderabad technology corridors concentrate hyperscaler edge deployments and domestic distribution engineering centers.
Singapore
Financial services buyers demand metered subscription billing with automatic security patch inclusion without breaking change guarantees. Monetary Authority of Singapore cybersecurity guidelines elevate Common Criteria certification to procurement prerequisite. Marina Bay financial district concentrates private banking and wealth management data center sovereignty requirements.
Server Operating System Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the server operating system landscape. The vendor ecosystem organizes around three strategic tiers: enterprise directory-integrated incumbents, commercial open-source subscription specialists, and cloud-native container-optimized challengers. Dominant competitive moves include certification portfolio expansion for regulated market access and consumption model rotation from perpetual licenses toward core-hour metering.
Within the enterprise incumbent tier, Microsoft Corporation exemplifies directory-ecosystem lock-in strategies. Among commercial open-source specialists, Red Hat Inc. and Canonical Ltd. occupy positions representing subscription-based and cloud-optimized archetypes respectively. These three entities anchor competitive positioning across divergent procurement modalities from Fortune 500 ELAs to hyperscale edge deployments.
| Leading Market Players |
|---|
| Oracle Corporation |
| IBM Corporation |
| Microsoft Corporation |
| Cisco Systems Inc. |
| Canonical Ltd. |
| Red Hat Inc. |
| Amazon Web Services Inc. |
| Dell Technologies Inc. |
| SUSE Group |
| Others |
Cost & Logistics Intelligence
Container-optimized kernel distributions displacing bare-metal legacy stacks simultaneously redraw supply geography toward hyperscale engineering hubs and compress pricing premiums for POSIX-compliant enterprise editions. This substitution dynamic concentrates procurement leverage among cloud-native buyers while fragmenting vendor pricing power across incompatible optimization paths.
Pricing Analysis
Geographic price spreads widen between Frankfurt-certified RHEL deployments and Bengaluru-optimized Ubuntu edge instances, reflecting divergent compliance burdens. Three-tier pricing structure across premium certification, standard subscription, and economy self-support levels tracks Common Criteria validation depth. Pricing pressure stems from hyperscale buyers negotiating core-hour metering against perpetual license anchors. SMBs exhibit highest price sensitivity, while German utilities accept certification premiums for EAL4+ guarantees.
Supply Chain Analysis
Just-in-time release engineering dominates container-native distributions, whereas strategic stockpiling of validated kernel versions persists among NIS2-regulated European operators. Engineering talent concentrates in United States hyperscaler corridors, Germany's industrial automation zones, and India's Bengaluru-Hyderabad technology corridors. Kernel development rests on upstream Linux Foundation governance, proprietary driver ecosystems from AMD and Intel, and distribution-specific patch maintenance. Single-source vulnerability concentrates in real-time scheduling expertise pools. Distribution runs through direct vendor subscriptions, hyperscaler marketplace integrations, and systems integrator channel partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Server operating system procurement is shifting toward service-attach models where automated security patch pipelines and compliance attestation layers expand faster than base license revenue. This rotation elevates vendors with operationalized continuous delivery capabilities over perpetual license incumbents.
For Market Incumbents: Consolidate certification portfolios against EU Cybersecurity Act gates, acquiring Common Criteria evaluation expertise to defend energy and transport procurement eligibility. Deepen upstream control over kernel real-time patch maintenance to offset hyperscaler talent poaching. Directory-ecosystem lock-in remains defensible only where Active Directory integration anchors Microsoft-centric productivity workflows. For New Entrants and Emerging Players: Anchor in India's MeitY-certified government cloud channel, where domestic data localization mandates disqualify incumbent foreign distributions from state digitization tenders. Target edge orchestration for factory robotics outside automotive captive programs, exploiting undersupply of lightweight immutable OS images. Lead with confidential computing attestation capabilities for Singapore financial services buyers demanding hardware-based trust verification. For Investors and Strategic Acquirers: EU NIS2 Directive reshapes the acquisition landscape by compressing vendor diversity around pre-certified distributions, elevating targets with existing EAL4+ evaluations over engineering-heavy challengers. Long-term viability hinges on subscription billing operationalization and sovereign cloud certification breadth. The signal to watch is kernel engineer wage inflation crossing hyperscaler affordability thresholds, triggering enterprise buyer consolidation toward managed service wrappers.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Portfolio Expansion | EAL4+ evaluations unlock EU energy and transport procurement gates previously closed to uncertified vendors. |
| Consumption Model Rotation | Core-hour metering with automatic patch inclusion captures Singapore and Swiss financial services buyers abandoning perpetual licenses. |
| Edge Orchestration Development | Immutable OS images for industrial robotics exploit supply gap outside automotive captive engineering programs. |
| Confidential Computing Integration | AMD SEV-SNP and Intel TDX attestation layers differentiate offerings for Tokyo-Osaka financial services deployments. |
| Sovereign Cloud Localization | MeitY-certified domestic hosting capabilities open Indian central and state government digitization procurement channels. |
Research Approach
Two parallel data streams informed the analysis: structured conversations with kernel engineering directors, cloud procurement officers, critical infrastructure CISOs, and hyperscaler platform teams; and secondary validation against SEC hyperscaler capex disclosures, Linux Foundation contribution metrics, EU Cybersecurity Act certification registers, and national government cloud procurement bulletins. Bottom-up deployment topology modeling triangulated against top-down vendor subscription revenue segmentation.
Across the projection horizon, the analytical framework modeled deployment topology, kernel architecture type, compliance sensitivity tier, organization size band, and regional regulatory cluster. CAGRs derived from segment-level buildups incorporating AI training cluster density assumptions, sovereign cloud mandate implementation timelines, and certification lag effects. Forecast inputs included hyperscaler bare-metal consumption patterns and NIS2-mandated refresh cycle acceleration.
Material uncertainties — regulatory certification timeline slippage, GPL enforcement action outcomes, and hyperscaler vertical integration into kernel customization — sit outside the modeled envelope. Forecasts reflect assumptions regarding talent pool bifurcation persistence and sovereign AI compute fragmentation versus consolidation dynamics. Revision becomes warranted when kernel engineer concentration among hyperscale employers crosses enterprise hiring cost elasticity thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Personal Budgeting Software Market
Software & Services
North America Servicenow Store Apps Market
Software & Services
Global Corporate Wellness Software Market
Software & Services
Camp Management Software Market
Software & Services
Global Advanced Planning and Scheduling (APS) Software Market
Software & Services
Landscaping Engineering Software Market
Software & Services
Construction Equipment Fleet Management Software Market
Software & Services
Europe Business Software Market
Software & Services
United Arab Emirates (UAE) Cloud Accounting Software Market
Software & Services
Global Customer Success Software Market
Software & Services
Business Analytics Software Market
Software & Services
Asia-Pacific Database Management Software Market
Software & Services
Global 360 Degree Feedback Software Market
Software & Services
Global Landscape Software Market
Software & Services
Design Engineering Software Market
Software & Services
Data Integration Software Market