
 Business Analytics Software Market | 2026-2036
Business Analytics Software Market Size, Share, and Industry Trends Forecast 2026-2036
Business Analytics Software Market Analysis
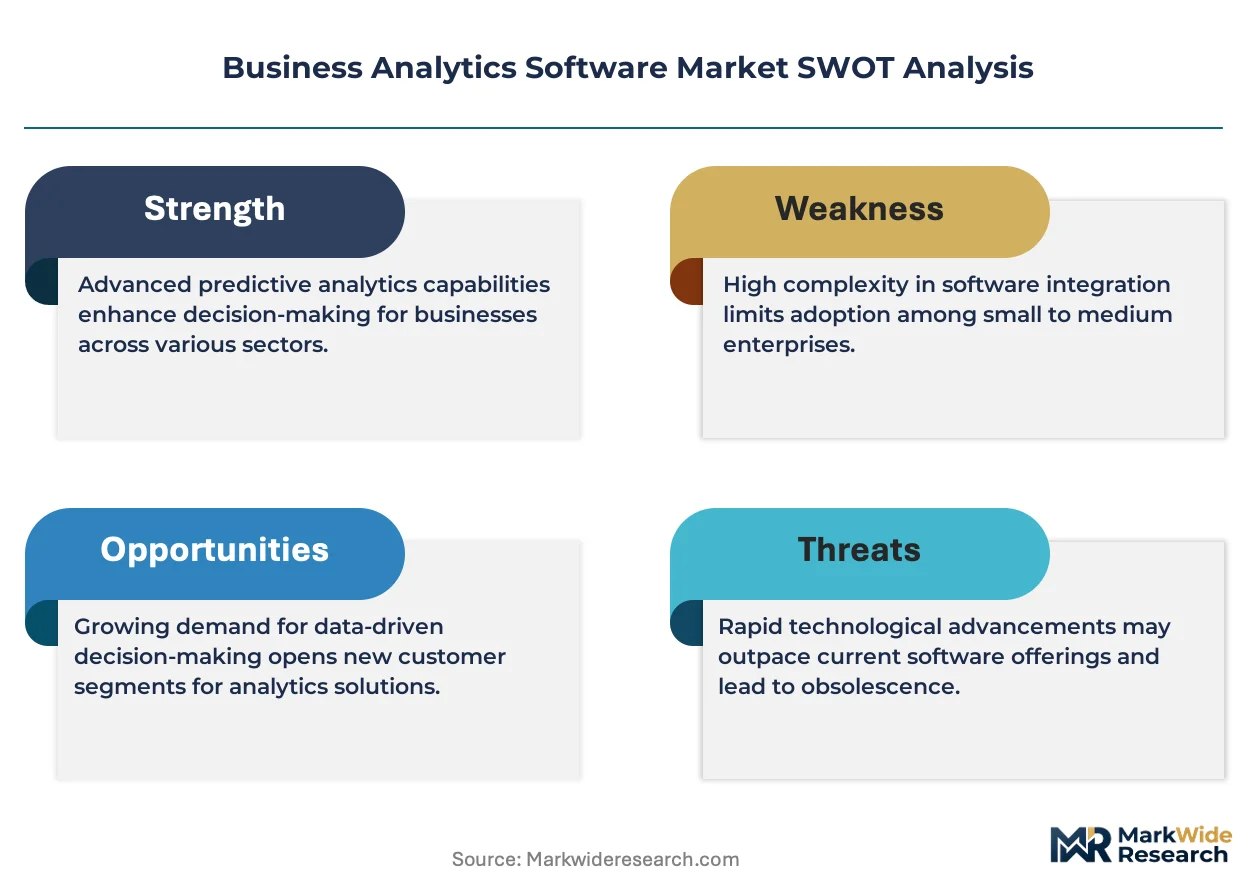
Embedded artificial intelligence within analytics pipelines is reconfiguring how business intelligence platforms process and surface insights to decision-makers. Microsoft Corporation leverages its Azure cloud ecosystem to anchor enterprise deployments across hybrid environments. SAP SE sustains deep integration with ERP systems, competing on operational data continuity for manufacturing and finance clients. Salesforce (Tableau) differentiates through intuitive visualization layers that occupy the self-service analytics tier for line-of-business users.
Business analytics software encompasses platforms that ingest, process, and visualize structured and unstructured data to support operational and strategic decision-making, typically operating through SQL-based querying, in-memory processing, or distributed compute architectures that handle terabyte-scale datasets with sub-second response thresholds. Cloud-based deployment models now lead new enterprise procurement cycles as organizations prioritize elastic scaling and reduced infrastructure overhead over fixed-capacity on-premises installations. Predictive analysis functionality captures expanding margin pools as vendors embed machine learning modules that automate forecasting and anomaly detection beyond static reporting outputs.
FDA guidelines on algorithmic transparency in clinical decision support, HIPAA data minimization requirements, and the SEC's climate disclosure rules are collectively elevating audit-trail and lineage capabilities as mandatory procurement criteria for regulated industries. The EU AI Act and GDPR cross-border transfer mechanisms are forcing multi-tenant platform providers to engineer region-specific data residency controls or risk exclusion from European public sector tenders. Stakeholders must weigh whether to build proprietary analytics stacks or accept vendor lock-in as cloud providers deepen integration between storage, compute, and visualization layers.
Market Dynamics
Cloud migration mandates under GDPR and sector-specific data governance rules in Europe are accelerating compliance-driven software refreshes, forcing vendors to engineer region-specific data residency controls or risk exclusion from public sector tenders.
Growth Catalysts
- Federal data transparency requirements:United States government mandates for open data and performance reporting sustain large-scale deployments across federal agencies and federally funded healthcare systems.
- Healthcare analytics procurement:Hospital networks and payers are expanding analytics budgets to manage patient outcomes, reduce readmission penalties, and optimize operating room utilization.
- Embedded machine learning modules:Automated forecasting and anomaly detection capabilities are capturing expanding margin pools as vendors differentiate beyond static reporting outputs.
Market Restraints
- Cross-border data transfer friction:GDPR adequacy decisions and Schrems II rulings create legal uncertainty for multi-tenant platform providers serving European enterprises from US-based infrastructure.
- Specialized talent scarcity:Shortage of data engineers fluent in distributed compute architectures and MLOps pipelines constrains implementation velocity for complex deployments.
- Legacy ERP integration costs:Custom API development and data schema harmonization for decades-old on-premises systems inflate total cost of ownership and extend payback periods.
Strategic Opportunities
- SEC climate disclosure rules:Mandatory emissions reporting and supply chain transparency requirements are elevating audit-trail and lineage capabilities as mandatory procurement criteria for publicly traded manufacturers.
- Edge analytics convergence:Integration of stream processing with IoT sensor networks enables real-time quality control and predictive maintenance for industrial asset operators.
- Self-service visualization layers:Intuitive drag-and-drop interfaces for line-of-business users reduce IT ticket backlogs and accelerate time-to-insight for operational decision-makers.
Industry Challenges
- Algorithmic explainability requirements:FDA guidelines on transparency in clinical decision support systems demand documentation of model training data, performance metrics, and failure modes that many black-box architectures cannot readily produce.
- Multi-cloud orchestration complexity:Enterprises pursuing hybrid strategies face skill gaps in Kubernetes management, cross-cloud identity federation, and unified cost governance across AWS, Azure, and Google Cloud environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Business Analytics Software Market |
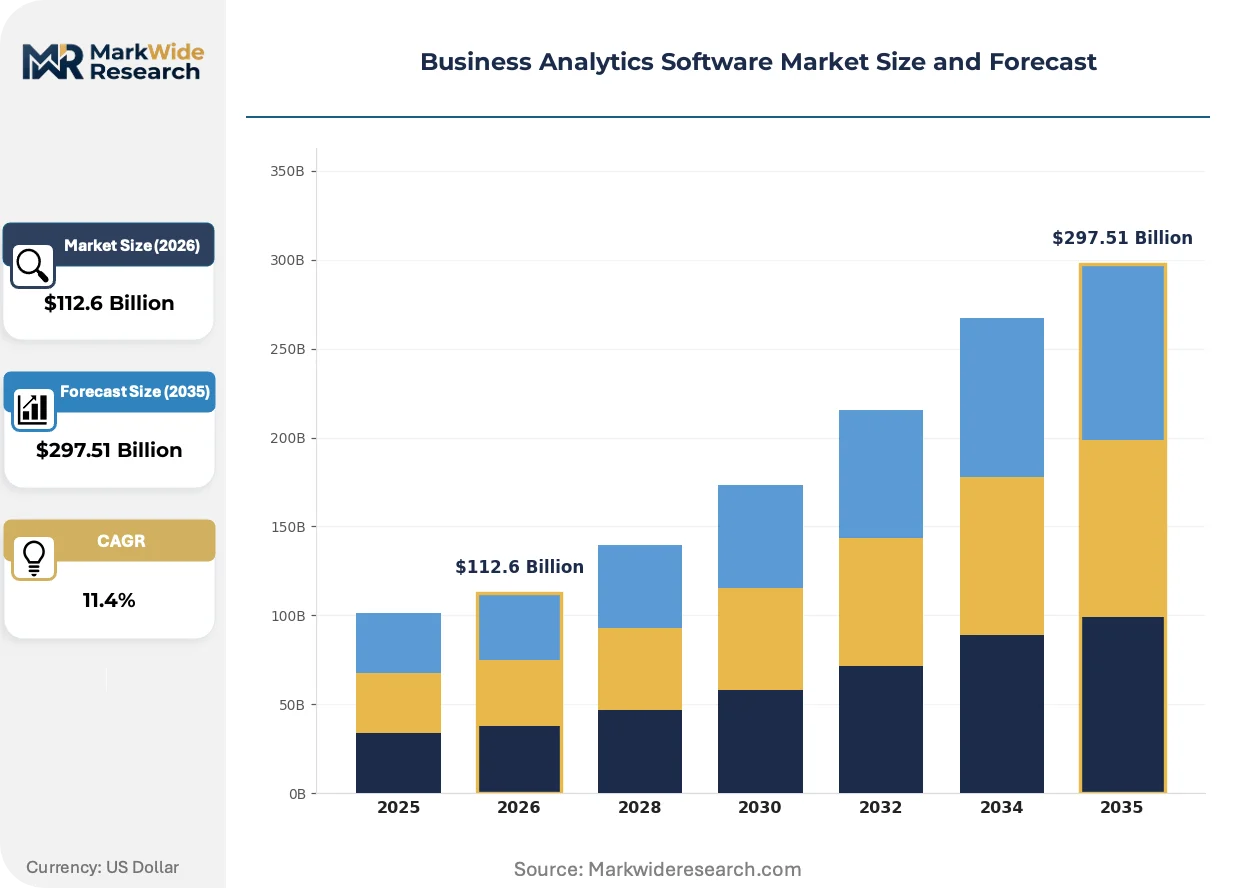
| Market Size in 2026 | $112.6 Billion |
| Market Size in 2035 | $297.51 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: On-Premises, Cloud-Based, Hybrid, Multi-Tenant End User: Retail, Healthcare, Manufacturing, Finance Functionality: Reporting, Predictive Analysis, Data Mining, Visualization Industry Vertical: Telecommunications, Energy, Transportation, Education |
| Companies Covered | Microsoft Corporation, SAP SE, Oracle Corporation, IBM Corporation, SAS Institute Inc., Salesforce (Tableau), Qlik, TIBCO Software Inc., Google LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Business Analytics Software Market Emerging Trajectories
Artificial intelligence is reconfiguring how business intelligence platforms process and surface insights, compressing the gap between raw data ingestion and actionable recommendations for decision-makers.
Serverless query engines are virtualizing the compute layer beneath analytics workloads, eliminating provisioning overhead for sporadic usage patterns. Mid-market enterprises with seasonal reporting cycles are adopting pay-per-scan architectures fastest. This shift is virtualizing infrastructure capital into operational expenditure, flattening barriers to terabyte-scale analytics for organizations lacking dedicated platform engineering teams.
The EU AI Act's risk-based classification system is mandating conformity assessments for high-risk applications including credit scoring and recruitment analytics. Vendors must now maintain technical documentation, human oversight protocols, and accuracy metrics subject to market surveillance authority audits. Financial services and HR technology providers operating in France, Germany, and the Netherlands are restructuring product roadmaps to secure CE marking for AI components.
Subscription-based consumption models are displacing perpetual license agreements as the dominant commercial structure. Enterprise buyers now expect elastic scaling, automatic feature updates, and embedded professional services rather than upfront capital commitments with annual maintenance fees. This transition is most pronounced in United States healthcare systems and German automotive suppliers modernizing their analytics stacks.
Business Analytics Software Market Segmentation
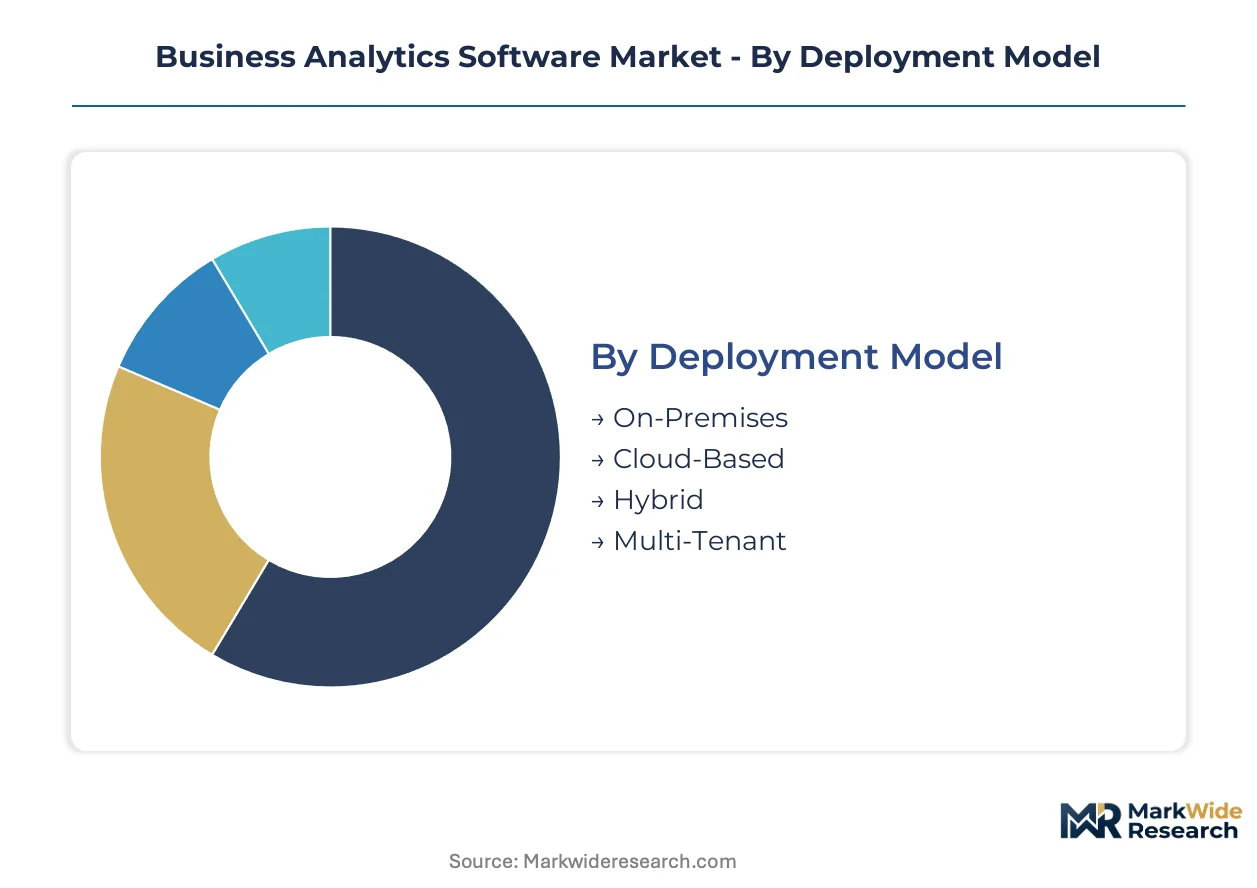
Deployment architecture determines total cost of ownership and compliance posture for analytics buyers. End-use concentration and functional requirements further stratify vendor competitive positioning across procurement cycles.
Deployment Model:
Cost tier structures procurement decisions, separating capital-intensive infrastructure from operational expenditure models.
- Cloud-Based:Elastic compute and storage resources provision through subscription billing, eliminating fixed hardware commitments. United States healthcare systems and German automotive suppliers prioritize this model for GDPR-aligned data residency controls and automatic feature updates.
- Hybrid:Workloads split between on-premises data lakes and cloud processing layers, preserving sensitive records behind firewall perimeters while leveraging distributed analytics for non-critical datasets. Manufacturing clients with legacy ERP investments favor this architecture to defer full migration costs.
- On-Premises:Fixed-capacity installations in sovereign data centers serve defense contractors and financial institutions subject to strict data localization mandates.
- Multi-Tenant:Shared infrastructure platforms reduce per-seat licensing costs for mid-market enterprises with standardized reporting requirements.
Cloud-Based commands the established base. The steepest expansion runs through Hybrid.
End User:
Application-specific compliance burdens and data velocity requirements create divergent purchasing criteria across sectors.
- Healthcare:HIPAA data minimization protocols and FDA algorithmic transparency guidelines mandate audit-trail capabilities for clinical decision support systems. Hospital networks expand procurement to manage patient outcomes and reduce readmission penalties.
- Finance:SEC climate disclosure rules and Basel III risk reporting requirements elevate lineage documentation to mandatory procurement criteria. Investment banks and insurers prioritize predictive modules for fraud detection and portfolio stress testing.
- Manufacturing:Industrial IoT integration drives demand for edge analytics converging with quality control systems.
- Retail:Seasonal demand forecasting and supply chain transparency requirements concentrate procurement in omnichannel operators.
Healthcare commands the established base. The steepest expansion runs through Finance.
Functionality:
Capability maturity separates commodity reporting from premium-margin predictive and prescriptive modules.
- Predictive Analysis:Machine learning pipelines automate forecasting and anomaly detection beyond static outputs, capturing expanding margin pools as vendors differentiate through embedded AI. Financial services and energy traders deploy these modules for risk scoring and demand prediction.
- Visualization:Self-service drag-and-drop interfaces reduce IT ticket backlogs and accelerate time-to-insight for line-of-business users. Tableau and Power BI deployments concentrate in United States retail and professional services sectors.
- Data Mining:Pattern recognition across unstructured datasets supports customer segmentation and sentiment analysis for telecommunications marketers.
- Reporting:Standardized dashboard exports satisfy regulatory filing requirements in transportation and logistics operations.
Reporting commands the established base. The steepest expansion runs through Predictive Analysis.
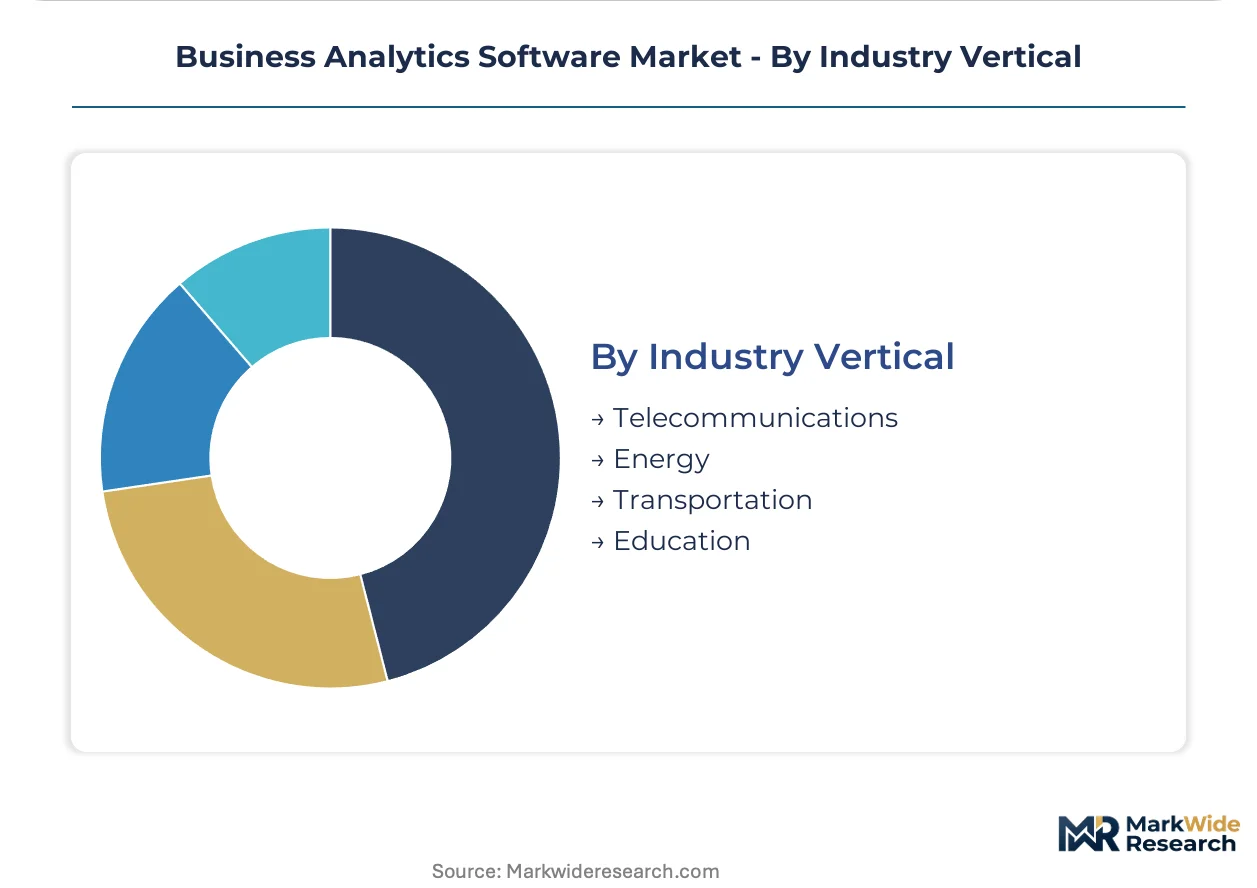
Industry Vertical:
Customer-type concentration varies by data governance maturity and digital transformation budget allocation.
- Telecommunications:Subscriber churn prediction and network optimization analytics process petabyte-scale streaming data from cell tower infrastructure. European operators face EU AI Act conformity assessments for automated credit scoring modules.
- Energy:Predictive maintenance for generation assets and grid load forecasting drive procurement among utilities modernizing SCADA integrations. German and French operators align analytics refreshes with CSRD emissions reporting deadlines.
- Transportation:Route optimization and fleet telematics concentrate demand in logistics providers and airline operators.
- Education:Student outcome analytics and enrollment forecasting gain traction among United States public university systems facing performance-based funding metrics.
Telecommunications commands the established base. The steepest expansion runs through Energy.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German analytics vendors export compliance-configured platforms to French healthcare networks and Dutch financial institutions under EU AI Act certification requirements. Cross-border procurement flows concentrate through the Rhine-Ruhr corridor and Amsterdam data hub interconnections.
United States
Federal data transparency mandates and CMS hospital performance reporting sustain large-scale deployments across Medicare-funded health systems. SEC climate disclosure rules elevate audit-trail capabilities to mandatory procurement criteria for publicly traded manufacturers. Boston and Seattle clusters anchor predictive analytics development for pharmaceutical supply chain optimization.
Germany
Automotive suppliers and industrial machinery producers drive hybrid cloud procurement to preserve legacy ERP continuity while enabling AI-driven quality control. CSRD emissions reporting deadlines align analytics refreshes with sustainability disclosure requirements. Munich and Stuttgart engineering clusters concentrate edge analytics integration for factory floor IoT networks.
United Kingdom
Financial services firms in the City of London expand fraud detection and portfolio stress testing modules under Bank of England operational resilience guidelines. NHS trusts procure patient outcome analytics to reduce readmission penalties and optimize theater utilization. Cambridge and Manchester technology corridors host machine learning pipeline development for telecommunications marketers.
France
Energy utilities modernize SCADA integrations for grid load forecasting ahead of CSRD compliance deadlines. CNIL data protection assessments constrain multi-tenant platform architectures serving credit scoring applications. Lyon and Toulouse industrial basins deploy predictive maintenance analytics for nuclear generation and aerospace manufacturing assets.
India
BFSI sector digitization and RBI regulatory reporting requirements concentrate demand in Mumbai and Bangalore. PLI scheme incentives for electronics manufacturing attract analytics procurement for supply chain quality control. Hyderabad and Pune IT corridors anchor captive development centers serving North American healthcare and retail clients.
Business Analytics Software Market Vendor Landscape
Channel-controlling players compete with product-specialist players across deployment architecture tiers. The vendor base stratifies between hyperscale cloud providers anchoring enterprise-wide subscriptions and vertical specialists capturing margin in regulated industry configurations. Three archetypes dominate: infrastructure-integrated platforms, ERP-native suites, and visualization-first self-service layers. Competitive moves concentrate on strategic partnerships with systems integrators and geographic expansion through region-specific data residency certifications.
Among infrastructure-integrated platforms, Microsoft Corporation and Google LLC exemplify the cloud-native archetype with elastic compute anchoring hybrid deployments. SAP SE occupies a position within the ERP-native tier, sustaining operational data continuity for manufacturing clients through embedded analytics modules. Salesforce, operating through its Tableau subsidiary, represents the visualization-first archetype with intuitive interfaces targeting line-of-business self-service adoption.
| Leading Market Players |
|---|
| Microsoft Corporation |
| SAP SE |
| Oracle Corporation |
| IBM Corporation |
| SAS Institute Inc. |
| Salesforce (Tableau) |
| Qlik |
| TIBCO Software Inc. |
| Google LLC |
| Others |
Supply Flow & Price Mechanics
Rhine-Ruhr corridor freight costs amplify supply concentration effects for European analytics vendors, compressing margins on on-premises hardware shipments while widening the technology-generation pricing gap between legacy ERP-integrated suites and cloud-native subscription tiers. This logistics dynamic concentrates pricing power with hyperscale cloud providers who virtualize infrastructure capital into operational expenditure models.
Pricing Analysis
The technology-generation pricing gap separates prior-generation perpetual-license ERP modules from current-generation SaaS subscriptions and emerging serverless query engines. Three-tier pricing structure across premium, standard, and economy levels differentiates by deployment complexity and compliance certification grade, with GDPR-aligned data residency commands carrying brand premiums. Pricing pressure stems from mid-market buyers demanding pay-per-scan architectures that eliminate fixed provisioning overhead. Healthcare systems in the United States exhibit highest price sensitivity due to CMS reimbursement constraints, while defense contractors accepting on-premises sovereign installations show lowest sensitivity.
Supply Chain Analysis
Export-control regimes restricting GPU and advanced semiconductor flows to Chinese hyperscalers reshape component sourcing strategies for analytics platform providers. Supply concentration centers on Taiwan for advanced foundry capacity, the United States for chip design and cloud infrastructure, and Ireland for European data residency operations. Raw material dependencies span silicon wafers, specialized memory modules, and rare-earth elements for server manufacturing. Single-source vulnerability in Taiwan semiconductor fabrication poses structural risk. Distribution runs through direct enterprise sales teams and systems integrator partnerships for complex deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a defensive-moat story where regulatory entrenchment creates formidable switching costs. Compliance certification investments and embedded ERP integration deepen customer captivity beyond pure technology differentiation.
For Market Incumbents: Entrench competitive position by deepening vertical integration into specialized healthcare and financial services compliance modules, countering emerging cloud-native entrants. Prioritize capacity addition in Frankfurt and Amsterdam data hubs to satisfy EU AI Act data residency mandates. Channel control through systems integrator exclusivity agreements defends margin pools against self-service visualization layer commoditization. For New Entrants and Emerging Players: Pursue white-space opportunities in edge analytics convergence for industrial IoT networks, where legacy ERP incumbents lack real-time stream processing capabilities. German automotive suppliers and French energy utilities represent most penetrable verticals due to CSRD-driven analytics refresh cycles. Go-to-market angle emphasizing out-of-box EU AI Act conformity assessments accelerates procurement velocity against uncertified competitors. For Investors and Strategic Acquirers: Carve-out targets emerge from industrial conglomerates spinning off captive analytics units lacking cloud-native architecture. Long-term viability favors platforms with regulatory certification moats rather than pure visualization layer specialists. Signal to watch is FDA algorithmic transparency guideline enforcement accelerating consolidation around audit-trail-capable vendors.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Azure and AWS deepen embedded AI modules, capturing healthcare procurement under HIPAA mandates. |
| Geographic Expansion | Munich and Singapore data hubs secure EU AI Act and Singapore PDPA certifications for Asian financial services. |
| Acquisition of Specialist Firm | Edge analytics startups with SCADA integration expertise address German manufacturing predictive maintenance demand. |
| Strategic Partnership | Systems integrator alliances accelerate FDA-validated clinical decision support deployments in hospital networks. |
| Product Launch | Serverless query engines with pay-per-scan billing flatten barriers for mid-market seasonal reporting cycles. |
Methodological Framework
The analysis maps cloud deployment models, hybrid architectures, and on-premises installations, each validated through CTOs, IT procurement officers, platform engineers, and channel partners across primary interviews. Secondary validation draws from SEC filings, hyperscaler capex disclosures, CMS Medicare data, and EU public procurement databases. Bottom-up sizing of vendor-reported subscription revenues triangulates with top-down IT budget allocation surveys across healthcare, finance, and manufacturing verticals.
Assumption sets held regulatory enforcement timelines and cloud migration elasticities fixed while varying enterprise digital transformation budget trajectories and cross-border data transfer legal interpretations. Segmentation dimensions modeled span deployment model, organization size, vertical industry, integration complexity with legacy ERP systems, and regional adoption pattern. CAGRs derive from logistic diffusion curves fitted to historical procurement velocity, with inputs including federal data transparency mandate implementation schedules and EU AI Act conformity assessment rollout pace.
Sensitivities concentrate around Schrems II ruling expansions restricting EU-US data flows and FDA algorithmic transparency guideline enforcement intensity. Forecasts reflect documented assumptions on compliance cost pass-through rates and mid-market buyer price elasticity. Material shifts in cross-border data transfer legal frameworks or federal healthcare IT reimbursement policy would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Software Repository Market
Software & Services
Global Jewelry Store Management Software Market
Software & Services
Global Diagram Software Market
Software & Services
Nonconformance Management Software Market
Software & Services
User Interface Software Market
Software & Services
Global Content Management Software Market
Software & Services
Global Webinar Software Market
Software & Services
Software Release Management Tools Market
Software & Services
Global Time Tracking Software Market
Software & Services
Labor Management Software Market
Software & Services
Outsourced Software Testing Services Market
Software & Services
Machine Translation Software Market
Software & Services
Vacation Rental Software Market
Software & Services
Web Framework Software Market
Software & Services
Service Dispatch Software Market
Software & Services
File Sharing Software Market