
 Global Advanced Planning and Scheduling (APS) Software Market | 2026-2036
Global Advanced Planning and Scheduling (APS) Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Advanced Planning and Scheduling (APS) Software Market Foresight
ISO 27001 certification cycles for cloud-hosted manufacturing data are unwinding competitive access across the APS landscape, forcing vendors to demonstrate continuous security governance. SAP SE leverages its embedded S/4HANA manufacturing execution backbone to anchor enterprise-wide scheduling contracts. Oracle Corporation competes through database-tier integration that collapses planning latency into transactional systems. Siemens AG specializes in shop-floor-centric APS modules that extend its PLC and MES hardware dominance into software subscriptions.
Advanced Planning and Scheduling software comprises algorithmic engines that optimize production sequences, resource allocation, and material flows against capacity constraints, lead times, and demand variability, typically employing constraint-based programming or genetic algorithms with solve horizons ranging from hours to eighteen months. Its primary commercial purpose is to minimize makespan, inventory carrying costs, and late deliveries in discrete and process manufacturing environments. Cloud-based deployment is capturing the fastest expansion as manufacturers abandon capital-intensive on-premise infrastructure, while demand planning modules command disproportionate margin pools due to their direct linkage to revenue forecasting and S&OP processes. Production scheduling retains the largest installed base but faces compression as hybrid architectures allow edge-based execution with cloud-based optimization.
The U.S. Food and Drug Administration's 21 CFR Part 11 electronic records requirements shape validation protocols for pharmaceutical APS implementations, while the EU's Cybersecurity Act and GDPR impose cross-border data residency constraints on cloud deployments serving European chemical and aerospace clusters. China's GB/T standards for industrial software interoperability, administered by MIIT, create localization prerequisites for foreign vendors accessing state-owned manufacturing enterprises. Stakeholders must monitor how divergent data sovereignty regimes fragment cloud architecture roadmaps and whether constraint-solving engine performance becomes the decisive procurement criterion as planning horizons compress toward real-time execution.
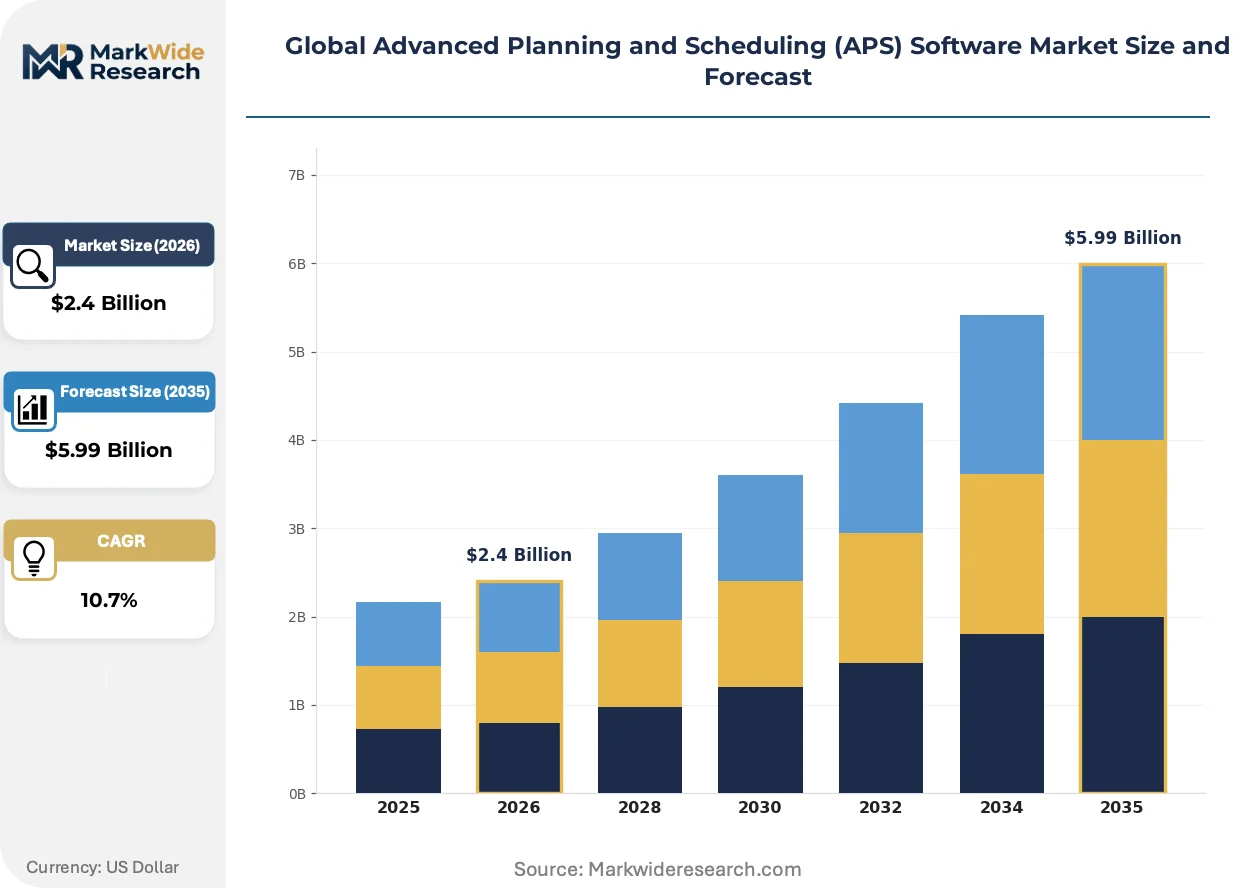
Market Dynamics
Cloud-native architectures are compressing planning latency from days to minutes, forcing incumbent vendors to rearchitect monolithic engines into microservices or surrender enterprise accounts to API-first competitors.
Growth Catalysts
- EU CSRD supply-chain disclosure mandates:European automotive and chemical manufacturers must document Scope 3 emissions, creating procurement pull for APS platforms with embedded carbon accounting.
- Multi-site synchronization:German and Japanese automotive OEMs require real-time coordination across distributed production networks, driving demand for federated planning engines.
- Constraint-based programming:Semiconductor fabs in Taiwan and South Korea deploy genetic algorithm solvers to optimize wafer starts against photolithography bottlenecks.
Market Restraints
- Data residency fragmentation:China's GB/T standards and EU GDPR impose conflicting localization requirements, forcing vendors to maintain redundant infrastructure stacks.
- Legacy ERP lock-in:Decades of customized SAP R/3 and Oracle E-Business Suite implementations create switching costs exceeding three-year total cost of ownership.
- Edge computing hardware:Real-time shop-floor optimization requires industrial PCs and time-sensitive networking, inflating deployment costs for mid-tier manufacturers.
Strategic Opportunities
- India's PLI scheme:Electronics and pharmaceutical contract manufacturers receive production-linked incentives, creating greenfield APS deployments without legacy displacement.
- FDA 21 CFR Part 11 validation:Pharmaceutical manufacturers seek pre-validated cloud APS modules to accelerate electronic batch record compliance.
- Digital twin convergence:APS vendors integrating physics-based simulation with optimization engines capture premium positioning in aerospace and energy equipment.
Industry Challenges
- Operations research talent scarcity:Constraint programming and mixed-integer linear optimization expertise concentrates in academic and defense sectors, not commercial software.
- ISO 27001 continuous audit cycles:Cloud-hosted manufacturing data requires annual recertification, consuming engineering resources that could advance product roadmaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Advanced Planning and Scheduling (APS) Software Market |
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.99 Billion |
| CAGR (2026 – 2036) | 10.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, Private Cloud Solution Type: Demand Planning, Production Scheduling, Inventory Optimization, Order Management, Supply Chain Modeling Industry Vertical: Manufacturing, Aerospace, Consumer Electronics, Chemicals, Pharmaceuticals End User: OEMs, Tier-1 Suppliers, Third-Party Logistics, Contract Manufacturers |
| Companies Covered | SAP SE, Oracle Corporation, Blue Yonder Group, Inc., Siemens AG, Dassault Systèmes SE, Kinaxis, Infor, ORTEC, Asprova, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Advanced Planning and Scheduling (APS) Software Market Shifts & Advancements
Algorithmic planning engines are migrating from batch optimization toward continuous re-planning, collapsing the historical separation between strategic S&OP and tactical execution.
Graph neural networks are supplanting traditional heuristic solvers in semiconductor and pharmaceutical scheduling. TSMC and Samsung Foundry deploy these architectures to model complex tool interdependencies across 300mm wafer fabs. The technology is supplanting rule-based dispatch systems that cannot adapt to stochastic equipment downtime.
REACH substance restriction updates are forcing chemical manufacturers to reformulate product portfolios, requiring APS platforms to dynamically re-optimize campaigns around substitute raw materials. European specialty chemical clusters in Germany and Belgium face the steepest reconfiguration burden, with planning horizons compressing from quarters to weeks.
Subscription pricing for APS modules is displacing perpetual license models among North American contract manufacturers. Third-party logistics providers in the United States now procure planning capacity as metered cloud services rather than capital assets, shifting vendor revenue recognition and customer retention metrics.
Global Advanced Planning and Scheduling (APS) Software Market Segmentation
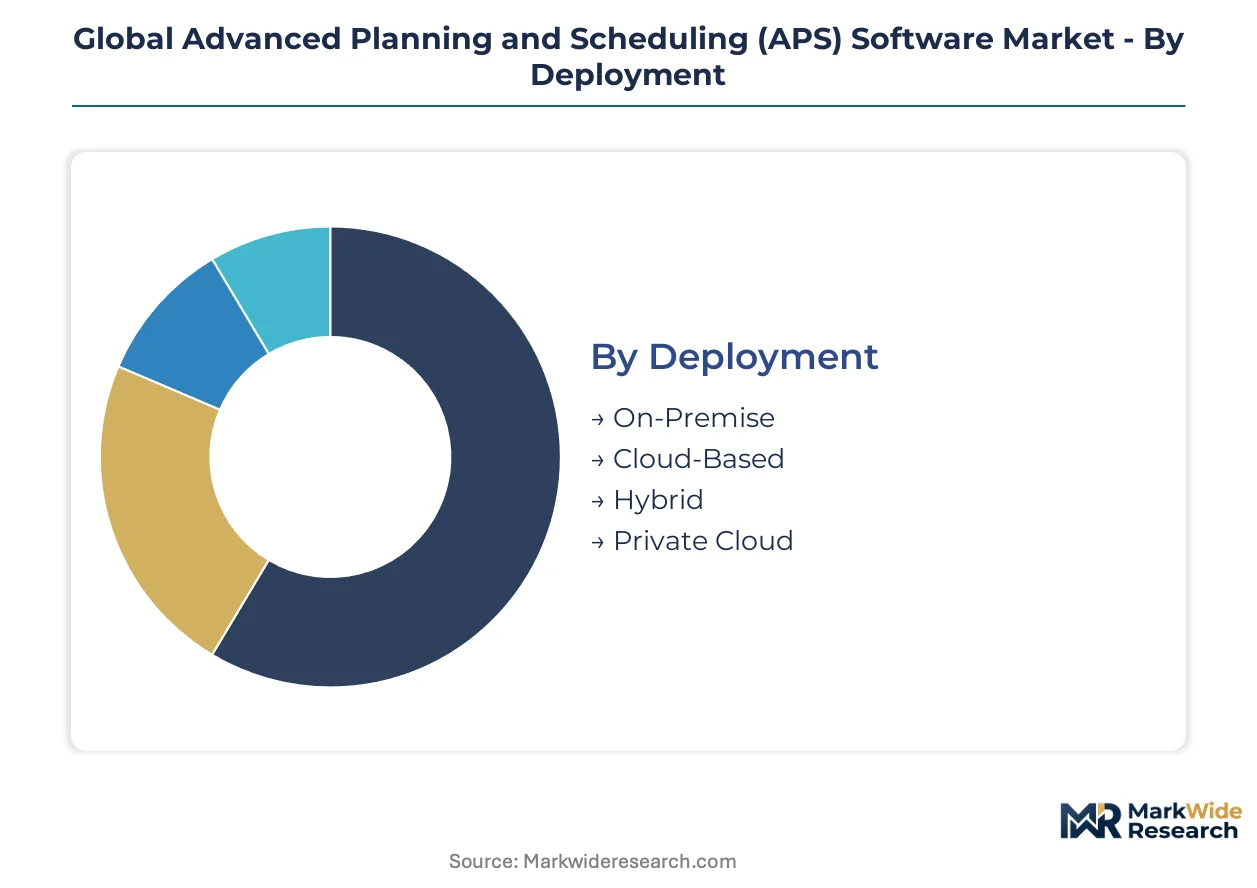
APS software procurement patterns diverge sharply across deployment architectures and user sophistication levels. Pharmaceutical manufacturers prioritize validated cloud environments while automotive OEMs demand hybrid latency optimization.
Deployment:
Cloud-native platforms face acute substitution pressure from edge-optimized private cloud stacks as manufacturers reconcile data sovereignty with real-time performance.
- On-Premise:Legacy installations persist in defense-aerospace clusters and classified chemical processing facilities where air-gapped networks remain mandatory. German automotive suppliers maintain these stacks for shop-floor systems integration despite rising maintenance overhead.
- Cloud-Based:Multi-tenant SaaS architectures dominate North American contract manufacturing and third-party logistics procurement. FDA 21 CFR Part 11 pre-validation accelerates pharmaceutical adoption.
- Hybrid:Federated architectures partition optimization engines centrally while executing scheduling decisions at plant-edge nodes. Japanese automotive OEMs deploy these configurations for multi-site synchronization.
- Private Cloud:Single-tenant dedicated instances satisfy EU GDPR data residency mandates and China's GB/T localization requirements for state-owned enterprises.
On-Premise retains volume leadership; Cloud-Based holds the steepest expansion curve.
Solution Type:
Margin concentration follows functional proximity to revenue forecasting, with demand planning modules commanding premium pricing against execution-focused alternatives.
- Demand Planning:Statistical forecasting engines integrate S&OP workflows with constraint-based capacity modeling. Consumer electronics brands in Taiwan deploy these modules for new product introduction volatility.
- Production Scheduling:Constraint programming solvers optimize job sequences against equipment availability and material flows. Semiconductor fabs in South Korea represent the most demanding deployment environment.
- Inventory Optimization:Multi-echelon stochastic models balance service levels against working capital. Chemical manufacturers reformulate campaigns around REACH substance restrictions.
- Order Management:ATP/CTP engines promise delivery dates against real-time capacity and supply availability. Third-party logistics providers meter these capabilities as cloud services.
- Supply Chain Modeling:Digital twin simulation platforms model network disruptions and carbon accounting for EU CSRD disclosure compliance.
Production Scheduling retains volume leadership; Supply Chain Modeling gains share fastest.
Industry Vertical:
Regulatory validation requirements fragment procurement criteria, with life sciences demanding pre-certified platforms while discrete manufacturing prioritizes solver performance.
- Manufacturing:Discrete and process subsegments span automotive, industrial equipment, and food processing. India's PLI scheme electronics manufacturers deploy greenfield without legacy displacement.
- Aerospace:AS9100 quality mandates and long-tailed supplier networks require traceability-integrated scheduling. Boeing and Airbus tier-nets drive federated planning adoption.
- Consumer Electronics:High-mix low-volume assembly and seasonal demand spikes stress heuristic solver limitations. Graph neural networks penetrate this vertical first.
- Chemicals:Campaign optimization around reactor cleaning constraints and REACH reformulation drives dynamic re-planning frequency. Belgian and German specialty chemical clusters face compressed planning horizons.
- Pharmaceuticals:Electronic batch record integration and FDA validation protocols dominate vendor selection. Pre-validated cloud modules accelerate compliance timelines.
Manufacturing retains volume leadership; Pharmaceuticals climbs the fastest.
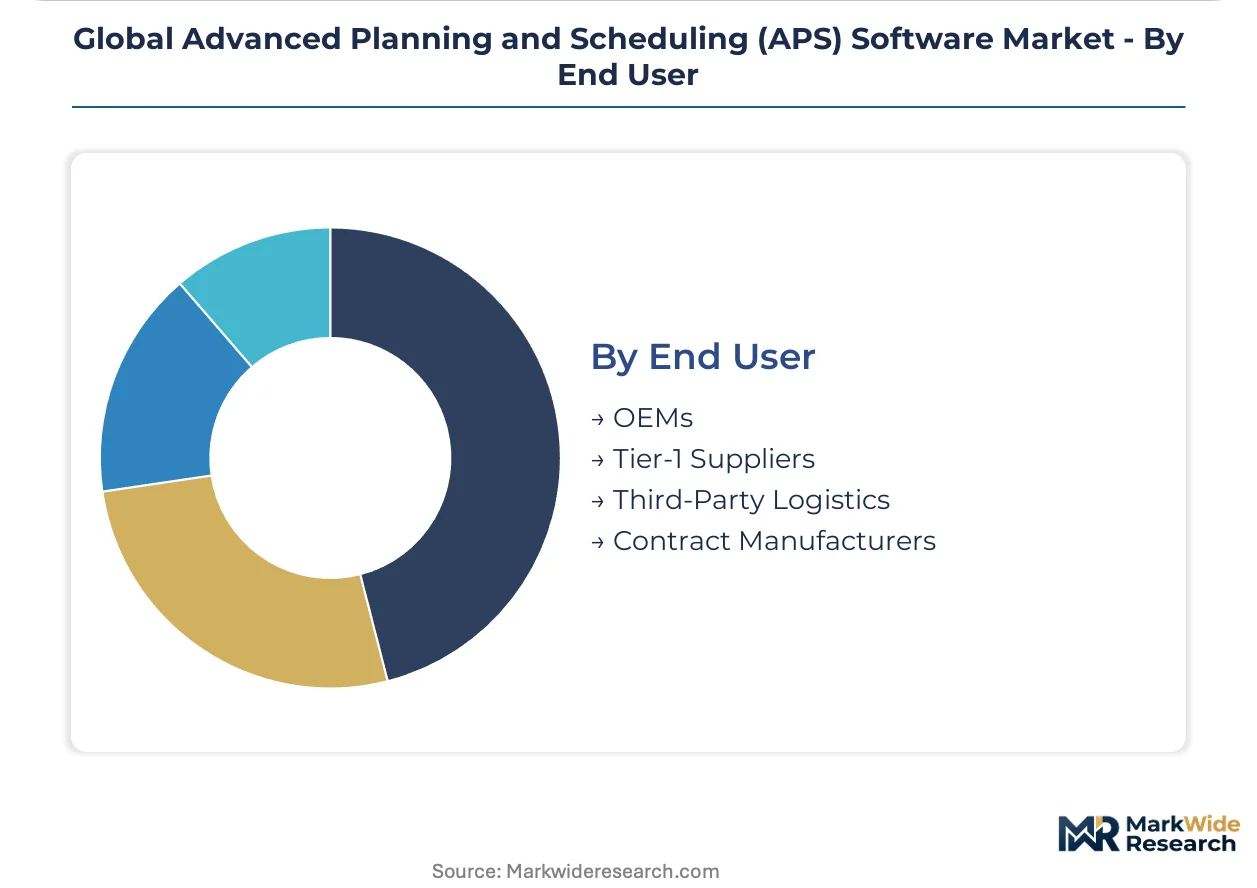
End User:
Supply chain position determines integration complexity, with OEMs orchestrating tiered supplier networks while contract manufacturers absorb planning as a service.
- OEMs:Enterprise-wide scheduling contracts anchor vendor relationships through embedded ERP manufacturing execution backbones. SAP S/4HANA integration secures long-term platform stickiness.
- Tier-1 Suppliers:Synchronous sequencing with OEM final assembly lines demands real-time API connectivity. German automotive suppliers invest in constraint solver customization.
- Third-Party Logistics:Metered cloud procurement replaces capital asset ownership. United States-based 3PLs now subscribe to planning capacity rather than licensing perpetual seats.
- Contract Manufacturers:Multi-customer environment complexity drives hybrid deployment preferences. Electronics and pharmaceutical contract manufacturers in India leverage PLI incentives for greenfield APS investment.
OEMs retain volume leadership; Contract Manufacturers expand most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Hamburg-Berlin high-speed rail corridor and Rhine-Alpine freight corridor underpin Germany's central role in synchronizing multi-site automotive production networks across the continent.
United States
Contract manufacturers and third-party logistics providers drive hybrid deployment adoption to balance latency-sensitive shop-floor control with centralized demand planning. FDA 21 CFR Part 11 electronic records requirements shape validation protocols for pharmaceutical APS implementations. The Midwest manufacturing belt around Detroit and Chicago hosts the densest concentration of automotive and industrial equipment scheduling deployments.
Germany
Automotive OEMs expand APS adoption to synchronize multi-site production networks across supplier tiers. EU CSRD supply-chain disclosure mandates accelerate replacement of legacy scheduling tools with carbon-accounting-integrated platforms. The Baden-Württemberg and Bavaria industrial clusters lead shop-floor-centric APS module procurement tied to PLC and MES hardware ecosystems.
Japan
Automotive OEMs require real-time coordination across distributed production networks, driving demand for federated planning engines. METI industrial policy emphasizes smart manufacturing interoperability standards. The Nagoya-Toyota industrial corridor and Kanto region around Tokyo represent the primary concentration of hybrid architecture deployments for multi-site synchronization.
China
State-owned manufacturing enterprises drive localization requirements under GB/T standards for industrial software interoperability administered by MIIT. Data residency constraints and cybersecurity regulations fragment cloud architecture roadmaps. The Yangtze River Delta around Shanghai and Pearl River Delta manufacturing clusters face the steepest reconfiguration burden for supply-chain disclosure compliance.
India
Electronics and pharmaceutical contract manufacturers receive production-linked incentives under the PLI scheme, creating greenfield APS deployments without legacy displacement. BIS standards and CDSCO regulations shape validation requirements for pharmaceutical implementations. The Karnataka and Tamil Nadu electronics manufacturing corridors host the fastest-expanding deployment base for cloud-native scheduling platforms.
Global Advanced Planning and Scheduling (APS) Software Market Competitive Landscape
Listed leaders compete with private specialists across database-tier integration and shop-floor hardware anchoring strategies. The vendor landscape exhibits tiered consolidation around enterprise ERP incumbents and vertical specialists. Three archetypes dominate: database-integrated platform providers, manufacturing execution backbone extenders, and constraint-solving engine specialists. M&A activity concentrates on acquiring operations research talent and API-first optimization startups, while geographic expansion targets India's PLI-driven greenfield opportunities.
Within the enterprise backbone tier, SAP SE and Oracle Corporation occupy positions that leverage embedded manufacturing execution integration and database-tier architecture respectively. Siemens AG exemplifies the shop-floor-centric archetype, extending industrial automation hardware dominance into software subscriptions. Blue Yonder Group, Inc. represents the supply-chain-focused specialist position. These three anchors illustrate how competitive positioning diverges between ERP-integrated breadth and vertical depth.
| Leading Market Players |
|---|
| SAP SE |
| Oracle Corporation |
| Blue Yonder Group, Inc. |
| Siemens AG |
| Dassault Systèmes SE |
| Kinaxis |
| Infor |
| ORTEC |
| Asprova |
| Others |
Supply & Pricing Matrix
Eighteen-month planning horizons in automotive and semiconductor fabs compress procurement cycles for constraint-solving engines, concentrating pricing power with vendors whose solvers demonstrate sub-minute latency on stochastic equipment downtime scenarios. This lead-time compression elevates solver performance above license cost as the decisive procurement criterion, reshaping how manufacturers allocate software budgets across hybrid deployment architectures.
Pricing Analysis
Volume-discount tiering structures stratify across enterprise-wide, plant-level, and module-specific licensing bands. Three-tier pricing separates perpetual seat licenses from annual SaaS subscriptions and metered cloud capacity consumed by third-party logistics providers. Price differentiation rests on ISO 27001 certification grade and embedded carbon-accounting capabilities for EU CSRD compliance. Cost compression in mid-tier manufacturing intensifies because edge-computing hardware requirements inflate total cost of ownership. Contract manufacturers in India exhibit highest price sensitivity due to PLI scheme margin constraints, while German automotive OEMs prioritize solver performance over unit cost.
Supply Chain Analysis
Inbound logistics costs through the Yangtze River Delta and Pearl River Delta manufacturing clusters face elevated container availability constraints on transpacific trade lanes. Cloud-native APS platform development concentrates in the United States, Germany, and Japan, drawing from specialized operations research talent pools and embedded ERP manufacturing execution ecosystems. Raw material dependencies span industrial-grade server components, time-sensitive networking hardware, and pre-validated pharmaceutical compliance modules. Single-source vulnerability concentrates in Taiwan and South Korea for semiconductor-grade optimization engines. Distribution runs through direct enterprise sales forces and hyperscaler marketplace integrations for mid-market SaaS procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
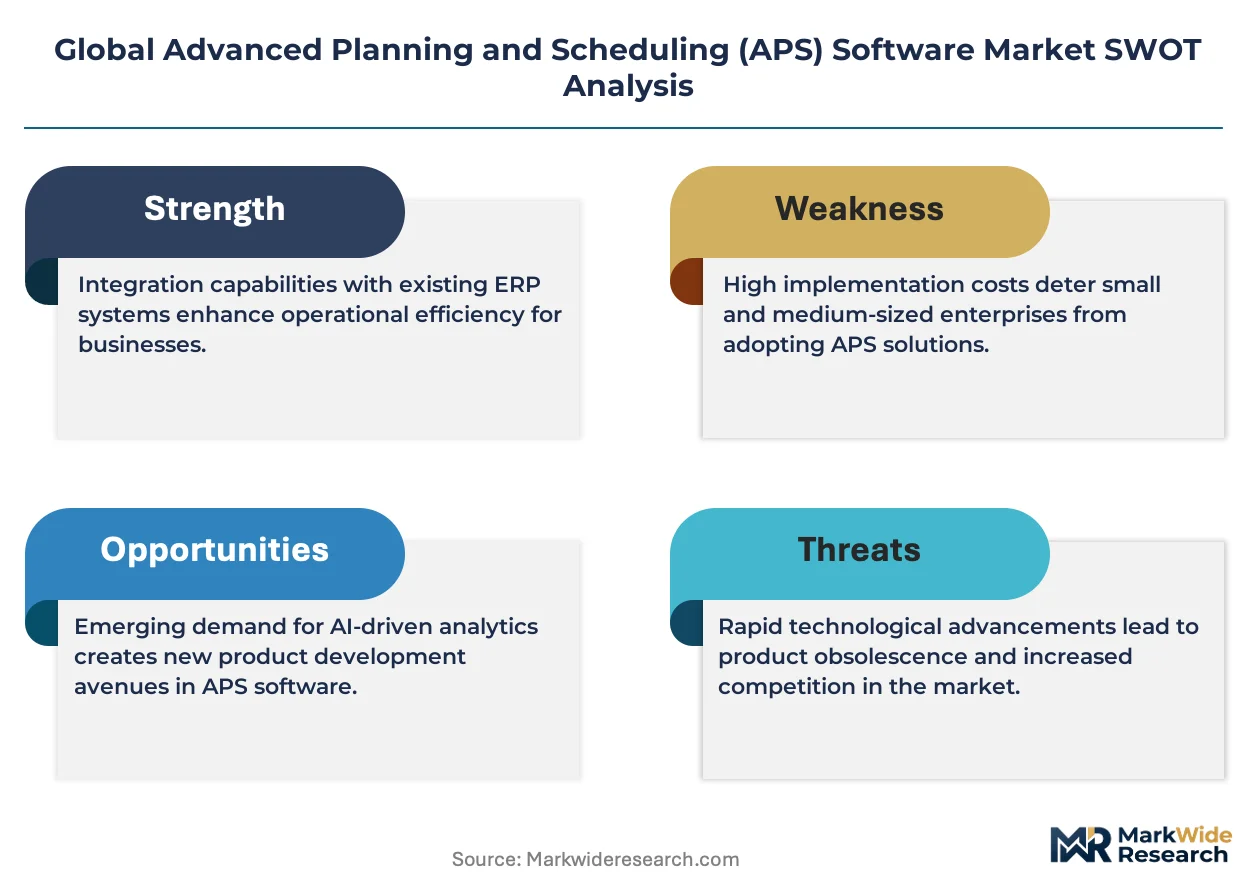
Incumbent APS vendors face substitution pressure from API-first optimization startups rearchitecting monolithic engines into microservices, threatening enterprise account retention through superior planning latency performance.
For Market Incumbents: Fortify embedded ERP integration moats by deepening manufacturing execution backbone connectivity and accelerating ISO 27001 continuous audit cycle automation. SAP SE and Oracle Corporation anchor enterprise-wide scheduling contracts through database-tier architecture lock-in. Siemens AG extends PLC and MES hardware dominance into software subscriptions. Threat from API-first competitors demands accelerated cloud-native rearchitecture or acquisition of constraint-solving engine specialists.
For New Entrants and Emerging Players: Anchor in India's PLI-driven greenfield electronics and pharmaceutical contract manufacturing corridors, where legacy displacement costs are minimized. Target hybrid deployment preferences among multi-customer contract manufacturers seeking latency-optimized shop-floor control with centralized demand planning. Go-to-market angle: pre-validated FDA 21 CFR Part 11 cloud modules for pharmaceutical compliance acceleration.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because operations research talent scarcity and ISO 27001 certification overhead favor scaled vendors with engineering resource depth. Acquisition target archetype: API-first optimization startups with graph neural network solver capabilities and established semiconductor fab deployments. Signal to watch: planning horizon compression below one hour as real-time execution convergence accelerates.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Rearchitecture | Microservices migration collapses planning latency from days to minutes for automotive OEMs. |
| Acquisition of Specialist Firm | Operations research talent scarcity drives M&A targeting constraint-solving engine startups. |
| Strategic Partnership | Hyperscaler alliances accelerate FDA 21 CFR Part 11 pre-validated module deployment. |
| Platform Integration | Embedded carbon-accounting capabilities address EU CSRD supply-chain disclosure mandates. |
| Geographic Expansion | India PLI scheme electronics corridors enable greenfield APS deployment without legacy displacement. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC 10-K filings, hyperscaler capex disclosures, and EU regulatory filings to validate market sizing and competitive positioning assessments. Primary interviews engaged CTOs, IT procurement officers, platform engineers, and integration specialists at automotive OEMs, semiconductor fabs, and pharmaceutical manufacturers across the United States, Germany, Japan, and India. Secondary validation drew from customs records, FDA 21 CFR Part 11 validation databases, and MIIT GB/T standard documentation. Bottom-up deployment counts triangulate against top-down vendor revenue attribution.
Segmentation dimensions modeled span deployment architecture, solution type, industry vertical, and end-user supply chain position across the projection horizon. Analytical framework derives CAGRs from algorithmic solver adoption curves, cloud migration velocity, and regulatory compliance deadline clustering. Forecast inputs include EU CSRD implementation timelines, India's PLI scheme incentive trajectories, and semiconductor fab capacity expansion patterns.
Material uncertainties — tariff exposure on industrial computing hardware, divergent data sovereignty regime enforcement, and operations research talent migration patterns — sit outside the modeled envelope. Forecasts reflect assumptions about cloud-native architecture adoption rates and hybrid deployment preference stability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Computer Software Market
Software & Services
Global Quantum Computing Software Market
Software & Services
Petcare Software Market
Software & Services
Global Photogrammetry Software Market
Software & Services
Global Project Software Market
Software & Services
Sales Platforms Software Market
Software & Services
Digital Illustration App Market
Software & Services
Contract Abstraction Software Market
Software & Services
Global Calendar Scheduling Software Market
Software & Services
POS Software Market
Software & Services
Invoice Processing Software Market
Software & Services
Software License Management (SLM) Market
Software & Services
Customer Self-Service Software Market
Software & Services
Vehicle Embedded Software Market
Software & Services
Image Analysis Software Market
Software & Services
App Development Software Market