
 Global Customer Success Software Market | 2026-2036
Global Customer Success Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Customer Success Software Market Analysis
Direct-to-customer digital channels are rewriting how customer success software reaches end users, with SaaS marketplaces and API-first integrations displacing traditional reseller networks. Gainsight, Inc. leverages deep workflow embedding within enterprise CRM stacks to sustain renewal rates above industry benchmarks. HubSpot, Inc. anchors its competitive position through inbound methodology alignment, while Freshworks, Inc. competes aggressively on price-performance ratios across mid-market segments.
Customer success software encompasses applications that monitor user behavior, calculate health scores, automate intervention workflows, and orchestrate onboarding journeys across subscription-based business models. These systems typically integrate via REST APIs with CRM, billing, and product analytics layers to trigger actions when usage thresholds or sentiment indicators deviate from expected patterns. Health scoring and automation tools command the widest deployment footprints among product type segments, with feedback management gaining traction as real-time sentiment analysis matures. Cloud-based and SaaS deployment modes dominate structural demand, though hybrid solutions attract regulated verticals in healthcare and financial services where data residency requirements persist.
The EU AI Act and GDPR constrain how European vendors deploy predictive churn models and automated customer communications, while the SEC's disclosure requirements in the United States push publicly traded software buyers toward auditable success metrics. ISO 27001 certification has become a baseline procurement filter for enterprise adopters evaluating vendor security postures. Stakeholders must weigh regulatory compliance costs against algorithmic personalization gains when selecting platform architectures for multi-jurisdiction deployments.
Market Dynamics
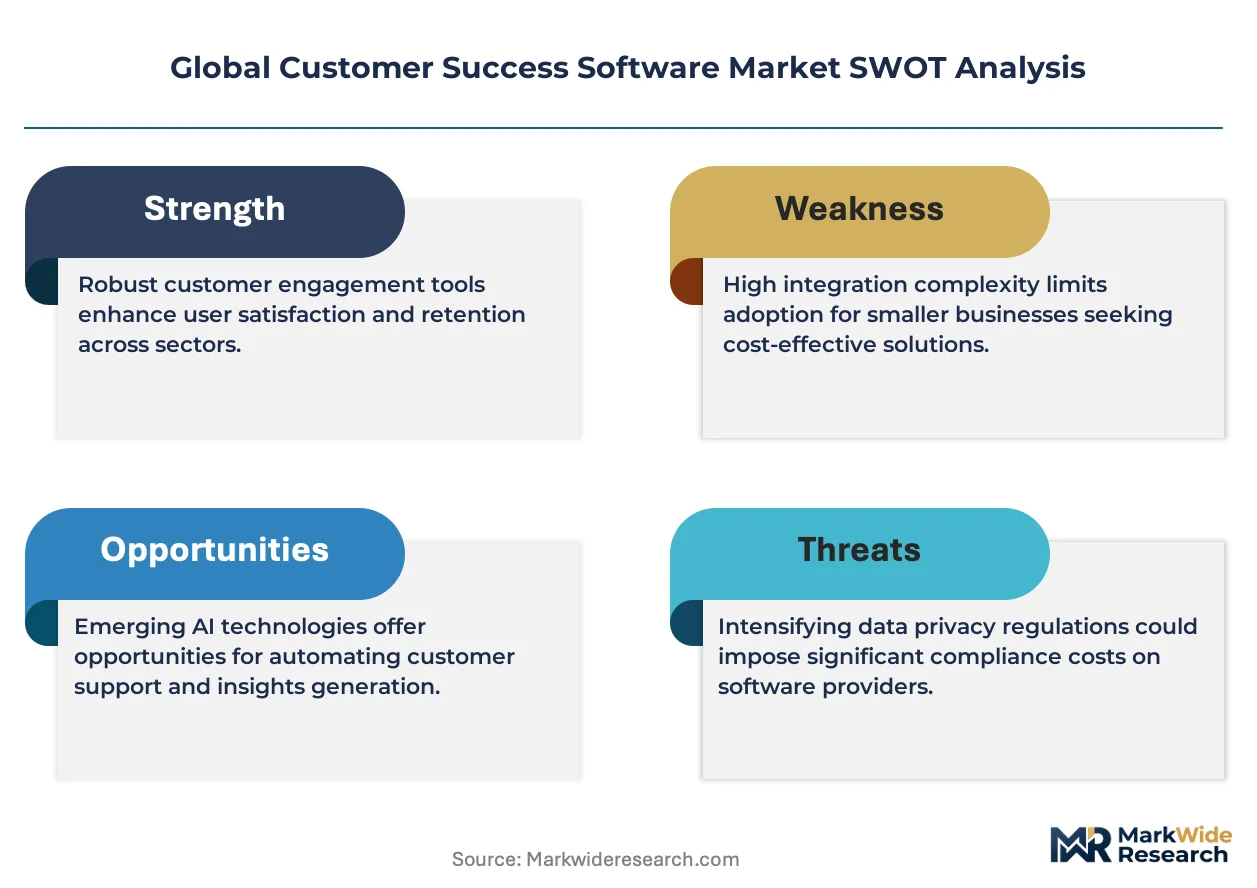
Health scoring algorithms and predictive churn models are compressing the customer success software market's value chain, forcing vendors to embed deeper into enterprise CRM and billing stacks to justify subscription pricing.
Growth Catalysts
- EU AI Act compliance mandates:European enterprises must deploy auditable customer engagement algorithms, creating procurement urgency for platforms with built-in explainability features and consent management workflows.
- Mid-market SaaS expansion:Digital-native companies in India and Germany are operationalizing customer success functions earlier in their lifecycle, driving demand for modular, API-first toolkits.
- Real-time sentiment analysis:Natural language processing advances enable instant intervention triggers based on support ticket tone and product review sentiment, reducing manual health score calibration.
Market Restraints
- GDPR algorithmic accountability:European vendors face elevated legal exposure when automated systems make retention decisions without human oversight, slowing predictive model deployment.
- Cloud infrastructure concentration:Hyperscaler dominance in compute and storage creates vendor lock-in risks for customer success platforms running multi-tenant architectures.
- Legacy CRM integration friction:On-premise SAP and Oracle installations resist REST API connectivity, forcing costly middleware development for enterprise deployments.
Strategic Opportunities
- India's PLI scheme for software:Production-linked incentives for digital infrastructure are lowering operational costs for vendors establishing development centers in Bangalore and Hyderabad.
- Healthcare vertical specialization:HIPAA-compliant health scoring for patient engagement platforms represents an underpenetrated segment with distinct workflow requirements.
- API marketplace distribution:HubSpot and Salesforce app exchanges are displacing traditional reseller channels, enabling direct developer adoption and faster proof-of-concept cycles.
Industry Challenges
- Data science talent scarcity:Vendors struggle to hire machine learning engineers capable of building interpretable churn models that satisfy both performance and compliance requirements.
- ISO 27001 certification timelines:Enterprise procurement filters now require current security credentials, creating six-to-twelve month sales cycle extensions for uncertified vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Customer Success Software Market |
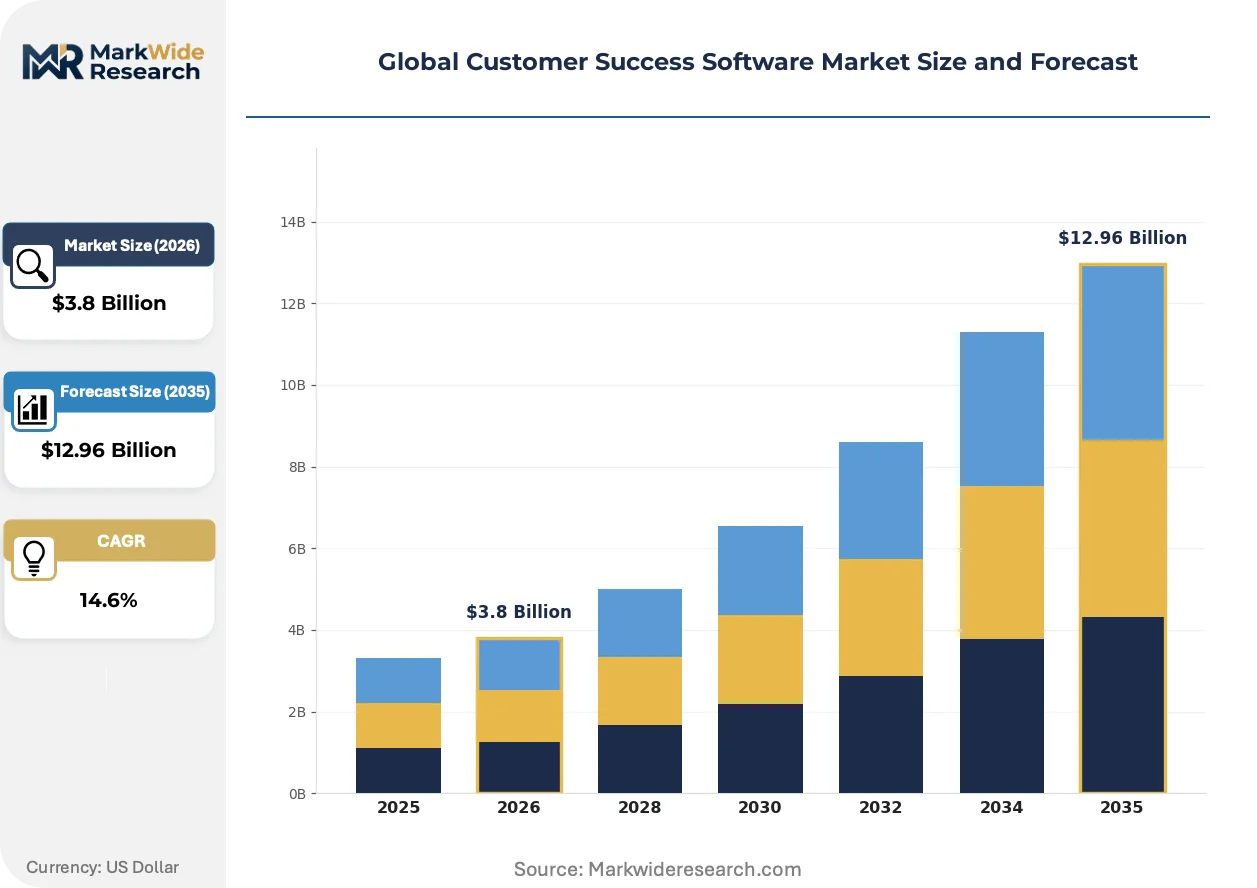
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
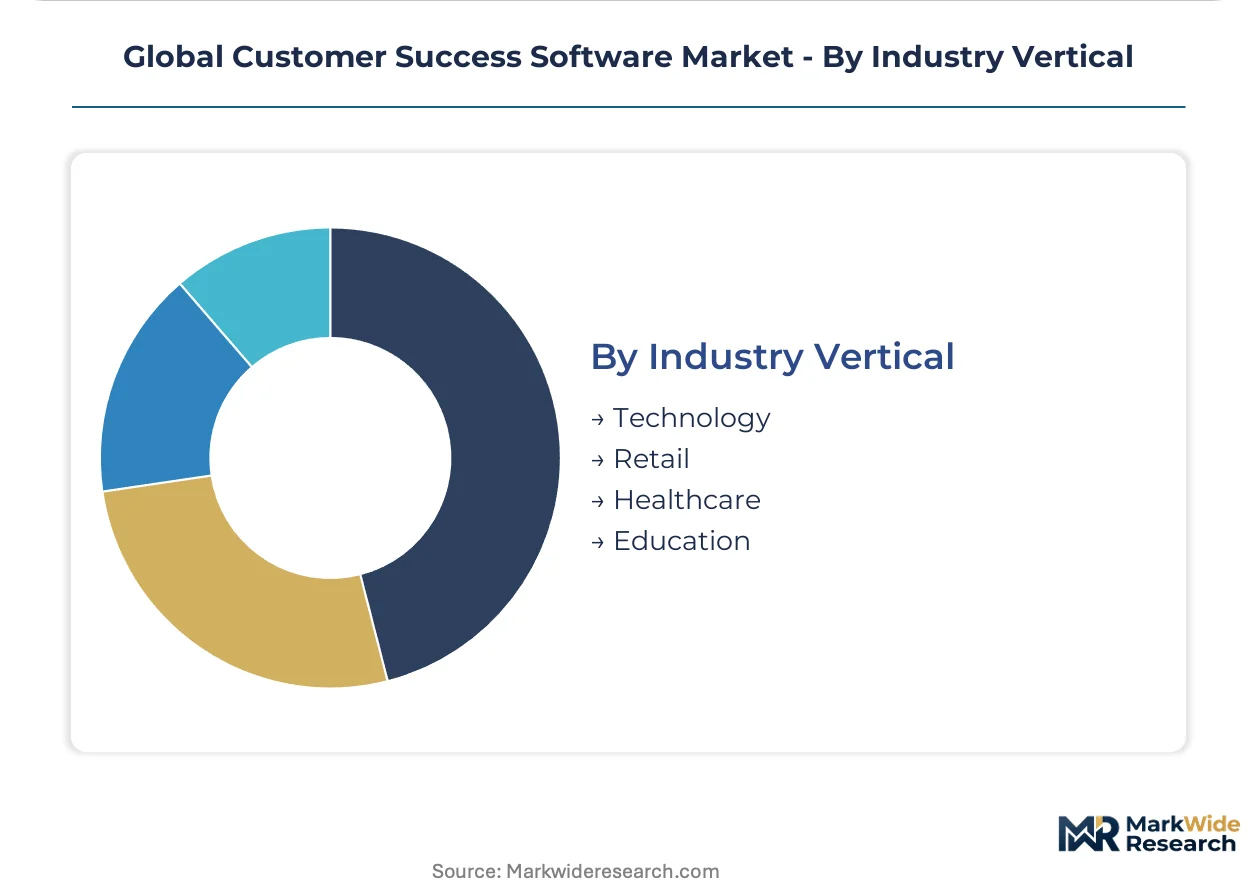
| Segmentation | Product Type: Onboarding Tools, Feedback Management, Health Scoring, Automation Tools Deployment: Cloud-based, On-premise, Hybrid Solutions, SaaS End User: SMBs, Enterprises, Startups, Non-profits Industry Vertical: Technology, Retail, Healthcare, Education |
| Companies Covered | Salesforce.com, Inc., Gainsight, Inc., HubSpot, Inc., Cisco Systems, Inc., Freshworks, Inc., Totango, Ltd., ChurnZero, Medallia, Inc., Planhat AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Customer Success Software Market Emerging Trajectories
Embedded workflow automation is reshaping how customer success software delivers value, with vendors racing to move from standalone dashboards to invisible infrastructure within daily user journeys.
Health scoring methodology is migrating from rules-based point systems to dynamic machine learning ensembles that weight behavioral signals by cohort and lifecycle stage. Mid-market SaaS operators in Germany are adopting these adaptive models fastest, replacing quarterly business reviews with automated trigger-based interventions. This compression of insight-to-action latency is reducing customer success headcount requirements per account.
The EU AI Act's risk classification framework is forcing European vendors to rearchitect predictive churn models as "limited risk" rather than "high risk" applications. Automated customer communications now require explicit consent logging and human-in-the-loop overrides for retention decisions. Healthcare and financial services buyers in France and Germany are demanding pre-built compliance documentation to accelerate procurement.
Enterprise buyers are consolidating vendor relationships by requiring customer success platforms to absorb adjacent functions—onboarding orchestration, feedback management, and expansion revenue forecasting—into unified contracts. SaaS marketplaces and API-first distribution are displacing traditional value-added reseller networks, particularly in the United States where procurement teams prefer direct vendor relationships with transparent usage-based pricing.
Global Customer Success Software Market Segmentation
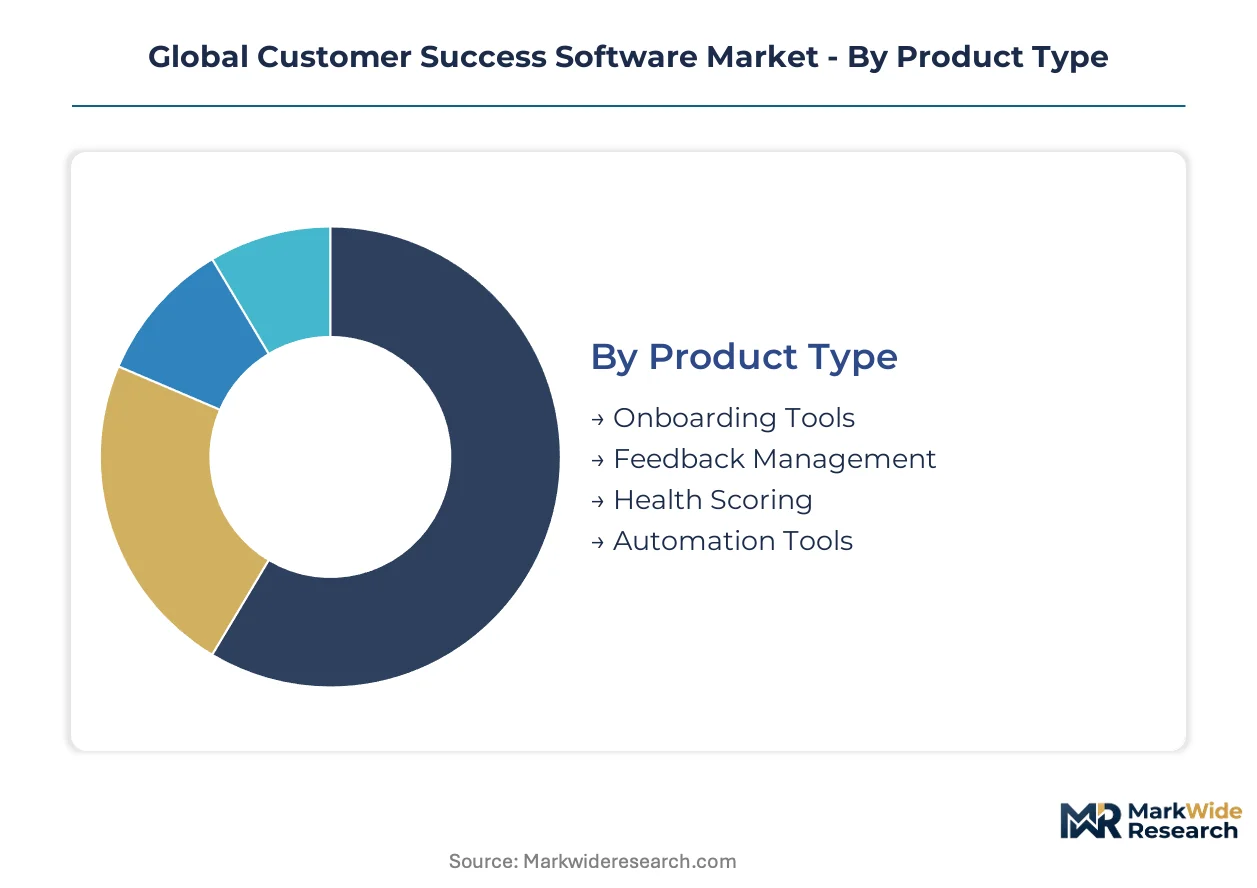
Segmentation in customer success software reveals distinct procurement cycles and integration complexity across buyer profiles. Enterprise deployments demand twelve-to-eighteen month implementation timelines, while SMB segments compress activation to weeks through self-service onboarding.
Product Type:
Health scoring algorithms refresh weekly in high-velocity SaaS environments, whereas onboarding tools see concentrated deployment spikes during Q1 budget cycles. Feedback management modules exhibit the longest sales cycles due to cross-functional stakeholder alignment requirements.
- Health Scoring:Machine learning ensembles weight product usage, support ticket sentiment, and billing history into composite risk indicators. Demand concentrates among mid-market SaaS operators in Germany replacing quarterly business reviews with automated triggers.
- Automation Tools:Workflow engines orchestrate intervention sequences across email, in-app messaging, and CRM task creation. Technology verticals in the United States deploy these most aggressively to reduce customer success headcount per account.
- Onboarding Tools:Journey orchestration platforms guide users through activation milestones with contextual guidance.
- Feedback Management:Real-time sentiment analysis pipelines processing NPS, CSAT, and qualitative inputs.
Health scoring dominates installed base. Automation tools are where expansion concentrates.
Deployment:
Cost tier stratification separates hyperscaler-native architectures from compliance-heavy hybrid stacks requiring dedicated infrastructure investment.
- SaaS:Multi-tenant architectures with usage-based metering and automatic feature delivery. Startups in India adopt these fastest through API-first procurement via Salesforce and HubSpot marketplaces.
- Cloud-based:Single-tenant instances on AWS, Azure, or GCP with dedicated resource pools. Healthcare enterprises in the United States favor these for HIPAA-aligned business associate agreements.
- Hybrid Solutions:Split architectures keeping PII on-premise while analytics processing shifts to cloud.
- On-premise:Fully air-gapped installations behind corporate firewalls with manual update cycles.
SaaS commands the largest subscriber base. Hybrid solutions are climbing the fastest as regulated verticals seek jurisdictional control.
End User:
Customer success function maturity varies dramatically—enterprises operate dedicated CS operations centers while startups embed success responsibilities within founding teams.
- Enterprises:Multi-year contracts with professional services overlays and custom integration development. These buyers in Germany require EU AI Act compliance documentation and ISO 27001 certification as baseline procurement filters.
- SMBs:Self-service adoption with credit-card procurement and standardized implementation playbooks. Technology sector concentration in the United States drives highest volume here.
- Startups:Founding-team-led success functions with tool consolidation priorities.
- Non-profits:Grant-funded deployments with donor reporting requirements and volunteer coordinator workflows.
Enterprises dominate contract value. SMBs are gaining share fastest as product-led growth normalizes CS tooling earlier in company lifecycles.
Industry Vertical:
Application-specific compliance requirements fragment vendor selection—healthcare demands HIPAA business associate agreements while retail prioritizes seasonal elasticity.
- Technology:Native SaaS operators with product-led growth engines and developer-centric onboarding. This vertical in the United States consumes the highest per-seat automation tool density.
- Healthcare:Patient engagement platforms and provider network management with stringent audit trails. HIPAA compliance requirements in the United States create vendor stickiness and extended procurement timelines.
- Retail:Seasonal customer bases with churn prediction focused on post-holiday retention.
- Education:Semester-aligned activation cycles with institutional procurement complexity.
Technology vertical dominates seat count. Healthcare is expanding most quickly as digital health platforms operationalize patient success functions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in United States enterprise contracts, while German procurement teams extract compliance documentation concessions that compress vendor margins. Indian mid-market adoption accelerates through API-first procurement channels at unit economics that reshape global pricing benchmarks.
United States
Enterprise SaaS operators in San Francisco and Seattle drive the highest per-seat automation density worldwide. SEC disclosure requirements push publicly traded buyers toward auditable success metrics with ISO 27001 certification as baseline filter. Technology vertical concentration in Silicon Valley and Austin sustains premium pricing for platforms embedding into Salesforce and HubSpot stacks.
Germany
Mid-market SaaS companies in Munich and Berlin operationalize customer success functions earlier than European peers, replacing quarterly reviews with automated triggers. EU AI Act mandates force rearchitecture of predictive churn models as limited-risk applications with human-in-the-loop overrides. Industrial software clusters in Baden-Württemberg demand pre-built compliance documentation to accelerate procurement cycles.
India
Digital-native enterprises in Bangalore and Hyderabad adopt modular API-first toolkits through self-service onboarding compressed to weeks. PLI scheme for software infrastructure lowers operational costs for vendors establishing development centers. Technology sector expansion in Delhi-NCR and Pune normalizes customer success tooling at earlier company lifecycles than Western markets.
United Kingdom
London-based financial services firms require hybrid deployments keeping PII on-premise while analytics processing shifts to cloud. GDPR algorithmic accountability constrains automated retention decisions without human oversight, slowing predictive model deployment. Fintech concentration in London and Manchester drives demand for HIPAA-aligned business associate agreements in adjacent health-tech verticals.
Japan
Enterprise buyers in Tokyo and Osaka favor single-tenant cloud instances with dedicated resource pools and extended implementation timelines. METI digital transformation incentives accelerate adoption of health scoring for manufacturing customer bases. Automotive and industrial software clusters in Nagoya and Osaka sustain demand for on-premise SAP and Oracle integrations requiring costly middleware development.
Global Customer Success Software Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream with narrower workflow embedding. The vendor base stratifies across three tiers: hyperscaler-native suites, independent vertical specialists, and API-first modular toolkits. Consolidation pressure favors vendors absorbing adjacent functions into unified contracts. Dominant competitive moves include M&A to capture onboarding orchestration capabilities and strategic partnerships with CRM hyperscalers to secure distribution.
Within the platform integrator tier, Salesforce.com, Inc. and HubSpot, Inc. exemplify archetypes that embed customer success workflows deeply within existing enterprise stacks. Gainsight, Inc. occupies a position representing the independent vertical specialist model with focused health scoring methodology. These three entities collectively illustrate how competitive positioning depends on distribution channel control rather than feature differentiation alone.
| Leading Market Players |
|---|
| Salesforce.com, Inc. |
| Gainsight, Inc. |
| HubSpot, Inc. |
| Cisco Systems, Inc. |
| Freshworks, Inc. |
| Totango, Ltd. |
| ChurnZero |
| Medallia, Inc. |
| Planhat AB |
| Others |
Supply Flow & Price Mechanics
Hyperscaler cloud infrastructure concentration in the United States anchors cost structures for customer success software vendors, compressing margins for European and Indian competitors who face higher compute procurement expenses. This upstream dependency forces pricing stratification across deployment models, with hybrid architectures commanding configuration premiums while SaaS tiers compete on volume efficiency.
Pricing Analysis
The customization-premium spread separates enterprise-configured deployments from self-service SaaS tiers by a factor of three to five in annual contract value. Subscription models dominate, with price differentiation driven by ISO 27001 certification grade and vertical-specific compliance documentation depth. Pricing pressure stems from API-first modular toolkits entering at aggressive unit economics, particularly from Indian development centers benefiting from PLI scheme incentives. SMB segments exhibit highest price sensitivity, while German and United States enterprises absorb premiums for EU AI Act auditable features and SEC-aligned disclosure capabilities.
Supply Chain Analysis
Export-control regimes on advanced GPU clusters and AI training hardware constrain compute access for European and Indian vendors, fragmenting infrastructure procurement strategies. Supply draws from United States hyperscaler data centers, Taiwanese semiconductor fabrication for AI accelerators, and Indian software engineering talent pools. Single-source vulnerability concentrates in NVIDIA-dominated GPU supply chains for machine learning model training. Distribution runs through SaaS marketplaces—Salesforce AppExchange and HubSpot ecosystem—displacing traditional reseller networks with direct API procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The customer success software market is recovering from a cyclical trough in enterprise procurement cycles, with SaaS vendor budget restorations and EU AI Act compliance deadlines driving replacement demand.
For Market Incumbents: Entrench platform positions by absorbing adjacent onboarding orchestration and feedback management functions into unified contracts before modular specialists capture expansion revenue. Invest in ISO 27001 certification maintenance and pre-built EU AI Act compliance documentation to defend against API-first entrants exploiting procurement friction. Prioritize Salesforce and HubSpot marketplace presence to control distribution channels where mid-market buyers consolidate vendor relationships. For New Entrants and Emerging Players: Healthcare vertical specialization in HIPAA-compliant health scoring represents the most penetrable entry point, with patient engagement platforms lacking purpose-built customer success tooling. India's PLI scheme-subsidized development centers enable cost structures that undercut incumbent pricing by thirty to fifty percent for equivalent feature sets. Pursue developer-led adoption through API-first distribution with transparent usage-based metering to compress proof-of-concept cycles. For Investors and Strategic Acquirers: Capital is best deployed toward vertical specialists with embedded workflow integration in healthcare or financial services, where compliance moats sustain pricing power through regulatory complexity. Long-term viability across a five-to-ten year window favors vendors with hybrid deployment architectures addressing data residency requirements. Monitor EU AI Act enforcement patterns and GDPR algorithmic accountability rulings as inflection indicators for compliance-documentation premium sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Deep embedding into Salesforce and HubSpot stacks captures renewal decision-making authority from standalone vendors. |
| Acquisition of Specialist Firm | Onboarding orchestration capabilities fill functional gaps that enterprise buyers now demand in consolidated contracts. |
| Geographic Expansion | Development center establishment in Bangalore and Hyderabad exploits PLI scheme subsidies to reshape global cost benchmarks. |
| Product Launch | EU AI Act-compliant health scoring modules with built-in explainability features address procurement urgency in Germany and France. |
| Strategic Partnership | Hyperscaler alliances with AWS and Azure secure compute allocation priority for machine learning model training pipelines. |
Methodological Framework
Initial hypotheses were tested against primary input from chief customer officers, VP customer success operations, enterprise IT procurement officers, and SaaS CFOs, then refined through secondary validation against SEC 10-K filings, hyperscaler capex disclosures, EU AI Act implementation guidance, and healthcare HIPAA audit documentation. Bottom-up segmentation modeling triangulated with top-down market sizing from CRM platform ecosystem data and API marketplace transaction velocity metrics.
Demand-supply balance framing anchored the analytical framework, with deployment model, organization size, vertical industry, and regional regulatory cluster serving as core segmentation dimensions across the analysis window. CAGRs were derived from cohort-based adoption curves weighted by compliance deadline impacts and SaaS vendor funding cycle recoveries. Forecast inputs incorporated EU AI Act enforcement timelines and Indian PLI scheme uptake rates as regional demand modifiers.
Practitioners should monitor EU AI Act risk classification rulings, GDPR algorithmic accountability case law, and hyperscaler compute pricing adjustments for early signals requiring forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Qualitative Data Analysis Software Market
Software & Services
Global Content Management Systems (CMS) Market
Software & Services
Global Gamification Software Market
Software & Services
Aviation Software Market
Software & Services
Global Gym Software Market
Software & Services
Session Support Software Market
Software & Services
Global Virtual Data Room (VDR) Market
Software & Services
Event Management Software Market
Software & Services
Global Email Management Software Market
Software & Services
Global Manufacturing Operations Management (MOM) Software Market
Software & Services
On-Demand Wellness Software Market
Software & Services
Global Configuration Management Software Market
Software & Services
Global Customer Experience Software Market
Software & Services
Global Translation Software Market
Software & Services
Landscaping Engineering Software Market
Software & Services
Ground Handling Software Market