
 Semiconductor Chip Test Probes Market | 2026-2036
Semiconductor Chip Test Probes Market Size, Share, and Industry Trends Forecast 2026-2036
Semiconductor Chip Test Probes Market Insights
Automotive semiconductor validation is expanding as a demand pillar for probe solutions, driven by functional safety requirements under ISO 26262. FormFactor leverages vertical integration across MEMS probe manufacturing to capture premium wafer-level test positions. Technoprobe sustains R&D intensity focused on advanced probe cards for sub-7nm nodes. MPI Corporation anchors geographic dominance through Taiwan-based production serving the island's concentrated foundry ecosystem.
Semiconductor chip test probes are precision electromechanical contactors, typically fabricated from beryllium copper or tungsten-rhenium alloys with tip diameters below 50 micrometers, designed to establish temporary electrical pathways between test equipment and device under test during wafer and packaged chip validation. Spring probes occupy the largest volume share due to their reusability and compatibility with high-pin-count BGA and LGA socket configurations. Cantilever probes represent the fastest-growing product category, driven by their critical role in wafer probing for advanced memory and logic devices where pitch shrinkage demands compliant contact structures. Reliability testing applications command margin concentration as automotive and aerospace end-users impose extended temperature cycling and mechanical stress qualification protocols.
FDA oversight of medical device semiconors and EPA restrictions on beryllium compound handling shape material selection and worker safety protocols for probe manufacturers operating in the United States. REACH and RoHS compliance in Europe constrain lead content and hazardous substance profiles in probe alloys and plating chemistries, elevating qualification costs for suppliers serving EU-based semiconductor firms. Stakeholders must monitor how China's NMPA and GB standards for medical and automotive electronics converge with environmental regulations to redefine probe material specifications and testing documentation requirements.
Market Dynamics
Advanced packaging architectures in high-performance computing are compressing probe pitch requirements below 35 micrometers while automotive functional safety mandates under ISO 26262 extend validation cycles. Probe card suppliers must reconcile these contradictory pressures through materials engineering and test protocol redesign.
Growth Catalysts
- Automotive functional safety mandates:ISO 26262 certification requirements for ADAS and powertrain semiconors are extending probe test cycles and expanding socket replacement rates in validation labs across Germany and Japan.
- Hsinchu Science Park concentration:Taiwan's foundry-OSAT clustering creates co-location efficiencies that compress probe logistics lead times and enable same-day engineering support for sub-7nm wafer test.
- GB standards compliance:China's dual carbon goals and energy-efficiency mandates for semiconductor manufacturing are accelerating beryllium-free probe alloy qualification programs.
Market Restraints
- Beryllium copper price volatility:EPA restrictions on beryllium compound handling in the United States have concentrated specialty alloy supply among three certified smelters, elevating raw material cost uncertainty.
- Taiwan production concentration:Over 70% of advanced probe card assembly capacity sits within earthquake-exposed zones on the island, creating single-point vulnerability for global logic device test.
- MEMS probe yield limitations:Microelectromechanical spring structures face dimensional repeatability challenges below 30 micrometer pitch, constraining adoption for next-generation DRAM interfaces.
Strategic Opportunities
- India OSAT buildout:PLI scheme incentives for semiconductor assembly and test are attracting probe socket vendors to establish technical service centers in Gujarat and Karnataka.
- Photonics test integration:Silicon photonics packaging for AI clusters is creating demand for electro-optical probe interfaces that bridge electrical signal integrity with optical coupling verification.
- CE marking pathway expansion:EU MDR and RoHS compliance documentation is becoming a competitive differentiator for probe suppliers targeting European automotive tier-1 semiconductor sourcing.
Industry Challenges
- MEMS process engineer scarcity:Wafer-level probe card fabrication requires combined expertise in semiconductor front-end processes and precision mechanical design, a skill intersection with limited trained personnel.
- Multi-site qualification timelines:Automotive probe sockets must pass AEC-Q100 validation across temperature cycling, mechanical shock, and humidity protocols, extending new product introduction cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Semiconductor Chip Test Probes Market |
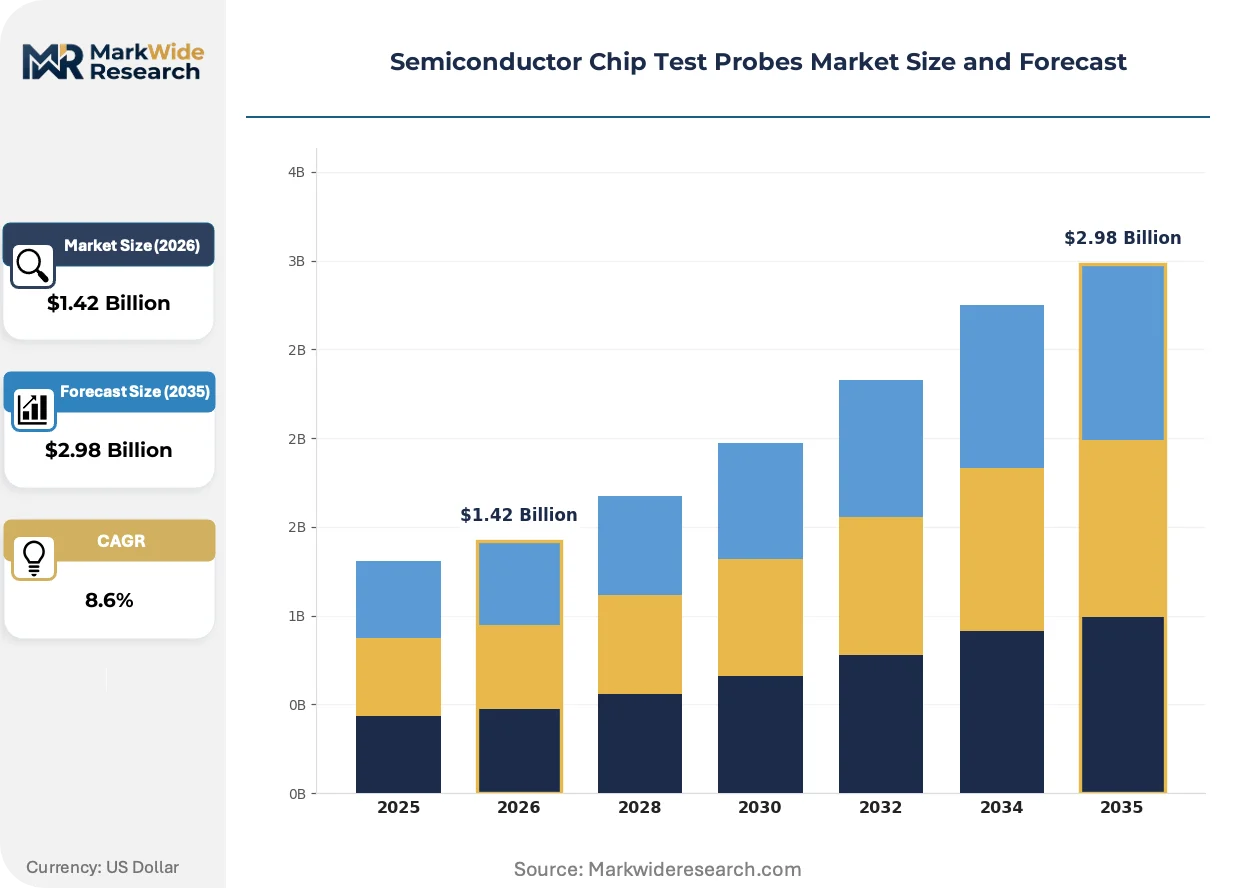
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.98 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spring Probes, Vacuum Probes, Cantilever Probes, Pin Probes Connector Type: BGA, LGA, PGA, Socket Adapter Application: Wafer Testing, IC Testing, Reliability Testing, Signal Integrity Testing End User: Semiconductor Manufacturers, Test Equipment Providers, R&D Laboratories, Electronics Firms |
| Companies Covered | FormFactor, MPI Corporation, Technoprobe, Japan Electronic Materials, Micronics Japan, Advantest, Feinmetall, Korea Instrument, SV Probe, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Semiconductor Chip Test Probes Market Trends and Innovations
Probe architecture is fragmenting between standardized spring sockets for packaged device test and custom cantilever arrays for wafer-level validation, with materials science emerging as the primary differentiation vector.
MEMS-based probe technology is modularizing traditional monolithic probe card architectures into interchangeable sub-assemblies. Leading foundries in Taiwan are adopting these segmented designs to reduce field replacement time from hours to minutes. This structural shift is compressing the economic viability window for conventional epoxy-ring probe cards in sub-5nm logic test.
REACH substance restrictions in Europe are forcing tungsten-rhenium alloy substitutions for legacy beryllium-copper probe tips. ECHA authorization requirements for carcinogenic materials have extended plating chemistry qualification timelines by 8-14 months. Probe manufacturers serving EU-based automotive semiconductor firms are responding with accelerated palladium-nickel alloy development programs.
Contract test houses are consolidating probe procurement under multi-year managed service agreements rather than transactional socket purchases. This vendor-managed inventory model displaces spot-buying through authorized distributors in North America and Western Europe. The shift is most pronounced among fabless semiconductor firms outsourcing final test to OSATs in Taiwan and Singapore.
Semiconductor Chip Test Probes Market Segmentation
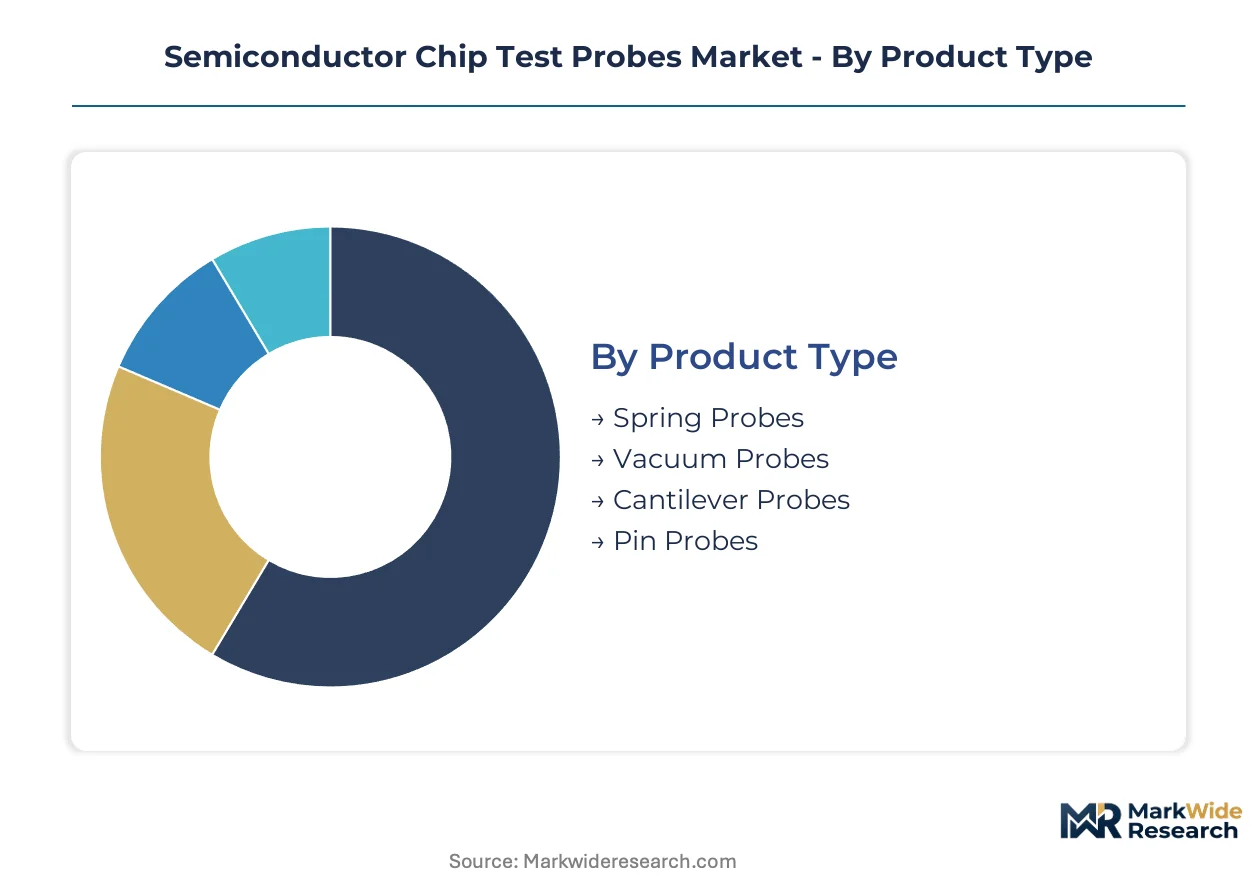
Test probe procurement patterns diverge sharply between high-volume packaged device validation and precision wafer-level inspection, with material specifications and contact geometries driving fundamentally different supplier selection criteria across end-use categories.
Product Type:
Buyers differentiate primarily by reusability economics versus pitch compliance requirements, trading off spring durability against cantilever density for advanced node probing.
- Spring Probes:Coiled beryllium copper or tungsten-rhenium contactors deliver repeatable insertion force across 10,000+ cycles. High-pin-count BGA and LGA socket configurations in Taiwan OSAT facilities consume the majority of volume, driven by packaged logic device test automation.
- Cantilever Probes:Compliant beam structures fabricated through MEMS processes achieve sub-35 micrometer pitch for wafer-level DRAM and logic validation. Foundry demand in Hsinchu Science Park is accelerating adoption as 3nm and 2nm nodes enter risk production.
- Vacuum Probes:Pneumatically actuated contact systems for temporary die handling in known-good-die testing applications.
- Pin Probes:Rigid needle-style contacts for burn-in oven environments requiring elevated temperature cycling endurance.
Spring probes lead volumes today; cantilever probes are gaining share fastest.
Connector Type:
Package form factor evolution in high-performance computing is fragmenting socket architectures between ball-grid and land-grid standards, with adapter solutions bridging legacy infrastructure.
- BGA:Ball grid array sockets accommodate solder sphere pitches down to 0.35mm for GPU and AI accelerator packages. NVIDIA and AMD reference designs are standardizing BGA probe configurations in validation labs across Germany and Japan.
- LGA:Land grid array interfaces eliminate solder balls for CPU and FPGA test, enabling higher pin density with reduced contact resistance. Intel and AMD server processor qualification programs in Oregon and Penang are driving LGA probe card refresh cycles.
- PGA:Pin grid array legacy sockets for automotive microcontroller burn-in applications requiring through-hole mechanical stability.
- Socket Adapter:Interposer solutions enabling probe card reuse across multiple package generations, popular among contract test houses managing diverse customer portfolios.
BGA connectors dominate current procurement; LGA configurations are expanding most quickly in datacenter semiconductor validation.
Application:
Test protocol duration and environmental stress severity separate wafer-level screening from packaged device qualification, with automotive reliability mandates extending cycle times disproportionately.
- Wafer Testing:Full-wafer probe card contact for die sort and parametric screening prior to dicing. Taiwan foundries are compressing probe card replacement intervals below 48 hours for sub-5nm logic ramp.
- Reliability Testing:Accelerated life testing under temperature cycling, mechanical shock, and humidity stress per AEC-Q100 and MIL-STD protocols. Automotive tier-1 semiconductor suppliers in Nagoya and Stuttgart are expanding socket capacity for extended qualification cycles.
- IC Testing:Final packaged device functional test at OSAT facilities, characterized by high throughput and rapid socket changeover requirements.
- Signal Integrity Testing:High-frequency characterization for 112Gbps SerDes and HBM interface validation in AI training chip development.
Wafer testing commands the largest probe card spend; reliability testing is climbing the fastest as automotive safety mandates tighten.
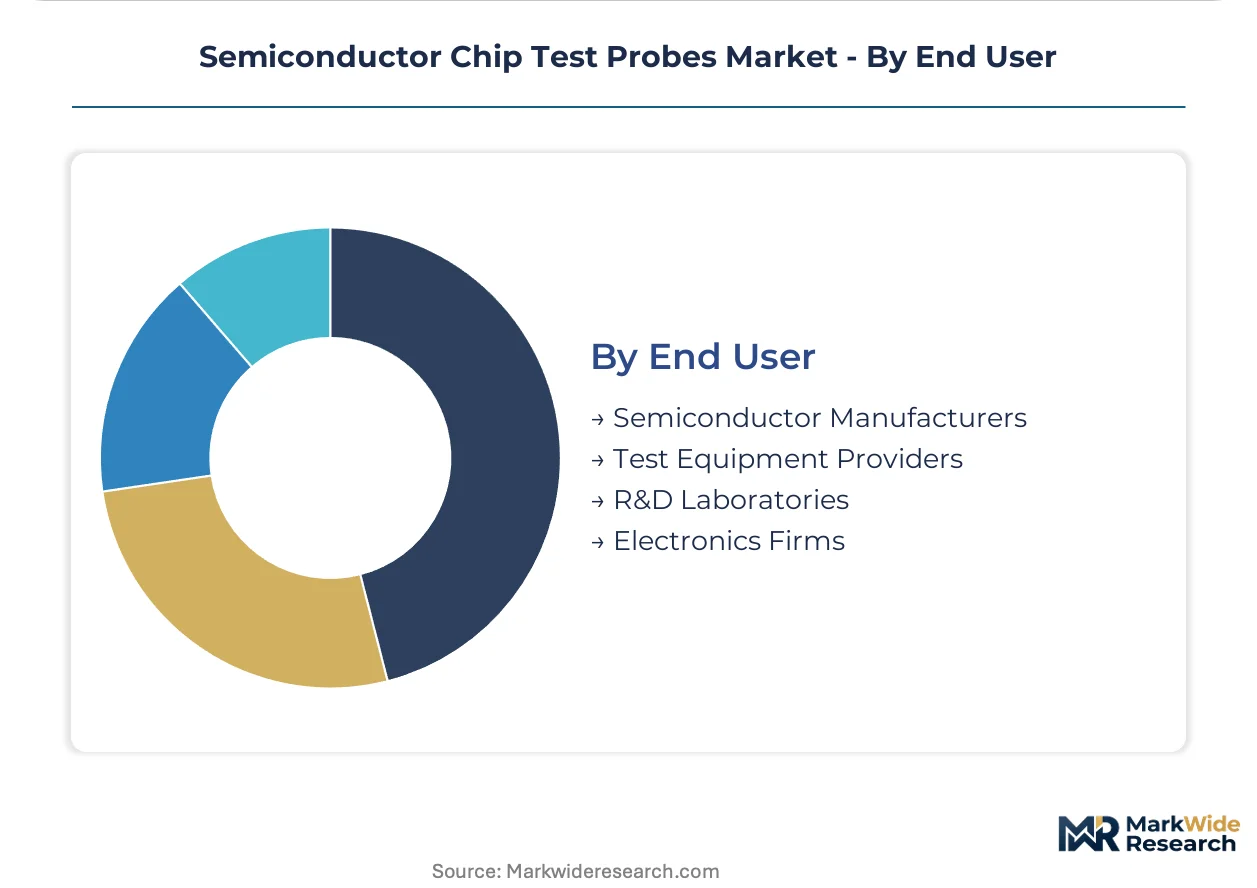
End User:
Capital intensity and in-house versus outsourced test strategy determine procurement centralization, with IDMs maintaining captive probe engineering capabilities while fabless firms rely on OSAT-managed inventory.
- Semiconductor Manufacturers:Integrated device manufacturers and foundries with captive probe card design teams, primarily concentrated in Taiwan and South Korea. Samsung and TSMC internal probe engineering groups specify custom cantilever arrays for leading-edge nodes.
- Test Equipment Providers:Advantest and Teradyne system integration requirements drive standardized socket interface specifications for tester-probe interoperability.
- R&D Laboratories:University and corporate research facilities requiring low-volume, high-flexibility probe configurations for emerging device architectures.
- Electronics Firms:System-level integrators performing incoming inspection and failure analysis on semiconductor components.
Semiconductor manufacturers account for the dominant share of probe procurement; test equipment providers are expanding their influence fastest through system-level specification control.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting probe manufacturing footprints as REACH compliance costs in Europe and EPA beryllium handling restrictions in the United States elevate production economics in Asian jurisdictions with streamlined environmental permitting.
United States
Automotive functional safety validation under ISO 26262 is expanding probe socket demand among Detroit and Austin semiconductor design centers. EPA restrictions on beryllium compound handling have concentrated specialty alloy supply among certified domestic smelters. Oregon's Silicon Forest hosts Intel's server processor qualification programs driving LGA probe card refresh cycles.
Germany
ADAS semiconductor development in Stuttgart and Munich is extending probe test cycles for powertrain validation. REACH substance restrictions through ECHA are forcing tungsten-rhenium alloy substitutions for legacy probe tip materials. Bavaria's automotive tier-1 supplier cluster is expanding socket capacity for extended AEC-Q100 qualification protocols.
China
Dual carbon goals and GB standards for energy-efficient semiconductor manufacturing are accelerating beryllium-free probe alloy qualification programs. NMPA oversight of medical device semiconductors is tightening material specifications and testing documentation requirements. Yangtze River Delta foundries are compressing probe card replacement intervals below 48 hours for sub-5nm logic ramp.
Taiwan
Hsinchu Science Park clustering creates co-location efficiencies that compress probe logistics lead times and enable same-day engineering support for sub-7nm wafer test. Over 70% of advanced probe card assembly capacity sits within earthquake-exposed zones on the island. Foundry-OSAT proximity is accelerating MEMS-based probe technology adoption for segmented probe card architectures.
Japan
Automotive semiconductor burn-in applications in Nagoya are driving PGA socket demand for microcontroller validation. METI industrial standards are shaping probe material specifications for domestic semiconductor equipment integration. Kyushu's silicon island hosts specialized probe engineering groups serving Toyota and Honda tier-1 sourcing requirements.
Semiconductor Chip Test Probes Market Competitive Landscape
Capacity expansion dominates the current landscape as probe card suppliers add cleanroom assembly lines to address Taiwan foundry demand compression. The vendor base separates into three tiers: integrated MEMS fabricators with captive semiconductor front-end capabilities, precision mechanical specialists serving packaged device test, and regional socket assemblers competing on logistics proximity. Two archetypes are emerging: vertically integrated probe card designers controlling MEMS manufacturing in-house, and modular sub-assembly suppliers enabling field-replaceable cantilever arrays. Geographic expansion into India and strategic partnerships for photonics test integration represent the dominant competitive vectors.
Among Asia-Pacific-based fabricators, FormFactor exemplifies the vertically integrated archetype through its control over MEMS probe manufacturing processes. Technoprobe occupies a position within the R&D-intensive tier focused on advanced node development. MPI Corporation anchors the geographic concentration archetype through Taiwan-based production serving the island's foundry ecosystem. Feinmetall represents European precision mechanical expertise in spring probe fabrication for automotive validation applications.
| Leading Market Players |
|---|
| FormFactor |
| MPI Corporation |
| Technoprobe |
| Japan Electronic Materials |
| Micronics Japan |
| Advantest |
| Feinmetall |
| Korea Instrument |
| SV Probe |
| Others |
Pricing and Supply Chain Analysis
Family-owned precision mechanical specialists concentrated in Germany and Japan anchor probe socket production, enabling disciplined pricing through long-term customer relationships while resisting margin compression from Asian contract manufacturers. Their ownership structure insulates pricing decisions from quarterly earnings pressure, sustaining premium positioning for automotive validation applications despite cost competition from Taiwan-based MEMS fabricators.
Pricing Analysis
Distributor margin layers in North America and Western Europe add fifteen to twenty-five points above direct-to-foundry pricing in Taiwan, compressing price realization for suppliers without captive channel control. Three-tier pricing structure across automotive-grade, industrial-grade, and commercial-grade certification levels separates ISO 26262-qualified probe cards from standard socket configurations. Cost compression in commercial-grade spring probes is intensifying because OSAT procurement teams consolidate volume under multi-year managed service agreements. Fabless semiconductor firms outsourcing final test exhibit highest price sensitivity; captive IDM probe engineering groups prioritize performance metrics over unit cost.
Supply Chain Analysis
Returns and refurbishment flows for epoxy-ring probe cards extend asset life in burn-in oven applications, creating secondary supply streams that compete with new socket sales in price-sensitive segments. Raw material supply draws from beryllium copper smelters in the United States, tungsten-rhenium alloy producers in Germany, and palladium-nickel plating chemistry specialists in Japan. Single-source vulnerability concentrates in Taiwan's Hsinchu Science Park, where seismic exposure threatens seventy percent of advanced probe card assembly capacity. Distribution runs through authorized distributors in North America and Western Europe, shifting toward vendor-managed inventory at Taiwan and Singapore OSAT facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EPA beryllium handling restrictions in the United States elevate production economics for Asian jurisdictions with streamlined environmental permitting.
For Market Incumbents: Anchor MEMS fabrication capabilities in Taiwan's Hsinchu Science Park cluster to maintain same-day engineering support relationships with leading foundries. Defend against modular sub-assembly suppliers by accelerating segmented probe card architectures that reduce field replacement intervals. Certification investment in China's GB standards for energy-efficient semiconductor manufacturing opens procurement pathways into Yangtze River Delta foundries. For New Entrants and Emerging Players: Direct-to-OSAT digital procurement platforms bypass established distributor relationships in North America and Western Europe, enabling price-transparent socket sourcing for mid-tier fabless firms. White-space targets include India's Gujarat and Karnataka OSAT buildout under PLI scheme incentives, plus silicon photonics packaging for AI cluster electro-optical probe interfaces. The most penetrable segment is contract test house managed service agreements displacing spot-buying through authorized distributors. For Investors and Strategic Acquirers: Semiconductor test equipment providers are the most active acquirer in this space, seeking probe card capabilities to bundle with system-level sales. Long-term viability hinges on MEMS process engineering talent scarcity and the five-to-ten year transition window for sub-5nm logic node adoption. Watch for AEC-Q100 validation timeline extensions as the inflection indicator signaling automotive probe socket replacement rate acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| MEMS Fabrication Scale-Up | Captive MEMS production in Taiwan compresses lead times for sub-7nm wafer probe cards. |
| GB Standards Compliance Program | Beryllium-free alloy qualification aligns probe suppliers with China's dual carbon mandates. |
| Managed Service Agreement Expansion | Multi-year vendor-managed inventory contracts displace spot-buying through North American distributors. |
| Photonics Test Integration Partnership | Electro-optical probe interfaces address silicon photonics packaging for AI training clusters. |
| India Technical Service Center Buildout | Gujarat and Karnataka facilities capture PLI scheme incentives for semiconductor assembly and test. |
Research Methodology
Bottom-up wafer-level and packaged-device test modeling reconciled against top-down probe card supplier capacity tracking forms the analytical core. Primary interviews with probe card design engineers, OSAT procurement managers, foundry test integration specialists, and semiconductor equipment sales directors combined with secondary validation from SEC filings, Taiwan Stock Exchange disclosures, customs trade data, and SEMI equipment market statistics. Triangulation across these sources ensures demand-side consumption patterns align with supply-side shipment reports.
Input-output matrices map probe card unit demand by node generation against foundry capex cycles and OSAT test floor expansion plans. Segmentation dimensions include product type, connector standard, application protocol, and end-user capital intensity across the projection horizon. CAGRs derive from regression analysis of historical probe card replacement intervals correlated with semiconductor node transition timelines. Industry-specific forecast inputs incorporate MEMS probe yield trajectories and AEC-Q100 validation cycle extensions for automotive safety mandates.
The model assumes a particular technology adoption path; alternative pathways for MEMS-based segmented probe card architectures would alter the outlook if dimensional repeatability challenges below thirty micrometer pitch resolve faster than baseline assumptions. Practitioners should monitor EPA beryllium compound handling rule revisions, Taiwan seismic event frequency, and China GB standards enforcement intensity for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Silicon Photonics and Optical I/O Test and Measurement Systems Market
Test and Measurement
Leak Testing Market
Test and Measurement
Battery Testing Equipment Market
Test and Measurement
Hearing Aid and True Wireless Earbud Acoustic Performance Test Systems Market
Test and Measurement
Tribometer Market
Test and Measurement
Global Arbitrary Waveform Generator Market
Test and Measurement
MEMS and Sensor Performance and Reliability Test Equipment Market
Test and Measurement
In-Process Composite Layup Monitoring Sensors and Test Equipment Market
Test and Measurement
Wafer Testing Services Market
Test and Measurement
DSL Tester Market
Test and Measurement
Electrolyzer Test System Market
Test and Measurement
Signal Generator Market
Test and Measurement
Marine Electronics Tester Market
Test and Measurement
Surface Vision and Inspection Equipment Market
Test and Measurement
Sand Abrasion Tester Market
Test and Measurement
High-Aspect-Ratio 3D NAND Metrology Equipment Market