
 Global Arbitrary Waveform Generator Market | 2026-2036
Global Arbitrary Waveform Generator Market Size, Share, and Industry Trends Forecast 2026-2036
Global Arbitrary Waveform Generator Market Analysis
Defense electronics procurement is rotating toward commercial-off-the-shelf arbitrary waveform generator platforms with classified waveform libraries. Keysight Technologies leverages in-house semiconductor fabrication to control DAC linearity specifications across its PXIe portfolio. TEKTRONIX, INC. anchors its position through deep calibration service networks in aerospace hubs. Rohde & Schwarz competes on vector signal generation integration, bundling arbitrary waveform capability with real-time spectrum analysis.
An arbitrary waveform generator produces user-defined electrical waveforms with programmable amplitude, frequency, and phase parameters, typically achieving sample rates from hundreds of MSa/s to tens of GSa/s with vertical resolutions of 8 to 16 bits; its primary purpose is emulating complex real-world signals for device validation before physical deployment. Multi-channel product configurations command premium positioning because phased array radar and MIMO communications testing require precise inter-channel synchronization. Software-based technology is displacing hardware-centric architectures as Python and MATLAB APIs allow test engineers to deploy custom waveforms without proprietary firmware constraints.
FCC Part 15 emissions testing and EU CE marking directives enforce spectral purity benchmarks that arbitrary waveform generators must demonstrably exceed during equipment-under-test validation. FDA 21 CFR Part 820 quality system regulations shape medical device manufacturers' instrument qualification protocols, while China's GB/T national standards and MIIT radio transmission certifications create parallel compliance pathways for domestic 5G base station deployments. Stakeholders must monitor whether open-source waveform definition formats gain traction among automotive radar developers, as this would erode proprietary software lock-in that currently protects incumbent margins.
Market Dynamics
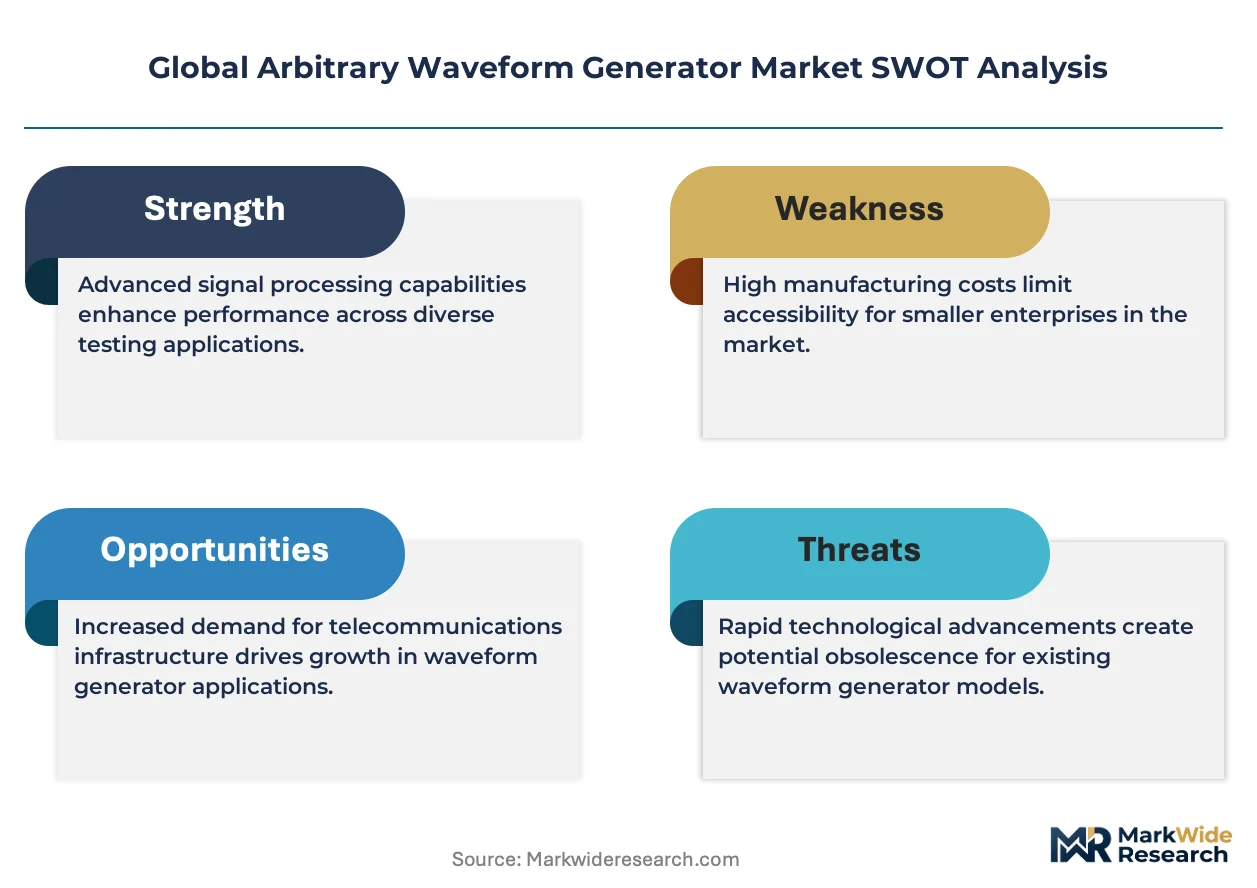
Software-defined instrument architectures are compressing hardware refresh cycles across test and measurement portfolios, forcing incumbent vendors to unbundle firmware from signal generation hardware.
Growth Catalysts
- IEEE 802.11be mandates:Wi-Fi 7 protocol validation requires sub-nanosecond timing precision that only multi-channel arbitrary waveform generators deliver.
- 6G research programs:Germany, South Korea, and the United States are funding terahertz-band signal emulation for pre-standardization testing.
- East Asian semiconductor clusters:Taiwan and South Korea fabs are procuring high-channel-count instruments for wafer-level RF characterization.
Market Restraints
- Gallium nitride substrate costs:High-performance DACs depend on GaN foundry capacity concentrated in Taiwan and Japan.
- FCC Part 15 compliance burden:Spectral purity documentation adds 12-18 months to product qualification for US market entry.
- Direct digital synthesis substitution:Lower-cost DDS chips capture basic function generator applications below 500 MHz.
Strategic Opportunities
- India PLI scheme:Telecom manufacturing incentives are creating domestic test equipment demand for 5G base station exports.
- Automotive radar validation:77-81 GHz FMCW signal libraries for ADAS sensor testing remain underdeveloped relative to communications.
- Python API integration:Open-source waveform definition formats threaten proprietary software lock-in among research institutions.
Industry Challenges
- RF calibration expertise scarcity:Phased array synchronization requires specialized metrologists concentrated in aerospace corridors.
- Legacy GPIB infrastructure:Defense contractors maintain decades-old bus architectures that complicate modern PXIe migration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Arbitrary Waveform Generator Market |
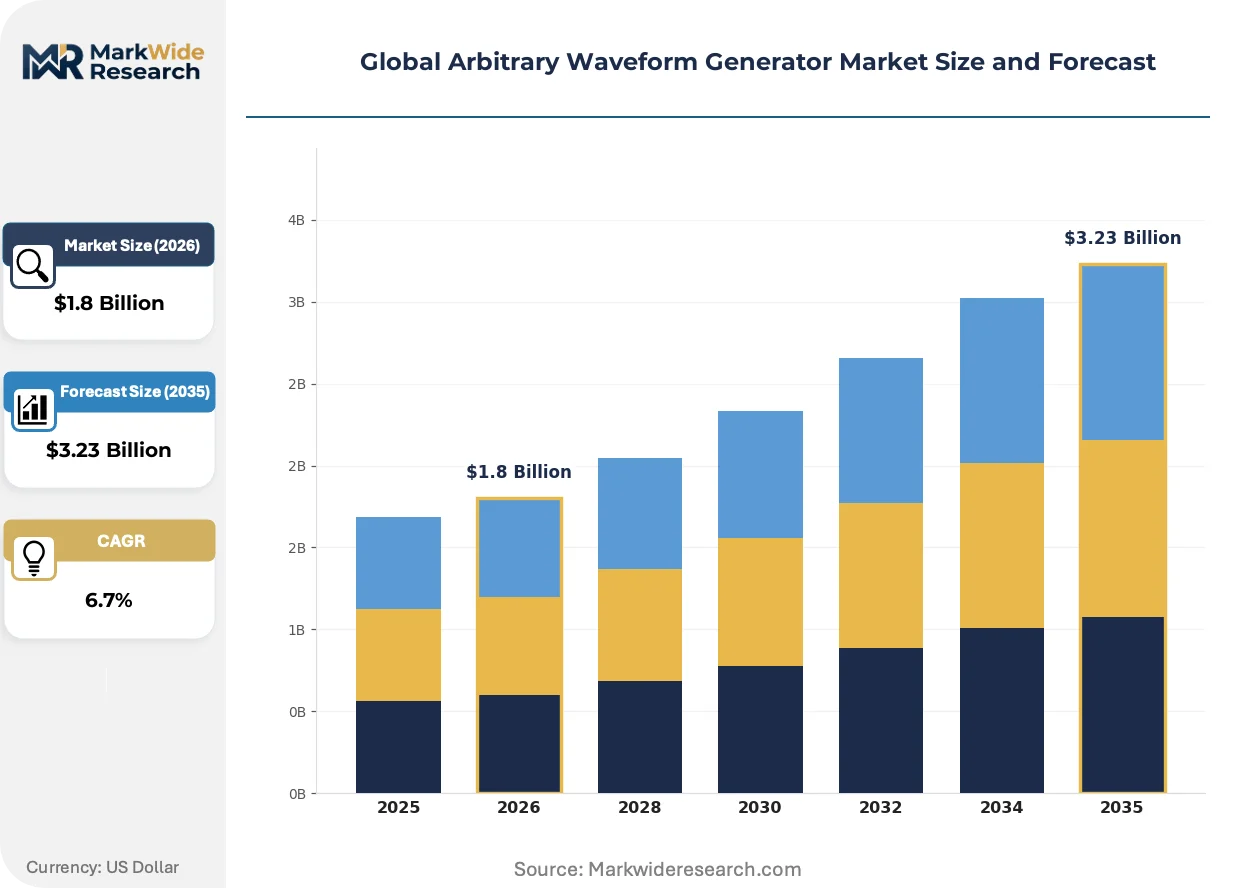
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital, Analog, Hybrid, Multi-Channel Technology: FPGA, Direct Digital Synthesis, Software-Based, Thermoelectric End User: Aerospace, Automotive, Telecommunications, Research Labs Application: Signal Simulation, Testing & Measurement, Communication, Signal Processing |
| Companies Covered | Keysight Technologies, TEKTRONIX, INC., Rohde & Schwarz, NATIONAL INSTRUMENTS CORP., B&K Precision Corporation, Fluke Corporation, Teledyne Technologies Incorporated, ANRITSU CORPORATION, Yokogawa Test & Measurement Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Arbitrary Waveform Generator Market Emerging Trajectories
Arbitrary waveform generation is fragmenting across two incompatible performance tiers: ultra-high-sample-rate hardware for defense and semiconductor validation, versus API-accessible cloud instruments for software-centric workflows.
Direct-to-RF DAC architectures are bifurcating the signal chain. These converters eliminate intermediate frequency stages by generating carrier frequencies directly at microwave bands. Defense electronics primes in the United States are adopting 64 GSa/s converters for electronic warfare simulation. The technology is compressing rack-space requirements while fragmenting vendor ecosystems between RF semiconductor specialists and traditional test equipment houses.
EU F-Gas Regulation restrictions on fluorinated greenhouse gases are reshaping thermal management in high-density arbitrary waveform generator chassis. Liquid cooling loops are displacing compressor-based refrigeration in instruments exceeding 8 channels. German aerospace test facilities are retrofitting existing racks to accommodate sealed-loop cooling, while Asian manufacturers face compliance timelines lagging European adoption by 18-24 months.
Subscription-based waveform library access is displacing perpetual software licenses. Research institutions in South Korea and Germany now procure signal definitions through annual contracts rather than capitalized IP purchases. This unbundling compresses upfront instrument costs while shifting margin capture toward recurring revenue pools.
Global Arbitrary Waveform Generator Market Segmentation
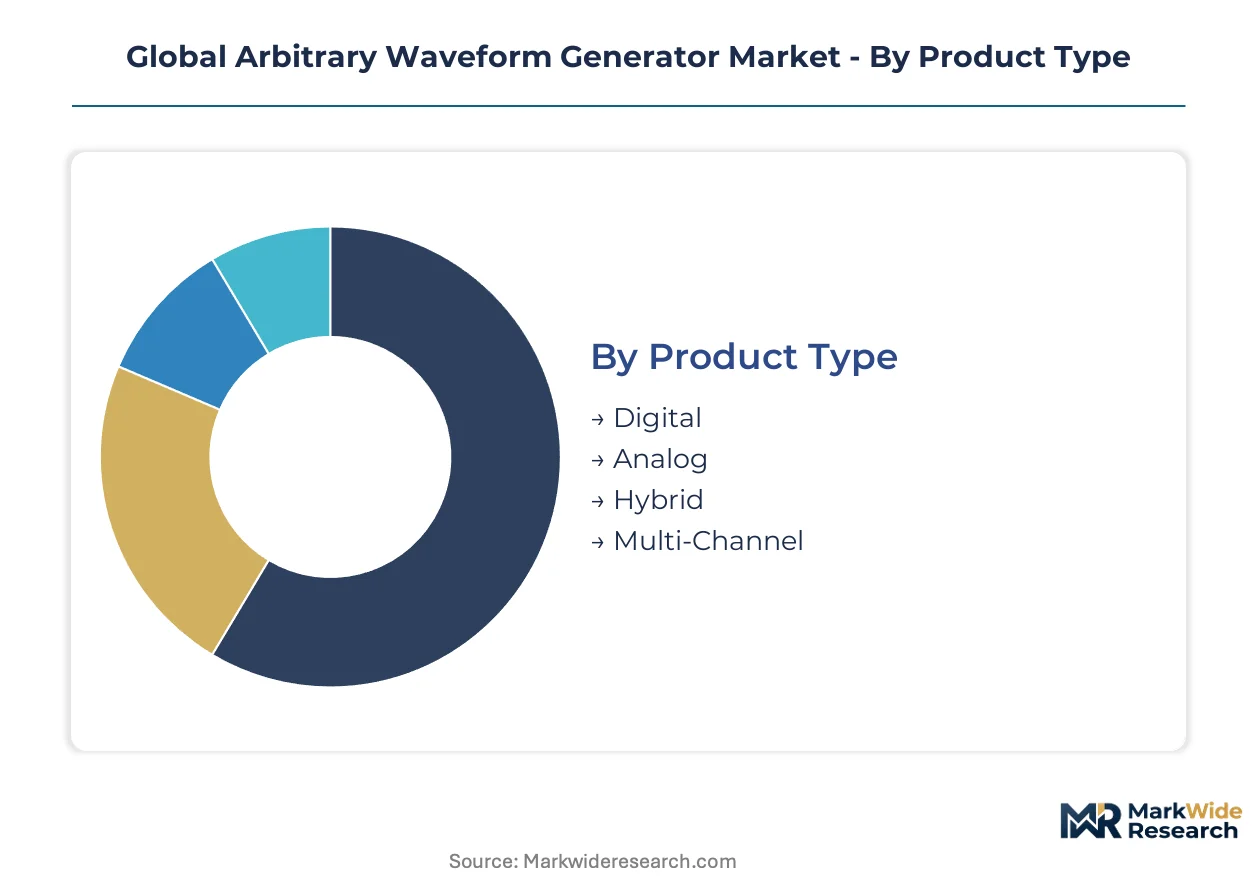
Arbitrary waveform generator procurement channels diverge sharply by performance tier. Defense primes source through calibrated service networks, while semiconductor fabs favor direct manufacturer relationships for multi-channel configurations.
Product Type:
Channel mix varies by bandwidth requirement: direct sales dominate multi-channel installations above 8 GHz, whereas distributors handle standard-function replacements below 500 MHz.
- Digital:FPGA-based architectures enable precise timing control with programmable logic blocks managing waveform sequencing. Taiwan semiconductor fabs deploy these for wafer-level RF validation where timing jitter must stay below 100 femtoseconds.
- Multi-Channel:Phased array testing demands precise inter-channel synchronization with shared clock distribution networks. South Korean 6G research programs in Daejeon and Seongnam are procuring 16-channel configurations for MIMO protocol validation.
- Analog:Legacy test benches in US defense corridors retain these for backward compatibility with GPIB infrastructure.
- Hybrid:Combines direct digital synthesis with analog filtering for cost-sensitive automotive radar development.
Multi-Channel dominates installed base. Digital is where expansion concentrates.
Technology:
Cost tier stratification separates research-grade FPGA implementations from economy DDS chips. Premium pricing attaches to software-defined architectures with open API access.
- FPGA:Field-programmable gate arrays allow dynamic reconfiguration of waveform parameters without hardware swaps. German aerospace test facilities in Munich and Hamburg specify these for electronic warfare simulation requiring 64 GSa/s sample rates.
- Software-Based:Python and MATLAB APIs eliminate proprietary firmware constraints for research institutions. South Korean universities in Seoul and Pohang are migrating procurement toward these platforms to enable collaborative waveform library development.
- Direct Digital Synthesis:Captures basic function generator applications below 500 MHz through integrated circuit cost advantages.
- Thermoelectric:Stabilizes reference oscillators against temperature drift in outdoor telecommunications field testing.
FPGA commands premium positioning. Software-Based is climbing the fastest as research procurement shifts toward subscription models.
End User:
Application maturity determines margin structure: aerospace procurement carries 18-24 month qualification cycles, while automotive validation programs compress vendor selection to 6-9 months.
- Telecommunications:5G base station and Wi-Fi 7 protocol validation requires sub-nanosecond timing precision. US IEEE 802.11be research programs in California and Massachusetts are mandating instrumentation upgrades for pre-standardization testing.
- Aerospace:Electronic warfare and radar simulation demand classified waveform libraries with ITAR-controlled distribution. Defense electronics corridors in Texas and Arizona specify commercial-off-the-shelf platforms with security modifications.
- Automotive:77-81 GHz FMCW signal generation for ADAS sensor validation remains underdeveloped relative to communications testing.
- Research Labs:Academic institutions prioritize API accessibility over raw sample rate specifications.
Telecommunications anchors volume demand. Aerospace retains the steepest pricing premiums.
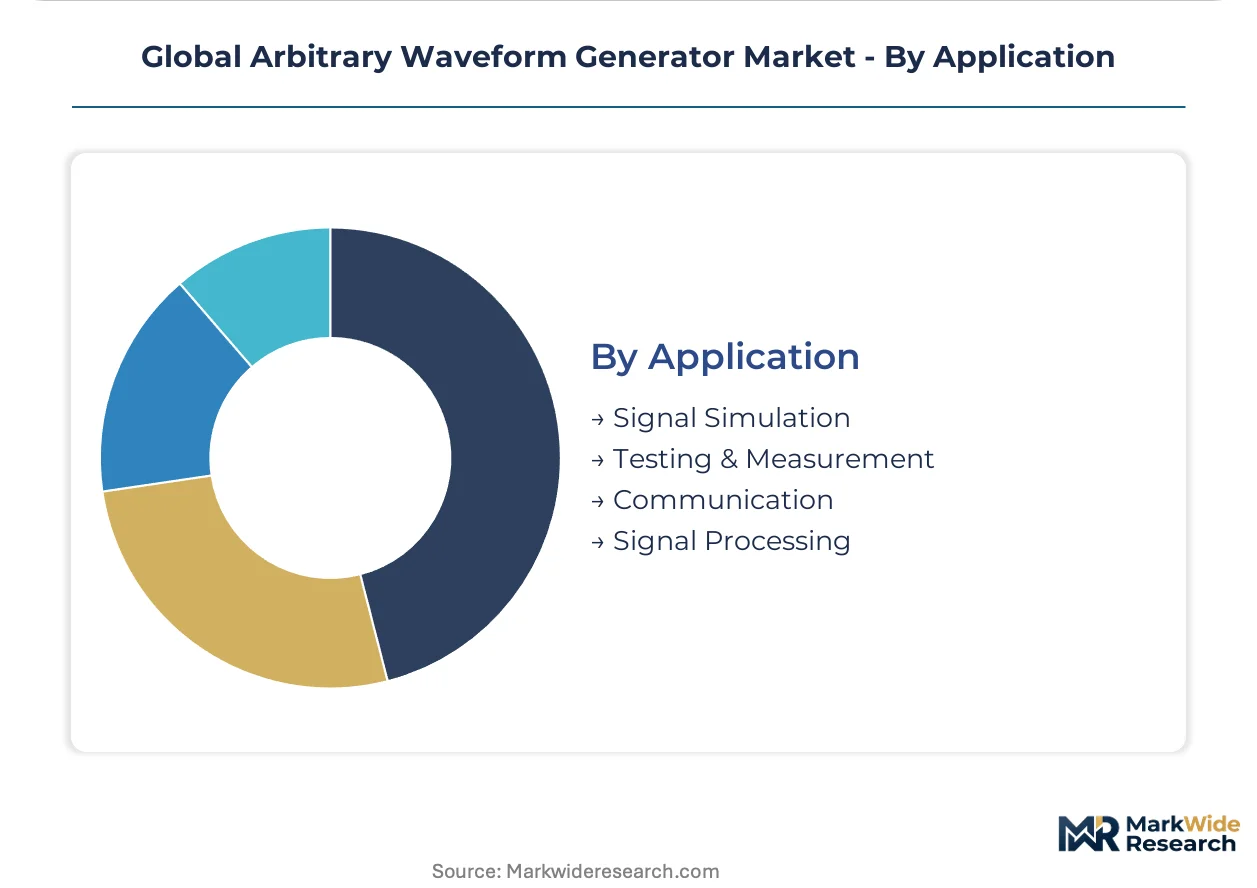
Application:
Geography shapes specification intensity: East Asian semiconductor clusters prioritize signal simulation density, while North American defense corridors emphasize testing & measurement traceability.
- Testing & Measurement:Equipment-under-test validation requires documented spectral purity exceeding FCC Part 15 and EU CE marking benchmarks. German test houses in Stuttgart and Berlin maintain calibration chains traceable to PTB national standards.
- Signal Simulation:Emulates complex real-world scenarios including multipath fading and interference patterns. South Korean 6G terahertz research in Sejong City depends on these capabilities for pre-deployment device characterization.
- Communication:Protocol conformance testing for emerging wireless standards.
- Signal Processing:Algorithm development and filter characterization in academic environments.
Testing & Measurement dominates qualification spending. Signal Simulation is gaining share fastest as 6G research accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
GaN foundry capacity for high-performance DACs concentrates in Taiwan and Japan, while defense electronics demand clusters in US aerospace corridors and East Asian semiconductor manufacturing drives multi-channel instrument procurement.
United States
Defense electronics corridors in Texas and Arizona rotate procurement toward commercial-off-the-shelf platforms with classified waveform libraries. FCC Part 15 emissions testing mandates spectral purity documentation that extends product qualification cycles. IEEE 802.11be research programs in California and Massachusetts mandate instrumentation upgrades for Wi-Fi 7 pre-standardization testing.
Germany
Aerospace test facilities in Munich and Hamburg specify FPGA-based architectures for electronic warfare simulation requiring 64 GSa/s sample rates. EU F-Gas Regulation restrictions are reshaping thermal management as liquid cooling loops displace compressor-based refrigeration. Stuttgart and Berlin test houses maintain calibration chains traceable to PTB national standards.
South Korea
6G terahertz research programs in Daejeon and Seongnam are procuring 16-channel configurations for MIMO protocol validation. Seoul and Pohang universities are migrating procurement toward software-based platforms with Python APIs. The country's national radio transmission certifications under MIIT create parallel compliance pathways for domestic 5G base station deployments.
Taiwan
Semiconductor fabs deploy FPGA-based digital arbitrary waveform generators for wafer-level RF validation where timing jitter must stay below 100 femtoseconds. Gallium nitride substrate costs constrain high-performance DAC production given foundry concentration. The domestic semiconductor cluster anchors supply-side constraints for the broader East Asian market.
India
Telecom manufacturing incentives under the PLI scheme are creating domestic test equipment demand for 5G base station exports. Research institutions prioritize API accessibility over raw sample rate specifications. The country's national standards body and telecommunications regulator shape instrument qualification protocols for emerging wireless infrastructure.
Global Arbitrary Waveform Generator Market Vendor Landscape
Concentration sits with diversified test and measurement conglomerates controlling premium-tier positioning through in-house semiconductor fabrication and calibration service networks. The vendor base spans three strategic tiers: RF semiconductor specialists with direct-to-RF DAC capabilities, traditional test equipment houses with deep aerospace service networks, and software-centric entrants leveraging open API architectures. Dominant competitive moves include unbundling firmware from signal generation hardware and shifting toward subscription-based waveform library access.
Within the diversified instrumentation tier, Keysight Technologies and TEKTRONIX, INC. exemplify contrasting approaches to market positioning, while Rohde & Schwarz occupies a distinct vector through integrated spectrum analysis bundling. These three entities represent the primary competitive anchors against which specialized RF semiconductor houses and emerging software-defined instrument developers define their market entry strategies.
| Leading Market Players |
|---|
| Keysight Technologies |
| TEKTRONIX, INC. |
| Rohde & Schwarz |
| NATIONAL INSTRUMENTS CORP. |
| B&K Precision Corporation |
| Fluke Corporation |
| Teledyne Technologies Incorporated |
| ANRITSU CORPORATION |
| Yokogawa Test & Measurement Corporation |
| Others |
Supply Flow & Price Mechanics
Long-term capacity reservation contracts with Taiwan and Japan GaN foundries lock in DAC supply access and price visibility for defense electronics primes, insulating procurement teams from gallium nitride substrate volatility while compressing margin buffers for smaller instrument vendors.
Pricing Analysis
FCC Part 15 compliance documentation dictates the pricing tier structure across the market. Three-tier pricing separates ITAR-certified aerospace configurations from standard telecommunications instruments and economy DDS-based alternatives below 500 MHz. Price differentiation hinges on calibration traceability to national metrology institutes and software-defined architecture access. Cost compression in the economy tier is intensifying because direct digital synthesis chips capture basic function generator applications. Research labs exhibit highest price sensitivity; defense primes demonstrate lowest sensitivity due to classified waveform library requirements.
Supply Chain Analysis
GaN foundry chokepoints in Taiwan and Japan underwrite high-performance DAC availability for arbitrary waveform generator manufacturers. Raw material dependencies center on gallium nitride substrates, precision reference oscillators, and thermoelectric cooling components. Single-source vulnerability concentrates in Taiwan semiconductor fabrication capacity. Distribution runs through calibrated service networks for aerospace procurement and direct manufacturer relationships for semiconductor fab multi-channel installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Arbitrary waveform generator markets reward service-attach strategies as subscription-based waveform library access expands faster than hardware refresh cycles, shifting margin capture toward recurring revenue pools.
For Market Incumbents: Fortify calibration service network density in aerospace corridors to defend against software-centric entrants eroding proprietary firmware lock-in. Deepen backward integration into GaN DAC fabrication to control linearity specifications. Prioritize Python API compatibility to retain research institution procurement migrating toward open-source waveform definitions.
For New Entrants and Emerging Players: Subscription waveform library underdevelopment for 77-81 GHz automotive radar validation exposes a service-layer gap where incumbents under-serve ADAS sensor testing demand. Target South Korean and German research institutions prioritizing collaborative waveform development over raw sample rate specifications. Deploy cloud-accessible instrument platforms with annual contract pricing to bypass capital expenditure barriers.
For Investors and Strategic Acquirers: Capital is best deployed toward RF semiconductor specialists with direct-to-RF DAC capabilities and established GaN foundry relationships. Long-term viability hinges on defensible positioning in terahertz-band signal emulation for 6G pre-standardization testing. Monitor whether open-source waveform formats gain traction among automotive radar developers as an inflection indicator threatening incumbent software margins.
| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Service Network Expansion | Deepens aerospace customer retention in Texas and Arizona defense corridors. |
| Python API Platform Development | Captures South Korean and German research institution procurement shifting toward open-source collaboration. |
| Direct-to-RF DAC Integration | Eliminates intermediate frequency stages for 64 GSa/s electronic warfare simulation in German test facilities. |
| Subscription Waveform Library Launch | Shifts margin capture from capitalized IP toward recurring revenue pools in research markets. |
| Liquid Cooling Retrofit Partnership | Addresses EU F-Gas Regulation compliance for high-density multi-channel chassis in European aerospace. |
Methodological Framework
A spread of perspectives from test equipment procurement managers, RF calibration metrologists, semiconductor fab engineers, and defense electronics program directors converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation against SEC filings from diversified instrumentation conglomerates, IEEE standardization committee disclosures, and customs data tracking GaN substrate trade flows. Bottom-up channel checks triangulated against top-down market sizing across product type, technology, and end-user segmentation.
Segmentation dimensions modeled include channel configuration, sample rate tier, software architecture type, and geographic regulatory cluster. CAGRs were derived from instrument shipment trajectories, replacement cycle analysis, and research program funding disclosures across the projection horizon. Forecast inputs incorporated wafer-level RF characterization demand from Taiwan semiconductor fabs and phased array radar procurement patterns in US defense electronics corridors.
Forecasts assume regulatory continuity in FCC Part 15 emissions testing, EU CE marking directives, and China GB/T national standards; material policy shifts would require re-modeling qualification timeline assumptions. Practitioners should keep alternative scenarios live as open-source waveform format adoption and GaN foundry capacity allocation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Optical Critical Dimension (OCD) Measurements System Market
Test and Measurement
Ultrasonic Flaw Detector Market
Test and Measurement
High-Temperature Furnace Refractory Lining Inspection Systems Market
Test and Measurement
Satellite Communications and Direct-to-Device RF Test Platforms Market
Test and Measurement
Laser Interferometer Market
Test and Measurement
Clamp Meters Market
Test and Measurement
Onboard Charger and DC Fast-Charging Interoperability Test Equipment Market
Test and Measurement
Production Testing Market
Test and Measurement
LTE Testing Equipment Market
Test and Measurement
Inline Metrology Market
Test and Measurement
Permeability Testing Machine Market
Test and Measurement
Ultrasonic NDT Equipment Market
Test and Measurement
Asia-Pacific Nondestructive Testing Equipment Market
Test and Measurement
Radio Frequency Test Equipment Market
Test and Measurement
Global Platform Electronic Laboratory Balance Market
Test and Measurement
Digital Weighing Terminal Market