

Ballistic Protective Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Ballistic Protective Equipment Market Insights
Modular armor kits is decoupling traditional bundled procurement, letting buyers mix plate carriers, helmet systems, and accessory platforms from separate vendors. BAE Systems leverages its integrated defense electronics footprint to bundle communications-enabled helmet systems with traditional hard armor. Honeywell International anchors its position through captive aramid fiber production, giving it upstream control over Kevlar-based body armor supply. MKU specializes in night-vision compatible helmet designs, differentiating its offerings in military tender processes across Asia and the Middle East.
Ballistic protective equipment encompasses garments, headgear, and accessories engineered to absorb or deflect kinetic energy from projectiles, fragmentation, and edged weapons, typically constructed from aramid fibers, ultra-high-molecular-weight polyethylene, or ceramic composite matrices rated against specific threat velocities. The primary purpose is preserving operational capability of military personnel, law enforcement officers, and security contractors engaged in high-threat environments. Body armor commands the largest revenue pool due to mandatory individual issue across armed forces, while helmets represent the fastest-growing product category as integrated sensor and communication architectures drive replacement demand. Ultra-high-molecular-weight polyethylene is displacing traditional steel plates in law enforcement applications where weight reduction directly improves officer mobility and endurance during extended patrol cycles.
NIJ Standard-0101.07 governs ballistic resistance of body armor in the United States, mandating rigorous testing against specified threat levels and conditioning protocols before market access. The EU AI Act and CE marking under the Personal Protective Equipment Regulation shape European procurement, requiring conformity assessment for equipment deployed by police and border agencies. The F-Gas Regulation indirectly affects manufacturing by restricting certain foam-blowing agents used in helmet liner production. Stakeholders must monitor evolving multi-hit requirements and cross-border certification reciprocity as defense procurement regionalizes and joint standards emerge between allied nations.
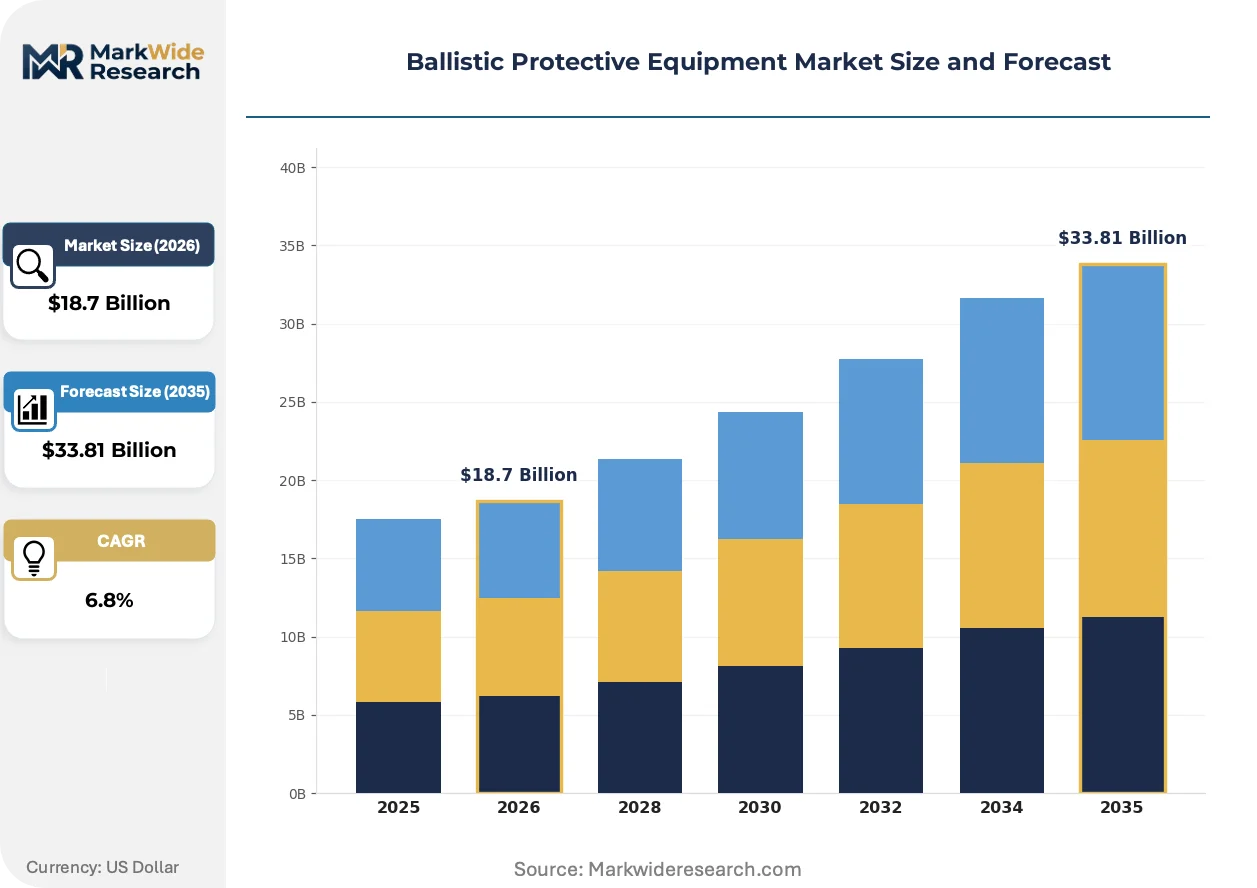
Market Dynamics
Modular armor procurement is decoupling traditional bundled contracts, forcing manufacturers to compete at the subsystem level rather than integrated platform level. NATO standardization efforts and NIJ Standard-0101.07 certification timelines are compressing development cycles while fragmenting vendor relationships across plate carriers, helmet systems, and accessory platforms.
Growth Catalysts
- NIJ Standard-0101.07:United States federal law enforcement grant programs mandate multi-hit capable ceramic-composite solutions, accelerating replacement cycles for legacy steel and aramid systems in municipal police departments.
- Integrated sensor architectures:Military helmet systems now require night-vision compatibility and communications mounting points, expanding addressable equipment sets per soldier beyond standalone ballistic protection.
- Ultra-high-molecular-weight polyethylene:Law enforcement agencies prioritize officer mobility during extended patrol cycles, driving material substitution away from traditional steel plates in concealed and external vest applications.
Market Restraints
- Aramid fiber supply concentration:Captive production of para-aramid fibers sits with a limited set of chemical conglomerates, creating input cost volatility for Kevlar-dependent body armor manufacturers.
- Ceramic composite technical limitations:Multi-hit performance against armor-piercing threats requires thicker ceramic strike faces, adding weight penalties that conflict with mobility requirements in dismounted infantry operations.
- Cross-border certification friction:Lack of reciprocity between NIJ Standard-0101.07 and CE marking under the EU Personal Protective Equipment Regulation forces redundant testing for vendors serving both United States and European defense procurement channels.
Strategic Opportunities
- Asia-Pacific military modernization:India's defense procurement reforms under the PLI scheme and indigenization mandates create openings for helmet system vendors offering night-vision compatible designs.
- Private security contractor expansion:Corporate close protection details and maritime security operations generate demand for concealable soft armor rated against handgun threats, distinct from military hard plate requirements.
- EU F-Gas Regulation tailwinds:Restrictions on foam-blowing agents in helmet liner production favor manufacturers with alternative energy-absorbing material formulations and molded polymer expertise.
Industry Challenges
- Ballistic testing engineer scarcity:Specialized expertise in terminal ballistics and backface signature measurement is concentrated among retired military technicians, constraining R&D throughput for new product qualification.
- Legacy system integration complexity:Next-generation plate carriers must interface with existing load-bearing equipment and radio harnesses, requiring backward-compatible attachment systems that add design cycle time.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ballistic Protective Equipment Market Trends and Innovations
Active developments in materials science and procurement digitization are compressing product lifecycles while elevating performance thresholds. Three convergent forces are redefining how protective equipment is specified, manufactured, and fielded.
Ceramic-composite strike faces bonded to ultra-high-molecular-weight polyethylene backings are integrating multi-hit capability with weight reduction targets previously considered mutually exclusive. United States Army modernization programs specify these hybrid configurations for next-generation soldier protection systems. The structural consequence is tiered supplier relationships where ceramic foundries and fiber weavers must coordinate quality systems rather than delivering to separate prime contractors.
REACH restrictions on persistent organic pollutants and the EU F-Gas Regulation are eliminating certain solvent-based adhesives and foam-blowing chemistries from helmet liner production. European manufacturers face reformulation timelines that compress margin structures during transition periods. Personal protective equipment vendors serving French Gendarmerie and German Federal Police tenders are accelerating partnerships with polymer compounders holding alternative resin portfolios.
Defense procurement agencies are unbundling platform-level contracts into subsystem competitions, allowing end-users to mix plate carriers from one vendor with helmet systems from another. This disaggregation disrupts traditional prime contractor relationships and elevates component-level certification importance. The United States Department of Defense and United Kingdom Ministry of Defence tender processes exhibit this pattern most visibly, with modular technical requirements replacing integrated system specifications.
Ballistic Protective Equipment Market Segmentation
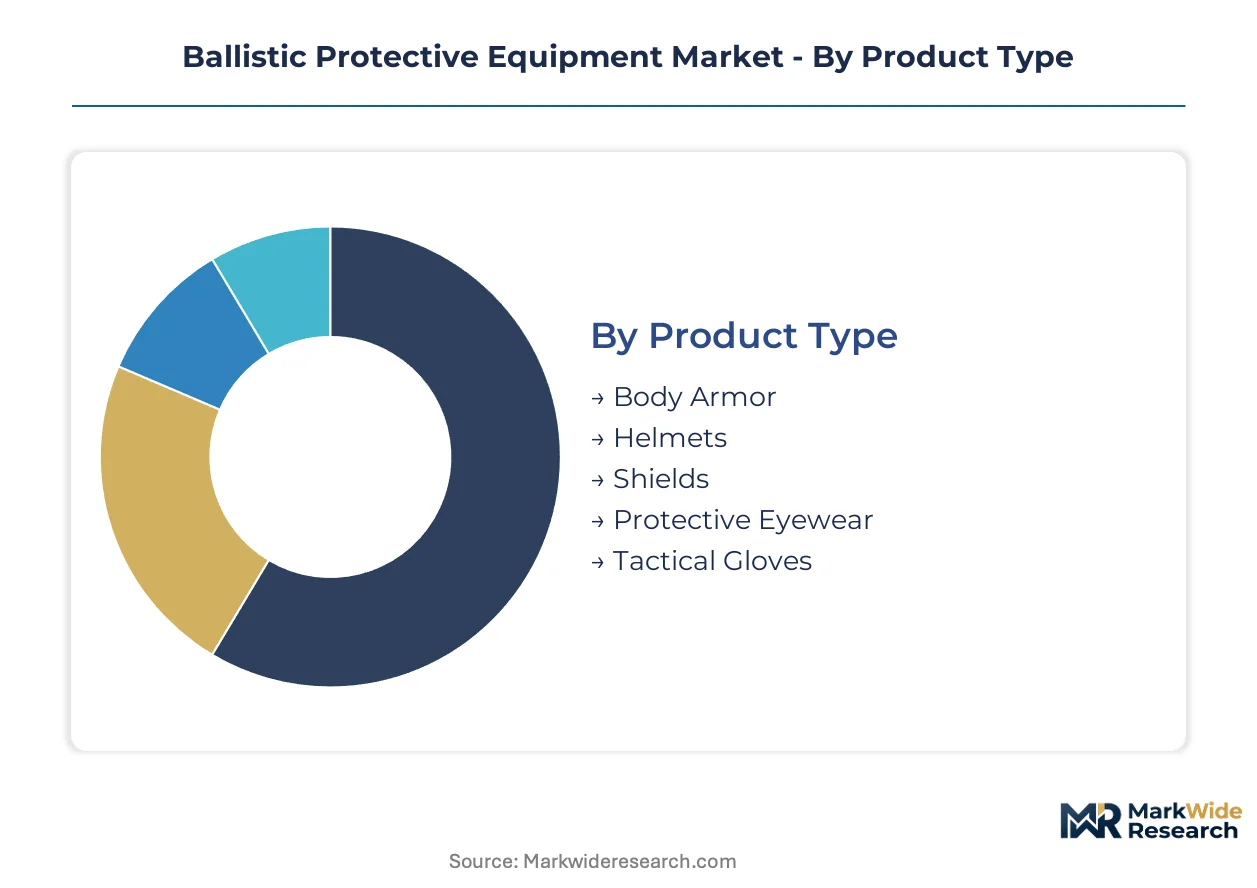
Ballistic protective equipment procurement fragments across four distinct classification axes, each revealing divergent cost sensitivities and certification requirements. Understanding these splits illuminates where technology premiums command pricing power versus where commoditization pressures dominate vendor margins.
Product Type:
Body armor and helmets anchor procurement volumes, while shields and eyewear capture niche premium tiers.
- Body Armor:Plate carriers and concealable vests constructed from ceramic-composite matrices or ultra-high-molecular-weight polyethylene backings absorb the largest procurement outlays across NATO armed forces. United States Department of Defense modernization budgets sustain replacement cycles for legacy steel and aramid systems, with NIJ Standard-0101.07 multi-hit requirements accelerating ceramic-composite adoption in federal law enforcement grant programs.
- Helmets:Modular helmet systems integrating night-vision shrouds and communications mounting points are expanding addressable equipment sets per soldier beyond standalone ballistic protection. Night-vision compatibility specifications in Indian and Middle Eastern military tenders favor vendors with integrated sensor architectures.
- Shields:Ballistic shields rated for rifle threats serve tactical entry teams and correctional emergency response units requiring mobile cover solutions.
- Protective Eyewear:Ballistic-rated spectacles and goggles protect against fragmentation and blunt impact in training and operational environments.
- Tactical Gloves:Cut-resistant and flame-retardant hand protection completes individual equipment ensembles for dismounted infantry and special operations personnel.
Mature deployment sits with body armor across conventional military formations. Newer deployment is concentrated in helmet systems with integrated electronics.
Material:
Weight-performance tradeoffs segment materials into mobility-optimized and threat-optimized tiers.
- Ultra-High-Molecular-Weight Polyethylene:Dyneema and comparable grades displace traditional steel in law enforcement concealed vest applications where officer endurance during extended patrol cycles outweighs maximum threat ratings. Honeywell International's captive fiber production secures upstream supply continuity for vest manufacturers.
- Ceramic Plates:Alumina, silicon carbide, and boron carbide strike faces bonded to composite backings deliver multi-hit capability against armor-piercing threats specified in United States Army next-generation soldier protection programs. Thicker strike faces impose weight penalties that conflict with dismounted infantry mobility requirements.
- Kevlar:Para-aramid fabrics retain cost advantages in soft armor for handgun threat protection and fragmentation vests.
- Dyneema:Branded ultra-high-molecular-weight polyethylene from DSM competes on strength-to-weight metrics against generic UHMWPE grades.
- Steel Plates:Legacy steel armor persists in budget-constrained procurement channels where weight tolerance permits cost minimization.
Established supply chains concentrate around Kevlar and steel. Material substitution is expanding most quickly in polyethylene and ceramic hybrid configurations.
Application:
Threat environment severity and procurement funding sources differentiate end-use segments.
- Military Personnel:Dismounted infantry and mechanized forces require plate carriers, helmet systems, and accessory platforms rated against rifle and fragmentation threats. NATO standardization efforts compress development cycles while fragmenting vendor relationships across subsystem competitions.
- Law Enforcement:Municipal police departments and federal agencies balance concealability against NIJ Standard-0101.07 certification tiers, with grant programs accelerating replacement of legacy equipment.
- Private Security:Corporate close protection details and maritime security operations generate demand for concealable soft armor distinct from military hard plate requirements.
- Correctional Facilities:Stab-resistant and blunt-trauma protection dominates over ballistic ratings in prison and detention center applications.
Institutional procurement maturity sits with military personnel. Budget flexibility is gaining share fastest in private security channels.
End User:
Contracting mechanisms and certification reciprocity requirements shape vendor access patterns.
- Government Agencies:Department of Defense, Department of Homeland Security, and allied defense ministries specify technical requirements and conduct conformance testing through national laboratories.
- Security Contractors:Private military and security companies procure equipment through commercial channels with less stringent certification documentation than government tenders.
- Defense Manufacturers:Prime contractors integrate subsystem components into platform-level soldier modernization programs.
- Special Response Teams:Tactical units within law enforcement and corrections agencies require rapid procurement turnaround for mission-specific equipment configurations.
Formal tender processes concentrate with government agencies. Procurement velocity is climbing the fastest in special response team channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity concentrates in the United States and Germany, while procurement demand scales fastest across India and the Middle East. Defense ministries in NATO member states drive replacement cycles for legacy steel and aramid systems.
United States
Department of Defense modernization budgets and federal law enforcement grants sustain elevated replacement cycles for legacy equipment. NIJ Standard-0101.07 certification requirements push manufacturers toward lighter, multi-hit capable ceramic-composite solutions. Industrial clusters in Virginia and Texas host prime contractors integrating subsystem components into platform-level soldier protection programs.
Germany
Rheinmetall anchors European hard armor production through integrated defense electronics capabilities. The EU F-Gas Regulation and CE marking under the Personal Protective Equipment Regulation shape procurement for police and border agencies. Manufacturing concentration in Bavaria and North Rhine-Westphalia supports NATO standardization efforts for modular helmet systems.
India
Defense procurement reforms under the PLI scheme and indigenization mandates create openings for helmet system vendors offering night-vision compatible designs. The country's national defense regulator mandates local content thresholds for military tenders. Production clusters in Maharashtra and Telangana are expanding molded polymer expertise for alternative energy-absorbing material formulations.
United Kingdom
Ministry of Defence tender processes exhibit modular technical requirements replacing integrated system specifications. The country's national procurement agency conducts conformance testing through national laboratories. Industrial capacity in the Midlands and Scotland focuses on ceramic-composite strike faces and ultra-high-molecular-weight polyethylene backings.
Israel
Domestic security threats sustain demand for concealable soft armor rated against handgun threats in close protection details. The national defense procurement agency prioritizes rapid turnaround for mission-specific equipment configurations. Manufacturing expertise in the Tel Aviv corridor concentrates on multi-hit capable solutions for armor-piercing threats.
Ballistic Protective Equipment Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the ballistic protective equipment market. The vendor base spans three distinct tiers: integrated defense electronics conglomerates, captive fiber producers with upstream material control, and specialized helmet system fabricators. Strategic moves center on subsystem-level certification capture and backward integration into ceramic or polymer feedstocks.
Within the integrated systems tier, BAE Systems and Rheinmetall represent archetypes bundling communications-enabled platforms with traditional hard armor. Honeywell International occupies a position anchored by captive aramid fiber production. MKU exemplifies the specialist model, sitting within the night-vision compatible helmet segment.
| Leading Market Players |
|---|
| BAE Systems |
| Honeywell International |
| DuPont |
| Rheinmetall |
| Point Blank Enterprises |
| 3M |
| MKU |
| ArmorSource |
| Mehler Systems |
| Others |
Pricing and Supply Chain Analysis
Para-aramid fiber spot indices cascade through ballistic protective equipment supply chains into three distinct pricing tiers, with upstream volatility compressing margins for vest manufacturers lacking captive fiber production while ceramic-composite suppliers command performance premiums tied to NIJ Standard-0101.07 certification tiers.
Pricing Analysis
Margin tightening in soft armor reflects aramid fiber supply concentration among chemical conglomerates, forcing non-integrated manufacturers to absorb input volatility. Three-tier pricing structure across NIJ-certified, CE-marked, and uncertified tiers segments buyers by threat rating and institutional procurement rigor. Cost-down pressure on legacy steel plate configurations accelerates as law enforcement agencies prioritize officer mobility over maximum ballistic ratings. Municipal police departments exhibit highest price sensitivity, while special operations units tolerate premium tiers for multi-hit ceramic-composite solutions.
Supply Chain Analysis
Single-source vulnerability sits with para-aramid fiber production concentrated in the United States and Germany, constraining global vest manufacturing capacity. Ceramic strike faces draw from alumina and silicon carbide processing clusters in the United Kingdom and Germany, while ultra-high-molecular-weight polyethylene backings source from DSM's Dyneema operations in the Netherlands. Tariff exposure on Chinese ceramic precursors threatens cost structures for hybrid plate configurations. Distribution runs through defense prime contractors and direct government tenders, with subsystem vendors increasingly accessing end-users via modular procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ballistic protective equipment markets favor consolidation plays as NIJ Standard-0101.07 compliance costs and multi-hit ceramic R&D requirements force sub-scale vendors toward exit or acquisition.
For Market Incumbents: Acquire ceramic foundry capacity and para-aramid weaving operations to secure upstream supply continuity against fiber price volatility. Defensive positioning requires capturing subsystem-level certification for helmet electronics integration before modular procurement fully disaggregates platform contracts. Threat substitution from ultra-high-molecular-weight polyethylene in law enforcement channels demands backward integration into fiber production or exclusive supply agreements with DSM. For New Entrants and Emerging Players: Private security contractors in Asia-Pacific represent an underserved buyer archetype with faster procurement cycles and lower certification documentation requirements than government tenders. White-space concentration sits with night-vision compatible helmet systems for Indian defense modernization under PLI scheme local content mandates. Go-to-market execution favors partnering with established European polymer compounders holding alternative resin portfolios for F-Gas Regulation-compliant helmet liner production. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier ceramic-composite plate manufacturers in the United Kingdom facing margin compression from REACH reformulation costs and legacy steel competition. Long-term viability hinges on five-to-ten year defense procurement visibility in NATO standardization corridors. The inflection signal to watch is reciprocity progress between NIJ Standard-0101.07 and CE marking regimes, which would eliminate redundant testing costs and expand addressable vendor pools.| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Foundry Acquisition | Secures strike face supply for multi-hit plate configurations against armor-piercing threats. |
| NIJ Standard-0101.07 Certification Investment | Unlocks federal law enforcement grant program access for ceramic-composite vest suppliers. |
| Helmet Electronics Integration Partnership | Captures modular procurement demand for communications-enabled soldier protection systems. |
| Alternative Polymer Formulation Development | Positions vendors ahead of EU F-Gas Regulation restrictions on foam-blowing chemistries. |
| India PLI Scheme Joint Venture | Satisfies local content thresholds for night-vision compatible helmet military tenders. |
Research Methodology
Multi-period observation of defense procurement budgets, NIJ certification timelines, and ceramic-composite adoption rates anchored the trend analysis, supplemented by interviews with program managers at defense ministries, procurement officers at federal law enforcement agencies, R&D directors at fiber and ceramic manufacturers, and contracts specialists at government laboratories. Secondary validation drew from Department of Defense modernization disclosures, NATO standardization committee documentation, EU Personal Protective Equipment Regulation filings, and Indian PLI scheme administrative records. Bottom-up segment sizing triangulated against top-down defense expenditure allocations.
Segment-weighting across product type, material composition, application severity, and end-user contracting mechanism structured the analytical framework. CAGRs were derived from fitted growth curves calibrated to procurement cycle lengths and replacement demand elasticity. Industry-specific forecast inputs included NIJ Standard-0101.07 implementation schedules, EU F-Gas Regulation phase-out timelines, and Indian indigenization mandate compliance trajectories across the projection horizon.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to defense budget reallocation, cross-border certification reciprocity negotiations, and breakthrough materials science displacing ceramic-polyethylene hybrids. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.