
 Safety Mirrors Market | 2026-2036
Safety Mirrors Market Size, Share, and Industry Trends Forecast 2026-2036
Safety Mirrors Market Analytics
Industrial warehouse operations is expanding mirror installations for forklift visibility and pedestrian safety corridors. Lester L. Brossard Company leverages its manufacturing scale to dominate supply for North American distribution centers. Peterson Manufacturing Company anchors its position through specialized traffic safety mirror lines for municipal buyers. Se-Kure Controls differentiates via channel control across institutional and commercial security accounts.
Safety mirrors are optical devices with curved or flat reflective surfaces, typically fabricated from glass, acrylic, or polycarbonate substrates with vacuum-deposited aluminum or silver coatings, engineered to eliminate blind spots in traffic corridors, industrial aisles, and retail environments. Polycarbonate mirrors now lead material selection in high-impact zones due to superior shatter resistance versus glass alternatives. Dome mirrors command premium positioning in ceiling-mounted retail surveillance applications where wide-angle coverage reduces theft incidents. Flat mirrors retain mature demand in parking facilities where precise distance judgment matters most.
FDA guidelines for facility safety in pharmaceutical manufacturing, OSHA workplace visibility standards, and NHTSA traffic control device regulations collectively mandate mirror deployment in regulated environments. ISO 9001 quality certifications and CE marking requirements shape product standards for international market access. Stakeholders must monitor evolving municipal procurement specifications for smart-city infrastructure integrations and weigh material substitutions against long-term durability claims.
Market Dynamics
Warehouse automation intensity and OSHA visibility mandates are compressing procurement cycles for impact-resistant mirror systems across North American distribution networks.
Growth Catalysts
- OSHA workplace visibility standards:Federal enforcement of pedestrian corridor sight-line requirements is mandating convex mirror installations in facilities exceeding 50,000 square feet.
- Polycarbonate substrate advances:Vacuum-deposited coating durability improvements are extending mirror service life in high-traffic forklift zones.
- German industrial safety culture:DGUV accident prevention regulations are driving specification-grade mirror adoption across automotive supplier parks.
Market Restraints
- Acrylic resin price volatility:Petrochemical feedstock fluctuations are compressing margin structures for mid-tier mirror fabricators.
- Glass substrate displacement limits:Premium architectural segments retain specification preference for silvered glass despite shatter risks.
- CE marking compliance costs:Small-batch European manufacturers face disproportionate testing burdens relative to production scale.
Strategic Opportunities
- Indian logistics corridor buildout:Dedicated freight corridors and inland container depots lack standardized visibility infrastructure.
- Smart-city traffic integration:Convex mirror deployments with embedded IoT sensors for congestion monitoring represent untapped municipal specifications.
- Pharmaceutical cleanroom applications:FDA facility safety guidelines for sterile manufacturing environments specify corrosion-resistant mirror materials.
Industry Challenges
- Optical coating technician scarcity:Vacuum deposition expertise concentrates in legacy automotive supplier regions, constraining quality-scale expansion.
- ISO 9001 certification timelines:International market access requires 12-18 month quality management system implementation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Safety Mirrors Market |
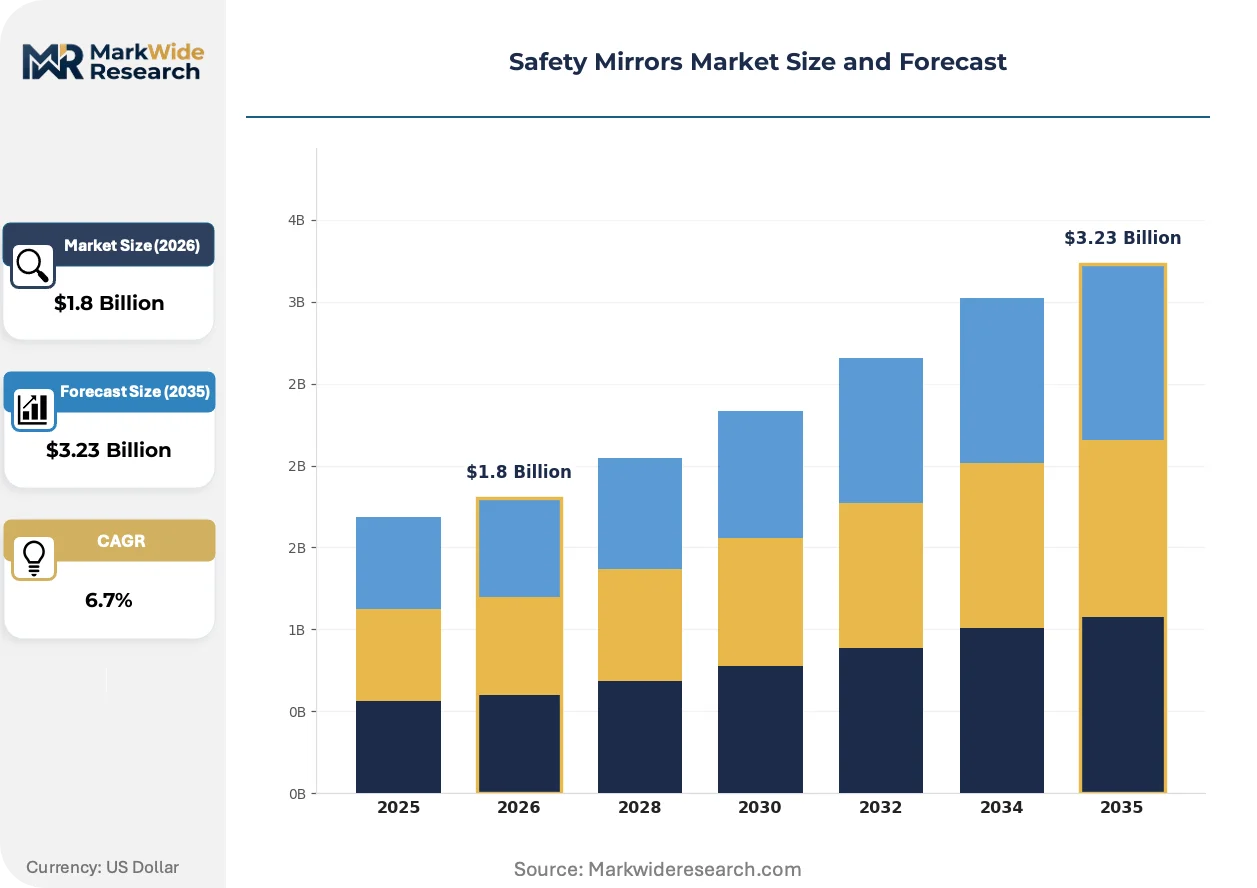
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Convex Mirrors, Flat Mirrors, Dome Mirrors, Traffic Mirrors Application: Commercial Use, Residential Use, Industrial Use, Parking Facilities Installation Type: Wall Mounted, Ceiling Mounted, Floor Mounted, Adjustable Material: Glass, Acrylic, Polycarbonate, Stainless Steel |
| Companies Covered | Clarke’s Safety Mirrors Limited, Lester L. Brossard Company, Fred Silver & Company, Inc, Se-Kure Controls, DENIOS, Inc., Ashtree Vision & Safety, Peterson Manufacturing Company, GrayGlass Company, Frontier Polymers Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Safety Mirrors Market Evolving Landscape
Material science convergence and regulatory precision are compressing product lifecycles while elevating performance specifications across industrial safety applications.
Polycarbonate-aluminum hybrid substrates are unifying impact resistance with optical clarity in warehouse environments. Amazon fulfillment centers and Kroger distribution hubs are specifying these composites for forklift collision zones. The technology is unifying previously separate safety and surveillance procurement categories under single vendor relationships.
REACH substance restrictions on cadmium-based stabilizers are forcing reformulation of PVC mirror housing compounds. European mirror manufacturers must certify alternative heat-stabilizer packages by 2025. German municipal traffic departments are accelerating tender specifications that preemptively exclude non-compliant housing materials.
Consolidated national account procurement is displacing regional distributor relationships in big-box retail mirror deployments. Walmart and Target are mandating direct manufacturer contracts with standardized dome mirror specifications. This concentration is most visible in Texas and Florida distribution center clusters where volume aggregation justifies captive installation crews.
Safety Mirrors Market Segmentation
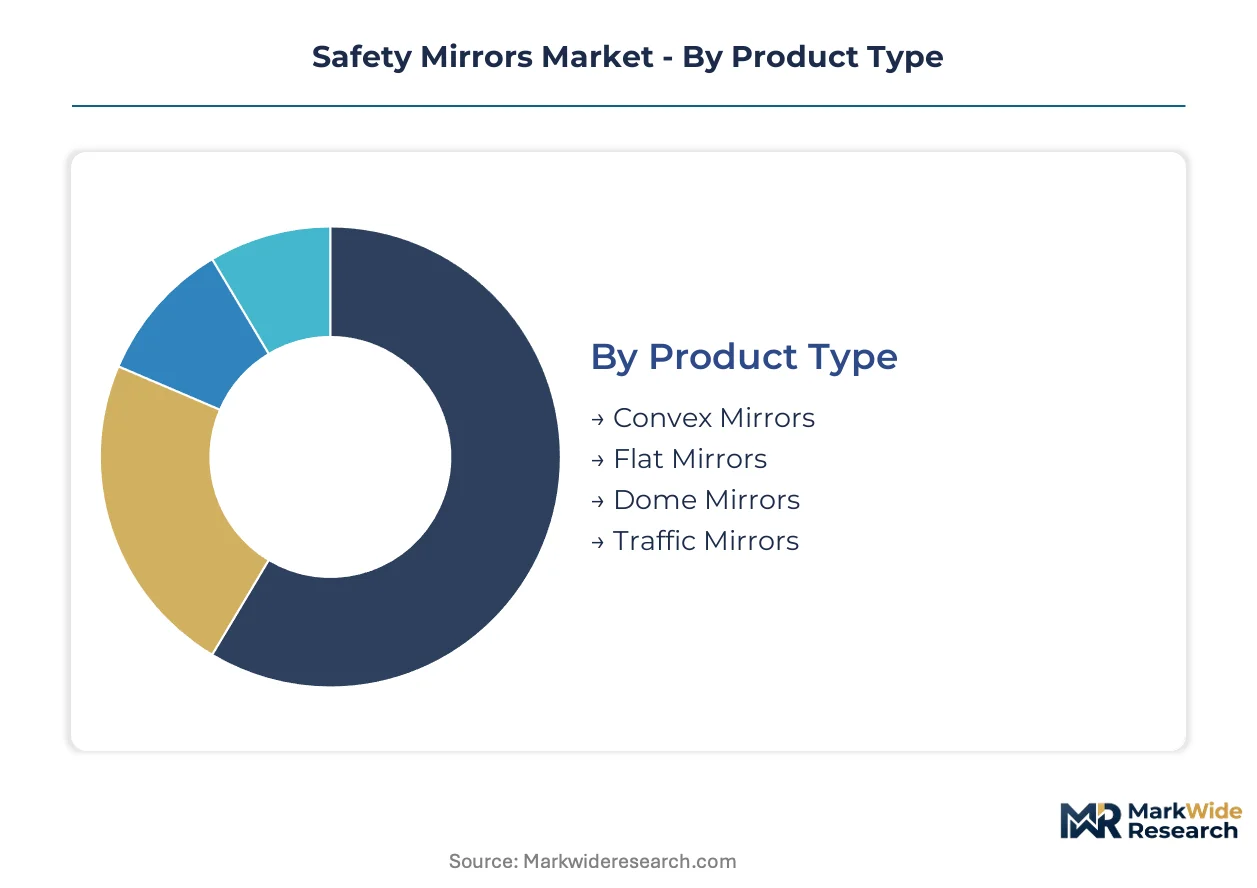
Safety mirror procurement patterns diverge sharply by operational environment, with material specifications and mounting configurations directly tied to regulatory exposure and collision risk profiles. Understanding these segment boundaries clarifies why polycarbonate dominates warehouse bids while glass retains architectural specification.
Product Type:
Convex mirrors demand the heaviest upfront tooling investment due to precision molding requirements for distortion-free curvature.
- Convex Mirrors:Curved reflective surfaces with 160-degree viewing angles eliminate blind spots in warehouse aisles and loading docks. OSHA pedestrian corridor mandates in facilities exceeding 50,000 square feet concentrate demand across United States distribution networks.
- Dome Mirrors:Hemispherical designs mount overhead to deliver 360-degree surveillance coverage. Retail theft reduction programs in big-box chains drive specification, with Walmart and Target mandating direct manufacturer contracts for standardized dome configurations.
- Flat Mirrors:Silvered glass or acrylic substrates provide undistorted distance judgment for vehicle positioning. Parking facility operators retain preference for flat geometry where precise spatial assessment matters.
- Traffic Mirrors:Weather-hardened convex designs with vandal-resistant housings serve municipal intersection visibility. German DGUV accident prevention regulations specify grade-rated traffic mirror adoption across automotive supplier parks.
Convex mirrors absorb the bulk of installed capacity; dome mirrors are expanding most quickly.
Application:
Industrial deployments carry the steepest performance certification burdens, separating specification-grade suppliers from commodity fabricators.
- Industrial Use:Forklift collision zones and pedestrian safety corridors in manufacturing plants require impact-resistant polycarbonate substrates. Amazon fulfillment centers and Kroger distribution hubs specify hybrid polycarbonate-aluminum composites for high-traffic aisles.
- Commercial Use:Retail surveillance and office security applications favor dome and convex configurations. Consolidated national account procurement is displacing regional distributor relationships in big-box retail deployments.
- Parking Facilities:Flat mirror preference persists where drivers judge precise vehicle positioning. Underground garages specify stainless steel housings for corrosion resistance.
- Residential Use:Driveway visibility and home security applications drive smaller-format convex mirror demand. Consumer channels favor acrylic substrates for lightweight DIY installation.
Industrial use commands the largest share of specification-grade revenue; commercial use is climbing the fastest.
Installation Type:
Wall-mounted systems require the most extensive structural anchoring engineering, particularly in seismic zones and high-wind corridors.
- Wall Mounted:Bracket systems affix convex and flat mirrors to vertical surfaces in warehouses and parking structures. Texas and Florida distribution center clusters justify captive installation crews for volume aggregation.
- Ceiling Mounted:Suspension hardware supports dome mirrors for overhead surveillance coverage. Retail environments specify ceiling mounting to unify safety and surveillance procurement under single vendor relationships.
- Floor Mounted:Weighted bases or embedded anchors secure mirrors in temporary traffic control or construction zones. Municipal departments specify floor mounting for flexible intersection visibility.
- Adjustable:Articulating armatures allow post-installation angle correction for changing sight-line requirements. Pharmaceutical cleanroom applications specify adjustable mounting to accommodate FDA facility safety guideline compliance.
Wall-mounted configurations retain the dominant installed base; ceiling-mounted systems are gaining share fastest.
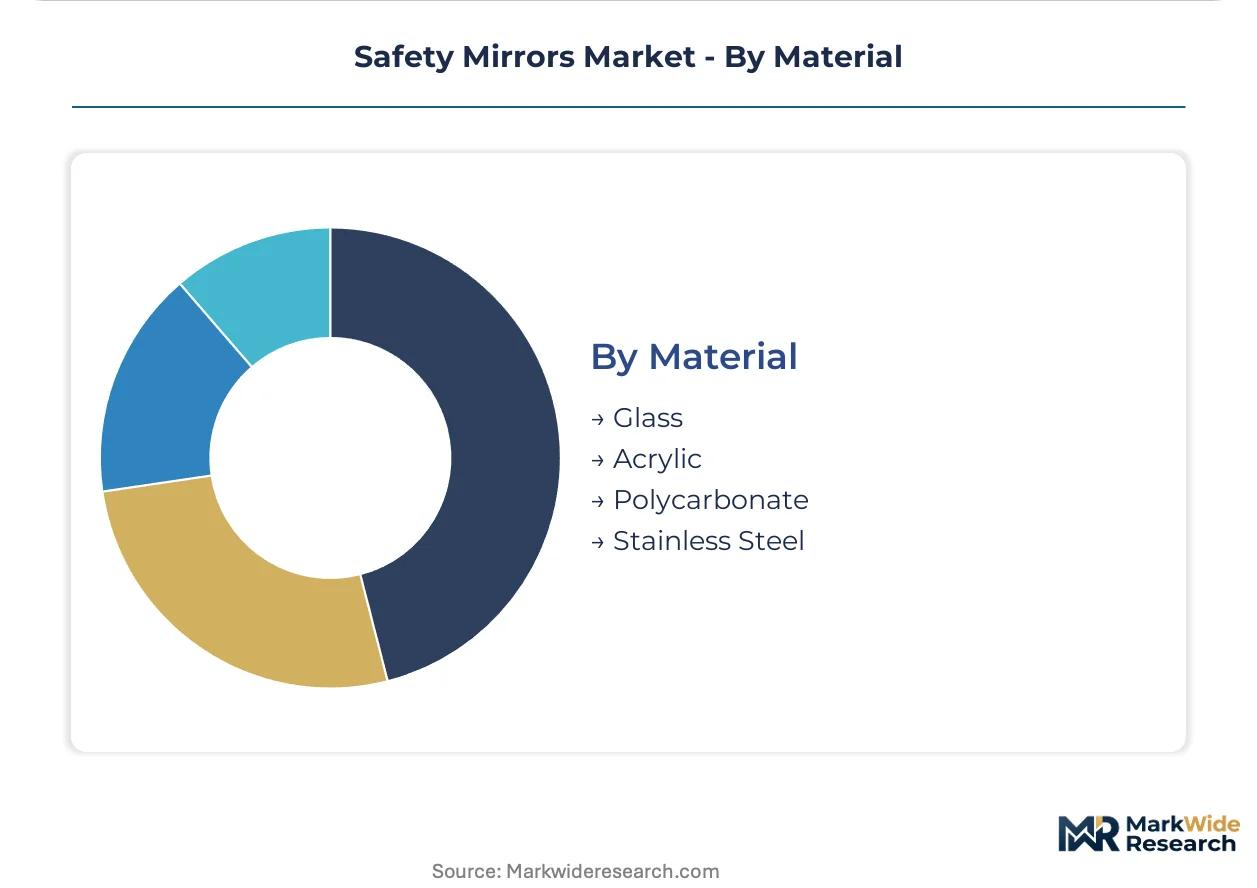
Material:
Polycarbonate substrate production demands vacuum deposition expertise that concentrates in legacy automotive supplier regions, constraining quality-scale expansion.
- Polycarbonate:Shatter-resistant thermoplastic with vacuum-deposited aluminum coatings dominates high-impact warehouse zones. REACH substance restrictions on cadmium-based stabilizers are forcing reformulation of housing compounds.
- Glass:Silvered float glass retains specification preference in premium architectural segments despite fragmentation risks. Municipal traffic departments in Germany are accelerating tender specifications that exclude non-compliant housing materials.
- Acrylic:Lightweight thermoplastic with optical clarity comparable to glass at reduced weight. Petrochemical feedstock fluctuations compress margin structures for mid-tier mirror fabricators.
- Stainless Steel:Corrosion-resistant substrates serve pharmaceutical cleanroom and food processing environments where FDA guidelines mandate corrosion-resistant mirror materials.
Polycarbonate captures the majority of new industrial specifications; stainless steel is expanding most quickly in regulated cleanroom applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity clusters in Germany and the United States, while consumption concentrates in logistics-intensive markets with strict workplace visibility enforcement. Mirror substrate fabrication requires vacuum deposition expertise that legacy automotive supplier regions retain. Distribution networks radiate from these production nodes to serve warehouse buildouts across multiple continents.
United States
OSHA pedestrian corridor mandates in facilities exceeding 50,000 square feet concentrate demand across distribution networks. Federal enforcement of workplace visibility standards compresses procurement cycles for impact-resistant mirror systems. Texas and Florida distribution center clusters justify captive installation crews for volume aggregation by big-box retailers.
Germany
DGUV accident prevention regulations drive specification-grade mirror adoption across automotive supplier parks. REACH substance restrictions on cadmium-based stabilizers force reformulation of PVC mirror housing compounds by 2025. Municipal traffic departments in Baden-Württemberg accelerate tender specifications excluding non-compliant housing materials.
China
Dual carbon goals and industrial safety standardization expand mirror deployment in logistics corridor buildouts. GB standards for workplace visibility equipment shape product specifications for domestic manufacturers. Yangtze River Delta warehouse automation projects specify polycarbonate-aluminum hybrid substrates for forklift collision zones.
India
Dedicated freight corridors and inland container depots lack standardized visibility infrastructure, creating specification gaps. BIS certification requirements for industrial safety equipment filter market access for imported mirror systems. Maharashtra logistics parks near Mumbai and Pune drive initial demand for convex mirror installations in loading dock configurations.
United Kingdom
CE marking compliance costs burden small-batch mirror manufacturers relative to production scale. Health and safety executive guidelines for warehouse visibility shape procurement specifications across distribution networks. Midlands distribution centers serving e-commerce fulfillment operations anchor regional demand for dome mirror surveillance systems.
Safety Mirrors Market Competitive Landscape
Top-tier vendors anchor specification-grade supply for regulated industrial environments, while mid-tier fabricators compete on price in commercial applications. The vendor base stratifies across three tiers: multinational safety equipment conglomerates, specialized mirror fabricators with vacuum deposition capabilities, and regional distributors with installation service bundling. Two dominant competitive moves are reshaping positioning: direct manufacturer contracts with national retail accounts displacing distributor relationships, and backward integration into polycarbonate substrate production to secure coating quality control.
Among North American fabricators, Lester L. Brossard Company and Peterson Manufacturing Company occupy positions representing scale-driven and specialized-tier archetypes respectively. Se-Kure Controls exemplifies channel-control positioning across institutional security accounts. These three named entities anchor the competitive structure without exhausting the participant base, as regional specialists and private-label suppliers fill price-sensitive segments below the specification-grade threshold.
| Leading Market Players |
|---|
| Clarke's Safety Mirrors Limited |
| Lester L. Brossard Company |
| Fred Silver & Company, Inc |
| Se-Kure Controls |
| DENIOS, Inc. |
| Ashtree Vision & Safety |
| Peterson Manufacturing Company |
| GrayGlass Company |
| Frontier Polymers Ltd |
| Others |
Value Network & Pricing Analysis
Backward integration into polycarbonate substrate production anchors supply position and pricing power for specification-grade mirror fabricators, as vacuum deposition expertise concentrates in legacy automotive supplier regions of Germany and the United States. Captive coating quality control separates premium-tier suppliers from mid-tier fabricators exposed to acrylic resin price volatility.
Pricing Analysis
Short lead-time premiums command pricing power in warehouse automation procurement cycles, where OSHA-mandated installations in facilities exceeding 50,000 square feet compress delivery windows. Three-tier pricing structure across specification-grade, certified-standard, and economy levels differentiates by ISO 9001 certification status and impact-resistance testing. Pricing pressure stems from petrochemical feedstock fluctuations compressing margin structures for mid-tier acrylic fabricators. Big-box retail national accounts exhibit lowest price sensitivity due to consolidated direct-manufacturer contracts, while municipal traffic departments show highest sensitivity to unit cost in volume tenders.
Supply Chain Analysis
Freight cost exposure runs through containerized shipments of vacuum-deposited aluminum coatings from German specialty chemical suppliers to North American mirror fabricators. Supply concentrates in Germany, the United States, and China, where automotive supplier park legacy infrastructure sustains optical coating technician pools. Raw material dependencies center on polycarbonate resin, acrylic sheet stock, and vacuum-deposition aluminum feedstock. Single-source vulnerability in optical coating equipment constrains quality-scale expansion for new entrants. Distribution runs through national safety equipment distributors and direct-manufacturer contracts with retail and logistics accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
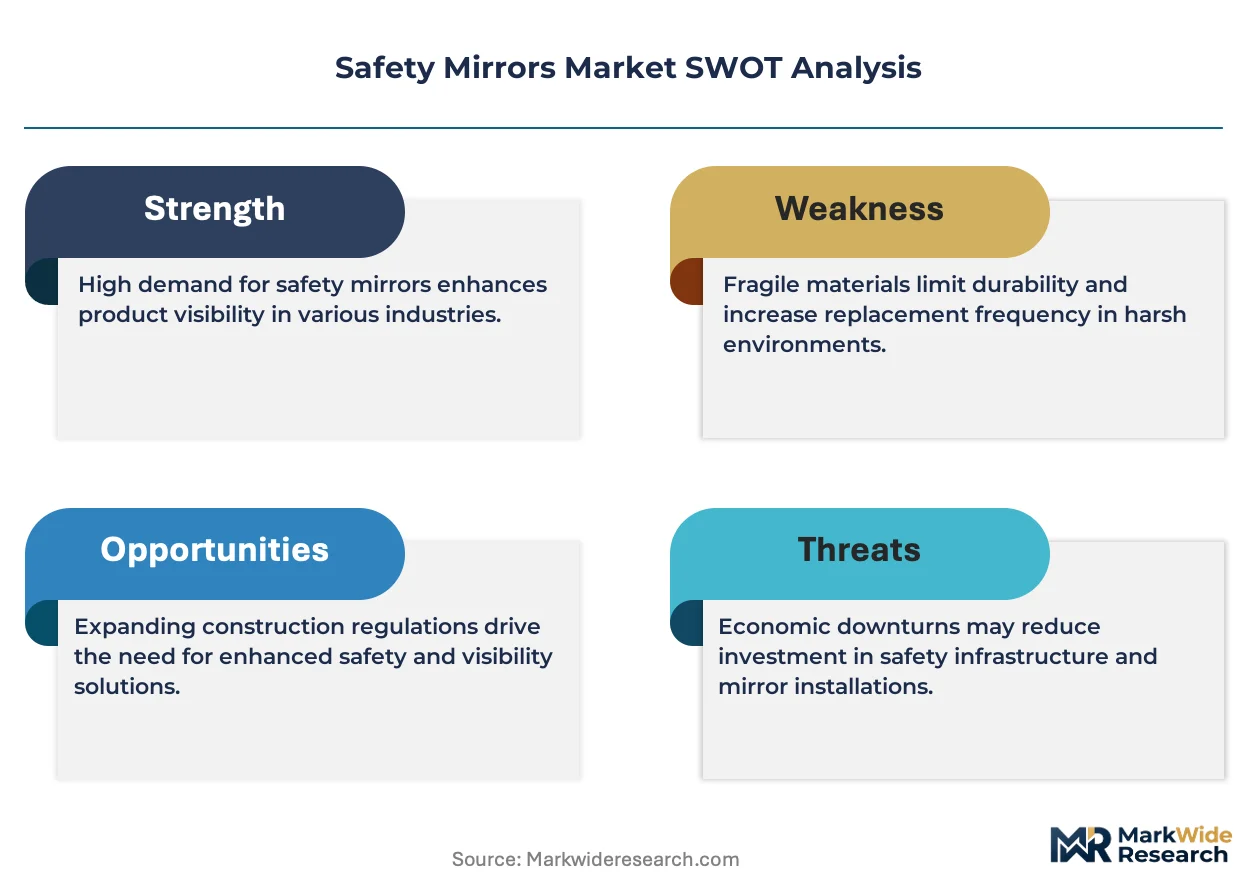
This market operates as a cost-of-compliance story where OSHA workplace visibility standards and DGUV accident prevention regulations create durable barrier-to-entry moats for certified players. Regulatory enforcement intensity separates specification-grade suppliers from price-commoditized fabricators.
For Market Incumbents: Anticipate consolidation pressure from national account procurement concentration by securing captive installation crews in Texas and Florida distribution center clusters. Reinforce channel control through direct-manufacturer contracts with Walmart and Target that displace regional distributor relationships. Invest in polycarbonate-aluminum hybrid substrate R&D to unify safety and surveillance procurement categories under single vendor relationships.
For New Entrants and Emerging Players: Begin with Indian logistics corridor buildout where dedicated freight corridors and inland container depots lack standardized visibility infrastructure. Target Maharashtra logistics parks near Mumbai and Pune with convex mirror installations for loading dock configurations. Pursue BIS certification pathways to filter market access against imported competition.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by multinational safety equipment conglomerates seeking vacuum deposition capabilities. Long-term viability hinges on regulatory enforcement durability across OSHA, DGUV, and GB standards jurisdictions. Watch for smart-city traffic integration specifications embedding IoT sensors as inflection indicator for technology-forward targets.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polycarbonate Substrate Production | Captive vacuum deposition quality control secures specification-grade positioning against mid-tier competitors. |
| Direct-Manufacturer Contracting with National Retail Accounts | Walmart and Target mandates displace regional distributors and consolidate procurement under single vendor relationships. |
| Smart-City Traffic Mirror Integration with IoT Sensors | Municipal specifications for congestion monitoring create technology differentiation in German DGUV-regulated markets. |
| Pharmaceutical Cleanroom Mirror Certification | FDA facility safety guidelines for sterile manufacturing specify corrosion-resistant materials in high-margin applications. |
| Indian Logistics Corridor Market Entry | Dedicated freight corridors and inland container depots lack standardized visibility infrastructure, creating first-mover positioning. |
Research Methodology
Multi-period observation of OSHA enforcement intensity, warehouse automation capex cycles, and municipal traffic mirror tender volumes anchored the trend analysis, supplemented by interviews with plant safety managers, distribution center operations directors, optical coating technicians, and municipal procurement officers. Secondary validation drew from OSHA citation databases, DGUV accident statistics, BIS certification registries, and customs trade data for mirror substrate imports. Bottom-up installation unit estimates triangulated against top-down market value reconstruction.
Input-output matrices mapped polycarbonate resin feedstock costs, vacuum deposition capacity utilization, and regulatory enforcement intensity to segment-level demand projections across the analysis window. Modeled dimensions included product type, application environment, installation configuration, material substrate, and regional regulatory cluster. CAGRs derived from regression-weighted historical elasticities applied to projected enforcement schedule and logistics buildout timelines. Industry-specific inputs incorporated forklift collision incident rates and smart-city infrastructure spending commitments.
Underlying measurement precision varies by segment; industrial use and specification-grade product categories carry tighter precision than residential and economy-tier segments due to documented procurement records. Forecasts reflect assumptions about regulatory enforcement continuity, petrochemical price stability, and logistics automation adoption curves. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Tourniquet Market
Safety Equipment and Personal Protective Equipment (PPE)
North America Explosion-Proof Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Protective Eye Wear Market
Safety Equipment and Personal Protective Equipment (PPE)
FFP2 Grade Medical Protective Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
Asia-Pacific Explosion Proof Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
N95 Grade Medical Protective Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
Radiation Protection Cabins Market
Safety Equipment and Personal Protective Equipment (PPE)
Industrial Personal Protective Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Explosion Proof Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Flammable Storage Cabinets Market
Safety Equipment and Personal Protective Equipment (PPE)
Smart Seat Belt Technology Market
Safety Equipment and Personal Protective Equipment (PPE)
Active Seat Belt System Market
Safety Equipment and Personal Protective Equipment (PPE)
Particulate Respirators Market
Safety Equipment and Personal Protective Equipment (PPE)
Middle East and Africa Intrinsically Safe Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Biodegradable Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Non-Powered Air Purifying Respirator Market