
 Latin America Electronics Security Market | 2026-2036
Latin America Electronics Security Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Electronics Security Market Insights
Capital-intensity divergence between integrated platform providers and component assemblers is unwinding competitive stability across the Latin America Electronics Security Market. Hangzhou Hikvision Digital Technology Co., Ltd. leverages its in-house semiconductor fabrication to control costs on IP-based cameras deployed from Mexico City to Lima. Bosch Security Systems Inc. anchors its regional position through localized technical support networks and compliance certification laboratories in Colombia and Argentina. Zhejiang Dahua Technology Co., Ltd. competes aggressively on wireless perimeter solutions tailored to agricultural and mining estates with limited fiber infrastructure.
Electronics security encompasses integrated hardware-software systems for threat detection, access management, and real-time monitoring, typically incorporating sensors with 1080p to 4K resolution, edge-computing analytics processors, and encrypted data transmission protocols operating across 2.4 GHz to 5 GHz spectrums. These systems serve to protect physical assets, personnel, and information infrastructure across commercial, governmental, and residential environments. Video surveillance systems dominate procurement volumes, particularly IP-based configurations with cloud-native storage architectures that reduce on-premise server capital expenditure for mid-sized commercial buyers in Chile and Peru. Access control systems represent the fastest-expanding product category, driven by biometric integration and mobile credential adoption in Brazil's financial services towers and Mexico's pharmaceutical manufacturing campuses.
Brazil's ANPD enforces LGPD-mandated data localization and consent protocols for biometric and video data, compelling vendors to re-architect cloud storage with domestic server presence. Mexico's IFAI privacy standards and Colombia's ICT Ministry cybersecurity directives further fragment compliance requirements across national boundaries. Stakeholders must monitor evolving encryption certification mandates and cross-border data flow restrictions that will determine which technology architectures achieve sustainable market access.
Market Dynamics
Biometric credential adoption and cloud-native video analytics are compressing procurement cycles across Latin America's commercial security sector, forcing vendors to re-architect service delivery models around subscription-based architectures rather than capital-heavy hardware sales.
Growth Catalysts
- LGPD Compliance Mandates:Brazil's ANPD enforcement of biometric data localization rules compels financial institutions in São Paulo to upgrade legacy access control systems with domestically hosted cloud infrastructure.
- Smart City Infrastructure:Metropolitan clusters along the São Paulo-Rio de Janeiro corridor are bundling surveillance procurement with urban mobility upgrades, creating consolidated tender opportunities for integrated platform providers.
- Edge Computing Integration:On-device analytics processors are reducing bandwidth requirements for mining and agricultural estates in Chile's Atacama region, enabling wireless perimeter deployments where fiber remains uneconomical.
Market Restraints
- Semiconductor Supply Concentration:Dependence on East Asian fabrication for image sensors and AI accelerators exposes Latin American integrators to extended lead times and tariff volatility.
- Cross-Border Data Friction:Mexico's IFAI privacy standards and Colombia's ICT Ministry directives create incompatible cloud storage architectures, fragmenting vendor operating leverage across national boundaries.
- Substitution by Cyber-Physical Convergence:IT security vendors are bundling physical access telemetry into zero-trust platforms, compressing standalone electronics security budgets in enterprise accounts.
Strategic Opportunities
- Peru and Ecuador Expansion:Underpenetrated commercial banking and retail sectors in Lima and Guayaquil offer first-mover positioning before regulatory frameworks mature.
- Mobile Credential Convergence:Integration of smartphone-based access tokens with building management systems creates new recurring revenue streams in Mexico's pharmaceutical manufacturing campuses.
- ANPD Certification Acceleration:Early alignment with Brazil's emerging encryption certification mandates positions compliant vendors for preferred supplier status in federal procurement.
Industry Challenges
- Specialized Integration Talent Scarcity:Shortage of technicians certified in both legacy analog systems and IP-based architectures complicates multi-site rollouts for regional banking networks.
- Legacy System Interoperability:Hybrid deployments requiring protocol translation between 20-year-old analog infrastructure and modern API-driven platforms inflate project complexity and margin erosion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Electronics Security Market |
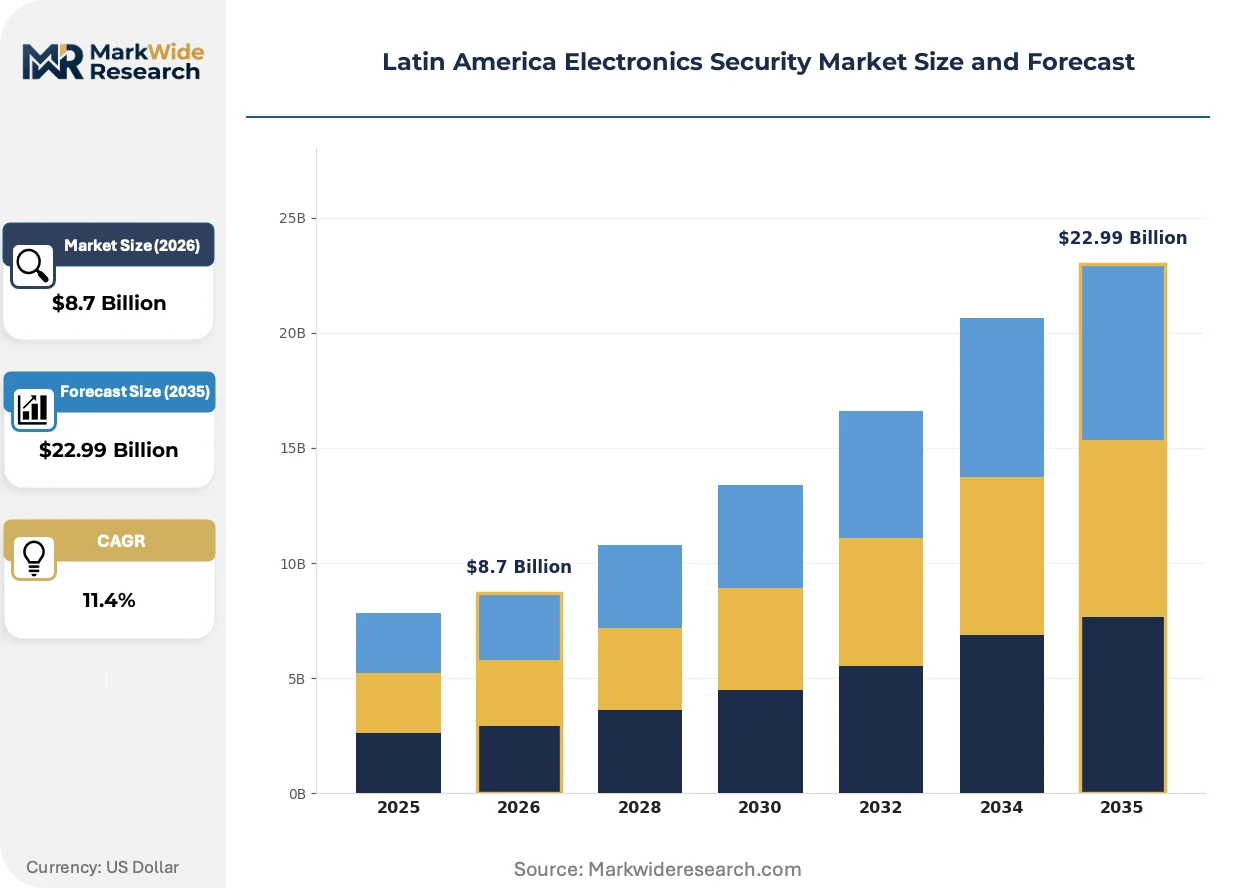
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Intrusion Detection Systems, Video Surveillance Systems, Access Control Systems, Alarms End User: Government, Commercial, Residential, Transportation Technology: Analog, IP-Based, Wireless, Cloud-Based Application: Building Security, Perimeter Security, Cybersecurity, Asset Protection |
| Companies Covered | Hangzhou Hikvision Digital Technology Co., Ltd., Bosch Security Systems Inc., Zhejiang Dahua Technology Co., Ltd., Honeywell International Inc., NEC Corporation, Magal Security Systems, Bykom, Allcomnet, Digiware, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Electronics Security Market Trends and Innovations
Artificial intelligence inference at the network edge is redistributing computational load away from centralized servers, enabling real-time threat detection in bandwidth-constrained environments while compressing total cost of ownership for mid-sized commercial buyers.
Edge-native video analytics is fragmenting the traditional server-centric architecture that has dominated Latin American enterprise security deployments for two decades. Mining operators in Chile's northern regions are deploying solar-powered camera stations with on-board person-vehicle classification, eliminating fiber trenching costs across vast extraction zones. This distributed intelligence model is compressing hardware margins for traditional NVR manufacturers while expanding software licensing opportunities for algorithm developers.
Brazil's ANPD is tightening consent audit requirements for biometric data retention, compelling financial services firms to implement automated data lifecycle management tools alongside physical access systems. The regulation's industrial consequence is a surge in integrated identity governance platforms that unify physical and logical access logs. Large commercial banks in São Paulo are responding by consolidating vendor relationships around providers with certified domestic data centers.
Subscription-based service contracts are displacing capital-intensive hardware purchases among mid-sized retail chains in Colombia and Peru. Channel partners are repositioning as managed security providers, bundling equipment refresh cycles with 24/7 monitoring services. This shift is most visible in Bogotá's shopping center sector, where property managers prioritize operational expenditure predictability over upfront ownership.
Latin America Electronics Security Market Segmentation
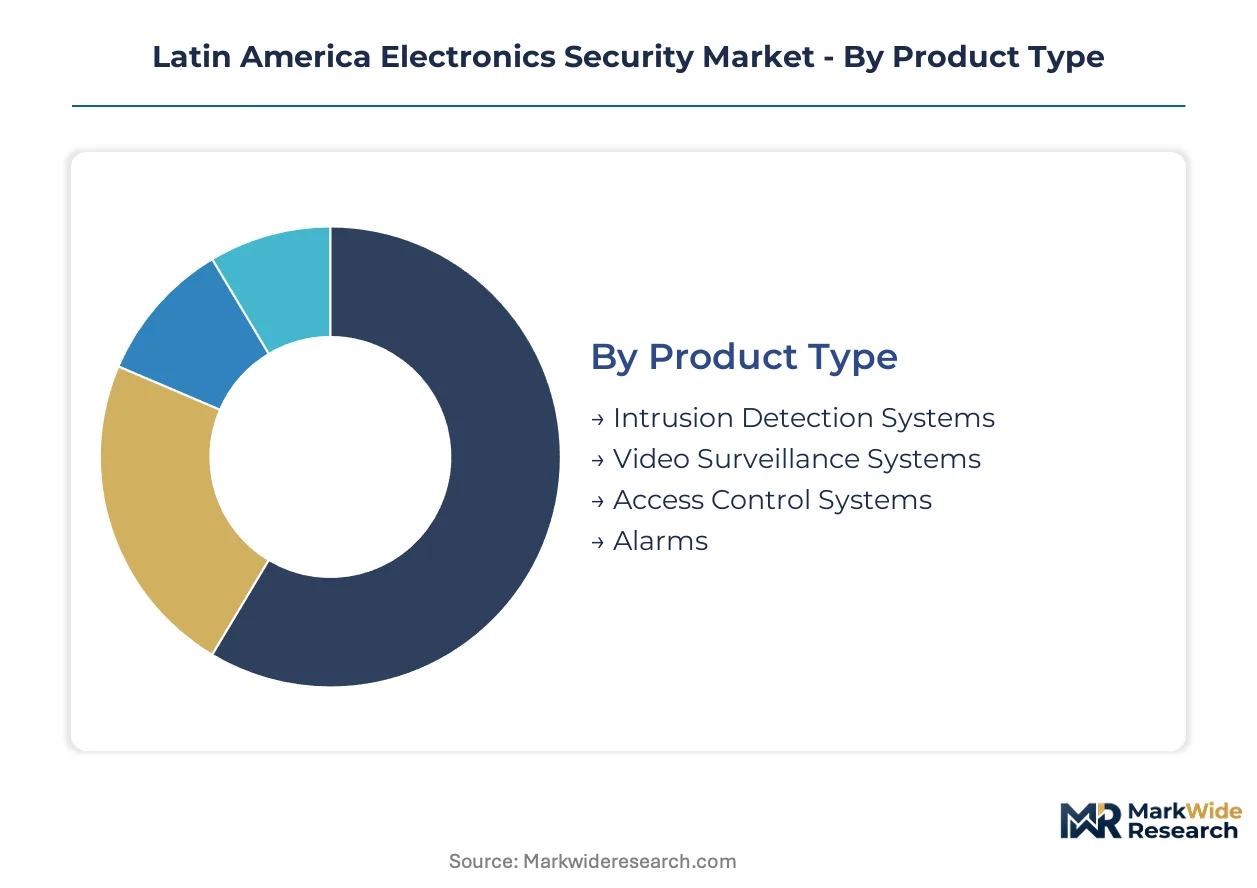
Segmentation in Latin America's electronics security market reveals distinct procurement patterns across national boundaries. Brazil's LGPD compliance requirements and Chile's mining-driven perimeter demands create divergent product specifications that vendors must navigate simultaneously.
Product Type:
Domestic manufacturing presence concentrates in Brazil and Mexico for assembly operations, while core semiconductor components flow from East Asian supply chains. Export-led segments dominate high-complexity integrated systems.
- Video Surveillance Systems:IP-based configurations with 1080p to 4K resolution sensors and edge-computing analytics processors serve commercial banking towers in São Paulo and retail complexes across the São Paulo-Rio de Janeiro corridor. Cloud-native storage architectures reduce capital expenditure for mid-sized Chilean and Peruvian buyers managing distributed branch networks.
- Access Control Systems:Biometric credential readers and mobile token platforms integrate with building management systems in Brazil's financial services sector. ANPD-mandated data localization compels domestic server deployment, elevating total solution cost while tightening vendor qualification requirements.
- Intrusion Detection Systems:Sensor arrays combining motion detection, glass-break acoustic monitoring, and perimeter beam technology protect pharmaceutical manufacturing campuses in Mexico and agricultural estates in Argentina's Pampas region.
- Alarms:Audible and silent alert mechanisms with cellular backup connectivity serve residential developments in Colombian metropolitan zones where fiber infrastructure remains inconsistent.
Video Surveillance Systems commands the established base. The steepest expansion runs through Access Control Systems.
End User:
Cost tier differentiation separates enterprise-grade integrated platforms from component-level procurement. Premium deployments cluster in regulated industries with compliance audit requirements.
- Commercial:Financial institutions, retail chains, and pharmaceutical manufacturers drive procurement volume. Brazil's banking sector upgrades legacy analog infrastructure to biometric-enabled platforms under LGPD enforcement timelines.
- Government:Federal and municipal smart city initiatives bundle surveillance with urban mobility infrastructure. Procurement concentrates in metropolitan corridors with consolidated tender processes.
- Residential:Gated communities and high-rise developments in São Paulo, Mexico City, and Bogotá adopt wireless perimeter solutions where trenching costs prohibit fiber deployment.
- Transportation:Airport authorities and port operators in Chile, Peru, and Brazil implement integrated threat detection for cargo screening and passenger flow monitoring.
Commercial buyers absorb the majority of current procurement spend. Government accounts are expanding most quickly as smart city budgets consolidate.
Technology:
Volume concentration favors IP-Based architectures as legacy analog replacement cycles accelerate across the region's installed base of aging security infrastructure.
- IP-Based:Network-addressable cameras and access controllers with Power-over-Ethernet connectivity dominate new installations. API-driven integration enables unified physical-logical access management for enterprise accounts.
- Cloud-Based:Subscription-managed video storage and analytics reduce on-premise server capital requirements. ANPD data localization mandates require domestic cloud infrastructure presence, fragmenting vendor architectures across national boundaries.
- Wireless:Solar-powered stations with cellular backhaul serve mining perimeters in Chile's Atacama and agricultural estates in Brazil's interior where fiber economics fail.
- Analog:Coaxial-cable systems persist in legacy installations requiring phased migration. Hybrid NVR platforms bridge protocol translation during transition periods.
IP-Based technology holds the dominant installed position. Cloud-Based deployment is gaining share fastest as managed service contracts displace capital purchases.
Application:
Customer type segmentation separates perimeter-focused deployments with environmental exposure from controlled indoor environments with network integration requirements.
- Building Security:Integrated access control, video verification, and intrusion detection protect corporate headquarters and data centers. Brazil's financial towers demand biometric multi-factor authentication with audit trail retention.
- Perimeter Security:Thermal imaging, radar, and video analytics secure extraction zones and agricultural boundaries. Chilean mining operators deploy solar-powered edge stations eliminating trenching across vast territories.
- Asset Protection:Museum, warehouse, and logistics facilities implement sensor fusion combining video, environmental monitoring, and access logging.
- Cybersecurity:Physical access telemetry integration with zero-trust IT platforms compresses standalone electronics security budgets in enterprise accounts.
Building Security represents the largest application segment. Perimeter Security demonstrates the steepest expansion trajectory driven by mining and agricultural estate automation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazilian buyers absorb premium pricing for LGPD-compliant systems while Peruvian and Ecuadorian markets remain acutely price-sensitive, creating divergent vendor strategies across the region.
Brazil
São Paulo's financial towers drive demand for biometric multi-factor authentication with domestic data center hosting. ANPD enforcement of LGPD consent audit requirements compels automated data lifecycle management integration. The São Paulo-Rio de Janeiro corridor concentrates smart city procurement bundling surveillance with urban mobility infrastructure.
Mexico
Pharmaceutical manufacturing campuses in the Bajío Region and Mexico City Metro adopt mobile credential platforms integrated with building management systems. IFAI privacy standards fragment cloud storage architectures with incompatible cross-border data protocols. Nuevo León's industrial parks witness concentrated deployment of IP-based access control for automotive supplier facilities.
Chile
Mining operators in the Atacama region deploy solar-powered edge stations with on-board analytics for perimeter security across vast extraction zones. The country's cybersecurity infrastructure law tightens encryption certification requirements for surveillance data transmission. Santiago's commercial banking sector upgrades legacy analog infrastructure to cloud-native video storage.
Colombia
Bogotá's shopping center sector shifts procurement toward subscription-based managed security services prioritizing operational expenditure predictability. ICT Ministry cybersecurity directives create domestic cloud infrastructure preferences that elevate vendor qualification barriers. Medellín's corporate headquarters cluster drives integrated platform demand for building security applications.
Argentina
Agricultural estates in the Pampas region adopt wireless perimeter solutions where fiber trenching costs remain prohibitive. The country's national data protection authority enforces consent protocols for biometric deployment in commercial settings. Buenos Aires metropolitan area concentrates legacy system migration projects requiring hybrid analog-IP protocol translation.
Latin America Electronics Security Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the upper tier commanding premium positioning through domestic compliance certification and localized technical infrastructure. The middle tier competes on wireless and edge-native solutions for bandwidth-constrained deployments. Two dominant competitive moves are reshaping positioning: strategic partnerships with domestic cloud infrastructure providers to satisfy data localization mandates, and portfolio diversification into subscription-managed service contracts displacing capital-heavy hardware sales.
Among East Asian technology conglomerates, Hangzhou Hikvision Digital Technology Co., Ltd. and Zhejiang Dahua Technology Co., Ltd. occupy positions exemplifying integrated manufacturing scale, while Bosch Security Systems Inc. represents the European industrial archetype with established regional compliance laboratories. These three anchors illustrate divergent strategic vectors: semiconductor cost control through captive fabrication, aggressive wireless specialization for infrastructure-poor environments, and localized certification infrastructure for regulatory adherence.
| Leading Market Players |
|---|
| Hangzhou Hikvision Digital Technology Co., Ltd. |
| Bosch Security Systems Inc. |
| Zhejiang Dahua Technology Co., Ltd. |
| Honeywell International Inc. |
| NEC Corporation |
| Magal Security Systems |
| Bykom |
| Allcomnet |
| Digiware |
| Others |
Pricing and Supply Chain Analysis
Semiconductor fabrication scale in East Asia creates asymmetric cost advantages that compress price floors for IP camera assemblies across São Paulo and Mexico City while elevating margin capture for vendors with captive wafer production. This concentration simultaneously fragments Latin American integrators' bargaining leverage and forces tiered service bundling to recover hardware profitability.
Pricing Analysis
Extended service contracts and firmware subscription tiers now generate lifetime value exceeding original hardware margins for integrated platform providers. Three-tier pricing structure across premium, standard, and economy levels separates ANPD-certified domestic cloud deployments from basic IP configurations and legacy analog replacements. Cost compression in economy tiers is intensifying because Brazilian distributors absorb tariff volatility on image sensors. Mid-sized retail chains in Colombia exhibit acute price sensitivity, while São Paulo financial towers accept premium positioning for biometric systems with audit-grade data localization.
Supply Chain Analysis
Panama Canal transit congestion and Pacific port capacity constraints expose Latin American integrators to logistics chokepoints that extend component lead times unpredictably. Manufacturing concentration in Taiwan, South Korea, and China feeds image sensors, AI accelerators, and edge-computing processors into regional assembly plants in Brazil and Mexico. Supply chain risk centers on single-source vulnerability for advanced CMOS sensors where alternative qualified vendors remain scarce. Distribution runs through authorized distributor networks with technical certification requirements that filter unauthorized gray-market imports.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Physical security is consolidating around platform economics where API-driven interoperability between access control, video analytics, and building management systems creates winner-take-most dynamics. Vendors that own the integration layer capture recurring revenue while component specialists face margin compression.
For Market Incumbents: Shield installed base relationships by embedding ANPD-compliant domestic cloud infrastructure before regulatory deadlines harden qualification requirements. Accelerate certification laboratory investment in Colombia and Argentina to preempt emerging encryption mandates. Channel control through exclusive technical training programs limits integrator poaching by low-cost wireless specialists targeting agricultural estates. For New Entrants and Emerging Players: Anchor in Peru's underpenetrated commercial banking sector and Ecuador's retail corridor before compliance frameworks mature and incumbent switching costs solidify. Wireless perimeter solutions for mining and agricultural estates with limited fiber infrastructure offer the most penetrable entry vector. Go-to-market execution should prioritize solar-powered edge stations with cellular backhaul to bypass established distributor relationships. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among managed security service providers with subscription-based equipment refresh cycles. Long-term viability favors vendors with demonstrated ANPD certification acceleration and domestic data center presence. Acquisition targets should demonstrate software licensing growth outpacing hardware sales. The signal to watch is federal procurement preference list publication timing, which will abruptly re-rank vendor competitiveness.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Cloud Infrastructure Partnership | ANPD data localization mandates require certified server presence for federal procurement eligibility. |
| Biometric Certification Acceleration | Early alignment with Brazil's encryption standards secures preferred supplier status in financial services. |
| Managed Service Contract Conversion | Subscription bundling with 24/7 monitoring displaces capital-heavy hardware sales in Colombian retail. |
| Edge-Native Analytics Development | On-device processing reduces bandwidth costs for Chilean mining perimeters without fiber trenching. |
| Mobile Credential Platform Integration | Smartphone-based access tokens create recurring revenue streams in Mexico's pharmaceutical manufacturing. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, customs trade records, and sector procurement databases to validate market sizing and competitive positioning assessments. Primary interviews engaged security systems integrators, ANPD compliance officers at financial institutions, mining operations technology managers, and commercial real estate facility directors across Brazil, Mexico, Chile, Colombia, and Argentina. Secondary sources included ANPD enforcement bulletins, ICT Ministry cybersecurity directives, smart city tender documentation, and SEC filings of publicly traded technology conglomerates with regional security divisions. Bottom-up demand modeling triangulated against top-down supply-side capacity assessments.
Segmentation dimensions modeled span product type, end-user industry, technology architecture, and application environment across the analysis window. Deployment model differentiation between on-premise, hybrid, and cloud-native configurations intersected with organization size tiers and national regulatory clusters. CAGRs were derived from fitted growth curves anchored to documented procurement volumes and announced smart city infrastructure budgets. Industry-specific forecast inputs incorporated LGPD enforcement timeline assumptions and mining sector capital expenditure patterns for perimeter automation.
Decision-makers should treat outputs as directional under assumptions of sustained ANPD enforcement intensity and stable East Asian semiconductor supply; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as cross-border data flow restrictions and tariff regime shifts evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security and Surveillance
Stadium Security Market
Security and Surveillance
Narcotics Scanner Market
Security and Surveillance
Global Acoustic Hailing Devices Market
Security and Surveillance
Alarm Monitoring Software Market
Security and Surveillance
Global Wireless Monitoring and Surveillance Market
Security and Surveillance
Burglar Alarm Systems Market
Security and Surveillance
Global Police and Law Enforcement Equipment Market
Security and Surveillance
Security Operations Center Market
Security and Surveillance
Global Alarm Monitoring Market
Security and Surveillance
Swimming Pool Alarm Market
Security and Surveillance
Anti-Piracy Protection Market
Security and Surveillance
Europe Cargo and Vehicle Screening Market
Security and Surveillance
Baggage Scanner Market
Security and Surveillance
Proactive Security Market
Security and Surveillance
Situational Awareness System Market
Security and Surveillance
Europe Baggage and Parcel Screening Market