
 E-Bike Charging Station Market | 2026-2036
E-Bike Charging Station Market Size, Share, and Industry Trends Forecast 2026-2036
E-Bike Charging Station Market Intelligence
Modular charging pods bundled with solar canopies and battery storage are restructuring buyer choice across municipal and commercial segments. Robert Bosch GmbH leverages its automotive power-electronics heritage to anchor premium hardware positions. ChargePoint, Inc. competes through software-integrated network management that sustains recurring revenue streams. EVBox B.V. specializes in open-protocol interoperability, differentiating its hardware for multi-brand fleet compatibility.
An e-bike charging station is an electrical infrastructure unit that converts grid or renewable AC power to regulated DC output, typically delivering 250W to 3kW through standardized connectors for lithium-ion battery packs, with primary purpose of enabling safe, rapid energy replenishment for electric two-wheelers in public and semi-public environments. Docked stations dominate urban street deployments where permanence and vandal resistance matter, while smart-connected units capture the fastest expansion as operators demand remote monitoring, payment integration, and dynamic load balancing. Fleet operator applications concentrate margin pools through volume procurement contracts and long-term service agreements that standardize on medium-power hardware.
EU Green Deal framework and F-Gas Regulation shape product standards by mandating energy efficiency disclosures and restricting refrigerants in thermal management systems, while CE marking requirements govern electrical safety and electromagnetic compatibility for market access. Germany's KBA and the Netherlands' national cycling infrastructure agency enforce installation codes that dictate spacing, accessibility, and grid-connection protocols. Stakeholders must monitor evolving interoperability mandates and subsidy qualification criteria that will determine which hardware configurations qualify for public funding pools.
Market Dynamics
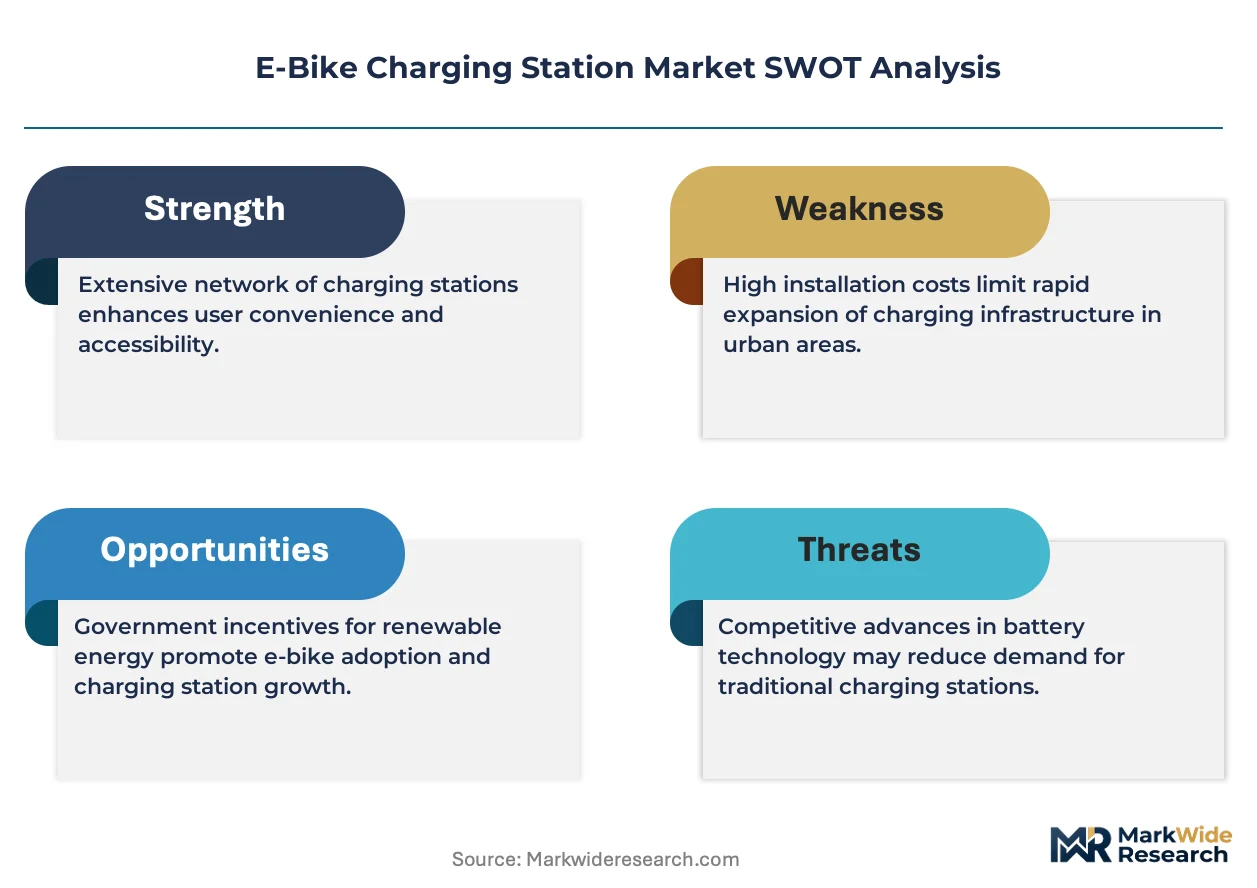
Grid-edge intelligence and bidirectional power electronics are compressing hardware margins while elevating software and energy-management services as the primary value capture layer for station operators.
Growth Catalysts
- EU Green Deal emissions targets:Municipal fleet operators in Germany, the Netherlands, and Denmark are accelerating public procurement of charging infrastructure to meet binding carbon reduction timelines for urban logistics.
- Shared mobility services:Dockless e-bike and e-cargo bike rental platforms require dense, networked charging coverage to maintain vehicle utilization rates above sixty percent.
- Lithium-ion battery chemistry advances:Higher energy density cells now tolerate faster charge rates, enabling 3kW rapid-charge stations that cut dwell times by half compared to legacy 250W hardware.
Market Restraints
- Copper and rare-earth magnet costs:Power conversion modules depend on copper windings and neodymium-dysprosium magnets whose prices fluctuate with mining output from China and the Democratic Republic of Congo.
- Grid connection queuing:Distribution network operators in dense urban cores impose eighteen-to-thirty-six-month lead times for new medium-voltage connections, freezing deployment timelines.
- Interoperability fragmentation:Proprietary connector standards from Asian e-bike manufacturers create compatibility dead zones that strand public investment in single-brand infrastructure.
Strategic Opportunities
- French suburban retrofit programs:The country's national cycling plan allocates dedicated funding for charging hubs at commuter rail stations serving the Île-de-France periphery.
- Solar canopy integration:Photovoltaic shade structures paired with DC-coupled battery storage allow off-grid operation during peak demand events, reducing utility demand charges.
- Last-mile logistics electrification:Courier and parcel delivery fleets in Belgian and Dutch cities are tendering for dedicated depot charging with load-balancing software to manage overnight vehicle preparation.
Industry Challenges
- Power electronics engineering talent:Design of GaN and SiC inverter topologies requires specialized expertise concentrated in automotive and renewable energy sectors, creating recruitment competition.
- CE marking electromagnetic compatibility testing:Certification laboratories face twelve-month backlogs for conducted emissions and immunity validation, delaying product launches.
- Legacy street furniture integration:Retrofitting charging capability into existing lamp posts and bus shelters demands mechanical redesign to accommodate thermal management and cable routing constraints.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | E-Bike Charging Station Market |
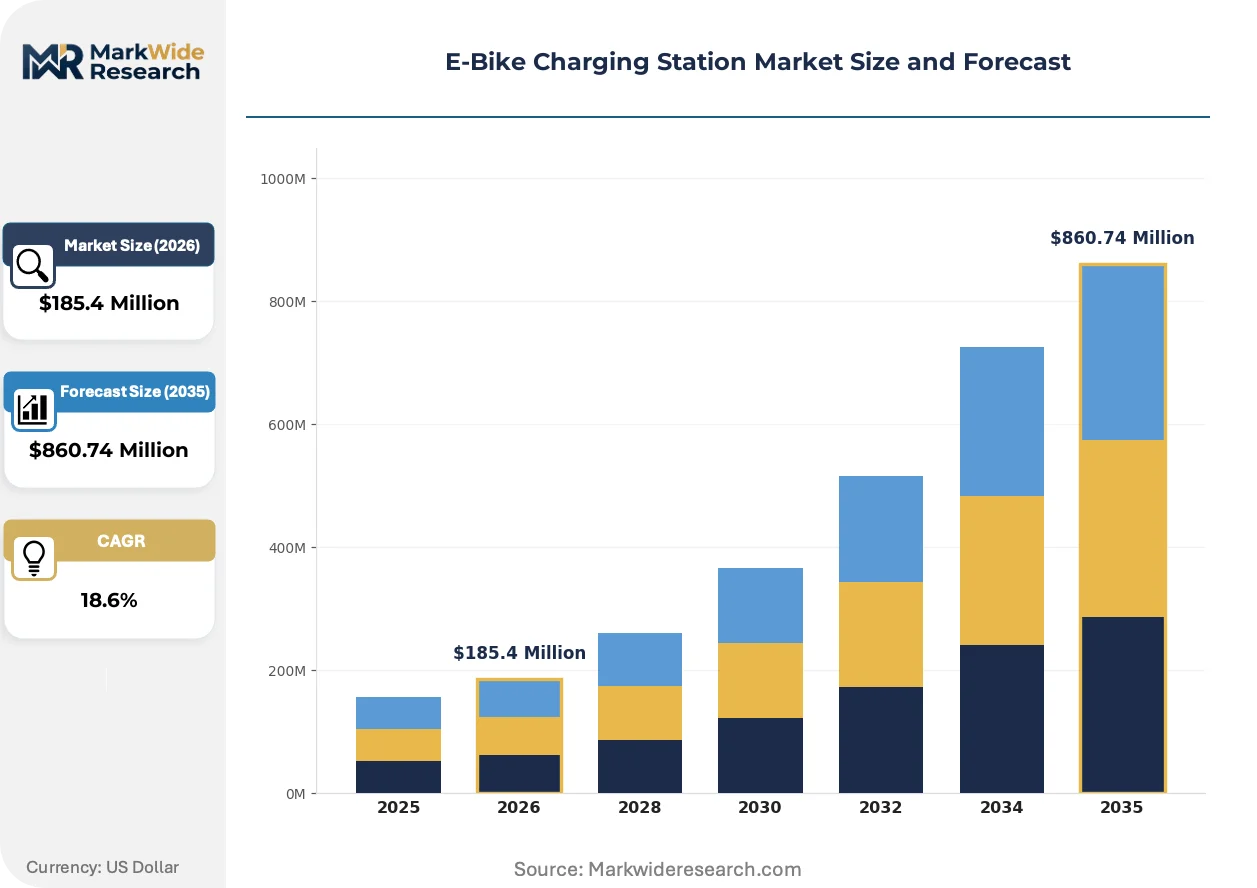
| Market Size in 2026 | $185.4 Million |
| Market Size in 2035 | $860.74 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Station Type: Docked, Mobile, Smart, Solar-Powered, Ultra-Fast Power Capacity: Low Power, Medium Power, High Power, Rapid Charge, Standard Output User Application: Commuters, Tourists, Delivery Riders, Campus Users, Fleet Operators Installation Environment: Urban Streets, Shopping Centers, Parking Garages, Public Parks, Transit Hubs |
| Companies Covered | Robert Bosch GmbH, Amezeus, Ather Energy, Bikeep, CYCLE WORKS, EV Motors India Pvt. Ltd., ChargePoint, Inc., Swiftmile, Inc., EVBox B.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
E-Bike Charging Station Market Strategic Shifts & Innovations
Silicon carbide semiconductors, dynamic load-balancing algorithms, and vehicle-to-grid protocols are converging to transform charging stations from passive outlets into active grid assets.
Silicon carbide MOSFETs in power conversion stages operate at switching frequencies five times higher than silicon IGBTs, shrinking magnetics volume and cooling requirements. Tier-one automotive suppliers are transferring this capability to e-bike charging hardware, cutting station footprints by forty percent. This semiconductor transition is rewriting the economics of high-density urban deployments where sidewalk space commands premium lease rates.
The EU F-Gas Regulation mandates phase-down of hydrofluorocarbon refrigerants in thermal management systems, pushing manufacturers toward dielectric fluid immersion and thermoelectric cooling. Station designers must now validate passive cooling architectures or invest in alternative active systems. Hardware destined for Southern European markets faces the steepest redesign burden as ambient temperature specifications tighten.
Fleet operators are consolidating vendor relationships around full-service contracts that bundle hardware, installation, software licensing, and energy procurement into per-kilometer or per-charge pricing. This unbundles capital expenditure from operational budgets, favoring vendors with balance-sheet capacity to finance asset deployment. The model is most advanced in Copenhagen and Amsterdam, where municipal logistics tenders now specify outcome-based availability guarantees rather than equipment procurement.
E-Bike Charging Station Market Segmentation
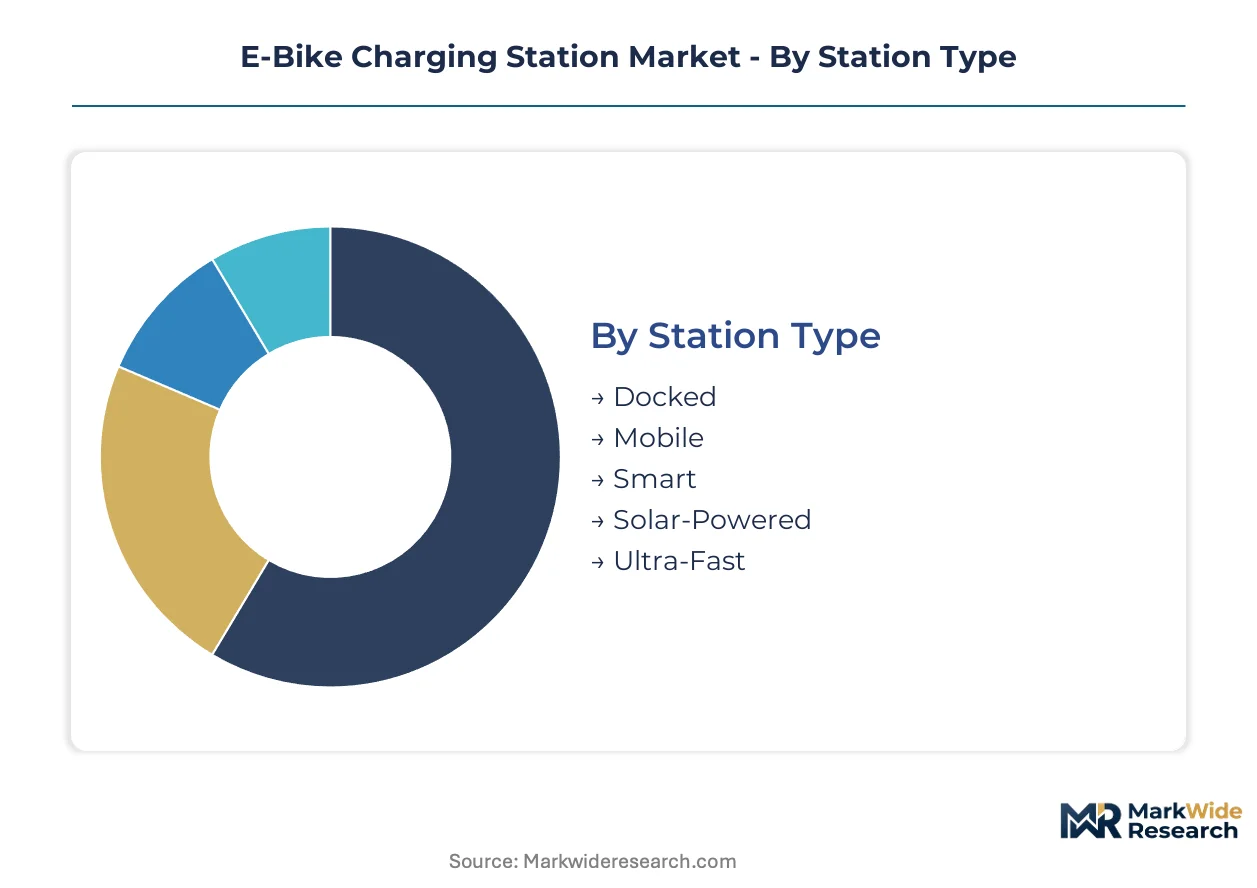
Station type and power capacity configurations determine hardware margins and deployment economics for operators across municipal and commercial procurement channels. User application and installation environment variables dictate site selection criteria, utilization rates, and revenue model design for network planners.
Station Type:
Physical form factor and connectivity architecture separate permanent infrastructure from flexible deployment options.
- Docked:Fixed-position units with integrated locking mechanisms dominate urban street deployments where vandal resistance and permanence justify higher capital outlay. German municipal tenders specify docked hardware for shared mobility contracts exceeding five-year service terms.
- Smart:Network-connected stations with remote monitoring, dynamic load balancing, and payment integration capture the steepest expansion trajectory as fleet operators demand real-time utilization analytics. Copenhagen's municipal logistics contracts now mandate API-accessible station data.
- Mobile:Trailer-mounted or containerized units serve temporary events and construction zones where grid connections remain unavailable.
- Solar-Powered:Off-grid configurations with photovoltaic canopies and battery buffers reduce utility dependency for suburban rail station deployments.
- Ultra-Fast:High-current output stations targeting commercial delivery fleets with sub-thirty-minute charge cycles.
Docked stations lead on scale; smart stations lead on momentum.
Power Capacity:
Output specifications align charging duration with dwell-time economics across commuter, tourist, and logistics use cases.
- Medium Power:500W to 1.5kW output stations balance charge speed against grid connection costs for multi-hour parking scenarios. Dutch shopping center operators standardize on this tier for customer amenity programs.
- Rapid Charge:2kW to 3kW stations exploit lithium-ion chemistry advances that tolerate faster charge rates without thermal degradation. Belgian parcel delivery fleets specify rapid-charge hardware for depot overnight preparation.
- Low Power:250W to 500W units serve workplace and residential settings where vehicles park for extended durations.
- High Power:Above 3kW configurations reserved for heavy cargo bikes and commercial vehicle classes.
- Standard Output:Legacy 250W hardware facing replacement pressure from faster alternatives.
Medium power dominates procurement volume; rapid charge gains share fastest in logistics segments.
User Application:
Customer segment characteristics determine pricing tolerance, frequency of use, and network density requirements.
- Fleet Operators:Volume procurement contracts with long-term service agreements concentrate margin pools and standardize on interoperable hardware. Amsterdam municipal tenders specify outcome-based availability guarantees rather than equipment purchase.
- Delivery Riders:High-frequency users with predictable routes generate the most consistent utilization rates for network revenue models. Danish courier cooperatives negotiate dedicated depot charging with load-balancing software.
- Commuters:Regular but lower-frequency users demanding reliability for daily transportation.
- Tourists:Seasonal demand concentration requiring flexible pricing and multilingual interfaces.
- Campus Users:Captive populations with predictable parking durations favoring subscription pricing.
Fleet operators anchor procurement scale; delivery riders drive utilization intensity.
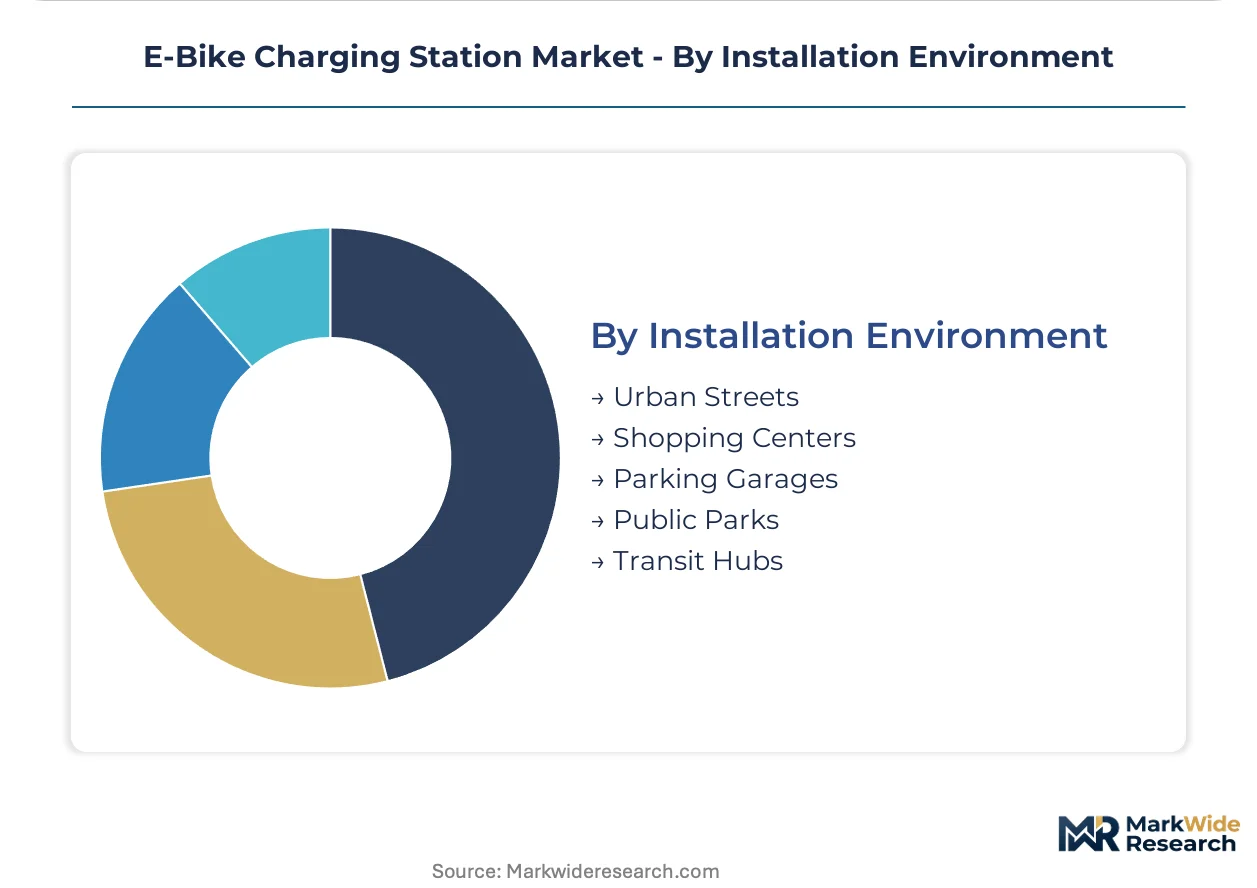
Installation Environment:
Site ownership structures and foot traffic patterns shape capital deployment priorities and partnership strategies.
- Transit Hubs:Rail and bus interchanges generate the highest dwell-time utilization for commuter-oriented networks. French national cycling plan funding targets charging hubs at Île-de-France commuter rail stations.
- Urban Streets:Public right-of-way deployments require compliance with KBA and Netherlands cycling infrastructure agency codes on spacing and accessibility.
- Shopping Centers:Private property hosts seeking customer retention through amenity provision.
- Parking Garages:Existing electrical infrastructure reduces grid connection costs for indoor installations.
- Public Parks:Recreational corridors with seasonal demand variation and aesthetic design constraints.
Transit hubs concentrate revenue density; urban streets expand network coverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The e-bike charging station industry traces its commercial roots to Northern European cycling infrastructure investments during the early 2010s, when Dutch and Danish municipal planners first standardized public charging hardware for shared mobility fleets.
Germany
Kraftfahrt-Bundesamt installation codes mandate spacing and accessibility standards for urban street deployments. The EU Green Deal framework accelerates municipal procurement timelines for logistics electrification. Berlin and Hamburg anchor fleet operator concentration, with depot charging contracts specifying outcome-based availability guarantees rather than equipment purchase.
Netherlands
The national cycling infrastructure agency enforces grid-connection protocols that shape hardware specifications for public right-of-way installations. F-Gas Regulation compliance requirements push manufacturers toward dielectric fluid immersion cooling. Amsterdam and Rotterdam drive smart-connected station adoption through API-accessible data mandates in municipal tenders.
Denmark
Copenhagen's municipal logistics contracts pioneered full-service bundling that unbundles capital expenditure from operational budgets. CE marking requirements govern electromagnetic compatibility for market access. Danish courier cooperatives negotiate dedicated depot charging with load-balancing software integration.
France
The national cycling plan allocates dedicated funding for charging hubs at Île-de-France commuter rail stations serving suburban peripheries. Energy efficiency disclosure mandates under EU Green Deal shape product standards. Paris and Lyon cluster shopping center operators standardizing on medium-power hardware for customer amenity programs.
Belgium
Parcel delivery fleets in Brussels and Antwerp tender for rapid-charge depot infrastructure to manage overnight vehicle preparation. Copper and rare-earth magnet cost volatility affects power conversion module economics. Belgian logistics operators concentrate procurement volume through long-term service agreements.
E-Bike Charging Station Market Key Industry Players
Premium-margin players sit above commodity-margin players across software-integration and thermal-management capabilities. The vendor base organizes into three tiers: automotive heritage suppliers with power-electronics expertise, network-management specialists with recurring revenue platforms, and regional hardware fabricators competing on installation cost. Strategic moves concentrate on interoperability certification and solar-canopy bundling to escape hardware margin compression.
Within the automotive heritage tier, Robert Bosch GmbH exemplifies premium positioning through power-electronics engineering depth. Among network-management specialists, ChargePoint, Inc. and EVBox B.V. occupy positions emphasizing software-integrated operations and open-protocol interoperability respectively. These three anchors represent divergent paths to value capture as grid-edge intelligence elevates service layers above commodity hardware.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Amezeus |
| Ather Energy |
| Bikeep |
| CYCLE WORKS |
| EV Motors India Pvt. Ltd. |
| ChargePoint, Inc. |
| Swiftmile, Inc. |
| EVBox B.V. |
| Others |
Cost & Logistics Intelligence
EU F-Gas Regulation phase-down mandates gate qualified supply and premium-tier pricing access, restricting thermal management architectures to dielectric fluid immersion or thermoelectric cooling systems that only certified manufacturers can deliver at margin. German KBA installation codes and Netherlands cycling infrastructure agency protocols further segment hardware tiers by compliance depth, concentrating price premiums among vendors with electromagnetic compatibility validation and multi-year municipal track records.
Pricing Analysis
Full-service bundling with per-kilometer or per-charge contracting dominates procurement in Copenhagen and Amsterdam, separating outcome-based availability guarantees from capital expenditure. Price differentiation hinges on software-integrated network management depth and CE marking tier, with rapid-charge hardware commanding premiums over legacy 250W units. Cost compression in medium-power tiers intensifies as silicon carbide MOSFET adoption shrinks magnetics volume and invites automotive supplier entry. Fleet operators exhibit lowest price sensitivity due to long-term service agreements, while shopping center amenity programs show highest elasticity to upfront hardware costs.
Supply Chain Analysis
CE marking electromagnetic compatibility certification creates twelve-month laboratory backlogs that filter hardware vendors by balance-sheet capacity to finance delayed revenue recognition. Power conversion module supply concentrates in Germany, China, and Taiwan, drawing from copper winding and neodymium-dysprosium magnet feedstocks anchored in Chinese and Democratic Republic of Congo mining output. Single-source vulnerability runs through rare-earth magnet processing concentration. Distribution feeds from Tier-1 automotive heritage suppliers and network-management specialists through municipal procurement channels and fleet operator direct contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The E-Bike Charging Station Market functions as a geographic-arbitrage play where Dutch and Danish outcome-based contracting models export premium pricing structures into German and French markets still anchored to equipment purchase paradigms.
For Market Incumbents: Anchor software-integrated network management capabilities against automotive supplier entry by deepening API-accessible data services for fleet operator utilization analytics. Pursue backward integration into silicon carbide power electronics to defend margin position as semiconductor transitions rewrite hardware economics. Lock municipal logistics contracts through outcome-based availability guarantees that unbundle capex from opex and raise switching costs for competitor displacement. For New Entrants and Emerging Players: Launch via solar-canopy bundling in French suburban retrofit programs where national cycling plan funding reduces customer acquisition friction. Target Belgian parcel delivery depot charging with rapid-charge hardware and load-balancing software integration, a segment where incumbent coverage remains thin. Penetrate through full-service financing structures that assume asset ownership risk in exchange for long-term energy management contracts. For Investors and Strategic Acquirers: Valuations sit cheapest among regional hardware fabricators lacking software layers but holding certified manufacturing capacity and municipal installation relationships. Long-term viability across the analysis window favors vendors with balance-sheet capacity to finance asset deployment under outcome-based contracting models. Watch API-accessible data mandates in municipal tenders as the inflection signal for software-integrated network management becoming table stakes rather than premium differentiation.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Power Electronics Transition | Shrinks station footprints by forty percent and rewrites high-density urban deployment economics. |
| Full-Service Outcome-Based Contracting | Unbundles capital expenditure from operational budgets in Copenhagen and Amsterdam municipal logistics. |
| Solar Canopy Integration | Enables off-grid operation during peak demand events and reduces utility demand charges. |
| Open-Protocol Interoperability Certification | Differentiates hardware for multi-brand fleet compatibility under EU Green Deal procurement. |
| API-Accessible Data Platform Development | Meets Copenhagen municipal logistics contract mandates for real-time station utilization analytics. |
Research Approach
Direct dialogue with municipal fleet procurement officers, charging station OEM product managers, power electronics engineering directors, and distribution network operators grounds qualitative findings, validated against secondary sources including KBA installation code filings, Netherlands cycling infrastructure agency technical specifications, EU F-Gas Regulation compliance databases, and municipal tender documentation from Berlin, Amsterdam, and Copenhagen. Bottom-up and top-down triangulation cross-checks hardware shipment data against public infrastructure investment disclosures.
Bottom-up modeling aggregates station-type, power-capacity, and user-application segments across the projection horizon, while top-down validation benchmarks against EU Green Deal emissions target trajectories and national cycling infrastructure subsidy allocations. CAGRs derive from logistic diffusion curves fitted to lithium-ion chemistry adoption rates and fleet electrification timelines. Forecast inputs incorporate silicon carbide semiconductor cost curves and grid-connection queuing durations from distribution network operators.
Forecast precision tightens around the base case; tail outcomes carry wider variance under copper and rare-earth magnet price volatility or extended CE marking laboratory backlogs. Projections reflect assumptions of continued EU Green Deal framework stability and F-Gas Regulation enforcement trajectory. A model refresh is warranted upon material change in interoperability mandate timing or subsidy qualification criteria revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
Electric Vehicle Showroom Charger Market
Electric Vehicle Charging
Electric Vehicle (EV) Charging Connector Market
Electric Vehicle Charging
South America Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Global Electric Vehicle (EV) Charging Service Market
Electric Vehicle Charging
Solar Charging Station Market
Electric Vehicle Charging
Battery Liquid Cooling Plates for Electric Vehicle Market
Electric Vehicle Charging
EV Charging Infrastructure Market
Electric Vehicle Charging
Asia-Pacific Electric Vehicle Charging Cable Market
Electric Vehicle Charging
Second Life Electric Vehicle Battery Market
Electric Vehicle Charging
Electric Vehicle (EV) Charging Station Operation Market
Electric Vehicle Charging
Electric Vehicle Safe Charging Inlet Market
Electric Vehicle Charging
Bi Directional Electric Vehicle Charger Market
Electric Vehicle Charging
Stationary Electric Vehicle Charging Gun Market
Electric Vehicle Charging
North America Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Electric Vehicle DC Fast Charging Station Market
Electric Vehicle Charging
India Battery Swapping for Electric Two-Wheelers Market