
 Agrimony Market | 2026-2036
Agrimony Market Size, Share, and Industry Trends Forecast 2026-2036
Agrimony Market Outlook
European herb cultivation is rebalancing after weather-driven shortages in Balkan growing regions. MOUNTAIN ROSE HERBS leverages its Pacific Northwest sourcing network to secure consistent organic supply. Penn Herb anchors its position through deep retail penetration in Philadelphia's herbalist corridor. Falcon Russia competes on volume in Eastern European wholesale channels despite logistical complexity.
Agrimony designates a perennial herb from the Rosaceae family, containing tannins, flavonoids, and volatile oils extracted through aqueous or ethanol-based processes for therapeutic and flavoring applications. The dried aerial parts serve pharmaceutical and nutraceutical manufacturers seeking astringent and anti-inflammatory properties. Herbal extracts and liquid tinctures occupy the premium tier where organic certification commands price separation, while powder form dominates bulk ingredient procurement for supplement blending. Nutraceuticals represents the fastest-growing end use industry as functional food brands incorporate agrimony into digestive wellness formulations.
EMA's Committee on Herbal Medicinal Products governs monograph compliance for agrimony-based therapeutics in Europe, while the EU Organic Regulation enforces traceability from field to finished product. REACH and F-Gas Regulation indirectly shape extraction solvent standards and processing equipment emissions for herb processors. Stakeholders must monitor evolving monograph updates and organic equivalency agreements to sustain market access across European distribution channels.
Market Dynamics
The Agrimony Market is being fundamentally restructured by tightening EU Herbal Medicinal Products Directive compliance requirements that are forcing processors to upgrade documentation systems and traceability infrastructure. German pharmaceutical formulators now demand certified organic supply chains with full batch records, compressing margins for smaller Balkan cultivators who lack digital field-to-finished-product tracking capabilities.
Growth Catalysts
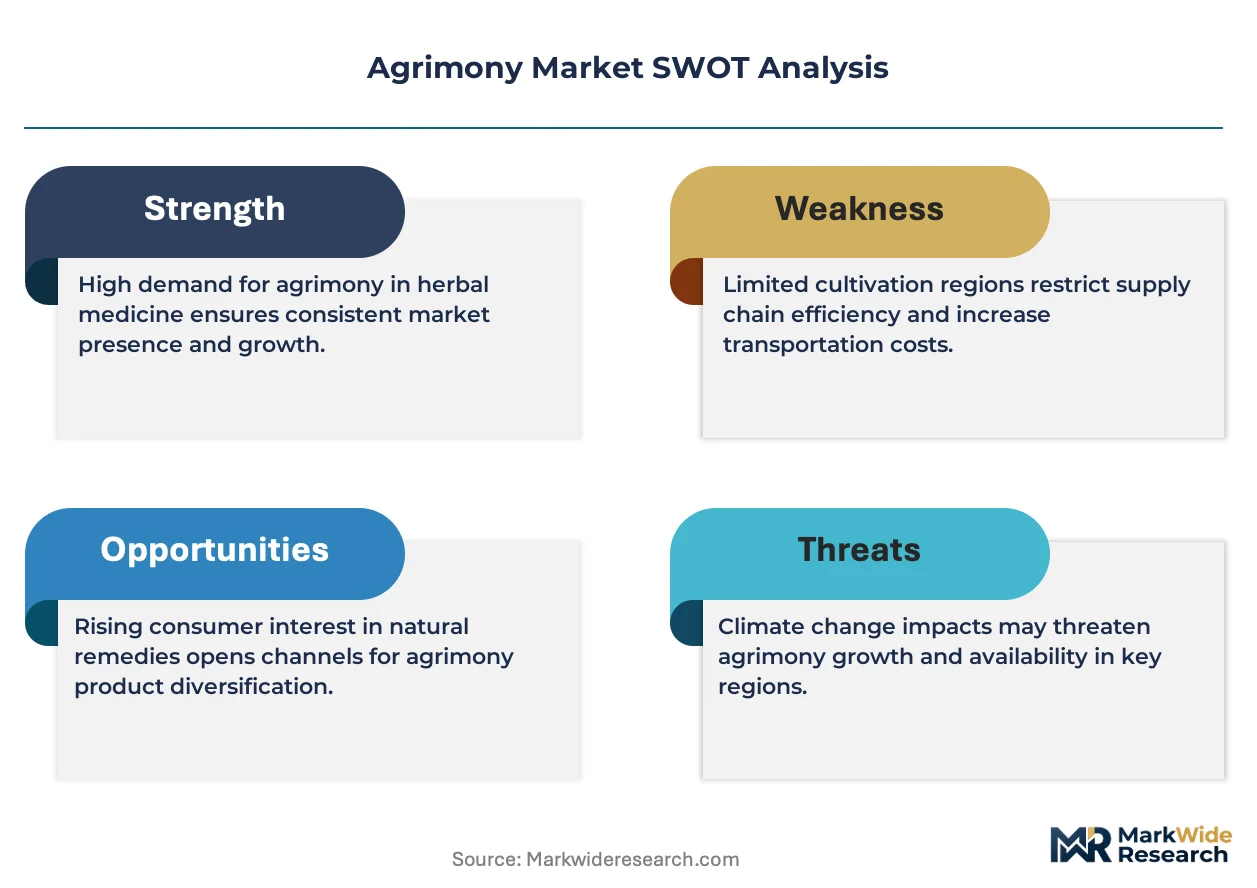
- Digestive wellness formulations:Functional food brands in Poland and the Czech Republic are incorporating agrimony extracts into gut health supplements, creating sustained procurement volume from traditional herbal medicine loyalists.
- REACH solvent standards:Evolving extraction equipment emissions rules are accelerating adoption of closed-loop ethanol recovery systems that improve yield consistency and reduce environmental liability for processors.
- Wound-healing applications:German pharmaceutical manufacturers are expanding agrimony-based topical development programs, driven by EMA monograph recognition of astringent and anti-inflammatory properties.
Market Restraints
- Weather-driven Balkan supply volatility:Concentrated cultivation in Bulgarian and Romanian growing regions exposes processors to yield instability from drought and flooding cycles.
- Organic certification cost burden:Smallholder farms face prohibitive EU Organic Regulation compliance expenses for soil testing, buffer zones, and third-party audit fees.
- Synthetic astringent substitution:Aluminum-based compounds in conventional wound care products compete on price and supply predictability against botanical alternatives.
Strategic Opportunities
- Polish retail herbalist channel expansion:Independent apothecaries and natural product stores represent underdeveloped distribution infrastructure for premium organic tinctures and extracts.
- Carbon-negative extraction technology:Supercritical CO2 systems powered by renewable energy are converging with agrimony processing to create climate-certified ingredient tiers commanding price separation.
- Nutraceutical contract manufacturing:White-label production partnerships with functional food brands allow processors to capture value without building proprietary consumer marketing capabilities.
Industry Challenges
- Phytochemical standardization expertise:Analytical chemists capable of validating consistent tannin and flavonoid content across harvest batches remain scarce in Eastern European processing hubs.
- Legacy drying infrastructure:Many Balkan cooperatives operate convection ovens that degrade volatile oil content, requiring capital-intensive upgrades to vacuum or freeze-drying systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Agrimony Market |
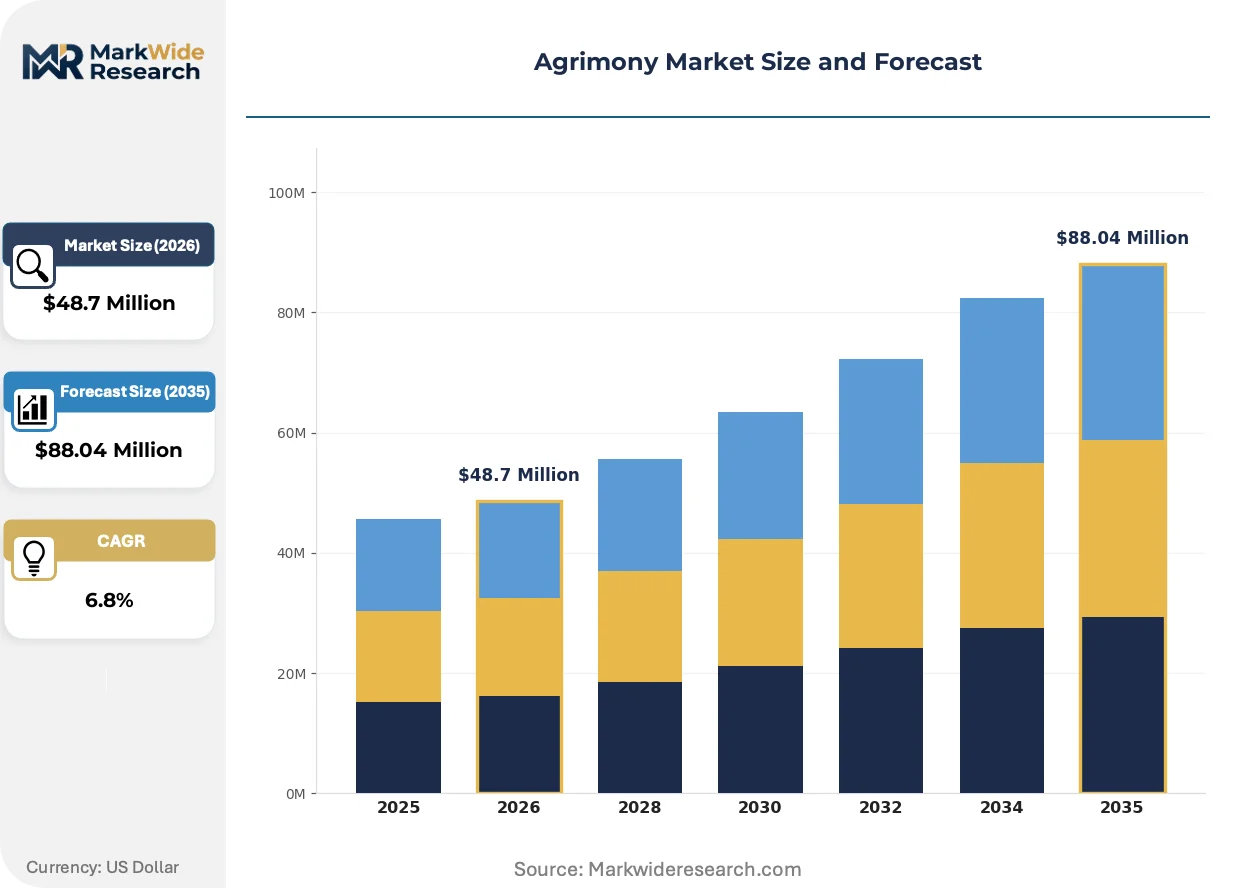
| Market Size in 2026 | $48.7 Million |
| Market Size in 2035 | $88.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Herbal Extracts, Powder Form, Liquid Tinctures, Capsules End Use Industry: Pharmaceuticals, Food & Beverages, Cosmetics, Nutraceuticals Distribution Channel: Online Retail, Health Stores, Pharmacies, Supermarkets Packaging Type: Glass Bottles, Blister Packs, Pouches, Jars |
| Companies Covered | RJWhelan, Penn Herb, Herbs In A Bottle, MOUNTAIN ROSE HERBS, Falcon Russia, Carrubba, Organic Herb, Woodland Herbs, Panacea Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Agrimony Market Strategic Shifts
Digital traceability platforms and sustainable extraction technologies are converging to reshape how agrimony moves from field to pharmaceutical and nutraceutical finished products. These shifts are compressing supplier qualification timelines while opening premium market tiers for climate-verified supply chains.
Blockchain-enabled provenance tracking is converging with mobile soil-monitoring sensors to create immutable organic certification records. German and Polish buyers are adopting these systems fastest, requiring suppliers to upload real-time cultivation data. This technology convergence is compressing supplier audit cycles from months to weeks while raising barriers for non-compliant cultivators.
EMA's Committee on Herbal Medicinal Products is tightening monograph update frequencies for botanical therapeutics, forcing processors to maintain active pharmacovigilance databases. The industrial consequence is mandatory investment in post-market surveillance systems that track adverse event reporting. German pharmaceutical formulators face the steepest compliance burden, with several reformulating products to preempt monograph revision risks.
Direct contracting between processors and herbalist retailers is displacing traditional wholesale distribution layers in Poland and the Czech Republic. Independent apothecaries now source organic agrimony extracts through B2B platforms that bypass regional distributors. This channel disintermediation is most visible in Prague and Warsaw, where retail buyers prioritize traceability documentation over volume discounts.
Agrimony Market Segmentation
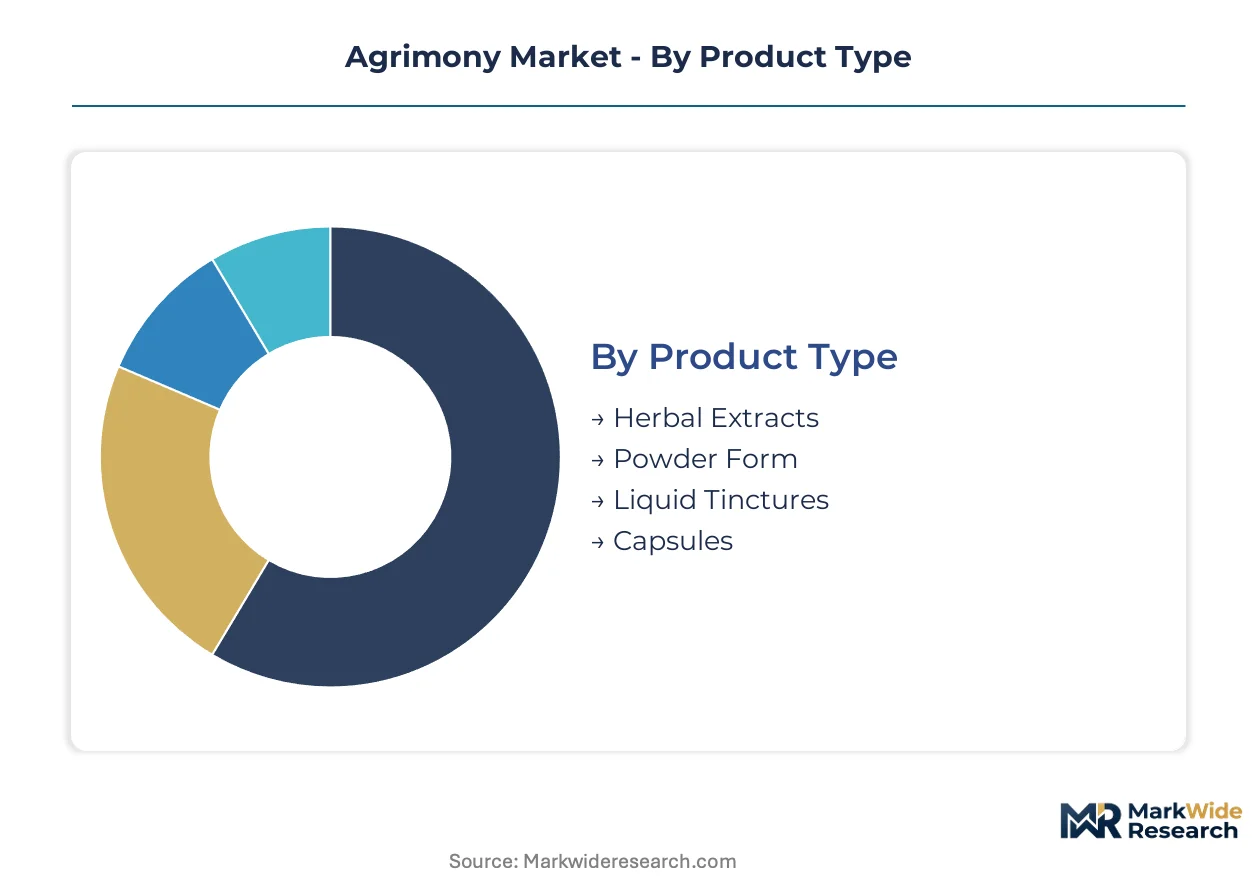
Agrimony procurement decisions hinge on certification grade and extraction method, with pharmaceutical buyers imposing stricter monograph compliance than nutraceutical or cosmetic channels. Segment boundaries blur where organic tinctures cross into functional food applications, forcing suppliers to maintain dual documentation systems.
Product Type:
EMA monograph compliance separates pharmaceutical-grade extracts from cosmetic-tier powders, while EU Organic Regulation traceability applies variably across aqueous versus ethanol-processed formats.
- Herbal Extracts:Concentrated tannin and flavonoid preparations standardized through aqueous or ethanol-based processes. German pharmaceutical formulators dominate procurement for digestive and wound-healing applications, with EMA batch record requirements compressing supplier qualification timelines.
- Liquid Tinctures:Alcohol-based or glycerite preparations preserving volatile oil integrity for premium wellness positioning. Polish and Czech herbalist retailers drive demand where organic certification commands price separation from conventional alternatives.
- Powder Form:Dried aerial parts milled for supplement blending and bulk ingredient procurement.
- Capsules:Standardized dosing formats for nutraceutical contract manufacturing and white-label distribution.
Leading the category by volume: Powder Form. Growing fastest: Herbal Extracts.
End Use Industry:
Application-specific purity standards create tiered entry barriers, with pharmaceutical manufacturing requiring active pharmacovigilance systems absent in food or cosmetic channels.
- Pharmaceuticals:EMA-governed therapeutic applications leveraging astringent and anti-inflammatory monograph properties. German manufacturers anchor demand for topical development programs, with REACH solvent standards shaping extraction equipment investment.
- Nutraceuticals:Functional food and supplement integration targeting digestive wellness formulations. Polish and Czech consumer loyalty to traditional herbal medicine sustains procurement volume for gut health positioning.
- Food & Beverages:Flavoring and functional ingredient applications in premium beverage and confectionery segments.
- Cosmetics:Topical astringent applications in natural skincare and personal care formulations.
Dominating procurement value: Pharmaceuticals. Expanding most quickly: Nutraceuticals.
Distribution Channel:
Channel selection determines documentation depth, with pharmacy and health store buyers demanding full organic traceability that supermarket and pure-play online retailers rarely require.
- Pharmacies:Regulated healthcare access points in Germany and Poland requiring EMA-compliant product registration. Full batch documentation and adverse event reporting systems differentiate qualified suppliers from general wellness distributors.
- Health Stores:Independent apothecaries and natural product retailers prioritizing traceability over volume discounts. Direct B2B platform procurement is displacing traditional wholesale layers in Prague and Warsaw corridors.
- Online Retail:Direct-to-consumer and marketplace distribution with variable certification transparency.
- Supermarkets:Mass-market placement for commoditized powder and capsule formats with limited organic penetration.
Highest margin capture: Health Stores. Steepest expansion trajectory: Online Retail.
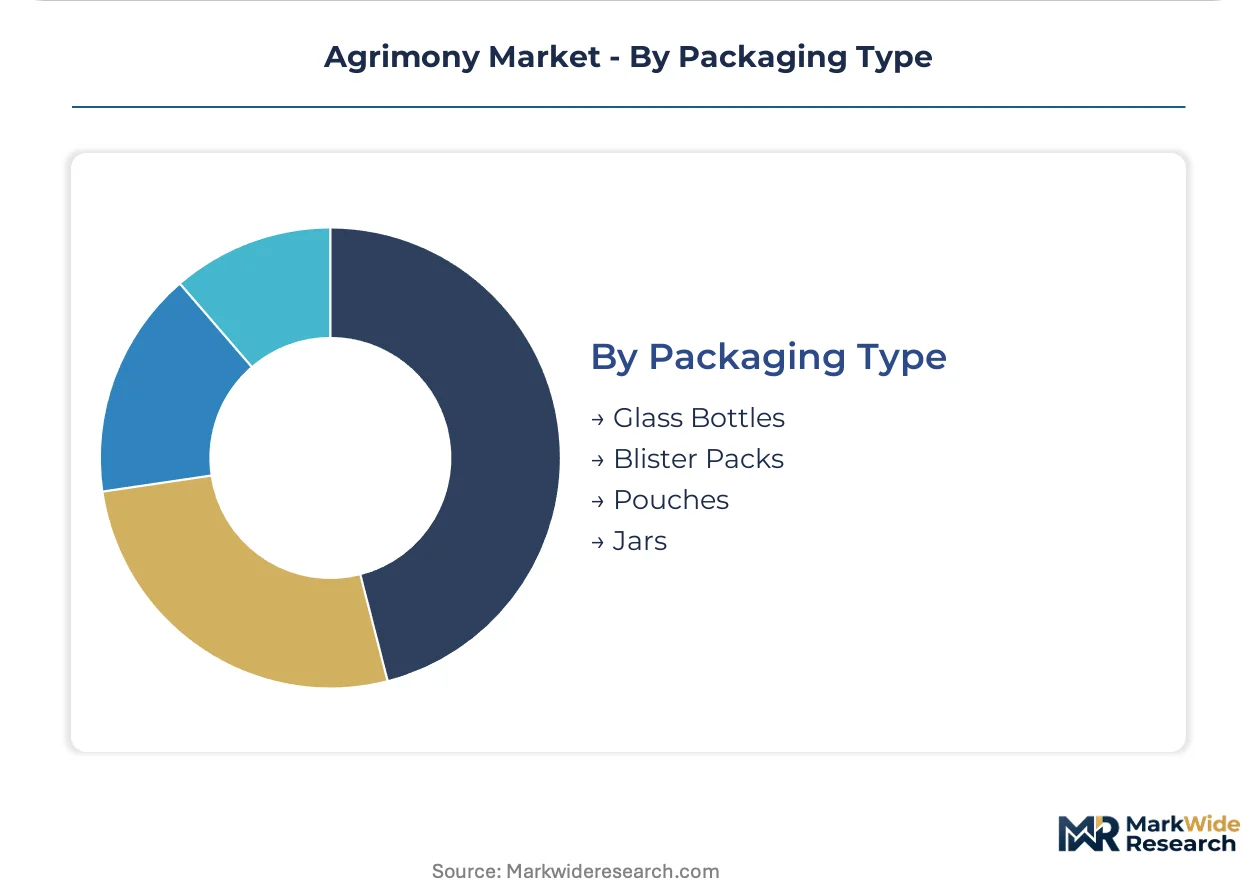
Packaging Type:
Packaging specifications align with channel preservation requirements and consumer premium perception, with glass and blister formats commanding unit economics that pouches and jars cannot sustain.
- Glass Bottles:Amber and cobalt containers protecting photosensitive tincture integrity for premium pharmacy and health store placement. German and Polish buyers specify pharmaceutical-grade closure systems preventing volatile oil degradation.
- Blister Packs:Unit-dose formats for pharmaceutical and travel-positioned nutraceutical applications. Child-resistant and senior-friendly designs segment compliance investment across regulatory jurisdictions.
- Pouches:Flexible formats for bulk powder and sample-sized distribution in online channels.
- Jars:Wide-mouth containers for cosmetic and food-grade powder access and dispensing convenience.
Premium positioning leader: Glass Bottles. Fastest volume scaling: Pouches.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Balkan growing regions anchor raw-material supply for European agrimony processors, though weather volatility is accelerating geographic diversification into Poland, the Czech Republic, and Pacific Northwest cultivation networks.
Germany
Pharmaceutical formulators in Bavaria and Baden-Württemberg drive certified organic procurement for digestive and wound-healing applications. EMA's Committee on Herbal Medicinal Products enforces batch record documentation that compresses supplier qualification timelines. The Stuttgart pharmaceutical corridor hosts processors upgrading to closed-loop ethanol recovery systems to meet REACH solvent emission standards.
Poland
Traditional herbal medicine loyalty sustains demand for liquid tinctures and organic extracts in Warsaw and Krakow retail channels. The EU Organic Regulation enforces traceability from field to finished product for all imported botanical ingredients. Independent apothecaries in the Mazovia region now source directly through B2B platforms, bypassing traditional wholesale distributors.
Czech Republic
Prague's herbalist corridor concentrates procurement of premium organic agrimony for gut health formulations and functional food integration. EMA monograph compliance requirements shape product registration for pharmacy-distributed therapeutics. Moravian growing cooperatives are investing in vacuum drying infrastructure to preserve volatile oil content for extract standardization.
Bulgaria
Balkan cultivation clusters face yield instability from drought and flooding cycles that expose processors to supply disruption. The EU Herbal Medicinal Products Directive tightens quality documentation requirements that strain smallholder digital traceability capabilities. Rose Valley cooperatives lack capital for organic certification soil testing and third-party audit fees required by German buyers.
United States
Pacific Northwest organic herb networks secure consistent supply for premium nutraceutical and cosmetic channels. USDA organic certification aligns with EU equivalency agreements for cross-Atlantic ingredient trade. Oregon and Washington cultivation operations leverage blockchain-enabled provenance tracking to compress audit cycles for European pharmaceutical formulators.
Agrimony Market Competitive Environment
Global majors compete with regional champions across certification tiers and distribution channel depth, creating a bifurcated structure where scale-driven processors face specialized organic suppliers. The vendor base clusters around three archetypes: Pacific Northwest organic sourcing networks, Eastern European volume wholesalers, and direct-to-retail herbalist channel specialists. Consolidation pressure is mounting as EMA documentation requirements favor processors with capital for pharmacovigilance databases and closed-loop extraction equipment. Competitive positioning hardens through backward integration into cultivation and direct B2B platform contracting that displaces traditional distribution layers.
Among North American organic specialists, MOUNTAIN ROSE HERBS exemplifies the certified sourcing network archetype, while Penn Herb anchors direct retail penetration in Philadelphia's herbalist corridor. Falcon Russia occupies the Eastern European wholesale tier, competing on volume despite logistical complexity across border regulations. These three patterns—organic certification depth, retail channel control, and regional volume positioning—define the competitive terrain as documentation requirements intensify.
| Leading Market Players |
|---|
| RJWhelan |
| Penn Herb |
| Herbs In A Bottle |
| MOUNTAIN ROSE HERBS |
| Falcon Russia |
| Carrubba |
| Organic Herb |
| Woodland Herbs |
| Panacea Health |
| Others |
Value Chain & Pricing Dynamics
Organic certification grade divergence separates pharmaceutical-grade agrimony extracts from commodity powder tiers, compressing procurement economics for Balkan smallholders while Pacific Northwest cultivators capture traceability premiums through blockchain-enabled batch documentation demanded by German formulators.
Pricing Analysis
Service-bundled documentation packages separate qualified suppliers from commodity sellers, with EMA-compliant batch records and adverse event reporting systems commanding 15-25% price separation over basic organic certificates. Price differentiation hinges on EU Organic Regulation traceability depth and closed-loop ethanol recovery yield consistency. Cost compression in Balkan-origin powder runs through weather-driven yield volatility and synthetic astringent substitution pressure from aluminum-based wound care compounds. Nutraceutical contract manufacturers exhibit highest price sensitivity, while German pharmaceutical formulators prioritize documentation completeness over unit cost.
Supply Chain Analysis
Raw agrimony supply rests on Bulgarian and Romanian growing clusters, with Polish and Czech cultivation expanding as weather hedges and Pacific Northwest organic networks serving premium nutraceutical channels. Dried aerial parts, extraction solvents, and vacuum-drying equipment feed processing economics. Single-source vulnerability concentrates in Balkan cooperatives lacking capital for organic certification infrastructure. Distribution runs through direct B2B platforms displacing traditional wholesale layers in Warsaw and Prague herbalist corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Agrimony processing is consolidating around EMA documentation capabilities, with pharmacovigilance database investments forcing smaller Balkan cooperatives toward acquisition or exit.
For Market Incumbents: Acquire vacuum-drying and closed-loop extraction assets in Moravian and Pacific Northwest hubs to secure volatile oil preservation capabilities. German pharmaceutical formulators anchor demand, but REACH solvent emission upgrades threaten margin structures for processors lacking ethanol recovery systems. Backward integration into Polish cultivation buffers Balkan weather exposure.
For New Entrants and Emerging Players: Begin with Polish independent apothecary channel penetration, where direct B2B platform procurement remains underdeveloped relative to Prague and Warsaw density. Carbon-negative supercritical CO2 extraction positioning opens climate-certified premium tiers that incumbent processors have not prioritized. White-label nutraceutical contract manufacturing offers revenue without consumer marketing infrastructure.
For Investors and Strategic Acquirers: Exit pathways concentrate in mid-cap processors with EMA-compliant documentation systems and established German pharmaceutical relationships. Five-to-ten year viability favors operators with captive organic supply and digital traceability platforms already deployed. Watch EMA monograph update frequency as inflection signal for reformulation-driven procurement surges.
| Strategic Initiative | Industry Significance |
|---|---|
| EMA Documentation Compliance Investment | Pharmacovigilance databases secure German pharmaceutical procurement and compress supplier qualification timelines. |
| Closed-Loop Ethanol Recovery Deployment | REACH solvent emission standards in Stuttgart pharmaceutical corridor mandate extraction equipment upgrades. |
| Blockchain Traceability Platform Integration | Immutable organic certification records compress audit cycles for Polish and Czech retail buyers. |
| Polish Apothecary Channel Direct Contracting | B2B platform procurement bypasses wholesale layers in Warsaw and Mazovia retail corridors. |
| Carbon-Negative Extraction Certification | Supercritical CO2 systems powered by renewable energy create climate-verified ingredient premiums. |
Study Parameters
Independent corroboration across EMA monograph databases, EU Organic Regulation certification records, and REACH solvent emission filings underwrites the qualitative findings. Primary interviews with pharmaceutical formulators, herbal extract processors, Polish apothecary buyers, and Balkan cooperative managers combined with secondary validation from customs trade data, herbal medicine regulatory filings, and organic certification agency disclosures. Bottom-up cultivation volume estimates and top-down pharmaceutical procurement value triangulation anchored segmentation outputs.
Rate-of-change decomposition across product type, end use industry, distribution channel, and certification grade dimensions shaped the analytical framework. CAGRs derived from weighted average growth contributions across German pharmaceutical demand, Polish nutraceutical expansion, and Pacific Northwest supply diversification. Modeled inputs included EMA monograph update schedules, EU Organic Regulation equivalency agreement status, and supercritical CO2 extraction capacity buildout trajectories.
Underlying measurement precision varies by segment; pharmaceutical-grade extracts with EMA batch documentation carry tighter precision than commodity powder tiers with fragmented Balkan sourcing. Forecasts reflect documented assumptions regarding regulatory compliance timelines and organic certification adoption rates. Weather-driven yield volatility, synthetic astringent substitution acceleration, and EMA monograph revision scope warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
GCC Compound Feed Market
Agriculture and Agri Products
Thailand Compound Feed Market
Agriculture and Agri Products
Coir Market
Agriculture and Agri Products
Africa Cashew Market
Agriculture and Agri Products
Saudi Arabia Alfalfa Market
Agriculture and Agri Products
United Kingdom Poultry Meat Market
Agriculture and Agri Products
Fish Feed Market
Agriculture and Agri Products
Argentina Compound Feed Market
Agriculture and Agri Products
Poultry Fat Market
Agriculture and Agri Products
Uruguay Agricultural Products Market
Agriculture and Agri Products
India Palm Oil Market
Agriculture and Agri Products
GCC Poultry Meat Market
Agriculture and Agri Products
Europe Poultry Feed Market
Agriculture and Agri Products
Global Warm Water Aquaculture Feed Market
Agriculture and Agri Products
Feed Protein Market
Agriculture and Agri Products
Flower and Ornamental Plants Market