
 Functional Apparel Market | 2026-2036
Functional Apparel Market Size, Share, and Industry Trends Forecast 2026-2036
Functional Apparel Market Analysis
Subscription-based performance analytics and software-defined fit customization is restructuring how functional apparel brands monetize customer relationships. Nike, Inc. leverages its digital ecosystem to sustain direct-to-consumer engagement beyond the initial garment sale. Under Armour, Inc. anchors its competitive position through biometric-integrated product development. Lululemon Athletica Inc. differentiates via community-driven membership models that extend lifetime value per user.
Functional apparel encompasses garments engineered with technical specifications such as moisture vapor transmission rates, four-way stretch recovery, and thermal resistance measured in clo units, designed to enhance human performance across athletic, occupational, and protective applications. The fabric type dimension shows moisture-wicking and breathable constructions commanding premium positioning, while anti-odor treatments face margin pressure from regulatory scrutiny on silver nanoparticle biocides. Product type segmentation reveals athleisure as the mature volume base and outdoor wear as the fastest-growing margin pool, driven by climate-adaptive layering systems and technical hiking demand.
The US EPA regulates per- and polyfluoroalkyl substance (PFAS) content in water-repellent textiles, while the EU REACH framework restricts hazardous chemical inputs across the supply chain, collectively elevating compliance costs for moisture management and durable water repellency finishes. China's GB standards and dual carbon goals impose additional material sourcing constraints on suppliers serving multiple regulatory jurisdictions. Stakeholders must monitor diverging chemical compliance regimes when selecting coating technologies and membrane suppliers for next-generation product lines.
Market Dynamics
Biometric sensor integration and software-defined fit systems are collapsing the traditional garment lifecycle, transforming one-time transactions into continuous data relationships that manufacturers monetize through subscription analytics and predictive replacement algorithms.
Growth Catalysts
- EU Green Deal compliance mandates:REACH chemical restrictions and carbon border adjustments are accelerating certified sustainable material adoption across European supply chains, forcing reformulation of water-repellent finishes and membrane chemistries.
- Military procurement programs:Defense agencies in the United States, United Kingdom, and Australia are expanding multi-year contracts for flame-resistant, moisture-managed combat uniforms with embedded physiological monitoring capabilities.
- China domestic consumption:Local sportswear brands are scaling technical manufacturing capacity to serve rising middle-class demand for performance-engineered daily wear, compressing import dependence.
Market Restraints
- PFAS regulatory friction:The US EPA's evolving restrictions on per- and polyfluoroalkyl substances in durable water repellency treatments are eliminating proven chemistries before viable fluorine-free alternatives achieve equivalent wash durability.
- Silver nanoparticle biocide constraints:Anti-odor treatments face margin compression as ECHA scrutiny of nanosilver toxicity forces expensive reformulation or removal from premium product lines.
- Membrane supply concentration:Expanded polytetrafluoroethylene and polyurethane laminate production clusters in Japan and Germany create geographic vulnerability for brands dependent on waterproof-breathable technologies.
Strategic Opportunities
- India technical textile expansion:PLI scheme incentives and BIS standardization are enabling domestic production of moisture-wicking knits previously imported from China, opening cost-competitive sourcing for mid-market brands.
- Occupational heat stress applications:Construction, agriculture, and logistics employers are adopting phase-change material cooling garments as OSHA heat illness prevention enforcement intensifies across sunbelt states.
- Circular material recovery systems:EU textile waste directives and extended producer responsibility frameworks are creating closed-loop feedstock opportunities for recycled polyester and nylon 6,6 engineered for performance retention.
Industry Challenges
- Cross-functional talent scarcity:Apparel brands struggle to hire textile chemists capable of navigating divergent PFAS regulations across US, EU, and Chinese jurisdictions while maintaining performance specifications.
- Certification timeline compression:OEKO-TEX and bluesign approval cycles for reformulated finishes lag product development schedules, delaying market entry for compliant seasonal collections.
- Legacy ERP integration:Size recommendation algorithms and 3D body scanning data streams require expensive middleware development to connect with established PLM and inventory management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Functional Apparel Market |
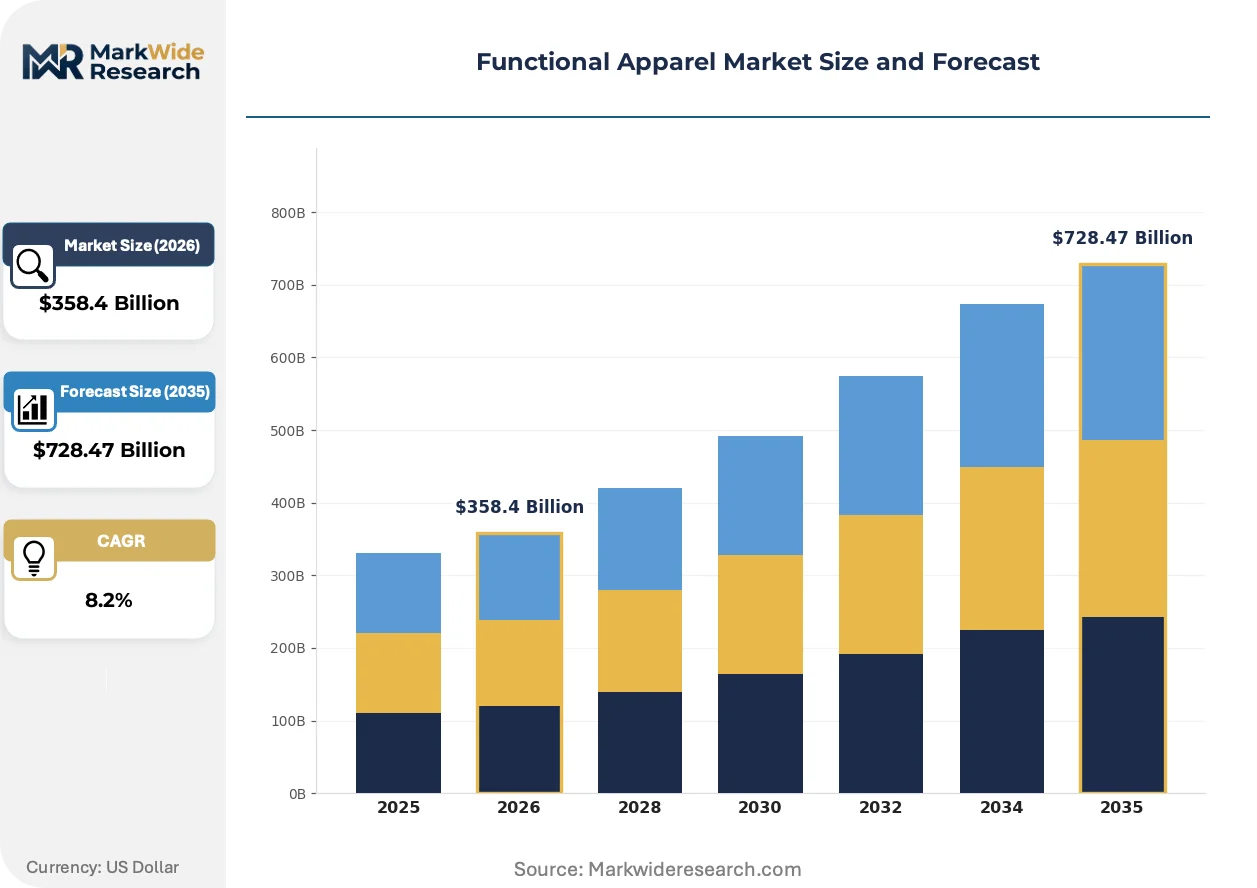
| Market Size in 2026 | $358.4 Billion |
| Market Size in 2035 | $728.47 Billion |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Activewear, Athleisure, Outdoor Wear, Workwear End User: Men, Women, Children, Seniors Fabric Type: Moisture-Wicking, Anti-Odor, UV-Resistant, Breathable Distribution Channel: Online Retail, Specialty Stores, Department Stores, Supermarkets |
| Companies Covered | Under Armour, Inc., PUMA SE, VF Corporation, ASICS Corporation, Lululemon Athletica Inc., Nike, Inc., adidas AG, Decathlon S.A., Columbia Sportswear Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Functional Apparel Market Emerging Trajectories
Digital fit infrastructure and biomaterial breakthroughs are dissolving boundaries between garment hardware, embedded software, and ongoing service relationships, redefining how technical apparel generates lifetime value.
Knitted sensor arrays woven directly into compression base layers are modularizing how physiological data collection deploys across athletic, clinical, and occupational monitoring applications. Professional sports franchises and corporate wellness programs are piloting these systems for real-time exertion tracking. This convergence is modularizing the traditional separation between wearable electronics and textile manufacturing, compressing supply chains that previously required discrete device assembly.
REACH authorization requirements for perfluorinated chemicals are forcing systematic replacement of C6 and C8 water-repellent treatments with hydrocarbon and silicone-based alternatives across European-sourced outerwear. The industrial consequence is accelerated R&D investment in dendrimer and hyperbranched polymer topologies that approximate fluorine performance without regulatory liability. Outdoor and protective segments are responding fastest, with leading membrane suppliers now offering dual-certified product lines that satisfy both EU chemical restrictions and US military durability specifications.
Direct-to-consumer subscription models for performance wear are displacing traditional retail replenishment cycles, with brands offering algorithmic size prediction and seasonal replacement scheduling. Specialty running and cycling retailers are losing attach-rate leverage as manufacturers capture recurring revenue through owned digital channels. This behavioral shift concentrates most visibly in North American and Western European urban markets where consumers prioritize convenience over tactile pre-purchase evaluation.
Functional Apparel Market Segmentation
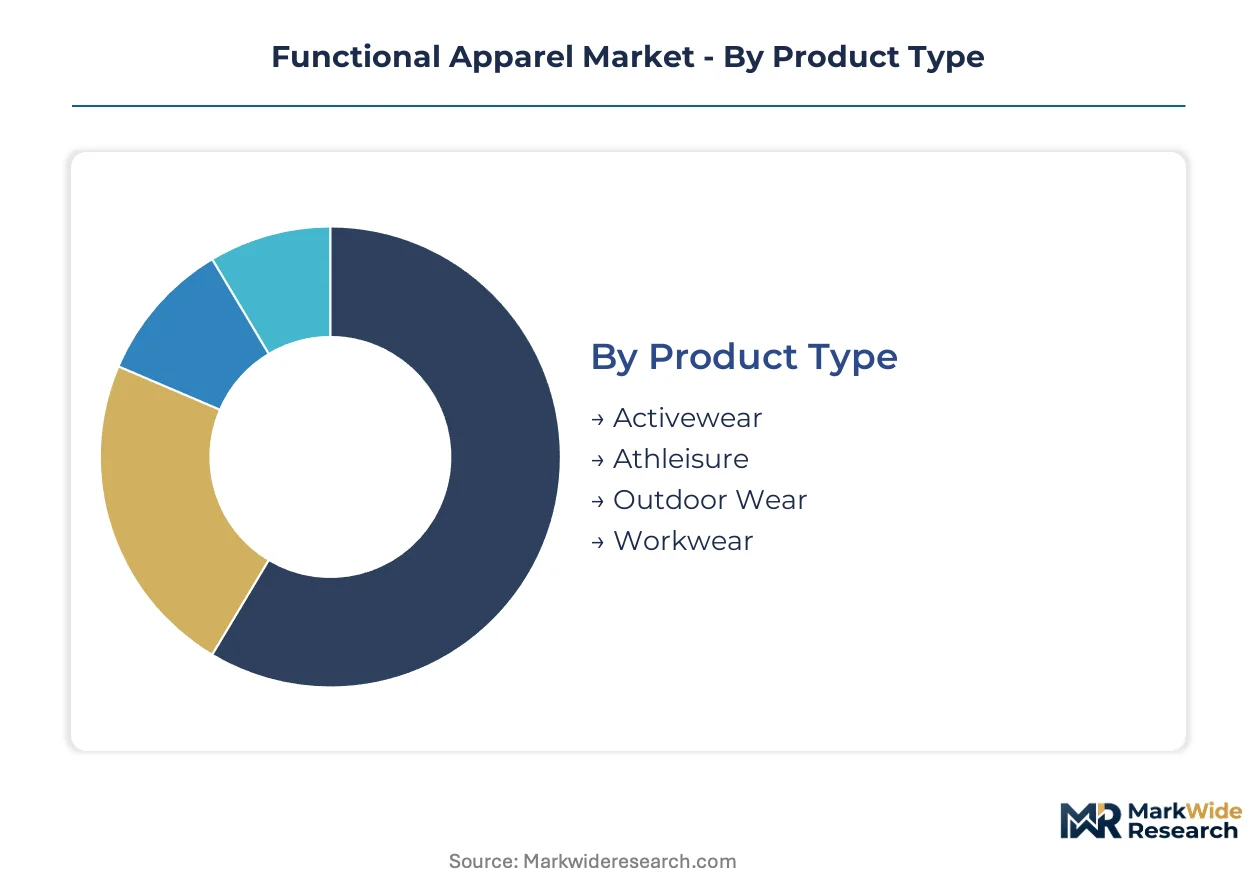
Segmentation in functional apparel determines which certification pathways manufacturers must navigate. Product specifications dictate whether OEKO-TEX, bluesign, or military-grade approvals become mandatory gatekeepers to market access.
Product Type:
Certification burden varies sharply across product types, with military and occupational segments requiring NFPA or EN ISO flame-resistance validation while consumer athletic lines face lighter OEKO-TEX screening.
- Activewear:Compression knits and four-way stretch constructions dominate professional athlete procurement. US military contracts for flame-resistant base layers are expanding volume through Defense Logistics Agency multi-year agreements.
- Athleisure:Technical specifications center on moisture vapor transmission rates and stretch recovery measured by ASTM D2594. Chinese domestic brands are scaling manufacturing capacity to serve middle-class demand for performance-engineered daily wear.
- Outdoor Wear:Climate-adaptive layering systems with measured clo thermal resistance values serve technical hiking demand. REACH authorization requirements for perfluorinated chemicals are forcing systematic replacement of C6 and C8 water-repellent treatments.
- Workwear:OSHA heat illness prevention enforcement is driving phase-change material cooling garment adoption across construction and logistics employers.
Athleisure sits at the top of the volume ranking, with outdoor wear climbing the fastest.
End User:
Customer lifetime value potential and replacement frequency create distinct margin profiles across demographic segments, with biometric-integrated lines commanding premium positioning in professional adult categories.
- Men:Professional sports franchises and corporate wellness programs are piloting knitted sensor arrays for real-time exertion tracking. Subscription-based performance analytics concentrate recurring revenue in this segment.
- Women:Community-driven membership models extend lifetime value through algorithmic size prediction and seasonal replacement scheduling. Direct-to-consumer channels are displacing specialty retailer attach-rate leverage.
- Children:Growth-accommodating fit systems and rapid size turnover create volume concentration. UV-resistant fabric treatments face simplified regulatory pathways compared to occupational wear.
- Seniors:Clinical monitoring applications leverage compression base layers with modular physiological data collection. Medicare reimbursement pathways are emerging for prescribed therapeutic garments.
Men's professional and military applications anchor revenue concentration, with women's subscription models gaining share fastest.
Fabric Type:
Material chemistry determines regulatory exposure, with silver nanoparticle biocides and PFAS-based water repellency facing divergent compliance timelines across US EPA, ECHA, and Chinese GB standard jurisdictions.
- Moisture-Wicking:Engineered polyester and nylon 6,6 constructions with specified moisture vapor transmission rates command premium positioning. India's PLI scheme incentives are enabling domestic production previously imported from China.
- Anti-Odor:Silver nanoparticle treatments face margin compression as ECHA scrutiny of nanosilver toxicity forces expensive reformulation. Hydrocarbon and silicone-based alternatives are displacing proven chemistries before fluorine-free options achieve equivalent wash durability.
- UV-Resistant:Titanium dioxide and zinc oxide embedded knits serve outdoor and children's segments with lighter certification burdens than occupational flame-resistance standards.
- Breathable:Expanded polytetrafluoroethylene and polyurethane laminate production clusters in Japan and Germany create geographic supply vulnerability for waterproof-breathable technologies.
Moisture-wicking constructions dominate unit volume, with anti-odor reformulations expanding most quickly as regulatory deadlines compress.
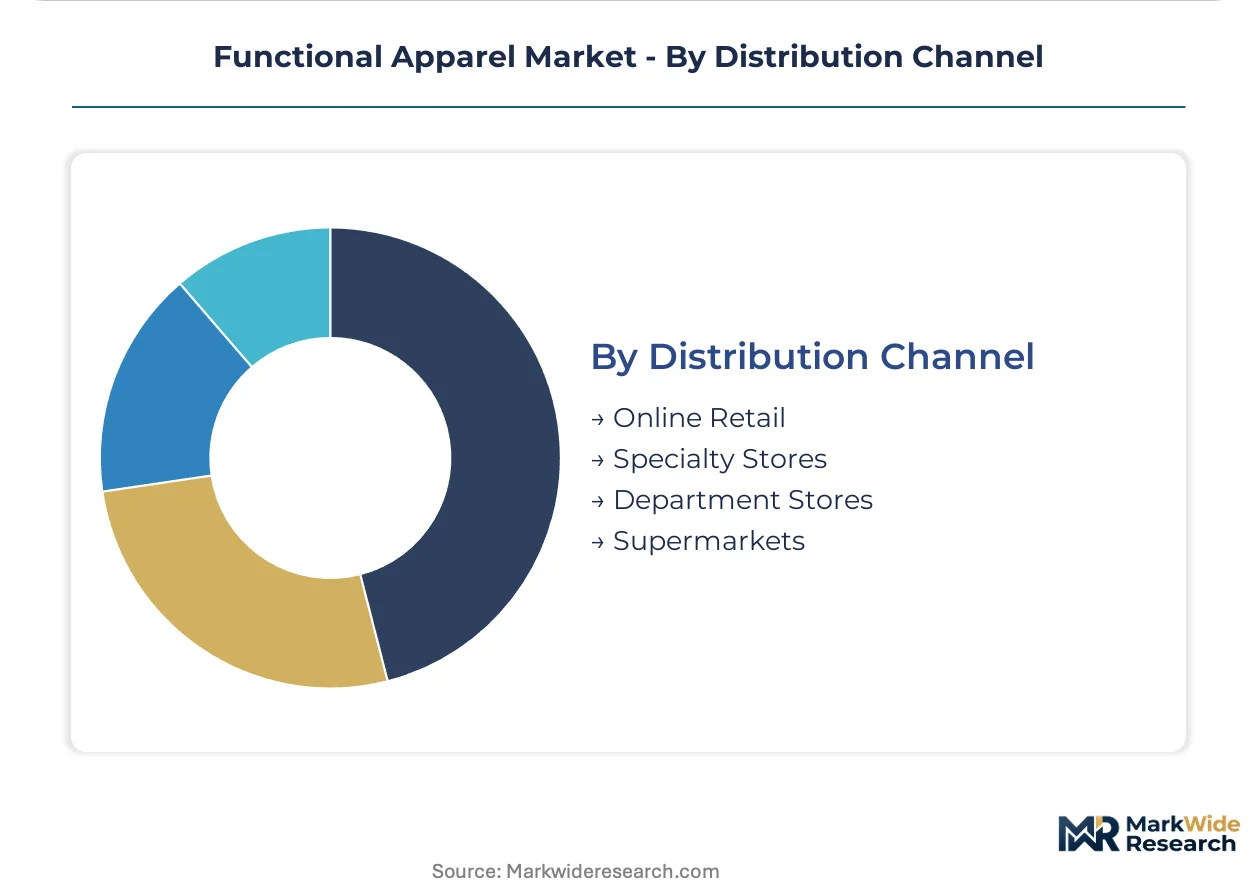
Distribution Channel:
Channel selection determines data capture depth and margin retention, with owned digital infrastructure enabling subscription monetization that third-party retail cannot replicate.
- Online Retail:Algorithmic size prediction and 3D body scanning data streams require expensive middleware development to connect with established PLM systems. Nike's digital ecosystem exemplifies direct-to-consumer engagement beyond initial garment sale.
- Specialty Stores:Running and cycling retailers are losing attach-rate leverage as manufacturers capture recurring revenue through owned channels. Tactile pre-purchase evaluation retains importance in technical outdoor categories.
- Department Stores:Mid-market volume concentration faces compression as athleisure brands bypass wholesale margins for direct distribution.
- Supermarkets:Entry-level moisture-wicking basics serve price-sensitive daily wear demand with minimal technical specification requirements.
Online retail commands the steepest expansion trajectory, while specialty stores retain defensive positioning in technical outdoor evaluation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's domestic sportswear consumption outpaces United States military procurement volumes, while European regulatory stringency reshapes material sourcing decisions across all three markets.
United States
Defense Logistics Agency multi-year contracts for flame-resistant combat uniforms with embedded physiological monitoring expand manufacturing demand. EPA restrictions on PFAS in durable water repellency treatments force systematic chemistry reformulation. Technical textile production concentrates in North Carolina's Research Triangle and Georgia's carpet belt region, where moisture-wicking knit capacity serves both military and athletic segments.
China
Domestic sportswear brands scale technical manufacturing to serve middle-class demand for performance-engineered daily wear, compressing import dependence. GB standards and dual carbon goals impose material sourcing constraints on suppliers serving multiple regulatory jurisdictions. Yangtze River Delta clusters around Shanghai and Suzhou dominate moisture-wicking polyester production, with local brands capturing share from Western imports.
Germany
REACH chemical restrictions and carbon border adjustments accelerate certified sustainable material adoption across European supply chains. ECHA scrutiny of nanosilver toxicity forces expensive anti-odor treatment reformulation. Bavaria's technical textile corridor and Baden-Württemberg's polymer research centers drive dendrimer-based water-repellent chemistry development for outdoor wear applications.
India
PLI scheme incentives and BIS standardization enable domestic production of moisture-wicking knits previously imported from China. Construction and logistics employers adopt phase-change material cooling garments as heat stress prevention intensifies. Tamil Nadu's Tiruppur knitwear cluster and Gujarat's synthetic fiber belt expand technical capacity for mid-market brand sourcing.
Japan
Expanded polytetrafluoroethylene membrane production serves waterproof-breathable demand for technical hiking and protective applications. METI standards guide performance specification benchmarking for regional brands. Osaka-Kobe industrial zone maintains concentration in polyurethane laminate manufacturing, though geographic vulnerability concerns prompt diversification discussions among downstream customers.
Functional Apparel Market Vendor Landscape
Top-tier vendors anchor premium positioning through biometric integration and direct-to-consumer digital ecosystems, while mid-tier specialists compete on technical specification compliance and regional manufacturing scale. Market structure shows consolidation around vertically integrated sportswear conglomerates alongside fragmentation among niche membrane suppliers and sensor-embedded garment developers. Three archetypes dominate: digital-native subscription platforms, military-contracting technical specialists, and mass-market athleisure scale players. Competitive moves center on strategic partnerships for sensor technology licensing and geographic expansion into India's technical textile corridor.
Within the digital ecosystem tier, Nike, Inc. and Lululemon Athletica Inc. exemplify subscription-based customer relationship models that extend lifetime value beyond initial garment transactions. Under Armour, Inc. occupies a position representing biometric-integrated product development archetypes, anchoring competitive positioning through physiological monitoring capabilities. These three entities collectively illustrate how functional apparel monetization is restructuring from hardware sales toward continuous data and service relationships.
| Leading Market Players |
|---|
| Under Armour, Inc. |
| PUMA SE |
| VF Corporation |
| ASICS Corporation |
| Lululemon Athletica Inc. |
| Nike, Inc. |
| adidas AG |
| Decathlon S.A. |
| Columbia Sportswear Company |
| Others |
Supply Flow & Price Mechanics
Certification-grade bifurcation between bluesign-approved premium lines and uncertified commodity basics manifests in both margin capture and supplier selection. Premium tiers command sustained pricing power through restricted chemical compliance, while commodity moisture-wicking knits face cost compression as Indian PLI-subsidized capacity enters the market.
Pricing Analysis
Capacity additions in India are reshaping price floors for standard-grade moisture-wicking polyester knits. Three-tier pricing structure across premium, standard, and economy levels separates military-specified flame-resistant base layers from athleisure basics. Cost compression in the standard tier intensifies because Yangtze River Delta producers absorb REACH compliance costs for European export orders. Corporate wellness programs show least price sensitivity for biometric-integrated subscriptions, while supermarket channel buyers drive hard bargaining on entry-level daily wear.
Supply Chain Analysis
Expanded polytetrafluoroethylene membrane supply rests on Japanese and German specialty chemical producers. Raw material dependencies include dendrimer-based water-repellent chemistries, silver nanoparticle biocide alternatives, and phase-change material cooling substrates. Single-source vulnerability concentrates in Osaka-Kobe polyurethane laminate manufacturing clusters. Distribution runs through vertically integrated brand-owned digital channels and remnant specialty retail for technical outdoor evaluation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story justified by procurement shift toward military-specified flame-resistant base layers with embedded physiological monitoring. Premium specification demand now anchors sustainable margin pools.
For Market Incumbents: Anchor competitive position through backward integration into certified sustainable material production. Incumbents must defend against digital-native subscription platforms by capturing biometric sensor array supply chains. Investment in bluesign-approved finishing capacity insulates against REACH authorization delays that disrupt seasonal collection launches. For New Entrants and Emerging Players: Direct-to-consumer algorithmic fit platforms offer the most penetrable white-space entry. New entrants should exploit OSHA heat stress enforcement tailwinds in sunbelt construction and logistics segments. Medicare reimbursement pathway development for senior therapeutic compression garments provides a specific go-to-market angle with lighter competitive density. For Investors and Strategic Acquirers: Consolidation pressure builds where membrane supply concentration creates geographic vulnerability for downstream brands. Long-term viability favors targets with dual-certified product lines satisfying EU chemical restrictions and US military durability specifications. Watch for ECHA nanosilver toxicity rulings as the inflection signal triggering anti-odor treatment reformulation costs.| Strategic Initiative | Industry Significance |
|---|---|
| Biometric Sensor Integration | Knitted sensor arrays transform garment hardware into continuous data service relationships. |
| REACH-Compliant Chemistry Reformulation | Dendrimer-based water-repellent development eliminates regulatory liability for European outerwear sales. |
| Direct-to-Consumer Digital Launch | Owned channels capture subscription revenue that specialty retailers previously extracted through attach rates. |
| India Technical Textile Capacity Expansion | PLI scheme incentives enable cost-competitive sourcing for mid-market moisture-wicking production. |
| Circular Material Recovery Partnership | EU textile waste directives create closed-loop feedstock for recycled polyester performance retention. |
Methodological Framework
Coverage spans the United States, China, Germany, India, and Japan, with primary inputs from each market. The approach combines interviews with textile chemists, military procurement officers, brand supply chain directors, and specialty retail buyers with secondary validation from EPA PFAS guidance documents, ECHA authorization lists, BIS standard notifications, and METI performance benchmarking reports. Bottom-up and top-down triangulation cross-checks manufacturing capacity estimates against import-export customs data.
Granularity-level modeling distinguishes moisture-wicking, anti-odor, UV-resistant, and breathable fabric types across activewear, athleisure, outdoor wear, and workwear product categories. End-user segmentation captures men, women, children, and seniors with distinct replacement frequencies and lifetime value profiles. CAGRs derive from trend extrapolation of military contract volumes, domestic consumption indices, and regulatory compliance cost absorption rates. Phase-change material cooling garment adoption curves and biometric sensor integration penetration serve as industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for fluorine-free durable water repellency would alter the outlook. Forecasts reflect assumptions about REACH authorization timelines, EPA PFAS restriction enforcement, and PLI scheme disbursement continuity. Regulatory reversal, membrane supply disruption, or certification timeline compression could revise projections. A small set of named triggers—ECHA nanosilver rulings, Defense Logistics Agency contract awards, and India BIS standard implementation—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel Textiles
Dye Sublimated Apparel Market
Apparel Textiles
Sweat Resistant Apparel Market
Apparel Textiles
Blank Apparel Market
Apparel Textiles
Women's Jerseys, Sweatshirts and Pullovers Market
Apparel Textiles
Down Jacket Market
Apparel Textiles
China Flame Retardant Apparel Market
Apparel Textiles
North America Insect Repellent Apparel Market
Apparel Textiles
Rain Apparel Market
Apparel Textiles
Rolle Market
Apparel Textiles
Thailand Garment Industry Market
Apparel Textiles
Asia-Pacific Textile Garment Market
Apparel Textiles
Denim Market
Apparel Textiles
Middle East and Africa Textile Garment Market
Apparel Textiles
Africa Textile Market
Apparel Textiles
Hosiery Market
Apparel Textiles
Global Maternity Innerwear Market