
 Africa Textile Market | 2026-2036
Africa Textile Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Textile Market Outlook
The capital-intensity divergence between integrated spinners and fragmented weavers is bifurcating competitive outcomes across the continent. Egyptian Cotton Egypt leverages its control over long-staple giza cultivation to sustain premium positioning in upstream segments. Vlisco Group dominates wax-print distribution through deep channel control in West African consumer markets. Korteks Textiles Africa anchors its operations around synthetic fiber conversion for industrial buyers.
Textiles encompass woven, knitted, and non-woven structures engineered from natural or synthetic filaments with defined yarn counts, tensile strengths, and finish specifications for end-use performance. Cotton retains volume leadership across African production due to favorable agro-climatic zones and established ginning infrastructure, though synthetic fibers represent the fastest-expanding product type as polyester-cotton blends gain traction in mass apparel. Home furnishing applications command higher margin pools than commodity apparel because of smaller batch sizes and specialized finishing requirements.
Egypt's Ministry of Trade and Industry enforces export-quality standards through the General Organization for Export and Import Control, while South Africa's National Regulator for Compulsory Specifications governs textile labeling and safety for domestic retail. The African Continental Free Trade Area rules of origin are forcing manufacturers to restructure supply chains toward regional fiber sourcing to qualify for tariff exemptions. Stakeholders must monitor how AfCFTA implementation affects input-cost structures relative to Asian import competition.
Market Dynamics
The African Continental Free Trade Area is forcing manufacturers to restructure supply chains toward regional fiber sourcing to qualify for tariff exemptions, compressing lead times and rewiring procurement patterns across the continent.
Growth Catalysts
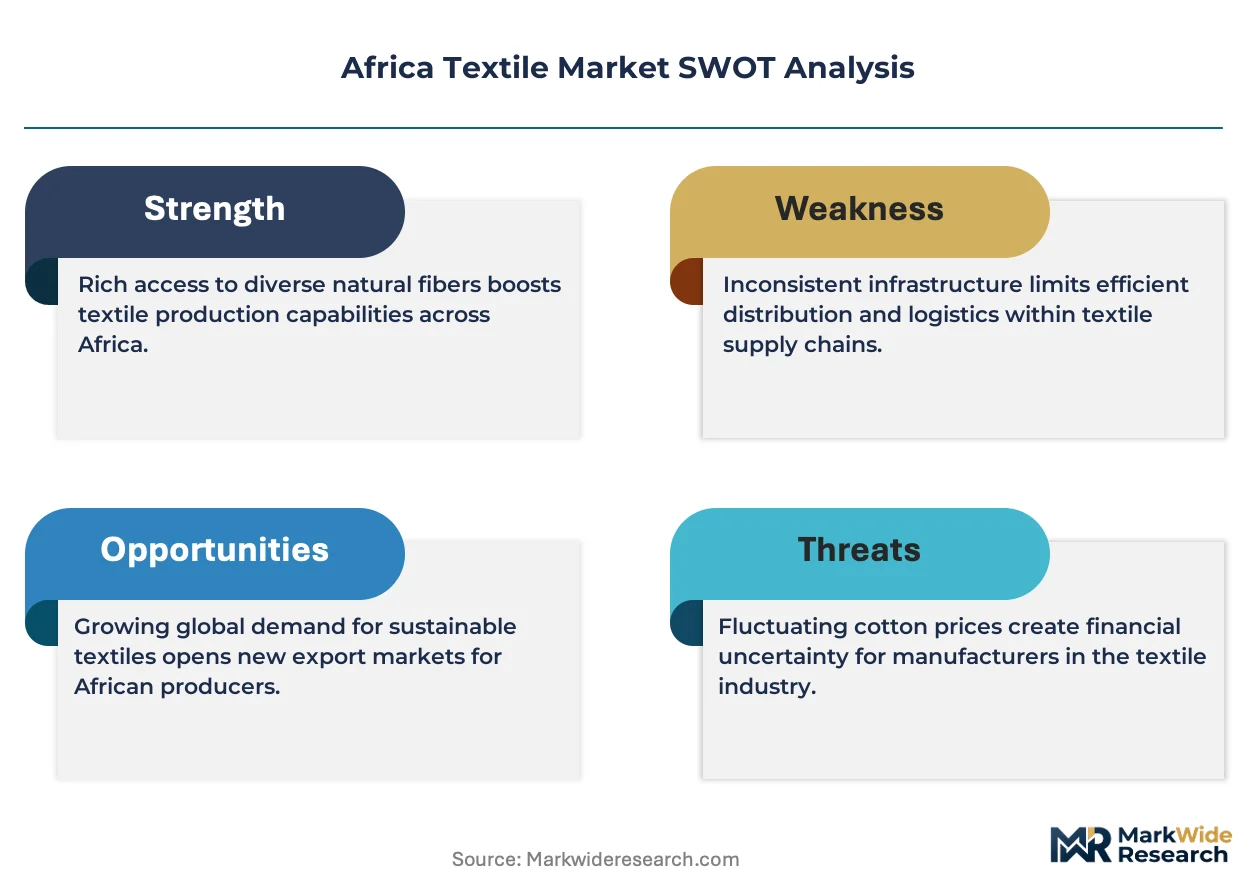
- AfCFTA Rules of Origin:Tariff exemptions on intra-African trade are pulling Egyptian spinners and Ethiopian weavers into cross-border supply arrangements that bypass Asian import dependencies.
- Synthetic Fiber Conversion:Polyester-cotton blends are displacing pure cotton in mass apparel as industrial buyers in South Africa and Nigeria seek cost-performance optimization.
- Nile Delta Cluster Expansion:Egypt's integrated textile corridor is deepening backward integration into long-staple cultivation, capturing margin pools previously exported to European finishers.
Market Restraints
- Cotton Input Volatility:Rainfall dependency across Sahel growing zones and currency mismatches in francophone West African procurement expose spinners to raw material cost swings.
- Asian Import Competition:Chinese and Vietnamese finished apparel floods North and West African retail channels, compressing domestic manufacturer pricing power.
- Power Infrastructure Deficits:Unreliable grid supply in Nigerian and Kenyan industrial zones forces captive diesel generation, elevating unit costs versus Asian competitors.
Strategic Opportunities
- Ethiopian Industrial Parks:Underpenetrated apparel manufacturing capacity in Hawassa and Adama offers tariff-advantaged export platforms to US and EU markets under AGOA and Everything But Arms.
- Technical Textiles:Geotextile and automotive interior applications remain nascent, creating white space for synthetic converters serving infrastructure and mobility sectors.
- Digital Printing Convergence:Direct-to-garment inkjet systems merging with ERP-enabled micro-batch production allow West African distributors to collapse design-to-shelf cycles.
Industry Challenges
- Skilled Technician Scarcity:Dyehouse chemists and loom maintenance engineers are concentrated in Egypt and South Africa, creating recruitment bottlenecks for expanding Ghanaian and Rwandan operations.
- AfCFTA Compliance Complexity:Certificate of origin documentation and rules-of-origin verification timelines delay shipment clearances at Lagos, Mombasa, and Durban ports.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Textile Market |
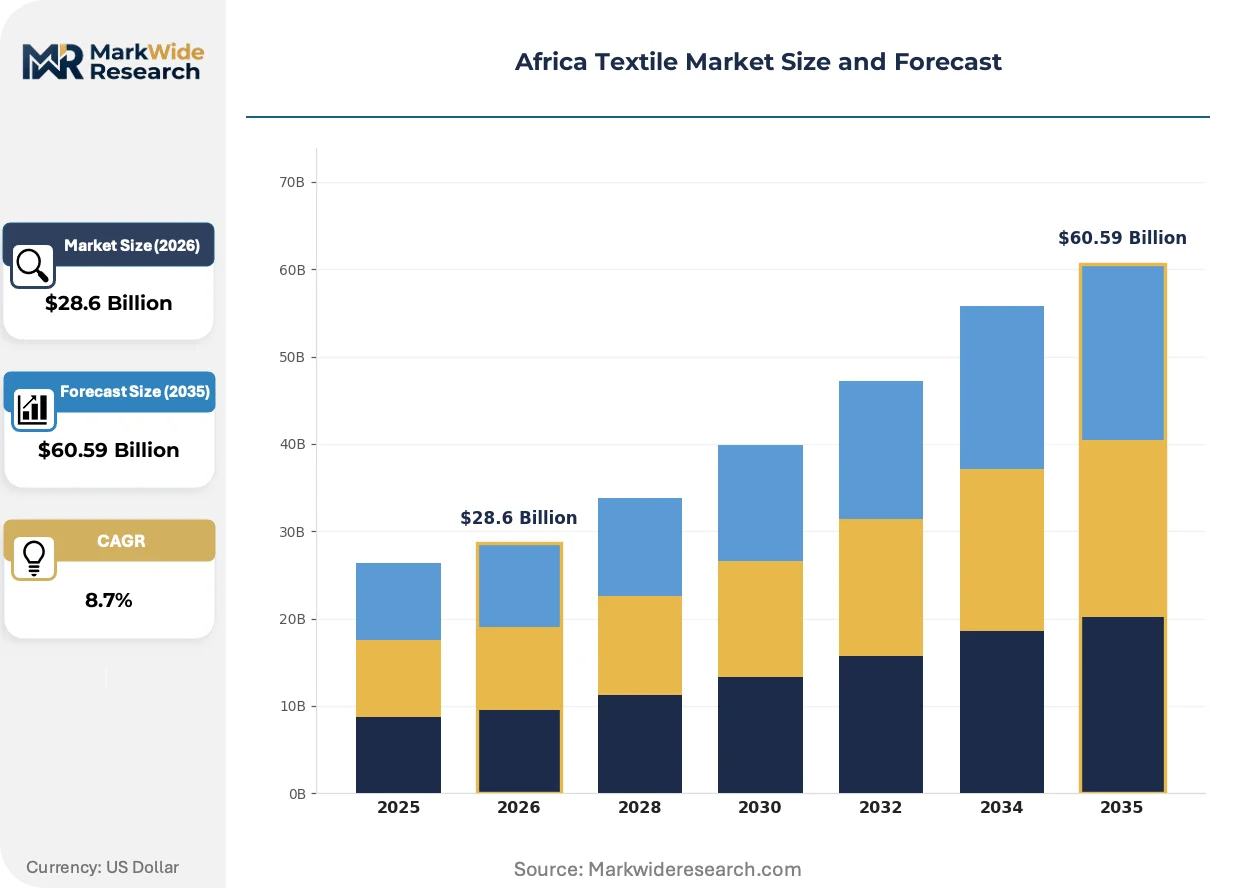
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $60.59 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cotton, Wool, Silk, Synthetic Fibers Application: Apparel, Home Furnishing, Industrial Textiles, Automotive Textiles Distribution Channel: Online Retail, Offline Retail, Wholesale, Direct Sales End User: Textile Manufacturers, Fashion Designers, Retailers, Exporters |
| Companies Covered | Nouvelle Fibre Textile SA, Egyptian Cotton Egypt, Korteks Textiles Africa, Vlisco Group, KAMAL Yarns (Pty) Ltd, CIEL Textile Ltd, Akosombo Textiles Ltd, Rivatex East Africa Ltd, Mediterranean Textile Company SAE, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Textile Market Strategic Shifts
Digital production systems and policy-driven supply chain regionalization are compressing traditional batch economics and rewiring competitive advantage toward speed-to-market capabilities.
Digital textile printing is miniaturizing minimum order quantities from thousands to dozens of units. Small-scale apparel distributors in Lagos and Accra are adopting direct-to-fabric inkjet systems to serve fast-fashion micro-seasons. This compression is fragmenting demand away from centralized volume producers toward agile, design-integrated converters.
Egypt's General Organization for Export and Import Control is tightening export-quality certification requirements for cotton yarn and finished textiles. Domestic spinners are upgrading laboratory testing capacity to meet GOEIC standards, while non-compliant informal operators face exclusion from official export channels. The premium apparel segment is absorbing compliance costs fastest.
Brand procurement departments are unbundling design, manufacturing, and logistics functions previously locked under single-source contracts. East African apparel exporters are capturing disaggregated manufacturing blocks from European retailers, while West African distributors absorb regional logistics consolidation. Kenya and Madagascar are seeing the most visible contract fragmentation.
Africa Textile Market Segmentation
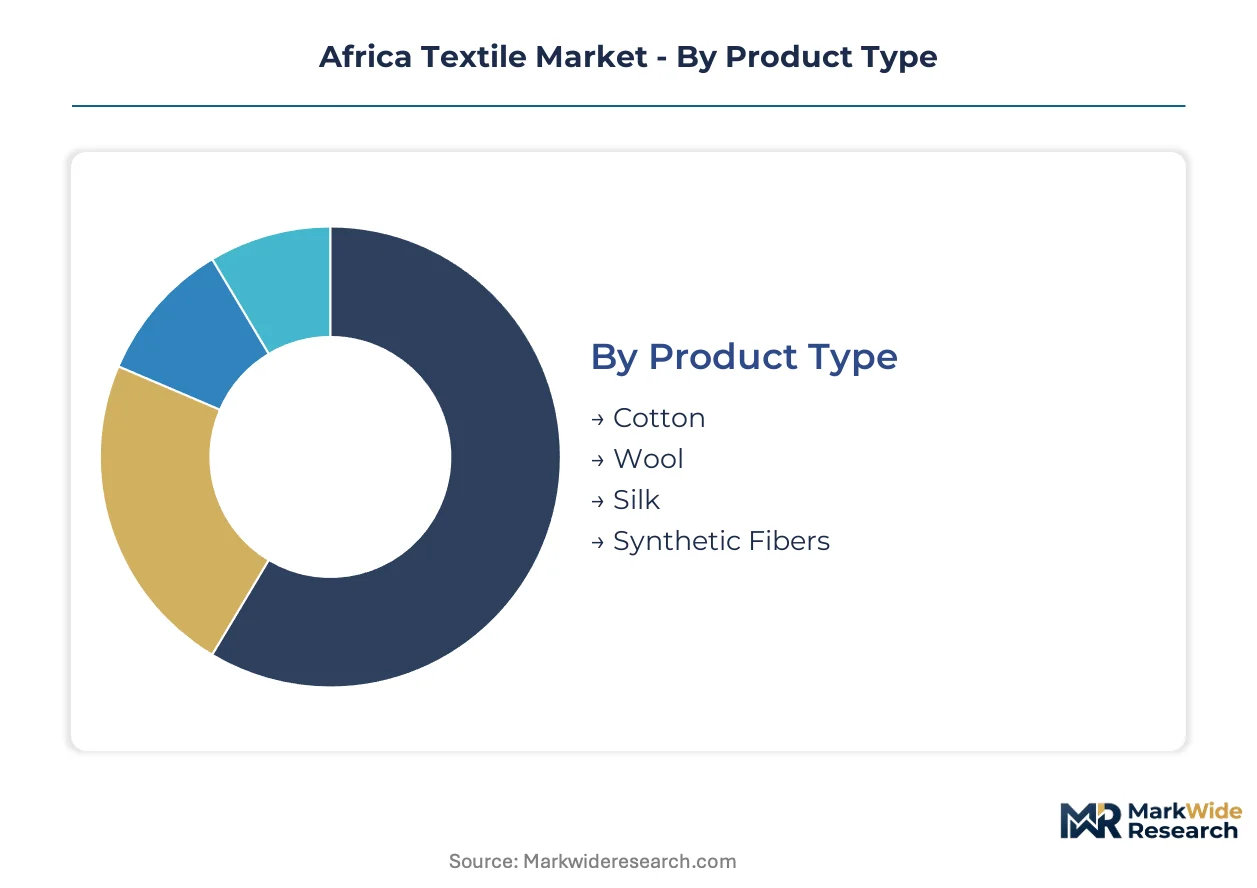
Segmentation in the Africa textile market reveals how fiber substitution pressures, channel fragmentation, and end-user consolidation are reshaping procurement hierarchies. Each dimension exposes distinct margin pools and competitive vulnerabilities across Egypt's integrated spinners and West Africa's distributed weavers.
Product Type:
Synthetic fibers face the most intense substitution pressure from cotton in premium apparel, while cotton confronts cost-driven displacement by polyester blends in mass-market segments.
- Cotton:Long-staple varieties from Egypt's Nile Delta command premium positioning in upstream yarn markets. Egyptian Cotton Egypt controls giza cultivation, supplying European finishers and domestic spinners with fiber meeting GOEIC export-quality standards.
- Synthetic Fibers:Polyester-cotton blends are displacing pure cotton in South African and Nigerian mass apparel as industrial buyers optimize cost-performance ratios. Korteks Textiles Africa anchors synthetic conversion capacity for regional industrial buyers seeking consistent dye uptake and tensile uniformity.
- Wool:Merino and crossbred grades serve South Africa's domestic knitwear manufacturers and limited export channels to European cold-climate markets.
- Silk:Cultivation remains negligible across the continent; import dependency confines usage to high-end fashion designers in Lagos and Nairobi.
Cotton retains volume leadership; synthetic fibers hold the steepest expansion curve.
Application:
Cost tier stratification separates commodity apparel from specialized finishing applications, with margin concentration shifting toward smaller-batch technical segments.
- Apparel:Mass-market garment production dominates employment and fiber consumption across Ethiopian industrial parks and Egyptian cut-make-trim facilities. AGOA and Everything But Arms tariff advantages pull Hawassa and Adama capacity toward US and EU export markets.
- Home Furnishing:Curtains, upholstery, and bedding command higher margin pools than commodity apparel due to specialized finishing requirements and smaller production runs. Egyptian weavers capture premium positioning through jacquard and damask capabilities.
- Industrial Textiles:Geotextile applications for infrastructure projects remain underpenetrated, creating white space for synthetic converters serving road construction and erosion control in Kenya and Nigeria.
- Automotive Textiles:Seat fabric and interior panel applications are nascent, with South African assemblers importing most requirements from Asian tier-one suppliers.
Apparel absorbs the largest fiber volumes; home furnishing commands the highest unit margins.
Distribution Channel:
Customer type fragmentation is splitting procurement between consolidated wholesale buyers and fragmented direct-to-consumer platforms, rewiring inventory risk allocation.
- Wholesale:Volume aggregation through Lagos, Accra, and Durban trading hubs supplies informal retail networks across West and Southern Africa. Vlisco Group's wax-print distribution leverages deep channel control in these wholesale corridors.
- Offline Retail:Formal apparel stores and open-air markets remain the dominant transaction venue for mass-market consumers, though foot traffic is fragmenting toward digital discovery.
- Direct Sales:Large South African industrial buyers contract directly with Egyptian spinners and Ethiopian garment exporters, bypassing distributor markups for volume commitments.
- Online Retail:Direct-to-garment inkjet systems and ERP-enabled micro-batch production allow Lagos and Accra distributors to collapse design-to-shelf cycles for fast-fashion micro-seasons.
Wholesale retains transaction volume leadership; online retail is climbing the fastest as digital printing converges with micro-batch economics.
End User:
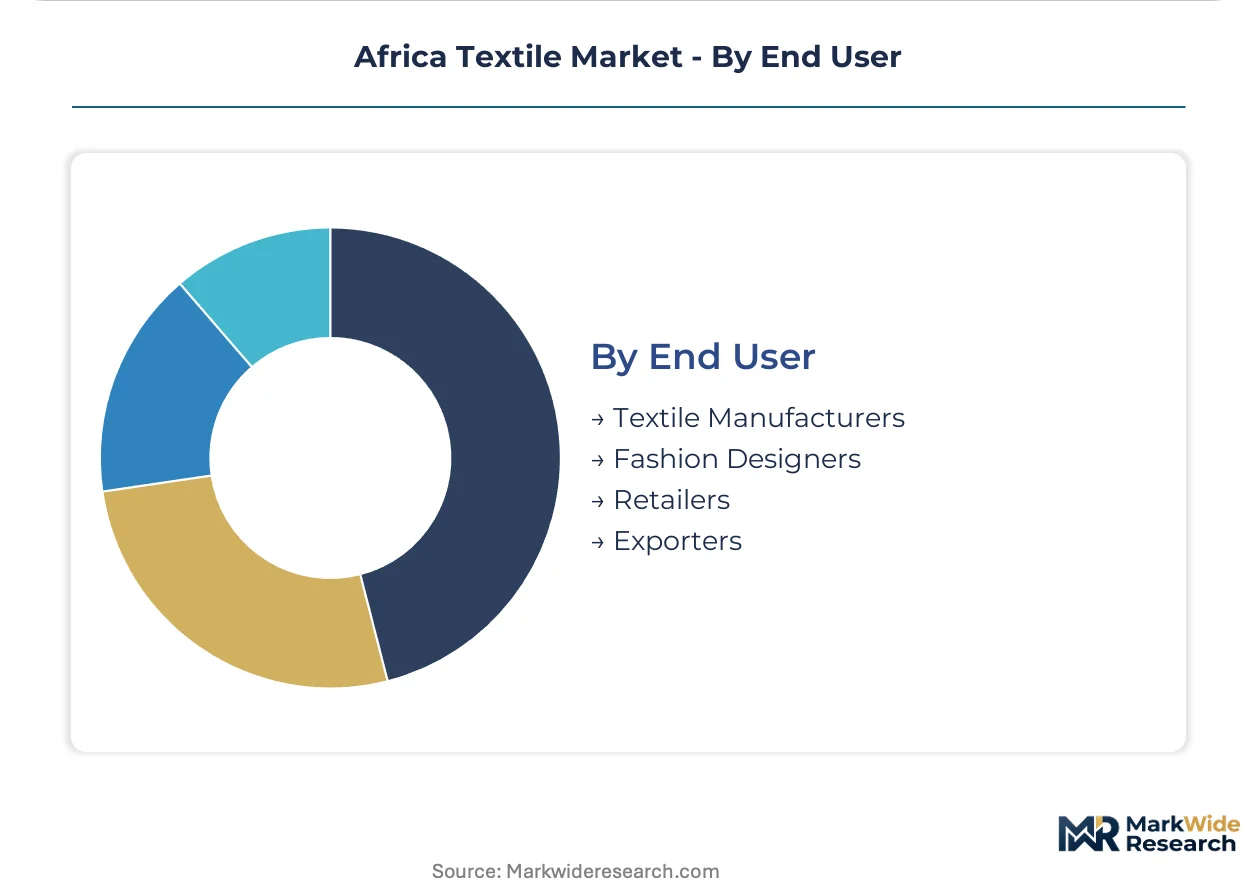
Supply concentration among integrated textile manufacturers is squeezing independent fashion designers and fragmented retailers on input pricing and minimum order quantities.
- Textile Manufacturers:Integrated spinners and weavers in Egypt's Nile Delta cluster control upstream yarn and fabric supply, dictating terms to downstream converters. Backward integration into long-staple cultivation captures margin pools previously exported to European finishers.
- Retailers:Formal apparel chains and informal market traders absorb finished goods through wholesale and direct import channels, facing compressed pricing power from Chinese and Vietnamese finished apparel competition.
- Fashion Designers:Small-scale creators in Lagos and Nairobi source limited quantities through digital printing converters and import agents, paying premium unit costs for design differentiation.
- Exporters:Ethiopian and Kenyan garment exporters serve as manufacturing blocks for European retailers unbundling design, production, and logistics functions previously locked under single-source contracts.
Textile manufacturers retain upstream control; exporters are gaining share fastest as contract fragmentation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances across African textile corridors are driving capital relocation toward integrated production zones. Nations with captive fiber supply and preferential trade access capture disproportionate manufacturing investment.
Egypt
Long-staple cotton cultivation in the Nile Delta underpins upstream yarn exports to European finishers. The General Organization for Export and Import Control enforces quality certification that informal operators struggle to meet. Alexandria and Damietta industrial zones deepen backward integration into ginning and spinning capacity.
Ethiopia
Hawassa and Adama industrial parks attract apparel manufacturing contracts under AGOA and Everything But Arms tariff preferences. The Ethiopian Investment Commission coordinates land and utility allocation for export-oriented garment exporters. Cut-make-trim facilities cluster around these parks, serving disaggregated European retail procurement blocks.
South Africa
Synthetic fiber conversion for automotive and industrial applications concentrates in KwaZulu-Natal and Eastern Cape manufacturing corridors. The National Regulator for Compulsory Specifications governs textile labeling and safety standards for domestic retail. Durban trading hubs supply wholesale distribution networks across Southern Africa.
Nigeria
Lagos and Kano absorb Chinese and Vietnamese finished apparel imports that compress domestic manufacturer pricing power. The country's national trade regulator administers import documentation that delays clearance at Apapa and Tin Can Island ports. Captive diesel generation in industrial zones elevates unit costs versus Asian competitors.
Kenya
Apparel exporters in Nairobi and Mombasa serve as manufacturing blocks for European retailers unbundling design and production functions. The Export Processing Zones Authority administers tariff-advantaged status for garment exporters under AGOA. Geotextile applications for infrastructure projects remain underpenetrated, creating white space for synthetic converters.
Africa Textile Market Competitive Environment
Concentration sits with integrated spinners controlling upstream fiber supply and fragmented weavers serving regional wholesale channels. Egyptian and Turkish-backed operators dominate long-staple yarn and synthetic conversion respectively. Three archetypes define competitive positioning: captive cultivation specialists, synthetic fiber converters, and wax-print distributors with deep channel control. Capacity expansion and strategic partnerships represent the dominant competitive moves as players respond to AfCFTA rules-of-origin requirements.
Among cultivation-anchored operators, Egyptian Cotton Egypt exemplifies upstream control over premium fiber supply. Vlisco Group occupies a position within the wax-print distribution archetype, leveraging channel depth across West African consumer markets. Korteks Textiles Africa sits within the synthetic conversion tier, serving industrial buyers seeking consistent dye uptake and tensile uniformity.
| Leading Market Players |
|---|
| Nouvelle Fibre Textile SA |
| Egyptian Cotton Egypt |
| Korteks Textiles Africa |
| Vlisco Group |
| KAMAL Yarns (Pty) Ltd |
| CIEL Textile Ltd |
| Akosombo Textiles Ltd |
| Rivatex East Africa Ltd |
| Mediterranean Textile Company SAE |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts between Egyptian spinners and European finishers lock in both supply access and price visibility across the Nile Delta cluster, insulating premium yarn producers from cotton input volatility while compressing margin flexibility for weavers locked into spot procurement.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in African textile markets. Price differentiation rests on GOEIC certification grade and volume scale, with certified Egyptian long-staple yarn commanding premiums over informal West African alternatives. Cost compression in mass-market polyester blends is intensifying because Chinese import competition floods Nigerian and Kenyan retail channels. Informal apparel traders show highest price sensitivity; European finishers buying certified Nile Delta yarn exhibit lowest.
Supply Chain Analysis
Container availability constraints on Asia-Africa trade lanes elevate inbound logistics costs for synthetic fiber imports serving South African industrial buyers. Supply concentrates in Egypt's Nile Delta, Ethiopia's Hawassa-Adama corridor, and South Africa's KwaZulu-Natal manufacturing zones. Raw material flows draw from Sahel cotton cultivation, Asian polyester filament, and Egyptian long-staple giza. Single-source vulnerability sits with dyehouse chemical imports. Distribution runs through Lagos, Accra, and Durban wholesale hubs supplying informal retail networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The scarcity of trained dyehouse chemists and loom maintenance engineers concentrates technical capability in Egypt and South Africa, leaving expanding Ghanaian and Rwandan operations dependent on expatriate recruitment or knowledge transfer partnerships.
For Market Incumbents: Fortify upstream control through backward integration into long-staple cultivation and laboratory testing capacity upgrades to meet tightening GOEIC standards. Channel control investments in West African wax-print distribution defend against digital printing converters collapsing design-to-shelf cycles for fast-fashion micro-seasons. For New Entrants and Emerging Players: Lead with technical textiles specialization targeting geotextile applications for Kenyan and Nigerian infrastructure projects, a segment where Asian tier-one suppliers currently dominate but local synthetic converters can establish presence. Direct-to-garment inkjet systems paired with ERP-enabled micro-batch production offer the most penetrable go-to-market angle for Lagos and Accra distributors serving fragmented fast-fashion demand. For Investors and Strategic Acquirers: The market sits at a regionalization phase that favors integrated cultivation-anchored operators with AfCFTA-compliant supply chains. Long-term viability across the projection horizon hinges on tariff-advantaged positioning under AGOA and Everything But Arms. Acquisition target archetype: mid-scale Ethiopian garment exporters with established European retail relationships. Watch for AfCFTA rules-of-origin verification timeline compression at Lagos, Mombasa, and Durban ports as inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Long-Staple Cultivation | Egyptian spinners capture margin pools previously exported to European finishers through captive giza supply. |
| Digital Printing System Deployment | Lagos and Accra distributors collapse design-to-shelf cycles for fast-fashion micro-seasons using direct-to-garment inkjet. |
| AfCFTA-Compliant Supply Chain Restructuring | Ethiopian weavers bypass Asian import dependencies through cross-border arrangements with Egyptian spinners. |
| Technical Textiles Capacity Addition | Synthetic converters serve underpenetrated geotextile demand for Kenyan road construction and erosion control. |
| Laboratory Testing Certification Investment | Domestic spinners upgrade capacity to meet GOEIC export-quality standards excluding informal operators. |
Study Parameters
Operator-level perspectives from spinning mill managers, dyehouse chemists, garment export facility directors, wholesale trading hub operators, and AfCFTA compliance officers anchored the qualitative base. Primary fieldwork combined with secondary validation from customs and trade data, national regulator filings, industrial park development records, and preferential trade agreement documentation. Bottom-up fiber consumption estimates and top-down macroeconomic indicators underwent triangulation to reconcile volume outputs.
Sensitivity analysis tested forecast robustness across alternative scenarios for AfCFTA implementation pace, AGOA renewal conditions, and synthetic-cotton substitution elasticity. The analytical framework modeled segmentation dimensions including fiber type, application end-use, distribution channel, and regional production cluster across the projection horizon. CAGRs derived from trend extrapolation adjusted for identified inflection factors. Industry-specific inputs incorporated cotton cultivation yield variability, industrial park capacity utilization rates, and port clearance efficiency metrics.
The analysis sits within stated boundaries; outcomes outside sustained AfCFTA tariff exemption enforcement, AGOA preference continuity, and power infrastructure stabilization would require recalibration. Forecasts reflect documented assumptions regarding trade policy trajectory and input cost structures. Cotton rainfall dependency, currency mismatch exposure, and Asian import competition intensity constitute specific risk factors that could revise projections. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel Textiles
Maternity Leggings Market
Apparel Textiles
Waterproof Fabrics for Sports Apparel Market
Apparel Textiles
Organic Baby Clothes Market
Apparel Textiles
Uniform Market
Apparel Textiles
Hunting Apparel Market
Apparel Textiles
Embroidery Market
Apparel Textiles
Clothing Manufacturing Service Market
Apparel Textiles
Global Textile Garment Market
Apparel Textiles
Global Western Wear Market
Apparel Textiles
Thailand Garment Industry Market
Apparel Textiles
Automotive Textiles Market
Apparel Textiles
Women's Cheongsam Market
Apparel Textiles
Middle East and Africa Footwear Sole Material Market
Apparel Textiles
Equestrian Apparel Market
Apparel Textiles
Rain Apparel Market
Apparel Textiles
Maternity Wear Market