
 Motorcycle ADAS Market | 2026-2036
Motorcycle ADAS Market Size, Share, and Industry Trends Forecast 2026-2036
Motorcycle ADAS Market Foresight
Silicon carbide is broadening thermal management options for motorcycle radar modules, replacing conventional silicon substrates in high-frequency applications. Robert Bosch GmbH leverages its Stuttgart sensor campus to dominate 77 GHz radar supply for European OEMs. Continental AG anchors rear-facing radar production for collision avoidance systems across premium motorcycle platforms. ZF Friedrichshafen AG competes through integrated corner-radar modules that reduce wiring complexity for mid-displacement bikes.
Motorcycle advanced driver-assistance systems comprise sensor arrays, electronic control units, and actuator interfaces designed to perceive roadway hazards and execute automated interventions such as emergency braking or throttle modulation, typically operating at detection ranges of 50–200 meters depending on sensor modality. Camera-based systems currently occupy the largest installed base due to lower per-unit cost, though radar systems represent the fastest-expanding technology segment as all-weather reliability becomes a procurement priority for fleet operators deploying in variable climates. Collision avoidance systems command the dominant share of product-type revenue, while adaptive cruise control is gaining traction among touring motorcycle buyers seeking reduced rider fatigue on highway segments.
The European Union's General Safety Regulation mandates intelligent speed assistance and automated emergency braking for new motorcycle types, compelling OEMs to redesign electrical architectures before type-approval deadlines. Euro NCAP's expanded motorcycle testing protocol amplifies this pressure by publishing comparative safety scores that influence consumer purchase decisions across EU member states. The U.S. NHTSA maintains voluntary guidance rather than mandatory ADAS requirements, creating a regulatory divergence that shapes supplier product roadmaps. Stakeholders must monitor whether NHTSA harmonizes with European mandates or perpetuates a two-track compliance environment that fragments development investment.
Market Dynamics
Euro NCAP's forthcoming motorcycle safety ratings are compressing development timelines across European OEMs, forcing sensor fusion architectures to mature before type-approval deadlines. This regulatory pressure is cascading through supplier ecosystems, redistributing engineering resources toward radar-camera integration.
Growth Catalysts
- EU General Safety Regulation:Intelligent speed assistance and automated emergency braking mandates for new motorcycle types are compelling electrical architecture redesigns ahead of enforcement deadlines.
- Silicon carbide substrates:Thermal management improvements in 77 GHz radar modules are expanding operational envelopes for high-frequency applications in variable climates.
- German supplier concentration:Stuttgart and Munich anchor dense ecosystems of radar specialists and tier-one integrators serving premium motorcycle platforms.
Market Restraints
- Silicon carbide supply concentration:Substrate fabrication capacity constraints limit module scaling for mid-displacement motorcycle programs.
- NHTSA voluntary guidance:Absence of mandatory ADAS requirements in the United States fragments supplier investment between compliance-driven and discretionary markets.
- Camera reliability limitations:All-weather performance degradation constrains sole-dependency on vision systems for collision avoidance.
Strategic Opportunities
- Mid-displacement segment:Corner-radar module integration at reduced wiring complexity opens volume tiers previously served by passive safety alone.
- Adaptive cruise control:Touring motorcycle buyers seeking fatigue reduction on highway segments represent an underpenetrated application for throttle modulation systems.
- Sensor fusion convergence:Radar-camera integration architectures enable tiered feature packaging across premium and standard equipment levels.
Industry Challenges
- Functional safety certification:ISO 26262 compliance for motorcycle-specific use cases extends validation timelines beyond automotive baselines.
- Legacy electrical architectures:12V system limitations in existing motorcycle platforms constrain power budgets for multi-sensor arrays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Motorcycle ADAS Market |
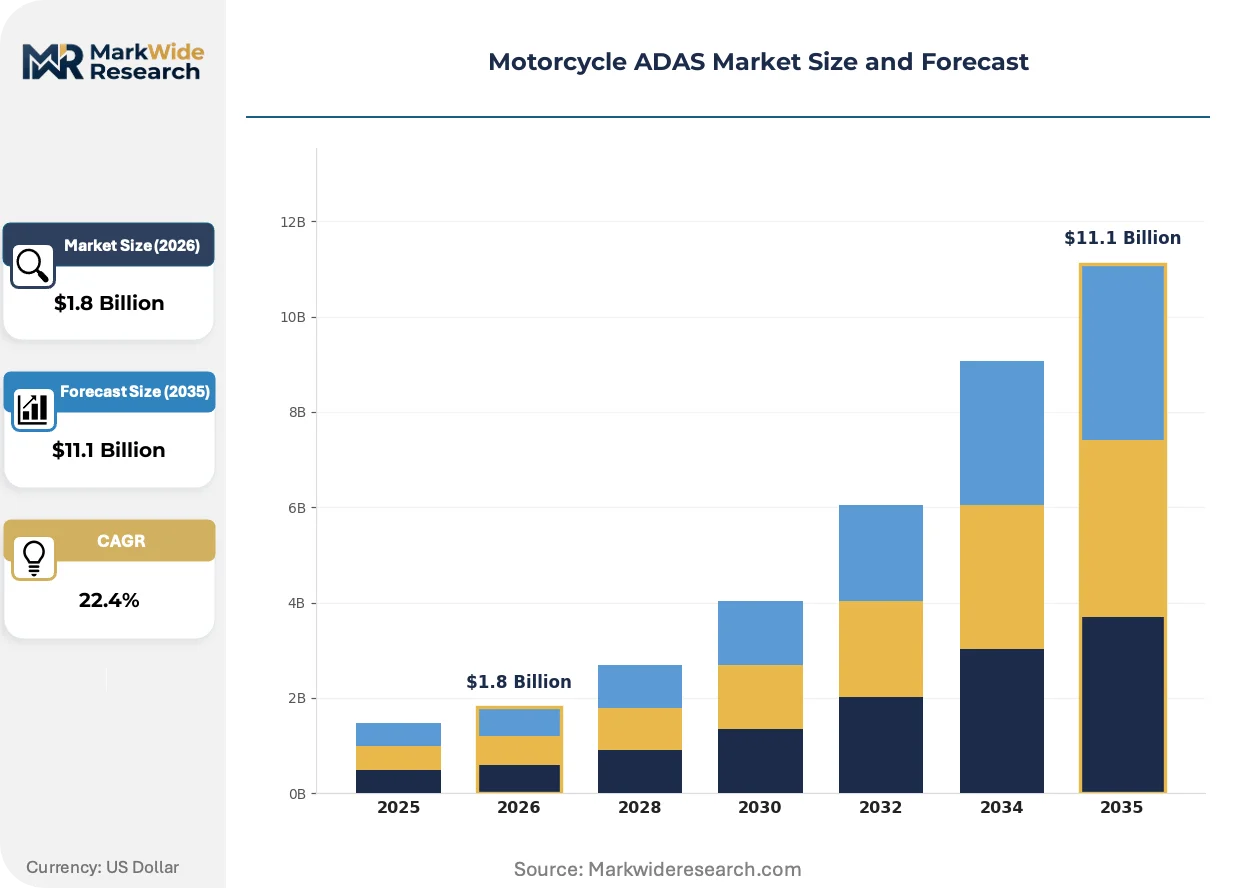
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $11.1 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Collision Avoidance Systems, Adaptive Cruise Control, Lane Departure Warning, Park Assist Technology: Radar Systems, Lidar Systems, Camera-Based Systems, Ultrasonic Sensors End User: Private Riders, Fleet Operators, Rental Services, Motorcycle Manufacturers Deployment: Aftermarket, OEM Integration, Fleet Management Solutions, Research and Development |
| Companies Covered | Continental AG, Robert Bosch GmbH, ZF Friedrichshafen AG, BMW Motorrad, Ducati Motor Holding, Honda Motor Co. Ltd., Yamaha Motor Co. Ltd., KTM AG, Valeo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Motorcycle ADAS Market Shifts & Advancements
Radar-based perception is displacing camera-only architectures as fleet operators prioritize all-weather reliability. Three interconnected developments are compressing technology adoption curves and reshaping supplier competitive positioning.
Silicon carbide substrates are replacing conventional silicon in 77 GHz radar modules, enabling higher thermal dissipation for continuous-wave operation. Premium motorcycle OEMs in Germany and Italy are accelerating procurement of SiC-based front-facing radar for adaptive cruise control. This material transition is converging with miniaturization demands to compress module form factors for fairing-integrated mounting.
REACH compliance deadlines for substance restrictions in electronic components are filtering sensor supplier qualification pools. Component vendors must demonstrate full material disclosure to maintain platform eligibility with European OEMs. Rear-facing radar modules for blind spot detection face the tightest certification timelines given their proximity to exhaust heat zones.
Fleet operators in Nordic climates are prioritizing radar-based systems over camera alternatives due to snow and ice occlusion risks. Commercial motorcycle leasing companies in Norway and Sweden now specify all-weather detection as a procurement threshold. This specification shift is transmitting upstream to tier-one suppliers as a contractual performance guarantee requirement.
Motorcycle ADAS Market Segmentation
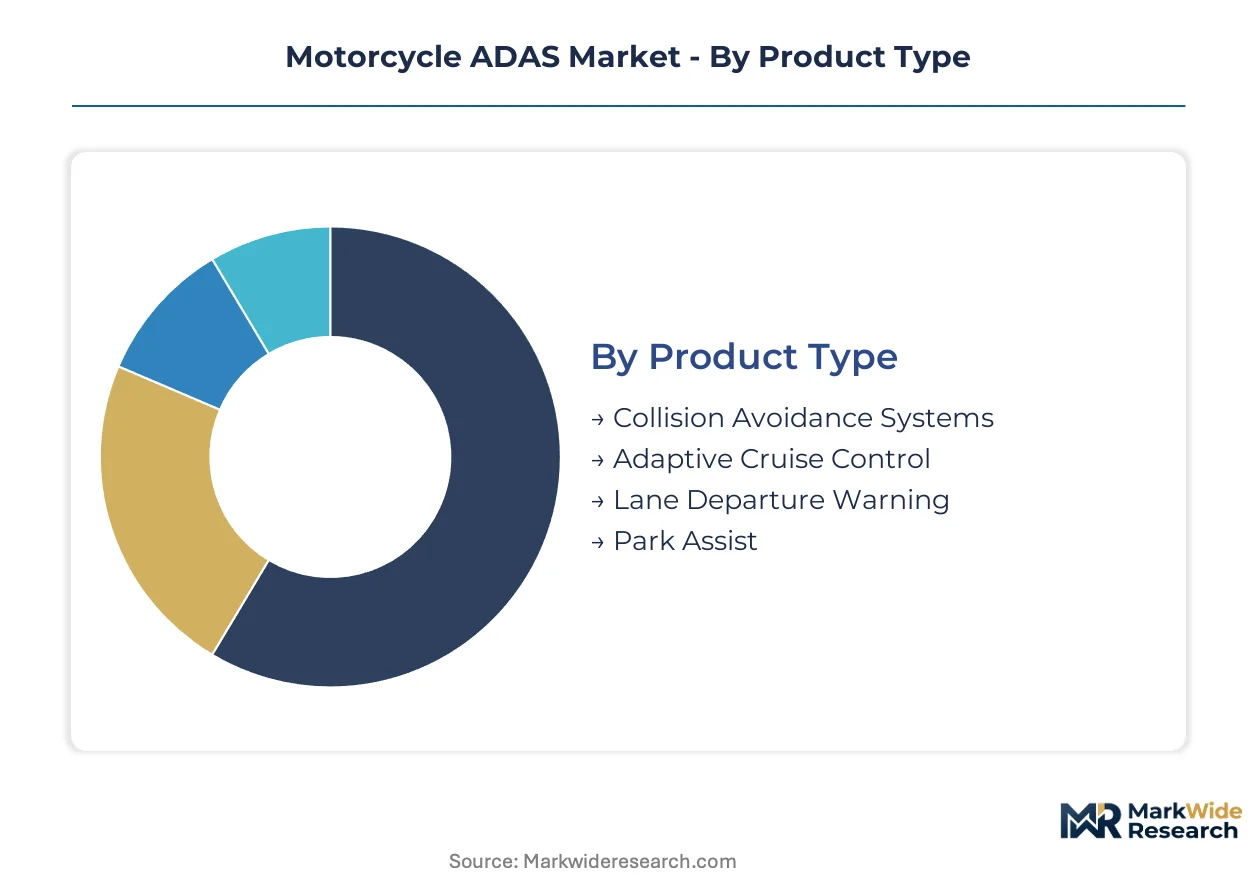
Motorcycle ADAS purchasing decisions diverge sharply across rider categories and integration pathways. Fleet operators prioritize all-weather reliability and service interval durability, while private buyers weigh feature visibility against incremental cost. Understanding these decision architectures enables suppliers to align sensor packaging with specific value thresholds.
Product Type:
Purchase prioritization follows a hierarchy of perceived risk reduction versus rider convenience enhancement.
- Collision Avoidance Systems:Emergency braking and throttle modulation interventions dominate procurement budgets across premium motorcycle platforms. Fleet operators in Germany and Italy specify these systems as baseline equipment for commercial leasing contracts.
- Adaptive Cruise Control:Throttle-maintaining radar systems reduce highway fatigue for touring motorcycle buyers. Demand concentrates among long-distance riders in North American and European markets where extended highway segments predominate.
- Lane Departure Warning:Camera-based drift alerts serve urban commuter segments with lower price elasticity.
- Park Assist:Ultrasonic proximity systems address low-speed maneuvering anxiety in dense European city centers.
Collision Avoidance Systems lead on scale; Adaptive Cruise Control leads on momentum.
Technology:
Climate exposure and maintenance access shape modality selection across operating environments.
- Radar Systems:77 GHz front-facing and corner-radar modules deliver all-weather detection for adaptive cruise and blind spot monitoring. Nordic fleet operators specify radar-based architectures exclusively due to snow and ice occlusion risks.
- Camera-Based Systems:Multi-lens arrays enable lane recognition and traffic sign detection at lower per-unit cost. Private rider demand in Mediterranean climates favors camera-primary configurations with radar supplementation.
- Lidar Systems:Solid-state units are emerging for high-resolution near-field mapping in experimental urban safety programs.
- Ultrasonic Sensors:Short-range parking assistance relies on proven low-cost transducer technology with minimal calibration requirements.
Camera-Based Systems capture the largest installed base; Radar Systems expand most quickly as climate durability becomes non-negotiable.
End User:
Volume concentration and specification authority diverge between institutional and individual purchasers.
- Fleet Operators:Commercial leasing companies and delivery services mandate standardized ADAS configurations across vehicle pools. Norwegian and Swedish operators now contractually require all-weather detection performance guarantees.
- Private Riders:Individual purchasers select feature packages based on touring versus commuting use profiles. German and Italian premium motorcycle buyers demonstrate highest willingness to pay for integrated sensor fusion.
- Rental Services:Short-term hire fleets prioritize damage reduction systems over comfort features.
- Motorcycle Manufacturers:OEM engineering teams specify tiered feature architectures for platform differentiation across displacement classes.
Fleet Operators drive standardization; Private Riders drive feature diversification.
Deployment:
Integration pathway determines electrical architecture constraints and regulatory compliance sequencing.
- OEM Integration:Factory-installed sensor arrays leverage dedicated 12V or 48V electrical systems with optimized mounting locations. Euro NCAP safety rating pressures are compressing development timelines for European OEM type-approval cycles.
- Aftermarket:Retrofit kits serve existing motorcycle populations with simplified wiring harnesses and universal mounting hardware. German regulatory frameworks require TÜV certification for aftermarket safety system installations.
- Fleet Management Solutions:Telematics-integrated ADAS packages enable centralized monitoring and predictive maintenance scheduling.
- Research and Development:Prototype platforms test sensor fusion algorithms and human-machine interface designs ahead of production scaling.
OEM Integration commands specification authority; Aftermarket channels address volume penetration in legacy fleets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors the densest supplier ecosystem for motorcycle radar modules, with Bosch and Continental co-locating engineering and production facilities around the Neckar Valley.
Germany
KBA type-approval standards for intelligent speed assistance compress development timelines for premium motorcycle platforms. The EU General Safety Regulation mandates automated emergency braking for new motorcycle types ahead of enforcement deadlines. Stuttgart and Munich host concentrated tier-one supplier campuses where Bosch and Continental scale 77 GHz radar production for adaptive cruise control systems.
United States
NHTSA voluntary guidance creates a compliance divergence that fragments supplier investment between mandate-driven and discretionary markets. Touring motorcycle buyers in California and Texas demonstrate highest willingness to pay for throttle-modulating adaptive cruise systems. The Pacific Northwest clusters aftermarket retrofit distributors serving legacy fleet conversions.
Italy
Bologna-based motorcycle manufacturers accelerate procurement of SiC-based radar modules for premium displacement platforms. Euro NCAP's expanded motorcycle testing protocol amplifies pressure for sensor fusion architectures ahead of publication deadlines. The Emilia-Romagna industrial corridor concentrates radar-camera integration engineering for Ducati and KTM platform variants.
Japan
METI standards for automotive-grade sensor reliability extend validation protocols to motorcycle-specific use cases. Honda and Yamaha engineering teams redesign electrical architectures to accommodate multi-sensor arrays within 12V constraints. The Chubu region around Nagoya hosts tier-two module fabricators supplying corner-radar units for mid-displacement programs.
India
BIS certification requirements for electronic safety systems filter supplier qualification pools for domestic motorcycle platforms. Commercial fleet operators in Maharashtra and Gujarat specify collision avoidance systems for delivery motorcycle pools. The Chennai-Bangalore corridor attracts radar module assembly investments serving ASEAN export markets.
Motorcycle ADAS Market Competitive Landscape
Global majors compete with regional champions across sensor modality and integration depth. The vendor base stratifies into three tiers: vertically integrated automotive suppliers, motorcycle-specialized tier-one integrators, and component-focused module specialists. Strategic moves concentrate on sensor fusion partnerships and SiC substrate supply security rather than direct M&A activity.
Within the vertically integrated tier, Robert Bosch GmbH and Continental AG occupy positions as archetypal full-stack suppliers. ZF Friedrichshafen AG represents the specialized tier-one model. These three German entities anchor the European supplier ecosystem around Stuttgart, with each occupying distinct positions across radar frequency bands and mounting configurations.
| Leading Market Players |
|---|
| Continental AG |
| Robert Bosch GmbH |
| ZF Friedrichshafen AG |
| BMW Motorrad |
| Ducati Motor Holding |
| Honda Motor Co. Ltd. |
| Yamaha Motor Co. Ltd. |
| KTM AG |
| Valeo |
| Others |
Supply & Pricing Matrix
Silicon carbide substrate adoption in 77 GHz radar modules simultaneously compresses thermal management costs and concentrates procurement leverage among German and Japanese wafer suppliers. This material transition is redistributing margin pools from module integrators toward substrate fabricators while OEMs absorb redesign costs ahead of Euro NCAP deadlines.
Pricing Analysis
Input-cost pass-through from silicon carbide wafer supply constrains margin flexibility for tier-one radar module suppliers. Pricing stratifies across premium, standard, and economy tiers based on ISO 26262 certification grade and volume commitment scale. Cost compression in mid-displacement segments is intensifying because fleet operators in Germany and Italy now mandate baseline collision avoidance as contractual terms. Private touring motorcycle buyers in North America demonstrate lowest price sensitivity for adaptive cruise control features.
Supply Chain Analysis
Photoresist and specialty chemical supply for SiC wafer fabrication rests on Japanese and German producers with limited second-source alternatives. Raw material dependencies span silicon carbide substrates, 77 GHz RF semiconductors, and automotive-grade connector systems. Single-source vulnerability in SiC boule growth capacity exposes module production to allocation risk during demand surges. Distribution runs through tier-one automotive supplier campuses in Stuttgart, Munich, and Nagoya before final assembly at OEM motorcycle plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Motorcycle ADAS Market functions as a stable compounder anchored by regulatory mandates that embed multi-year procurement visibility for sensor suppliers.
For Market Incumbents: Cement sensor fusion architecture dominance through backward integration into SiC substrate supply partnerships, insulating against allocation risk as mid-displacement programs scale. Lock in multi-year platform wins with Ducati and KTM before Euro NCAP rating publication forces competitive repositioning. Prioritize ISO 26262 certification investment for motorcycle-specific use cases to extend validation moats beyond automotive baselines. For New Entrants and Emerging Players: The EU General Safety Regulation in Europe opens a window for corner-radar module specialists to penetrate mid-displacement tiers previously served by passive safety alone. Target Nordic fleet operators in Norway and Sweden where all-weather detection specifications now carry contractual performance guarantees. Pursue telematics-integrated ADAS packages for commercial leasing companies as a channel entry point with lower OEM certification barriers. For Investors and Strategic Acquirers: Valuations sit cheapest among tier-two radar module fabricators with proven motorcycle thermal management expertise but limited OEM platform access. Long-term viability hinges on sensor fusion convergence creating durable supplier relationships across multiple displacement classes. Watch NHTSA regulatory harmonization signals as the inflection trigger that would consolidate development investment currently fragmented between mandate-driven and discretionary markets.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Fusion Partnership | Radar-camera integration architectures enable tiered feature packaging across premium and standard equipment levels. |
| SiC Supply Security Agreement | Long-term substrate offtake contracts with Japanese wafer producers anchor thermal performance for 77 GHz modules. |
| Mid-Displacement Platform Win | Corner-radar integration at reduced wiring complexity opens volume tiers previously served by passive safety alone. |
| Functional Safety Certification | ISO 26262 compliance for motorcycle-specific use cases extends validation timelines beyond automotive baselines. |
| Fleet Telematics Integration | ADAS-embedded telematics packages enable centralized monitoring and predictive maintenance scheduling for commercial operators. |
Research Methodology
Direct dialogue with tier-one supplier procurement managers, OEM platform engineers, aftermarket distributors, and fleet leasing operators grounded the qualitative assessment. Secondary validation drew from KBA type-approval databases, Euro NCAP testing protocols, NHTSA guidance documents, and vehicle production registration data. Bottom-up sensor shipment estimates triangulated against top-down OEM platform content assumptions.
Segment-level outputs across the projection horizon reflect modeled penetration rates by technology modality, displacement class, and end-user archetype. CAGRs were derived from regression analysis of historical automotive ADAS adoption curves adjusted for motorcycle-specific electrical constraints and regulatory enforcement timelines. Forecast inputs incorporated SiC substrate capacity expansion announcements and Euro NCAP protocol publication schedules.
Revisions become necessary when NHTSA shifts from voluntary guidance to mandatory requirements, SiC fabrication capacity constraints ease, or Euro NCAP rating publication triggers accelerated OEM procurement cycles. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bikes and Motorcycles
Child Bike Seats Market
Bikes and Motorcycles
Sweden Electric Bike Market
Bikes and Motorcycles
Motorcycle Advanced Rider Assistance System Market
Bikes and Motorcycles
Malaysia Bicycle Market
Bikes and Motorcycles
Trike Market
Bikes and Motorcycles
Europe E-Cargo Bike Market
Bikes and Motorcycles
Two Wheeler Kick Lever Market
Bikes and Motorcycles
India Two Wheeler Market
Bikes and Motorcycles
Motorcycle Airbag Market
Bikes and Motorcycles
Motorcycle Hub Motor Market
Bikes and Motorcycles
Japan Motorcycle ADAS Market
Bikes and Motorcycles
Two Wheeler Suspension System Market
Bikes and Motorcycles
Motorcycle Instrument Cluster Market
Bikes and Motorcycles
China Two Wheeler Market
Bikes and Motorcycles
Motorsports Motorcycle Market
Bikes and Motorcycles
Bicycle Mechanical Disc Brake Market