
 Freestanding Large Cooking Appliance Market | 2026-2036
Freestanding Large Cooking Appliance Market Size, Share, and Industry Trends Forecast 2026-2036
Freestanding Large Cooking Appliance Market Foresight
The EU Ecodesign Directive is pivoting demand toward induction and electric ranges across European residential channels. Whirlpool Corporation leverages its North American manufacturing footprint to sustain cost competitiveness in gas range production. Electrolux AB anchors its premium positioning through convection technology leadership in dual fuel segments. Samsung Electronics competes aggressively on smart connectivity integration across its freestanding cooker portfolio.
Freestanding large cooking appliances comprise self-contained kitchen units integrating cooktops with ovens, typically spanning 30 to 48 inches in width and operating via gas, electric, or dual fuel energy sources. These appliances serve residential and commercial end users requiring independent installation flexibility without built-in cabinetry constraints. Induction heating technology commands the fastest expansion trajectory among product categories, driven by efficiency mandates and precision temperature control demands. Gas range segments retain dominant volume share in North American residential markets where utility infrastructure and consumer preference sustain mature demand patterns. Commercial kitchens and catering services concentrate margin pools through higher-specification equipment requirements and replacement cycle compression.
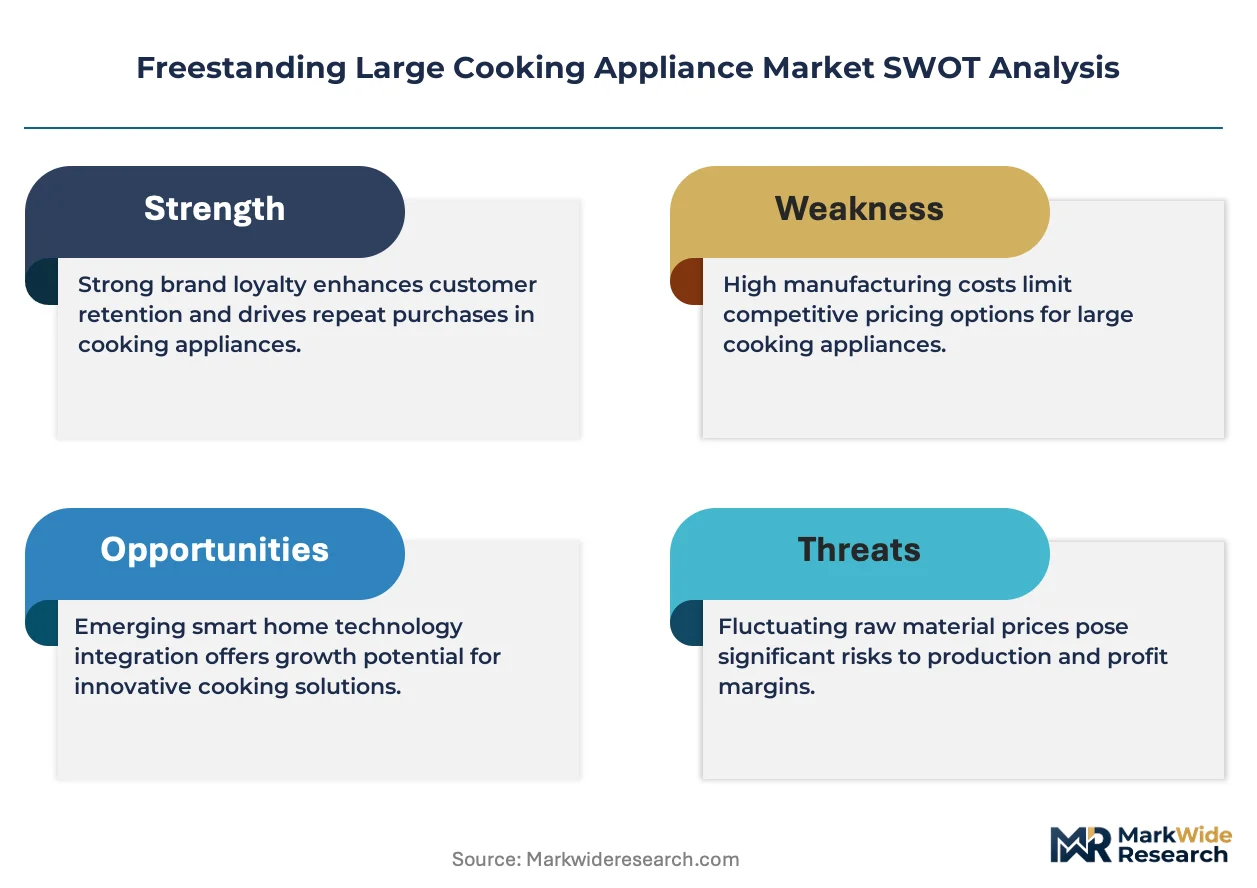
The EPA ENERGY STAR program shapes efficiency thresholds for electric and induction models sold in the United States, while the EU Ecodesign Directive and F-Gas Regulation constrain refrigerant and insulation material specifications across European supply chains. REACH compliance requirements from ECHA govern chemical substance restrictions in ceramic coatings and surface treatments, elevating compliance costs for manufacturers serving multiple jurisdictions. Stakeholders must monitor evolving electrification mandates in building codes and utility rebate programs that will progressively constrain gas appliance market access.
Market Dynamics
Electrification mandates embedded in building codes across developed economies are forcing a fundamental reconfiguration of product portfolios and manufacturing footprints in the freestanding cooking appliance sector.
Growth Catalysts
- EU Ecodesign Directive:Efficiency benchmarks for gas and dual fuel units are accelerating replacement cycles in European residential channels, pulling forward demand for induction-equipped models.
- Suburban housing development:North American residential builders specify energy-efficient electric ranges for new construction, creating specification-driven volume at the premium tier.
- Induction heating technology:Precision temperature control and superior energy efficiency are displacing conventional electric resistance cooking in renovation-driven markets.
Market Restraints
- Copper and electrical steel volatility:Input cost swings for induction coil materials compress margin stability for manufacturers scaling electric product lines.
- Gas infrastructure lock-in:Mature utility networks in the United States sustain consumer preference for gas ranges, constraining electrification velocity in the largest national market.
- REACH compliance costs:ECHA chemical substance restrictions on ceramic coatings elevate formulation expenses for pan-European product lines.
Strategic Opportunities
- German kitchen renovation market:Renovation rates outpacing broader European averages concentrate demand for premium freestanding replacements.
- Smart connectivity integration:Convergence of induction cooking with IoT-enabled energy management opens subscription service revenue streams.
- Commercial catering services:Higher-specification equipment requirements and compressed replacement cycles in foodservice create margin-rich volume pools.
Industry Challenges
- Electrical contractor certification:Induction installation requires specialized wiring expertise that remains scarce in rural and exurban service territories.
- Dual fuel product complexity:Maintaining gas and electric competency simultaneously strains R&D allocation and inventory management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Freestanding Large Cooking Appliance Market |
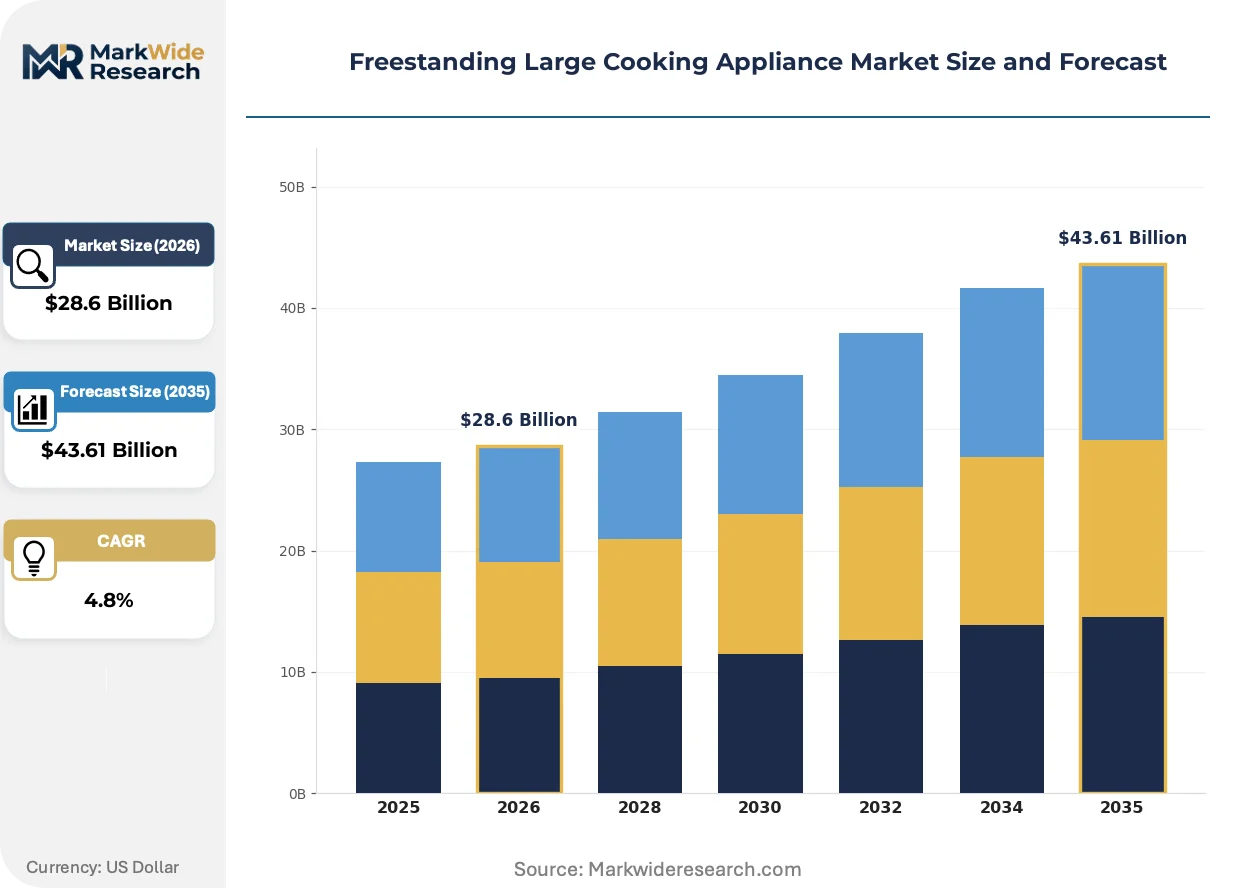
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $43.61 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Range, Gas Range, Dual Fuel Range, Induction Cooker, Ceramic Cooker Technology: Convection, Radiant, Infrared, Microwave-Assisted, Induction Heating Application: Residential Kitchens, Commercial Kitchens, Catering Services, Culinary Schools, Food Truck Operators End User: Homeowners, Restaurateurs, Culinary Institutions, Mobile Food Vendors, Event Caterers |
| Companies Covered | Whirlpool Corporation, Electrolux AB, Samsung Electronics, LG Electronics, BSH Home Appliances, GE Appliances, Frigidaire, KitchenAid, Miele, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Freestanding Large Cooking Appliance Market Shifts & Advancements
Product architecture and energy sourcing are undergoing parallel transformation as manufacturers reconcile efficiency mandates with installation flexibility demands.
Induction coil systems with discrete zone control are modularizing freestanding cooker design, enabling manufacturers to standardize chassis platforms across multiple price tiers. Residential builders in suburban developments specify these configurable units to streamline procurement while offering upgrade paths to homeowners. The technology is modularizing supply chains by decoupling cooktop electronics from oven cavities, compressing SKU complexity for regional assembly operations.
The EPA ENERGY STAR program is tightening efficiency thresholds for electric and induction models sold in the United States, forcing component suppliers to redesign heating elements and insulation packages. Manufacturers serving multiple jurisdictions face divergent compliance timelines between federal efficiency schedules and state-level electrification mandates. Electric range segments in California and New York are responding fastest, with product managers prioritizing ENERGY STAR qualification to access utility rebate programs.
Specification purchasing by multi-family developers is consolidating buyer power in the North American residential channel, displacing traditional retail-driven selection patterns. Appliance distributors are restructuring field sales organizations to serve builder accounts directly, bypassing dealer networks on volume contracts. This concentration is most visible in Texas and Florida metropolitan corridors where single-family construction permits remain elevated.
Freestanding Large Cooking Appliance Market Segmentation
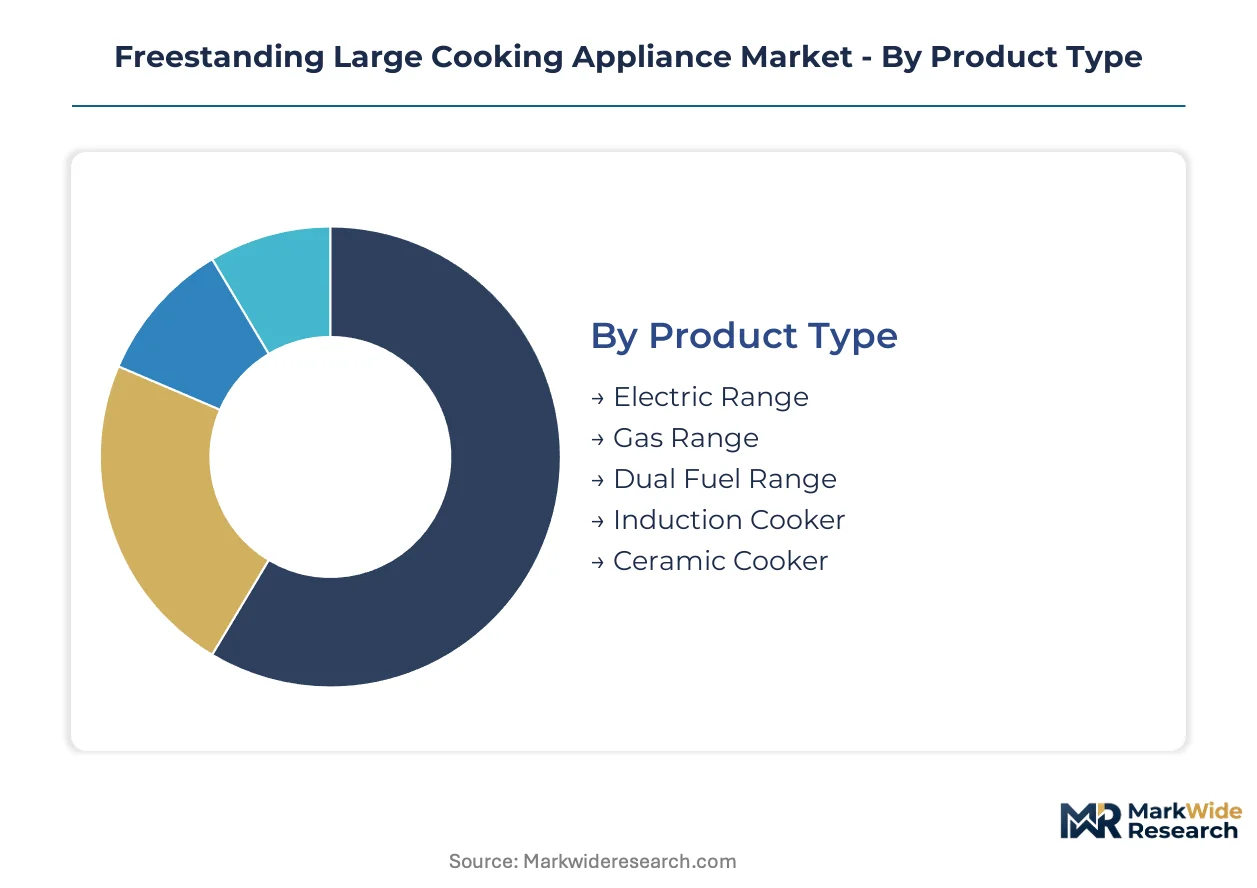
Product architecture in freestanding cooking appliances determines installation requirements, energy infrastructure compatibility, and replacement timing. Segmentation reveals where specification purchasing concentrates versus where consumer-driven selection dominates.
Product Type:
Upgrade cycles vary sharply by fuel source, with electrification mandates compressing replacement timelines for legacy gas installations in certain jurisdictions.
- Electric Range:Resistance coil or smooth-top configurations dominate builder specifications for suburban North American housing developments. ENERGY STAR qualification thresholds from the EPA govern efficiency compliance for these units in the United States.
- Induction Cooker:Electromagnetic coil systems deliver precision temperature control with superior energy conversion efficiency. Demand concentrates in German kitchen renovation channels where the EU Ecodesign Directive accelerates displacement of conventional electric resistance models.
- Gas Range:Open burner or sealed burner configurations retain volume leadership in markets with mature natural gas distribution infrastructure.
- Dual Fuel Range:Combines gas cooktop responsiveness with electric oven precision for premium residential installations.
- Ceramic Cooker:Halogen-heated smooth surfaces occupy the value tier in European retail channels.
Volume placements concentrate in gas ranges; the faster expansion belongs to induction cookers.
Technology:
Heat transfer mechanisms differentiate performance tiers and determine compatibility with specialized cookware materials.
- Convection:Forced-air circulation systems reduce cooking duration and temperature variance through integrated fan mechanisms. Restaurateurs in commercial kitchen applications specify these units for throughput optimization in high-volume service environments.
- Induction Heating:Magnetic field excitation of ferrous cookware eliminates thermal lag and improves safety profiles. The technology is gaining share fastest in residential renovation markets where electrical panel upgrades enable installation.
- Radiant:Electric coil or halogen elements provide baseline functionality at accessible price points.
- Infrared:Direct radiant heat transfer supports rapid searing applications in professional foodservice settings.
- Microwave-Assisted:Hybrid cooking systems combine conventional heating with microwave acceleration for time-sensitive residential users.
Convection technology anchors premium positioning; induction heating is climbing the fastest among emerging configurations.
Application:
End-use environment dictates durability specifications, duty cycle ratings, and regulatory compliance requirements.
- Residential Kitchens:Freestanding units in single-family and multi-family dwellings prioritize aesthetic integration and energy efficiency certifications. Suburban North American builders specify electric ranges for new construction developments at elevated rates.
- Commercial Kitchens:High-duty-cycle equipment with reinforced chassis and heavy-gauge components serves continuous operation demands. Foodservice operators concentrate procurement in metropolitan corridors with dense restaurant clusters.
- Catering Services:Mobile and event-based food preparation requires portable or rapidly deployable cooking infrastructure.
- Culinary Schools:Training environments demand durable, standardized equipment for instructional consistency.
- Food Truck Operators:Compact footprints and multi-fuel compatibility address space-constrained mobile installations.
Residential kitchens generate the highest unit volumes; commercial kitchens yield the steepest margin profiles.
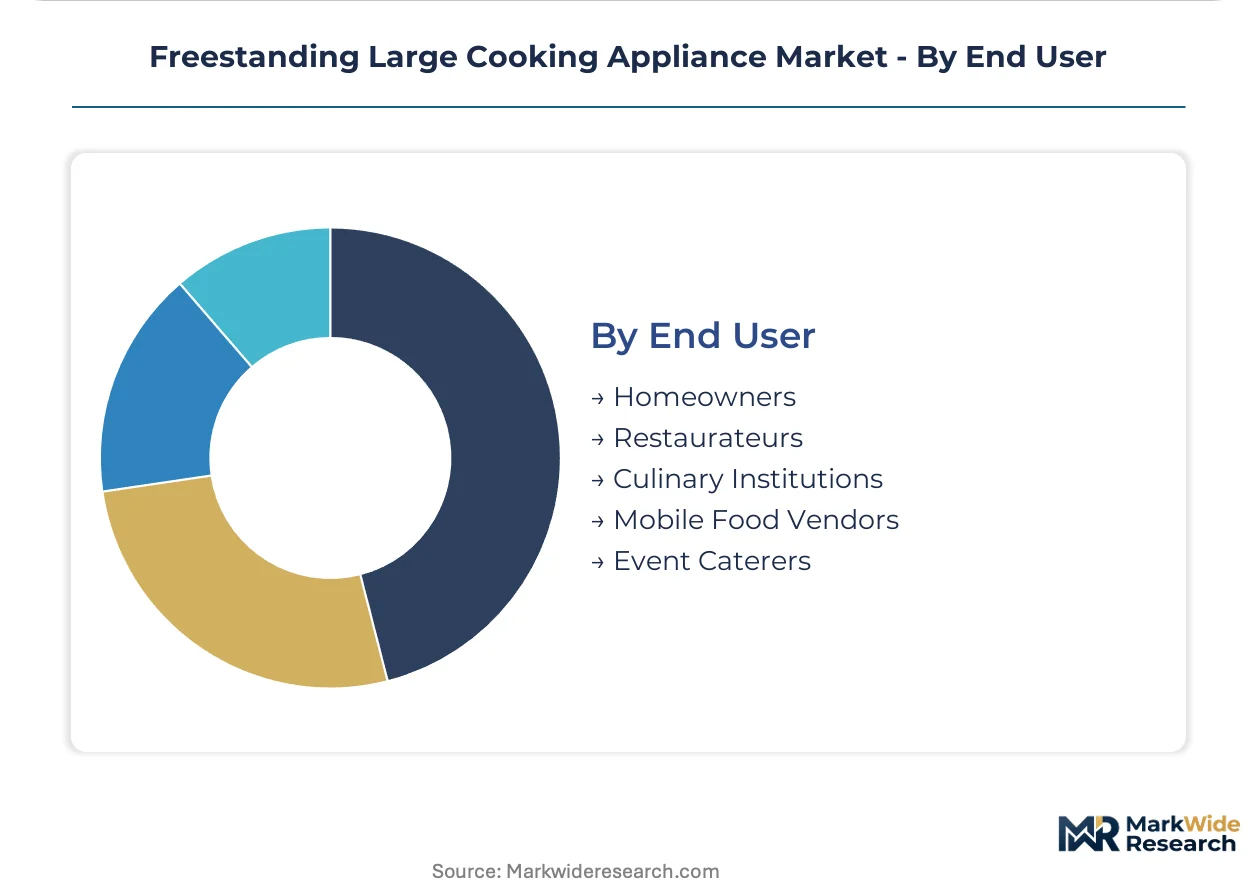
End User:
Purchasing authority and decision criteria fragment across consumer, institutional, and commercial buyer archetypes.
- Homeowners:Individual consumers selecting replacement units or specifying new construction appliances prioritize brand reputation and feature differentiation. German renovation markets show elevated replacement rates compared to broader European averages.
- Restaurateurs:Independent and chain restaurant operators balance capital expenditure constraints against throughput and reliability requirements. Texas and Florida metropolitan corridors concentrate specification purchasing by multi-family developers.
- Culinary Institutions:Educational and training facilities require standardized, durable equipment for instructional environments.
- Mobile Food Vendors:Food truck and cart operators prioritize compact dimensions and flexible fuel sourcing.
- Event Caterers:Temporary and seasonal foodservice providers demand rapid deployment and transportability.
Homeowners drive replacement cycle velocity; restaurateurs concentrate margin capture through higher-specification procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Dallas-Fort Worth metroplex anchors North American demand concentration for freestanding cooking appliances, with suburban construction pipelines sustaining specification volume for electric range deployments in master-planned communities.
United States
Texas and Florida metropolitan corridors concentrate multi-family developer procurement, with specification purchasing consolidating buyer power away from traditional retail channels. The EPA ENERGY STAR program governs efficiency thresholds for electric and induction models, shaping product qualification requirements for utility rebate access. California and New York state-level electrification mandates are accelerating displacement of gas range inventories in coastal markets.
Germany
Kitchen renovation rates in Bavaria and North Rhine-Westphalia outpace broader European averages, concentrating premium replacement demand for induction-equipped freestanding units. The EU Ecodesign Directive tightens efficiency benchmarks for gas and dual fuel products, compressing replacement timelines in residential channels. Stuttgart's industrial corridor hosts component suppliers specializing in induction coil systems for pan-European appliance assembly.
China
Yangtze River Delta manufacturing clusters dominate induction cooker export production, with Zhejiang and Jiangsu provinces housing specialized coil winding and control module suppliers. GB standards from SAMR establish electromagnetic compatibility and energy efficiency baselines for domestic market access. Shanghai's port infrastructure facilitates outbound shipment to Southeast Asian and Middle Eastern distribution hubs.
Japan
Kanto region residential developers specify compact induction cookers for Tokyo metro-area multi-family units, where space constraints favor freestanding configurations over built-in alternatives. METI energy conservation standards mandate standby power limits and cooking efficiency metrics for domestic sales. Osaka-based distributors coordinate aftermarket service networks across western Honshu renovation markets.
United Kingdom
Southeast England housing associations are piloting electric range specifications for social housing retrofit programs, creating volume anchors for mid-tier product lines. Building regulations amendments in England and Wales are progressively constraining gas appliance installations in new construction from 2025. Birmingham's distribution hubs serve as consolidation points for Irish and Scottish secondary market supply.
Freestanding Large Cooking Appliance Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technology integration and brand positioning dimensions, with the market exhibiting consolidated leadership at the top tier and fragmented specialization below. The vendor base stratifies into three archetypes: full-line conglomerates with multi-brand portfolios, regional specialists with channel-specific dominance, and component-integrated assemblers serving private-label contracts. Capacity expansion and strategic partnerships represent the dominant competitive moves, as manufacturers seek to reconcile electrification mandates with legacy gas infrastructure servicing requirements.
Among North American headquartered conglomerates, Whirlpool Corporation and GE Appliances exemplify full-line positioning across residential and commercial channels, while Electrolux AB represents European premium-tier anchoring through dual fuel and convection technology leadership. These three entities occupy positions that span specification purchasing relationships with multi-family developers, aftermarket retail distribution, and commercial foodservice procurement, with each archetype facing distinct margin pressures from input cost volatility and regulatory compliance fragmentation.
| Leading Market Players |
|---|
| Whirlpool Corporation |
| Electrolux AB |
| Samsung Electronics |
| LG Electronics |
| BSH Home Appliances |
| GE Appliances |
| Frigidaire |
| KitchenAid |
| Miele |
| Others |
Supply & Pricing Matrix
Copper and electrical steel coil costs cascade from Yangtze River Delta suppliers through OEM assembly floors, compressing margin pools at the mid-tier while premium brands pass through material volatility via convection technology bundling.
Pricing Analysis
Throughput-based pricing anchors commercial kitchen procurement, where restaurateurs calculate total cost of ownership across duty cycles and energy efficiency. Three-tier pricing structure across premium, standard, and economy levels separates Miele-grade dual fuel configurations from builder-specified electric ranges and entry-level ceramic units. Pricing pressure stems from copper and electrical steel volatility in induction coil production, squeezing manufacturers scaling electric portfolios fastest. Multi-family developers exhibit highest price sensitivity through consolidated specification purchasing, while German renovation homeowners show lowest sensitivity for induction-equipped premium replacements.
Supply Chain Analysis
Container freight rates from Shanghai to Rotterdam and Long Beach shape landed cost differentials for induction control modules and ceramic glass surfaces. Manufacturing gravity centers on China, Germany, and the United States, with Zhejiang Province housing specialized coil winding operations and Stuttgart's industrial corridor supplying pan-European assembly. Raw material dependencies include copper electrical steel for induction systems, ceramic glass for cooktops, and aluminum for chassis construction. Single-source vulnerability concentrates in advanced semiconductor components for IoT-enabled energy management. Distribution runs through appliance distributors restructuring field sales organizations to serve builder accounts directly, bypassing dealer networks on volume contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Induction coil winding capacity constraints in Yangtze River Delta manufacturing clusters prop pricing power for OEMs with captive supplier relationships or long-term offtake agreements.
For Market Incumbents: Deepen backward integration into induction coil production through partnerships with Zhejiang-based winding specialists, insulating margin pools from copper volatility. Secure ENERGY STAR pre-qualification pipelines for electric range portfolios ahead of California and New York state-level electrification mandates tightening. Reinforce specification purchasing relationships with Texas and Florida multi-family developers through dedicated builder sales teams. For New Entrants and Emerging Players: Food truck operators represent an underserved buyer archetype demanding compact multi-fuel compatibility and rapid deployment logistics. Target this segment through portable induction-gas hybrid configurations with modular power sourcing. Penetrate via direct equipment leasing models that bundle maintenance and fuel flexibility, bypassing traditional distributor markups. For Investors and Strategic Acquirers: German kitchen renovation permit acceleration is the leading indicator that premium induction replacement demand will sustain above-trend volume through the analysis window. Position for consolidation plays among component-integrated assemblers serving private-label contracts, particularly those with REACH-compliant coating capabilities and existing BSH or Electrolux supply relationships. Watch EU Ecodesign Directive amendment timelines as the signal for replacement cycle compression velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Induction Coil Capacity Expansion | Captive supply of copper electrical steel coils secures margin stability against raw material volatility. |
| Smart Connectivity Platform Integration | IoT-enabled energy management opens subscription service revenue streams beyond hardware sales. |
| REACH-Compliant Coating Investment | ECHA chemical restrictions on ceramic surfaces elevate compliance barriers for competitor formulations. |
| Builder Direct Sales Channel Buildout | Bypassing dealer networks captures specification purchasing volume from Texas and Florida developers. |
| Dual Fuel Product Line Rationalization | Streamlining R&D allocation between gas and electric competency reduces inventory complexity. |
Research Methodology
Document review covered EPA ENERGY STAR certification databases, EU Ecodesign Directive regulatory filings, and SAMR GB standards documentation, complemented by interviews with appliance manufacturing executives, electrical contractor trade associations, multi-family developer procurement directors, and commercial foodservice equipment distributors. Secondary validation drew from customs trade data, SEC 10-K appliance segment disclosures, and national kitchen renovation permit registries. Bottom-up unit shipment modeling triangulated against top-down market value estimates.
Historical shipment trajectories cross-referenced against industry expert panel input shaped the analytical framework across the analysis window. Segmentation dimensions modeled include fuel source architecture, heat transfer technology tier, end-use environment duty rating, and regional regulatory cluster. CAGRs derived from curve-fitting approaches applied to replacement cycle timing and electrification mandate implementation schedules. Industry-specific inputs incorporated copper futures pricing volatility and ENERGY STAR qualification threshold evolution.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to building code electrification timeline acceleration, electrical contractor certification scarcity in rural territories, and REACH amendment scope expansion. Forecasts reflect documented assumptions regarding renovation rate persistence and utility rebate program continuity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service Equipment
Prepared Food Equipment Market
Food Service Equipment
Commercial Bar Equipment Market
Food Service Equipment
Global Frozen Drink Machines Market
Food Service Equipment
Coffee Equipment and Supplies Market
Food Service Equipment
Commercial Rotisserie Equipment Market
Food Service Equipment
Culinary Torch Market
Food Service Equipment
Restaurant Equipment Market
Food Service Equipment
Europe Walk-In Refrigerators and Freezers Market
Food Service Equipment
United States Commercial Dishwasher Market
Food Service Equipment
Industrial Dishwasher Market
Food Service Equipment
Popcorn Machine Market
Food Service Equipment
North America Fountain Dispenser Equipment Market
Food Service Equipment
Commercial Convection Ovens Market
Food Service Equipment
Global Refrigerated Display Cases and Chilled Rooms Market
Food Service Equipment
Commercial Refrigerator Market
Food Service Equipment
Electric Commercial Deep Fryers Market